
 Vertical Platform Lift Market | 2026-2036
Vertical Platform Lift Market Size, Share, and Industry Trends Forecast 2026-2036
Vertical Platform Lift Market Analytics
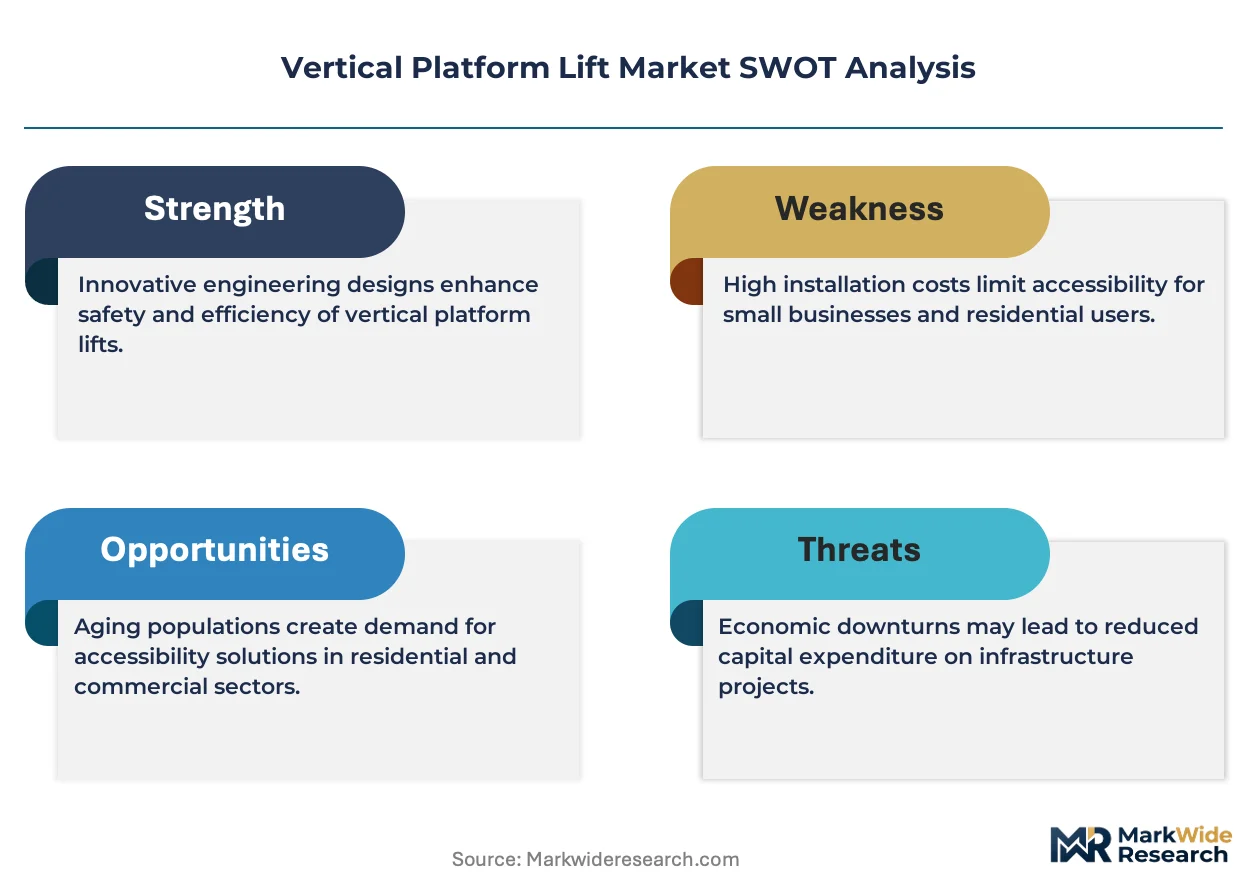
The gap between premium and commodity tiers is broadening as custom-engineered units with integrated safety sensors and weatherized enclosures command substantially higher margins than basic hydraulic models. Harmar leverages its R&D intensity to dominate the residential retrofit channel. Savaria anchors its position through geographic dominance across North American healthcare networks. Stiltz differentiates via compact electric drive technology for space-constrained European dwellings.
A vertical platform lift is a motorized accessibility device comprising a platform, drive mechanism, and safety enclosure that transports passengers or wheelchairs between vertical levels, typically rated for loads between 340 and 750 kilograms and operating at speeds up to 0.15 meters per second. Commercial lifts lead the product type category as retail establishments and educational institutions retrofit aging infrastructure to comply with accessibility mandates. Electric technology outpaces hydraulic systems in new installations where energy efficiency and reduced maintenance cycles concentrate margin pools for manufacturers.
The U.S. Department of Justice enforces ADA Standards for Accessible Design, mandating vertical platform lifts in public buildings with specific rise thresholds and platform dimensions. OSHA governs industrial lift installations through fall protection and guarding requirements that shape product engineering decisions. The European Union's Machinery Directive and CE marking framework control market access across member states. Stakeholders must monitor evolving national building codes and energy efficiency benchmarks as regulatory fragmentation intensifies procurement complexity across jurisdictions.
Market Dynamics
Electric drive systems are displacing hydraulic architectures across new installations, compressing maintenance revenue pools while redirecting manufacturer R&D toward sensor integration and predictive diagnostics. This technology pivot reconfigures competitive advantage toward software-enabled safety systems rather than mechanical engineering scale.
Growth Catalysts
- ADA Standards for Accessible Design:The U.S. Department of Justice mandates vertical platform lifts in public buildings with specific rise thresholds, forcing retrofit cycles in retail and educational infrastructure.
- Aging-in-place infrastructure:Germany's municipal investments in residential accessibility create concentrated demand for compact residential units with weatherized enclosures.
- Machine learning-enabled safety sensors:Predictive obstruction detection reduces liability exposure for healthcare facility operators, accelerating specification of premium-tier systems.
Market Restraints
- Steel and aluminum price volatility:Platform fabrication costs fluctuate with commodity input markets, squeezing margins on fixed-price municipal contracts.
- Certification timeline friction:CE marking under the EU Machinery Directive requires extensive third-party testing, extending product launch cycles by 8-14 months for European market entry.
- Stairlift substitution in low-rise residential:Inclined platform lifts and stairlifts capture budget-constrained home modification projects below 1.5 meter vertical rises.
Strategic Opportunities
- Modular retrofit kits:Pre-engineered platform and drive packages reduce installation labor by 40%, opening the contractor channel for residential accessibility projects.
- OSHA fall protection alignment:Industrial lift configurations meeting OSHA guarding requirements penetrate warehouse and manufacturing verticals previously served by freight elevators.
- Netherlands compact dwelling segment:Space-constrained urban housing stock creates demand for pitless, shaftless vertical platform lifts with sub-1 square meter footprints.
Industry Challenges
- Installation technician certification gaps:Qualified electricians with accessibility equipment credentials remain scarce in secondary U.S. metropolitan markets, constraining deployment velocity.
- Legacy hydraulic system interoperability:Building management system integration requires custom protocol bridges for pre-2015 installed bases, complicating upgrade pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertical Platform Lift Market |
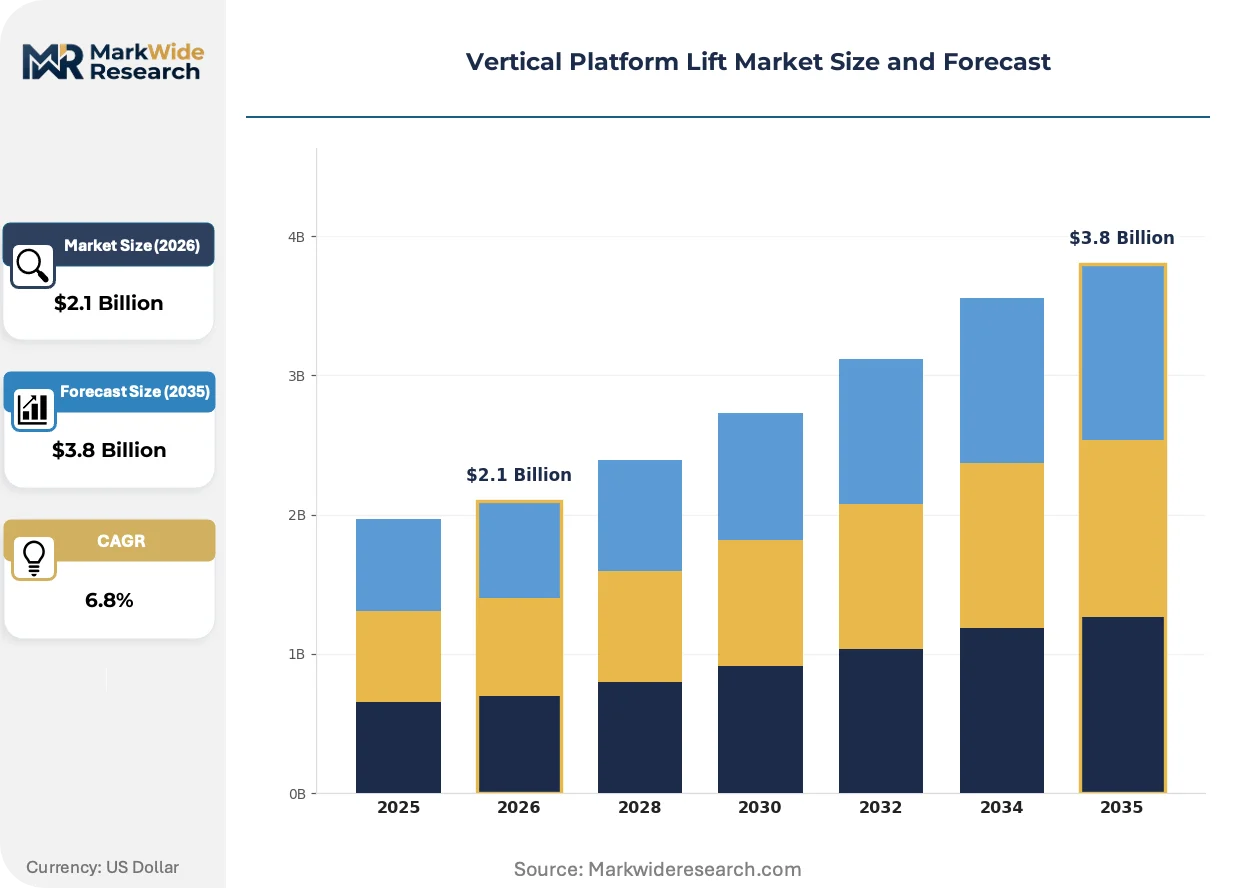
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Lifts, Residential Lifts, Industrial Lifts, Custom Lifts Deployment: Indoor, Outdoor, Mobile, Permanent End User: Healthcare Facilities, Retail Establishments, Residential Buildings, Educational Institutions Technology: Hydraulic, Electric, Mechanical, Vacuum |
| Companies Covered | Harmar, Savaria, Stiltz, JLG Industries, Garaventa Lift, Bruno, Stannah, Aritco, thyssenkrupp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertical Platform Lift Market Evolving Landscape
Sensor fusion and edge computing architectures are redefining safety system performance, while procurement patterns shift toward lifecycle cost optimization. Manufacturers must now compete on predictive maintenance capabilities rather than equipment durability alone.
Lithium iron phosphate battery systems are expanding into vertical platform lift drive architectures, replacing traditional lead-acid and wired electrical connections. Healthcare facilities in the United States specify these units for emergency power independence during grid failures. The technology is expanding into outdoor commercial installations where trenching costs for electrical runs exceed equipment capital expenditure.
The EU Machinery Directive's 2023 amendments impose stricter risk assessment documentation requirements for machinery with passenger transport functions. Manufacturers must now submit expanded technical files covering failure mode analysis for control system redundancies. German and French notified bodies report 20-30% longer evaluation periods, compressing product launch windows for Q4 specification cycles.
Facility managers increasingly bundle vertical platform lift procurement with 10-year service contracts, unbundling equipment margin from aftermarket revenue. Healthcare networks in the United States consolidate vendor relationships through single-source agreements covering multiple accessibility product categories. This concentration favors manufacturers with national service infrastructure over regional installation specialists.
Vertical Platform Lift Market Segmentation
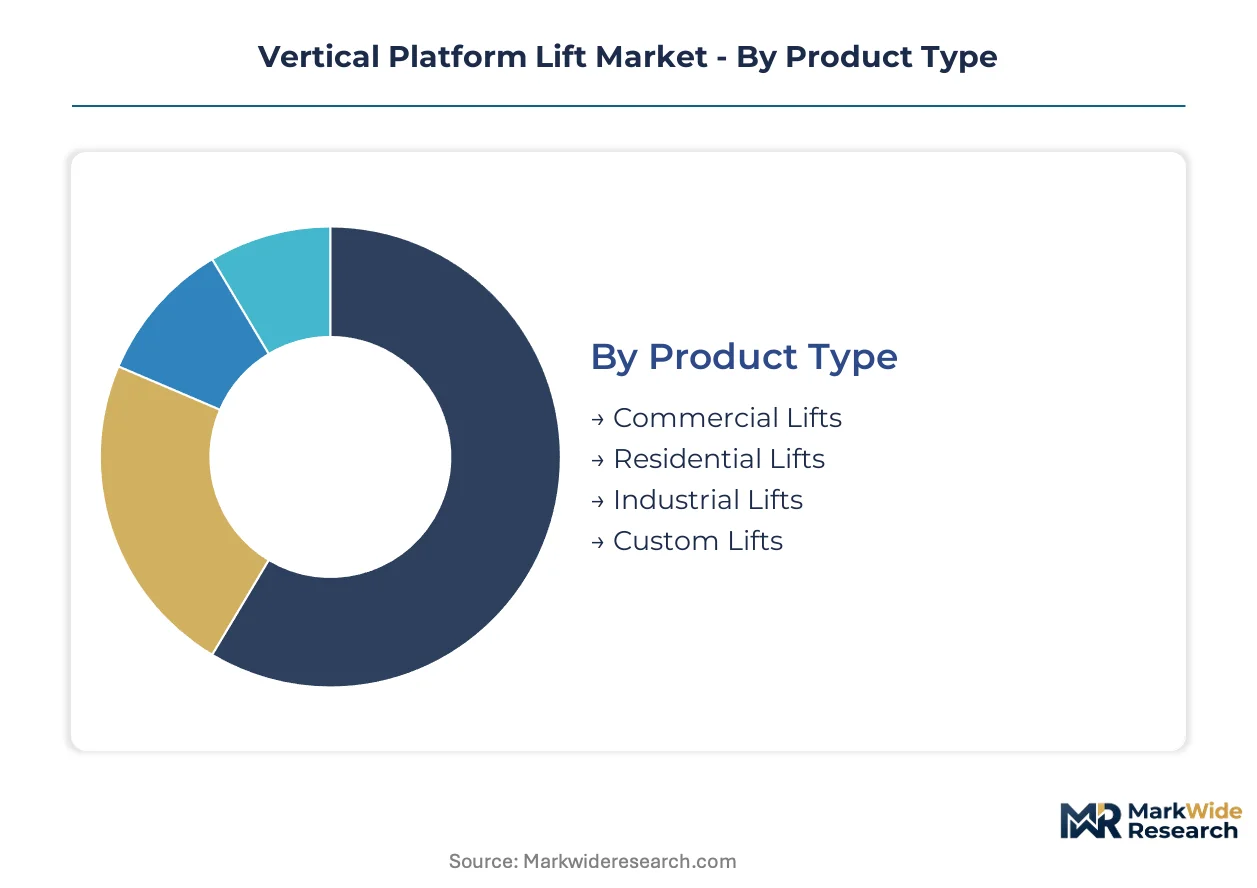
Vertical platform lift manufacturers configure product portfolios across four distinct category axes. Certification requirements, installation constraints, and end-use specifications vary sharply by segment, forcing modular platform designs and flexible drive system architectures.
Product Type:
CE marking under the EU Machinery Directive applies universally, though commercial and industrial installations trigger additional OSHA fall protection compliance in the United States.
- Commercial Lifts:Rated for 340-750 kilogram loads with weatherized enclosures and integrated safety sensors. Retail establishments and educational institutions in the United States drive specification volumes under ADA retrofit mandates. Leading the category by volume: Commercial Lifts. Growing fastest: Custom Lifts.
- Residential Lifts:Compact electric drive systems with sub-1 square meter footprints dominate space-constrained European dwellings. Germany's aging-in-place infrastructure investments concentrate demand for pitless, shaftless configurations.
- Industrial Lifts:OSHA guarding requirements shape engineering decisions for warehouse and manufacturing verticals.
- Custom Lifts:Pre-engineered modular retrofit kits reduce installation labor by 40% for specialized accessibility projects.
Commercial Lifts dominate procurement volumes. Custom Lifts climb the fastest as specification complexity intensifies.
Deployment:
Installation location determines weatherization requirements, foundation specifications, and power supply architectures.
- Indoor:Climate-controlled environments permit lighter enclosure specifications and standard electrical connections. Healthcare facilities in the United States specify lithium iron phosphate battery systems for emergency power independence during grid failures.
- Outdoor:Weatherized enclosures with sealed drive mechanisms withstand temperature extremes and precipitation exposure. Trenching costs for electrical runs frequently exceed equipment capital expenditure in commercial installations.
- Mobile:Temporary deployment configurations serve event venues and construction sites requiring rapid accessibility solutions.
- Permanent:Fixed installations anchor long-term service contract relationships and predictive maintenance revenue pools.
Permanent installations anchor manufacturer revenue stability. Mobile deployments expand most quickly in temporary infrastructure markets.
End User:
Procurement authority and specification complexity diverge sharply across facility types, with healthcare networks consolidating vendor relationships through single-source agreements.
- Healthcare Facilities:Machine learning-enabled safety sensors reduce liability exposure for operators, accelerating premium-tier system adoption. Predictive obstruction detection and 10-year bundled service contracts concentrate vendor selection criteria.
- Retail Establishments:ADA compliance mandates force retrofit cycles in aging commercial infrastructure across the United States.
- Residential Buildings:Municipal investments in accessibility infrastructure, particularly in Germany, drive compact unit demand.
- Educational Institutions:Public building retrofit requirements under accessibility standards sustain replacement demand cycles.
Healthcare Facilities command the highest specification intensity. Retail Establishments represent the largest addressable installation base.
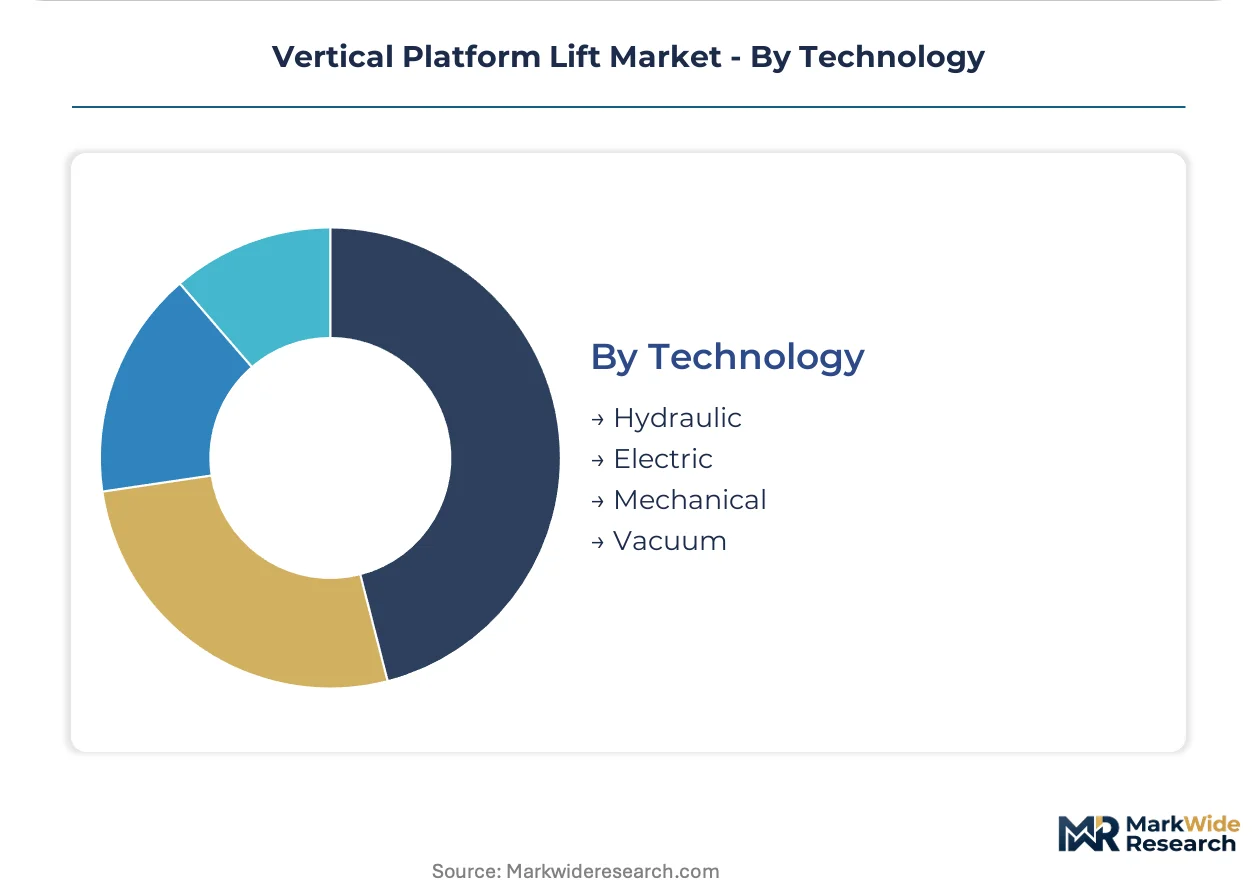
Technology:
Drive system selection determines maintenance revenue pools, energy efficiency profiles, and building management system integration complexity.
- Electric:Energy-efficient architectures with reduced maintenance cycles concentrate margin pools for manufacturers. Sensor integration and predictive diagnostics redirect competitive advantage toward software-enabled safety systems.
- Hydraulic:Legacy installed bases require custom protocol bridges for building management system integration, complicating upgrade pathways.
- Mechanical:Simplified drive mechanisms serve cost-sensitive applications with lower duty cycle requirements.
- Vacuum:Pneumatic lift technologies occupy niche applications with specific architectural constraints.
Electric systems displace hydraulic architectures across new installations. Mechanical systems retain position in budget-constrained retrofit projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors North American specification activity as healthcare networks consolidate vendor relationships across the Midwest corridor. The city's dense concentration of aging commercial infrastructure drives retrofit demand under federal accessibility mandates.
United States
Healthcare facilities in Chicago, New York, and Los Angeles drive premium-tier system adoption as patient mobility requirements intensify. The Department of Justice enforces ADA Standards for Accessible Design mandating specific rise thresholds and platform dimensions in public buildings. OSHA governs industrial lift installations through fall protection requirements that shape product engineering decisions for warehouse operators.
Germany
Municipal investments in aging-in-place infrastructure concentrate demand for compact residential units with weatherized enclosures. The EU Machinery Directive and CE marking framework control market access across member states with stricter risk assessment documentation requirements since 2023. Stuttgart and Munich anchor specification activity as retrofit cycles accelerate in dense urban housing stock.
United Kingdom
Educational institutions and retail establishments drive commercial lift procurement under building accessibility regulations. The Health and Safety Executive aligns with EU-derived machinery safety standards while post-Brexit certification timelines create procurement friction. London and Birmingham concentrate installation activity as aging infrastructure retrofit cycles intensify.
Netherlands
Space-constrained urban housing stock creates specialized demand for pitless, shaftless vertical platform lifts with sub-1 square meter footprints. National building codes emphasize energy efficiency benchmarks that favor electric drive architectures over hydraulic systems. Amsterdam and Rotterdam lead specification volumes as municipal accessibility investments expand.
Canada
Healthcare networks and public building retrofit requirements sustain replacement demand cycles across provincial jurisdictions. Health Canada and provincial regulators enforce accessibility standards harmonized with U.S. ADA specifications. Toronto and Vancouver concentrate procurement activity as commercial infrastructure ages and compliance deadlines approach.
Vertical Platform Lift Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and service infrastructure dimensions. The vendor base organizes into three tiers: integrated accessibility conglomerates with national service networks, specialized lift manufacturers with regional installation partnerships, and commodity fabricators competing on equipment price alone. Dominant competitive moves include geographic expansion through distribution partnerships and portfolio diversification into bundled service contracts.
Within the integrated conglomerate tier, Harmar and Savaria exemplify scale-driven positioning through R&D intensity and geographic dominance across North American healthcare networks. Stiltz occupies a specialist position representing compact electric drive technology for space-constrained European dwellings. These three anchors demonstrate how competitive advantage reconfigures toward software-enabled safety systems and predictive maintenance capabilities rather than mechanical engineering scale alone.
| Leading Market Players |
|---|
| Harmar |
| Savaria |
| Stiltz |
| JLG Industries |
| Garaventa Lift |
| Bruno |
| Stannah |
| Aritco |
| thyssenkrupp |
| Others |
Value Network & Pricing Analysis
EU Machinery Directive energy-efficiency benchmarks gate qualified supply and premium-tier pricing access for electric drive architectures, compressing margin pools for manufacturers lacking CE-marked component sourcing while elevating pricing power for integrated safety system suppliers.
Pricing Analysis
Value-based pricing anchored to uptime guarantees and predictive maintenance outcomes dominates healthcare facility procurement, with 10-year bundled service contracts separating premium-tier vendors from equipment-only suppliers. Price differentiation rests on sensor integration density and weatherization certification grade, with ADA-compliant commercial installations showing lowest price sensitivity and budget-constrained residential retrofits exhibiting highest elasticity. Pricing pressure stems from stairlift substitution in sub-1.5 meter rise applications, forcing margin compression on basic hydraulic models.
Supply Chain Analysis
Domestic-content mandates in U.S. federal accessibility contracts are reshaping sourcing toward North American steel and aluminum fabricators, displacing previously dominant Asian metal suppliers. Platform fabrication draws from Germany, China, and the United States for precision-machined drive components, with lithium iron phosphate battery cells resting on South Korean and Chinese cathode supply. Single-source vulnerability in semiconductor-based motor controllers creates procurement risk. Distribution runs through national accessibility equipment distributors and direct healthcare network contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as certification timeline friction and service infrastructure requirements force regional installation specialists toward acquisition or exit.
For Market Incumbents: Deploy predictive maintenance software platforms to lock in 10-year service contract renewals and defend against emerging IoT-enabled lift entrants. Acquire certified installation technician networks in secondary U.S. metropolitan markets where qualified electrician scarcity constrains deployment velocity. Backward integration into lithium iron phosphate battery pack assembly reduces exposure to South Korean cell supply volatility. For New Entrants and Emerging Players: Municipal contractors in Germany's aging-in-place infrastructure segment offer the most penetrable channel for compact electric drive units with sub-1 square meter footprints. Target Netherlands pitless, shaftless configurations for space-constrained urban housing stock where established players lack localized product adaptation. Pursue OEM partnerships with modular retrofit kit fabricators to bypass direct certification timeline friction. For Investors and Strategic Acquirers: CE marking evaluation period extensions at German and French notified bodies are the leading indicator that regulatory compliance scale will determine viable exit multiples. Five-to-ten year viability favors integrated accessibility conglomerates with national service networks over pure-play equipment manufacturers. Acquisition target archetype: regional lift specialists with dense healthcare facility relationships and pending ADA retrofit contract backlogs. Signal to monitor: bundled service contract pricing as percentage of total customer lifetime value.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Integration Partnership | Machine learning-enabled obstruction detection reduces liability exposure for U.S. healthcare facility operators. |
| CE Marking Fast-Track Investment | Compressed product launch windows at German notified bodies reward early regulatory engagement. |
| Modular Retrofit Kit Development | Pre-engineered platform packages reduce installation labor costs for residential accessibility contractors. |
| Technician Certification Program | Qualified electrician scarcity in secondary U.S. markets constrains deployment velocity for all vendors. |
| Lithium Battery Supply Agreement | Emergency power independence specifications from U.S. healthcare facilities anchor premium-tier demand. |
Research Methodology
Multi-period observation of ADA enforcement patterns, CE marking evaluation timelines, and municipal accessibility procurement cycles anchored the trend analysis, supplemented by interviews with lift manufacturer product managers, healthcare facility biomedical engineers, certified installation contractors, and GPO contracts managers. Secondary validation drew from OSHA enforcement databases, EU Machinery Directive amendment filings, U.S. Census building permit records, and hospital procurement database extracts. Bottom-up unit shipment estimates triangulated against top-down construction spending allocations.
Segment-weighting applied product type, deployment location, end-user facility category, and drive technology architecture as primary stratification dimensions across the modeling period. CAGRs derived from regression against construction spending indices, demographic aging curves, and regulatory compliance deadline clustering. Industry-specific forecast inputs included ADA retrofit mandate enforcement intensity and EU Machinery Directive risk assessment documentation burden evolution.
Caveats apply where steel and aluminum commodity volatility, CE marking timeline extensions, or stairlift technology substitution acceleration could materially shift the outlook. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Forklift Truck Market
Material Handling Equipment
Wear Plates Market
Material Handling Equipment
Dewatering Screen Market
Material Handling Equipment
East Africa Elevator and Escalator Market
Material Handling Equipment
Australia Forklift Market
Material Handling Equipment
Ball Screw Support Unit Market
Material Handling Equipment
Wire Rope Sling Market
Material Handling Equipment
Jaw Crushers Market
Material Handling Equipment
Freight Elevators Market
Material Handling Equipment
North America Conveyor Belt Market
Material Handling Equipment
Hydraulic Cylinder Rod Market
Material Handling Equipment
Electric Stacker Market
Material Handling Equipment
Pneumatic Conveying Diverters Market
Material Handling Equipment
Industrial Racking Systems Market
Material Handling Equipment
Hi Lift Jack Market
Material Handling Equipment
Sweep Depalletizers Market