
 Automotive Key Blanks Market | 2026-2036
Automotive Key Blanks Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Key Blanks Market Outlook
Fleet operators and commercial vehicle managers are rotating share toward high-security transponder key blanks as vehicle theft risks intensify. Kaba Ilco Corp. leverages its vertical integration across brass milling and transponder programming to sustain margin capture in the North American aftermarket. Silca S.p.A. anchors European demand through its dominance in laser-cut blank architectures for premium vehicle platforms.
Automotive key blanks are precision-machined metal or polymer substrates, typically brass or nickel-plated steel, cut to unique bitting patterns that mate with specific lock cylinders to enable vehicle access and ignition. Their primary commercial purpose spans original equipment supply, aftermarket replacement, and emergency locksmith services. Transponder and smart key categories command the strongest margin pools as embedded electronics raise technical barriers to commoditization, while standard brass blanks remain the highest-volume segment serving aging vehicle parcs. Material selection bifurcates along cost and corrosion-resistance requirements, with brass sustaining locksmith channel preference and aluminum gaining traction in lightweight OEM programs.
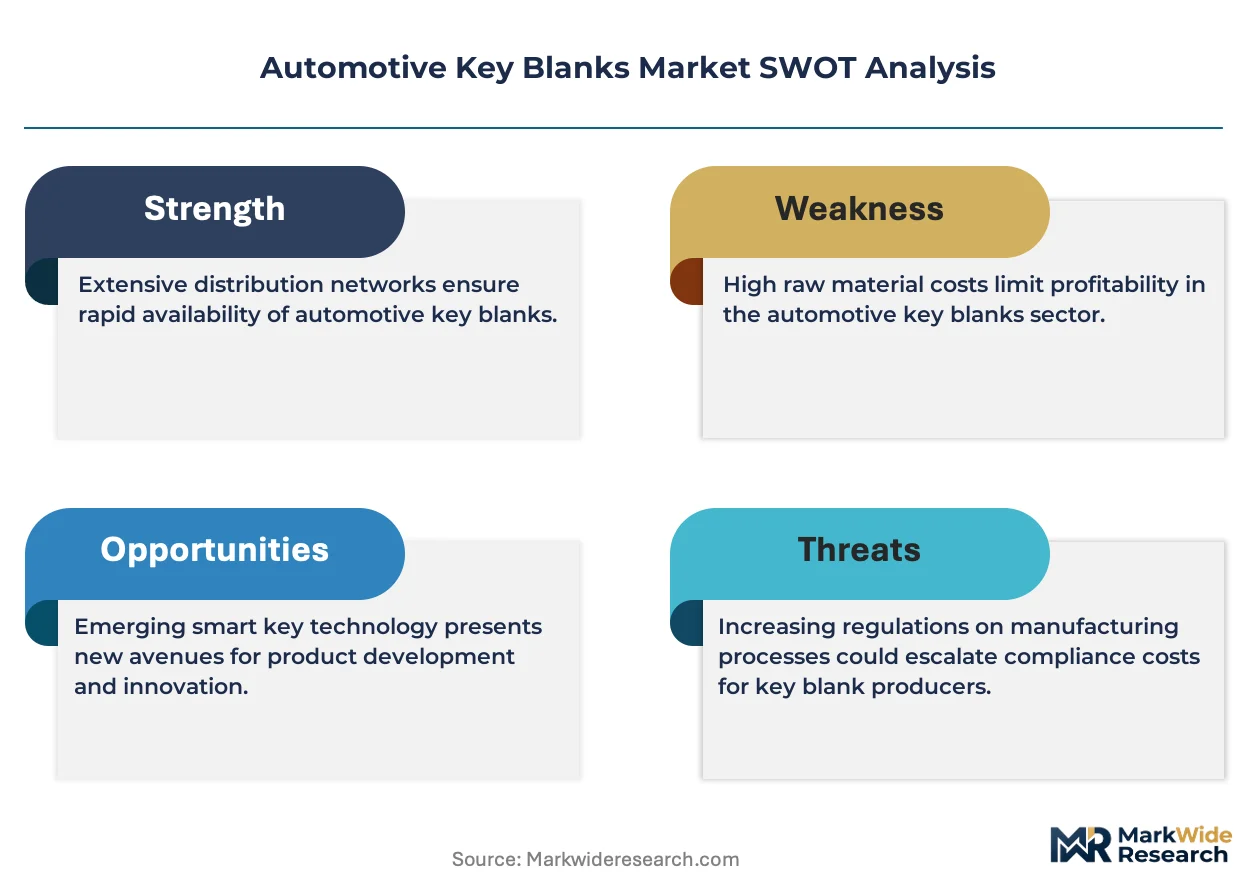
NHTSA immobilizer regulations, EPA hazardous substance restrictions on plating chemistries, and ISO 9001 quality management standards collectively shape product specifications and market access thresholds for key blank manufacturers. The EU REACH framework adds compliance burdens for nickel and chromium content in European-bound shipments. Stakeholders must monitor regulatory divergence between transponder-interoperability mandates and material-substitution timelines to align capacity investments with enforceable standards.
Market Dynamics
Transponder interoperability mandates and material-substitution timelines are compressing manufacturing flexibility while fragmenting procurement specifications across locksmith, fleet, and OEM channels.
Growth Catalysts
- NHTSA Immobilizer Mandates:Federal requirements for electronic theft-deterrent systems in new vehicles sustain replacement demand for transponder-equipped blanks as vehicle parcs age and keys require reprogramming.
- Fleet Utilization Intensity:Ride-sharing platforms and commercial vehicle operators rotate keys at accelerated rates, expanding aftermarket volume for high-wear brass and nickel-plated steel blanks.
- Brass Milling Automation:Precision CNC advancement reduces per-unit production variance, enabling smaller locksmiths to stock complex laser-cut architectures without dedicated machining investment.
Market Restraints
- Copper Price Volatility:Brass key blank margins compress when London Metal Exchange copper futures spike, forcing manufacturers to absorb cost swings or pass through to price-sensitive locksmith channels.
- Transponder Chip Supply Concentration:Semiconductor fabrication for immobilizer electronics concentrates in East Asian foundries, exposing blank assemblers to allocation rationing during capacity crunches.
- EU REACH Nickel Restrictions:Chromium and nickel plating chemistries face substance authorization hurdles, delaying European product launches and requiring costly formulation pivots to compliant alternatives.
Strategic Opportunities
- India Aftermarket Penetration:Low locksmith density relative to vehicle parc expansion creates whitespace for organized distribution networks to displace fragmented local metalworkers.
- Biopolymer Substrate Development:Corn-derived and recycled polymer key bodies align with OEM sustainability procurement criteria, opening specification slots previously closed to petroleum-based materials.
- Mobile Programming Services:Locksmith vans equipped with transponder cloning hardware capture emergency replacement demand outside fixed retail locations, collapsing response times for stranded motorists.
Industry Challenges
- Transponder Calibration Expertise Gap:Locksmiths trained on mechanical bitting lack firmware diagnostic skills, forcing distributors to subsidize technician certification or risk service failure rates.
- Multi-Protocol Inventory Burden:Proliferating OEM encryption standards require distributors to carry duplicative blank SKUs, tying working capital in slow-turning specialized stock.
- ISO 9001 Audit Compression:Quality management recertification timelines strain smaller mills lacking dedicated compliance staff, threatening market access for regional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Key Blanks Market |
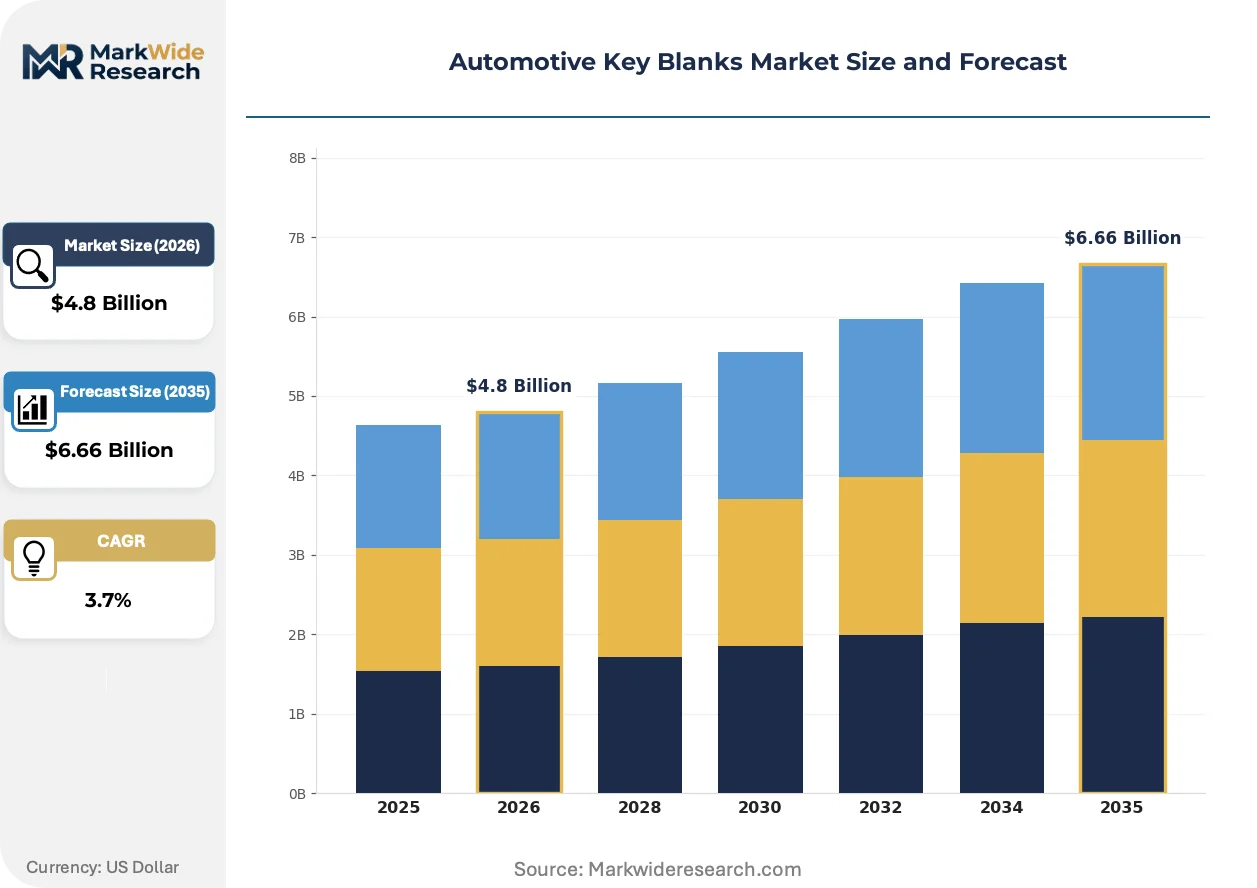
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Key Type: Transponder, Laser Cut, Standard, Smart Key Material: Brass, Steel, Plastic, Aluminum End User: Automotive OEMs, Locksmiths, Aftermarket Providers, Consumers Distribution Channel: Online Retailers, Specialty Stores, Direct Sales, Wholesalers |
| Companies Covered | JMA USA, Goto Manufacturing Co. Ltd., Kaba Ilco Corp., Hudson Lock LLC, Jet Hardware Manufacturing Co., Silca S.p.A., Strattec Security Corporation, Altuna Group, Keyline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Key Blanks Market Strategic Shifts
Digital key migration and substrate material science are splitting technical investment priorities between embedded electronics and sustainable metallurgy, reshaping where value accumulates across the supply chain.
Smart key and digital access technology is bifurcating the aftermarket into electronics-capable service providers and legacy mechanical cutters. Fleet managers at rental and logistics operators now specify smartphone-integrated entry systems for new procurements, compressing demand for traditional transponder blanks in commercial segments while sustaining residential locksmith reliance on physical key redundancy. The technology is bifurcating margin pools toward programming service revenue and away from commodity metal sales.
EPA hazardous substance restrictions on hexavalent chromium plating processes are forcing nickel-plating line conversions across North American manufacturing facilities. The industrial consequence is elevated capital expenditure for electroplating equipment upgrades and accelerated qualification of trivalent chromium alternatives. Premium vehicle key blank suppliers serving German OEM export programs are responding fastest, locking in compliant capacity ahead of enforcement phase-ins.
Consolidated fleet procurement is displacing fragmented individual consumer purchases as the dominant demand signal shaping distributor inventory planning. National rental chains and municipal vehicle pools now negotiate master supply agreements with direct manufacturer relationships, bypassing traditional locksmith wholesale tiers. This concentration is most visible in the United States, where enterprise fleet management platforms aggregate specification requirements across thousands of vehicles under single procurement umbrellas.
Automotive Key Blanks Market Segmentation
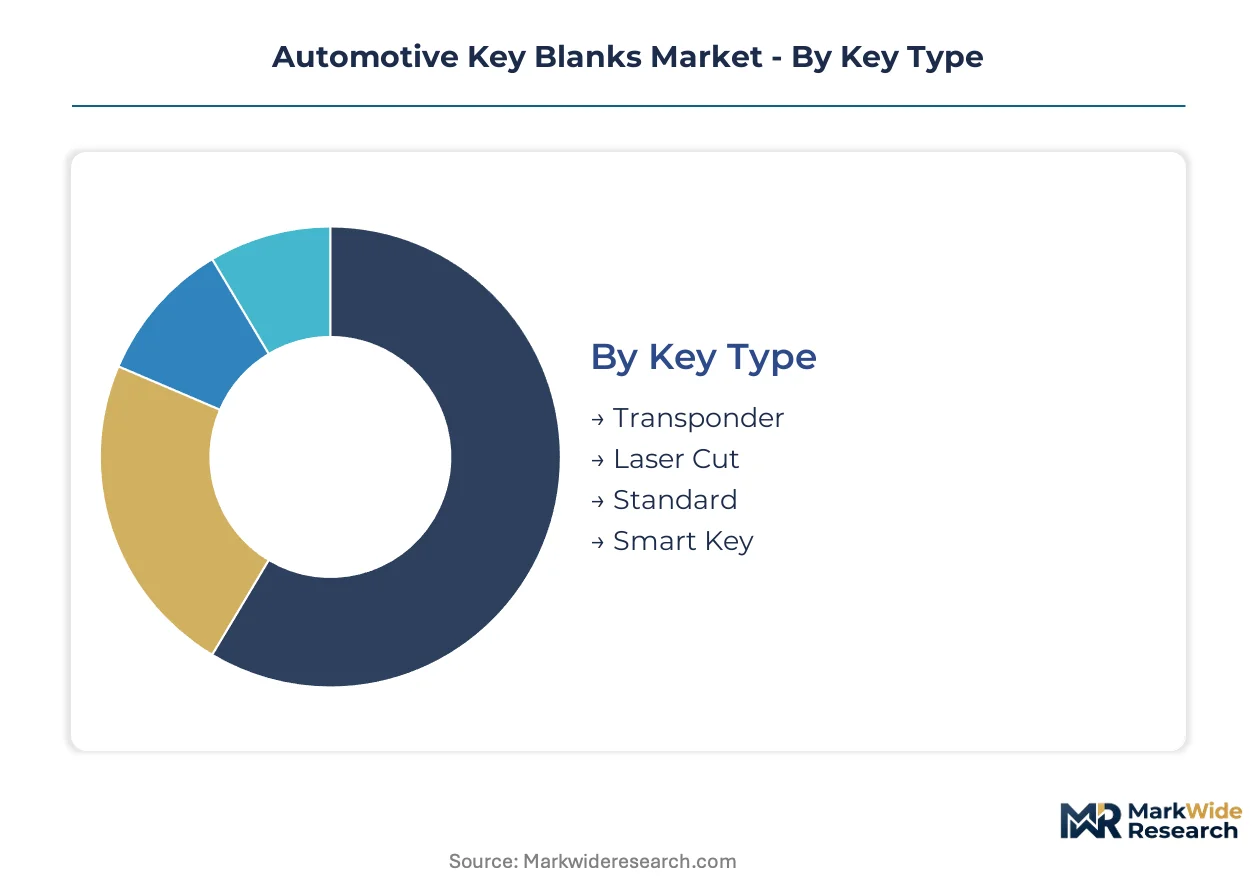
Automotive key blank procurement patterns diverge sharply across encryption sophistication, substrate metallurgy, and channel access. Manufacturers must align capacity investments with the specific technical and commercial requirements of each segment cluster.
Key Type:
Transponder and smart key architectures concentrate in Germany, Japan, and United States OEM supply chains, while standard and laser-cut formats dominate locksmith aftermarket demand across emerging markets.
- Transponder:Embedded RFID chips communicate with vehicle immobilizer systems to prevent unauthorized engine starts. Demand concentrates in United States and German replacement markets where NHTSA and KBA regulations mandate electronic theft deterrence, though chip supply bottlenecks constrain assembler margins.
- Smart Key:Proximity-based passive entry systems eliminate physical key insertion through encrypted low-frequency signaling. Fleet procurement at United States rental operators and Japanese corporate leasing divisions is displacing traditional transponder specifications in commercial vehicle segments.
- Laser Cut:Sidewinder bitting patterns machined into high-security blanks resist picking and impression attacks. European premium vehicle parcs sustain locksmith demand.
- Standard:Conventional mechanical bitting serves aging vehicle populations and cost-sensitive replacement scenarios. Volume concentrates in developing markets with limited immobilizer penetration.
Standard blanks command the established base. The steepest expansion runs through smart key architectures.
Material:
Cost tier stratification separates premium corrosion-resistant substrates from commodity metal formulations serving price-sensitive channels.
- Brass:Copper-zinc alloys deliver machinability and corrosion resistance that locksmiths prefer for high-wear cutting operations. United States and German distributors stock brass as the default substrate for transponder housing integration.
- Steel:Nickel-plated carbon steel blanks reduce material cost for high-volume aftermarket programs. EPA hexavalent chromium restrictions are forcing plating line conversions at North American mills.
- Plastic:Polymer key bodies reduce weight for smart key fob enclosures and non-structural applications. Biopolymer variants are qualifying under OEM sustainability procurement criteria.
- Aluminum:Lightweight substrates penetrate OEM programs targeting fuel efficiency improvements through component mass reduction.
Brass retains the volume anchor position. Aluminum is gaining specification share fastest in lightweighting-focused OEM supply agreements.
End User:
Customer type determines technical complexity requirements and margin capture potential across the value chain.
- Automotive OEMs:Factory-installed key systems require ISO 9001-certified production with traceable bitting security protocols. German and Japanese vehicle manufacturers specify transponder and smart key architectures exclusively.
- Locksmiths:Independent service providers demand blank compatibility across multiple vehicle platforms. United States locksmith density supports the most developed aftermarket infrastructure globally.
- Aftermarket Providers:Organized distribution networks aggregate demand from fragmented service points. Indian market development is concentrating procurement through emerging national distributors.
- Consumers:Direct replacement purchases occur primarily through online channels for standard and basic transponder formats.
Locksmiths anchor current volume flows. Aftermarket providers are consolidating procurement influence fastest in underpenetrated regions.
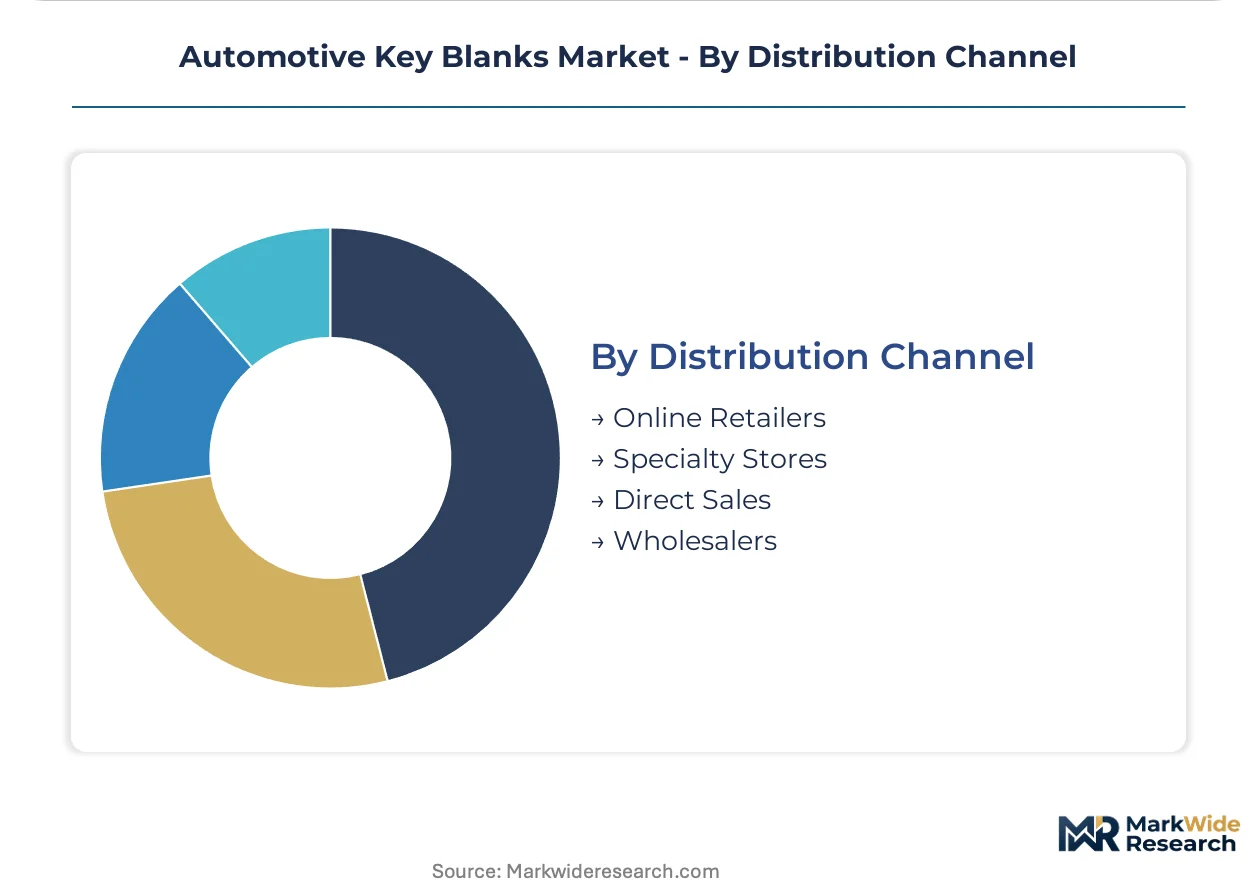
Distribution Channel:
Channel selection determines inventory velocity and technical support requirements for blank manufacturers.
- Online Retailers:E-commerce platforms aggregate long-tail demand for standard and basic transponder blanks. United States and Chinese digital marketplaces capture growing share of consumer-direct replacement purchases.
- Specialty Stores:Dedicated locksmith supply outlets provide technical consultation and cutting services. German and United States specialty networks maintain the deepest transponder programming capabilities.
- Direct Sales:Manufacturer relationships with fleet operators and OEMs bypass intermediary margins. National rental chains in the United States negotiate master supply agreements directly.
- Wholesalers:Regional distributors aggregate fragmented locksmith demand. Inventory burden from multi-protocol SKU proliferation strains working capital at smaller wholesale operations.
Wholesalers retain the broadest reach. Direct sales channels are capturing specification influence fastest through fleet procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles anchors North American aftermarket logistics for brass mill shipments from Asian foundries, while Rotterdam's Europort handles REACH-compliant nickel-plated steel consignments bound for German locksmith networks. These maritime gateways sustain the material flows that feed precision machining clusters across three continents.
United States
NHTSA immobilizer mandates sustain transponder blank demand across aging vehicle parcs in Texas and California. EPA hexavalent chromium restrictions force plating line conversions at Midwest mills. Chicago's locksmith supply corridor concentrates national distribution capacity for emergency replacement programs.
Germany
KBA regulations mandate electronic theft-deterrent systems in premium vehicle platforms, sustaining laser-cut blank specifications. EU REACH substance authorization hurdles delay nickel-plating product launches. Stuttgart's automotive supplier ecosystem anchors transponder programming service networks for Central European fleets.
China
Domestic vehicle parc expansion drives brass blank volume through aftermarket channels in Guangdong and Jiangsu provinces. SAMR quality certification requirements shape export-ready production standards. Shenzhen's electronics manufacturing clusters feed transponder chip assembly operations for regional blank assemblers.
India
Low locksmith density relative to vehicle stock creates whitespace for organized distribution networks in Maharashtra and Karnataka. BIS certification mandates establish quality thresholds for imported substrate materials. Pune's automotive component corridor attracts precision machining investments serving replacement key programs.
Japan
METI industrial standards govern smart key interoperability specifications for corporate leasing divisions. JIS quality management protocols constrain supplier qualification timelines. Nagoya's manufacturing belt sustains proximity-based entry system component flows for domestic OEM supply chains.
Automotive Key Blanks Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and regulatory compliance capabilities. The vendor base stratifies between scale-driven brass mills, transponder programming integrators, and regional locksmith supply houses. Three archetypes dominate: vertically integrated substrate-to-electronics assemblers, precision machining specialists, and distribution-anchored service networks. Competitive moves concentrate on plating line upgrades for EPA compliance and direct fleet procurement relationships that bypass wholesale tiers.
Within the integrated manufacturing tier, Kaba Ilco Corp. and Silca S.p.A. occupy positions exemplifying North American and European market anchoring respectively. Strattec Security Corporation represents the automotive OEM supply archetype. JMA USA anchors Spanish-origin penetration into North American aftermarket channels. These named entities sit within a broader constellation where geographic origin and corporate structure suffixes signal strategic positioning without requiring specific operational claims.
| Leading Market Players |
|---|
| JMA USA |
| Goto Manufacturing Co. Ltd. |
| Kaba Ilco Corp. |
| Hudson Lock LLC |
| Jet Hardware Manufacturing Co. |
| Silca S.p.A. |
| Strattec Security Corporation |
| Altuna Group |
| Keyline |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day brass mill lead times from Guangdong foundries concentrate pricing power with integrated substrate-to-electronics assemblers, while fragmented locksmith distributors absorb margin compression from copper price volatility.
Pricing Analysis
Volume-discount tiering separates master supply agreements for consolidated fleet operators from spot purchases by independent locksmiths. Three-tier pricing structure across premium, standard, and economy levels differentiates by transponder encryption complexity and ISO 9001 certification status. Cost compression in nickel-plated steel blanks is intensifying because EPA hexavalent chromium plating restrictions force costly electroplating line conversions. Fleet procurement managers exhibit lowest price sensitivity due to bundled programming service contracts, while individual consumers drive race-to-bottom dynamics in online retail channels.
Supply Chain Analysis
China and Taiwan anchor transponder chip fabrication and brass substrate milling for global blank assemblers. Raw material flows draw from Chilean copper concentrate, Indonesian nickel ore, and domestic zinc smelters. Single-source vulnerability concentrates in East Asian semiconductor foundries during capacity crunches. Distribution runs through Rotterdam and Los Angeles maritime gateways into regional wholesale networks serving locksmith supply corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across encryption protocols and regional regulatory clusters creates niche entry points for specialists targeting underserved fleet segments and biopolymer substrate development.
For Market Incumbents: Secure captive brass milling capacity in Midwest manufacturing clusters to defend against copper price volatility and transponder chip allocation rationing. Deepen backward integration into transponder programming firmware to capture service revenue pools as digital key migration displaces commodity metal sales.
For New Entrants and Emerging Players: ISO 9001 certification fast-track through German notified bodies unlocks specification slots in Stuttgart's automotive supplier ecosystem. Target India's organized aftermarket distribution whitespace in Maharashtra and Karnataka, where low locksmith density relative to vehicle parc expansion enables national distributor displacement of fragmented local metalworkers.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because fleet procurement concentration and regulatory compliance burdens favor scaled substrate-to-electronics integrators over regional machining specialists. Watch transponder interoperability mandate enforcement timelines as the inflection signal for programming service revenue inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Plating Line Upgrade | EPA trivalent chromium conversion locks in REACH-compliant capacity for German OEM export programs. |
| Biopolymer Substrate Qualification | Corn-derived key bodies capture OEM sustainability procurement criteria previously closed to petroleum materials. |
| Mobile Programming Fleet Deployment | Locksmith van-based transponder cloning collapses emergency response times for stranded motorists. |
| Direct Fleet Supply Agreement | National rental chain master contracts bypass wholesale tiers and capture specification influence. |
| India Distribution Network Buildout | Organized national distributors displace fragmented local metalworkers in underpenetrated aftermarket channels. |
Study Parameters
Desk research of customs trade data, vehicle registration databases, and regulatory filing repositories preceded structured interviews with OEM platform engineers, aftermarket distributor procurement leads, locksmith service operators, and brass mill production managers. Primary fieldwork across North American, German, and Chinese manufacturing clusters triangulated against secondary sources including NHTSA rulemaking dockets, EPA enforcement guidance, and EU REACH substance authorization timelines. Bottom-up blank volume estimates and top-down automotive parc projections were reconciled through iterative validation.
Variance decomposition across encryption sophistication tiers, substrate metallurgy grades, and channel access models structured the analytical framework over the projection horizon. Modeled dimensions spanned key type, material composition, end-user category, and distribution channel, with CAGRs derived from regression against vehicle parc aging curves and fleet utilization intensity indices. Forecast inputs incorporated transponder chip supply allocation patterns and plating chemistry substitution timelines.
Underlying assumptions cover NHTSA immobilizer mandate continuity, copper price band stability, and REACH substance authorization trajectories, with deviation risk concentrated in semiconductor foundry capacity crunches and EPA enforcement phase-in schedules. Recalibration cycles align with material shifts in fleet procurement consolidation rates and biopolymer substrate qualification milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automatic Bus Door System Market
Automotive Parts
North America Automotive Parts Die Casting Market
Automotive Parts
Two Speed Gearbox Market
Automotive Parts
Camshaft Bearings Market
Automotive Parts
Diesel Oxidation Catalyst Market
Automotive Parts
Automotive Exhaust Heat Recovery System Market
Automotive Parts
North America Ceramic Ball Bearings Market
Automotive Parts
Cheetah Friction Reduction Technologies Market
Automotive Parts
Europe Passenger Vehicles Lubricants Market
Automotive Parts
Argentina Automotive Parts Aluminium Die Casting Market
Automotive Parts
Automotive Piston Engine System Market
Automotive Parts
Timing Gear Market
Automotive Parts
Suspension Bump Stopper Market
Automotive Parts
Automotive Parts Zinc Die Casting Market
Automotive Parts
North America Automotive Airfilters Market
Automotive Parts
Wiper Systems Market