
 Italy Automotive Parts Zinc Die Casting Market | 2026-2036
Italy Automotive Parts Zinc Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Automotive Parts Zinc Die Casting Market Foresight
Asset-light leasing arrangements for multi-slide die casting equipment is narrowing the capital barrier for mid-tier Italian suppliers seeking OEM qualification. Bianchi Industrial S.p.A. leverages its vertical integration from alloy preparation to CNC finishing to secure long-term supply contracts with domestic vehicle assemblers. Fonderie Mora Dorno S.p.A. anchors its position through specialized thin-wall casting expertise for transmission housings, while Italpress S.p.A. competes on high-volume automation lines serving Tier-1 brake system manufacturers.
Italy automotive parts zinc die casting involves injecting zinc alloys with aluminum and copper additions into hardened steel molds at pressures exceeding 10 MPa, producing complex net-shape components with dimensional tolerances of ±0.05 mm for under-hood and chassis applications. Engine Components and Transmission Parts dominate current output volumes, reflecting sustained internal combustion vehicle program demand, while Brake Systems represents the fastest-expanding category as Italian suppliers adapt zinc casting geometries for integrated electric parking brake modules. High Pressure Die Casting commands the largest share of installed capacity, though Vacuum Die Casting is gaining traction where porosity-sensitive safety-critical applications require radiographic qualification.
CE marking under the EU Machinery Directive and Italy's transposed REACH enforcement through the National Institute of Health shape alloy composition limits and workplace exposure protocols for molten zinc operations. The Ministry of Enterprise and Made in Italy's National Resilience and Recovery Plan funding streams condition capital grants on energy efficiency benchmarks and scrap recycling quotas. Stakeholders must monitor how pending EU End-of-Life Vehicle Directive revisions redefine recycled content thresholds for zinc automotive castings.
Market Dynamics
REACH enforcement on zinc alloy composition and surface treatment chemistry is redirecting foundry capital toward closed-loop recycling infrastructure, compressing margins for operators dependent on virgin metal sourcing.
Growth Catalysts
- Powertrain zinc casting demand:OEM procurement of transmission housings and engine brackets is expanding across northern Italian manufacturing clusters as vehicle assemblers reshore critical component supply.
- Thin-wall casting expertise:Specialized capabilities for complex geometries below 2.0 mm wall thickness are qualifying Italian suppliers for integrated electric parking brake modules in premium vehicle platforms.
- Ministry of Enterprise capital grants:National Resilience and Recovery Plan funding streams condition awards on scrap recycling quotas and energy efficiency benchmarks, accelerating equipment modernization.
Market Restraints
- Aluminum substitution pressure:Magnesium-aluminum alloys in lightweighting programs threaten zinc's position in non-structural chassis brackets where corrosion resistance is secondary to mass reduction.
- Energy cost volatility:Natural gas pricing instability at Italian industrial tariffs directly impacts melting furnace operating economics, particularly for small-batch jobbing foundries.
- REACH compliance friction:ECHA substance restrictions on cadmium traces and hexavalent chromium surface treatments force alloy reformulation and process requalification cycles.
Strategic Opportunities
- Emilia-Romagna supplier corridor:Underpenetrated precision casting capacity in Modena and Bologna industrial zones offers geographic diversification from saturated Turin and Brescia clusters.
- Vacuum die casting adoption:Porosity-sensitive safety-critical applications in brake system modules create qualification pathways for radiographic-grade casting technology convergence.
- Closed-loop metal recovery:Process scrap recycling mandates under EU Circular Economy Action Plan incentives position Italian foundries for captive alloy supply cost advantages.
Industry Challenges
- Multi-slide die casting technician scarcity:Specialized mold setup and process control expertise for high-cavity tooling is concentrating among aging workforce cohorts with limited apprenticeship pipeline replacement.
- OEM qualification timeline compression:PPAP submission and production part approval cycles for new alloy specifications are extending 40-60% under heightened surface finish and dimensional tolerance requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Automotive Parts Zinc Die Casting Market |
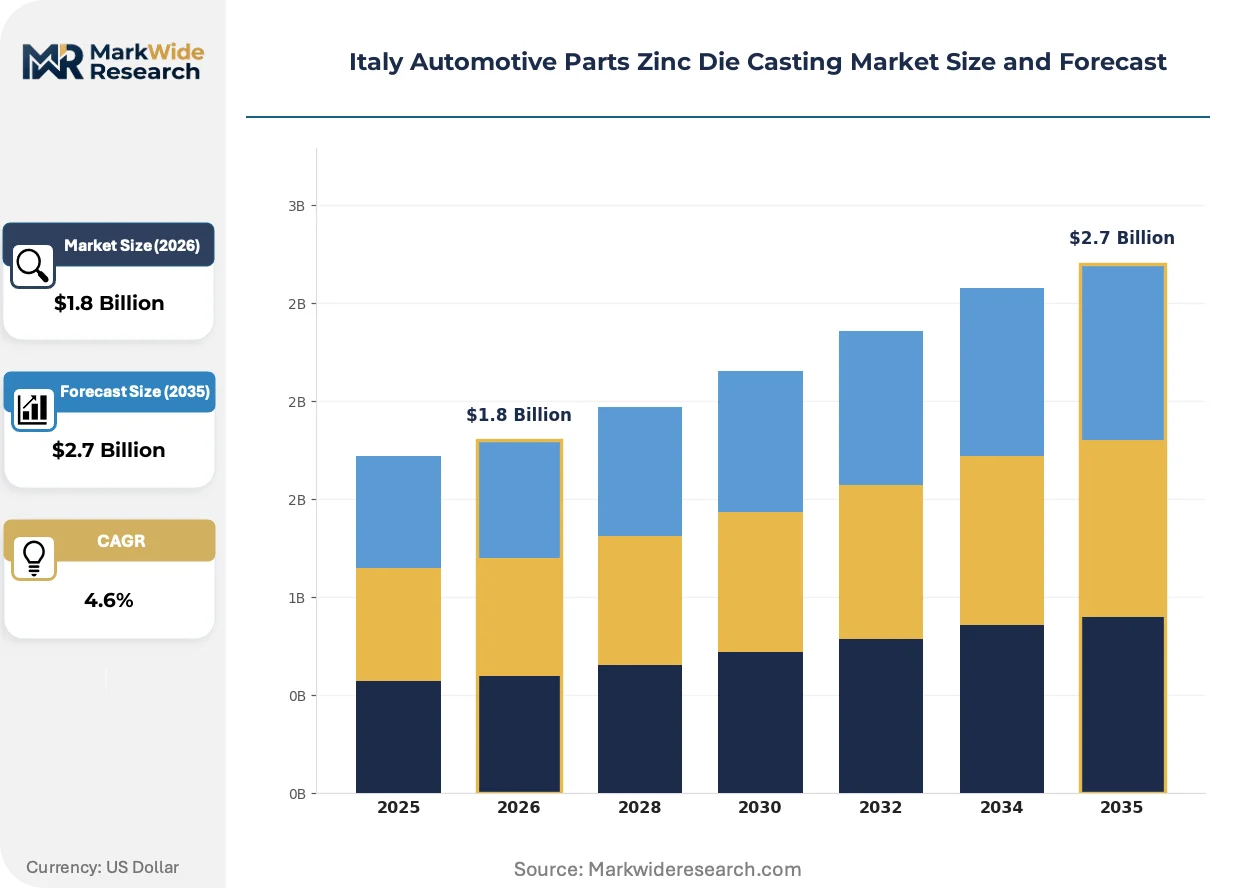
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Parts, Body Structure, Brake Systems End User: OEMs, Aftermarket Suppliers, Tier-1 Manufacturers, Vehicle Assemblers Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Light Trucks Manufacturing Technology: High Pressure Die Casting, Low Pressure Die Casting, Vacuum Die Casting, Gravity Die Casting |
| Companies Covered | Bianchi Industrial S.p.A., Fonderie Mora Dorno S.p.A., Italpress S.p.A., Carraro Die Casting, Zanardi Fonderie S.p.A., Bruschi S.p.A., Dynacast, Pace Industries, Ashok Minda Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Automotive Parts Zinc Die Casting Market Shifts & Advancements
Process automation and alloy chemistry control systems are reshaping competitive differentiation in Italian zinc die casting, separating capital-intensive operators from legacy jobbing foundries.
Multi-slide die casting automation with real-time cavity pressure monitoring is rendering obsolete manual trim and secondary machining operations for small complex components. Tier-1 brake system manufacturers are adopting these lines at replacement cycle pace. The technology is compressing labor content per part below thresholds where offshore sourcing retains cost advantage.
Italy's transposed REACH enforcement through the National Institute of Health is mandating workplace exposure protocols for molten zinc operations that exceed baseline EU requirements. Industrial hygiene infrastructure investments now consume 15-20% of annual maintenance capital at established foundries. Northern Italian manufacturing clusters are responding with centralized alloy preparation facilities to isolate exposure points.
Consolidated procurement by vehicle platform engineering teams is displacing fragmented component sourcing through long-term supply agreements tied to vehicle program life cycles. Domestic vehicle assemblers are centralizing zinc casting procurement under powertrain commodity managers. This concentration is most visible in Turin's automotive supplier corridor where single-source contracts now dominate transmission housing supply.
Italy Automotive Parts Zinc Die Casting Market Segmentation
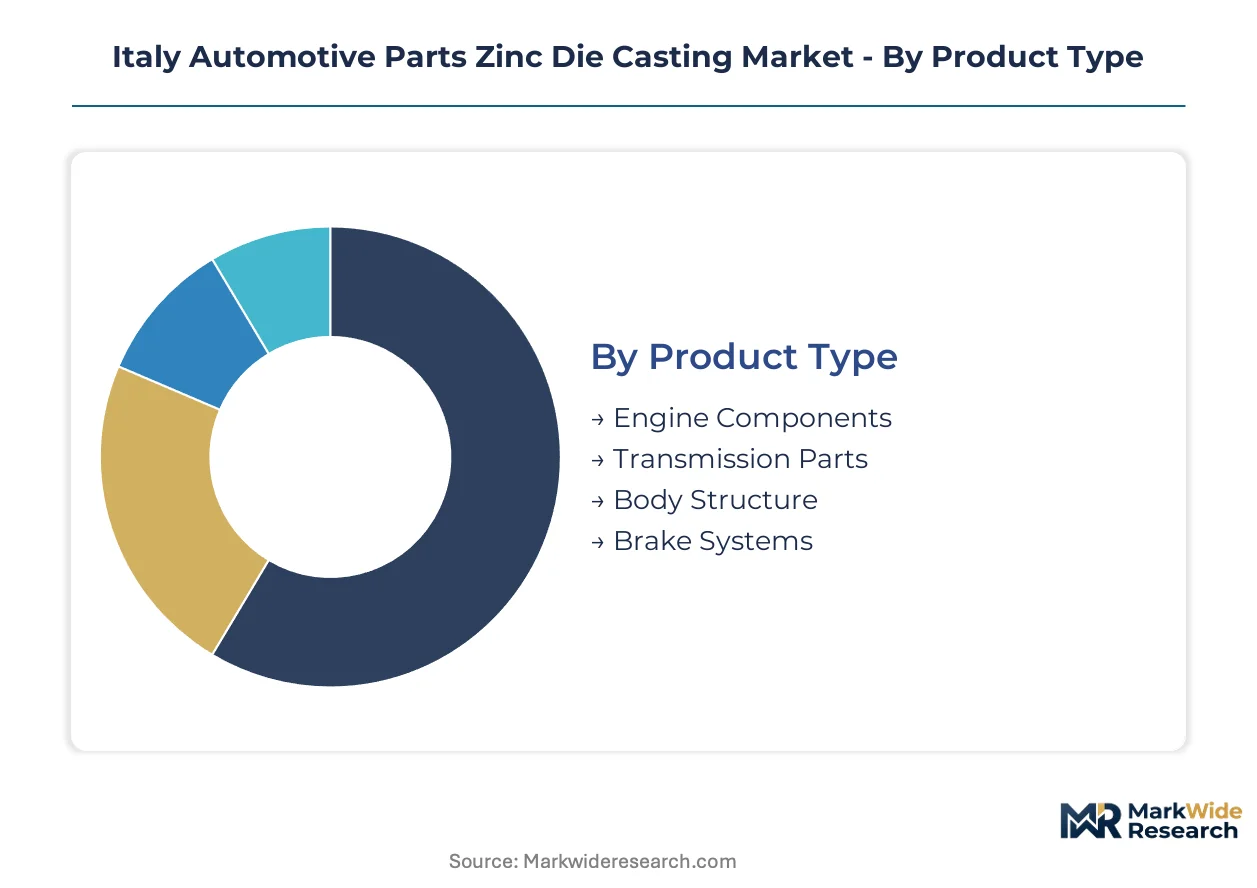
Zinc die casting procurement in Italy stratifies sharply across product complexity tiers and customer qualification barriers. Cycle times vary dramatically—high-volume brake components turn on 12-week automotive program schedules while specialized transmission housings lock into 3-year platform commitments.
Product Type:
Engine Components and Brake Systems rotate through production fastest, while Body Structure castings anchor the longest manufacturing cycles due to structural qualification requirements.
- Engine Components:Zinc-aluminum alloy castings for valve covers, timing chain housings, and oil pump bodies tolerate thermal cycling up to 150°C. Turin-based powertrain suppliers source these under 24-month blanket orders tied to Stellantis engine platform volumes.
- Brake Systems:Thin-wall zinc castings for caliper brackets and integrated electric parking brake modules demand ±0.03 mm dimensional stability. Brescia foundries with vacuum-assisted capability capture this demand as Italian Tier-1 brake manufacturers reshore from Eastern European subcontractors.
- Transmission Parts:Clutch housings and gear selector forks in ZA-8 alloy deliver wear resistance for manual and automated manual transmissions.
- Body Structure:Door hinge pillars and seat track anchors in ZA-12 alloy provide crash-energy absorption for premium vehicle architectures.
Engine Components dominates installed base. Brake Systems is where expansion concentrates.
End User:
Margin structures diverge sharply—captive OEM foundries absorb alloy volatility while independent jobbing shops price spot metal exposure into quotes.
- OEMs:Fiat, Iveco, and Maserati maintain captive zinc casting capacity for proprietary powertrain architectures. These operations prioritize traceability over unit cost, running dedicated alloy batches with full chemical certification chains.
- Tier-1 Manufacturers:Brembo, Magneti Marelli, and ZF Italy issue multi-year supply agreements with zinc casting specialists. Their qualification protocols mandate PPAP Level 3 submission with radiographic porosity mapping for safety-critical brake and steering components.
- Vehicle Assemblers:Final assembly operations in Pomigliano d'Arco and Cassino source zinc brackets and fasteners through consolidated commodity managers.
- Aftermarket Suppliers:Independent distributors serving collision repair and classic vehicle restoration purchase zinc castings through spot market channels with minimal technical specification enforcement.
Tier-1 Manufacturers command the densest supplier qualification networks. OEM captive capacity is where technology investment concentrates.
Application:
Platform electrification is redefining zinc casting relevance—thermal management hardware for battery packs outpaces declining internal combustion accessory demand.
- Passenger Vehicles:Premium and mass-market sedan platforms consume zinc castings for HVAC control modules, sunroof mechanisms, and power seat tracks. Italian luxury vehicle assemblers specify cosmetic-grade surface finishes requiring dedicated trim die operations.
- Electric Vehicles:Battery enclosure mounting brackets, inverter housings, and charging port assemblies in zinc alloy provide electromagnetic shielding and corrosion resistance. Startups in Modena's motor valley are qualifying Italian zinc casters for prototype-to-production ramps.
- Commercial Vehicles:Iveco Daily and heavy-duty truck programs specify high-strength zinc alloys for cab tilt mechanisms and fifth-wheel couplings.
- Light Trucks:Pickup platform derivatives for Southern European markets use zinc castings in tailgate hinges and running board brackets.
Passenger Vehicles anchors volume commitments. Electric Vehicles is gaining share fastest as thermal management casting demand accelerates.
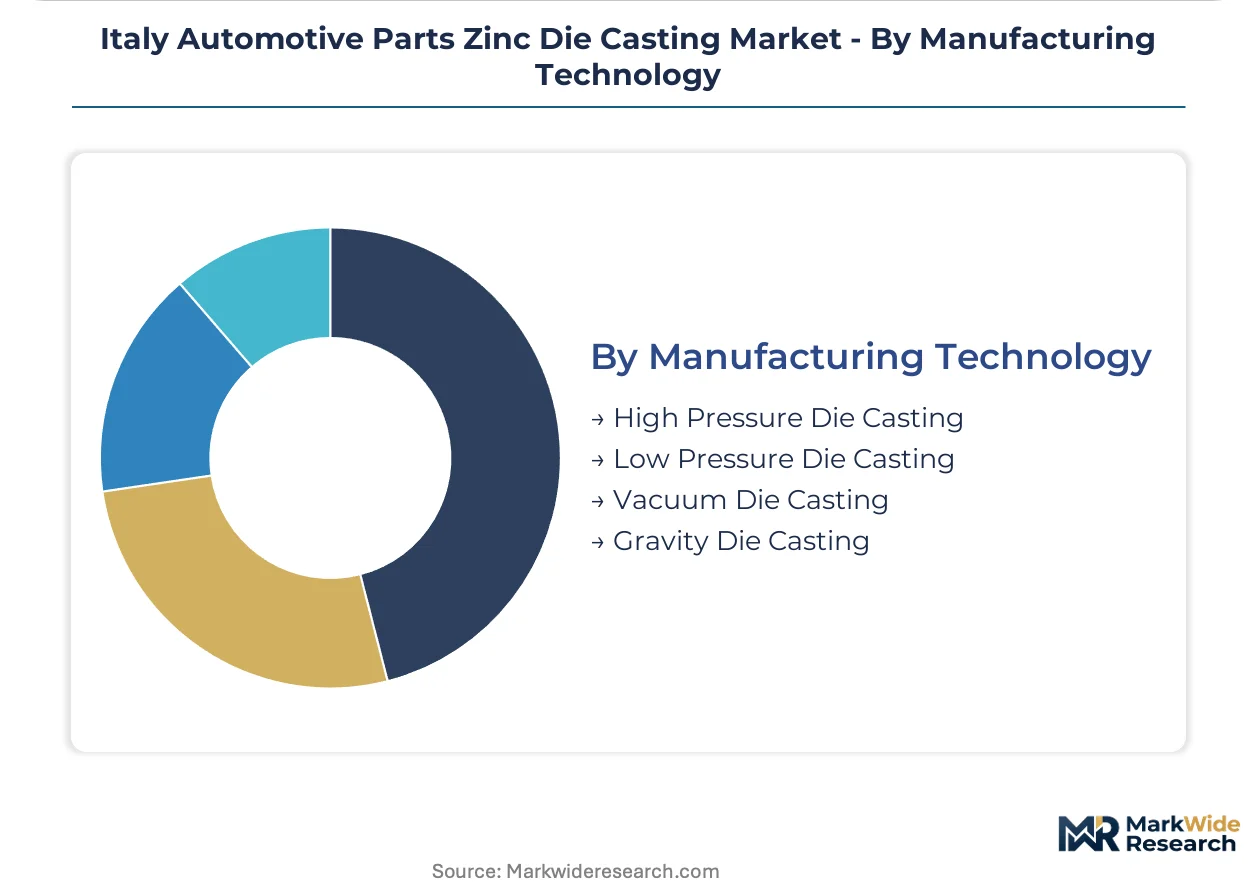
Manufacturing Technology:
Capital intensity separates the competitive tiers—automated high-pressure lines run 24-hour cycles while gravity operations batch-process architectural hardware.
- High Pressure Die Casting:Multi-slide tooling with 30-60 MPa injection pressure produces net-shape components at 200-400 shots per hour. Italpress and comparable operators deploy robotic extraction and inline trim to serve brake system manufacturers at six-sigma quality levels.
- Vacuum Die Casting:Evacuated die cavities before metal injection eliminate gas porosity for radiographic-grade safety castings. Fonderie Mora Dorno and specialized Brescia competitors have installed this capability for transmission housing contracts requiring X-ray qualification.
- Low Pressure Die Casting:Controlled metal rise from pressurized crucibles suits thicker-section structural castings with lower porosity sensitivity.
- Gravity Die Casting:Manual ladle pouring into permanent molds serves low-volume aftermarket and prototype production with minimal tooling investment.
High Pressure Die Casting dominates installed base. Vacuum Die Casting is where expansion concentrates as radiographic qualification requirements spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's National Resilience and Recovery Plan channels capital grants toward energy-efficient foundry modernization, accelerating zinc die casting capacity upgrades across northern industrial corridors while REACH enforcement redirects investment toward closed-loop recycling infrastructure.
Piedmont
Turin's automotive supplier corridor anchors OEM procurement of transmission housings and engine brackets as Stellantis reshoring programs expand. The Ministry of Enterprise conditions funding on scrap recycling quotas above 85%. Foundries in the metropolitan area consolidate around single-source contracts for powertrain zinc castings.
Lombardy
Brescia's precision casting district specializes in thin-wall geometries below 2.0 mm for integrated electric parking brake modules. ECHA substance restrictions on cadmium traces force alloy reformulation cycles. Vacuum-assisted die casting operators in the province capture Tier-1 brake manufacturer reshoring from Eastern Europe.
Emilia-Romagna
Modena and Bologna industrial zones offer underpenetrated precision casting capacity for geographic diversification from saturated northern clusters. The region's motor valley startups qualify Italian zinc casters for prototype-to-production ramps in battery enclosure mounting brackets. National Institute of Health workplace exposure protocols exceed baseline EU requirements.
Veneto
Vicenza and Verona foundry networks serve aftermarket distributors through spot market channels with minimal technical specification enforcement. Energy efficiency benchmarks under recovery plan funding accelerate furnace modernization. The region's jobbing foundries price natural gas volatility directly into spot quotes.
Lazio
Rome's administrative concentration shapes regulatory interpretation of CE marking under the EU Machinery Directive for southern Italian operators. The region lacks significant zinc casting capacity but hosts compliance consulting and certification bodies. Foundries in neighboring industrial zones reference Lazio-based technical services for PPAP submission support.
Italy Automotive Parts Zinc Die Casting Market Competitive Landscape
On the supply side, the industry is tiered between capital-intensive automated operators and legacy jobbing foundries with batch-process flexibility. Consolidated procurement by vehicle platform engineering teams displaces fragmented component sourcing. Three archetypes dominate: vertically integrated alloy-to-finish specialists, thin-wall geometry experts, and high-volume automation leaders. Competitive moves concentrate on equipment leasing arrangements and long-term supply agreement capture.
Among Italian S.p.A. structures, Bianchi Industrial S.p.A., Fonderie Mora Dorno S.p.A., and Italpress S.p.A. occupy distinct positioning vectors. Bianchi Industrial represents the vertically integrated archetype spanning alloy preparation through CNC finishing. Fonderie Mora Dorno exemplifies specialized thin-wall casting capability for porosity-sensitive applications. Italpress anchors the high-volume automation tier serving brake system manufacturers. These three entities collectively illustrate the strategic segmentation defining competitive dynamics in the Italian market.
| Leading Market Players |
|---|
| Bianchi Industrial S.p.A. |
| Fonderie Mora Dorno S.p.A. |
| Italpress S.p.A. |
| Carraro Die Casting |
| Zanardi Fonderie S.p.A. |
| Bruschi S.p.A. |
| Dynacast |
| Pace Industries |
| Ashok Minda Group |
| Others |
Supply & Pricing Matrix
Brescia's precision casting district concentrates thin-wall vacuum die casting capacity for Tier-1 brake manufacturers, translating specialized technical qualification into pricing power over commodity zinc casting suppliers. Turin's automotive supplier corridor anchors powertrain housing contracts where long-term offtake agreements insulate qualified foundries from spot metal volatility.
Pricing Analysis
Certification level (CE marking under EU Machinery Directive, REACH alloy compliance) creates the primary spread between premium and standard tiers. Contract-based long-term offtake dominates OEM and Tier-1 procurement, while spot market channels serve aftermarket distributors. Price differentiation hinges on radiographic qualification capability and scrap recycling quota compliance. Cost compression in standard-grade engine brackets is intensifying because aluminum-magnesium substitution programs threaten zinc's position in non-structural applications. Aftermarket suppliers exhibit highest price sensitivity; OEM captive foundries absorb alloy volatility through dedicated batch pricing.
Supply Chain Analysis
Extended payment terms from Tier-1 brake manufacturers and supply-chain finance facilities through Italian banking consortiums shape working capital dynamics for mid-tier foundries. Primary zinc concentrate draws from Australia, Peru, and Kazakhstan. Virgin zinc ingot and aluminum alloying additions constitute critical input dependencies. Single-source vulnerability concentrates in specialized vacuum die casting equipment sourced from German and Japanese suppliers. Distribution runs through consolidated commodity managers at domestic vehicle assemblers, displacing fragmented component sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized thin-wall casting expertise for sub-2.0 mm geometries represents the critical capability gap, with aging technician cohorts and limited apprenticeship pipelines constraining expansion beyond incumbent qualified suppliers.
For Market Incumbents: Build technical moats through vacuum die casting radiographic qualification and closed-loop alloy recycling infrastructure. Secure captive zinc supply through backward integration into scrap preparation facilities. Deepen certification investment beyond baseline REACH compliance to capture Tier-1 brake module contracts reshoring from Eastern Europe. Channel control through exclusive tooling arrangements with Stellantis platform engineering teams defends against aluminum substitution threats in chassis brackets.
For New Entrants and Emerging Players: Establish a beachhead in Emilia-Romagna's underpenetrated Modena-Bologna industrial corridor, where motor valley startups seek prototype-to-production zinc casting partners for battery enclosure hardware. Target electric vehicle thermal management bracket applications as the most penetrable segment, with qualification timelines compressed versus safety-critical brake castings. Pursue asset-light equipment leasing arrangements for multi-slide die casting lines to bypass capital barriers to OEM qualification.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because captive alloy supply and radiographic qualification capability are concentrating among three vertically integrated S.p.A. structures. Acquisition targets should display thin-wall geometry expertise or vacuum die casting installed base. Watch for EU End-of-Life Vehicle Directive recycled content threshold revisions as the signal for accelerated closed-loop infrastructure investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum Die Casting Capacity Expansion | Radiographic-grade porosity control qualifies suppliers for Stellantis transmission housing contracts. |
| Closed-Loop Alloy Recycling Investment | National Resilience and Recovery Plan grants condition funding on 85% scrap recycling quotas. |
| Multi-Slide Die Casting Automation | Real-time cavity pressure monitoring compresses labor content below offshore sourcing cost thresholds. |
| Long-Term Supply Agreement Capture | Consolidated procurement under powertrain commodity managers locks in 3-year platform commitments. |
| REACH Compliance Infrastructure | ECHA substance restrictions on cadmium traces force alloy reformulation and process requalification cycles. |
Research Methodology
The analysis maps high-pressure die casting, vacuum die casting, low-pressure operations, and gravity casting segments, each validated through Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distribution heads, and foundry operations directors. Primary fieldwork combined structured interviews with secondary validation against SEC filings of listed automotive suppliers, Italian Ministry of Enterprise recovery plan disbursement records, ECHA substance restriction databases, and IHS Markit vehicle production data. Bottom-up capacity assessments across Turin, Brescia, and Emilia-Romagna clusters were triangulated with top-down zinc alloy consumption estimates.
Model assumptions held fixed the current REACH enforcement trajectory and National Resilience and Recovery Plan funding availability, while varying natural gas tariff regimes and aluminum alloy substitution rates across sensitivity scenarios. Segmentation dimensions included manufacturing technology tier, end-user category (OEM captive, Tier-1 contract, aftermarket spot), application type (powertrain, brake, EV thermal), and regional production cluster. CAGRs were derived from installed capacity utilization trends and platform lifecycle commitments. Forecast inputs incorporated Stellantis reshoring program announcements and Tier-1 brake manufacturer supplier requalification timelines.
Stress conditions across energy cost volatility bands, ECHA substance restriction expansion scenarios, and aluminum alloy price differential ranges were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and baseline regulatory trajectories. Macroeconomic contraction, accelerated EU End-of-Life Vehicle Directive revisions, or breakthrough magnesium-aluminum alloy casting technologies would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Differential Housing Market
Automotive Parts
Spare Wheel Carrier Market
Automotive Parts
Philippines Automotive Lubricants Market
Automotive Parts
Automotive Oil Seals Market
Automotive Parts
Transfer Case Market
Automotive Parts
Automotive Pneumatic Actuators Market
Automotive Parts
Cheetah Friction Reduction Technologies Market
Automotive Parts
Light Vehicle Exhaust and Emissions Systems Market
Automotive Parts
US Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Bellows Market
Automotive Parts
Automotive Trim Part Market
Automotive Parts
South America Gear Market
Automotive Parts
Automotive Brake Actuator Market
Automotive Parts
Two-Wheeler Lubricants Market
Automotive Parts
Automotive Brake Shims Market
Automotive Parts
Electric Vehicle Aluminum Electric Drive Parts Market