
 Electric Axle Drive Systems Market | 2026-2036
Electric Axle Drive Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Axle Drive Systems Market Analysis
Project finance and green leasing structures for commercial fleet electrification is reconfiguring competitive access across the Electric Axle Drive Systems Market, lowering capital barriers for mid-tier suppliers. GKN Automotive leverages its integrated eDrive platform expertise to anchor high-volume contracts with European OEMs. Schaeffler AG sustains R&D intensity in bearing-integrated motor designs that reduce package weight. ZF Friedrichshafen AG dominates the commercial vehicle segment through its CeTrax and AxTrax product families.
Electric axle drive systems integrate high-torque electric motors, reduction gears, and power electronics into a single axle-mounted module, typically delivering continuous power from 75 kW to 250 kW for direct wheel propulsion without traditional driveline components. The primary purpose is to maximize packaging efficiency and energy recovery in battery-electric and hybrid platforms. Battery Electric Drive leads product type segmentation due to its share of OEM platform engineering investment, while Full Electric Drive represents the fastest-expanding category as dedicated EV architectures replace converted internal-combustion platforms. Passenger Vehicles anchor end-user demand volume, though Fleet Vehicles concentrate the highest per-unit margin pools through customized duty-cycle optimization.
The EPA tailpipe standards and NHTSA CAFE regulations in the United States mandate fleet-average CO2 reductions that compel OEMs to source integrated e-axle systems rather than retrofit internal-combustion platforms. EMA and REACH compliance in Europe shapes material selection for motor magnets and thermal interface compounds, directly affecting supplier qualification timelines. Stakeholders must monitor how China's MIIT dual carbon enforcement and evolving GB standards for electric commercial vehicles redirect procurement toward domestically certified axle platforms, reshaping export eligibility for non-Chinese suppliers.
Market Dynamics
The Electric Axle Drive Systems Market is experiencing structural compression as integrated e-axle platforms replace discrete motor-gearbox assemblies, forcing suppliers to consolidate power electronics, thermal management, and mechanical reduction into single-source modules or exit procurement lists.
Growth Catalysts
- EU CO2 fleet standards:Binding emissions caps on automotive OEMs mandate electrified powertrains, accelerating integrated e-axle procurement for passenger and commercial vehicle platforms across Germany, France, and Italy.
- China's NEV credit system:Mandatory new energy vehicle production quotas force domestic and joint-venture manufacturers to source certified electric axle systems from qualified Tier-1 suppliers.
- Fleet electrification mandates:Urban transit authorities and logistics operators in California, New York, and London specify zero-emission vehicle requirements that favor complete axle-drive solutions over retrofit kits.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium processing capacity concentrates in China's Inner Mongolia and Jiangxi provinces, exposing motor manufacturers to export quota volatility and price spikes.
- Silicon carbide substrate shortage:Limited 200mm SiC wafer fabrication capacity constrains inverter integration within e-axle modules, extending lead times for high-efficiency variants.
- REACH substance restrictions:ECHA classification of certain thermal interface compounds as substances of very high concern forces reformulation of motor cooling systems, delaying supplier qualification cycles.
Strategic Opportunities
- India's PLI scheme for auto components:Production-linked incentives for advanced automotive technology manufacturing attract e-axle assembly investments serving domestic OEMs and export markets.
- Wireless power transfer integration:Convergence of dynamic inductive charging infrastructure with onboard e-axle power electronics enables opportunity-charging for commercial fleets without depot infrastructure.
- Second-life battery repurposing:Retired electric bus and truck battery packs provide cost-competitive stationary storage for e-axle test facilities and manufacturing plants.
Industry Challenges
- Power electronics thermal management expertise:Shortage of engineers skilled in integrated cooling of silicon carbide inverters and high-torque motor windings extends product development cycles.
- Functional safety certification:ISO 26262 ASIL-D compliance for axle-mounted drive systems requires extensive fault analysis documentation, stretching validation timelines by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Axle Drive Systems Market |
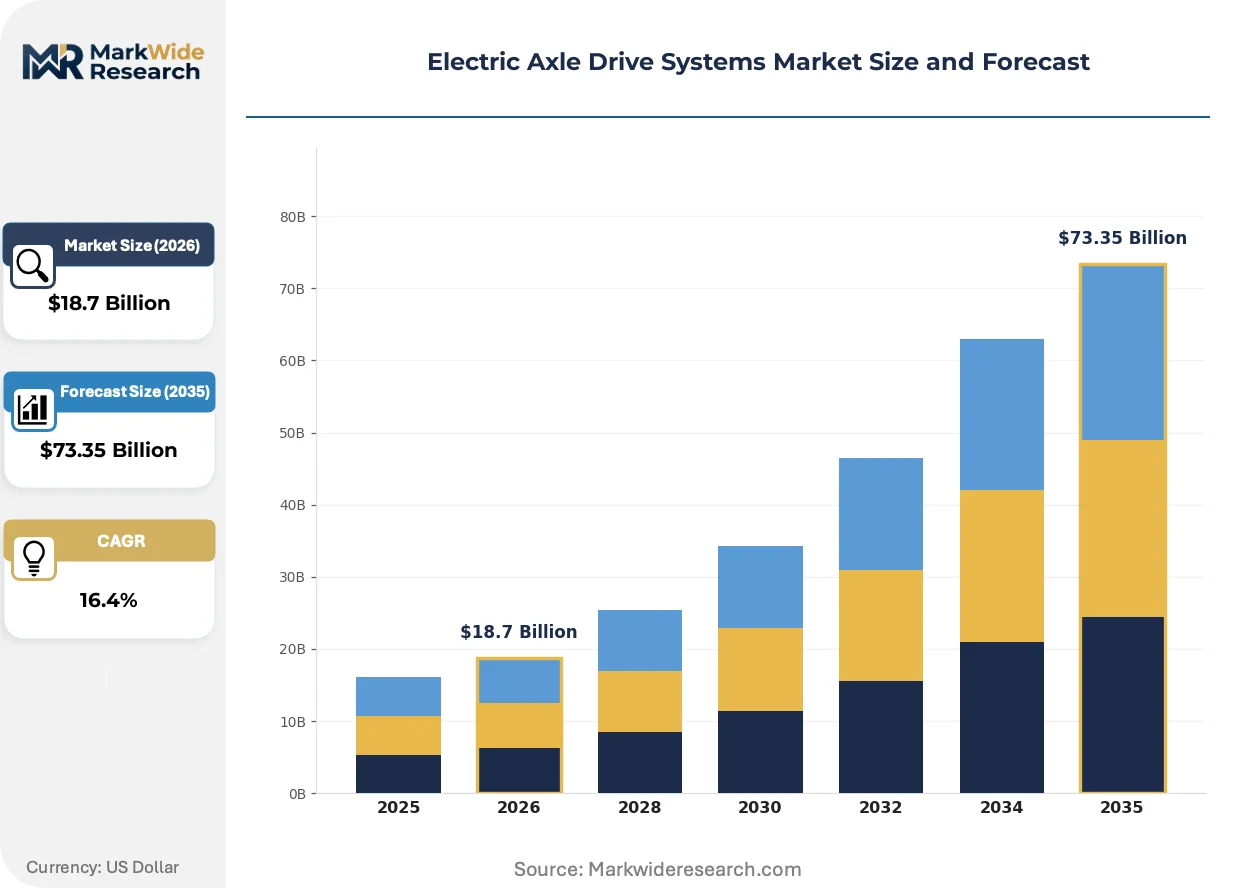
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Electric Drive, Hybrid Drive, Full Electric Drive, Plug-in Hybrid Drive End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Fleet Vehicles Installation: Original Equipment Manufacturer, Aftermarket, Custom Installations, Retrofits Technology: Permanent Magnet Synchronous Motor, Induction Motor, Switched Reluctance Motor, Others |
| Companies Covered | GKN Automotive, Schaeffler AG, ZF Friedrichshafen AG, Robert Bosch GmbH, Nidec Corporation, BorgWarner Inc., American Axle & Manufacturing, Continental AG, Dana Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Axle Drive Systems Market Emerging Trajectories
Electrification architecture decisions made during 2024-2026 platform cycles will lock in e-axle supplier relationships for decade-long production runs, intensifying competition around system efficiency and manufacturing scale.
Hairpin winding technology is collapsing the performance gap between conventional round-wire motors and expensive direct-oil-cooled alternatives. Commercial vehicle OEMs in Germany and the United States are adopting hairpin stators for 150-250 kW continuous-duty applications. This winding approach is collapsing total motor length by 20-30% while maintaining thermal margins, enabling packaging within existing axle housings without suspension redesign.
China's MIIT dual carbon enforcement and evolving GB standards for electric commercial vehicles are redirecting procurement toward domestically certified axle platforms. Non-Chinese suppliers face extended homologation timelines and joint-venture partnership requirements. European and Korean manufacturers are responding by licensing production to Chinese Tier-1 partners rather than exporting complete systems.
Fleet operators are consolidating supplier relationships around full-lifecycle cost guarantees rather than unit procurement. Logistics providers in California and the Netherlands now contract for guaranteed cost-per-kilometer over 8-10 year service terms, transferring operational risk to e-axle suppliers. This model compresses supplier margins but locks in multi-year volume commitments and aftermarket service revenue streams.
Electric Axle Drive Systems Market Segmentation
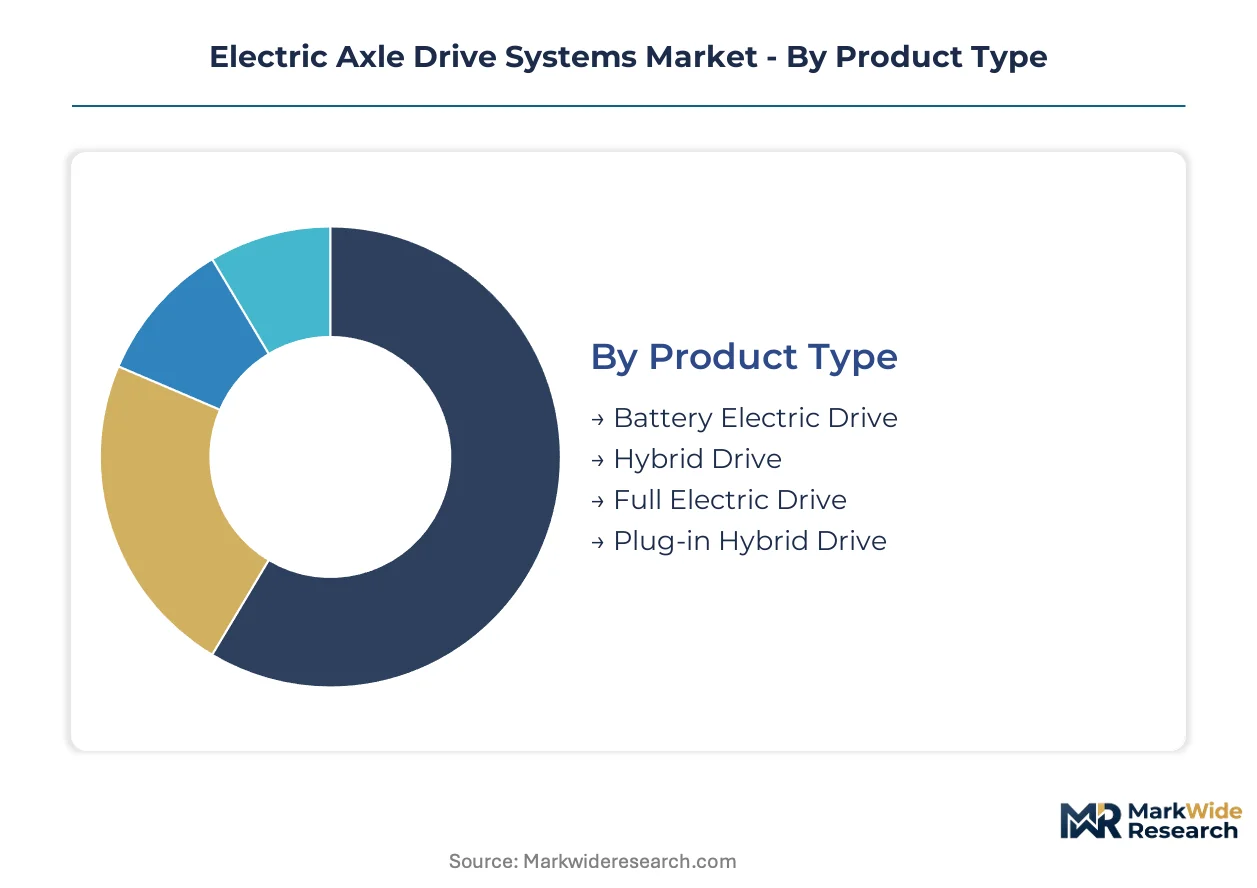
Segmentation in electric axle drive systems reveals how powertrain integration requirements diverge across vehicle architectures and duty cycles. Platform electrification strategies vary dramatically between passenger OEMs optimizing for range efficiency and fleet operators prioritizing total cost of ownership over decade-long service intervals.
Product Type:
The use-case spectrum spans converted combustion platforms through dedicated native electric architectures, with each product type demanding distinct motor-gearbox integration density and thermal management specifications.
- Battery Electric Drive:Systems engineered for dedicated BEV platforms integrate high-torque motors with single-speed reduction gears and onboard inverters delivering 150-250 kW continuous output. OEM platform engineering investment concentrates here, particularly in Germany's automotive corridor where Tier-1 suppliers anchor production capacity for European programs facing EU CO2 fleet standards.
- Full Electric Drive:Native electric axle modules eliminate mechanical driveline components entirely, enabling flat-floor packaging and maximized battery volume. Demand is expanding most quickly as dedicated EV architectures displace converted internal-combustion platforms, with China's NEV credit system accelerating domestic OEM procurement of fully integrated systems.
- Hybrid Drive:Axle-mounted electric assist units supplement combustion powertrains through P2 or P3 integration configurations. Japanese and Korean OEMs favor this architecture for transitional platform economics.
- Plug-in Hybrid Drive:Dual-mode systems combine electric-only axle propulsion with engine-coupled hybrid operation, requiring complex clutch mechanisms and dual thermal management circuits. European premium manufacturers deploy these for regulatory compliance during platform transition periods.
Established volume favors Battery Electric Drive; emerging adoption favors Full Electric Drive.
End User:
Customer economics separate individual ownership models from commercial utilization patterns, with fleet operators demanding guaranteed lifecycle cost structures that reshape supplier contract terms.
- Passenger Vehicles:Individual ownership platforms prioritize packaging efficiency and NVH reduction over absolute durability. OEMs in Germany, France, and Italy source integrated e-axle systems to meet binding EU emissions caps on automotive fleets.
- Fleet Vehicles:Logistics and urban transit operators specify zero-emission requirements that favor complete axle-drive solutions over retrofit kits. California, New York, and London procurement mandates concentrate the highest per-unit margin pools through customized duty-cycle optimization and 8-10 year service term guarantees.
- Commercial Vehicles:Heavy-duty applications demand continuous-duty thermal management and reinforced reduction gearing for stop-start urban operations. ZF Friedrichshafen AG dominates this segment through dedicated product families.
- Two-Wheelers:Compact hub-mounted and mid-mounted drive systems serve electric motorcycle and scooter platforms, particularly in Indian and Southeast Asian urban mobility markets.
Passenger Vehicles anchor absolute demand volume; Fleet Vehicles command premium pricing through operational risk transfer.
Installation:
Supply channel configuration distinguishes factory-integrated platforms from post-production conversion opportunities, with regulatory compliance timelines varying dramatically across installation modes.
- Original Equipment Manufacturer:Factory-integrated e-axle platforms lock in supplier relationships for decade-long production runs, with electrification architecture decisions made during 2024-2026 platform cycles determining procurement lists.
- Aftermarket:Replacement and upgrade channels serve existing electric vehicle populations, requiring diagnostic compatibility and standardized mounting interfaces. This segment climbs the fastest as early BEV cohorts exit warranty coverage.
- Custom Installations:Specialized vehicle builders and upfitters commission tailored axle configurations for vocational applications including refuse collection and airport ground support.
- Retrofits:Conversion of existing internal-combustion chassis faces extended homologation timelines and joint-venture partnership requirements, particularly under China's evolving GB standards for electric commercial vehicles.
OEM integration captures platform economics; aftermarket channels gain share as installed base matures.
Technology:
Motor topology selection determines efficiency maps, rare earth material exposure, and manufacturing capital requirements, with hairpin winding advances collapsing historical performance-cost tradeoffs.
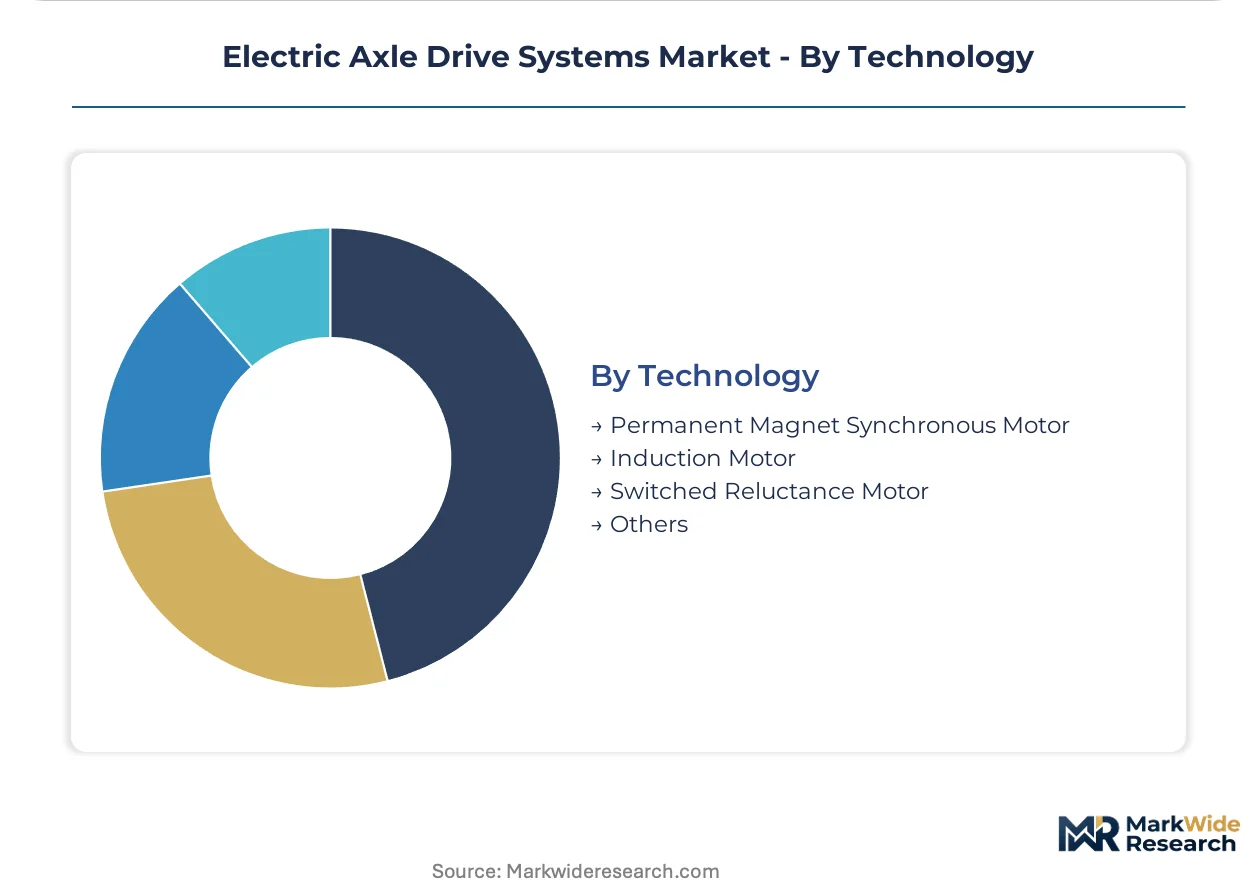
- Permanent Magnet Synchronous Motor:Neodymium-iron-boron rotor configurations deliver highest power density and efficiency across variable speed operation. Rare earth magnet supply concentration in China's Inner Mongolia and Jiangxi provinces exposes manufacturers to export quota volatility.
- Induction Motor:Copper rotor designs eliminate rare earth dependency while accepting modest efficiency penalties at partial load. Tesla and select European OEMs specify these for cost-optimized platform variants.
- Switched Reluctance Motor:Magnet-free topologies suit high-speed applications with simplified thermal management, though torque ripple challenges limit passenger vehicle adoption.
- Others:Emerging axial-flux and transverse-flux architectures promise step-change power density improvements for next-generation integrated axle modules.
Permanent Magnet Synchronous Motor dominates current procurement; Induction Motor gains traction as supply security priorities intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in electric axle drive systems reveal Germany and China as net exporters of integrated e-axle platforms, while the United States and India remain import-dependent for high-torque motor-gearbox assemblies. Trade flows concentrate along automotive manufacturing corridors where Tier-1 supplier ecosystems anchor production capacity.
China
Domestic OEM procurement of integrated e-axle platforms accelerates under MIIT dual carbon enforcement and the NEV credit system. GB standards for electric commercial vehicles redirect procurement toward domestically certified axle platforms, forcing European and Korean manufacturers into joint-venture partnerships. Production clusters in Shanghai and the Yangtze River Delta anchor capacity for BYD, NIO, and Xpeng platform programs.
Germany
EU CO2 fleet standards bind automotive OEMs to electrified powertrains, accelerating integrated e-axle procurement for passenger and commercial vehicle platforms. KBA homologation requirements shape supplier qualification timelines for motor-gearbox assemblies. The automotive manufacturing corridor between Stuttgart and Munich concentrates Tier-1 supplier production capacity for BMW, Mercedes-Benz, and Volkswagen Group programs.
United States
EPA tailpipe standards and NHTSA CAFE regulations mandate fleet-average CO2 reductions that compel OEMs to source integrated e-axle systems. Fleet electrification mandates in California and New York specify zero-emission vehicle requirements favoring complete axle-drive solutions. Manufacturing investment concentrates in Michigan and the Southeast, where suppliers anchor production for Ford, General Motors, and Stellantis EV platforms.
India
The PLI scheme for auto components attracts e-axle assembly investments serving domestic OEMs and export markets. BIS certification requirements for electric vehicle components extend qualification timelines for imported motor-gearbox systems. Industrial corridors in Tamil Nadu and Maharashtra concentrate supplier manufacturing for Tata Motors, Mahindra, and Ashok Leyland electrification programs.
Japan
METI carbon neutrality roadmaps accelerate OEM procurement of integrated e-axle platforms for hybrid and battery-electric architectures. JIS standards for electric vehicle components shape motor-gearbox integration specifications. Manufacturing clusters in Aichi Prefecture and the Kansai region anchor production capacity for Toyota, Honda, and Nissan electrification platforms.
Electric Axle Drive Systems Market Vendor Landscape
On the supply side, the industry is consolidating around integrated e-axle platforms that displace discrete motor-gearbox assemblies, forcing suppliers to consolidate power electronics, thermal management, and mechanical reduction into single-source modules. Tier-1 automotive suppliers dominate procurement lists through decade-long platform relationships. Two strategic archetypes prevail: diversified automotive conglomerates leveraging scale across powertrain portfolios, and specialized e-drive specialists concentrating R&D in motor-gearbox integration. Competitive moves center on capacity expansion in China and Germany, plus technology licensing partnerships to navigate domestic content requirements.
Among diversified automotive conglomerates, ZF Friedrichshafen AG, Robert Bosch GmbH, and Continental AG occupy positions spanning integrated e-axle platforms through full powertrain portfolios. These Germany-based entities exemplify the scale-driven archetype, anchoring high-volume supply relationships with European and North American OEMs. Specialized e-drive representation includes GKN Automotive and Nidec Corporation, which sit within the focused technology tier emphasizing motor-gearbox integration density. BorgWarner Inc. and Dana Incorporated represent the North American competitive set, while Schaeffler AG anchors bearing-integrated motor expertise within the European supplier base. American Axle & Manufacturing exemplifies the commercial vehicle specialist archetype serving fleet electrification programs.
| Leading Market Players |
|---|
| GKN Automotive |
| Schaeffler AG |
| ZF Friedrichshafen AG |
| Robert Bosch GmbH |
| Nidec Corporation |
| BorgWarner Inc. |
| American Axle & Manufacturing |
| Continental AG |
| Dana Incorporated |
| Others |
Supply Flow & Price Mechanics
Rare earth magnet export quota volatility from China's Inner Mongolia and Jiangxi provinces determines both the pricing spread between permanent magnet and induction motor axle variants and the geographic reconfiguration of supplier manufacturing footprints. Tier-1 suppliers absorb magnet price spikes through long-term offtake contracts while mid-tier competitors face margin compression that accelerates induction motor R&D investment.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for integrated e-axle platforms, with premium-mid-economy pricing differentiation driven by ISO 26262 ASIL-D certification tier and volume scale commitments. Pricing pressure stems from silicon carbide substrate shortages extending lead times for high-efficiency variants, compressing margins on premium tiers. Fleet operators demonstrate lowest price sensitivity due to total cost of ownership guarantees, while aftermarket retrofit channels face acute cost compression from homologation burden.
Supply Chain Analysis
Neodymium-iron-boron magnet feedstock concentrates in China, with silicon carbide wafer fabrication anchored in Germany and the United States. E-axle assembly draws from copper winding wire sourced through Chilean and Peruvian mining operations, with thermal interface compounds formulated under ECHA REACH restrictions. Single-source vulnerability runs through China's rare earth processing dominance. Distribution runs through Tier-1 supplier direct OEM relationships with limited aftermarket channel penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform electrification decisions fragmenting across passenger, commercial, and two-wheeler architectures create specialist supplier niches that favor focused motor-gearbox integrators over diversified conglomerates.
For Market Incumbents: Insulate high-volume European OEM relationships through captive magnet supply agreements with Chinese processors, while accelerating hairpin winding capacity expansion in Germany's automotive corridor to defend against induction motor substitution threats from Tesla and cost-optimized platform variants.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized e-axle assembly segment serving Tata Motors and Mahindra electrification programs, exploiting BIS certification gaps that delay established European supplier entry. Target wireless power transfer integration partnerships with commercial fleet operators in California and the Netherlands as a differentiated go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized e-drive specialists with proven motor-gearbox integration density over diversified automotive conglomerates facing powertrain portfolio complexity. Long-term viability hinges on silicon carbide inverter thermal management expertise and ISO 26262 ASIL-D certification velocity. Monitor China's MIIT dual carbon enforcement intensity as the inflection signal for domestic content requirement tightening.
| Strategic Initiative | Industry Significance |
|---|---|
| Hairpin Winding Manufacturing Scale-Up | Enables 20-30% motor length reduction for existing axle housing compatibility without suspension redesign. |
| Silicon Carbide Inverter Integration | Resolves substrate shortage constraints while capturing efficiency premiums from ZF Friedrichshafen AG's CeTrax product roadmap. |
| Joint Venture Localization in China | Satisfies GB standards compliance and MIIT dual carbon procurement redirection through BYD and NIO platform partnerships. |
| Wireless Power Transfer Convergence | Captures commercial fleet opportunity-charging demand in California and London zero-emission mandate jurisdictions. |
| Functional Safety Certification Investment | Accelerates ASIL-D validation timelines to secure decade-long OEM platform relationships locked in 2024-2026 architecture cycles. |
Methodological Framework
Desk research of vehicle production databases, IHS Markit registration data, customs and trade flow records, and SEC filings from automotive Tier-1 suppliers preceded structured interviews with OEM platform engineers, Tier-1 supplier procurement leads, fleet operator technical directors, and aftermarket distribution channel managers. Primary intelligence combined with secondary validation through bottom-up segment sizing and top-down market reconciliation.
Assumptions around EU CO2 fleet standard enforcement trajectory, China's NEV credit system quota evolution, and silicon carbide wafer fabrication capacity expansion were held fixed across baseline scenarios while rare earth magnet export quota volatility and REACH substance restriction timelines were stress-tested. The analytical framework modeled vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions across the projection horizon. CAGRs derived from segment-level volume buildups incorporating OEM platform launch calendars and fleet electrification mandate compliance deadlines.
Stress conditions across neodymium price bands, SiC substrate lead time extensions, and ECHA SVHC classification expansions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from regulatory enforcement intensity shifts or technology substitution accelerants. Cross-checking against IEA electric vehicle deployment benchmarks and automotive supplier order backlog disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
APAC E-Bikes Market
Electric Vehicles
France Solar E-Bike Market
Electric Vehicles
South America Electric Bus Battery Pack Market
Electric Vehicles
United Kingdom E-Bike Market
Electric Vehicles
EV PTC Heaters Market
Electric Vehicles
Asia Pacific Electric Commercial Vehicles Market
Electric Vehicles
Italy Hybrid Electric Vehicle Battery Market
Electric Vehicles
Foldable Electric Car Market
Electric Vehicles
Nordic E-Bike Market
Electric Vehicles
Two-Wheeled Electric Vehicle Battery Market
Electric Vehicles
Electric Loader Rickshaw Market
Electric Vehicles
Europe Electric Vehicle Thermal Management System Market
Electric Vehicles
Electric Van Market
Electric Vehicles
South America Electric Bus Market
Electric Vehicles
UK Electric Bus Battery Pack Market
Electric Vehicles
North America Electric Vehicle Battery Market