
 South America Electric Bus Market | 2026-2036
South America Electric Bus Market Size, Share, and Industry Trends Forecast 2026-2036
South America Electric Bus Market Analytics
Brazilian battery pack assembly capacity is pivoting toward bus-scale lithium-ion configurations. BYD Auto leverages its Campinas manufacturing base to supply municipal operators across São Paulo state. Zhengzhou Yutong Bus anchors its regional presence through localized chassis adaptation for Andean altitude performance. Scania competes on hybrid-electric architectures that bridge infrastructure gaps in secondary Brazilian cities.
A South America electric bus is a zero-emission or low-emission road vehicle designed for mass transit, typically powered by lithium-ion battery packs exceeding 250 kWh or hydrogen fuel cell stacks, with regenerative braking systems and conductive or wireless charging interfaces. Battery electric bus configurations dominate procurement volumes where grid reliability permits depot charging, while hybrid electric bus variants sustain deployment in mountainous Andean corridors lacking charging infrastructure. Public transport end users command the largest share of firm orders, though government fleet electrification programs in Chile and Colombia are generating parallel demand streams with distinct procurement timelines.
ANFAVEA, Brazil's automotive industry association, coordinates emission certification timelines with PROCONVE standards that mandate progressive nitrogen oxide reductions. Chile's Ministry of Transport enforces fleet electrification quotas through Santiago's Zona de Bajas Emisiones framework, restricting diesel bus access to central metropolitan areas. Colombia's Ministry of Mines and Energy structures power purchase agreements that stabilize electricity costs for depot charging operators. Stakeholders must monitor how Andean grid interconnection projects alter the economic viability of battery electric versus fuel cell configurations across Peruvian and Ecuadorian transit markets.
Market Dynamics
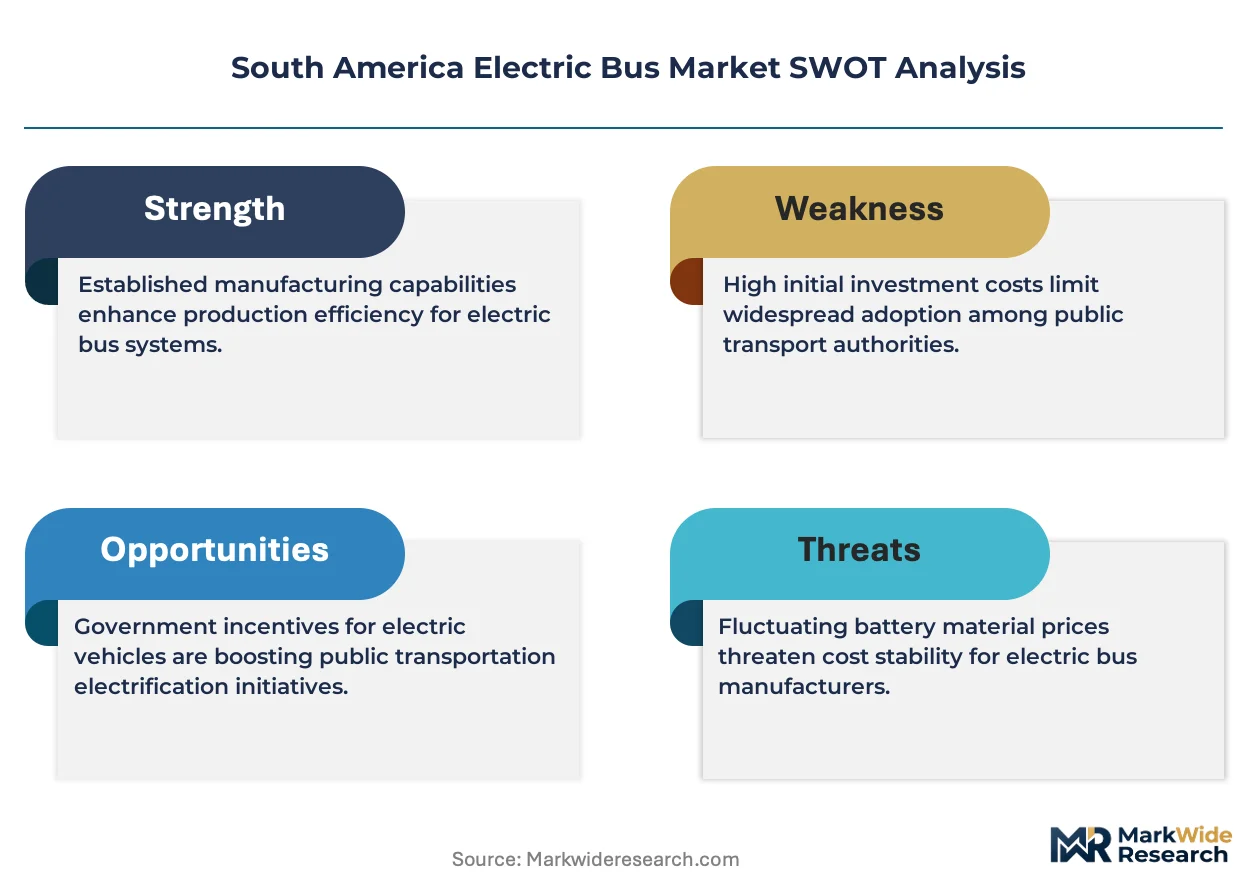
PROCONVE P-8 emission standards are compressing diesel bus replacement timelines across Brazilian metropolitan corridors, forcing municipal transit authorities to accelerate zero-emission procurement schedules while depot charging infrastructure struggles to match fleet expansion velocity.
Growth Catalysts
- Santiago's Zona de Bajas Emisiones:Chile's Ministry of Transport enforces fleet electrification quotas that restrict diesel bus access to central metropolitan areas, generating firm order pipelines for battery electric configurations.
- Bioelectricity integration policies:Brazil's national framework stabilizes renewable electricity costs for depot charging operators, improving total cost of ownership calculations against diesel alternatives.
- Transantiago network renewal:Chile's flagship transit system generates concentrated demand for articulated and standard electric buses with localized chassis specifications for Andean altitude performance.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack assembly capacity in Brazil depends on imported cell supply from East Asian manufacturers, exposing procurement timelines to maritime logistics volatility.
- Andean grid interconnection gaps:Peruvian and Ecuadorian transit markets lack reliable depot charging infrastructure, forcing continued reliance on hybrid-electric architectures despite higher per-unit costs.
- PROCONVE certification timelines:ANFAVEA coordination of nitrogen oxide reduction mandates creates regulatory friction for manufacturers adapting existing diesel platforms to electric drivetrains.
Strategic Opportunities
- Colombian government fleet programs:Ministry of Mines and Energy power purchase agreements create stable electricity cost structures for municipal operators in Bogotá and Medellín corridors previously underserved by electric bus deployment.
- Fuel cell convergence:Hydrogen fuel cell stacks paired with battery electric architectures address range limitations in mountainous secondary Brazilian cities beyond São Paulo's metropolitan core.
- Wireless charging corridors:Conductive charging interfaces at route terminus points enable opportunity charging for high-frequency urban routes without full depot infrastructure investment.
Industry Challenges
- High-voltage technician scarcity:Bus-scale lithium-ion configurations exceeding 250 kWh require specialized maintenance workforce development that outpaces regional vocational training program expansion.
- Regenerative braking integration:Legacy fleet management software in Colombian and Peruvian transit authorities lacks compatibility with electric drivetrain telemetry, forcing parallel system operation during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Electric Bus Market |
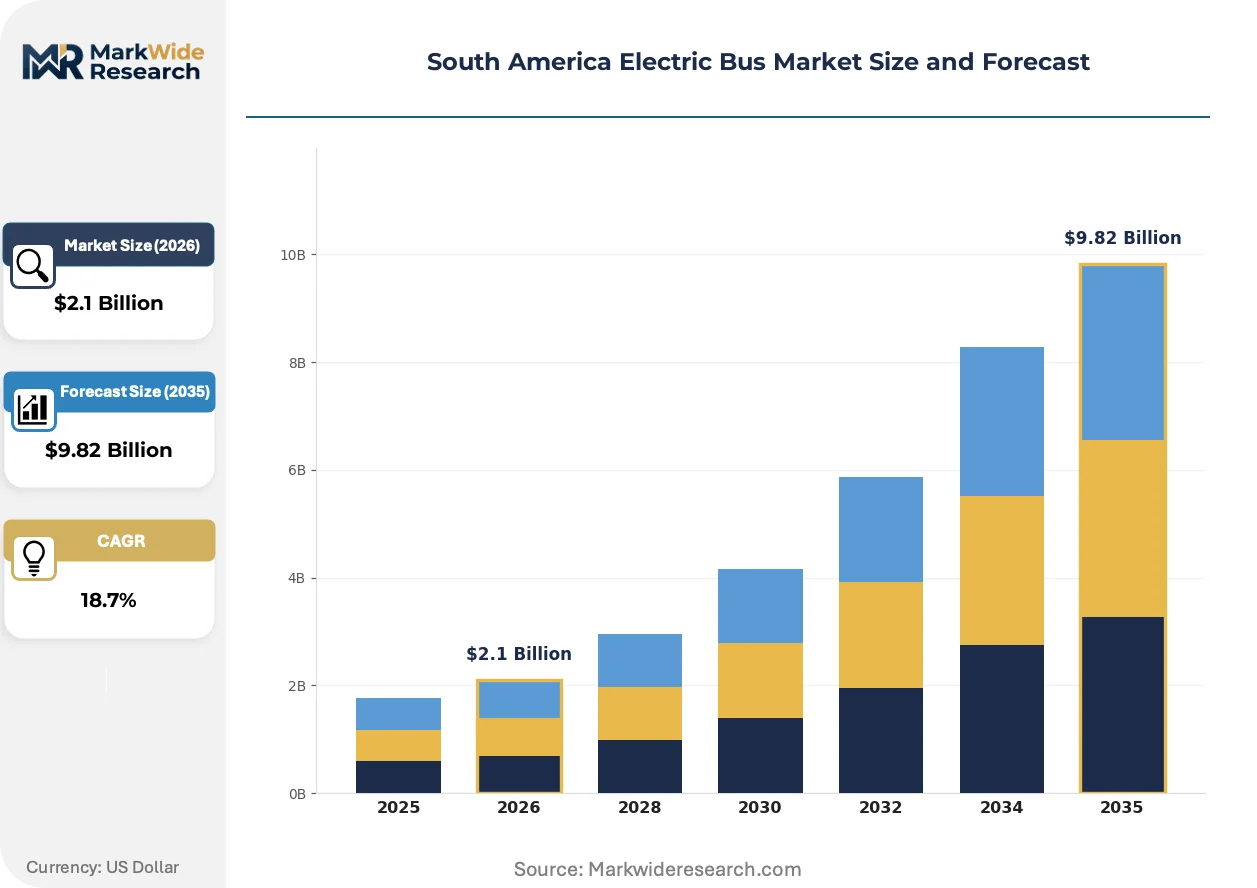
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $9.82 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Electric Bus, Hybrid Electric Bus, Fuel Cell Bus, Others End User: Public Transport, Private Companies, Government Fleets, Educational Institutions Power Rating: Medium Power, High Power, Low Power, Ultra High Power Charging Infrastructure: Rapid Charging Stations, Normal Charging Points, Wireless Charging Solutions, Destination Charging |
| Companies Covered | BYD Auto, Foton, Zhengzhou Yutong Bus, AB VOLVO, Scania, Irizar, Iveco, King Long United Automotive Industry, Zhongtong Bus Holding, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Electric Bus Market Evolving Landscape
Regenerative braking systems are converging with wireless charging interfaces to reshape how South American transit authorities calculate route viability and infrastructure investment requirements for zero-emission fleet conversion.
Battery thermal management systems are converging with altitude-compensated power electronics to enable consistent performance across São Paulo's coastal plains and Santiago's 500-meter-plus elevation corridors. Municipal operators in both cities are specifying these integrated packages for new procurements. The convergence is compressing supplier qualification timelines as manufacturers must demonstrate simultaneous thermal and altitude performance rather than sequential certification.
Chile's Zona de Bajas Emisiones framework is tightening diesel bus access restrictions annually through 2035. The policy is forcing rapid fleet turnover in Santiago's central business district. Articulated electric bus configurations are absorbing the majority of displacement volume as operators prioritize high-capacity replacements for restricted diesel units.
Service contract unbundling is separating vehicle procurement from charging infrastructure ownership across Brazilian municipal authorities. São Paulo state operators are purchasing buses while third-party energy utilities install and maintain depot charging systems. The split-responsibility model is most visible in Campinas and Sorocaba metropolitan expansions where electricity distributors compete for long-term charging service agreements.
South America Electric Bus Market Segmentation
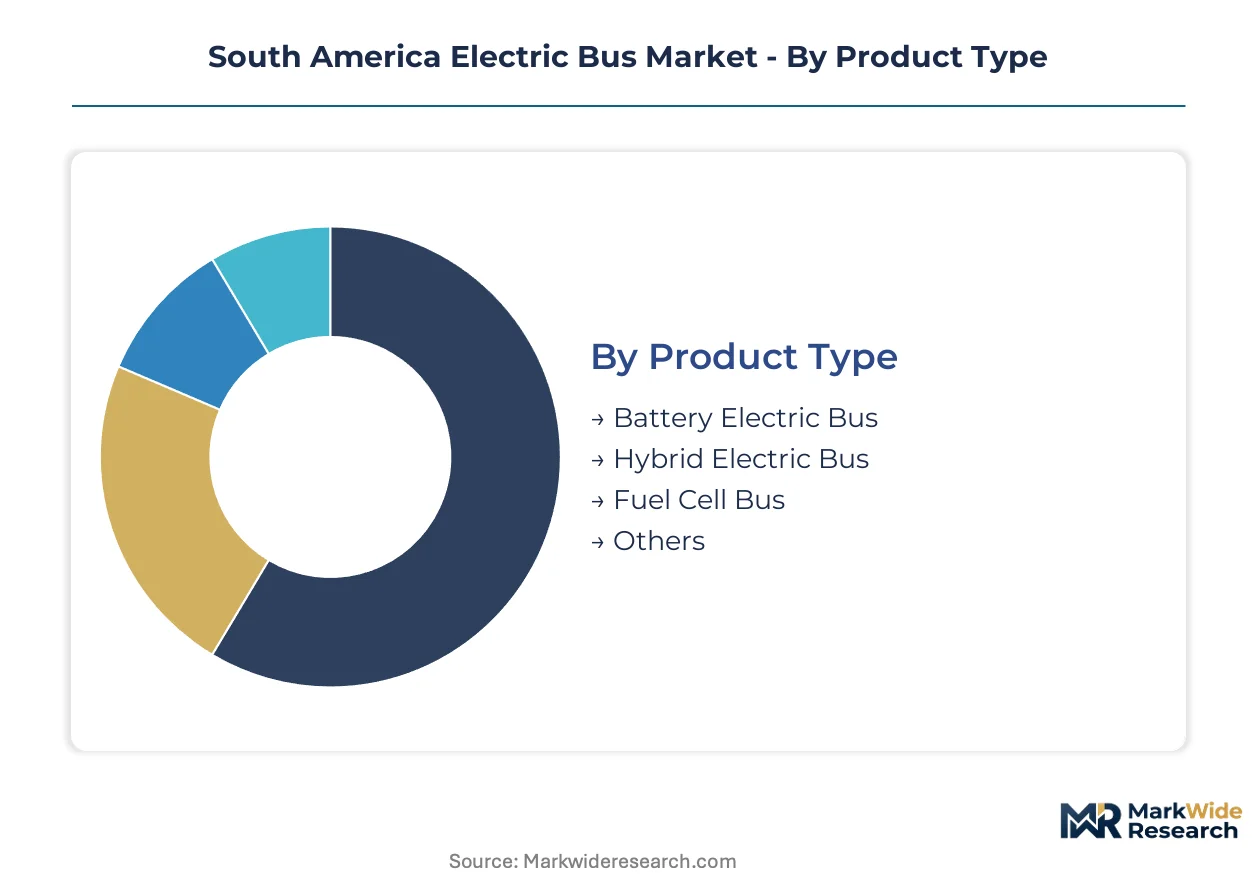
Segmentation reveals how PROCONVE P-8 certification timelines and ANFAVEA coordination requirements concentrate procurement around specific powertrain configurations. Transit authorities prioritize segments where depot charging infrastructure and maintenance workforce development align with emission mandate deadlines.
Product Type:
ANFAVEA emission certification applies differential pressure across battery electric, hybrid, and fuel cell architectures, with PROCONVE P-8 nitrogen oxide mandates accelerating zero-emission qualification timelines for some configurations over others.
- Battery Electric Bus:Lithium-ion battery packs exceeding 250 kWh power these vehicles, with regenerative braking systems and conductive charging interfaces. São Paulo's metropolitan corridor concentrates demand as municipal operators replace diesel fleets ahead of PROCONVE deadlines. Depot charging infrastructure gaps in secondary Brazilian cities constrain deployment velocity despite total cost of ownership advantages.
- Hybrid Electric Bus:Combines downsized internal combustion engines with electric drivetrains, bridging infrastructure gaps where grid reliability remains insufficient. Scania competes aggressively in this segment across mountainous Andean corridors and secondary Brazilian cities beyond São Paulo's electrified core. Operators accept higher per-unit costs to maintain route flexibility during transition periods.
- Fuel Cell Bus:Hydrogen fuel cell stacks paired with battery buffers deliver extended range for high-elevation corridors. Chile's Ministry of Transport evaluates these for Santiago's Transantiago network renewal where altitude performance and rapid refueling outweigh depot charging investments.
- Others:Compressed natural gas-electric hybrids and trolleybus retrofits serve niche applications in Colombian and Peruvian transit authorities with legacy infrastructure investments.
Leading the category by volume: Battery Electric Bus. Expanding most quickly: Fuel Cell Bus as hydrogen supply chains mature in Chile and Brazil.
End User:
Procurement authority fragmentation creates divergent timeline pressures, with public transport operators facing immediate fleet replacement mandates while government fleets navigate budget cycle constraints.
- Public Transport:Municipal transit authorities in São Paulo state and Santiago's Transantiago network generate concentrated order volumes. These operators specify altitude-compensated power electronics and thermal management packages for high-frequency urban routes.
- Private Companies:Corporate shuttle services and mining sector transport operators in Chile and Peru adopt electric configurations for emissions compliance and operational cost reduction. Procurement timelines align with contract renewal cycles rather than regulatory deadlines.
- Government Fleets:Chile's Ministry of Transport and Colombia's Ministry of Mines and Energy structure parallel demand streams through fleet electrification programs. Power purchase agreements stabilize electricity costs for depot charging operators in Bogotá and Medellín corridors.
- Educational Institutions:University and school district transport services in Brazilian state capitals pilot electric configurations, though procurement volumes remain limited by budget constraints and route predictability requirements.
Dominant procurement source: Public Transport. Steepest expansion trajectory: Government Fleets as Chile and Colombia accelerate quota enforcement.
Power Rating:
Grid interconnection capacity and route topography dictate power specification distributions, with Andean altitude performance requirements compressing demand toward higher-output configurations.
- High Power:Exceeds 350 kWh battery capacity or equivalent fuel cell output, specified for articulated bus configurations serving high-ridership corridors. Santiago's Zona de Bajas Emisiones enforcement drives displacement of diesel articulated units with these specifications.
- Medium Power:250-350 kWh configurations balance range and charging infrastructure requirements for standard urban routes. São Paulo state operators specify these for metropolitan corridor services with established depot charging.
- Low Power:Sub-250 kWh systems serve shuttle and feeder route applications with predictable duty cycles and opportunity charging access.
- Ultra High Power:Exceeds 450 kWh or fuel cell-battery hybrid architectures for extended-range intercity and mountainous corridor applications. Brazilian bioelectricity integration policies improve total cost of ownership calculations for these premium configurations.
Highest procurement volume: High Power. Gaining share fastest: Ultra High Power as range anxiety diminishes with charging infrastructure expansion.
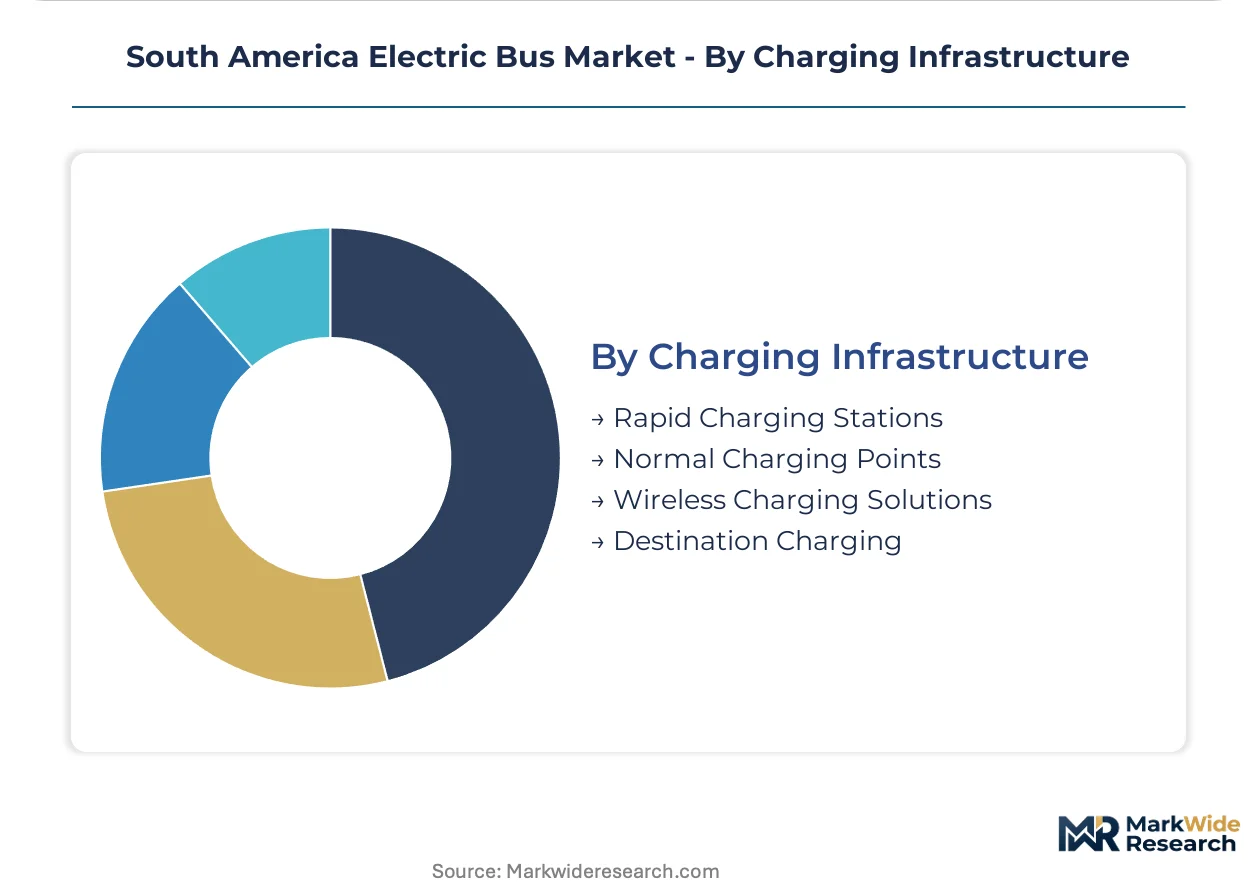
Charging Infrastructure:
Ownership model unbundling separates vehicle procurement from charging asset investment, with electricity distributors competing for long-term service agreements in Brazilian metropolitan expansions.
- Rapid Charging Stations:High-power conductive systems enable partial state-of-charge operation for high-frequency routes. Campinas and Sorocaba metropolitan operators deploy these at route terminus points to extend daily range without full depot infrastructure.
- Normal Charging Points:Standard depot charging infrastructure dominates Brazilian municipal procurement where overnight dwell time accommodates slower charge rates. Third-party energy utilities install and maintain these systems under split-responsibility contracts.
- Wireless Charging Solutions:Inductive systems at bus stops and terminals enable opportunity charging without driver intervention. Santiago's Transantiago network renewal evaluates these for central business district routes with minimal dwell time tolerance.
- Destination Charging:Workplace and terminal-based systems serve educational institution and private company fleets with predictable parking duration patterns.
Primary deployment mode: Normal Charging Points. Climbing the fastest: Wireless Charging Solutions as opportunity charging economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium reserves in Chile's Atacama salt flats and Brazil's Minas Gerais mining belt anchor South America's electric bus supply chain geography. These feedstock localities concentrate battery assembly capacity near transit demand centers.
Brazil
São Paulo state operators generate the continent's largest firm order volumes for battery electric configurations. ANFAVEA coordinates PROCONVE P-8 nitrogen oxide reduction timelines that compress diesel fleet replacement schedules. Campinas anchors BYD Auto's regional manufacturing base, supplying municipal operators across the metropolitan corridor.
Chile
Santiago's Transantiago network renewal drives concentrated demand for altitude-compensated chassis specifications. The Ministry of Transport enforces Zona de Bajas Emisiones quotas that restrict diesel access to central business districts. Antofagasta mining corridor operators pilot fuel cell configurations for extended-range applications.
Colombia
Bogotá and Medellín municipal authorities accelerate procurement through Ministry of Mines and Energy power purchase agreements. These contracts stabilize depot charging electricity costs previously volatile against diesel alternatives. Cundinamarca department transit operators specify medium-power configurations for Andean elevation routes.
Argentina
Buenos Aires metropolitan operators evaluate electric configurations amid fiscal constraints slowing fleet turnover velocity. The national transport secretariat structures emission reduction frameworks without mandatory quota enforcement. Córdoba province industrial clusters assemble battery packs from imported lithium cells.
Peru
Lima's transit authority deploys hybrid electric buses across mountainous corridors lacking reliable grid interconnection. The Ministry of Energy and Mines evaluates depot charging infrastructure investments for future battery electric transition. Arequipa operators test altitude-performance specifications for high-elevation urban routes.
South America Electric Bus Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue fuel cell and wireless charging integration. The market structures around three tiers: integrated battery-bus manufacturers, chassis specialists adapting global platforms, and hybrid-electric bridge solution providers. Strategic archetypes include Chinese state-backed exporters with localized assembly, European premium chassis licensors, and regional adaptation specialists. Competitive moves concentrate on manufacturing localization partnerships and charging infrastructure unbundling contracts with municipal utilities.
Within the integrated manufacturing tier, BYD Auto and Zhengzhou Yutong Bus exemplify state-backed exporters with Brazilian assembly presence. Scania occupies a position among European chassis specialists pursuing hybrid-electric architectures. These three anchors represent distinct competitive vectors: captive battery supply, localized altitude adaptation, and transitional powertrain bridging.
| Leading Market Players |
|---|
| BYD Auto |
| Foton |
| Zhengzhou Yutong Bus |
| AB VOLVO |
| Scania |
| Irizar |
| Iveco |
| King Long United Automotive Industry |
| Zhongtong Bus Holding |
| Others |
Value Network & Pricing Analysis
Lithium carbonate spot volatility feeds through to battery pack assembly costs in Campinas and São José dos Campos, compressing margins for Brazilian manufacturers while Chilean operators absorb premium pricing for altitude-compensated thermal management systems. Municipal procurement tenders in São Paulo state increasingly unbundle vehicle acquisition from charging infrastructure ownership, creating dual contract structures with divergent pricing logics.
Pricing Analysis
Warranty and after-sales service bundling separates premium-tier suppliers from economy-positioned competitors in Brazilian municipal tenders. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by PROCONVE P-8 certification timing and battery thermal management sophistication. Pricing pressure stems from East Asian cell import cost volatility and maritime logistics uncertainty. Government fleet operators in Chile and Colombia exhibit lowest price sensitivity due to power purchase agreement cost stabilization, while Peruvian transit authorities face acute budget constraints driving economy-tier procurement.
Supply Chain Analysis
Maritime freight cost fluctuations from East Asian ports to Santos and Valparaíso directly impact landed battery cell pricing for Brazilian and Chilean assemblers. Manufacturing concentration centers on China, South Korea, and Japan for lithium-ion cells, with Brazil and Argentina hosting emerging pack assembly capacity. Raw material dependencies span Chilean lithium carbonate, Congolese cobalt, and Australian spodumene. Single-source vulnerability in cell supply exposes procurement timelines to port congestion and customs clearance delays. Distribution runs through municipal tender processes and government fleet direct contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance arena where PROCONVE P-8 nitrogen oxide mandates erect regulatory moats favoring manufacturers with established ANFAVEA certification pathways and localized assembly presence.
For Market Incumbents: Anchor defensive positioning through backward integration into battery pack assembly and thermal management system production. BYD Auto's Campinas manufacturing base exemplifies this approach, capturing margin from cell-to-vehicle integration. Capacity addition in São Paulo state industrial corridors reinforces proximity to Transantiago network renewal demand. Threat from Chinese state-backed exporters with government fleet financing packages demands accelerated localization partnerships. For New Entrants and Emerging Players: Digital tender platforms and municipal procurement databases offer lower-friction market entry than traditional dealer networks. White-space targets concentrate in Colombian secondary cities beyond Bogotá and Medellín, where Ministry of Mines and Energy power purchase agreements reduce electricity cost volatility for depot charging operators. Peruvian hybrid-electric retrofit demand presents immediate revenue potential while grid infrastructure matures. Go-to-market positioning should emphasize wireless charging integration for high-frequency urban routes lacking full depot investment. For Investors and Strategic Acquirers: ANFAVEA PROCONVE P-8 certification award acceleration is the leading indicator that manufacturing localization moats are widening for compliant players. Long-term viability hinges on captive battery supply and altitude-performance engineering capabilities. Acquisition targets should display Brazilian or Chilean assembly presence paired with municipal service contract backlogs. Fuel cell supply chain maturation in Antofagasta mining corridors signals hydrogen infrastructure inflection potential.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Captive lithium-ion cell access insulates Brazilian assemblers from maritime logistics volatility. |
| Manufacturing Localization | Campinas and São José dos Campos assembly presence satisfies ANFAVEA domestic content preferences. |
| Charging Infrastructure Partnership | Third-party utility contracts unbundle capital burden from municipal fleet procurement budgets. |
| Altitude Performance Certification | Thermal management validation for Andean elevation opens Santiago and Bogotá high-elevation corridors. |
| Wireless Charging Integration | Opportunity charging systems reduce depot infrastructure requirements for high-frequency route operators. |
Research Methodology
Document review covered ANFAVEA emission certification records, Chile Ministry of Transport fleet electrification quotas, and Colombian Ministry of Mines and Energy power purchase agreement frameworks, complemented by interviews with municipal transit authority procurement directors, battery pack assembly plant managers, and electricity utility charging infrastructure planners. Secondary validation drew from customs trade data, PROCONVE regulatory filings, and transit operator tender documentation. Bottom-up fleet deployment tracking and top-down market sizing triangulated volume estimates.
Segment-level outputs across battery electric, hybrid electric, and fuel cell configurations combined with power rating tiers, charging infrastructure ownership models, and end-user procurement authority types. CAGRs derived from regression analysis of historical fleet replacement rates against regulatory mandate acceleration curves. Industry-specific inputs incorporated Andean altitude performance degradation factors and bioelectricity grid integration cost structures.
Inputs from ANFAVEA certification timelines and Chilean Zona de Bajas Emisiones enforcement schedules were available through the study window; gaps in Peruvian and Ecuadorian grid interconnection investment timelines introduce uncertainty bands for battery electric deployment velocity in secondary Andean markets. Forecasts reflect documented assumptions regarding PROCONVE P-8 compliance rates and lithium cell import cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Cold Plates Market
Electric Vehicles
Neighbourhood Electric Vehicle Market
Electric Vehicles
EV Condenser Market
Electric Vehicles
Electric Scooters and Mopeds Market
Electric Vehicles
Europe Automotive High Performance Electric Vehicle Market
Electric Vehicles
US Electric Mobility Market
Electric Vehicles
Global Industrial Electric Vehicle Market
Electric Vehicles
Electric Vehicle Electric Heating Film Market
Electric Vehicles
Electric Vehicle Regenerative Braking System Market
Electric Vehicles
Asia-Pacific Electric Vehicle Thermal Management System Market
Electric Vehicles
South America E-Bike Market
Electric Vehicles
Electric Vehicle Electronic Expansion Valve (EXV) Market
Electric Vehicles
Europe Fuel Cell Electric Vehicle Market
Electric Vehicles
Speed Pedelec E-Bike Market
Electric Vehicles
South America Automotive High Performance Electric Vehicles Market
Electric Vehicles
Canada E-Bike Market