
 EV PTC Heaters Market | 2026-2036
EV PTC Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
EV PTC Heaters Market Insights
Modular heating system bundling is consolidating buyer choice around integrated thermal management packages rather than standalone PTC components. BorgWarner Inc. leverages its power electronics heritage to anchor integrated cabin-and-battery heating solutions across North American EV platforms. MAHLE GmbH sustains engineering intensity in compact high-voltage PTC designs for European premium OEM thermal contracts. Eberspacher competes through specialized auxiliary heating modules optimized for cold-climate electric commercial vehicles.
EV PTC heaters are self-regulating ceramic heating elements composed of barium titanate-based semiconductor materials that exhibit positive temperature coefficient resistance, automatically limiting current draw as operating temperatures rise to prevent thermal runaway in high-voltage electric vehicle architectures. Cabin heating applications dominate current volume while battery thermal management represents the fastest-expanding segment as OEMs prioritize cold-weather range preservation and fast-charging preconditioning protocols. OEM end users command the largest value share due to platform-level thermal system integration requirements, though aftermarket providers occupy a growing niche serving retrofit and replacement demand in aging electric fleets.
FDA device-grade ceramic safety standards, China's GB/T electric vehicle thermal management protocols, and the EU Green Deal's F-Gas Regulation phase-down are collectively elevating PTC heater demand by restricting combustion-based auxiliary heating and mandating zero-emission thermal solutions. NHTSA cold-start safety requirements and ECE R122 cabin warming standards further harden product certification barriers for market entrants. Stakeholders must monitor how solid-state battery thermal profiles and heat-pump integration roadmaps reshape PTC component specifications and platform attachment rates across major EV architectures.
Market Dynamics
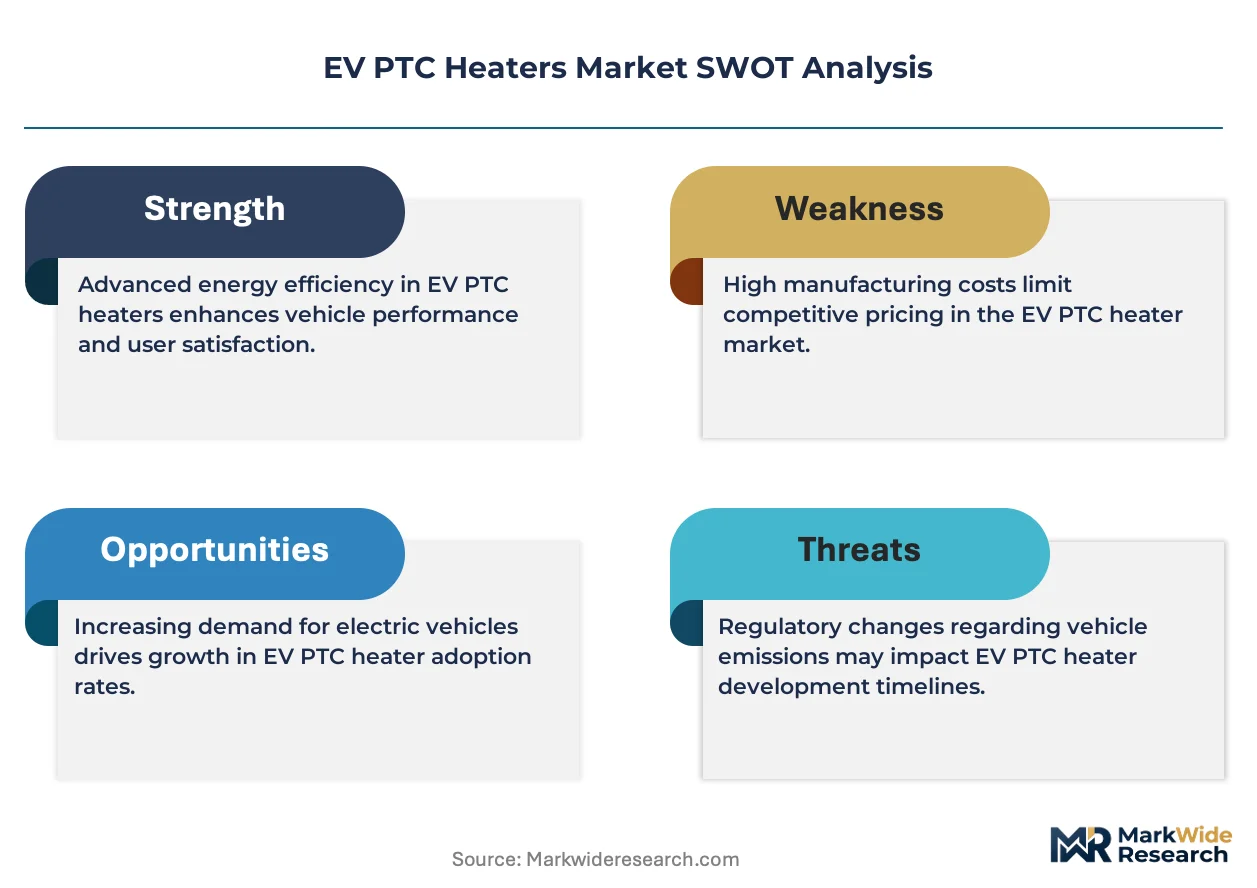
Platform-level thermal management integration is compressing standalone PTC heater procurement, forcing component suppliers to anchor integrated cabin-and-battery heating architectures or face displacement from tier-one supplier lists.
Growth Catalysts
- China's NMPA safety standards:Tightening thermal efficiency mandates under dual carbon goals are compelling OEMs to replace combustion-based auxiliary heaters with zero-emission PTC solutions across new energy vehicle platforms.
- Fast-charging preconditioning protocols:Battery thermal management applications are accelerating as OEMs prioritize cold-weather range preservation and DC fast-charging readiness in premium EV architectures.
- Jiangsu-Zhejiang manufacturing clusters:Co-location of PTC component suppliers with EV assembly plants is reducing logistics friction and enabling just-in-time thermal module delivery to domestic OEMs.
Market Restraints
- Barium titanate supply concentration:Ceramic semiconductor feedstock sourcing depends on limited high-purity mining operations, creating input cost volatility for PTC element manufacturers.
- Heat pump substitution threat:Integrated heat-pump thermal systems are displacing standalone PTC heaters in mild-climate EV platforms, compressing attachment rates in European and Chinese passenger segments.
- ECE R122 certification timelines:Extended cabin warming validation protocols are delaying product launches and freezing working capital for tier-two suppliers seeking OEM qualification.
Strategic Opportunities
- Commercial vehicle cold-climate auxiliary heating:Electric bus and heavy-duty truck fleets in Nordic markets present underpenetrated demand for specialized high-voltage PTC modules optimized for extreme operating conditions.
- EU F-Gas Regulation phase-down:The combustion heater restriction is creating regulatory tailwinds for zero-emission thermal solutions across European commercial and passenger EV platforms through 2030.
- Solid-state battery thermal profiles:Next-generation cell chemistries with narrower operating windows will require precision PTC preconditioning systems, opening specification upgrade cycles for advanced ceramic designs.
Industry Challenges
- High-voltage systems engineering talent:Scarce expertise in 800V+ PTC integration is extending development cycles and forcing OEMs to retain specialized thermal engineering consultancies.
- Platform attachment rate uncertainty:Heat-pump adoption roadmaps vary across OEMs, complicating capacity planning and creating stranded asset risk for PTC-dedicated production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV PTC Heaters Market |
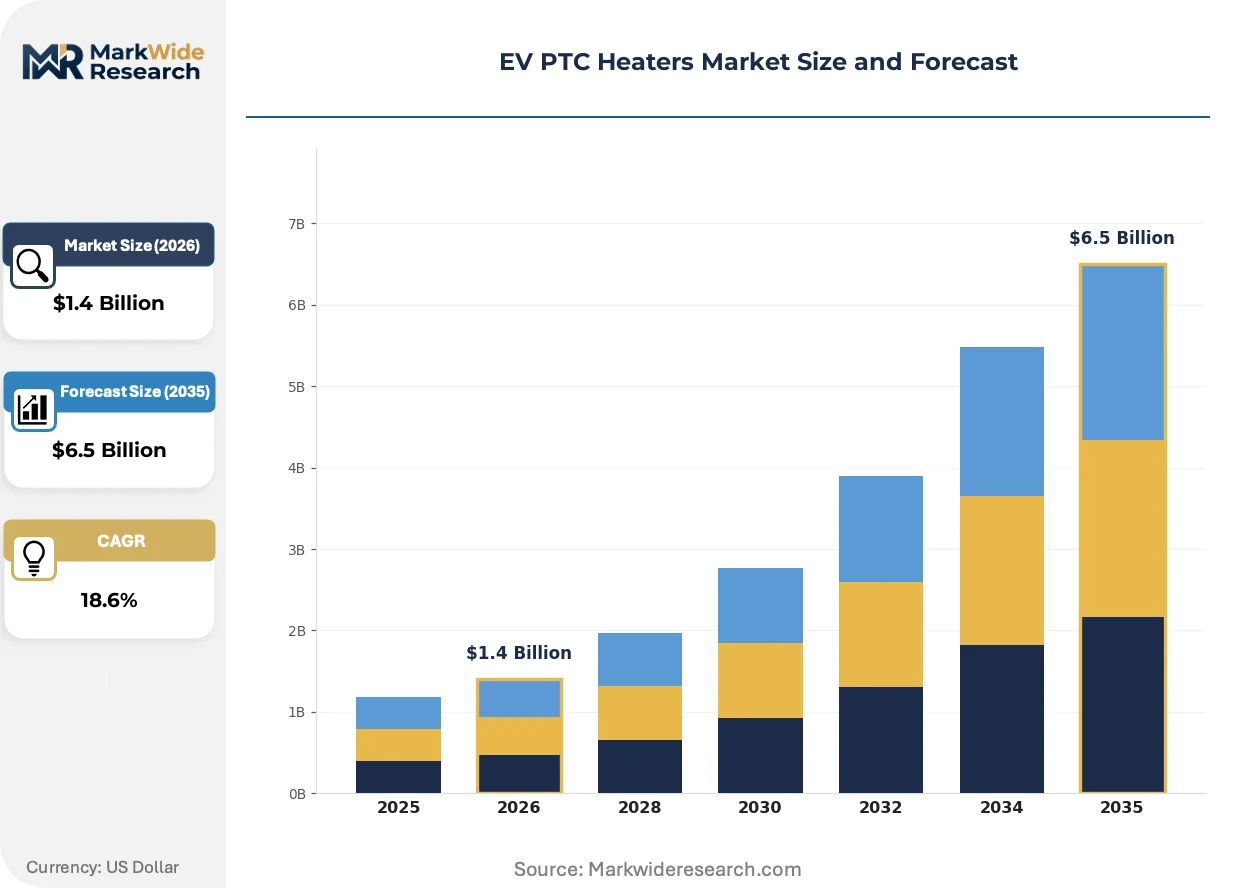
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $6.5 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heating Modules, Thermostatic Controls, Sensors, Connectors Application: Cabin Heating, Battery Heating, Seat Heating, Windshield Defrosting End User: OEMs, Aftermarket Providers, Fleet Operators, Vehicle Assemblers Technology: Conductive, Radiant, Convection, Advanced Materials |
| Companies Covered | Eberspacher, DBK Group, Mitsubishi Heavy Industries, MAHLE GmbH, BorgWarner Inc., Huagong Tech Company, Woory Corporation, Shanghai Xinye Electronic Co., Ltd., Zhenjiang Dongfang Electric Heating, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV PTC Heaters Market Trends and Innovations
Three interconnected shifts are reshaping competitive positioning: ceramic material evolution enabling higher voltage operation, regulatory compression of combustion-based alternatives, and procurement consolidation around integrated thermal system suppliers.
Silicon carbide-compatible PTC ceramic formulations are consolidating high-voltage heating architectures into unified cabin-and-battery thermal modules. Premium OEMs in Germany and South Korea are adopting these consolidated designs at platform launch, compressing the supplier base to power electronics-anchored tier ones capable of delivering integrated solutions rather than discrete heating elements.
China's GB/T electric vehicle thermal management protocols are tightening efficiency benchmarks and mandating real-time thermal monitoring data streams. The industrial consequence is a certification barrier elevation that favors domestic suppliers with established MIIT testing relationships, while foreign entrants face extended qualification timelines and localization requirements for NMPA compliance.
Buyer concentration around integrated thermal management packages is displacing component-level procurement. Tier-one suppliers with captive power electronics capabilities are capturing platform-level contracts, while standalone PTC specialists are retreating to aftermarket retrofit channels and aging fleet replacement demand concentrated in North American and European urban commercial operators.
EV PTC Heaters Market Segmentation
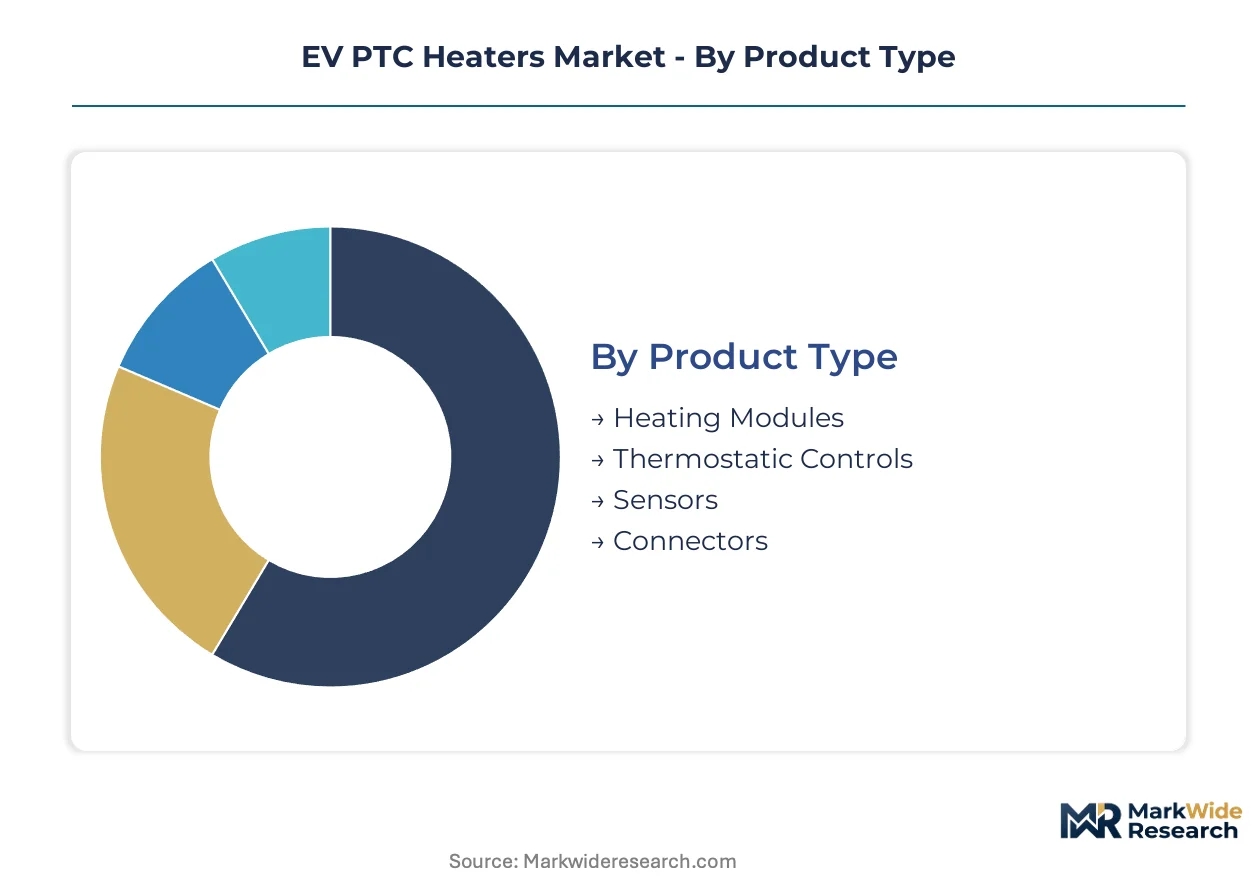
PTC heater procurement patterns diverge sharply across certification regimes, with NMPA-compliant modules commanding premium positioning in Chinese platforms while ECE R122-validated systems anchor European supply contracts. Understanding segment-specific regulatory burdens enables suppliers to align R&D spend with qualification timelines and avoid stranded certification investments.
Product Type:
Heating Modules require NMPA thermal efficiency validation and ECE R122 cabin warming certification, while Sensors face GB/T protocol compliance for real-time monitoring data streams in Chinese platforms. Thermostatic Controls and Connectors carry lighter regulatory loads but demand ISO 26262 functional safety alignment for high-voltage architectures.
- Heating Modules:Integrated ceramic element assemblies incorporating barium titanate semiconductor cores with self-regulating resistance profiles. Demand concentrates in Jiangsu and Zhejiang manufacturing clusters serving domestic Chinese OEMs under tightening NMPA safety mandates for zero-emission thermal solutions.
- Thermostatic Controls:Precision voltage regulation circuits governing PTC element activation thresholds and thermal cutoff protocols. European premium OEMs source these through tier-one power electronics suppliers capable of delivering consolidated cabin-and-battery heating architectures.
- Sensors:Temperature feedback devices enabling real-time thermal monitoring for battery preconditioning and cabin climate management.
- Connectors:High-voltage interface components rated for 800V+ architectures with integrated safety interlocks.
Leading the category by volume: Heating Modules. Growing fastest: Thermostatic Controls.
Application:
Cabin heating volume correlates with cold-climate vehicle registration density, while battery heating attachment rates track DC fast-charging infrastructure expansion. Seat heating and windshield defrosting represent cost-tier differentiators in premium versus economy platform configurations.
- Cabin Heating:Primary occupant thermal comfort systems replacing combustion-based auxiliary heaters in passenger EV architectures. Nordic markets and China's northern provinces drive specification intensity for extreme operating condition performance.
- Battery Heating:Cell preconditioning systems preserving cold-weather range and enabling fast-charging readiness. South Korean and German OEMs integrate these most aggressively into premium platform thermal management packages.
- Seat Heating:Localized occupant warming reducing overall cabin thermal load and extending vehicle range.
- Windshield Defrosting:Targeted glass heating modules ensuring visibility compliance under ECE R122 cabin warming standards.
Cabin Heating retains dominant share. Battery Heating climbs fastest on fast-charging protocol adoption.
End User:
OEM procurement concentrates platform-level thermal system integration spend, while fleet operators generate replacement demand cycles for aging electric bus and heavy-duty truck installations. Aftermarket channels serve retrofit requirements as early EV cohorts exit warranty coverage.
- OEMs:Original equipment manufacturers specifying integrated thermal management architectures at vehicle platform conception. Chinese NEV platforms from BYD, NIO, and XPeng anchor the largest contract values through bundled cabin-and-battery heating procurement.
- Aftermarket Providers:Independent service networks addressing component replacement and thermal system upgrades. European urban commercial operators in Berlin and Amsterdam represent concentrated demand for aging electric fleet retrofit.
- Fleet Operators:Electric bus and heavy-duty truck fleet managers with specialized cold-climate auxiliary heating requirements.
- Vehicle Assemblers:Contract manufacturing facilities integrating PTC modules into completed vehicle thermal systems.
OEMs command category value. Fleet Operators expand most quickly on commercial electrification timelines.
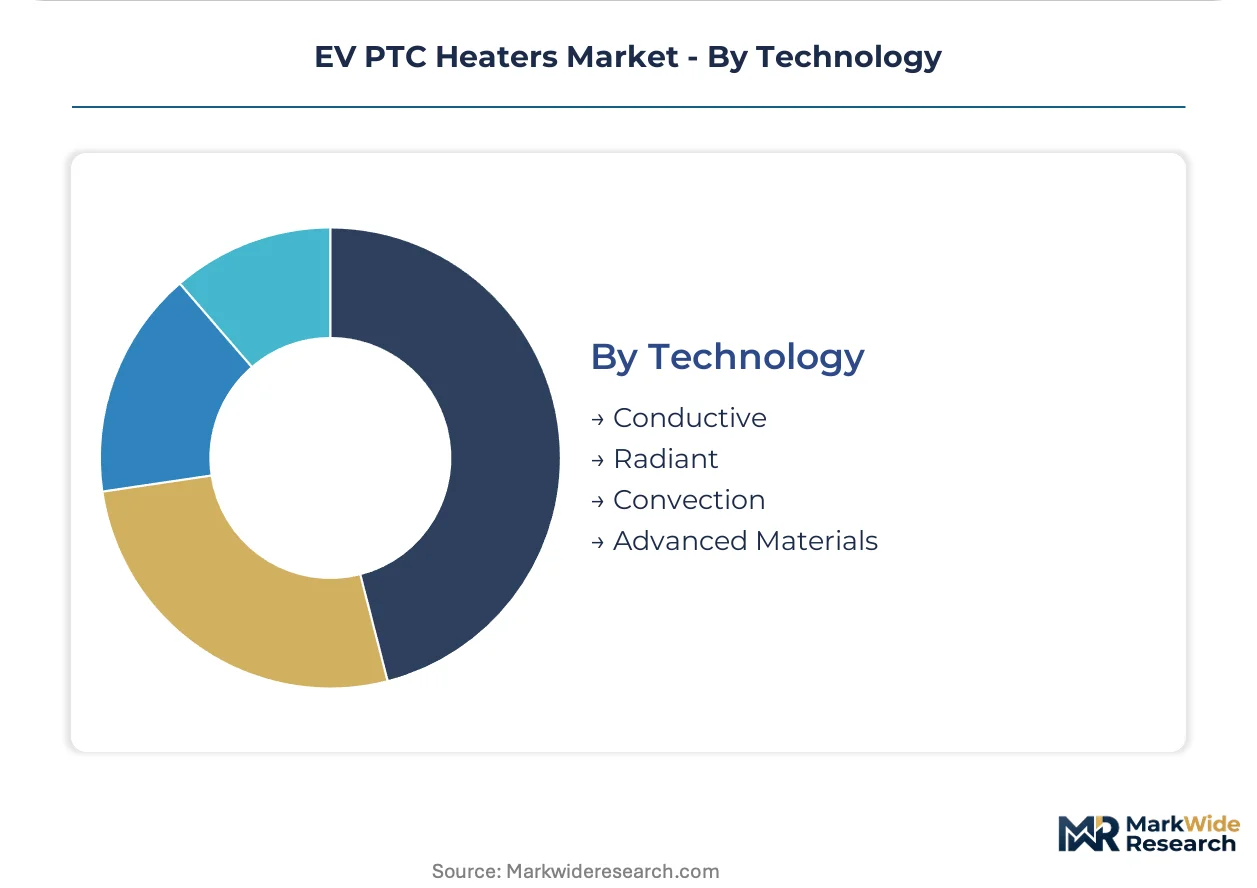
Technology:
Conductive and radiant technologies dominate current production, while advanced materials development targets silicon carbide-compatible ceramic formulations for next-generation 800V+ architectures. Convection systems retain niche positioning in commercial vehicle auxiliary applications.
- Conductive:Direct-resistance heating through barium titanate ceramic elements with positive temperature coefficient characteristics. Jiangsu-based suppliers optimize these for cost-efficient Chinese domestic market supply.
- Advanced Materials:Silicon carbide-compatible ceramic formulations enabling unified high-voltage thermal module designs. South Korean battery electric platforms from Hyundai and Kia adopt these for consolidated cabin-and-battery heating integration.
- Radiant:Infrared emission heating directed at specific cabin zones or battery pack surfaces.
- Convection:Forced-air thermal transfer systems optimized for electric commercial vehicle auxiliary heating in extreme cold climates.
Conductive technology leads volume. Advanced Materials gains share fastest on high-voltage platform proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Zhejiang provinces anchor PTC heater manufacturing through designated new energy vehicle industrial zones that concentrate component suppliers adjacent to EV assembly plants. China's dual carbon policy framework and NMPA safety mandates compress qualification timelines for domestic producers while foreign entrants face extended MIIT testing protocols.
China
Jiangsu-based ceramic element fabricators supply BYD, NIO, and XPeng platforms under tightening GB/T thermal efficiency benchmarks. NMPA safety standards mandate real-time thermal monitoring data streams, elevating certification barriers for non-domestic suppliers. Zhejiang manufacturing clusters enable just-in-time module delivery to Shanghai and Hefei assembly plants.
Germany
Premium OEM thermal contracts from BMW, Mercedes-Benz, and Volkswagen drive specification intensity for compact high-voltage PTC designs. ECE R122 cabin warming standards and EU F-Gas Regulation phase-down restrict combustion-based auxiliary heating, compelling zero-emission thermal solution procurement. Bavarian engineering centers coordinate platform-level integration with tier-one power electronics suppliers.
South Korea
Hyundai and Kia battery electric platforms adopt silicon carbide-compatible ceramic formulations for consolidated cabin-and-battery heating architectures. MFDS-aligned safety protocols and KBA-type approval requirements govern 800V+ system validation. Seoul Capital Area R&D facilities prototype next-generation thermal modules for export to European and North American OEMs.
United States
Detroit Three electrification programs and Tesla's thermal management roadmaps anchor North American demand for integrated heating solutions. NHTSA cold-start safety requirements harden product certification barriers for market entrants. Midwest manufacturing corridors in Michigan and Ohio co-locate PTC module assembly with battery pack production facilities.
Japan
Tokyo-based OEMs prioritize precision PTC preconditioning systems for solid-state battery thermal profiles under development at Toyota and Nissan. METI technology roadmaps and JIS standards govern high-voltage component interoperability. Kansai region ceramic suppliers optimize barium titanate formulations for next-generation cell chemistry operating windows.
EV PTC Heaters Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three distinct capability tiers. Tier-one power electronics suppliers with captive thermal engineering resources capture platform-level integration contracts, while standalone ceramic element fabricators retreat to aftermarket channels. Component specialists, system integrators, and materials suppliers constitute the primary strategic archetypes. Competitive dynamics center on M&A-driven capability consolidation and geographic co-location with major EV assembly clusters.
Among Germany-based diversified industrial groups, MAHLE GmbH and BorgWarner Inc. exemplify tier-one positioning through power electronics-anchored thermal system integration. Eberspacher occupies a specialist position in auxiliary heating modules for commercial vehicle applications. Shanghai Xinye Electronic Co., Ltd. represents Chinese domestic capability in ceramic element fabrication serving NMPA-compliant platforms. These three anchors illustrate the geographic and strategic segmentation defining procurement access.
| Leading Market Players |
|---|
| Eberspacher |
| DBK Group |
| Mitsubishi Heavy Industries |
| MAHLE GmbH |
| BorgWarner Inc. |
| Huagong Tech Company |
| Woory Corporation |
| Shanghai Xinye Electronic Co., Ltd. |
| Zhenjiang Dongfang Electric Heating |
| Others |
Pricing and Supply Chain Analysis
Platform-level thermal system bundling by tier-one power electronics suppliers has compressed component-level procurement, shifting pricing power toward integrated cabin-and-battery heating architectures under long-term offtake contracts with Chinese NEV OEMs and European premium manufacturers.
Pricing Analysis
Short lead-time premiums for NMPA-compliant modules serving Jiangsu and Zhejiang assembly plants command pricing advantages over spot inventory drawn from non-certified ceramic fabricators. Three-tier pricing structure across premium, standard, and economy levels separates silicon carbide-compatible 800V+ designs from conventional conductive elements and basic auxiliary heating modules. Cost compression in economy-tier conductive ceramics is intensifying because Jiangsu-based suppliers are expanding barium titanate element capacity. Fleet operators and aftermarket retrofit channels exhibit highest price sensitivity, while German and South Korean premium OEMs prioritize performance certification over unit cost.
Supply Chain Analysis
China's MIIT domestic-content mandates for NEV thermal management components are reshaping sourcing patterns, compelling foreign suppliers to localize ceramic element fabrication or surrender tier-one qualification status. High-purity barium titanate mining concentrates in China and Japan, while precision thermostatic control manufacturing anchors in Germany and South Korea. Single-source vulnerability runs through concentrated high-purity ceramic semiconductor feedstock operations. Distribution runs through just-in-time module delivery networks co-located with EV assembly clusters in Jiangsu, Zhejiang, and Michigan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-level procurement consolidation is accelerating industry shakeout, with integrated thermal management capabilities forcing standalone PTC specialists toward aftermarket retreat or acquisition by power electronics conglomerates.
For Market Incumbents: Deploy silicon carbide-compatible ceramic formulation R&D to anchor consolidated cabin-and-battery heating architectures before heat-pump substitution erodes attachment rates in mild-climate segments. Deepen backward integration into high-purity barium titanate sourcing to insulate margin structures from mining concentration volatility. Capture long-term offtake contracts with Chinese NEV platforms under tightening GB/T efficiency benchmarks. For New Entrants and Emerging Players: The gap between premium 800V+ silicon carbide-compatible modules and economy-tier conductive ceramics presents white-space opportunity for mid-voltage precision designs targeting European commercial vehicle cold-climate auxiliary heating. Nordic electric bus fleets and North American heavy-duty truck electrification programs offer underpenetrated demand with lighter tier-one supplier list entrenchment. Pursue Eberspacher-style specialization rather than head-to-head integrated system competition. For Investors and Strategic Acquirers: The window for entry favors power electronics conglomerates seeking thermal management capability gaps to fill through targeted ceramic element fabricator acquisition. Long-term viability hinges on positioning within solid-state battery preconditioning specification cycles rather than incumbent lithium-ion platform attachment. Watch heat-pump integration roadmaps across German and Chinese OEMs as inflection signal for PTC component demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Ceramic Formulation Development | Enables unified 800V+ cabin-and-battery thermal modules for South Korean and German premium platforms. |
| Backward Integration into Barium Titanate Supply | Secures captive high-purity ceramic semiconductor feedstock against Jiangsu-Zhejiang mining concentration. |
| NMPA Certification Investment | Unlocks tier-one supplier list access for BYD, NIO, and XPeng platform thermal contracts. |
| Commercial Vehicle Cold-Climate Specialization | Captures Nordic electric bus and North American heavy-duty truck auxiliary heating demand. |
| Solid-State Battery Preconditioning R&D | Positions for next-generation cell chemistry thermal profile specification upgrades at Toyota and Nissan. |
Research Methodology
Multi-period observation of NMPA certification timelines, GB/T thermal efficiency benchmark evolution, and OEM platform thermal integration roadmaps anchored the trend analysis, supplemented by interviews with tier-one supplier procurement directors, OEM platform thermal engineers, ceramic element fabrication plant managers, and aftermarket fleet retrofit specialists. Secondary validation drew from MIIT new energy vehicle production databases, ECE R122 cabin warming standard filings, SEC 10-K disclosures from listed automotive suppliers, and IHS Markit vehicle registration data. Bottom-up segment sizing triangulated against top-down OEM platform thermal content estimates.
Segment-weighting across product type, application, end user, and technology dimensions informed the analytical framework over the projection horizon. Vehicle class, propulsion architecture, and regional production cluster variables modeled attachment rate variation. CAGRs derived from regression analysis of historical platform thermal content trajectories and OEM electrification commitment disclosures. Forecast inputs incorporated solid-state battery commercialization timelines and heat-pump integration roadmaps from German and South Korean OEM engineering centers.
Underlying measurement precision varies by segment; OEM platform-level thermal contracts carry tighter precision than aftermarket retrofit demand estimation. Forecasts reflect assumptions regarding NMPA enforcement intensity, barium titanate supply stability, and heat-pump technology cost curves. Regulatory acceleration in China's dual carbon framework or abrupt solid-state battery thermal profile shifts could revise trajectory. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Solar Golf Cart Market
Electric Vehicles
Global Electric Scooters Market
Electric Vehicles
United States Electric Pick-Up Trucks Market
Electric Vehicles
Global Electric Vehicles Market
Electric Vehicles
Extended Range Electric Vehicle (EREV) Market
Electric Vehicles
EV Taxi Market
Electric Vehicles
Central and Eastern Europe E-Bike Market
Electric Vehicles
Hybrid E-Scooter Market
Electric Vehicles
Electric Tuk-Tuks Market
Electric Vehicles
Russia Electric Cars Market
Electric Vehicles
Electric Scooters and Mopeds Market
Electric Vehicles
E-Bike Lithium-Ion Battery Market
Electric Vehicles
Vehicle Electrification Market
Electric Vehicles
Automotive Battery Thermal Management System Market
Electric Vehicles
Asia Pacific Automotive High Performance Electric Vehicles Market
Electric Vehicles
Global Automotive Lithium Ion Battery Controller Market