
 Europe Electric Vehicle Thermal Management System Market | 2026-2036
Europe Electric Vehicle Thermal Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Vehicle Thermal Management System Market Foresight
Modular thermal system packaging is pivoting from discrete component sales to integrated battery-cabin-powertrain modules that simplify OEM assembly lines. Robert Bosch GmbH leverages its electronics and thermal hardware portfolio to offer bundled control units. MAHLE GmbH anchors its position through dedicated R&D centers in Stuttgart focused on refrigerant circuits and heat exchanger miniaturization. Valeo competes aggressively on heat pump technology, extending its climate-system expertise into electric platforms.
The Europe Electric Vehicle Thermal Management System encompasses the engineered subsystems that regulate temperature across battery packs, passenger cabins, power electronics, and electric drivetrains, typically operating within narrow thermal windows to preserve cell longevity and passenger comfort. These systems employ liquid coolant loops, refrigerant circuits, phase change materials, or air channels to transfer heat between sources and sinks under varying ambient and load conditions. Heat pumps and liquid cooling dominate technology procurement because they deliver coefficient-of-performance advantages that air-based alternatives cannot match in cold climates. Battery thermal management commands the largest application share due to cell degradation sensitivity, while electronics cooling represents the fastest-expanding margin pool as silicon carbide inverters and 800-volt architectures multiply heat flux densities.
The EU Green Deal, F-Gas Regulation, and ECHA REACH framework collectively mandate lower-global-warming-potential refrigerants, stricter material disclosure, and embedded carbon tracking across automotive supply chains. EMA and national type-approval bodies in Germany, France, and Italy enforce these standards through homologation gates that block market access for non-compliant thermal system designs. Stakeholders must monitor refrigerant transition timelines and heat pump efficiency benchmarks to align product roadmaps with evolving compliance thresholds.
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing refrigerant choices and forcing heat pump architectures into standard vehicle configurations, eliminating legacy compressor designs from new platform approvals.
Growth Catalysts
- Heat pump mandates:The EU Green Deal's efficiency benchmarks push OEMs toward integrated heat pump systems for cabin and battery conditioning, expanding addressable system value per vehicle.
- Battery gigafactory clustering:Germany's manufacturing corridor concentrates demand for localized thermal system supply, reducing logistics costs and accelerating development cycles.
- 800-volt architectures:Silicon carbide inverters and high-voltage platforms multiply heat flux densities, requiring liquid cooling loops that expand the thermal management content per powertrain.
Market Restraints
- Refrigerant transition costs:The F-Gas Regulation's phase-down of high-GWP refrigerants forces costly retooling of compressor and heat exchanger production lines.
- Copper and aluminum price volatility:Raw material swings in heat exchanger metals compress margin stability for tier suppliers.
- Heat pump cold-climate performance gaps:Sub-zero efficiency degradation limits Nordic market penetration without supplemental resistive heating, adding cost and complexity.
Strategic Opportunities
- Poland and Czech Republic manufacturing:Central European labor cost advantages attract thermal component assembly for German OEM supply chains.
- Commercial vehicle electrification:Electric bus and truck fleets require scaled thermal systems with duty cycles distinct from passenger cars, opening specialized product lines.
- CSRD embedded carbon tracking:The Corporate Sustainability Reporting Directive creates first-mover advantage for suppliers with lifecycle-assessed thermal modules.
Industry Challenges
- Systems engineering talent scarcity:The intersection of refrigerant thermodynamics, battery electrochemistry, and vehicle electronics requires hybrid skill sets in short supply across Stuttgart and Munich engineering pools.
- Homologation timeline compression:EMA and KBA type-approval gates for new refrigerant circuits extend development schedules, delaying platform launches.
- Legacy HVAC integration complexity:Incumbent climate-system architectures resist modular retrofit, forcing parallel development tracks for ICE and BEV platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Vehicle Thermal Management System Market |
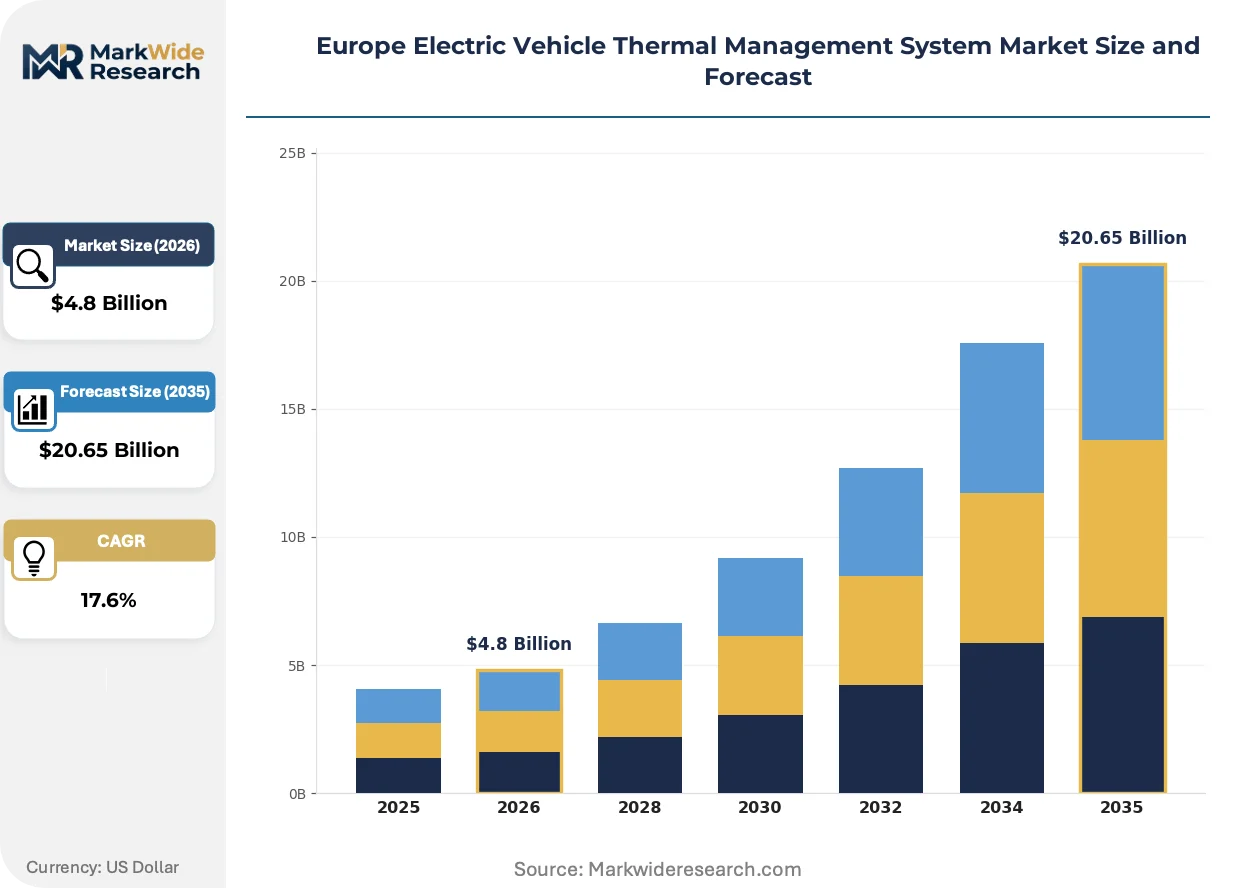
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $20.65 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Exchangers, Cooling Systems, Heating Systems, Thermal Insulation Technology: Liquid Cooling, Air Cooling, Phase Change Materials, Heat Pumps End User: OEMs, Aftermarket Providers, Fleet Operators, Public Transport Application: Battery Thermal Management, Cabin Heating, Powertrain Cooling, Electronics Cooling |
| Companies Covered | Robert Bosch GmbH, MAHLE GmbH, Valeo, VOSS Automotive GmbH, Continental AG, BorgWarner Inc., Dana Limited, Hanon Systems, Denso Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Vehicle Thermal Management System Market Shifts & Advancements
Refrigerant chemistry, voltage architecture, and procurement logic are simultaneously shifting, collapsing the traditional separation between powertrain and cabin thermal loops into unified control strategies.
CO2 transcritical heat pump cycles are integrating battery, cabin, and power electronics cooling into single-refrigerant architectures. German OEMs are adopting these systems for premium BEV platforms launching through 2026. This convergence is integrating previously separate supplier tiers into direct competition for module-level contracts.
The F-Gas Regulation's phased GWP limits are eliminating R-134a and constraining R-1234yf availability for high-volume production. Compressor manufacturers are requalifying designs for R-744 and R-290 compatibility. France's ANSM and Germany's KBA are enforcing these transitions through homologation gates that block non-compliant systems from type approval.
Fleet operators in the Netherlands and Denmark are consolidating thermal system procurement through leasing subsidiaries rather than OEM pass-through. These entities now specify performance warranties and refrigerant handling protocols directly. This disintermediation is most visible in electric bus deployments, where municipal transport authorities negotiate thermal module service contracts separate from vehicle purchase agreements.
Europe Electric Vehicle Thermal Management System Market Segmentation
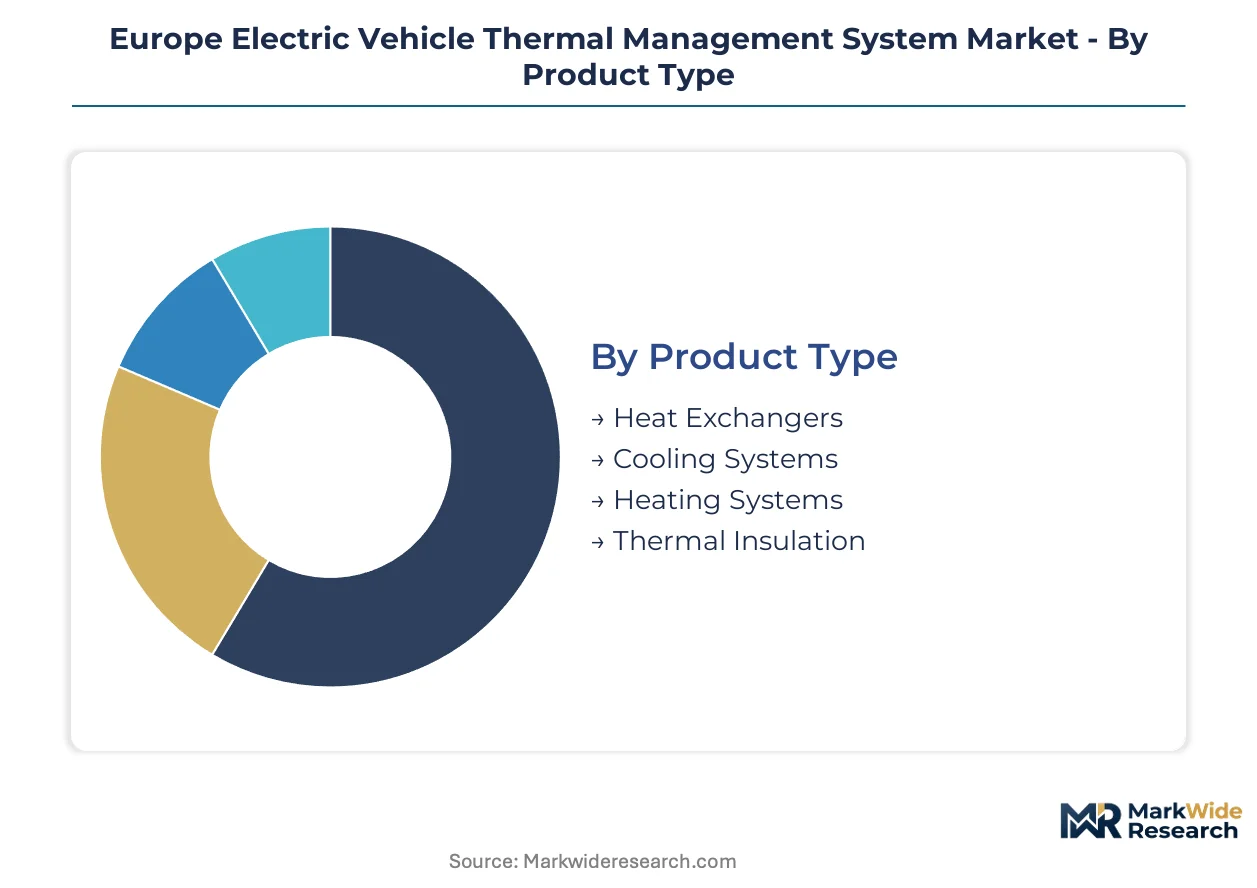
Thermal system procurement in Europe fragments across four dimensions that determine engineering specifications, margin structures, and regulatory compliance pathways. Product type and technology choices cascade through application requirements and end-user procurement models, creating distinct competitive arenas with divergent growth trajectories.
Product Type:
Cost tier separates volume buyers seeking standardized heat exchangers from premium platforms demanding integrated thermal modules.
- Heat Exchangers:Aluminum-brazed plate-and-fin architectures dominate battery cooling circuits, with Stuttgart-based OEMs specifying compact designs for underfloor pack integration. Demand concentrates in Germany's automotive corridor where battery gigafactory proximity reduces logistics costs for high-volume aluminum stampings.
- Cooling Systems:Liquid coolant loops with electric pumps and expansion valves form the backbone of 800-volt architectures, managing heat flux from silicon carbide inverters. French OEMs are expanding procurement of these systems for premium BEV platforms requiring sustained fast-charge capability.
- Heating Systems:Resistive PTC heaters supplement heat pumps in Nordic configurations.
- Thermal Insulation:Aerogel and foam barriers protect cabin and battery compartments from ambient thermal loss.
Volume sits with Heat Exchangers; growth tilts toward Cooling Systems.
Technology:
Application temperature precision dictates technology selection, with narrow thermal windows favoring active liquid systems over passive alternatives.
- Liquid Cooling:Ethylene-glycol and dielectric fluid circuits deliver precise temperature control for battery packs operating within 15-35°C windows. Netherlands fleet operators specify these systems for electric bus depots where duty cycles demand consistent thermal performance across variable ambient conditions.
- Heat Pumps:CO2 transcritical cycles integrate cabin, battery, and power electronics conditioning into unified refrigerant architectures. German OEM adoption for premium platforms is accelerating supplier competition for module-level contracts.
- Air Cooling:Simplified blower systems persist in low-cost urban mobility applications.
- Phase Change Materials:Paraffin and salt-hydrate composites buffer thermal spikes in compact electronics enclosures.
Liquid Cooling commands current procurement volumes; Heat Pumps are expanding most quickly under EU Green Deal efficiency mandates.
End User:
Procurement authority concentration shapes contract structures, with direct fleet negotiation displacing traditional OEM pass-through in commercial segments.
- OEMs:Integrated vehicle manufacturers specify thermal modules at platform design stage, bundling battery and cabin systems under single-source contracts. Germany's KBA homologation requirements force early supplier engagement for refrigerant circuit validation.
- Fleet Operators:Leasing subsidiaries in Denmark and the Netherlands now negotiate thermal performance warranties and refrigerant handling protocols directly with tier suppliers, bypassing OEM intermediaries in electric bus deployments.
- Aftermarket Providers:Service networks handle replacement heat exchangers and compressor units.
- Public Transport:Municipal authorities specify thermal durability for high-utilization electric bus corridors.
Contract value concentrates with OEMs; margin expansion tilts toward Fleet Operators.
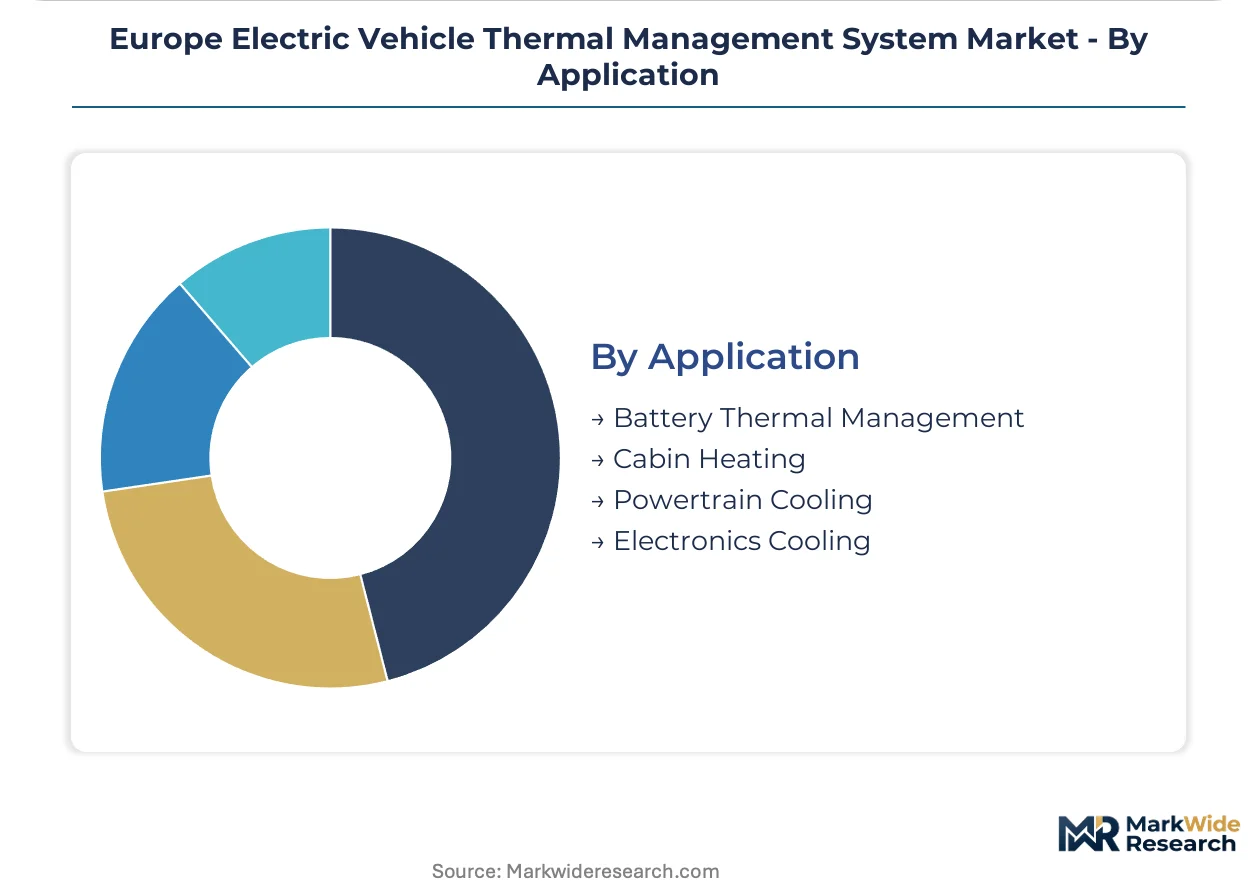
Application:
Thermal load density and failure cost determine specification stringency, with battery systems commanding the tightest control tolerances.
- Battery Thermal Management:Cell-level temperature uniformity prevents lithium-ion degradation and thermal runaway, requiring multi-zone coolant distribution and predictive control algorithms. France's ANSM enforces these specifications through type-approval gates that validate pack-level thermal safety.
- Electronics Cooling:Silicon carbide inverters and onboard chargers generate heat flux densities exceeding 50 W/cm², driving demand for micro-channel cold plates and direct liquid contact schemes. Czech Republic manufacturing clusters are expanding capacity for these precision-machined components.
- Cabin Heating:Occupant comfort systems compete for thermal energy with battery conditioning in cold climates.
- Powertrain Cooling:Electric motor and gearbox thermal management maintains efficiency and lubricant integrity.
Installed base sits with Battery Thermal Management; Electronics Cooling is gaining share fastest from 800-voltage architecture proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany's automotive corridor while consumption spreads across fleet electrification programs in France, the Netherlands, and Nordic markets. Battery gigafactory buildouts create localized supply chain gravity near Stuttgart and Munich assembly plants.
Germany
Stuttgart-based OEMs drive procurement of integrated thermal modules for premium BEV platforms launching through 2026. The KBA enforces F-Gas Regulation compliance through homologation gates that validate refrigerant circuit safety. Bavaria's battery gigafactory cluster near Munich attracts localized heat exchanger stamping capacity from aluminum suppliers.
France
Paris-region fleet operators specify thermal performance warranties for electric bus deployments through direct supplier negotiations. ANSM enforces REACH framework disclosure requirements for refrigerant materials in automotive supply chains. Auvergne-Rhône-Alpes hosts specialized R&D centers focused on heat pump efficiency optimization for cold-climate operation.
Netherlands
Municipal transport authorities in Amsterdam and Rotterdam negotiate thermal module service contracts separate from vehicle purchase agreements. The national leasing subsidiary model consolidates procurement authority for electric bus thermal systems. Eindhoven's high-tech manufacturing corridor supplies precision-machined cold plates for silicon carbide inverter cooling.
Poland
Central European labor cost advantages attract thermal component assembly operations serving German OEM supply chains. Lower Silesia's automotive supplier parks expand capacity for aluminum-brazed heat exchangers and electric coolant pumps. Warsaw-based engineering centers support refrigerant circuit design for CO2 transcritical heat pump architectures.
Sweden
Nordic cold-climate performance requirements drive demand for supplemental resistive heating in heat pump configurations. Gothenburg's automotive engineering cluster develops predictive thermal control algorithms for sub-zero battery conditioning. Scania's electric truck manufacturing in Södertälje creates specialized thermal system demand for heavy-duty commercial vehicle duty cycles.
Europe Electric Vehicle Thermal Management System Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across module-level and component-level supply tiers. Tier-one automotive suppliers leverage electronics integration capabilities to capture bundled control unit contracts. Three archetypes dominate: diversified industrial conglomerates with thermal hardware portfolios, climate-system specialists pivoting from ICE architectures, and pure-play thermal engineering firms. Capacity expansion and refrigerant circuit requalification constitute the dominant competitive moves as F-Gas Regulation timelines compress.
Within the diversified conglomerate tier, Robert Bosch GmbH and Continental AG exemplify players leveraging cross-divisional electronics and automotive expertise. MAHLE GmbH occupies a position among climate-system specialists transitioning expertise toward electric platforms. Valeo anchors the heat pump technology vector, representing specialists extending thermal management capabilities into integrated BEV architectures.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| MAHLE GmbH |
| Valeo |
| VOSS Automotive GmbH |
| Continental AG |
| BorgWarner Inc. |
| Dana Limited |
| Hanon Systems |
| Denso Corporation |
| Others |
Supply & Pricing Matrix
Captive aluminum stamping capacity in Germany's automotive corridor anchors supply positioning and pricing power for heat exchanger manufacturers serving Stuttgart and Munich battery gigafactories. This backward integration into raw metal processing insulates tier-one suppliers from spot market volatility while compressing margin capture opportunities for mid-tier competitors dependent on merchant aluminum sources.
Pricing Analysis
Cost-down pressure on integrated thermal modules accelerates because OEMs bundle battery, cabin, and power electronics conditioning under single-source contracts. Three-tier pricing structure across premium, standard, and economy levels separates CO2 transcritical heat pump architectures from conventional refrigerant circuits and basic air-cooled alternatives. Price differentiation hinges on F-Gas Regulation compliance certification and volume scale commitments across platform generations. Fleet operators in the Netherlands exhibit highest price sensitivity through direct service contract negotiations, while German premium OEMs prioritize performance warranties over unit cost.
Supply Chain Analysis
Freight cost optimization drives aluminum-brazed heat exchanger assembly into Poland and Czech Republic supplier parks serving German OEM corridors. Manufacturing concentrates in Germany, Poland, and Czech Republic for proximity to Stuttgart and Munich vehicle assembly plants. The supply chain draws from copper cathodes, aluminum coil stock, and rare-earth magnet feedstocks for electric coolant pumps. Single-source vulnerability around silicon carbide inverter cold plates from Eindhoven precision machining clusters poses concentration risk. Distribution runs through tier-one module suppliers delivering integrated thermal systems directly to OEM platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around refrigerant circuit requalification capabilities as F-Gas Regulation timelines eliminate players lacking capital for CO2 transcritical heat pump retooling.
For Market Incumbents: Deploy capacity addition in Poland and Czech Republic manufacturing corridors to capture labor cost advantages while maintaining German OEM proximity. Defensive consolidation requires acquiring refrigerant circuit engineering talent scarce across Stuttgart and Munich pools, and securing KBA homologation pre-approval for R-744 compressor designs before platform freeze gates close.
For New Entrants and Emerging Players: Launch via direct fleet operator contracting in Netherlands and Denmark electric bus deployments, bypassing OEM intermediaries that dominate passenger vehicle procurement. White-space targets include specialized thermal systems for Scania's Södertälje electric truck manufacturing and predictive control algorithms for Nordic sub-zero battery conditioning. Municipal transport authorities offer the most penetrable entry point through separate thermal module service contracts.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified automotive conglomerates seeking refrigerant circuit expertise. Long-term viability favors suppliers with lifecycle-assessed thermal modules aligned to CSRD embedded carbon tracking requirements. Watch for ANSM enforcement actions on REACH framework material disclosures as the inflection signal for compliance-driven consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Circuit Requalification | CO2 transcritical heat pump validation through KBA homologation gates secures platform access for German OEM launches. |
| Central European Manufacturing Footprint | Poland and Czech Republic assembly expansion reduces logistics costs to Stuttgart battery gigafactory clusters. |
| Direct Fleet Contracting Model | Netherlands municipal transport authorities now negotiate thermal performance warranties separate from vehicle purchase agreements. |
| CSRD Lifecycle Assessment Investment | Embedded carbon tracking capabilities create first-mover advantage for suppliers reporting under Corporate Sustainability Reporting Directive. |
| Predictive Thermal Control Development | Gothenburg engineering clusters advance sub-zero battery conditioning algorithms addressing Nordic cold-climate performance gaps. |
Research Methodology
Multi-period observation of battery gigafactory buildout timelines, F-Gas Regulation enforcement patterns, and heat pump technology adoption curves anchored the trend analysis, supplemented by interviews with OEM platform engineers, tier-one supplier procurement directors, fleet operator leasing subsidiary managers, and KBA homologation officials. Secondary validation drew from EU Green Deal policy documents, ECHA REACH substance databases, vehicle production registries, and aluminum trade flow customs records. Bottom-up segment sizing triangulated against top-down market value estimates from supplier revenue disclosures.
Segment-weighting across product type, technology, application, and end-user dimensions structured the analytical framework across the projection horizon. Vehicle class, propulsion architecture, and content-per-vehicle thermal system value formed the core automotive-specific segmentation. CAGRs derived from regression analysis of historical procurement volumes against battery electric vehicle registration trajectories, with silicon carbide inverter penetration and 800-volt architecture adoption as key forecast inputs.
Refrigerant transition timeline delays, copper and aluminum price volatility spikes, and heat pump cold-climate performance shortfalls are the dominant revision risks. Forecasts reflect documented assumptions on regulatory enforcement intensity and technology cost curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Solar Car Market
Electric Vehicles
Africa Electric Vehicle Market
Electric Vehicles
Europe Hybrid Electric Vehicle Battery Market
Electric Vehicles
Compact E-Scooter Market
Electric Vehicles
UK Electric Bus Battery Pack Market
Electric Vehicles
Fuel Cell Electric Vehicle (FCEV) Market
Electric Vehicles
Electric Vehicle UBI Market
Electric Vehicles
Saudi Arabia Electric Vehicle Market
Electric Vehicles
Electric Tricycle Market
Electric Vehicles
EV Thermal Management System Market
Electric Vehicles
Electric Utility Vehicle Market
Electric Vehicles
Cargo-to-Passenger Convertible eVTOL Cabin Systems Market
Electric Vehicles
APAC E-Bikes Market
Electric Vehicles
Global Automotive Inductive Wireless Charging Systems Market
Electric Vehicles
Driveline Electric Vehicle Market
Electric Vehicles
Denmark Solar E-Bike Market