
 Two-Wheeled Electric Vehicle Battery Market | 2026-2036
Two-Wheeled Electric Vehicle Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Two-Wheeled Electric Vehicle Battery Market Insights
Lithium-iron-phosphate chemistry is fragmenting the traditional supply base for two-wheeled electric vehicle batteries, pulling cell design away from cobalt-dense formats toward cheaper, thermally stable architectures. Contemporary Amperex Technology Co. Limited anchors the Asia-Pacific supply chain through massive cylindrical and prismatic cell output. LG Energy Solution competes on high-nickel chemistry expertise, leveraging automotive-grade quality systems for premium scooter platforms. Samsung SDI specializes in solid-state and next-generation prototypes, positioning its R&D pipeline for mid-decade commercialization.
Two-wheeled electric vehicle batteries are rechargeable electrochemical storage systems, typically rated between 48 V and 72 V nominal, engineered to deliver sustained discharge currents above 2C for acceleration and hill-climb torque in motorcycles, scooters, and mopeds. Lithium-ion cells dominate new platform designs due to gravimetric energy density exceeding 250 Wh/kg, while lead-acid retains residual share in price-sensitive replacement markets across South Asia and Africa. Fast charging infrastructure is expanding fastest among technology segments, though swappable battery networks capture disproportionate capital flow from fleet operators seeking asset-light uptime models. The 21-30 Ah capacity band holds the deepest margin pool, balancing urban range requirements against pack weight constraints.
FDA-equivalent national pharmaceutical regulators do not govern this sector; instead, China's NMPA certifies cell safety under GB standards, the EU enforces CE marking and the Battery Regulation for carbon footprint disclosure, and India's BIS mandates IS 16046 testing for lithium-ion imports. These frameworks are forcing manufacturers to localize assembly and source recycled content to maintain market access. Stakeholders must track which jurisdiction moves first on mandatory battery passport requirements, as this will reshape supply chain documentation burdens and competitive positioning across export markets.
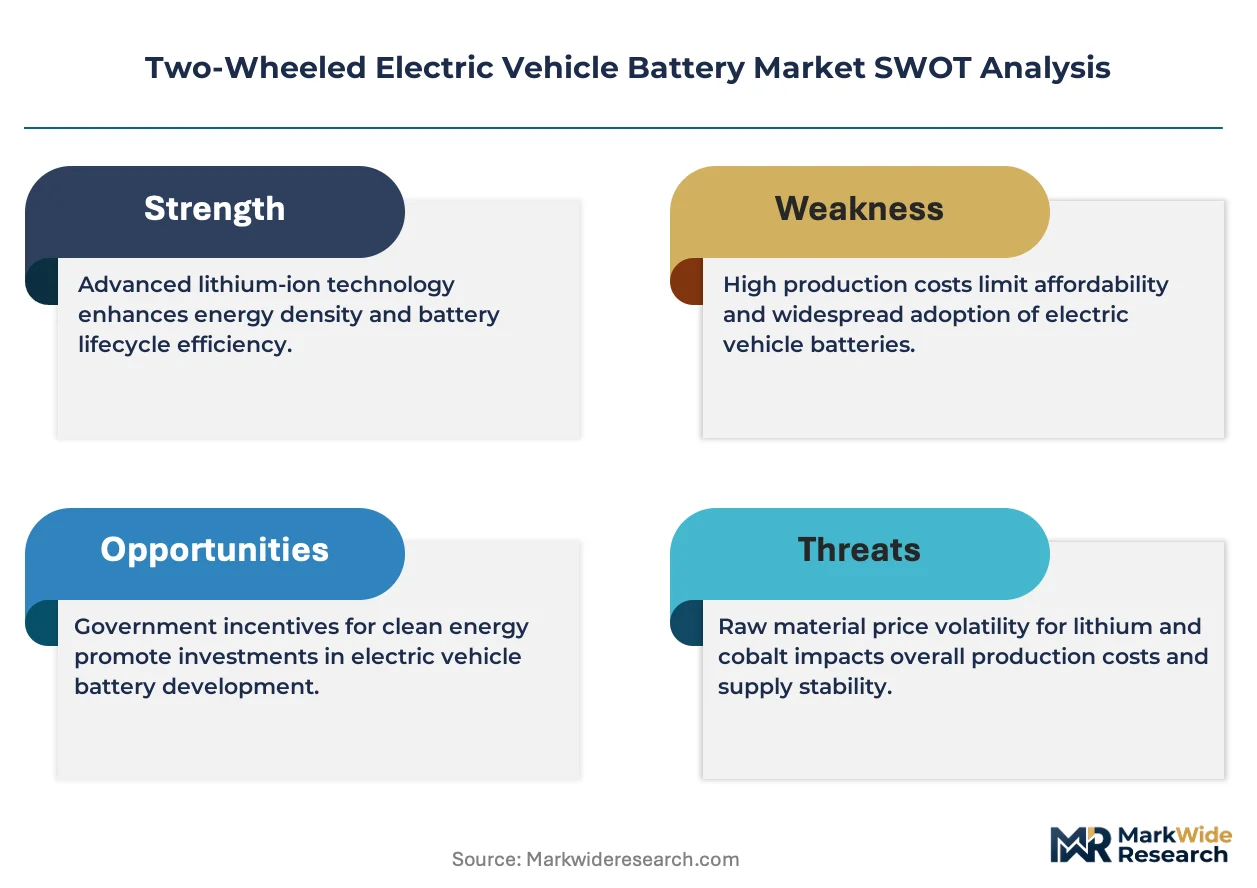
Market Dynamics
China's NMPA cell certification rules and the EU Battery Regulation are fragmenting the supply base, forcing manufacturers to localize assembly and source recycled content to maintain market access across major export corridors.
Growth Catalysts
- Last-mile delivery electrification:Fleet operators are converting to electric two-wheelers at accelerating rates, pulling demand for swappable battery networks and fast-charging infrastructure.
- Lithium-iron-phosphate chemistry:This cell architecture offers cheaper, thermally stable alternatives to cobalt-dense formats, expanding addressable markets in price-sensitive segments.
- India's BIS IS 16046 mandate:Import testing requirements for lithium-ion batteries are driving domestic assembly investments and quality upgrades across the supply chain.
Market Restraints
- Cobalt price volatility:Input cost swings for cobalt-dense chemistries compress margins for manufacturers locked into legacy cell designs.
- Supply concentration in Asia-Pacific:Cell production gravity centers on a limited geography, exposing buyers to geopolitical and logistics disruption risks.
- Lead-acid residual share:Price-sensitive replacement markets across South Asia and Africa retain this substitute technology, slowing premium battery penetration.
Strategic Opportunities
- Solid-state commercialization:Next-generation prototypes targeting mid-decade market entry promise energy density breakthroughs for premium scooter platforms.
- Battery passport mandates:Early compliance with carbon footprint disclosure requirements will reshape supply chain documentation and create first-mover advantages.
- Southeast Asian urban corridors:Underpenetrated demand concentrates in Indonesia, Vietnam, and Thailand, where two-wheeler dependency remains structural.
Industry Challenges
- GB standards compliance timelines:China's NMPA certification processes create bottlenecks for new market entrants unfamiliar with local testing protocols.
- Swappable network integration:Fleet operators demand asset-light uptime models, forcing battery makers to reconfigure product architectures for interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Two-Wheeled Electric Vehicle Battery Market |
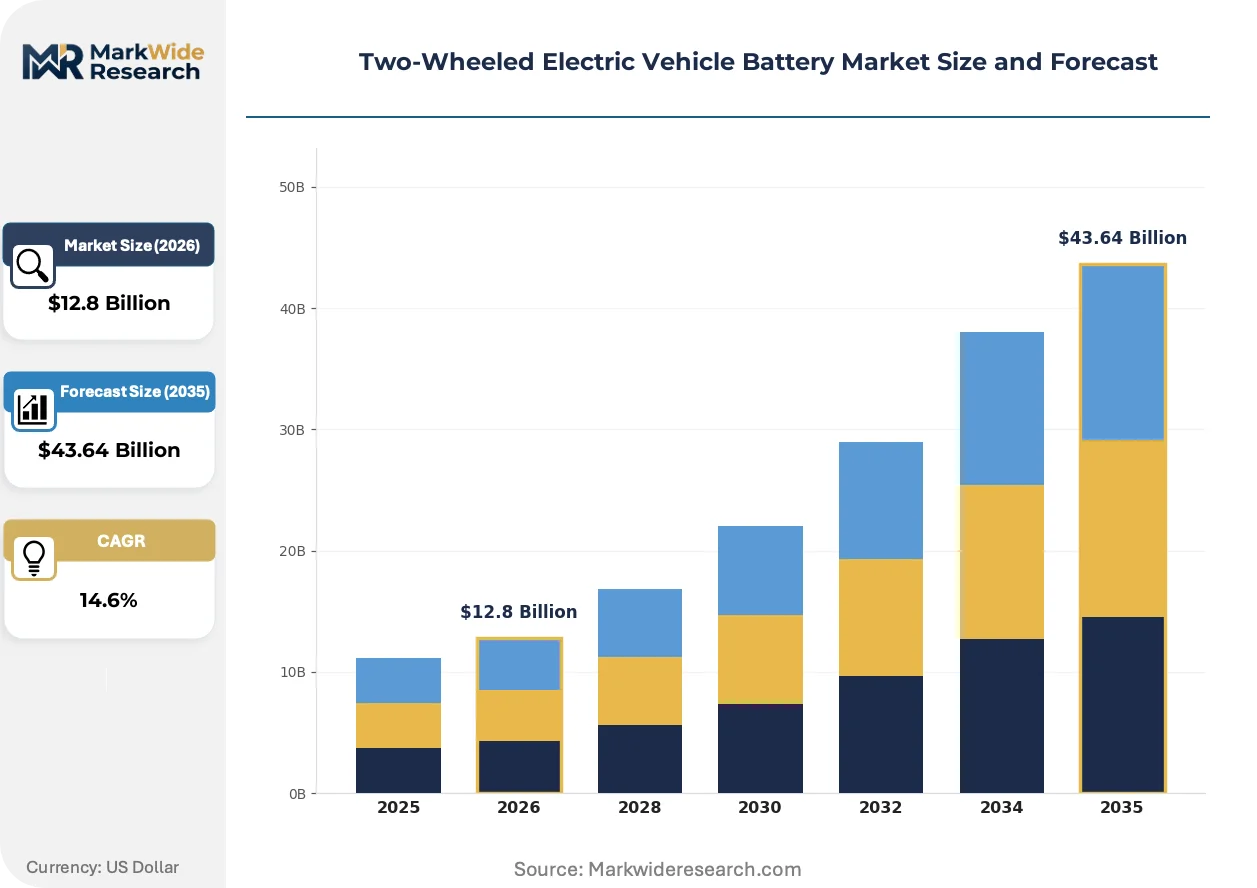
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $43.64 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Nickel-metal Hydride, Others End User: Delivery Services, Recreational Users, Commuters, Manufacturers Technology: Fast Charging, Swappable Battery, Smart Battery Management, Regenerative Braking Capacity: Below 10 Ah, 10-20 Ah, 21-30 Ah, Above 30 Ah |
| Companies Covered | Panasonic Holdings Corporation, BYD Company Ltd, EnerSys, Exide Industries Ltd, Duracell Inc., Contemporary Amperex Technology Co. Limited, LG Energy Solution, Samsung SDI, ATL Advanced Technology & Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Two-Wheeled Electric Vehicle Battery Market Trends and Innovations
Cell chemistry diversification, regulatory disclosure mandates, and fleet procurement model evolution are compressing product lifecycles and rewiring competitive advantage in the two-wheeled electric vehicle battery sector.
Lithium-iron-phosphate cells deliver sustained discharge currents above 2C with superior thermal stability compared to nickel-cobalt-manganese alternatives. Scooter OEMs in India and Southeast Asia are adopting this chemistry for urban range-optimized packs. The shift is rendering obsolete cobalt-dependent supply contracts that anchored premium pricing structures.
The EU Battery Regulation mandates carbon footprint disclosure and recycled content thresholds for cells entering European markets. Manufacturers must localize assembly and establish reverse logistics for end-of-life collection. Premium scooter platforms targeting EU type-approval face the steepest compliance cost escalations.
Fleet operators now prioritize battery-as-a-service models over capital-heavy pack ownership. Swappable network providers capture disproportionate capital flow by guaranteeing uptime through standardized form factors. This behavioral pivot is most visible in India's last-mile delivery corridors, where asset-light structures dominate procurement decisions.
Two-Wheeled Electric Vehicle Battery Market Segmentation
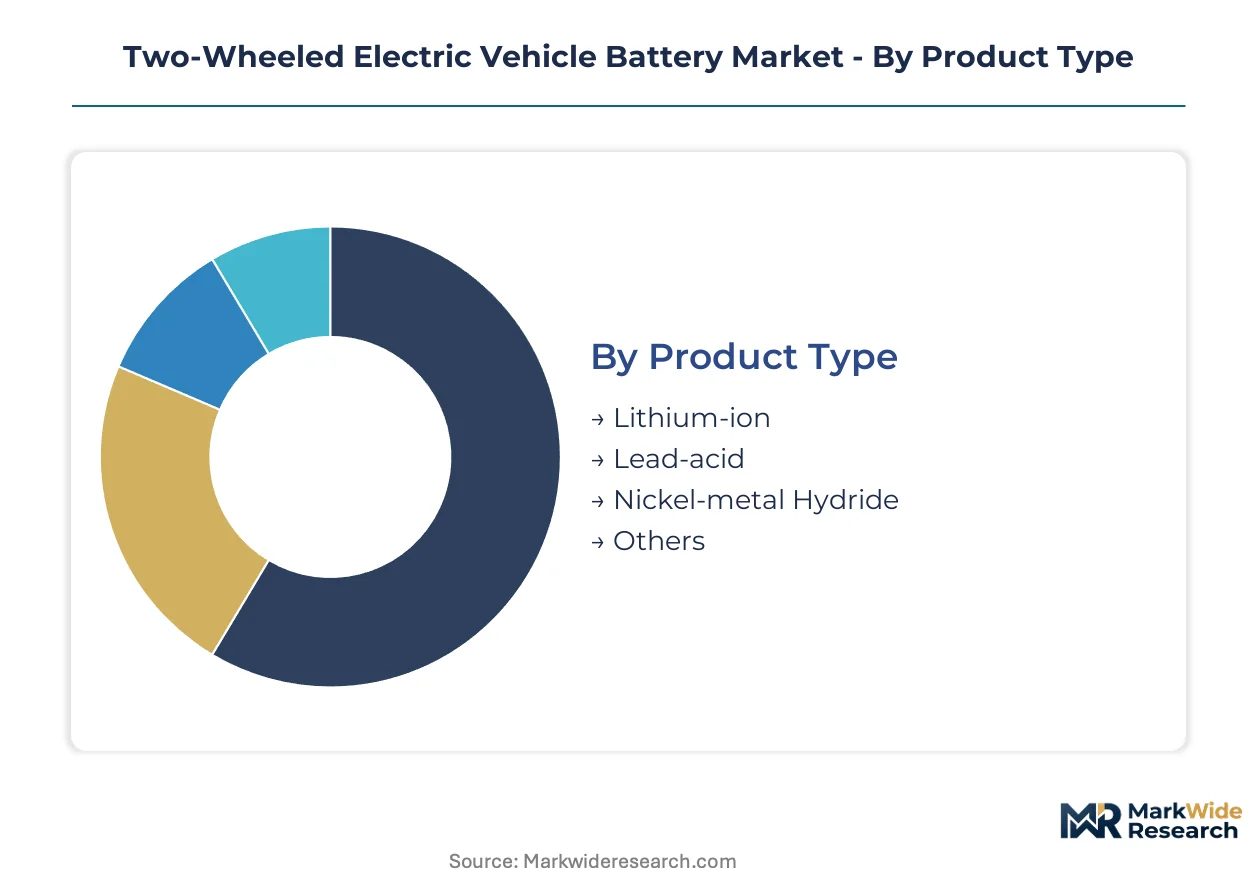
Two-wheeled electric vehicle battery segmentation reveals distinct replacement cycles and margin profiles across chemistry types, user behaviors, and technical specifications. Fleet operators and individual consumers exhibit fundamentally different procurement patterns, forcing manufacturers to architect parallel product lines.
Product Type:
Replacement frequency varies dramatically across chemistries, with some technologies cycling every 18 months under heavy fleet use while others persist for 4-5 years in light commuter applications.
- Lithium-ion:Gravimetric energy density exceeding 250 Wh/kg enables compact pack designs for premium scooters and electric motorcycles. India's BIS IS 16046 certification requirements are accelerating domestic assembly investments for this chemistry as imports face extended testing timelines.
- Lead-acid:Residual cost advantage sustains demand in South Asian and African replacement markets where upfront price sensitivity dominates total cost-of-ownership calculations. Thermal management requirements are minimal, simplifying pack integration for low-speed mopeds.
- Nickel-metal Hydride:Moderate energy density and established recycling infrastructure support niche applications in hybrid two-wheeler prototypes. Toyota's Prius-era cell architecture occasionally resurfaces in experimental platforms.
- Others:Sodium-ion and solid-state prototypes occupy pre-commercial development phases, with laboratory cells targeting mid-decade scooter integration.
Lithium-ion anchors the volume base while Lead-acid retains residual share in price-sensitive replacement corridors.
End User:
Procurement scale and uptime requirements separate fleet purchasers from individual consumers, rewiring distribution channels and service expectations.
- Delivery Services:Asset-light operators prioritize swappable battery networks guaranteeing 99% fleet availability through standardized form factors. Zomato and Swiggy in India have converted substantial last-mile fleets to electric two-wheelers, pulling capital toward interoperability-focused pack designs.
- Commuters:Daily urban travel under 50 kilometers drives demand for 21-30 Ah capacity bands balancing range anxiety against pack weight. Charging infrastructure access shapes purchase decisions more than absolute range specifications.
- Recreational Users:Weekend touring and enthusiast segments tolerate premium pricing for high-discharge-rate cells enabling rapid acceleration. Aftermarket modification culture sustains niche demand for custom pack configurations.
- Manufacturers:OEM integration contracts require automotive-grade quality systems and multi-year supply commitments, favoring established cell producers with proven scale.
Delivery Services command the steepest procurement volume growth while Commuters represent the broadest addressable population.
Technology:
Capital deployment intensity separates infrastructure-heavy models from electronics-integrated pack architectures.
- Swappable Battery:Network providers capture disproportionate investor attention by decoupling battery ownership from vehicle acquisition. Gogoro's Taiwan-origin system demonstrates viability at metropolitan scale, with Indian operators replicating the model across Bangalore and Delhi corridors.
- Fast Charging:80% state-of-charge targets within 30 minutes require specialized thermal management and high-C-rate cell chemistries. Grid connection upgrades at charging hubs constrain deployment velocity in emerging markets.
- Smart Battery Management:Cell balancing algorithms and predictive degradation monitoring extend effective pack life while enabling usage-based insurance products. Firmware update capabilities differentiate premium offerings.
- Regenerative Braking:Kinetic energy recovery systems add 8-15% range extension in stop-and-go urban environments, justifying incremental cost for fleet operators with predictable route profiles.
Swappable Battery networks expand most quickly in capital-rich metropolitan deployments while Smart Battery Management penetrates across all price tiers.
Capacity:
Urban range requirements and vehicle weight regulations create distinct optimization points across the capacity spectrum.
- 21-30 Ah:The deepest margin pool in the sector balances 60-80 kilometer urban range against pack mass constraints for 50-125cc equivalent scooters. India's Ola Electric and Ather Energy have standardized around this band for domestic market dominance.
- 10-20 Ah:Entry-level mopeds and low-speed electric bicycles target price points under $1,500, accepting 40-50 kilometer range limitations. Lead-acid competition is most intense in this bracket.
- Below 10 Ah:Micro-mobility applications including e-bikes and standing scooters prioritize minimal weight over range, with 15-25 kilometer ratings sufficient for last-kilometer connectivity.
- Above 30 Ah:Electric motorcycles and premium touring scooters require 100+ kilometer range capabilities, demanding sophisticated thermal management and chassis integration engineering.
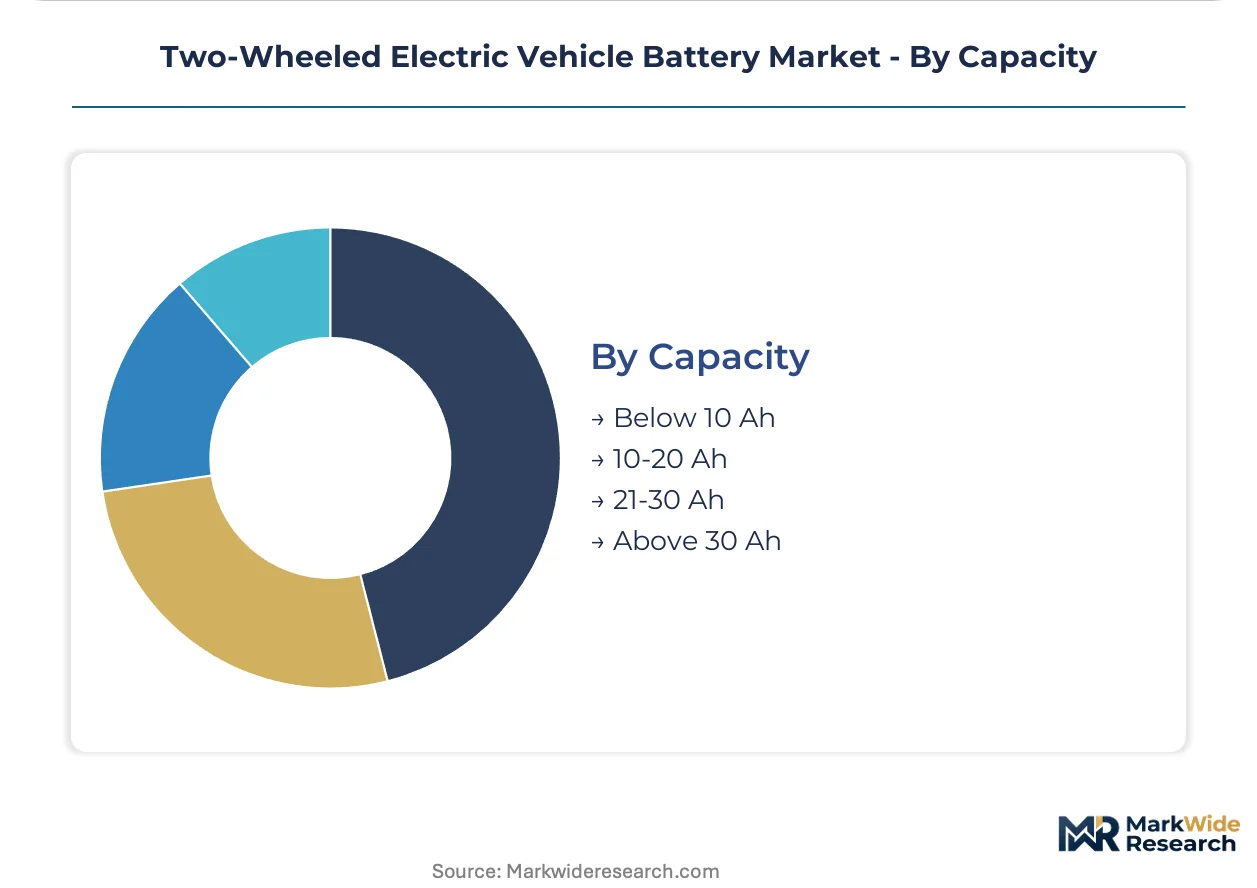
21-30 Ah holds the revenue concentration while Above 30 Ah climbs the fastest as electric motorcycle platforms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese cell exports dominate supply corridors into India and Southeast Asian urban markets, with NMPA-certified cylindrical and prismatic formats anchoring cross-border procurement flows for two-wheeled electrification programs.
China
Domestic OEM integration and export manufacturing pull massive cylindrical cell output from CATL and BYD facilities. NMPA certification under GB standards creates compliance bottlenecks for foreign entrants unfamiliar with local testing protocols. The Yangtze River Delta cluster around Shanghai and Suzhou concentrates prismatic cell assembly for premium scooter platforms.
India
Last-mile delivery electrification drives fleet procurement at accelerating rates, with Zomato and Swiggy converting substantial two-wheeler pools. BIS mandates IS 16046 testing for lithium-ion imports, forcing domestic assembly investments and quality upgrades. The Delhi-NCR corridor anchors swappable battery network deployments across Bangalore and Mumbai.
Vietnam
Motorcycle-dependent urban mobility sustains structural demand for 21-30 Ah capacity packs balancing range against chassis weight constraints. The country's national standards body enforces import testing regimes that favor localized pack integration. Ho Chi Minh City and Hanoi concentrate aftermarket conversion workshops and charging hub development.
Indonesia
Two-wheeler volume leadership across Southeast Asia creates underpenetrated addressable markets for lithium-ion substitution. Government electric vehicle incentive programs target domestic manufacturing capacity buildout. The Jakarta-Bandung industrial corridor attracts cell assembly joint ventures seeking proximity to ASEAN distribution networks.
Germany
Premium scooter OEMs source automotive-grade cells for EU type-approval platforms facing steep compliance cost escalations. KBA enforcement of CE marking and the EU Battery Regulation mandates carbon footprint disclosure and recycled content thresholds. Bavaria's industrial base hosts pack integration facilities serving continental last-mile logistics operators.
Two-Wheeled Electric Vehicle Battery Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base concentrates around three strategic archetypes: scale-driven cylindrical cell producers, chemistry-specialist premium suppliers, and integrated battery-as-a-service network operators. Dominant competitive moves include strategic partnerships for swappable network interoperability and geographic expansion through localized assembly investments.
Among Asia-Pacific-based producers, Contemporary Amperex Technology Co. Limited and BYD Company Ltd exemplify scale-driven archetypes with massive cylindrical and prismatic output. LG Energy Solution occupies a position within the chemistry-specialist tier, representing high-nickel expertise leveraged for automotive-grade quality systems. Panasonic Holdings Corporation anchors the diversified industrial conglomerate archetype with cross-sector electrochemical capabilities.
| Leading Market Players |
|---|
| Panasonic Holdings Corporation |
| BYD Company Ltd |
| EnerSys |
| Exide Industries Ltd |
| Duracell Inc. |
| Contemporary Amperex Technology Co. Limited |
| LG Energy Solution |
| Samsung SDI |
| ATL Advanced Technology & Materials |
| Others |
Pricing and Supply Chain Analysis
China's NMPA certification bottlenecks create asymmetric tariff exposure that widens pricing spreads between certified and non-certified cell tiers while forcing supply chain reconfiguration toward localized assembly hubs. This regulatory chokepoint simultaneously compresses margins for importers and rewards domestic producers with pricing power across India and Southeast Asian corridors.
Pricing Analysis
The technology-generation pricing gap separates lithium-iron-phosphate deployments from cobalt-dense legacy formats and pre-commercial solid-state prototypes. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under EU Battery Regulation carbon disclosure rules and volume scale commitments from fleet operators. Cost compression in the economy tier intensifies because lead-acid substitution pressure from South Asian replacement markets forces lithium-ion producers to match upfront price points. Delivery services exhibit the sharpest price sensitivity due to asset-light procurement models, while recreational users tolerate premium positioning for high-discharge-rate cell configurations.
Supply Chain Analysis
Tariff exposure between China and India dominates supply chain risk calculations for cylindrical cell imports facing BIS IS 16046 testing delays. Production gravity centers on China, South Korea, and Japan, with the Yangtze River Delta and Gyeonggi Province anchoring cathode active material and separator supply. Raw material dependencies rest on lithium carbonate from Australian hard-rock operations, cobalt hydroxide from the DRC, and nickel sulfate from Indonesian integrated facilities. Single-source vulnerability concentrates in separator membrane supply where Japanese and Korean producers control technical-grade output. Distribution runs through OEM direct contracts for premium scooter platforms and aftermarket channel networks for replacement demand across urban Indian corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-as-a-service subscription layers expand faster than hardware sales as fleet operators prioritize uptime guarantees over capital ownership, creating recurring revenue pools that reshape valuation frameworks across the sector.
For Market Incumbents: Entrench network effects by deepening backward integration into cathode precursor production and securing exclusive interoperability standards with dominant swappable network operators. Threaten margin compression from sodium-ion substitution in the economy tier demands defensive certification investments under India's BIS regime to maintain premium positioning. Capacity addition in Vietnam and Indonesia preserves access to ASEAN growth corridors while mitigating tariff exposure. For New Entrants and Emerging Players: Establish a beachhead in Indonesia's underpenetrated two-wheeler conversion market where domestic manufacturing incentives reduce import dependency for new cell assembly investments. The 21-30 Ah commuter segment offers the most penetrable white space given established players' fleet-focused product architectures. A go-to-market angle emphasizing smart battery management firmware differentiation targets premium commuter price tolerance for predictive degradation monitoring. For Investors and Strategic Acquirers: The market sits at a chemistry-transition phase that favors integrated battery-as-a-service operators with captive network density over pure-play cell producers. Long-term viability across the next decade hinges on regulatory compliance capabilities rather than scale economics alone. Acquisition target archetype: regional pack integrators with established reverse logistics infrastructure and BIS or NMPA certification track records. The signal to watch is mandatory battery passport implementation timelines in the EU, which will abruptly revalue documentation-ready supply chains against legacy competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Swappable Network Interoperability | Gogoro-standard compatibility unlocks fleet procurement decisions from Zomato and Swiggy operators. |
| Localized Assembly Investment | Domestic pack integration in India satisfies BIS IS 16046 mandates while reducing import testing timelines. |
| Lithium-Iron-Phosphate Transition | Cobalt chemistry abandonment aligns with EU Battery Regulation carbon disclosure thresholds and thermal stability requirements. |
| Solid-State R&D Partnership | Samsung SDI-type prototype collaboration positions premium scooter platforms for mid-decade energy density breakthroughs. |
| Reverse Logistics Buildout | End-of-life collection infrastructure satisfies EU recycled content mandates and creates secondary material feedstock security. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement directors at Indian delivery services, cell engineering leads at cylindrical producers, aftermarket distributors in Ho Chi Minh City, and regulatory compliance officers navigating NMPA certification protocols. Secondary validation drew from customs trade databases, BIS notification records, EU Battery Regulation implementation guidance, and IEA electric vehicle deployment tracking. Bottom-up cell shipment modeling and top-down two-wheeler electrification penetration rates were triangulated to constrain estimate variance.
Calibration against historical chemistry transitions and regulatory implementation timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include cell chemistry type, end-user procurement behavior, technology integration level, and capacity band clustering. CAGRs were derived from installed base turnover rates and replacement cycle compression under fleet utilization intensity. Industry-specific forecast inputs incorporated NMPA certification queue lengths and swappable network station deployment trajectories.
Sensitivities concentrate around NMPA processing delays, cobalt price volatility, and EU battery passport mandate acceleration. Forecasts reflect documented assumptions regarding fleet conversion timelines and infrastructure buildout rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Singapore Electric Vehicle Market
Electric Vehicles
China Automotive High Performance Electric Vehicle Market
Electric Vehicles
Africa Electric Scooter Market
Electric Vehicles
Global Electric Vehicle (EV) Management Solution Market
Electric Vehicles
Electric Mobility Market
Electric Vehicles
Asia-Pacific Train Battery Market
Electric Vehicles
E-Bike Battery Pack Market
Electric Vehicles
Electric Vehicle Power Control Unit Market
Electric Vehicles
Oman EV Market
Electric Vehicles
EV Lightweight Materials Market
Electric Vehicles
48V Mild Hybrid Electric Vehicle (MHEV) Market
Electric Vehicles
Electric Vehicle UBI Market
Electric Vehicles
Automotive Battery Pack Compression Pad Market
Electric Vehicles
High Voltage PTC Heaters for Electric Vehicles Market
Electric Vehicles
France Hybrid Electric Vehicle Battery Market
Electric Vehicles
Europe Electric Truck Market