
 France Solar E-Bike Market | 2026-2036
France Solar E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
France Solar E-Bike Market Insights
Pay-as-you-ride leasing and fleet-as-a-service subscription models is fragmenting capital requirements across the France solar e-bike competitive landscape. Wayscral leverages its vertically integrated manufacturing footprint in Brittany to control component costs and shorten delivery cycles. Velobecane competes through design specialization in lightweight frames optimized for photovoltaic panel integration. Eovolt anchors its position via direct-to-consumer digital channels that bypass traditional retail markups.
A solar e-bike combines a battery-electric bicycle with photovoltaic cells mounted on the frame, cargo rack, or detachable panel arrays, typically generating 6-15 watts under standard irradiance to supplement or recharge the lithium-ion power system during daylight operation. The primary purpose is extending range and reducing grid-dependency for urban and peri-urban mobility applications. Fully assembled units dominate current revenue pools due to consumer preference for warranty-backed, road-legal configurations, while conversion kits represent the fastest-expanding segment among technically adept users retrofitting conventional bicycles. Lithium-ion batteries sustain the majority of installed capacity, though lithium polymer variants gain traction in premium models seeking reduced weight profiles.
France's national regulator for energy transition, ADEME, shapes product eligibility through clean mobility subsidy frameworks that favor domestically assembled vehicles with verified carbon footprints. The Fédération des Usagers de la Bicyclette influences municipal procurement standards, while EU-wide CE marking and the Machinery Directive establish baseline safety and electromagnetic compatibility requirements for photovoltaic-integrated transport equipment. Stakeholders must monitor how forthcoming revisions to France's sustainable transport subsidy tiers treat imported versus locally manufactured solar charging components.
Market Dynamics
Municipal procurement cycles for solar-assisted fleet bicycles are compressing delivery timelines and forcing manufacturers to pre-certify photovoltaic-integrated configurations before tender submission windows open.
Growth Catalysts
- ADEME Clean Mobility Subsidies:France's national energy transition agency ties purchase incentives to verified domestic assembly and carbon footprint thresholds, accelerating certified product pipelines.
- Île-de-France Municipal Fleets:Paris and surrounding municipalities mandate photovoltaic charging infrastructure in new bike-sharing contracts, creating guaranteed offtake for compliant suppliers.
- Perovskite Cell Efficiency Gains:Laboratory-grade thin-film photovoltaic materials are transitioning to bicycle-mountable formats, extending supplemental charge rates beyond legacy silicon benchmarks.
Market Restraints
- Lithium Carbonate Price Volatility:Battery pack input costs fluctuate with Chilean and Australian spodumene contract pricing, squeezing margin structures for mid-tier assemblers.
- Photovoltaic Component Import Concentration:High-efficiency cells for bicycle-scale panels concentrate among East Asian wafer manufacturers, exposing supply continuity to maritime logistics disruptions.
- CE Marking Electromagnetic Compatibility:The Machinery Directive's testing protocols for integrated solar charging systems extend certification timelines by four to six months versus conventional e-bikes.
Strategic Opportunities
- Auvergne-Rhône-Alpes Regional Expansion:Lyon and Grenoble municipal transit authorities lag Paris procurement volumes, presenting first-mover positioning for certified entrants.
- Last-Mile Logistics Substitution:Courier and parcel delivery fleets in peri-urban zones are piloting solar e-bikes to displace small-format thermal vehicles, opening fleet-as-a-service contract structures.
- Fédération des Usagers de la Bicyclette Procurement Standards:Advocacy-aligned municipal purchasing frameworks favor vehicles with verified lifecycle carbon assessments, rewarding transparent supply chain documentation.
Industry Challenges
- Photovoltaic-Battery Thermal Integration:Engineers with combined expertise in semiconductor packaging and lithium-ion thermal management remain scarce in French manufacturing clusters.
- Multi-Agency Certification Sequencing:Products must clear ADEME carbon verification, ANSM electrical safety review, and municipal technical specifications in non-overlapping review cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Solar E-Bike Market |
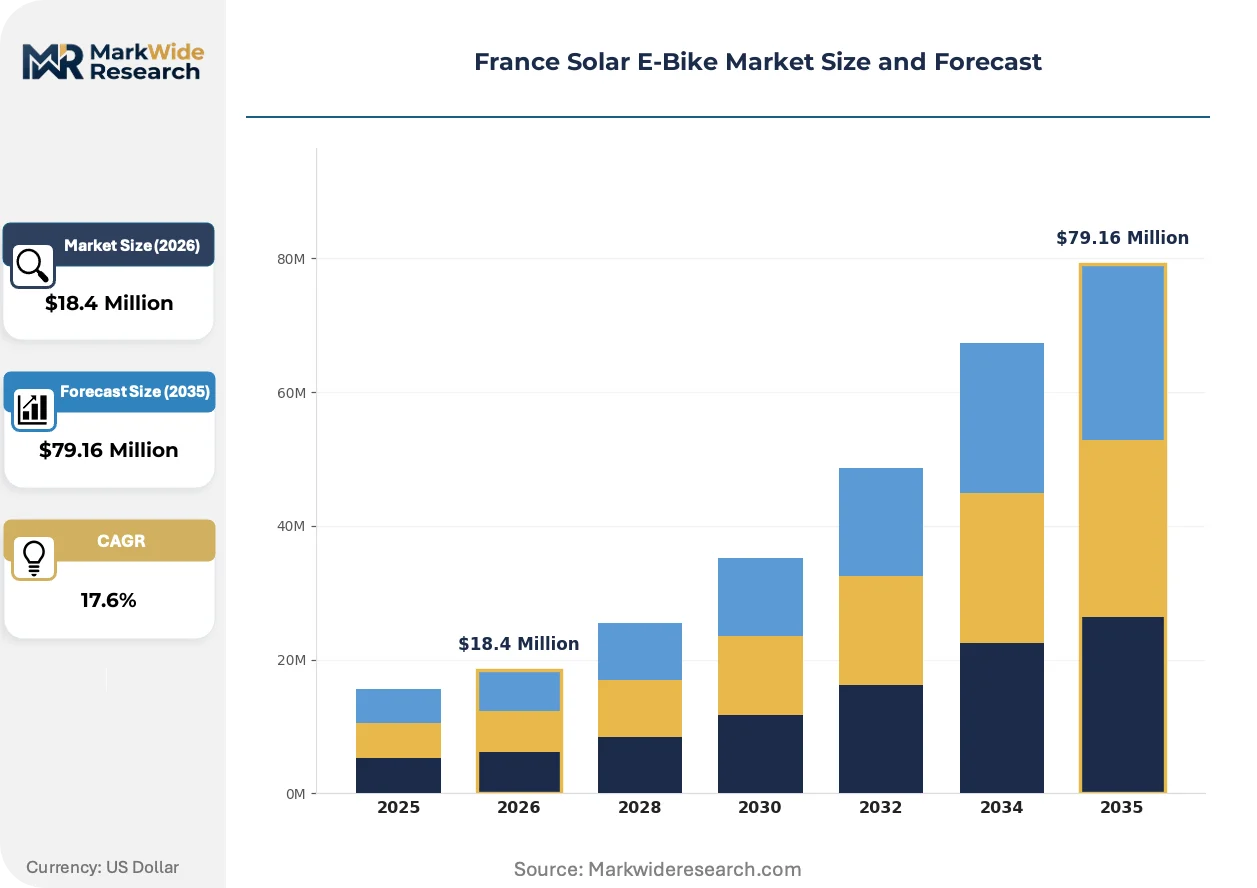
| Market Size in 2026 | $18.4 Million |
| Market Size in 2035 | $79.16 Million |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semi-Finished, Fully Assembled, DIY Kits, Conversion Kits Battery Type: Lithium-Ion, Lithium Polymer, Lead Acid, Others Sensor Technology: Torque Sensors, Cadence Sensors, Speed Sensors, Integrated Sensors Usage Type: Commuting, Leisure, Cargo Transport, Off-Road |
| Companies Covered | Wayscral, Velobecane, Eovolt, O2feel, Voltaire, Zoov, Rossignol, T-bird, Vepli, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Solar E-Bike Market Trends and Innovations
Photovoltaic integration architectures and procurement financing models are diverging from conventional e-bike industry templates, compressing product development cycles and fragmenting buyer-seller relationships.
Detachable monocrystalline panel arrays with proprietary frame mounting systems are rendering obsolete fixed-frame solar configurations that limited rider flexibility and repair accessibility. Municipal fleet operators in Bordeaux and Nantes specify swappable panel formats to minimize downtime during maintenance windows. This modularity is rendering obsolete the integrated-frame designs that dominated early product generations.
France's transposition of the EU F-Gas Regulation into national environmental code is tightening refrigerant disclosure requirements for battery thermal management systems, even in non-refrigerated transport applications. Manufacturers must now document coolant chemistries across their supplier tiers to maintain ADEME subsidy eligibility. Premium lithium polymer configurations are most affected, as their gel electrolyte formulations require enhanced material safety data sheet compliance.
Subscription-based fleet access contracts are displacing direct capital purchase for urban delivery and municipal shared-mobility applications. Logistics coordinators in the Hauts-de-France region now contract for per-kilometer service levels rather than asset ownership, transferring photovoltaic performance risk to operator-lessors. This unbundling is most visible among refrigerated last-mile carriers seeking to offset diesel van kilometers with solar-assisted bicycle fleets.
France Solar E-Bike Market Segmentation
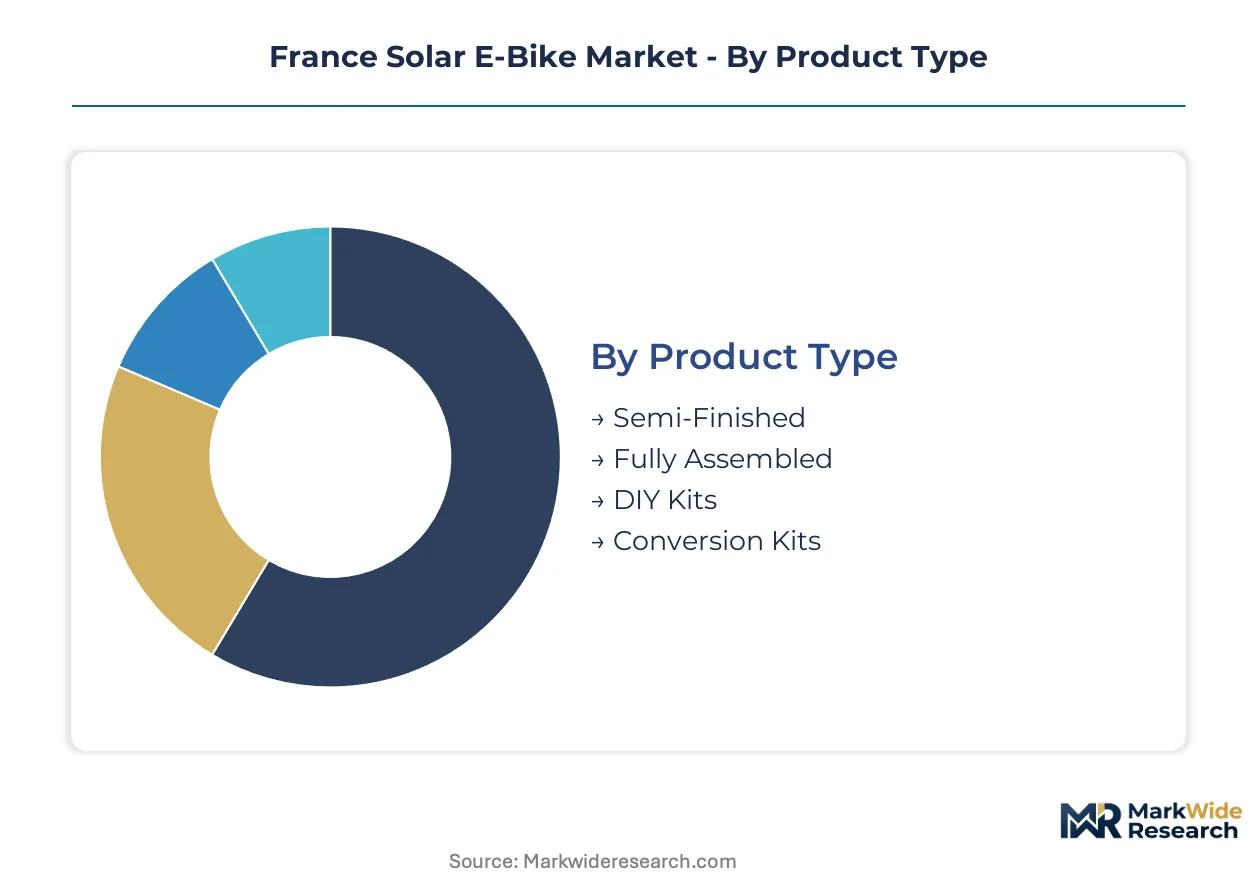
Segmentation in France's solar e-bike market reveals divergent procurement cycles and margin structures across product configurations and end-use applications. Municipal fleet buyers prioritize fully assembled units with certified photovoltaic integration, while enthusiast segments drive faster turnover in modular and retrofit categories.
Product Type:
Cycle times vary sharply across product formats, with fully assembled units requiring six-to-nine-month procurement pipelines versus DIY kits turning in two-to-four-week direct-to-consumer windows.
- Fully Assembled:Factory-integrated photovoltaic cells mounted on frames or cargo racks deliver warranty-backed, road-legal configurations certified under CE marking and Machinery Directive protocols. Paris municipal bike-sharing contracts and Île-de-France fleet operators specify these units exclusively, prioritizing manufacturer liability coverage over upfront cost minimization.
- Conversion Kits:Retrofit photovoltaic panel arrays and controller systems attach to conventional bicycle frames, appealing to technically adept users seeking range extension without complete vehicle replacement. The segment expands most quickly among peri-urban commuters in Auvergne-Rhône-Alpes upgrading existing assets.
- Semi-Finished:Partially assembled chassis with pre-wired electrical architecture await final photovoltaic module installation at regional assembly points.
- DIY Kits:Component bundles including cells, controllers, and mounting hardware target self-build enthusiasts with electrical competency.
Fully assembled units anchor the volume base while conversion kits gain share at the steepest rate.
Battery Type:
Cost tier stratification separates premium lithium polymer configurations from standardized lithium-ion packs, with lead acid occupying residual price-sensitive niches.
- Lithium-Ion:Cylindrical or prismatic cell configurations dominate installed capacity across French solar e-bike fleets, balancing energy density against thermal stability requirements. ADEME clean mobility subsidies require verified carbon footprint documentation for battery pack assembly, favoring domestically integrated cell management systems.
- Lithium Polymer:Pouch-cell architectures with gel electrolyte formulations reduce weight profiles for premium commuter and cargo applications. France's transposed F-Gas Regulation mandates enhanced material safety data sheet compliance for thermal management chemistries, elevating documentation burdens for this tier.
- Lead Acid:Sealed absorbent glass mat batteries persist in entry-level price brackets where range requirements remain minimal.
- Others:Emerging solid-state and sodium-ion chemistries occupy pre-commercial evaluation phases among Brittany-based manufacturers.
Lithium-ion configurations sustain the dominant revenue share while lithium polymer variants expand most quickly in premium positioning.
Sensor Technology:
Application context determines sensor selection, with torque-dominant architectures commanding cargo and hill-climb specifications against cadence-optimized leisure configurations.
- Torque Sensors:Strain-gauge measurements of pedal force deliver proportional motor assistance calibrated to rider effort, essential for laden cargo transport in Bordeaux and Nantes municipal logistics fleets. The precision elevates battery efficiency by fifteen-to-twenty percent versus simpler architectures.
- Cadence Sensors:Magnetic ring detectors measuring crank rotation speed trigger binary on-off assistance modes, sufficient for flat-terrain leisure riding. Île-de-France recreational users favor these units for cost minimization where photovoltaic supplementation reduces range anxiety.
- Speed Sensors:Hall-effect devices monitoring wheel rotation enforce regulatory speed limitations under EU type-approval frameworks.
- Integrated Sensors:Multi-parameter fusion units combining torque, cadence, and incline data optimize energy management algorithms.
Cadence sensors retain the broadest installed base while integrated sensor packages climb the fastest in next-generation procurement specifications.
Usage Type:
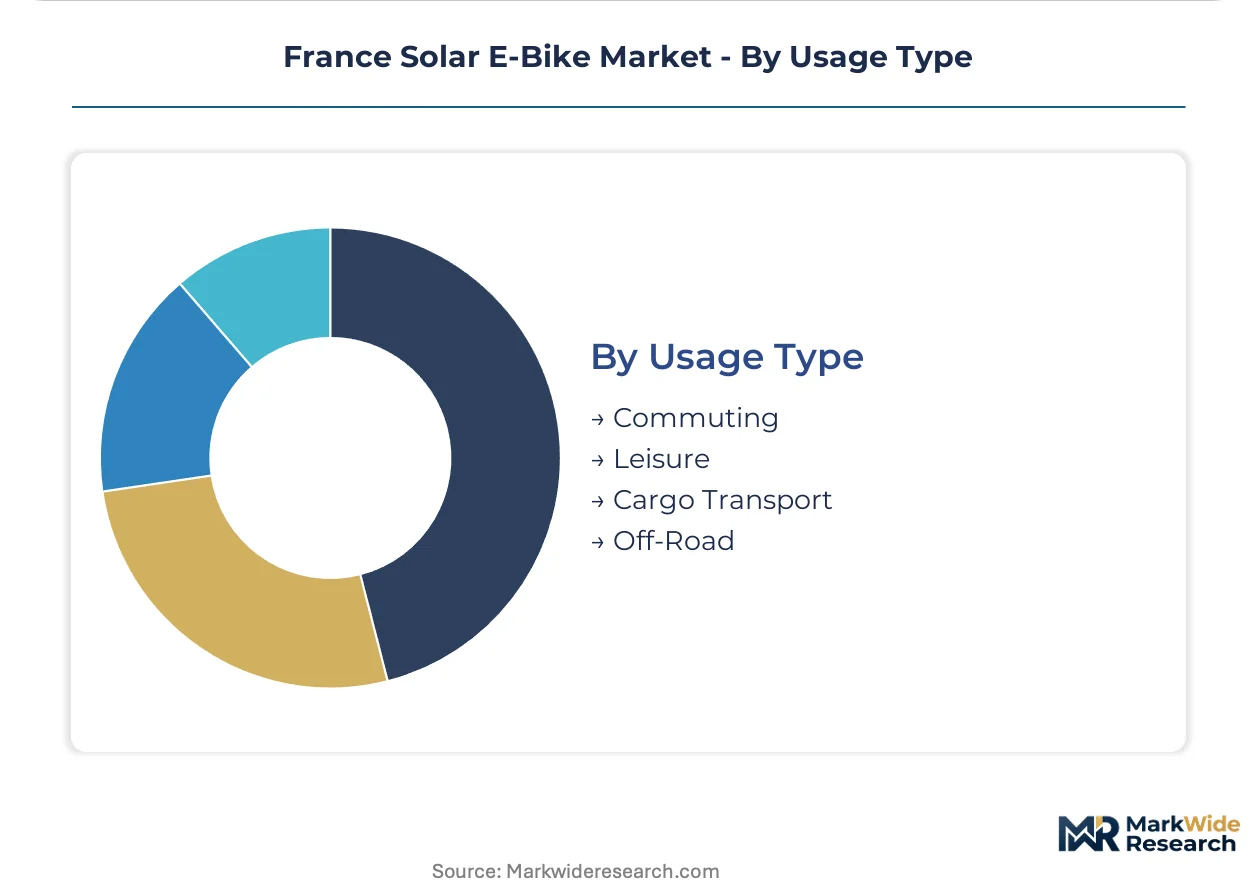
Geographic concentration patterns separate urban commuting demand in Paris and Lyon from dispersed leisure markets across coastal and alpine zones.
- Commuting:Daily urban mobility applications in Île-de-France and Auvergne-Rhône-Alpes integrate solar e-bikes into multimodal transit chains, with photovoltaic charging infrastructure at rail stations and workplace endpoints. The Fédération des Usagers de la Bicyclette advocacy alignment shapes municipal procurement standards favoring lifecycle carbon assessments.
- Cargo Transport:Last-mile delivery fleets in Hauts-de-France and Grand Est pilot solar-assisted bicycles with front-loading or long-tail configurations to displace small thermal vans. Subscription-based fleet-as-a-service contracts transfer photovoltaic performance risk from logistics operators to lessor-maintainers.
- Leisure:Recreational riding across Provence-Alpes-Côte d'Azur and Nouvelle-Aquitaine coastlines emphasizes extended range for multi-day touring.
- Off-Road:Trail and forest path applications in mountainous zones require reinforced frame architectures and all-weather photovoltaic encapsulation.
Commuting applications anchor the volume base while cargo transport gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ADEME's clean mobility subsidies and municipal procurement mandates concentrate solar e-bike deployment across France's most transit-integrated metropolitan zones. Regional demand patterns diverge sharply between dense urban cores with photovoltaic charging infrastructure and peri-urban corridors where range extension matters most.
Île-de-France
Paris municipal bike-sharing contracts mandate photovoltaic charging infrastructure, creating guaranteed offtake for certified suppliers. The Fédération des Usagers de la Bicyclette shapes procurement standards favoring lifecycle carbon assessments. Velib' operator Smovengo integrates solar-assisted fleets at Gare du Nord and La Défense transit hubs.
Auvergne-Rhône-Alpes
Lyon and Grenoble municipal transit authorities lag Paris procurement volumes, presenting first-mover positioning for certified entrants. The regional council's Mobilité Durable program subsidizes employer-provided solar e-bike fleets. Saint-Étienne hosts emerging assembly operations serving Alpine logistics corridors.
Nouvelle-Aquitaine
Bordeaux fleet operators specify swappable panel formats to minimize maintenance downtime. The Bordeaux Métropole climate plan targets thermal vehicle displacement in last-mile delivery. Arcachon Bay tourism operators pilot solar-assisted rental fleets for coastal touring circuits.
Hauts-de-France
Courier and parcel delivery fleets in Lille and Valenciennes pilot solar e-bikes to displace small-format thermal vehicles. The region's logistics density supports subscription-based fleet-as-a-service contract structures. Dunkirk port zone operators test photovoltaic-assisted cargo bicycles for intra-terminal freight.
Provence-Alpes-Côte d'Azur
Marseille and Nice municipal procurement cycles compress delivery timelines for pre-certified photovoltaic configurations. The region's solar irradiance levels optimize panel efficiency for extended recreational touring. Sophia Antipolis technology corridor attracts battery-thermal management engineering talent.
France Solar E-Bike Market Competitive Landscape
On the supply side, the industry is fragmented across vertically integrated manufacturers, design specialists, and direct-to-consumer digital platforms. Three strategic archetypes dominate: Brittany-based fabricators controlling component costs through captive production, lightweight frame specialists optimizing photovoltaic integration, and digital-native brands bypassing retail markups. Competitive moves center on pre-certification of photovoltaic-integrated configurations ahead of municipal tender windows and backward integration into battery pack assembly.
Among France-based manufacturers, Wayscral, Velobecane, and Eovolt exemplify contrasting positioning strategies. Wayscral anchors the vertically integrated archetype through its Brittany manufacturing footprint. Velobecane occupies the design-specialist tier with frame architectures optimized for photovoltaic panel mounting. Eovolt represents the direct-to-consumer digital platform model, eliminating intermediary retail layers. O2feel and Voltaire sit within adjacent competitive spaces, while specialized fleet operators including Zoov concentrate on municipal shared-mobility contracts.
| Leading Market Players |
|---|
| Wayscral |
| Velobecane |
| Eovolt |
| O2feel |
| Voltaire |
| Zoov |
| Rossignol |
| T-bird |
| Vepli |
| Others |
Pricing and Supply Chain Analysis
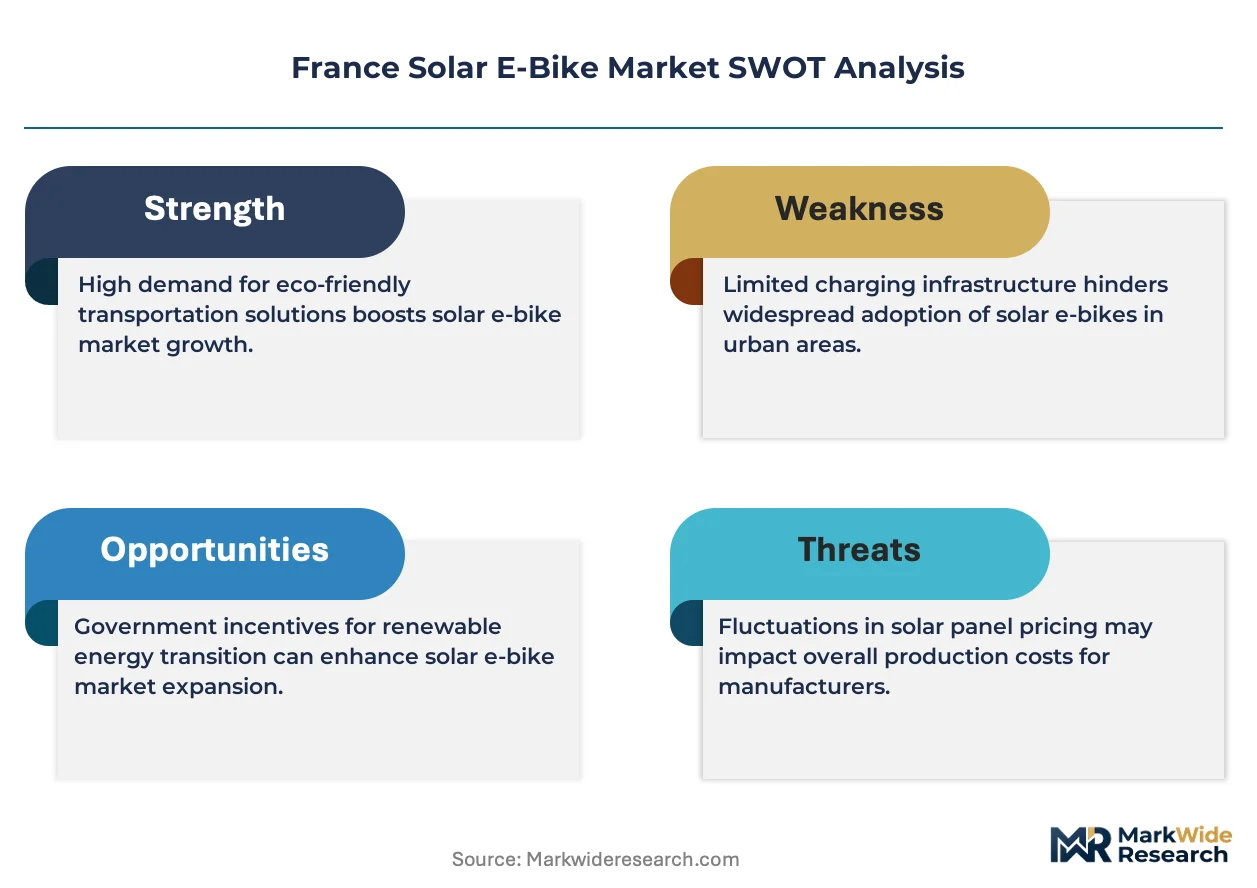
Photovoltaic cell import concentration among East Asian wafer manufacturers determines both pricing tier spreads and supply chain shape in France's solar e-bike market. Manufacturers absorbing maritime logistics volatility pass cost premiums into premium lithium polymer configurations, while mid-tier assemblers accepting longer lead times compete on entry-level lithium-ion pricing.
Pricing Analysis
Certification level under CE marking and the Machinery Directive creates the primary spread between premium and economy tiers. Three-tier pricing structure across premium, standard, and economy levels segments buyers by warranty coverage and photovoltaic integration depth. Pricing pressure stems from lithium carbonate contract volatility originating in Chilean and Australian spodumene markets. Fleet procurement coordinators in Île-de-France exhibit lowest price sensitivity due to ADEME subsidy absorption, while DIY kit enthusiasts in Auvergne-Rhône-Alpes drive hardest bargain hunting.
Supply Chain Analysis
Monocrystalline silicon wafers feed from China, Taiwan, and South Korea into Brittany-based assembly operations. Lithium-ion cell production draws from South Korean and Japanese manufacturers, with battery management system controllers sourced from German automotive tier suppliers. Single-source vulnerability concentrates in high-efficiency perovskite cell pilot lines. Distribution runs through municipal fleet procurement channels and direct-to-consumer digital platforms, bypassing traditional bicycle retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around ADEME carbon verification and CE marking protocols constructs defensive moats for certified incumbents. Municipal procurement windows favor pre-qualified suppliers with documented domestic assembly footprints.
For Market Incumbents: Harden certification pipelines by pre-clearing photovoltaic-integrated configurations through ANSM electrical safety review before tender submission deadlines. Anchor backward integration into battery pack assembly to offset lithium carbonate volatility. Secure long-term offtake agreements with Île-de-France municipal operators to lock out emerging competitors. For New Entrants and Emerging Players: Pursue white-space positioning in Auvergne-Rhône-Alpes municipal fleets, where Lyon and Grenoble procurement volumes lag Paris saturation. Target courier fleet-as-a-service contracts in Hauts-de-France logistics corridors as the most penetrable segment. Deploy direct-to-consumer digital channels to bypass retail markup structures established by incumbent distributors. For Investors and Strategic Acquirers: The market sits at an early consolidation phase that favors vertically integrated manufacturers with captive photovoltaic module sourcing. Long-term viability hinges on ADEME subsidy continuity and perovskite cell commercialization timelines. Acquisition target archetype: Brittany-based assemblers controlling component costs through in-house production. Watch lithium carbonate contract pricing as the primary inflection indicator for margin compression risk.| Strategic Initiative | Industry Significance |
|---|---|
| Photovoltaic Pre-Certification Pipeline | CE marking and Machinery Directive clearance ahead of municipal tender windows secures guaranteed offtake. |
| Battery Pack Backward Integration | In-house lithium-ion assembly reduces exposure to Chilean and Australian spodumene contract volatility. |
| Swappable Panel Modular Design | Bordeaux and Nantes fleet specifications favor detachable formats minimizing maintenance downtime. |
| Direct-to-Consumer Digital Launch | Bypassing retail markups captures price-sensitive peri-urban commuters in Auvergne-Rhône-Alpes. |
| Perovskite Cell Technology Licensing | Laboratory-grade thin-film efficiency gains extend supplemental charge rates beyond silicon benchmarks. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with product development directors at Brittany-based manufacturers, ADEME policy officers, Fédération des Usagers de la Bicyclette advocacy leads, and municipal procurement coordinators in Paris and Lyon; plus secondary validation against ADEME clean mobility subsidy filings, ANSM electrical safety registration databases, EU CE marking notification records, and municipal tender documentation from Île-de-France, Auvergne-Rhône-Alpes, and Nouvelle-Aquitaine. Bottom-up unit shipment estimates triangulated against top-down subsidy disbursement values.
Forecast inputs considered product type segmentation across fully assembled units, conversion kits, and DIY configurations; battery chemistry tiers from lithium-ion through lithium polymer; and usage type splits between commuting, cargo transport, and leisure applications. CAGRs derived from logistic growth curves fitted to municipal fleet procurement pipelines and per-kilometer fleet-as-a-service contract expansion. Industry-specific inputs incorporated photovoltaic cell efficiency improvement curves and lithium carbonate price volatility bands.
Macroeconomic conditions sit as an overlay; deviation in euro-zone industrial energy costs or maritime freight rates would shift the trajectory. Forecasts reflect documented assumptions around ADEME subsidy tier continuity and perovskite cell commercialization timelines. Cross-checking against EU bicycle import statistics and regional municipal procurement databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Self Balancing Electric Scooter Market
Electric Vehicles
Electromagnetic and Radio Frequency Interference Coating for Electric Vehicles Market
Electric Vehicles
Commercial Vehicle Electric Propulsion System Market
Electric Vehicles
Germany Electric Bus Battery Pack Market
Electric Vehicles
Scooter Market
Electric Vehicles
Train Battery Market
Electric Vehicles
Automotive Energy Harvesting and Regeneration Market
Electric Vehicles
Electric Vehicle Insulation Market
Electric Vehicles
Europe Electric Vehicle Power Inverter Market
Electric Vehicles
Global Smart Electric Drive Market
Electric Vehicles
Europe Electric Light Commercial Vehicles Market
Electric Vehicles
Electric Loader Rickshaw Market
Electric Vehicles
Europe Electric Car Market
Electric Vehicles
China Electric Truck Market
Electric Vehicles
Electric Vehicle Electric Heating Film Market
Electric Vehicles
Middle East and Africa Electric Vehicle Thermal Management System Market