
 Italy Hybrid Electric Vehicle Battery Market | 2026-2036
Italy Hybrid Electric Vehicle Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Hybrid Electric Vehicle Battery Market Insights
Italy is narrowing its reliance on imported battery cells through industrial policy aimed at reshoring production. Panasonic Holdings Corporation leverages its cylindrical cell expertise to supply European automakers from regional hubs. Italvolt anchors domestic ambitions with planned gigafactory capacity in Piedmont. LG Energy Solution competes through prismatic pouch formats optimized for hybrid architectures.
The Italy Hybrid Electric Vehicle Battery comprises electrochemical storage systems combining lithium-ion or nickel-metal hydride chemistries with power electronics, typically operating at 200-400V for mild-to-full hybrid drivetrains, designed to buffer kinetic energy during regenerative braking and discharge during torque assist. Lithium-ion dominates installed capacity due to superior energy density and cycle stability under partial-state-of-charge operation. Nickel-metal hydride retains structural relevance in cost-sensitive commercial vehicle applications where thermal tolerance outweighs gravimetric efficiency. OEMs represent the densest margin pool as they integrate battery systems at vehicle design stage rather than sourcing aftermarket replacements.
Italy's Ministry of Enterprise and Made in Italy administers automotive transition incentives under EU Green Deal alignment, while ECHA oversees REACH compliance for cathode active materials and electrolyte salts entering European supply chains. CE marking under the EU Battery Regulation mandates carbon footprint disclosure and recycled content thresholds that reshape supplier qualification criteria. Stakeholders must monitor how delegated acts on performance standards alter product development timelines and capital allocation across the value chain.
Market Dynamics
Italy's National Recovery and Resilience Plan channels state aid toward domestic cell manufacturing, compressing supplier qualification timelines and forcing Tier-1 system integrators to localize procurement or risk exclusion from OEM platform bids.
Growth Catalysts
- EU Green Deal alignment:Italy's Ministry of Enterprise and Made in Italy administers automotive transition incentives that accelerate fleet electrification procurement timelines for commercial vehicle operators.
- Lombardy supplier corridor concentration:The automotive supplier ecosystem near Milan and Turin creates dense logistics networks that reduce inbound material transit costs for battery pack assembly.
- Regenerative braking integration:Mild-hybrid architectures operating at 200-400V now standardize kinetic energy recovery systems across Italian OEM platforms, expanding addressable demand for lithium-ion cell suppliers.
Market Restraints
- Cathode active material import dependency:REACH compliance administered by ECHA for nickel, cobalt, and lithium salts entering European supply chains creates documentation bottlenecks that extend supplier onboarding cycles.
- Prismatic pouch format concentration:LG Energy Solution and Asian cell manufacturers dominate high-volume prismatic production, limiting Italian pack integrators to premium-priced cylindrical alternatives or lengthy offtake negotiations.
- Nickel-metal hydride substitution ceiling:Cost-sensitive commercial vehicle segments retain NiMH architectures where thermal tolerance outweighs gravimetric efficiency, capping lithium-ion penetration in heavy-duty applications.
Strategic Opportunities
- Piedmont gigafactory localization:Italvolt's planned production capacity anchors domestic ambitions, creating captive supply opportunities for regional automotive OEMs seeking CE marking compliance under EU Battery Regulation carbon footprint disclosure mandates.
- Cell-to-pack architecture convergence:Elimination of module housings reduces pack mass and assembly labor, enabling Italian system integrators to compete on cost with imported Asian pack solutions.
- Recycled content threshold preparation:Delegated acts under EU Battery Regulation mandate recycled lithium, nickel, and cobalt minimums that favor early movers building closed-loop partnerships with Piedmont metallurgical processors.
Industry Challenges
- Electrochemical engineering talent scarcity:Italian universities produce insufficient graduates with solid-state electrolyte and thermal runaway modeling expertise, forcing pack manufacturers to recruit from German and French competitor pools.
- CE marking certification timeline compression:Carbon footprint disclosure requirements and recycled content verification protocols demand documentation systems that most mid-tier Italian suppliers have not yet operationalized.
- Legacy 12V electrical architecture integration:Full-hybrid systems must interface with existing vehicle networks designed for lead-acid loads, creating voltage stabilization and fault-handling complexity that extends development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Hybrid Electric Vehicle Battery Market |
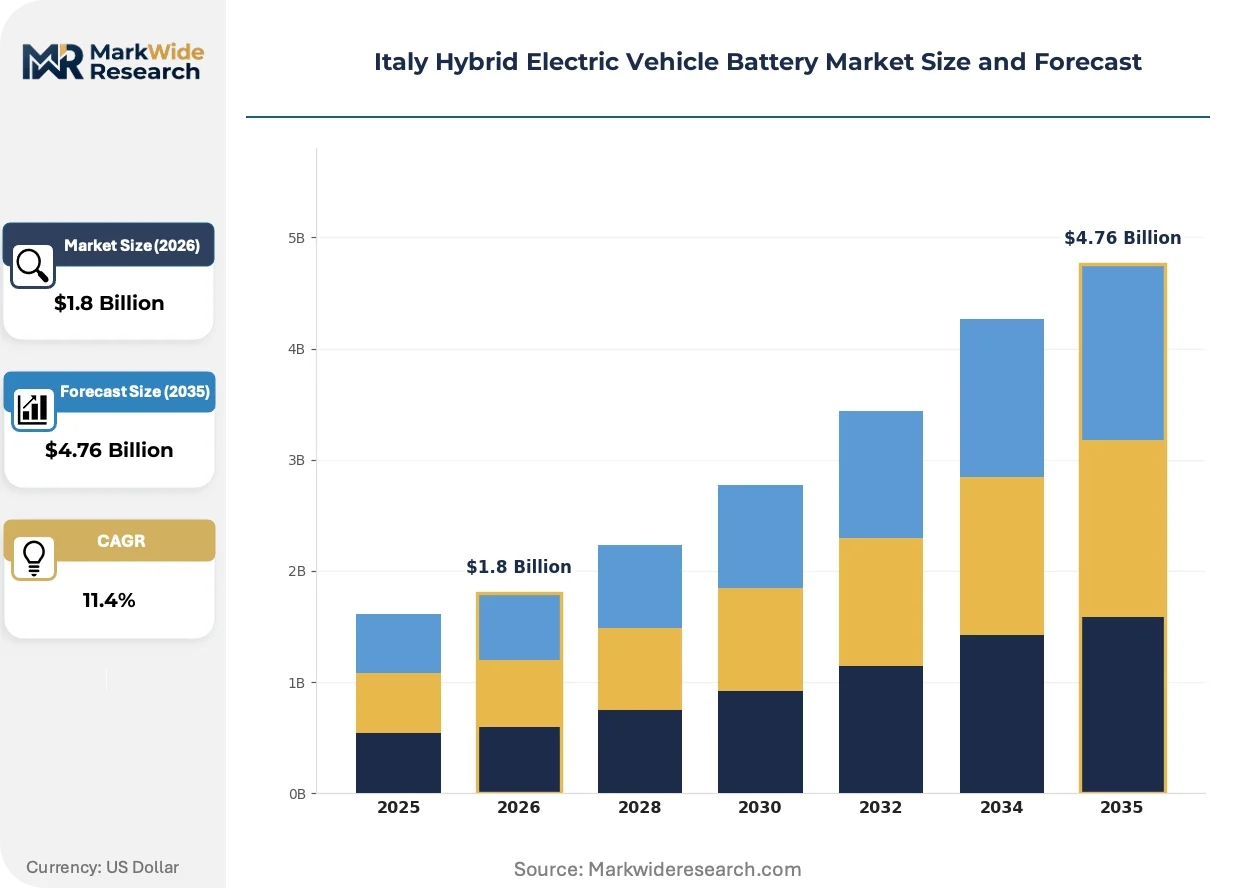
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-ion, Nickel-metal Hydride, Solid-state, Lead-acid Application: Passenger Cars, Commercial Vehicles, Two-wheelers, Buses End User: OEMs, Fleet Operators, Individual Consumers, Aftermarket Players Charging Method: Home Charging, Public Charging, Fast Charging, Inductive Charging |
| Companies Covered | EnerSys, Automotive Cells Company, Panasonic Holdings Corporation, Italvolt, Saft (TotalEnergies), BYD Company, Exide Industries Ltd, Gruppo Seri, LG Energy Solution, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Hybrid Electric Vehicle Battery Market Trends and Innovations
Cell chemistry and pack architecture decisions are converging around regulatory compliance rather than pure performance optimization, with Italian stakeholders prioritizing supply chain traceability systems that satisfy delegated acts under EU Battery Regulation.
Solid-state electrolyte research is hybridizing conventional lithium-ion manufacturing lines, with Piedmont-based pilot facilities retrofitting existing electrode coating equipment to handle sulfide and oxide ceramic separators. Italian automotive OEMs are qualifying these cells for 2028 platform introductions, compressing the timeline for liquid electrolyte dominance in European hybrid applications. The technology is hybridizing competitive positioning between established Asian cell giants and emerging European producers.
CE marking under EU Battery Regulation mandates carbon footprint disclosure at the cell level, forcing Italian pack integrators to deploy blockchain-tracked supply chain documentation systems. ECHA oversight of REACH compliance for cathode active materials now extends to recycled content verification protocols that reshape supplier qualification criteria. OEM platform teams in Turin and Milan are responding by pre-qualifying only those cell suppliers with operational European recycling partnerships.
Fleet operators are consolidating electrified logistics procurement through multi-year vehicle-as-a-service contracts that bundle battery maintenance and residual value guarantees. Traditional equipment finance channels serving small commercial fleets are losing share to OEM-captive leasing subsidiaries that internalize battery lifecycle risk. This concentration is most visible in Lombardy's dense urban delivery corridors where municipal low-emission zones accelerate fleet turnover decisions.
Italy Hybrid Electric Vehicle Battery Market Segmentation
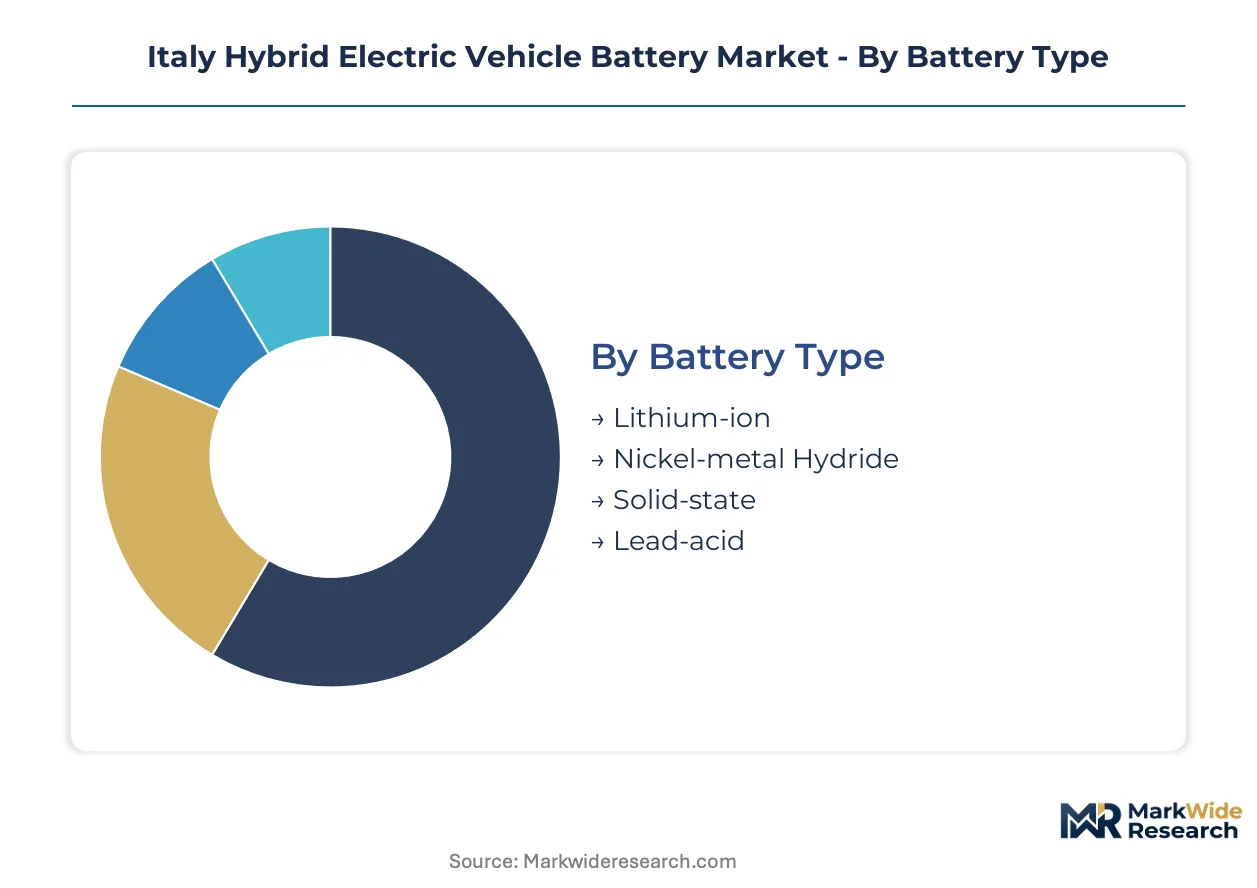
Segmentation in Italy's hybrid electric vehicle battery market reveals how after-sales service intensity varies dramatically across battery chemistries and customer types. Pack architecture decisions cascade through warranty obligations, thermal management maintenance, and end-of-life recovery protocols that reshape profit pools.
Battery Type:
After-sales service intensity peaks with solid-state and lithium-ion systems, where thermal runaway monitoring and electrolyte degradation tracking demand specialized diagnostic infrastructure.
- Lithium-ion:Dominant chemistry for mild-to-full hybrid architectures operating at 200-400V, combining nickel-manganese-cobalt or lithium-iron-phosphate cathodes with graphite anodes. Lombardy's automotive corridor near Milan concentrates demand from passenger car OEMs seeking energy density above 150 Wh/kg for regenerative braking buffers.
- Nickel-metal Hydride:Mature chemistry retaining cost advantages in commercial vehicle thermal environments where operating temperatures exceed 45°C. Turin-based bus manufacturers specify NiMH for route-duty cycles prioritizing calendar life over gravimetric efficiency.
- Solid-state:Emerging sulfide and oxide ceramic electrolyte designs undergoing qualification at Piedmont pilot facilities for 2028 platform introductions.
- Lead-acid:Legacy 12V auxiliary systems persisting in entry hybrid architectures for engine restart functions.
Lithium-ion holds the largest share; momentum sits with solid-state as CE marking carbon disclosure rules favor next-generation chemistries with simplified supply chains.
Application:
Volume concentration follows fleet procurement patterns, with commercial vehicle operators consolidating electrified logistics contracts that bundle battery lifecycle management.
- Passenger Cars:Premium and mass-market OEM platforms in Turin and Milan standardize 48V mild-hybrid systems, creating dense demand for prismatic pouch cells. Individual consumer purchasing decisions increasingly weight residual value guarantees against total cost of ownership.
- Commercial Vehicles:Urban delivery fleets in Lombardy's low-emission zones drive procurement of full-hybrid vans and light trucks. Vehicle-as-a-service contracts internalize battery degradation risk, compressing payback period calculations for fleet managers.
- Two-wheelers:Scooter electrification accelerates in dense Italian urban centers where parking constraints favor compact battery formats.
- Buses:Municipal transit authorities specify hybrid architectures for interurban routes where charging infrastructure gaps persist.
Passenger cars dominate installed capacity; commercial vehicles are climbing the fastest as fleet operators consolidate procurement through OEM-captive leasing.
End User:
Margin structure diverges sharply between OEM integration at vehicle design stage and aftermarket replacement cycles.
- OEMs:Capture densest margin pools through platform-level battery system integration, with Italian manufacturers in Piedmont pre-qualifying cell suppliers based on EU Battery Regulation recycled content verification.
- Fleet Operators:Negotiate multi-year service contracts bundling maintenance, residual value guarantees, and end-of-life recovery, shifting financial risk to battery manufacturers.
- Individual Consumers:Depend on authorized service networks for warranty-compliant pack replacements, with limited price transparency.
- Aftermarket Players:Face compressed margins under CE marking mandates requiring carbon footprint documentation and REACH compliance for cathode material sourcing.
OEMs retain the dominant share; fleet operators are gaining share fastest as electrified logistics procurement consolidates.
Charging Method:
Charging infrastructure availability shapes battery sizing decisions and duty cycle optimization across Italian urban and interurban corridors.
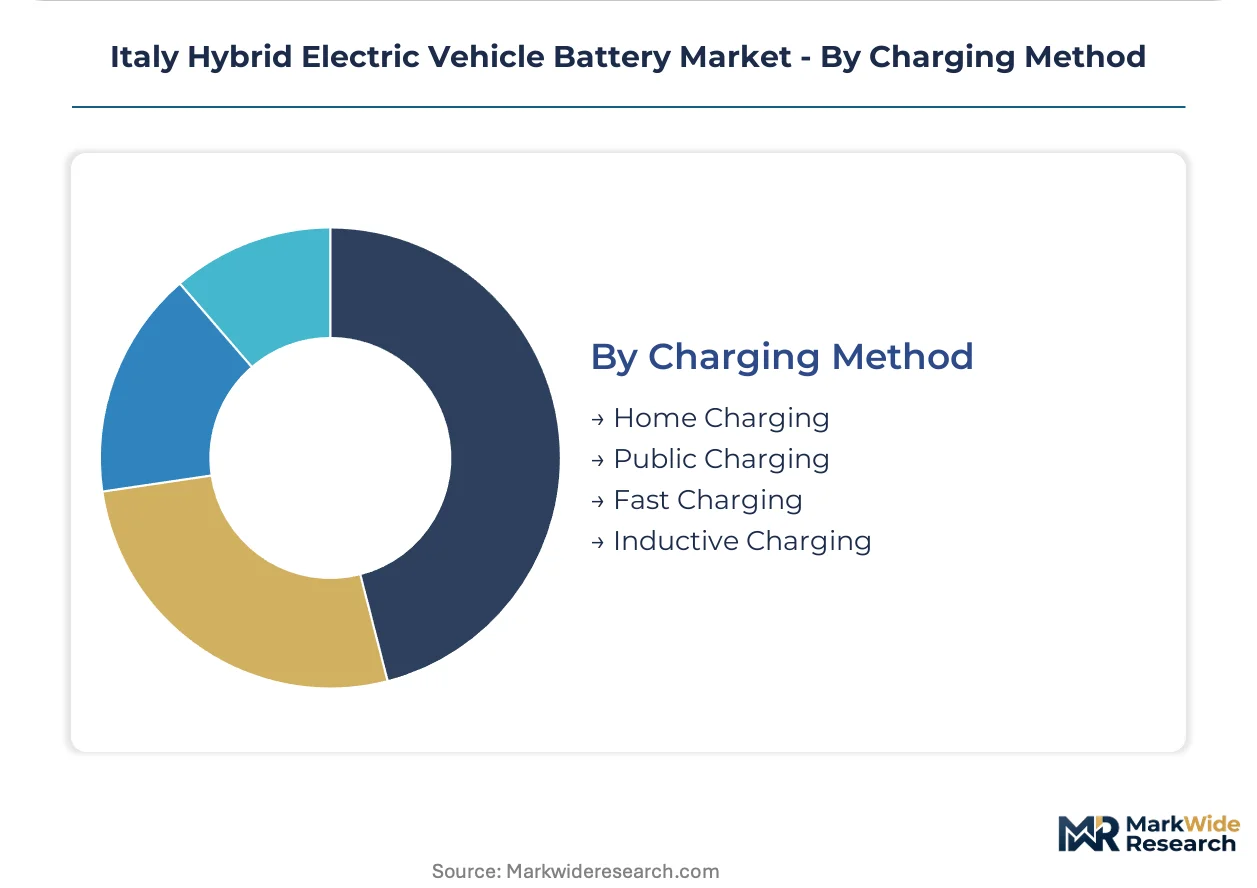
- Home Charging:Overnight AC charging at 3-7 kW dominates plug-in hybrid residential use patterns, with Lombardy utility Enel X deploying smart grid integration.
- Public Charging:Municipal and highway corridor networks expanding under EU Green Deal alignment, though coverage gaps persist in southern regions.
- Fast Charging:DC infrastructure at 50-150 kW enables opportunity charging for commercial fleet duty cycles, though hybrid architectures rarely require this capability.
- Inductive Charging:Pilot deployments for bus depot applications, with Turin testing dynamic charging segments on select routes.
Home charging commands the largest share; public charging infrastructure sees steepest expansion trajectory as municipal low-emission zones proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell manufacturing capacity concentrates in northern industrial corridors where automotive OEMs cluster. Regional differentiation follows electrification policy intensity and supplier ecosystem maturity rather than pure market size.
Germany
Volkswagen Group and BMW procurement decisions drive continental demand for prismatic pouch formats. The KBA enforces type approval standards that accelerate homologation timelines for battery systems entering German platforms. Stuttgart and Munich anchor supplier development programs linking cell producers with Tier-1 pack integrators.
France
Renault and Stellantis platform strategies prioritize 48V mild-hybrid architectures for mass-market segments. ANSM oversight of industrial chemical safety extends to cathode material processing facilities near Nantes. The Automotive Cells Company gigafactory in Douai reshapes procurement geography for French OEM battery sourcing.
Spain
SEAT and Renault Spanish operations expand electrified powertrain assembly for export markets. The Ministry of Industry administers PERTE VEC strategic project funding that channels state aid toward battery value chain localization. Martorell and Valladolid automotive corridors attract pack assembly investments from multinational Tier-1 suppliers.
Poland
LG Energy Solution Wrocław operations represent the largest European cell production footprint outside Asia. Polish Special Economic Zones offer tax incentives that compress capital recovery timelines for battery manufacturing investments. Lower Silesia's industrial base supplies electrode coating equipment and thermal management components to regional pack integrators.
Sweden
Northvolt Skellefteå gigafactory targets premium European OEM contracts with fossil-free production claims. The Swedish Energy Agency funds solid-state electrolyte research programs at Uppsala University. Gothenburg's automotive engineering cluster concentrates Volvo Cars platform development teams specifying cell chemistry requirements.
Italy Hybrid Electric Vehicle Battery Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in cell chemistry and power electronics. The vendor structure consolidates around Asian cell giants with European pack assembly subsidiaries, while domestic challengers pursue gigafactory scale. Three archetypes dominate: cylindrical cell specialists leveraging legacy consumer electronics expertise, prismatic pouch incumbents serving high-volume OEM platforms, and emerging solid-state developers targeting next-generation thermal performance. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with state aid qualification determining regional site selection.
Among established energy storage conglomerates, EnerSys and Exide Industries Ltd occupy positions in industrial battery segments adjacent to automotive applications. Panasonic Holdings Corporation anchors the cylindrical cell archetype with European supply hub operations. LG Energy Solution exemplifies prismatic pouch dominance through high-volume manufacturing scale. Italvolt represents domestic challenger ambitions with planned Piedmont production capacity targeting CE marking compliance.
| Leading Market Players |
|---|
| EnerSys |
| Automotive Cells Company |
| Panasonic Holdings Corporation |
| Italvolt |
| Saft (TotalEnergies) |
| BYD Company |
| Exide Industries Ltd |
| Gruppo Seri |
| LG Energy Solution |
| Others |
Pricing and Supply Chain Analysis
Asian cell manufacturing concentration in South Korea and Japan feeds margin compression downstream, forcing Italian pack integrators to absorb input volatility or surrender OEM platform bids to vertically integrated European competitors. CE marking carbon disclosure mandates add compliance premiums that stratify pricing across certified and non-certified supplier tiers.
Pricing Analysis
EU Battery Regulation dictates the pricing tier structure through carbon footprint disclosure thresholds and recycled content verification protocols. Three-tier pricing structure across premium, standard, and economy levels separates OEM-qualified cells with full traceability from uncertified imports and refurbished aftermarket packs. Cost compression in standard-tier cylindrical cells is intensifying because LG Energy Solution and Panasonic scale European hub operations. Fleet operators exhibit the highest price sensitivity due to vehicle-as-a-service contract economics, while OEM platform teams prioritize certification compliance over unit cost.
Supply Chain Analysis
Extended payment terms from Lombardy OEMs to Tier-1 pack integrators cascade upstream, compressing working capital for cathode active material importers. China, South Korea, and Japan anchor cell production, while Chile and Australia feed lithium concentrate to European refiners. The Italian value chain draws from German electrode coating equipment and Polish thermal management component suppliers. Single-source vulnerability concentrates in prismatic pouch cell supply where LG Energy Solution dominates high-volume contracts. Distribution runs through Milan-Turin automotive corridors with just-in-time delivery to OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's hybrid battery market represents high-growth disruption as solid-state electrolyte commercialization compresses the timeline for liquid chemistry dominance. EU Battery Regulation delegated acts on recycled content thresholds create first-mover advantages for suppliers with closed-loop metallurgical partnerships.
For Market Incumbents: Entrench platform relationships by pre-qualifying for 2028 solid-state introductions at Piedmont pilot facilities. Secure backward integration into cathode active material refining through partnerships with European metallurgical processors to deflect REACH compliance cost pressure from ECHA documentation bottlenecks.
For New Entrants and Emerging Players: Build out aftermarket diagnostic and thermal management service capabilities for Lombardy commercial fleets operating under vehicle-as-a-service contracts. Target bus manufacturers in Turin specifying nickel-metal hydride for high-temperature route cycles, where Asian incumbents have withdrawn from niche volume segments.
For Investors and Strategic Acquirers: Capital is best deployed toward cell-to-pack architecture specialists eliminating module housings to compete with imported Asian pack solutions. Long-term viability hinges on CE marking compliance infrastructure and closed-loop recycling partnerships. Watch for delegated acts on performance standards as the inflection signal accelerating supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Architecture Convergence | Eliminates module housings, reducing pack mass and enabling Italian integrators to match Asian pack costs. |
| Recycled Content Partnership | Secures lithium, nickel, and cobalt supply from Piedmont metallurgical processors ahead of EU Battery Regulation mandates. |
| Solid-State Pilot Qualification | Positions suppliers for 2028 OEM platform introductions as Piedmont facilities retrofit for sulfide electrolyte production. |
| Fleet Service Contract Bundling | Captures battery lifecycle value through maintenance and residual value guarantees under vehicle-as-a-service structures. |
| REACH Compliance Automation | Reduces ECHA documentation bottlenecks for cathode active materials entering European supply chains. |
Research Methodology
A standing panel of OEM platform engineers, Tier-1 pack integrator procurement leads, fleet operator logistics directors, and ECHA regulatory affairs specialists provided ongoing calibration across primary fieldwork. Secondary validation drew from EU Battery Regulation delegated acts, vehicle production databases, IHS Markit registration data, and SEC filings of listed cell manufacturers. Bottom-up cell demand estimates triangulated against top-down OEM platform electrification targets.
Scenario-bracketing framed volume and value outputs across the projection horizon, modeling propulsion architecture, battery chemistry, vehicle class, and regional production cluster dimensions. CAGRs derived from segment-level build-up analysis incorporating fleet procurement cycle timing, state aid disbursement trajectories under Italy's National Recovery and Resilience Plan, and solid-state commercialization readiness curves.
Practitioners should monitor regulatory timeline slippage for delegated acts and solid-state yield improvements at Piedmont pilot facilities for early signals. Forecasts reflect assumptions on OEM platform electrification commitments and REACH compliance process efficiency. Macroeconomic contraction, regulatory deviation, or solid-state technology delays would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Skateboard Chassis Market
Electric Vehicles
EV PTC Heaters Market
Electric Vehicles
US Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Asia Pacific Electric Three-Wheelers Market
Electric Vehicles
United States Electric Pick-Up Trucks Market
Electric Vehicles
Global Automotive Inductive Wireless Charging Systems Market
Electric Vehicles
Commercial Electric Vehicle Resistive Braking System Market
Electric Vehicles
Electric Vehicle on Board Charger Market
Electric Vehicles
Europe Solar E-Bike Market
Electric Vehicles
Electric Vehicle Testing, Inspection, and Certification Market
Electric Vehicles
Self Balancing Electric Scooter Market
Electric Vehicles
Latin America E-Bike Market
Electric Vehicles
Electric Bus Market
Electric Vehicles
Water Proof E-Scooter Market
Electric Vehicles
South America Automotive High Performance Electric Vehicles Market
Electric Vehicles
Electric Sports Utility Vehicle (E-SUV) Market