
 Foldable Electric Car Market | 2026-2036
Foldable Electric Car Market Size, Share, and Industry Trends Forecast 2026-2036
Foldable Electric Car Market Insights
Carbon fiber reinforced polymer is restructuring chassis economics for foldable electric vehicles by displacing conventional steel stampings in hinge mechanisms and collapsible frame nodes. BMW Group leverages its Munich-based composites research to sustain premium positioning in luxury variants. Hyundai Motor Group anchors volume manufacturing through integrated battery-pack assembly in South Korea. Tesla competes on software-defined folding logic and over-the-air kinematic updates.
A foldable electric car integrates collapsible body architecture with zero-emission powertrain systems, typically achieving sub-three-meter folded length through multi-link hinge geometries and telescoping wheelbases designed for dense urban parking. The primary commercial purpose centers on resolving last-mile mobility friction where conventional vehicles face registration restrictions or space penalties. Compact models dominate unit economics due to standardized battery skateboards and reduced material count per unit. Battery Electric technology leads installed base but Hybrid Electric configurations capture fleet buyers seeking range contingency without charging infrastructure dependency. Urban commuters represent the deepest addressable pool, though businesses are emerging as the fastest-growing end user category through last-mile delivery contracts.
EU F-Gas Regulation and REACH compliance shape thermal management system design for European-bound models, while NHTSA crashworthiness protocols govern folding-state structural integrity for US market access. Japan's METI subsidizes compact EV development through dedicated kei-car electrification channels, directly influencing product dimension targets. South Korea's KBA enforces battery safety certification that extends to foldable pack configurations. Stakeholders must monitor regulatory divergence between markets as folding mechanisms trigger novel homologation categories not addressed by existing passenger vehicle frameworks.
Market Dynamics
Parking density mandates in megacities are compressing vehicle footprint requirements below three meters, forcing chassis architectures toward multi-link hinge geometries that collapse telescoping wheelbases. This spatial constraint is restructuring supplier relationships around carbon fiber reinforced polymer stamping capabilities and software-defined kinematic controls.
Growth Catalysts
- EU F-Gas Regulation:Thermal management system redesigns for European-bound models are accelerating adoption of compact refrigerant architectures that integrate with foldable battery pack configurations.
- Last-mile delivery fleets:Urban logistics operators are contracting for sub-kei-car footprint vehicles that bypass congestion charging zones and access restricted central business districts.
- Carbon fiber hinge mechanisms:Reduced mass in collapsible frame nodes extends single-charge range without proportional battery cost increases, improving total cost of ownership for commuter segments.
Market Restraints
- Carbon fiber supply concentration:Precursor manufacturing for aerospace-grade CFRP concentrates among Japanese and South Korean suppliers, exposing chassis producers to input volatility and allocation constraints.
- NHTSA folding-state crashworthiness:Absence of established test protocols for collapsed-geometry structural integrity extends homologation timelines and increases certification uncertainty for US market entry.
- Micro-mobility substitution:Electric bicycles and standing scooters capture short-trip demand at sub-thousand-dollar price points, compressing the addressable window for motorized foldable alternatives.
Strategic Opportunities
- India's PLI scheme for automotive:Domestic manufacturing incentives for advanced chemistry cell batteries create localized assembly pathways for foldable EV platforms targeting tier-one city congestion.
- Over-the-air kinematic updates:Software-defined folding logic enables post-sale feature activation and usage-based unlocking, transforming hardware into recurring revenue vehicles.
- Corporate campus mobility:Business park operators are piloting shared foldable fleets for inter-building transit, opening B2B procurement channels distinct from individual consumer finance.
Industry Challenges
- Multi-physics simulation talent:Concurrent optimization of folding kinematics, crash dynamics, and thermal management requires scarce expertise in integrated CAE workflows spanning mechanical and battery engineering.
- REACH compliance documentation:Substance of very high concern tracking through collapsible wiring harnesses and lubricated hinge assemblies extends supplier audit cycles and increases traceability system costs.
- Patent thickets around origami-inspired chassis:Overlapping intellectual property claims from robotics and deployable space structures complicate freedom-to-operate analysis for novel folding geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foldable Electric Car Market |
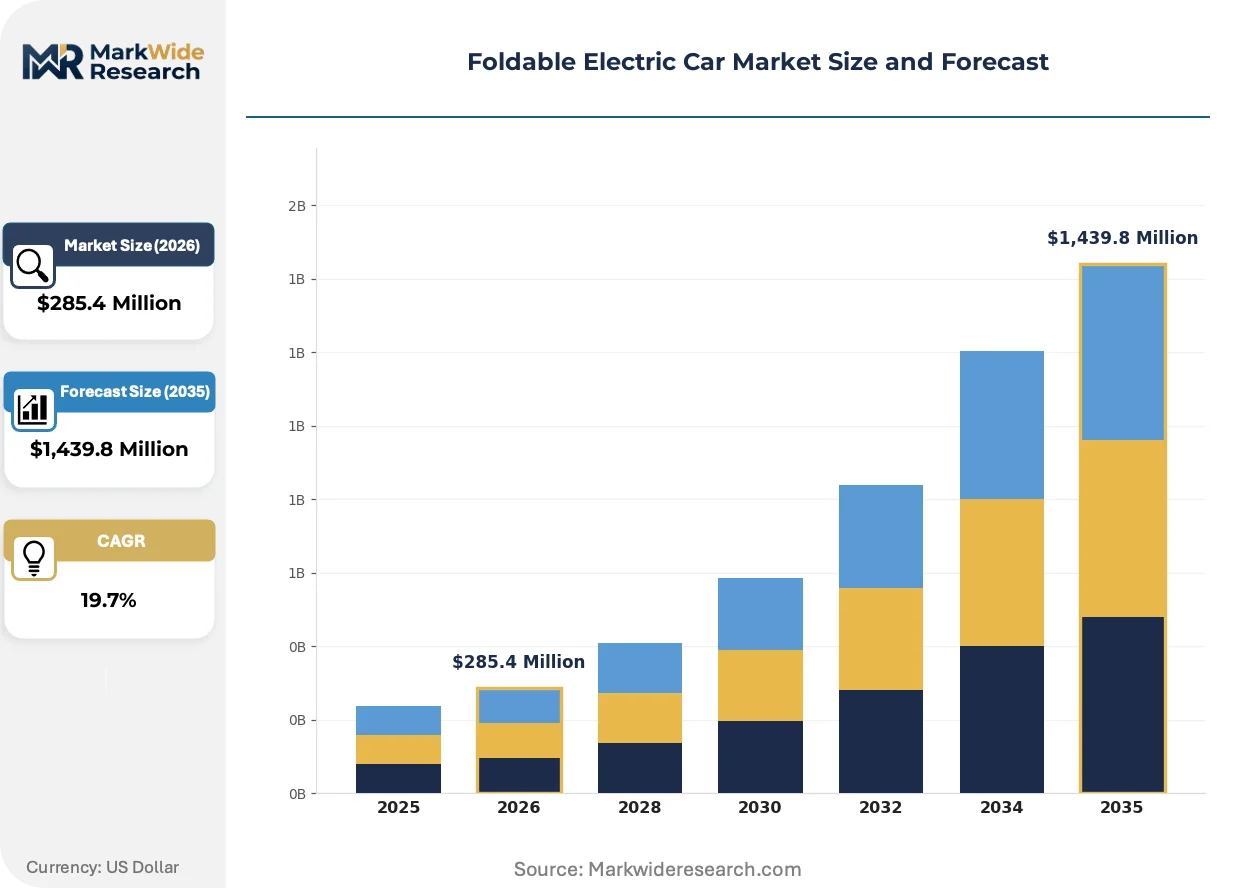
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,439.8 Million |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Models, Luxury Variants, Utility Vehicles, Concept Cars Technology: Battery Electric, Hybrid Electric, Fuel Cell, Autonomous Driving End User: Urban Commuters, Families, Businesses, Tourists Distribution Channel: Online Sales, Dealerships, Showrooms, Fleet Sales |
| Companies Covered | Volkswagen Group, Mercedes-Benz, Tesla, Polestar, Rivian, Hyundai Motor Group, BMW Group, General Motors, Kia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foldable Electric Car Market Trends and Innovations
Actuator miniaturization and edge-computing integration are collapsing the mechanical complexity of folding sequences, enabling single-button deployment that previously required manual multi-stage manipulation. These advances are repositioning foldable EVs from engineering curiosities to daily-driver viability.
Shape-memory alloy actuators are automating hinge synchronization across multi-link collapsible frames, eliminating mechanical linkages that previously added mass and failure points. Fleet operators in dense European urban cores are specifying these systems for delivery vehicles requiring sub-60-second deployment cycles. The technology is automating operator training requirements and reducing insurance exposure from improper manual folding sequences.
Japan's METI kei-car electrification subsidies are channeling R&D investment toward sub-3.4-meter platforms with standardized charging interfaces. Domestic manufacturers are prioritizing battery pack geometries that maintain structural integrity through repeated folding cycles. South Korean regulators are observing these developments to inform KBA certification extensions for collapsible pack configurations.
Subscription-based access models are displacing traditional ownership finance for urban commuters with intermittent vehicle needs. Mobility-as-a-service platforms in German metropolitan clusters are integrating foldable EVs into multi-modal bundles with transit and bike-share. This restructuring concentrates utilization risk with fleet aggregators rather than individual buyers, altering residual value forecasting and remarketing strategies.
Foldable Electric Car Market Segmentation
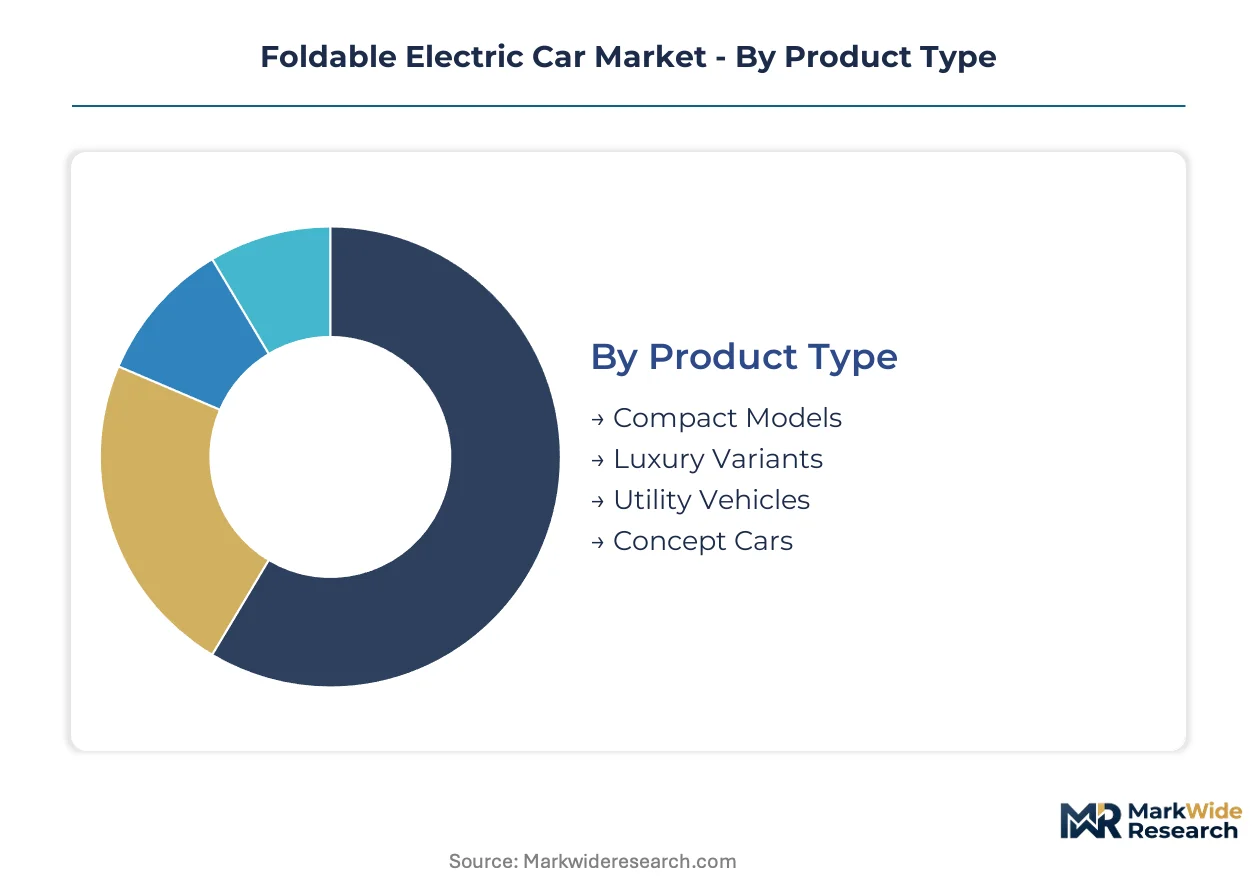
Segmentation in the foldable electric car market reveals divergent engineering priorities across customer archetypes. Product architecture, powertrain selection, and channel strategy must align with distinct usage patterns ranging from daily urban parking constraints to fleet deployment economics.
Product Type:
Standardization dominates at the volume end while customization concentrates in premium tiers, creating a bifurcated supplier landscape.
- Compact Models:Sub-three-meter folded dimensions achieved through telescoping wheelbases and standardized battery skateboards. Urban commuters in Germany and Japan drive procurement as parking density mandates tighten in Munich, Tokyo, and Seoul metropolitan zones.
- Luxury Variants:Carbon fiber reinforced polymer chassis with automated hinge synchronization and bespoke interior configurations. BMW Group's Munich composites research anchors European supply, with buyers prioritizing brand cachet over absolute footprint minimization.
- Utility Vehicles:Modular cargo configurations for last-mile logistics operators.
- Concept Cars:Technology demonstrators testing origami-inspired folding geometries and shape-memory alloy actuators.
Leading the category by volume: Compact Models. Growing fastest: Utility Vehicles.
Technology:
Cost tier stratification separates proven battery architectures from emerging powertrain alternatives still seeking manufacturing scale.
- Battery Electric:Dominant installed base leveraging lithium-ion cell geometries optimized for repeated folding cycles. South Korean manufacturers integrate pack assembly with chassis hinge nodes, reducing wiring harness fatigue through collapsible routing.
- Hybrid Electric:Range-extender configurations capturing fleet buyers in markets with sparse fast-charging infrastructure. European logistics operators specify these for cross-border routes where charging contingency outweighs pure-electric operating cost advantages.
- Fuel Cell:Proton exchange membrane stacks for extended-range commercial deployment.
- Autonomous Driving:Lidar-integrated folding logic enabling self-parking in compressed urban structures.
Highest production volumes: Battery Electric. Steepest expansion trajectory: Autonomous Driving.
End User:
Application-driven segmentation separates intermittent personal mobility from intensive commercial utilization patterns.
- Urban Commuters:Deepest addressable pool with intermittent vehicle needs favoring subscription access over ownership. German mobility-as-a-service platforms bundle foldable EVs with transit and bike-share, concentrating utilization risk with fleet aggregators.
- Businesses:Fastest-growing category through last-mile delivery contracts and corporate campus mobility pilots. Last-mile logistics operators in dense European urban cores specify sub-60-second deployment cycles for delivery vehicles accessing congestion-charged central business districts.
- Families:Multi-passenger configurations with enhanced crashworthiness for folded-state occupant protection.
- Tourists:Rental fleet integration at micro-mobility hubs in destination cities.
Widest penetration: Urban Commuters. Fastest volume gains: Businesses.
Distribution Channel:
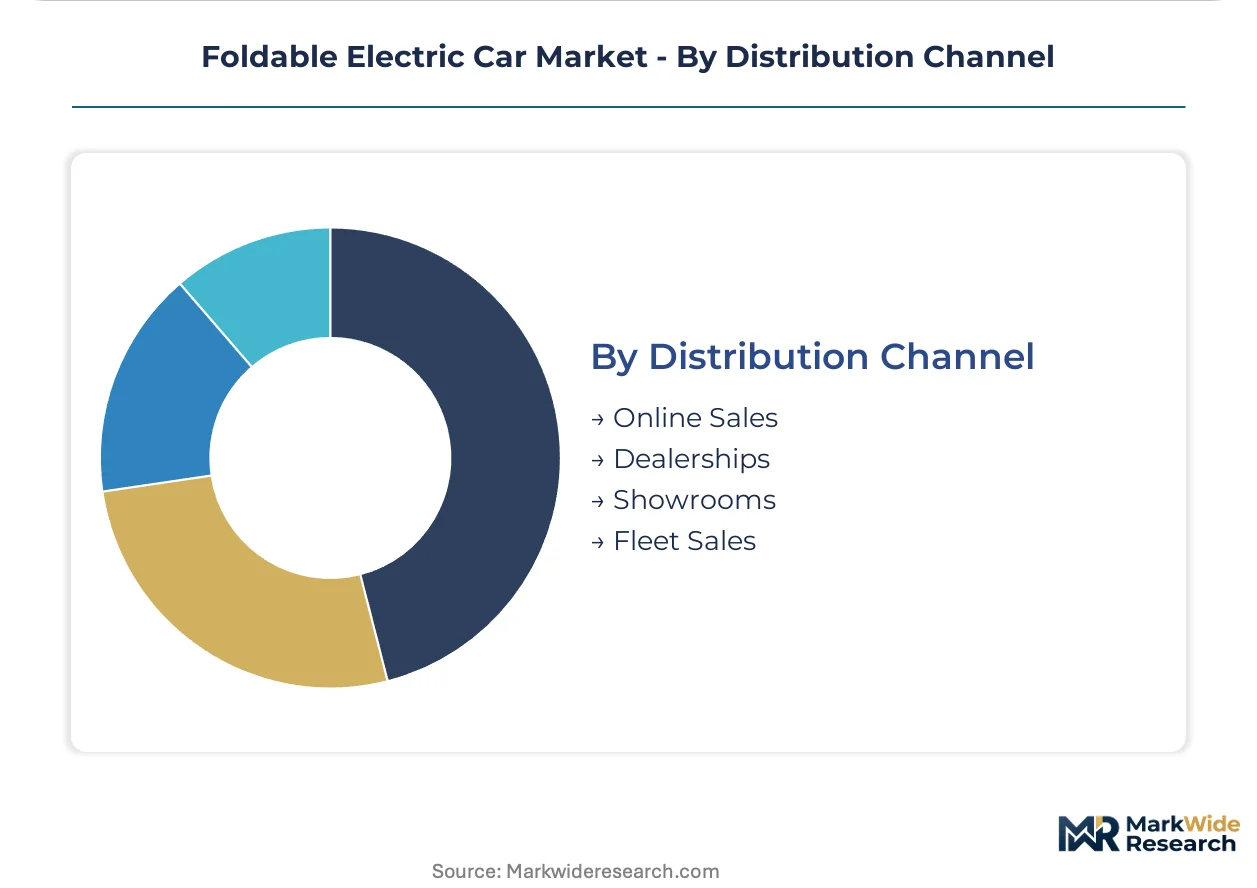
Customer type determines channel economics, with direct digital acquisition disrupting traditional automotive retail infrastructure.
- Online Sales:Software-defined vehicle architecture enables over-the-air kinematic updates and usage-based feature unlocking. Tesla competes through digital-first configuration with remote folding diagnostics, bypassing physical showroom requirements.
- Fleet Sales:B2B procurement channels for corporate campus operators and urban logistics aggregators. Business park pilots in German metropolitan clusters are restructuring residual value forecasting through shared utilization models.
- Dealerships:Legacy automotive retail networks requiring physical demonstration of folding mechanics.
- Showrooms:Experience centers in premium urban locations emphasizing brand positioning over transaction volume.
Dominant transaction volume: Online Sales. Fastest channel expansion: Fleet Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for foldable electric vehicles concentrates in metropolitan clusters where parking scarcity intersects with stringent emissions enforcement. Germany, Japan, South Korea, the United States, and China anchor procurement volumes through distinct regulatory and industrial pathways.
Germany
Munich and Stuttgart metropolitan zones drive commuter adoption as municipal parking density mandates compress below three meters. The KBA enforces battery safety certification that extends to collapsible pack configurations, creating homologation precedents for European-bound models. Bavaria's automotive R&D corridor anchors BMW Group's carbon fiber composites research for luxury variant chassis.
Japan
Tokyo's kei-car parking exemptions channel demand toward sub-3.4-meter platforms with standardized charging interfaces. METI subsidizes compact EV development through dedicated electrification channels that directly influence product dimension targets. Nagoya-based suppliers concentrate on hinge mechanism durability testing for repeated folding cycles.
South Korea
Seoul's congestion charging zones and micro-mobility infrastructure investments overlap to create fleet procurement pull. KBA-equivalent battery safety protocols govern foldable pack configurations, with regulators observing Japanese developments for certification extensions. Hyundai Motor Group anchors volume manufacturing through integrated battery-pack assembly in domestic facilities.
United States
San Francisco and New York City parking scarcity creates addressable commuter pools despite higher baseline vehicle footprints. NHTSA crashworthiness protocols govern folding-state structural integrity, extending homologation timelines for collapsed-geometry certification. California's ZEV program indirectly incentivizes footprint-reduction innovations through space-constrained urban compliance pathways.
China
Shenzhen and Shanghai municipal parking policies compress vehicle footprint requirements in central business districts. MIIT standards for new energy vehicles create regulatory scaffolding for compact EV platforms, though folding mechanisms trigger novel homologation categories not fully addressed by existing frameworks. Yangtze River Delta manufacturing clusters prototype origami-inspired chassis geometries for export markets.
Foldable Electric Car Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with automotive OEMs dominating premium tiers and electronics fabricators capturing component supply. The vendor base concentrates around three strategic archetypes: legacy automakers repurposing existing EV platforms, composites specialists controlling carbon fiber hinge production, and software-first entrants competing on kinematic control systems. Consolidation pressure operates through M&A activity targeting folding mechanism IP, while capacity expansion concentrates in South Korean and German industrial clusters.
Within the legacy automaker tier, Volkswagen Group, Hyundai Motor Group, and BMW Group occupy positions that exemplify divergent strategic postures. Volkswagen's scale-oriented structure represents volume manufacturing archetypes, while Hyundai's integrated battery-pack assembly anchors supply chain control. BMW's Munich-based research footprint exemplifies premium-tier positioning through materials science differentiation rather than absolute footprint minimization.
| Leading Market Players |
|---|
| Volkswagen Group |
| Mercedes-Benz |
| Tesla |
| Polestar |
| Rivian |
| Hyundai Motor Group |
| BMW Group |
| General Motors |
| Kia |
| Others |
Pricing and Supply Chain Analysis
Carbon fiber grade bifurcation between aerospace-spec precursors and industrial-grade alternatives manifests in both component pricing and supplier geography, with Japanese and South Korean feedstock commanding premium allocations while European chassis assemblers absorb tariff-layered logistics costs for collapsed-geometry vehicle platforms.
Pricing Analysis
Volume-manufactured compact models trade on thin margins anchored to standardized battery skateboards, while luxury variants capture brand premiums through Munich-sourced composites and automated hinge synchronization. Price differentiation hinges on certification tier—KBA battery safety validation versus uncertified aftermarket configurations—and carbon fiber content grade. Cost compression in the compact tier intensifies as South Korean producers scale integrated pack-assembly lines. Fleet buyers exhibit lowest price sensitivity due to total-cost-of-ownership optimization, while individual urban commuters demand subscription-access models below ownership thresholds.
Supply Chain Analysis
Freight costs for carbon fiber reinforced polymer precursors concentrate exposure on trans-Pacific lanes feeding German and South Korean stamping facilities. Aerospace-grade CFRP feedstock draws from Japanese and South Korean chemical conglomerates, with lithium-ion cell geometries and shape-memory alloy actuators as critical downstream inputs. Single-source vulnerability pervades the precursor tier, where Toray and Hyosung allocations determine chassis producer scheduling. Distribution runs through Tier 1 automotive supplier networks rather than direct OEM relationships, with hinge mechanism subassemblies shipped knocked-down for final integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU F-Gas Regulation and REACH documentation requirements erect regulatory moats favoring incumbent OEMs with established homologation teams over capital-constrained entrants.
For Market Incumbents: Deepen backward integration into carbon fiber precursor production to escape Japanese supplier allocation constraints, while expanding KBA-equivalent certification capabilities ahead of anticipated South Korean regulatory extensions. Micro-mobility substitution from electric bicycles and standing scooters threatens the commuter segment, requiring defensive subscription-model deployment through German mobility-as-a-service platforms. For New Entrants and Emerging Players: Fleet aggregators represent the most penetrable channel partner type for bypassing consumer finance infrastructure and accessing concentrated procurement volumes. White-space targets include India's PLI scheme for automotive battery assembly and corporate campus mobility pilots in German metropolitan clusters. A software-defined kinematic control go-to-market angle enables over-the-air feature differentiation without manufacturing scale. For Investors and Strategic Acquirers: Re-rating potential sits with composites specialists holding origami-inspired chassis IP given shape-memory alloy actuator adoption acceleration in European delivery fleets. Long-term viability favors targets with concurrent mechanical-and-battery engineering CAE workflows spanning folding kinematics and thermal management. The signal to watch is NHTSA folding-state crashworthiness protocol finalization, which would unlock US market access and trigger valuation step-functions for certified platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Fiber Precursor Backward Integration | Captive supply from Japanese chemical producers reduces allocation volatility for European chassis assemblers. |
| KBA Battery Safety Certification Extension | First-mover validation for collapsible pack geometries creates homologation precedents across EU member states. |
| Over-the-Air Kinematic Update Platform | Software-defined folding logic transforms hardware sales into recurring revenue through usage-based feature unlocking. |
| Last-Mile Fleet Subscription Partnership | B2B procurement channels with German logistics aggregators concentrate utilization risk away from individual buyers. |
| Shape-Memory Alloy Actuator Manufacturing Scale-Up | Automated hinge synchronization reduces insurance exposure and operator training costs for dense European urban cores. |
Research Methodology
Multi-period observation of parking density mandates, METI kei-car electrification subsidy disbursements, and CFRP precursor pricing anchored the trend analysis, supplemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, automotive regulatory affairs specialists, and fleet operations managers at German last-mile logistics providers. Secondary validation drew from KBA type-approval databases, EU F-Gas Regulation implementation notices, Japan's METI compact EV development filings, and South Korean industrial cluster investment disclosures. Bottom-up unit shipment estimates triangulated against top-down addressable parking space economics across Munich, Tokyo, and Seoul metropolitan zones.
Segment-weighting applied product type, powertrain architecture, end-user category, and distribution channel dimensions across the analysis window, with CAGRs derived from regression against macro-urbanization indicators and battery energy density improvement curves. Vehicle class stratification, propulsion system content per unit, and regional production cluster capacity utilization served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including NHTSA folding-state crashworthiness protocol finalization timing, aerospace-sector carbon fiber demand spikes disrupting automotive allocations, and unanticipated micro-mobility technology substitutions compressing motorized foldable addressable markets. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
BEV Electric Drive Unit Market
Electric Vehicles
Netherlands Solar E-Bike Market
Electric Vehicles
France Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
North America E-Bike Market
Electric Vehicles
Electric Vehicle (EV) Coating Market
Electric Vehicles
Peer-To-Peer Electric Vehicle Charging Market
Electric Vehicles
Silicone in Electric Vehicles Market
Electric Vehicles
ASEAN EV Battery Pack Market
Electric Vehicles
Electric Three Wheeler Market
Electric Vehicles
Recreational Vehicle (RV) Batteries Market
Electric Vehicles
Asia-Pacific Train Battery Market
Electric Vehicles
UK Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
High Voltage PTC Heaters for Electric Vehicles Market
Electric Vehicles
Electric Vehicle Liquid Cold Plates Market
Electric Vehicles
Electric Vehicle Sound Generators Market
Electric Vehicles
North America Electric Truck Market