
 North America Electric Vehicle Battery Market | 2026-2036
North America Electric Vehicle Battery Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electric Vehicle Battery Market Intelligence
The shift toward high-nickel cathode chemistries for improved energy density is reorganizing the competitive landscape in North America. Panasonic Energy leverages its long-standing partnership with Tesla to scale production of advanced cylindrical cells in the US. Ultium Cells, a joint venture between GM and LG Energy Solution, anchors a key domestic supply chain with its large-format pouch cells. SK On specializes in high-performance pouch cells for automakers like Ford.
An electric vehicle battery is a rechargeable energy storage system, typically a lithium-ion pack, designed to power a vehicle's electric motor. These systems are engineered for high energy density, measured in Wh/kg, and long cycle life to meet the demands of automotive use in North America. Li-ion technology dominates the product landscape, with solid-state batteries representing a long-term developmental focus. Passenger vehicles constitute the largest application segment, while commercial vehicles represent the fastest-growing opportunity.
In the United States, the Inflation Reduction Act (IRA) directly influences battery sourcing and manufacturing through substantial tax incentives. Concurrently, standards from the EPA and NHTSA on vehicle emissions and fuel economy are compelling automakers to accelerate their transition to electric vehicles. Stakeholder success now depends on securing a compliant and cost-effective supply of critical battery materials and components within the region.
Market Dynamics
The North American EV battery market is being fundamentally reshaped by the US Inflation Reduction Act. This policy's domestic content requirements are forcing an unprecedented onshoring of manufacturing and raw material processing, concentrating investment geographically and altering supply chain strategies.
Growth Catalysts
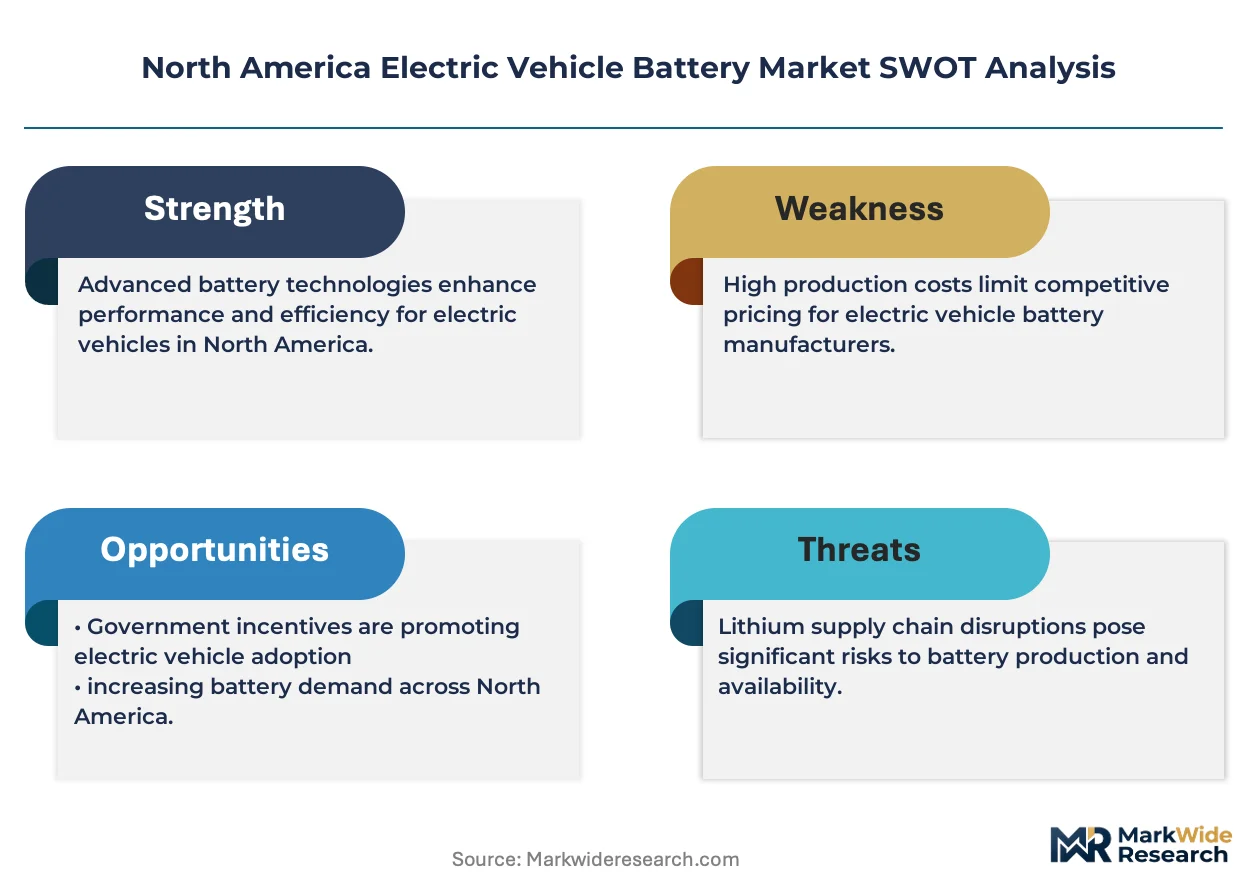
- Federal Policy Incentives:The US Inflation Reduction Act provides substantial tax credits for vehicles with batteries containing domestically sourced minerals and components, directly stimulating regional production.
- Commercial Fleet Electrification:Demand from logistics, delivery, and municipal fleets for electric trucks and vans is accelerating, creating a high-volume market for durable, long-cycle-life battery packs.
- Advanced Cathode Chemistries:The transition to high-nickel cathode materials improves vehicle range and performance, pulling demand for next-generation cell manufacturing capabilities within North America.
Market Restraints
- Critical Mineral Volatility:Price fluctuations and supply instability for key inputs like lithium and cobalt create significant cost uncertainty for battery manufacturers and automakers.
- Processing Bottlenecks:A heavy reliance on mineral processing capacity located outside North America exposes the regional supply chain to geopolitical risks and trade disruptions.
- Infrastructure Gaps:Insufficient public fast-charging infrastructure, particularly for medium and heavy-duty commercial vehicles, limits the operational viability of EVs in certain long-haul applications.
Strategic Opportunities
- Second-Life Applications:A growing stock of end-of-life EV batteries creates a significant opportunity for remanufacturing and deployment in stationary energy storage systems.
- Mexican Manufacturing Integration:Mexico's established automotive manufacturing ecosystem and trade agreements present an opportunity for cost-effective battery pack assembly and component production.
- Canadian EV Mandates:Federal and provincial zero-emission vehicle mandates in Canada create a guaranteed, growing market for compliant electric vehicles and their battery systems.
Industry Challenges
- Specialized Talent Scarcity:A shortage of qualified battery engineers, cell chemists, and manufacturing technicians threatens to slow the ramp-up of new production facilities across the continent.
- Intensive Capital Requirements:The construction of gigafactory-scale battery plants demands billions of dollars in upfront investment, posing a high barrier to entry for new market participants.
- IRA Compliance Complexity:Navigating the evolving and intricate sourcing rules of the Inflation Reduction Act to ensure tax credit eligibility presents a significant administrative and logistical burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electric Vehicle Battery Market |
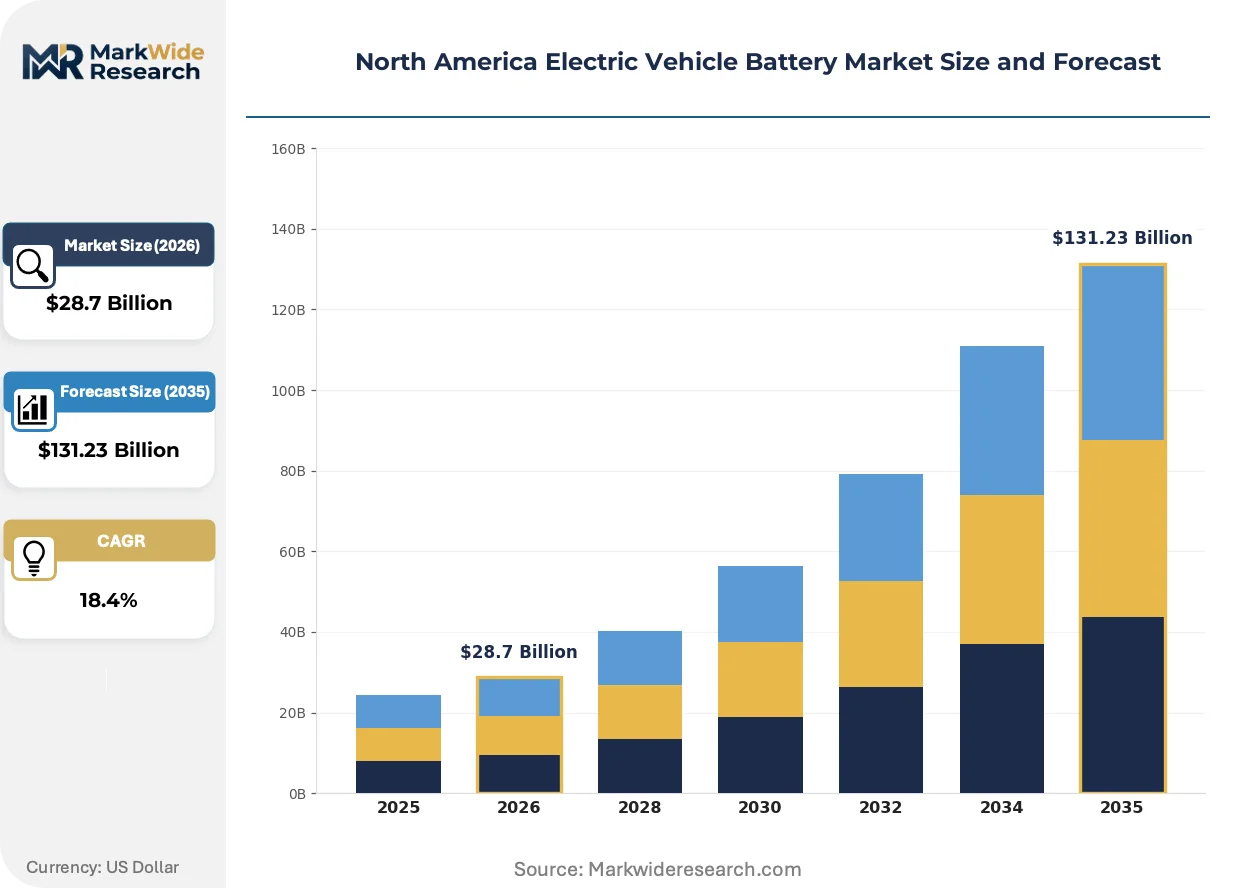
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $131.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Li-ion, NiMH, Lead-Acid, Solid-State End User: OEMs, Fleet Operators, Retail Consumers, Battery Swapping Stations Capacity: Below 30 kWh, 30-60 kWh, 60-100 kWh, Above 100 kWh Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Others |
| Companies Covered | Samsung SDI, AESC Envision, LG Energy Solution, BlueOval SK, Ultium Cells, SK On, Tesla, Umicore, Panasonic Energy, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electric Vehicle Battery Market Strategic Shifts & Innovations
Technological evolution and policy mandates are creating a new competitive reality in the North American EV battery sector. Success now hinges on an organization's ability to integrate advanced cell chemistry with a geopolitically resilient and compliant supply chain.
High-nickel chemistries, including Nickel-Manganese-Cobalt (NMC) and Nickel-Cobalt-Aluminum (NCA), offer superior energy density for extended vehicle range. Automakers are aggressively adopting these formulations for their flagship passenger EVs and electric trucks to meet consumer performance expectations. This shift is supplanting older, lower-energy cathode materials, particularly in the premium and long-range segments of the North American market.
The United States Inflation Reduction Act (IRA) is the most consequential policy influencing the market. It requires a rising percentage of battery components and critical minerals to be sourced from North America or free-trade partners for vehicles to receive consumer tax credits. Consequently, automakers are redirecting billions in capital to establish domestic battery plants, particularly within the US Southeast's emerging 'Battery Belt'.
Automaker procurement models are evolving from transactional cell purchasing to deep strategic partnerships and direct investment. This new paradigm involves creating joint ventures for cell manufacturing to guarantee access to IRA-compliant battery volume, a critical factor for competitive vehicle pricing. This direct-investment approach is most visible in the United States, where securing domestic supply is essential.
North America Electric Vehicle Battery Market Segmentation
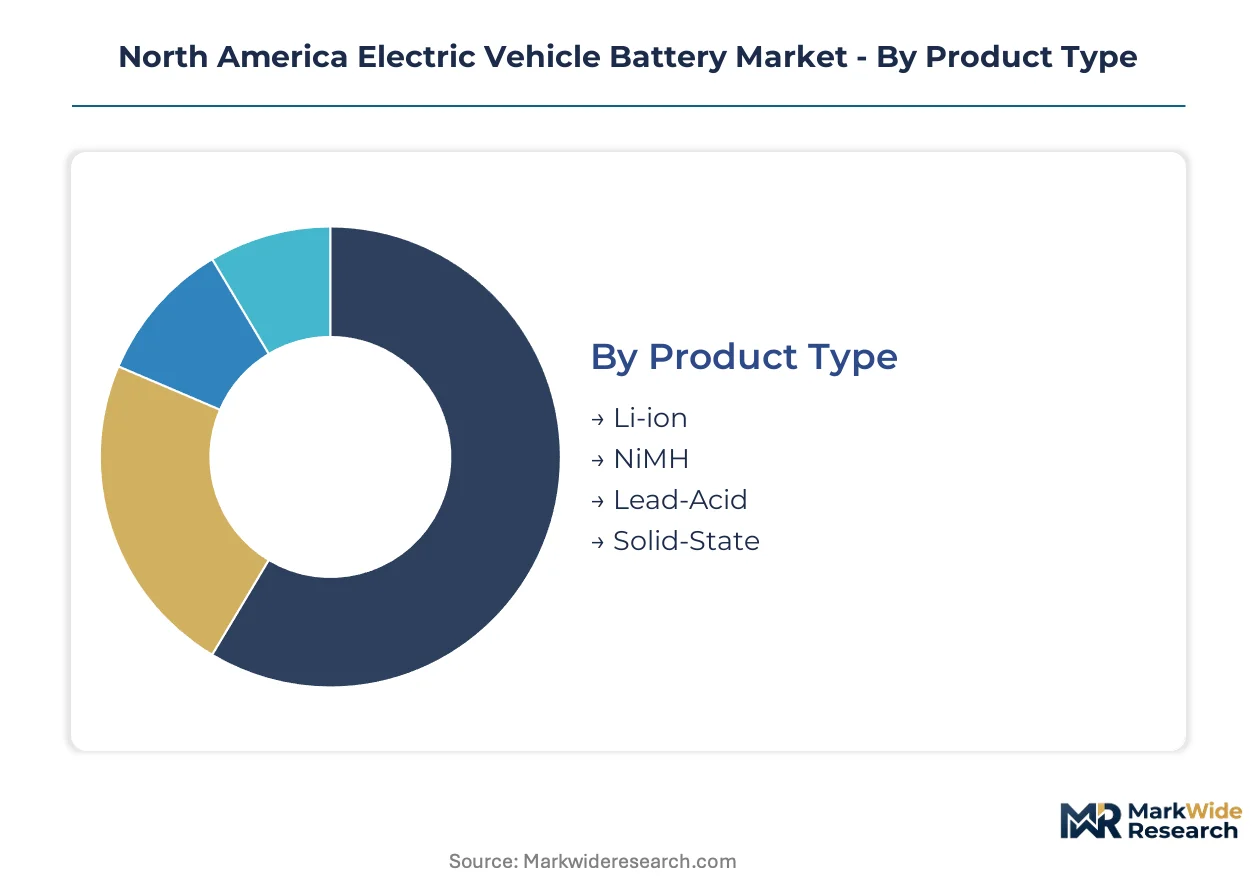
The North America electric vehicle battery market segmentation provides a granular view of diverse product types, end-user categories, capacity ranges, and application areas. Understanding these distinctions is crucial for stakeholders to align product development and investment strategies with specific market demands and regulatory landscapes.
Product Type:
Regulatory frameworks in North America increasingly differentiate battery chemistries based on energy density, safety profiles, and critical material sourcing implications.
- Li-ion:Lithium-ion technology dominates the market, utilizing various cathode materials like NMC, NCA, and LFP for high energy density. Demand concentrates in passenger vehicles and commercial fleets, driven by range requirements and federal tax credits from the US Inflation Reduction Act.
- Solid-State:Solid-state batteries employ a solid electrolyte, promising higher energy density, improved safety, and faster charging compared to liquid electrolyte counterparts. Research and development investments are heavily focused on this technology for next-generation premium EVs, aiming for long-term market disruption.
- NiMH:Nickel-metal hydride batteries offer robust performance in hybrid electric vehicles, providing a balance of power and cycle life for specific automotive applications.
- Lead-Acid:Lead-acid batteries primarily serve as 12V auxiliary power units in electric vehicles, supporting low-voltage systems and traditional vehicle functions.
Li-ion handles the majority of throughput; Solid-State is the fastest mover on share.
End User:
Supply chain dynamics in North America are increasingly shaped by the direct purchasing power and volume requirements of major end-user groups.
- OEMs:Original Equipment Manufacturers integrate EV batteries directly into new vehicle production lines, requiring high-volume, customized solutions and long-term supply agreements. This segment drives significant capital investment into regional battery manufacturing facilities, often through joint ventures.
- Fleet Operators:Commercial fleet operators purchase batteries for electric trucks, vans, and buses, prioritizing durability, total cost of ownership, and specific duty cycle performance. Demand from logistics and municipal fleets is accelerating across the US and Canada due to electrification mandates and operational cost savings.
- Retail Consumers:Individual retail consumers purchase electric vehicles, influencing battery demand through preferences for range, charging speed, and perceived safety.
- Battery Swapping Stations:Battery swapping stations provide rapid battery exchange services, primarily catering to commercial fleets and specific passenger vehicle models in urban centers.
OEMs command the largest volume share; Fleet Operators exhibit the most significant growth potential.
Capacity:
Electric vehicle battery capacity segments reflect diverse application requirements, from compact urban mobility to heavy-duty commercial transport.
- 60-100 kWh:This capacity range represents the sweet spot for mainstream long-range passenger electric vehicles and early electric light commercial vehicles. Demand is robust due to consumer expectations for extended range and the growing availability of fast-charging infrastructure.
- Above 100 kWh:Batteries exceeding 100 kWh are essential for high-performance passenger EVs, electric pickup trucks, and heavy-duty commercial vehicles. The segment's expansion is driven by the need for maximum range and payload capacity, particularly in the North American market.
- Below 30 kWh:Batteries under 30 kWh typically power smaller electric vehicles, urban delivery vans, and specific two-wheeler applications, balancing cost with sufficient range.
- 30-60 kWh:This capacity range serves entry-level passenger EVs and a variety of medium-duty commercial vehicles, offering a practical balance of cost and range.
The 60-100 kWh segment currently dominates market offerings; Above 100 kWh is rapidly gaining traction.
Application:
Application segments exhibit distinct margin profiles and technology requirements, influencing battery design and manufacturing priorities.
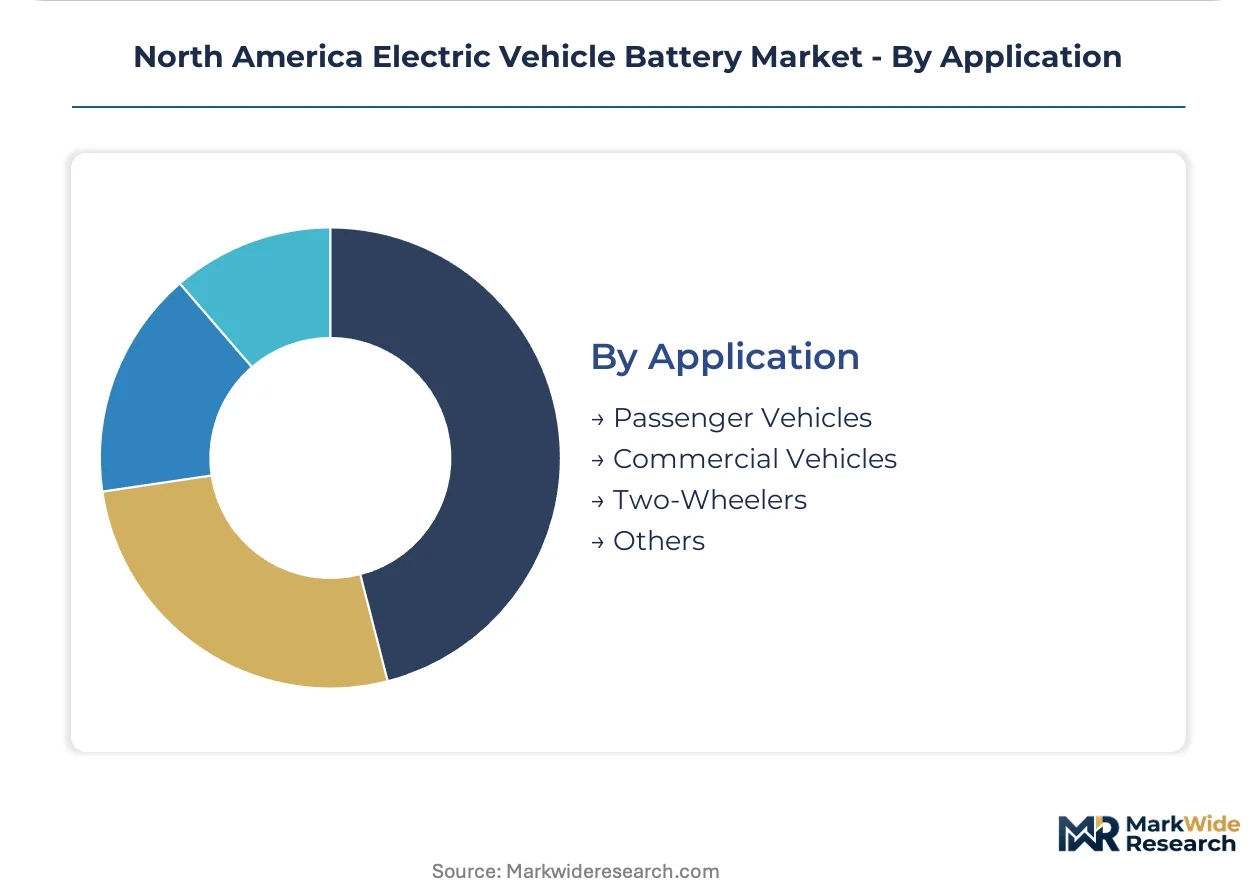
- Passenger Vehicles:This segment encompasses a wide array of electric cars, SUVs, and luxury vehicles, prioritizing energy density, fast charging, and safety features. Consumer preferences and regulatory mandates from the EPA and NHTSA drive substantial battery demand for this category across North America.
- Commercial Vehicles:Electric buses, trucks, and delivery vans constitute this segment, demanding robust, long-cycle-life batteries with high power output for heavy-duty operations. Commercial fleet electrification, spurred by federal policy incentives, is accelerating demand for durable battery packs tailored to specific operational profiles.
- Two-Wheelers:Electric two-wheelers, including motorcycles and scooters, require compact and lightweight battery solutions for urban mobility and short-distance travel.
- Others:This category includes specialized applications such as electric off-highway vehicles, marine vessels, and industrial equipment, each with unique battery performance requirements.
Passenger Vehicles account for the largest volume; Commercial Vehicles offer significant future growth potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American EV battery market is experiencing a significant shift in its trade balance. Policy incentives are driving a strong push towards reducing reliance on imported battery components and raw materials. This strategic pivot aims to establish robust domestic supply chains, fundamentally altering regional manufacturing footprints.
United States
Demand for EV batteries is surging from both passenger and commercial vehicle segments across the US. The US Inflation Reduction Act (IRA) provides substantial tax credits for domestically produced batteries and critical minerals. This policy has led to the concentration of new manufacturing investments within the US Southeast, forming a distinct 'Battery Belt'. States like Georgia, Kentucky, and Tennessee are seeing significant gigafactory development.
Canada
Electric vehicle mandates and consumer incentives are driving battery demand in Canada's growing EV market. Federal and provincial zero-emission vehicle policies create a guaranteed market for compliant electric vehicles and their battery systems. Ontario's established automotive manufacturing cluster is attracting significant investment for battery cell and component production. This includes projects focused on raw material processing and cathode active material facilities.
Mexico
Commercial vehicle electrification and established automotive production are boosting battery demand in Mexico. Mexico's existing automotive manufacturing ecosystem and favorable trade agreements present significant opportunities for cost-effective battery pack assembly. Several northern border states, particularly in the Bajío region, are becoming key sites for EV component and battery integration. This integration leverages proximity to US assembly plants and skilled labor.
North America Electric Vehicle Battery Market Key Industry Players
Concentration sits with established automotive battery manufacturers and their joint ventures. The market structure exhibits a tiered consolidation, with major players dominating cell production. Key archetypes include global battery giants, automaker-battery joint ventures, and specialized material suppliers. Competitive moves center on massive capacity expansion and securing long-term supply agreements for critical minerals.
Within the joint venture archetype, Ultium Cells, a collaboration between GM and LG Energy Solution, exemplifies a strategic domestic supply chain anchor for large-format pouch cells. SK On occupies a position as a specialist in high-performance pouch cells, supplying major automakers like Ford across North America. Panasonic Energy, leveraging its longstanding partnership with Tesla, represents a scaled producer of advanced cylindrical cells, particularly within the US. These players collectively reinforce the regional shift towards localized production and advanced battery chemistries.
| Leading Market Players |
|---|
| Samsung SDI |
| AESC Envision |
| LG Energy Solution |
| BlueOval SK |
| Ultium Cells |
| SK On |
| Tesla |
| Umicore |
| Panasonic Energy |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements, prevalent in the North American EV battery market, lock in both supply access and price visibility for critical battery components. This contract structure helps mitigate raw material volatility for major automotive OEMs.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing models for EV batteries. Price differentiation stems from cell chemistry performance, such as high-nickel content, and the volume scale of procurement. Pricing softness stems from intense competition among battery manufacturers to secure large OEM contracts, particularly for standard-range passenger vehicles. Commercial fleet operators exhibit the highest price sensitivity due to total cost of ownership considerations, while premium passenger vehicle manufacturers prioritize performance over cost.
Supply Chain Analysis
Strategic stockpiling of critical minerals and processed materials is gaining preference over just-in-time for North American EV battery manufacturers. The supply chain draws heavily from raw material extraction in Australia and Chile, with processing capacity primarily in Asia, particularly China and South Korea. Key dependencies include lithium, nickel, and cathode active materials. Critical mineral volatility represents a significant structural risk for regional battery production. Distribution runs through direct supply agreements between battery gigafactories in the US 'Battery Belt' and nearby automotive assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is experiencing a cyclical recovery, driven by sustained federal policy support through the US Inflation Reduction Act. Strategic positioning now hinges on localized production and resilient material sourcing.
For Market Incumbents:Shield market share by accelerating domestic capacity expansion in the US Southeast, specifically for high-nickel cathode chemistries. Consolidate upstream material processing through joint ventures to mitigate critical mineral volatility, a persistent threat. Invest in advanced manufacturing automation to reduce labor costs and improve production efficiency, leveraging IRA incentives. Control distribution channels directly to major automotive OEMs, ensuring compliant product delivery.
For New Entrants and Emerging Players:Anchor in niche applications like specialized commercial vehicles or stationary energy storage systems, which offer distinct performance requirements. Target cost-effective battery pack assembly in Mexico, leveraging its established automotive ecosystem for market entry. Focus on developing next-generation cell chemistries, such as solid-state batteries, to create a performance differentiation angle. Partner with regional material suppliers to ensure IRA compliance and secure critical mineral access.
For Investors and Strategic Acquirers:Capital is best deployed toward vertically integrated mid-cap specialists with established North American manufacturing footprints and compliant supply chains. Long-term viability in this sector hinges on securing access to critical minerals and advanced processing technologies. Target companies with intellectual property in solid-state battery development or advanced recycling capabilities for end-of-life EV batteries. A key signal to watch is the successful scaling of domestic cathode material production facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in US Southeast | Increases domestic battery output, supporting IRA compliance and regional automotive production. |
| Joint Ventures for Critical Mineral Processing | Secures stable supply of raw materials and reduces geopolitical supply chain risks for manufacturers. |
| Investment in Solid-State Battery R&D | Positions companies for next-generation EV performance and long-term technological leadership. |
| Commercial Vehicle Battery Customization | Addresses specific duty cycle and durability needs of growing logistics and municipal fleet segments. |
| Battery Recycling Infrastructure Development | Establishes a circular economy for materials, enhancing supply chain resilience and sustainability. |
Research Approach
The analysis maps the North America electric vehicle battery market, segmented by product type, end-user, capacity, and application, each validated through primary interviews with battery engineers, OEM procurement specialists, fleet operators, and material suppliers. Secondary validation draws from government reports, industry association data, and company financial filings. The study employs both bottom-up and top-down triangulation to ensure data accuracy and consistency.
All quantitative outputs were cross-referenced against external benchmarks and macro-economic indicators to ensure consistency over the projection horizon. The analytical framework models market volume and value across various segmentation dimensions, including vehicle class, propulsion architecture, and regional production cluster. Compound annual growth rates are derived from a combination of historical trends, EV sales projections, and anticipated raw material price shifts, applied across the modeling period.
Material uncertainties — including geopolitical shifts and unforeseen technological disruptions — sit outside the modeled envelope, as forecasts reflect current market assumptions. Practitioners should keep alternative scenarios live as regulatory landscapes, such as the US Inflation Reduction Act, and raw material availability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Latin America E-Bike Market
Electric Vehicles
Recreational Vehicle (RV) Batteries Market
Electric Vehicles
Scooter Market
Electric Vehicles
Europe Hybrid Electric Vehicle Battery Market
Electric Vehicles
Germany Electric Bus Battery Pack Market
Electric Vehicles
NGO Steel in Electric Vehicle Market
Electric Vehicles
Electric Moped Market
Electric Vehicles
South America Electric Bus Battery Pack Market
Electric Vehicles
Asia Pacific Electric Commercial Vehicles Market
Electric Vehicles
Electric Vehicle Regenerative Braking System Market
Electric Vehicles
E-Bike Smart Systems Market
Electric Vehicles
Europe Electric Bus Market
Electric Vehicles
Electric Vehicle Heating System Market
Electric Vehicles
Europe Electric Car Market
Electric Vehicles
Electric Two Wheelers MRO Market
Electric Vehicles
Lithium Battery Electric Scooters Market