
 Nordic E-Bike Market | 2026-2036
Nordic E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Nordic E-Bike Market Analytics
Danish battery pack assembly capacity is broadening as local producers scale cylindrical cell integration for Nordic weather conditions. Accell Group leverages its multi-brand portfolio to sustain distribution across Scandinavian specialty retailers. Giant Manufacturing Co Ltd anchors regional supply through its European logistics hub near Rotterdam. Trek Bicycle Corporation differentiates via dealer-service networks that handle winter salt corrosion and sub-zero battery performance.
Nordic e-bikes integrate brushless hub or mid-drive motors with lithium-ion battery packs rated for IP54 moisture protection and operating temperatures below minus fifteen degrees Celsius, delivering pedal-assisted propulsion for urban commuting, cargo hauling, and recreational trail riding across Denmark, Norway, Sweden, Finland, and Iceland. City bikes dominate unit volume as commuters prioritize step-through frames and integrated lighting for year-round use, while cargo bikes capture disproportionate margin pools from family transport and last-meter delivery substitution. Lithium-ion chemistry leads battery type segmentation due to energy density advantages in cold climates, though lithium polymer variants gain traction in premium foldable designs where weight reduction commands price premiums.
Denmark's national building codes mandate workplace bicycle parking minimums, while Norway's VAT framework and Sweden's climate action subsidies from the Swedish Environmental Protection Agency shape consumer purchase incentives. CE marking under EU machinery directives governs motor cutoff thresholds and electromagnetic compatibility for all Nordic market entrants. Stakeholders must monitor whether Finnish and Icelandic regulators adopt harmonized subsidy tiers or maintain divergent national schemes that fragment procurement economics.
Market Dynamics
Norway's VAT exemption for electric bicycles has triggered a structural demand pull that is reshaping Nordic municipal procurement patterns and consumer purchase behavior simultaneously.
Growth Catalysts
- Protected lane infrastructure:Copenhagen, Stockholm, and Oslo metropolitan authorities are expanding dedicated cycling corridors that reduce collision risk and commute times for pedal-assist users.
- CE marking harmonization:EU machinery directives governing motor cutoff thresholds and electromagnetic compatibility eliminate technical barriers to cross-border distribution within Denmark, Sweden, and Norway.
- Lithium-ion energy density:Cold-weather battery chemistry rated for operating temperatures below minus fifteen degrees Celsius extends usable range across Nordic winter conditions.
Market Restraints
- Cylindrical cell supply concentration:Battery pack assembly capacity remains concentrated among a limited set of regional integrators, creating input bottlenecks during demand surges.
- Sub-zero performance degradation:IP54 moisture protection standards do not fully address salt corrosion from road de-icing chemicals, accelerating frame and component wear.
- Workplace parking mandates:Denmark's national building codes impose compliance costs on commercial real estate developers that slow fleet adoption by small and medium enterprises.
Strategic Opportunities
- Finnish subsidy harmonization:Finnish regulators may adopt converged incentive tiers with Norwegian and Swedish frameworks, reducing procurement fragmentation across the Nordic zone.
- Cargo bike last-meter delivery:Family transport and urban logistics substitution is expanding addressable margin pools beyond traditional commuter segments.
- Folding premium designs:Lithium polymer variants in foldable configurations command price premiums from multi-modal transit users in dense metropolitan corridors.
Industry Challenges
- Dealer-service network scaling:Winter salt corrosion and battery thermal management require specialized technician training that outpaces current certification pipeline capacity.
- Swedish Environmental Protection Agency coordination:Climate action subsidy administration creates bureaucratic latency between application and disbursement, compressing seasonal sales windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nordic E-Bike Market |
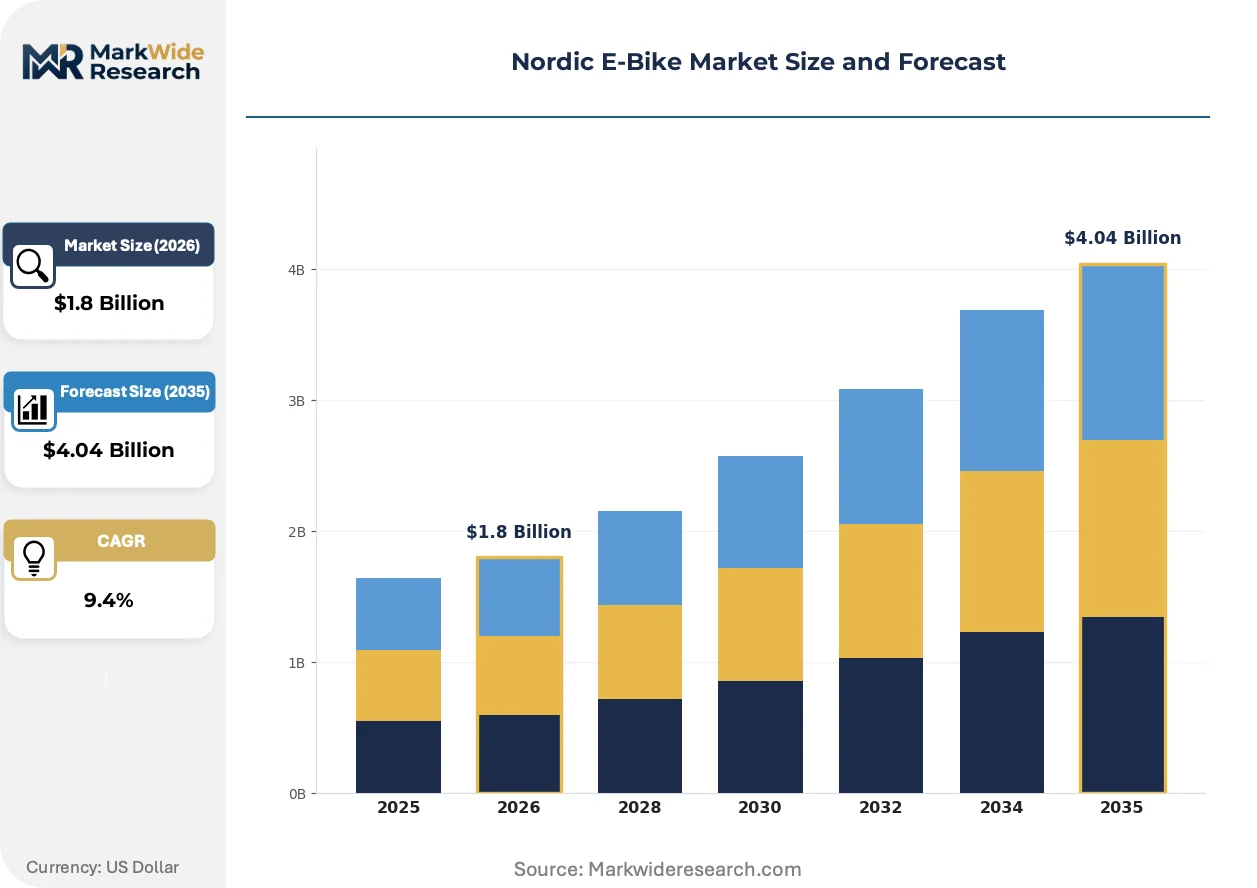
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: City Bikes, Mountain Bikes, Foldable Bikes, Cargo Bikes Battery Type: Lithium-Ion, Nickel-Metal Hydride, Lead-Acid, Lithium Polymer Consumer Segment: Recreational Users, Commuters, Delivery Services, Tourists Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Rental Services |
| Companies Covered | Accell Group, Giant Manufacturing Co Ltd, Trek Bicycle Corporation, CUBE Bikes, Royal Dutch Gazelle, Kalkhoff Werke GmbH, VanMoof, Cannondale Bicycle Corporation, Ecoride AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nordic E-Bike Market Evolving Landscape
Brushless hub and mid-drive motor architectures are converging with smart battery management systems to redefine reliability expectations for year-round Nordic cycling.
Cell-level battery management systems are integrating temperature monitoring and predictive heating algorithms that precondition lithium-ion packs before cold-weather discharge cycles. Fleet operators in Oslo and Copenhagen are adopting these systems fastest, prioritizing uptime guarantees over upfront hardware cost. This integration is compressing warranty claim rates and extending replacement intervals for commercial users.
Sweden's climate action subsidies from the Swedish Environmental Protection Agency are tightening eligibility criteria around lifecycle carbon accounting for imported components. Domestic assemblers are reconfiguring supply chains to capture these incentives. The cargo bike segment is responding most aggressively, with manufacturers accelerating local sourcing of frames and drivetrains.
Specialty retailers are unbundling after-sales service from hardware margins, creating subscription-based maintenance contracts for winter storage and corrosion prevention. This model is displacing traditional point-of-sale warranty bundles in Denmark's step-through city bike category. Copenhagen commuter clusters show the highest attachment rates for these service contracts.
Nordic E-Bike Market Segmentation
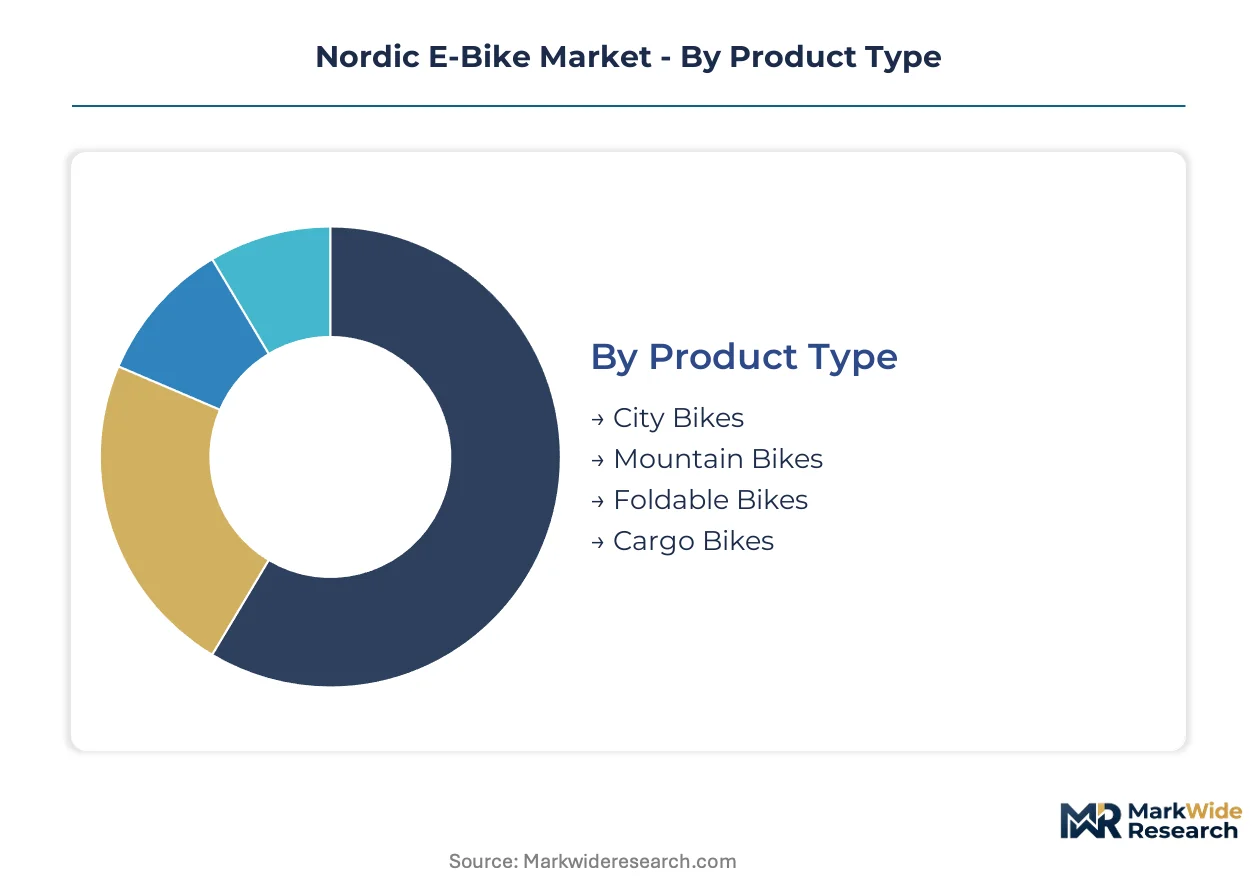
Segmentation in the Nordic E-Bike Market reveals how commuter priorities, climate adaptation, and subsidy eligibility reshape product development and channel strategy across Denmark, Norway, and Sweden.
Product Type:
City bikes dominate unit volume through step-through accessibility, while cargo bikes command disproportionate margin pools from family transport substitution.
- City Bikes:Step-through frames with integrated lighting and fenders address year-round commuting in Copenhagen and Stockholm. Danish workplace parking mandates and Norwegian VAT exemptions concentrate demand in metropolitan corridors where flat terrain favors pedal-assist adoption.
- Cargo Bikes:Extended wheelbase designs with dual-battery configurations haul children and commercial loads across Oslo's last-meter delivery networks. Sweden's climate action subsidies from the Swedish Environmental Protection Agency prioritize lifecycle carbon accounting that rewards locally assembled frames.
- Mountain Bikes:Full-suspension frames with torque-sensor mid-drives serve recreational trail networks in Norway's fjord regions.
- Foldable Bikes:Hinge-frame designs with lithium polymer packs target multi-modal transit users in dense urban cores.
Today's leader: City Bikes. Tomorrow's challenger: Cargo Bikes.
Battery Type:
Cold-weather chemistry separates premium from economy tiers, with energy density and thermal management defining regional suitability.
- Lithium-Ion:Cylindrical cell packs rated for IP54 moisture protection and operating temperatures below minus fifteen degrees Celsius power the majority of Nordic commuter fleets. Cell-level battery management systems with predictive heating algorithms are compressing warranty claims for Oslo fleet operators.
- Lithium Polymer:Pouch-cell configurations deliver weight reduction for premium foldable designs where gram savings justify price premiums in Copenhagen's multi-modal corridors.
- Nickel-Metal Hydride:Mature chemistry persists in budget commuter replacements with lower energy density tolerance for shorter Nordic winter ranges.
- Lead-Acid:Heavy, low-cycle chemistry occupies minimal share, limited to rental fleet backup power and entry-level price anchoring.
Today's leader: Lithium-Ion. Tomorrow's challenger: Lithium Polymer.
Consumer Segment:
Subsidy eligibility and trip distance requirements partition the market between individual purchasers and fleet procurement.
- Commuters:Daily pedal-assist users replacing car trips across Denmark, Sweden, and Norway's protected lane networks. CE marking harmonization under EU machinery directives eliminates cross-border technical barriers for this segment.
- Delivery Services:Commercial fleet operators in Oslo and Copenhagen adopting smart battery management systems for uptime guarantees over upfront hardware cost.
- Recreational Users:Weekend trail riders in Norway's mountain regions and Sweden's lake districts prioritizing suspension travel over urban utility.
- Tourists:Seasonal rental demand concentrated in Reykjavik and Helsinki waterfront corridors with short-trip, flat-terrain profiles.
Commuters anchor current volume. Delivery Services are expanding most quickly.
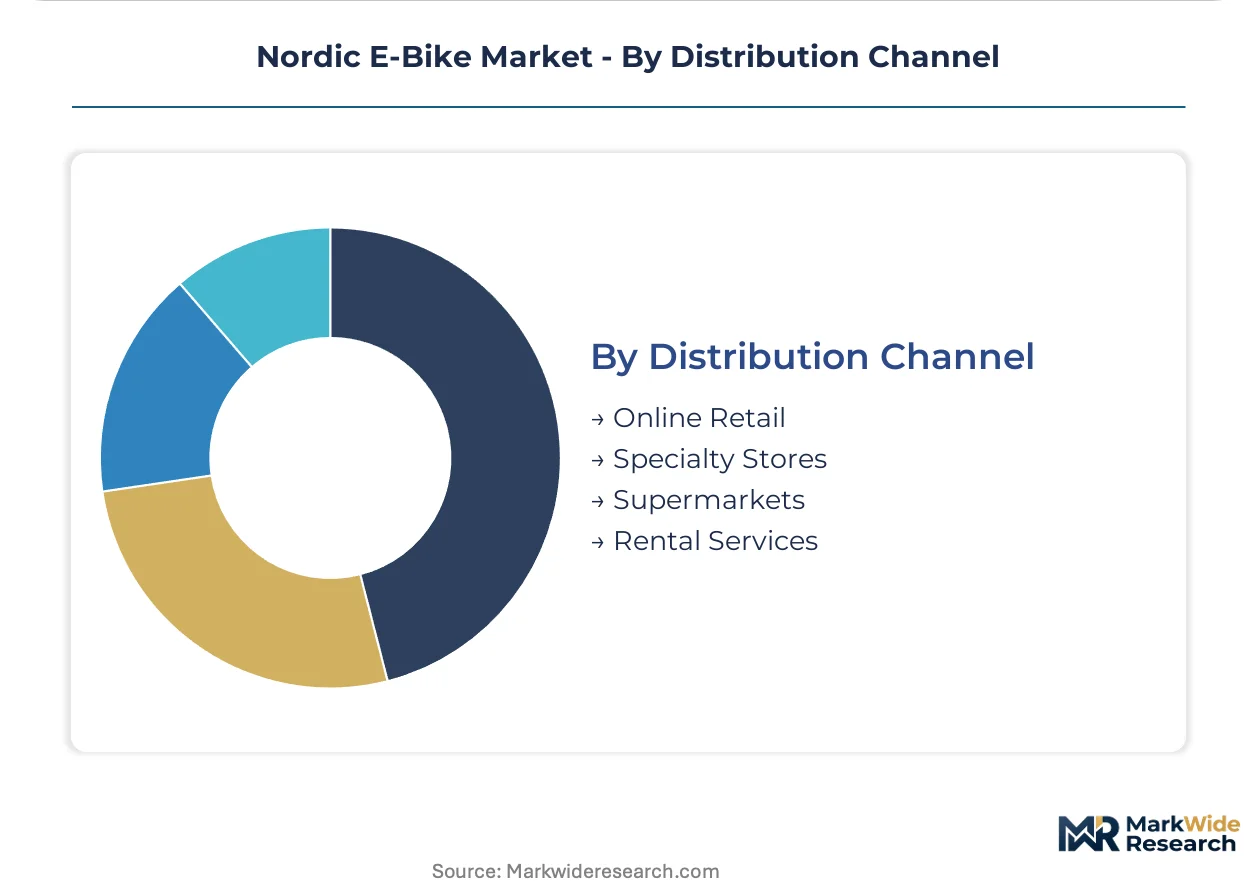
Distribution Channel:
Service integration and subsidy claim facilitation determine channel viability more than price competition alone.
- Specialty Stores:Dealer-service networks handling winter salt corrosion and sub-zero battery performance dominate premium city bike and cargo bike sales. Subscription-based maintenance contracts for winter storage are displacing traditional warranty bundles in Denmark.
- Online Retail:Direct-to-consumer platforms capture price-sensitive commuter volume where CE marking compliance is self-evident and assembly is minimal.
- Rental Services:Hourly and daily operators in tourist corridors and corporate fleet trials.
- Supermarkets:Mass-market entry points for basic commuter models with limited after-sales support.
Today's leader: Specialty Stores. Tomorrow's challenger: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where e-bike assembly capacity migrates within the Nordic zone, as cost-of-compliance gaps between Norwegian VAT frameworks and Swedish subsidy administration create divergent procurement economics for fleet operators and individual consumers.
Norway
Oslo's metropolitan corridor drives unit volume through last-meter delivery fleet expansion and family transport substitution. The national VAT exemption administered through Norwegian tax authorities eliminates a significant cost barrier that accelerates consumer purchase decisions. Bergen and Trondheim are emerging as secondary demand clusters where protected lane infrastructure is catching up to capital-region standards.
Denmark
Copenhagen anchors regional demand with the highest per-capita e-bike penetration among Nordic capitals, supported by flat terrain and dense metropolitan form. National building codes mandating workplace bicycle parking minimums impose compliance costs on commercial real estate that shape fleet adoption patterns. Aarhus and Odense are scaling cylindrical cell integration capacity to serve domestic assembly demand.
Sweden
Stockholm's archipelago geography concentrates demand in corridor-connected suburbs where pedal-assist bridges transit gaps. Climate action subsidies from the Swedish Environmental Protection Agency are tightening eligibility around lifecycle carbon accounting for imported components. Gothenburg and Malmö are reconfiguring supply chains to capture these incentives through local frame sourcing.
Finland
Helsinki's waterfront corridors generate seasonal rental demand with short-trip, flat-terrain profiles suited to tourist and commuter overlap. Finnish regulators are evaluating harmonized subsidy tiers with Norwegian and Swedish frameworks that would reduce procurement fragmentation. Tampere and Turku are developing dealer-service networks to handle winter salt corrosion and sub-zero battery performance.
Nordic E-Bike Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue premium foldable and cargo configurations that command price premiums in dense metropolitan corridors. The market structure exhibits moderate concentration with multi-brand portfolios coexisting alongside specialized single-brand operators. Three archetypes dominate: European legacy manufacturers with dealer-service networks, Asian scale producers with regional logistics hubs, and direct-to-consumer specialists with subscription-based maintenance models. Competitive moves center on strategic partnerships for battery pack assembly capacity and geographic expansion into Finnish and Icelandic markets where regulatory harmonization remains incomplete.
Within the multi-brand portfolio tier, Accell Group and Giant Manufacturing Co Ltd represent contrasting approaches to Nordic market coverage. Accell Group leverages its distributed brand architecture to sustain presence across Scandinavian specialty retailers handling winter service requirements. Giant Manufacturing Co Ltd anchors regional supply through its European logistics infrastructure positioned near Rotterdam. Trek Bicycle Corporation exemplifies the dealer-service network archetype, with positioning that emphasizes technician training for cold-climate battery thermal management.
| Leading Market Players |
|---|
| Accell Group |
| Giant Manufacturing Co Ltd |
| Trek Bicycle Corporation |
| CUBE Bikes |
| Royal Dutch Gazelle |
| Kalkhoff Werke GmbH |
| VanMoof |
| Cannondale Bicycle Corporation |
| Ecoride AB |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap assemblers in Denmark and Sweden anchor regional pricing discipline through captive battery pack integration and direct retailer relationships, insulating premium tiers from the cost volatility that squeezes economy imports.
Pricing Analysis
Retailer markup layers in Scandinavian specialty stores sustain premium positioning for city and cargo bikes through bundled winter service contracts. Three-tier pricing structure across premium, standard, and economy levels separates lithium polymer foldables with predictive heating from basic nickel-metal hydride commuters. Cost compression in economy tiers intensifies as online direct-to-consumer platforms bypass dealer networks. Fleet operators in Oslo show lowest price sensitivity, prioritizing uptime guarantees over per-unit acquisition cost.
Supply Chain Analysis
Cylindrical lithium-ion cell supply rests on South Korean and Chinese producers, with Danish integrators performing final pack assembly for Nordic thermal specifications. Key inputs include nickel-cobalt-manganese cathode material, electrolyte formulations rated for sub-zero operation, and IP54-rated battery management system housings. Single-source vulnerability concentrates in cathode precursor chemicals subject to EU critical raw materials list restrictions. Distribution runs through Rotterdam-anchored European logistics hubs serving Copenhagen, Stockholm, and Oslo metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Norway's VAT exemption operates as a regulatory compounder, accelerating purchase velocity and reshaping municipal procurement economics across the Nordic zone.
For Market Incumbents: Hedge against subsidy harmonization risk by diversifying assembly capacity across Danish, Swedish, and prospective Finnish production nodes. Deepen captive supply of cold-weather battery management systems to defend margin position against emerging direct-to-consumer entrants with offshore assembly. Prioritize technician certification pipelines for winter corrosion service. For New Entrants and Emerging Players: The gap between premium lithium polymer foldables and economy lead-acid rentals offers white-space entry for mid-tier lithium-ion city bikes with modular battery architecture. Finnish dealer-service networks remain underpenetrated relative to Copenhagen and Stockholm density. Capture this through subsidy-claim facilitation partnerships with local retailers. For Investors and Strategic Acquirers: Valuations sit cheapest among cylindrical cell integrators with established Nordic thermal testing protocols and retailer service contracts. Long-term viability hinges on regulatory persistence of national subsidy frameworks and building code mandates. Watch Finnish regulator announcements on harmonized incentive tiers as inflection signal for regional procurement consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Pack Assembly Scale-Up | Danish integrators expanding cylindrical cell capacity capture Norwegian VAT-exempt demand surge. |
| Dealer-Service Network Expansion | Technician training investments in Finland address winter corrosion and thermal management gaps. |
| Local Frame Sourcing Reconfiguration | Swedish assemblers pivot supply chains to satisfy Swedish Environmental Protection Agency lifecycle criteria. |
| Subscription Maintenance Launch | Copenhagen retailers unbundle service contracts to displace traditional point-of-sale warranty bundles. |
| Predictive Heating Algorithm Integration | Oslo fleet operators adopt smart battery management systems to compress commercial warranty claim rates. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with e-bike category managers at Scandinavian specialty retailers, procurement leads at Oslo and Copenhagen fleet operators, battery pack assembly engineers in Aarhus and Odense, and regulatory affairs specialists at national tax and environmental agencies. Secondary validation drew from EU machinery directive filings, national customs trade data, Swedish Environmental Protection Agency subsidy disbursement records, and municipal protected lane infrastructure investment disclosures. Bottom-up unit demand estimates triangulated against top-down market value reconstructions.
Comparable-period anchoring linked projection assumptions to historical VAT exemption uptake curves and workplace parking mandate compliance phases across the analysis window. Segmentation modeling spanned product type, battery chemistry, consumer segment, and distribution channel dimensions, with geographic regulatory cluster as an additional cross-cutting variable. CAGRs derived from logistic adoption curve fitting calibrated to Nordic urban density and fuel price differentials. Forecast inputs incorporated fleet operator battery replacement cycle data and specialty retailer inventory turnover benchmarks.
Caveats apply where Finnish subsidy harmonization delays or lithium-ion cell supply disruptions could materially shift the outlook. Forecasts reflect assumptions around regulatory persistence and input cost stability that warrant sensitivity testing. A small set of named triggers—Finnish incentive tier announcements, EU critical raw materials list revisions, and municipal lane infrastructure completion schedules—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Construction Electric Vehicle Market
Electric Vehicles
Electric Vehicle Battery Trays Market
Electric Vehicles
China Automotive High Performance Electric Vehicle Market
Electric Vehicles
South America Automotive High Performance Electric Vehicles Market
Electric Vehicles
Global Automotive High-Performance Electric Vehicles Market
Electric Vehicles
United Kingdom Electric Vehicle (EV) Market
Electric Vehicles
China Solar E-Bike Market
Electric Vehicles
Europe Electric Vehicle Thermal Management System Market
Electric Vehicles
Electric Vehicle Power Control Unit Market
Electric Vehicles
Canada E-Bike Market
Electric Vehicles
Middle East Electric Vehicle Market
Electric Vehicles
United Kingdom Hybrid Electric Vehicle Battery Market
Electric Vehicles
Latin America E-Bike Market
Electric Vehicles
Electric Vehicle (EV) Range Extender Market
Electric Vehicles
New Zealand E-Bike Market
Electric Vehicles
Automotive Battery Powered Propulsion System Market