
 United Kingdom E-Bike Market | 2026-2036
United Kingdom E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom E-Bike Market Analytics
The capital-intensity divergence between mass-market assemblers and premium engineering houses is unwinding competitive dynamics across the sector. Giant Manufacturing Co. Ltd. leverages integrated motor and battery supply chains to dominate volume manufacturing at scale. Brompton Bicycle Ltd. anchors its position through proprietary folding-frame engineering and domestic production in West London. Specialized Bicycle Components differentiates via advanced pedal-assist algorithms and direct-to-consumer digital channels.
A United Kingdom e-bike constitutes a bicycle equipped with an electric motor providing supplementary propulsion, typically limited to 250 watts of continuous rated power and pedal-assist cutoff at 25 km/h under UK and EU type-approval frameworks. These machines serve dual commercial and consumer purposes: reducing physical exertion for commuters while extending cargo-hauling range for urban logistics operators. City E-Bikes occupy the mature volume core, sustained by commuting demand and Cycle to Work salary-sacrifice schemes. Cargo E-Bikes represent the fastest-expanding product category, capturing margin pools from commercial fleet procurement as delivery services replace van-based last-mile operations. Mid-Drive Motor technology leads the premium tier, concentrating where torque sensing and hill-climbing performance command price premiums over hub-motor alternatives.
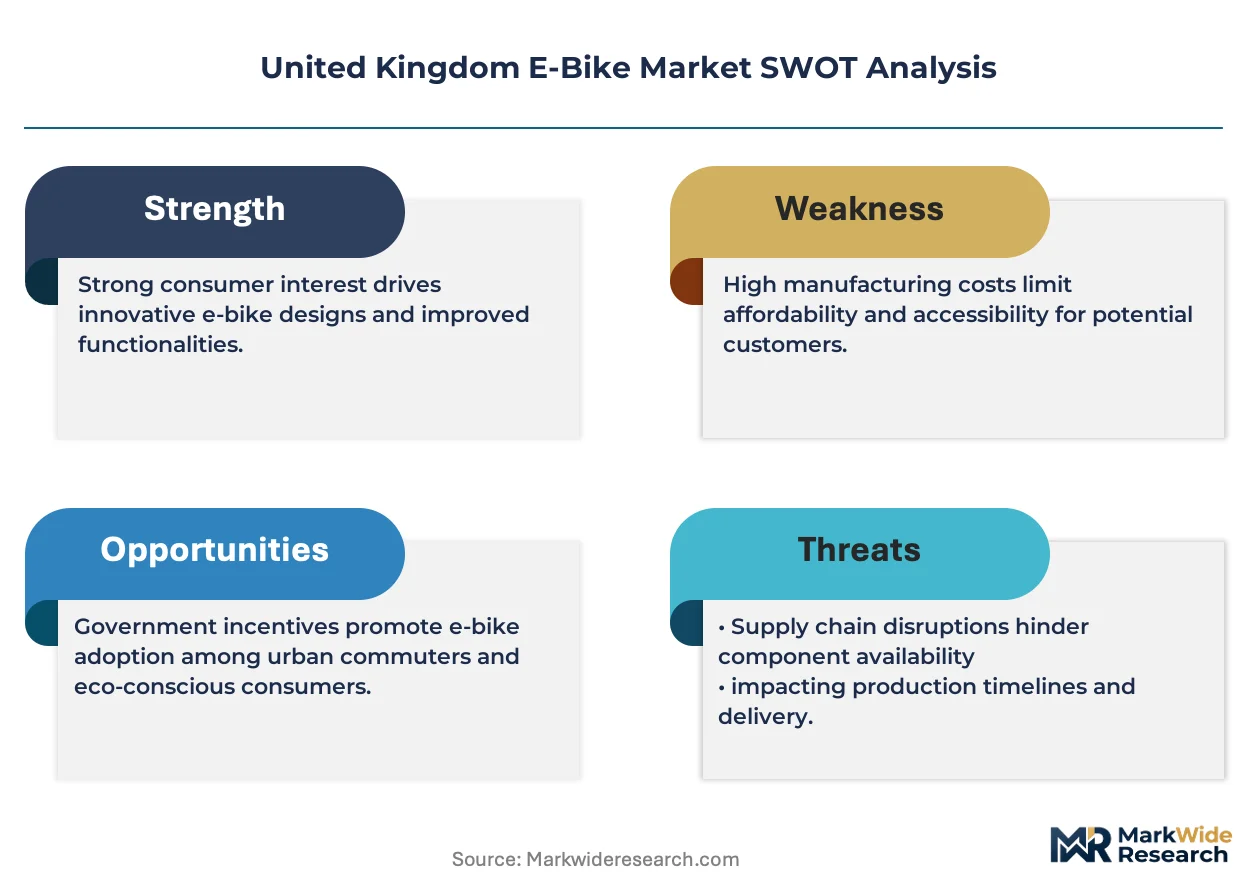
The UK's Vehicle Certification Agency enforces EU-derived type-approval standards for e-bike motor ratings and speed limitations, while the Department for Transport governs Cycle to Work tax relief thresholds that directly shape consumer affordability. Health and Safety Executive guidelines additionally influence commercial fleet adoption by establishing workplace charging and battery-storage protocols. Stakeholders must monitor how impending revisions to construction and use regulations, alongside potential battery-safety mandates from the Office for Product Safety and Standards, will reshape product design requirements and compliance costs.
Market Dynamics
Commercial fleet electrification is compressing replacement cycles and pulling mid-drive motor technology from premium consumer tiers into high-utilization logistics applications across Greater London.
Growth Catalysts
- Cycle to Work tax relief:Salary-sacrifice schemes reduce effective purchase prices for commuters, expanding addressable demand beyond enthusiast segments into mainstream mobility substitution.
- Low-emission zone expansion:Transport for London's ULEZ boundaries and congestion charging zones penalize internal-combustion van access, accelerating modal shift toward cargo e-bikes for last-mile delivery.
- Hub-motor cost curves:Chinese motor manufacturing scale has collapsed unit economics for entry-level propulsion systems, enabling sub-£1,000 retail price points that unlock mass-market penetration.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack assembly depends on cylindrical cell imports from East Asian suppliers, exposing assemblers to freight cost volatility and currency fluctuation risk.
- EU type-approval rigidity:The Vehicle Certification Agency's 250-watt continuous power ceiling and 25 km/h pedal-assist cutoff prevent product differentiation through performance tuning, compressing premium tier margins.
- Van-based delivery substitution:Subsidized electric van leasing through fleet operators presents a cost-competitive alternative for parcel volumes above 50kg, capping cargo e-bike addressable market expansion.
Strategic Opportunities
- Workplace charging infrastructure:Health and Safety Executive battery-storage protocol compliance creates service revenue pools for installers certifying commercial depot charging arrays.
- Midlands manufacturing corridor:Underutilized automotive component supplier capacity in the West Midlands offers nearshoring alternatives to Far Eastern frame and motor sourcing.
- Battery second-life applications:Degraded e-bike packs retain 70-80% capacity for stationary energy storage, opening circular-economy revenue streams through domestic refurbishment partnerships.
Industry Challenges
- Power electronics engineering scarcity:Motor controller firmware development requires embedded systems expertise concentrated in automotive and aerospace sectors, driving recruitment premiums above cycling industry pay scales.
- Insurance classification ambiguity:Underwriters lack standardized risk tables for commercial cargo e-bike fleets, delaying policy product development and fleet financing availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom E-Bike Market |
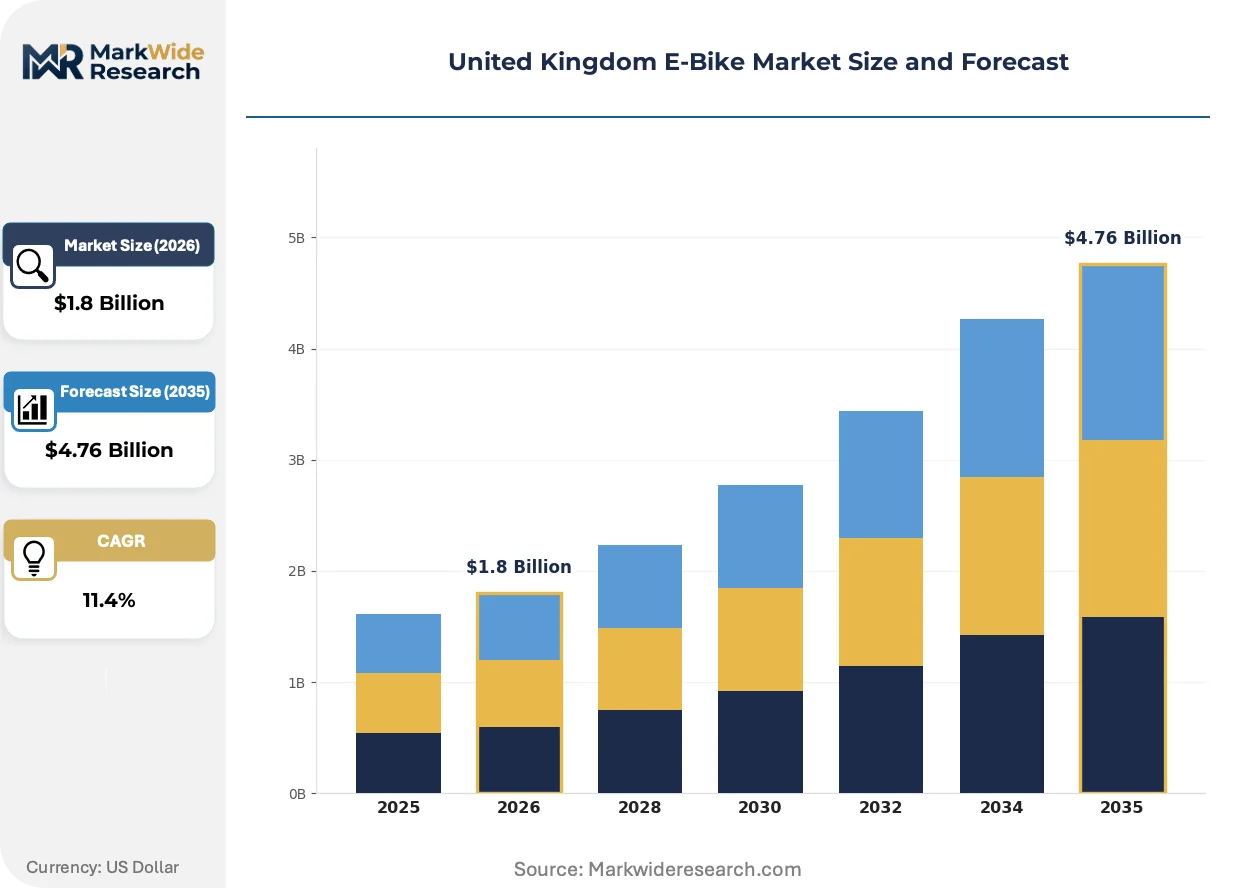
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: City E-Bikes, Mountain E-Bikes, Folding E-Bikes, Cargo E-Bikes Technology: Hub Motor, Mid-Drive Motor, Pedal Assist, Throttle Control End User: Commuters, Recreational Riders, Delivery Services, Tourists Sales Channel: Online Retailers, Specialty Bike Shops, Supermarkets, Rental Services |
| Companies Covered | Giant Manufacturing Co. Ltd., Trek Bicycle Corporation, Brompton Bicycle Ltd., Specialized Bicycle Components, Raleigh UK Ltd., CUBE Bikes, Accell Group, Canyon Bicycles, Rad Power Bikes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom E-Bike Market Evolving Landscape
Three parallel developments are restructuring how propulsion systems, regulatory compliance, and buyer relationships intersect in the United Kingdom market.
Mid-drive torque sensing is decomposing the historical trade-off between hill-climbing performance and battery range. Logistics operators running Greater London delivery circuits are specifying torque-vectoring mid-drive units for loaded cargo applications. This specification shift is decomposing hub-motor dominance in the commercial tier and compressing price premiums between consumer and fleet-grade propulsion systems.
Office for Product Safety and Standards battery-safety consultations are mandating thermal-runaway containment standards for e-bike battery packs. The proposed regulations would require flame-retardant casing materials and cell-level fusing that add £40-60 to pack manufacturing costs. Fleet procurement teams are pre-emptively specifying compliant designs to avoid retrofit obsolescence risk.
Subscription-based fleet provisioning is displacing capital purchase models among urban delivery operators. Third-party providers now offer per-mile pricing that bundles hardware, maintenance, and battery swap infrastructure. This arrangement concentrates most visible in London boroughs where depot space constraints prevent in-house charging infrastructure investment.
United Kingdom E-Bike Market Segmentation
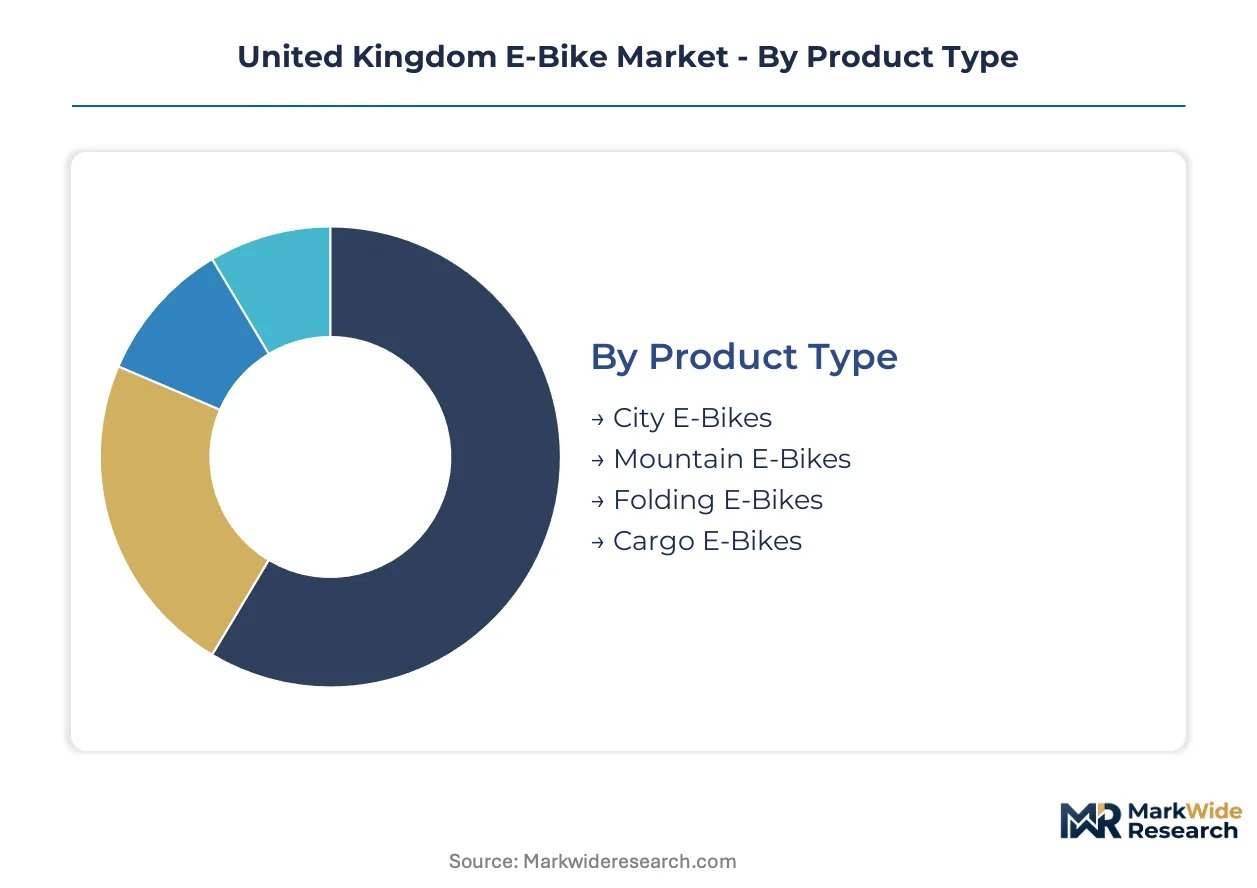
Segmentation reveals how distinct buyer motivations and use cases fragment the United Kingdom e-bike market into addressable tiers. Each dimension exposes different margin structures, channel requirements, and regulatory sensitivities that shape competitive positioning.
Product Type:
Domestic production concentrates on folding and cargo variants, while city and mountain e-bikes rely heavily on Far Eastern assembly imports.
- City E-Bikes:These machines feature step-through frames and integrated lighting systems optimized for urban commuting. Demand concentrates in Greater London and the Southeast, where Cycle to Work salary-sacrifice schemes reduce effective purchase prices below £800 entry points.
- Cargo E-Bikes:Extended wheelbases and reinforced frames accommodate 100-200kg payloads for commercial logistics. Fleet procurement from last-mile delivery operators across London boroughs is compressing replacement cycles and pulling mid-drive technology into high-utilization applications.
- Mountain E-Bikes:Suspension travel exceeds 120mm with torque-vectoring motor mapping for trail gradients.
- Folding E-Bikes:Brompton's West London manufacturing anchors proprietary hinge engineering for multimodal commuters.
City E-Bikes holds the largest share; momentum sits with Cargo E-Bikes.
Technology:
Cost tier separation runs deepest here, with hub-motor entry points below £1,000 and mid-drive systems commanding £2,500-plus premiums.
- Hub Motor:Direct-drive units integrated into wheel hubs deliver simplicity and low maintenance for price-sensitive buyers. Chinese manufacturing scale has collapsed unit economics, enabling mass-market penetration through online retailers and supermarket channels.
- Mid-Drive Motor:Centralized motor placement at the crankset enables torque sensing and optimized weight distribution. Premium positioning in cargo fleet specifications and enthusiast mountain applications sustains margins despite higher bill-of-materials costs.
- Pedal Assist:The 25 km/h cutoff mandated by Vehicle Certification Agency type-approval dominates UK regulatory compliance.
- Throttle Control:Restricted to private land use under Department for Transport construction regulations.
Hub Motor captures volume leadership; steepest expansion trajectory belongs to Mid-Drive Motor.
End User:
Application maturity varies sharply, with commuters representing a developed replacement market while delivery services drive net-new unit growth.
- Delivery Services:Commercial fleet operators specify modular battery systems and telematics integration for route optimization. Transport for London's ULEZ expansion and congestion charging zones penalize van access, accelerating modal shift toward electrified last-mile operations.
- Commuters:Salary-sacrifice procurement through employer Cycle to Work schemes dominates this segment, with tax relief thresholds directly shaping affordability ceilings.
- Recreational Riders:Weekend trail use and fitness applications concentrate in the Peak District and Scottish Highlands.
- Tourists:Rental demand clusters in Oxford, Cambridge, and coastal heritage destinations.
Commuters retain the largest installed base; Delivery Services is climbing the fastest.
Sales Channel:
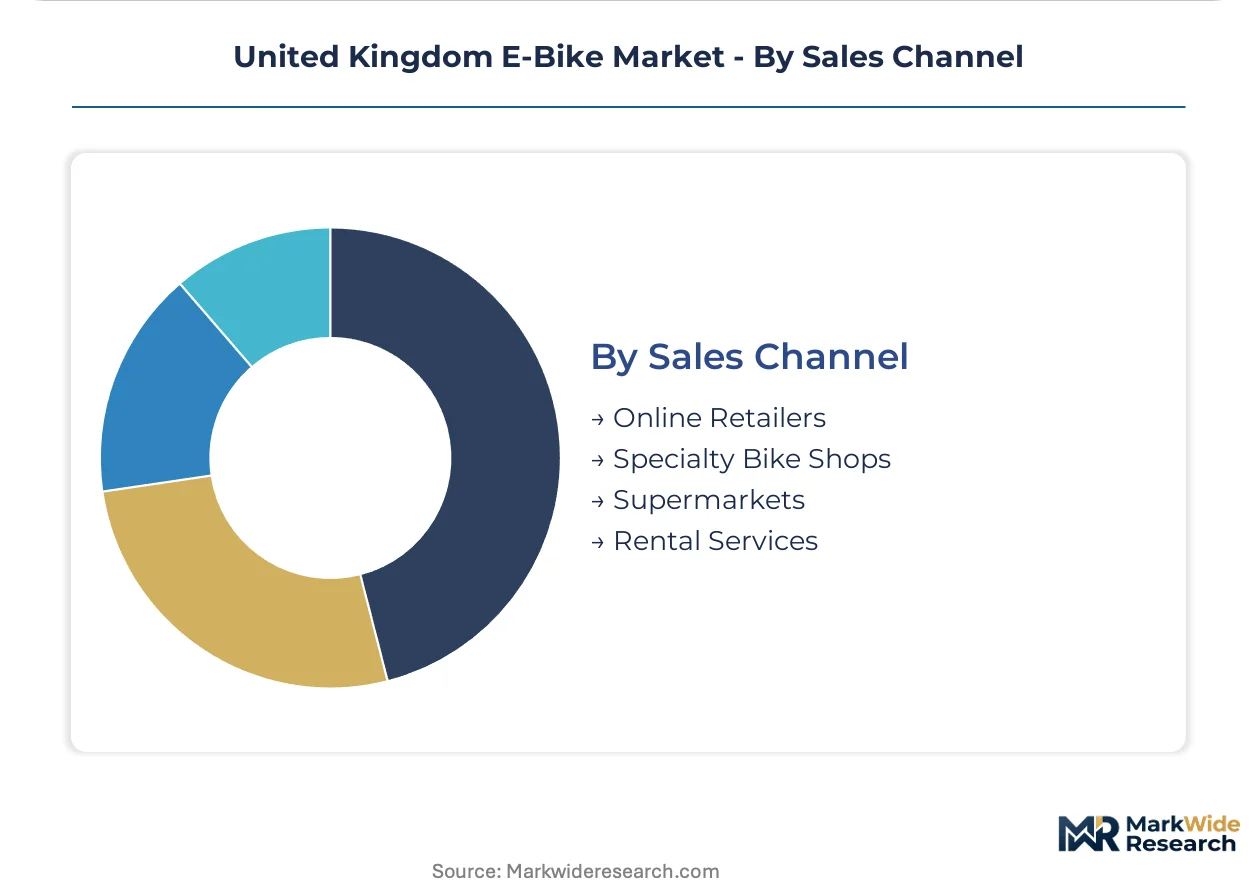
Customer type and purchase complexity dictate channel selection, with high-consideration buyers favoring physical inspection while price-sensitive segments migrate online.
- Specialty Bike Shops:Technical consultation and test-ride availability justify premium positioning. Independent retailers in London, Manchester, and Bristol concentrate mid-drive and cargo expertise for fleet procurement relationships.
- Online Retailers:Direct-to-consumer models bypass distributor margins, with logistics operators leveraging volume purchasing for standardized fleet specifications.
- Supermarkets:Hub-motor entry-level SKUs target impulse and gift purchasers.
- Rental Services:Subscription provisioning bundles maintenance and battery swap infrastructure for operators lacking depot space.
Specialty Bike Shops commands the highest transaction values; Online Retailers is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater London commands price premiums 15-20% above Northern England, while Midlands manufacturing clusters erode that advantage through domestic sourcing. Regional divergence reflects congestion charging enforcement density, employer scheme penetration, and logistics fleet electrification rates across sub-national markets.
London and Southeast
Transport for London's ULEZ expansion and congestion charging zones penalize van access, accelerating cargo e-bike procurement among last-mile operators. Cycle to Work salary-sacrifice scheme uptake concentrates here, with employer participation rates exceeding national averages. Fleet electrification in Camden, Hackney, and Southwark boroughs pulls mid-drive motor specifications from premium consumer tiers into commercial applications.
Midlands
West Midlands automotive component supplier capacity offers nearshoring alternatives to Far Eastern frame and motor sourcing. Birmingham and Coventry logistics corridors test cargo e-bike viability for regional distribution hubs outside London's regulatory perimeter. Manufacturing cost advantages from underutilized supplier networks support price-competitive assembly for national distribution.
North England
Manchester and Leeds cycling infrastructure investments expand commuter addressable markets beyond London-centric demand patterns. Employer scheme penetration lags the Southeast, suppressing effective price points and favoring hub-motor entry-level SKUs. Last-mile logistics electrification concentrates in city centers with emerging low-emission zone pilots.
Scotland
Edinburgh and Glasgow active travel budgets subsidize cargo e-bike procurement for municipal fleet operations. Scottish Government transport decarbonization targets outpace UK-wide timelines, accelerating commercial adoption curves. Highland recreational demand sustains premium mountain e-bike distribution through specialty retail channels.
Wales
Cardiff and Newport urban consolidation creates concentrated commuter demand corridors along the M4 corridor. Welsh Government transport grants supplement employer schemes, reducing effective purchase barriers below English market equivalents. Rural topography limits cargo fleet viability outside urban cores, segmenting demand toward recreational and tourist rental applications.
United Kingdom E-Bike Market Competitive Landscape
Concentration sits with integrated manufacturing houses and specialized engineering boutiques rather than pure-play assemblers. Giant Manufacturing Co. Ltd. leverages captive motor and battery supply chains to dominate volume manufacturing at scale. Brompton Bicycle Ltd. anchors position through proprietary folding-frame engineering and domestic West London production. Specialized Bicycle Components differentiates via advanced pedal-assist algorithms and direct-to-consumer digital channels. Strategic moves center on backward integration into power electronics and geographic diversification of battery pack assembly.
Within the premium engineering tier, Brompton Bicycle Ltd. and Specialized Bicycle Components exemplify divergent specialization strategies. Brompton occupies a position tied to multimodal urban mobility and domestic manufacturing heritage. Specialized sits within the performance-technology vector, emphasizing algorithmic differentiation and digital channel control. Giant Manufacturing Co. Ltd. represents the scale-driven archetype, with integrated supply chains enabling cost leadership across mass-market segments. These three anchors illustrate how competitive positioning fragments across manufacturing integration depth, proprietary engineering, and channel architecture rather than converging on single-dominant business models.
| Leading Market Players |
|---|
| Giant Manufacturing Co. Ltd. |
| Trek Bicycle Corporation |
| Brompton Bicycle Ltd. |
| Specialized Bicycle Components |
| Raleigh UK Ltd. |
| CUBE Bikes |
| Accell Group |
| Canyon Bicycles |
| Rad Power Bikes |
| Others |
Value Network & Pricing Analysis
Mid-drive motor substitution for hub-motor propulsion in cargo fleet specifications is simultaneously redrawing supply geography toward Taiwanese and German engineering houses while compressing the pricing premium between consumer and commercial tiers across the United Kingdom market.
Pricing Analysis
Configured-to-order cargo fleet specifications command 35-45% premiums over standard consumer SKUs, reflecting modular battery architectures and telematics integration requirements. Three-tier pricing structure across premium, standard, and economy levels stratifies around motor technology grade, with mid-drive systems anchoring the top tier and Chinese hub-motor units populating entry points below £1,000. Pricing pressure stems from subsidized electric van leasing programs that cap cargo e-bike addressable markets above 50kg payload thresholds. Delivery services exhibit the highest price sensitivity due to per-mile unit economics, while commuter enthusiasts through Cycle to Work schemes demonstrate lower elasticity for premium positioning.
Supply Chain Analysis
Inventory buffers for lithium-ion cylindrical cells have compressed to 6-8 weeks as East Asian suppliers prioritize automotive contract volumes over e-bike pack assembly. Motor controller firmware and battery management systems draw from Chinese, Taiwanese, and South Korean manufacturing clusters, with frame fabrication concentrated in Vietnam and Cambodia for cost-competitive entry-level SKUs. Single-source vulnerability sits with cylindrical cell supply from East Asian suppliers, exposing assemblers to freight cost volatility and currency fluctuation. Distribution runs through specialty bike shops for high-consideration purchases, direct-to-consumer digital channels for standardized fleet procurement, and supermarket retail for impulse-driven hub-motor entry points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom e-bike market is approaching a platform-economics inflection where subscription-based fleet provisioning and battery-swap infrastructure interoperability will determine competitive survival, driven by Transport for London's depot space constraints and the emergence of third-party per-mile pricing models.
For Market Incumbents: Compound defensive positioning through backward integration into power electronics engineering and captive battery pack assembly capacity in the West Midlands corridor. The scarcity of embedded systems firmware talent concentrated in automotive and aerospace sectors threatens margin sustainability. Prioritize certification investment for Office for Product Safety and Standards thermal-runaway containment standards to preempt retrofit obsolescence risk across fleet customer bases. For New Entrants and Emerging Players: Anchor in the Midlands manufacturing corridor where underutilized automotive component supplier networks offer nearshoring alternatives to Far Eastern sourcing. The most penetrable white space sits with workplace charging infrastructure installation and Health and Safety Executive compliance certification services for commercial depots lacking in-house technical capacity. Pursue direct-to-fleet digital channels bypassing traditional distributor markups. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed European e-bike assemblers lacking motor or battery supply chain captivity. Long-term viability over a 5-10 year window hinges on backward integration depth and geographic diversification of cell sourcing away from East Asian concentration. The signal to watch is subscription-fleet provider consolidation velocity as per-mile pricing models displace capital purchase arrangements among London borough delivery operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Electronics | In-house motor controller firmware development reduces dependency on automotive-sector recruitment premiums. |
| Midlands Manufacturing Footprint Expansion | West Midlands automotive supplier capacity offers nearshoring alternatives to Chinese frame sourcing. |
| Battery Second-Life Partnership Development | Domestic refurbishment channels for degraded packs open circular-economy revenue streams in stationary storage. |
| Subscription Fleet Platform Launch | Per-mile pricing bundles address depot space constraints across Transport for London's borough networks. |
| Workplace Charging Infrastructure Certification | Health and Safety Executive compliance services capture service revenue from commercial fleet operators. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement managers at last-mile delivery operators, product directors at domestic and international assemblers, independent specialty bike shop owners in London and Manchester, and regulatory affairs leads at the Vehicle Certification Agency and Office for Product Safety and Standards. Secondary validation drew from Department for Transport construction and use regulation filings, Transport for London ULEZ impact assessments, Health and Safety Executive battery-storage protocol documentation, and customs trade data for e-bike component imports. Bottom-up unit shipment estimates by product tier and technology type were triangulated against top-down market value reconstructions from salary-sacrifice scheme participation data and fleet procurement disclosures.
Across the analysis window, the quantitative framework modeled volume and value trajectories through segmentation by product type, motor technology architecture, end-user application, and sales channel configuration. CAGRs were derived from regression analysis against macroeconomic drivers including congestion charging zone expansion timelines, Cycle to Work tax relief threshold adjustments, and lithium-ion cell import cost indices. Industry-specific forecast inputs incorporated commercial fleet electrification rates across Greater London boroughs and the penetration velocity of subscription-based provisioning models.
Decision-makers should treat outputs as directional under assumptions of sustained ULEZ expansion and stable East Asian cell supply; material deviation in regulatory enforcement density or trade policy would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Norway E-Bike Market
Electric Vehicles
Vehicle Solar Panel Market
Electric Vehicles
Global Electric Vehicles Market
Electric Vehicles
Global Smart Electric Drive Market
Electric Vehicles
Electric Axle Drive Systems Market
Electric Vehicles
Electric Vehicle Sound Generators Market
Electric Vehicles
BEV On-Board Charger Market
Electric Vehicles
Commercial Electric Vehicle Dynamic Braking Resistors Market
Electric Vehicles
Pedelec Market
Electric Vehicles
Europe Electric Vehicle Power Inverter Market
Electric Vehicles
Mexico Electric Car Market
Electric Vehicles
South America Electric Bus Market
Electric Vehicles
South America Automotive High Performance Electric Vehicles Market
Electric Vehicles
Mexico Electric Bus Market
Electric Vehicles
Global EV on-Board Chargers Market
Electric Vehicles
Singapore Electric Vehicle Market