
 North America Real Estate Brokerage Market | 2026-2036
North America Real Estate Brokerage Market Size, Share, and Industry Trends Forecast 2026-2036
North America Real Estate Brokerage Market Insights
First-time millennial buyers and institutional single-family rental operators is bifurcating the client base that traditional brokerages must serve simultaneously. CBRE Group Inc. dominates institutional capital deployment through its global investor platform, while Compass leverages proprietary technology stacks to capture high-velocity residential transactions in coastal metros. eXp Realty sustains agent recruitment through its cloud-based commission model, challenging legacy brick-and-mortar cost structures across multiple state markets.
North America real estate brokerage encompasses licensed intermediary services that match property assets with capital sources, executing transactions governed by multiple listing service protocols, fiduciary duty standards, and localized escrow processes. Residential brokerage commands the largest transaction volume pipeline, though investment brokerage captures disproportionate fee margins per deal closure. Online platforms within the sales channel dimension are displacing traditional agent-dependent workflows fastest, while high-value transactions concentrate expertise and brand premium among established institutional advisors.
The Department of Housing and Urban Development enforces fair housing standards that constrain marketing practices and client qualification protocols across all fifty states. State-level real estate commissions layered beneath federal oversight create a fragmented licensing mosaic that elevates compliance costs for multi-jurisdictional operators. Stakeholders must monitor how artificial intelligence-driven valuation tools trigger fresh regulatory scrutiny from consumer protection agencies before embedding automated pricing engines into client-facing workflows.
Market Dynamics
Digital commission compression and cloud-based agent platforms are dismantling traditional brick-and-mortar cost structures across Sun Belt metropolitan corridors. Institutional capital deployment through specialized brokerage channels is simultaneously elevating service expectations for fiduciary-grade advisory.
Growth Catalysts
- Single-family rental institutionalization:Pension funds and REITs channel capital through dedicated investment brokerage desks, generating recurring advisory mandates and cross-border placement fees.
- HUD digital disclosure mandates:Federal transparency requirements accelerate platform adoption for transaction documentation and client qualification workflows.
- PropTech valuation engines:Automated pricing algorithms reduce time-to-listing for residential assets in high-velocity Texas and Florida markets.
Market Restraints
- State licensing fragmentation:Fifty separate real estate commission jurisdictions impose redundant compliance costs on multi-state operators seeking geographic expansion.
- Agent commission compression:Cloud-based competitors with lower fixed-cost structures force downward fee pressure on traditional percentage-based splits.
- Interest rate volatility:Federal Reserve policy shifts directly freeze transaction velocity in mortgage-dependent buyer segments.
Strategic Opportunities
- Arizona retirement corridor penetration:Demographic inflows into Phoenix-Tucson metroplexes create under-served listing inventory for tech-enabled brokerages.
- 1031 exchange advisory specialization:Tax-deferred replacement property rules incentivize dedicated intermediary services for accredited investor segments.
- AI-driven lead scoring:Predictive analytics converge with CRM platforms to prioritize high-intent buyer prospects before competitive contact.
Industry Challenges
- Dual-client fiduciary tension:Transaction brokers serving both institutional sellers and retail buyers face escalating litigation exposure around disclosure adequacy.
- MLS data integration latency:Legacy multiple listing service protocols create technical friction for real-time mobile platform synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Real Estate Brokerage Market |
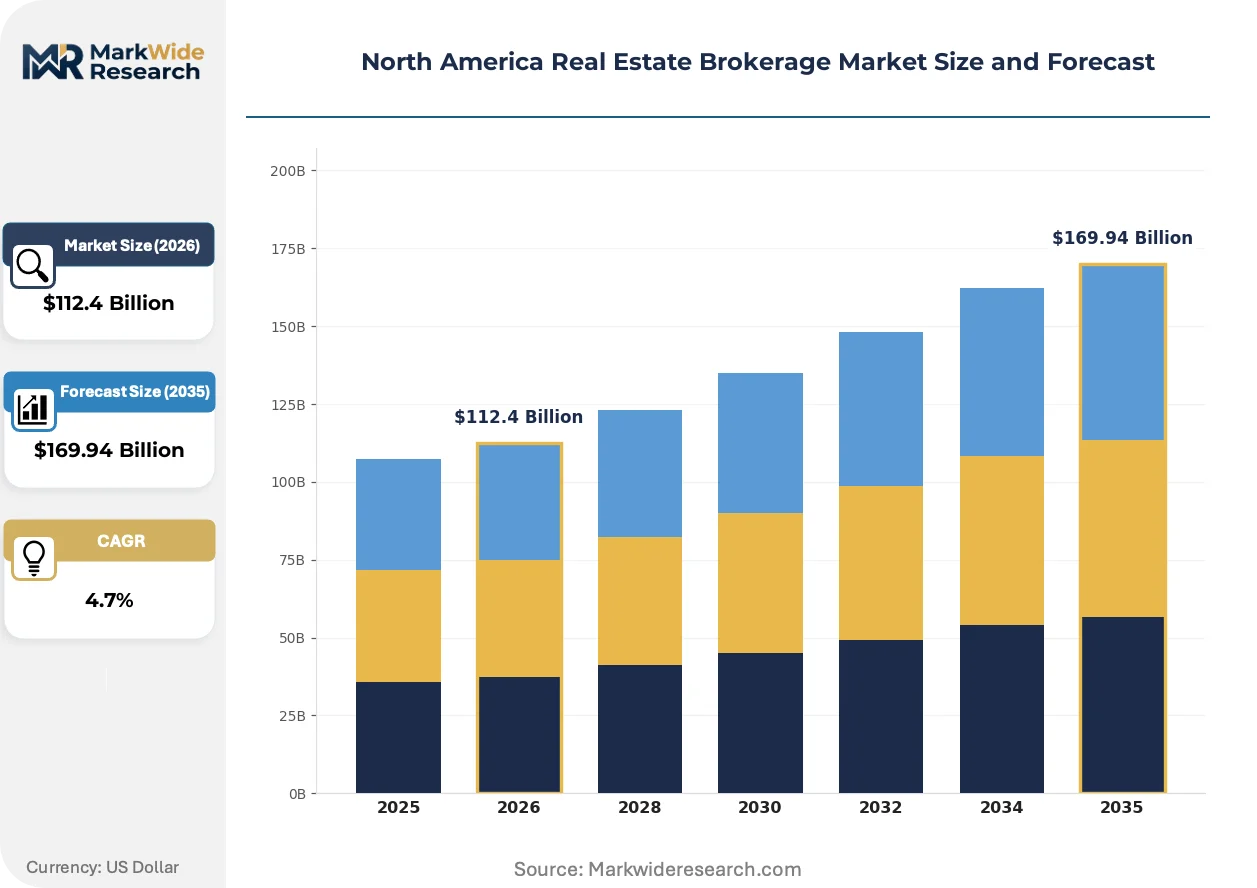
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $169.94 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential Brokerage, Commercial Brokerage, Investment Brokerage, Property Management Client Type: Individual Buyers, institutional Investors, Corporations, Real Estate Developers Transaction Size: Small Scale, Medium Scale, Large Scale, High-Value Transactions Sales Channel: Online Platforms, Traditional Agents, Auctions, Referral Networks |
| Companies Covered | CBRE Group Inc., JLL, Colliers International Group Inc., eXp Realty, Keller Williams Realty, Compass, Anywhere Advisors, Berkshire Hathaway HomeServices, HFF, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Real Estate Brokerage Market Trends and Innovations
Technology stacks are compressing traditional agent value propositions while regulatory scrutiny intensifies around algorithmic decision-making in housing markets. Capital allocation patterns favor platforms that reconcile speed with compliance depth.
Blockchain-based transaction records are fragmenting escrow and title verification workflows across distributed ledger architectures. Title insurers and underwriters in Texas and Florida pilot smart-contract closings to compress settlement timelines from weeks to days. This fragmentation threatens traditional title company intermediation by enabling peer-to-peer verification without centralized clearing.
The Department of Housing and Urban Development enforces algorithmic fairness audits on automated valuation models used in marketing and underwriting. Brokerage platforms deploying AI pricing tools must document disparate impact testing across protected class dimensions. Residential operators in California and New York face the steepest compliance retrofit costs as enforcement priorities concentrate in high-litigation jurisdictions.
Institutional buyers now unbundle transaction advisory from property management and asset disposition services. Single-family rental operators negotiate flat-fee placement arrangements separate from ongoing portfolio oversight, compressing traditional full-service commission structures. This unbundling is most advanced in Phoenix and Dallas-Fort Worth markets where institutional buyer concentration exceeds national averages.
North America Real Estate Brokerage Market Segmentation
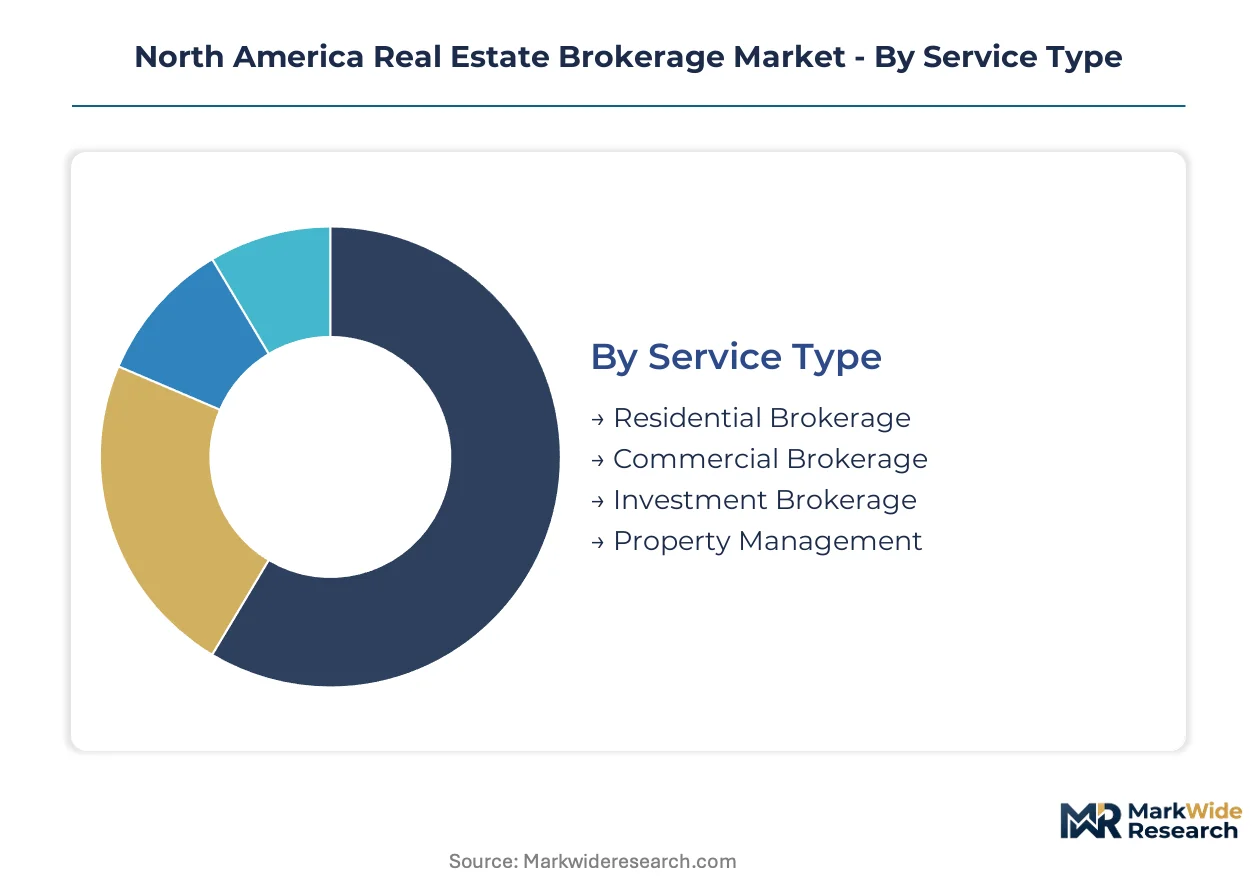
Segmentation reveals how regulatory fragmentation and capital source differentiation reshape service economics across North American real estate intermediation. Understanding these divisions exposes where compliance costs concentrate and which client relationships command premium advisory margins.
Service Type:
HUD disclosure mandates and state licensing requirements create divergent compliance burdens across service categories, elevating fixed costs for cross-border operators.
- Residential Brokerage:Licensed agents match individual buyers with single-family and condominium inventory through multiple listing service protocols. Transaction velocity concentrates in Sun Belt metropolitan corridors spanning Texas, Florida, and Arizona, where millennial first-time buyer demand intersects with institutional rental operator acquisition programs.
- Commercial Brokerage:Specialized advisors execute office, retail, and industrial asset transactions governed by complex environmental disclosure and zoning verification requirements. Fee structures in California and New York absorb elevated liability insurance costs from heightened litigation exposure around material defect representations.
- Investment Brokerage:Placement desks connect pension funds and REITs with income-producing assets through fiduciary-grade advisory mandates.
- Property Management:Ongoing operational oversight services unbundle from transaction execution under flat-fee arrangements in Phoenix and Dallas-Fort Worth.
Established volume favors Residential Brokerage; emerging adoption favors Investment Brokerage.
Client Type:
Capital source determines service intensity, with institutional mandates demanding dedicated coverage teams while retail segments absorb standardized platform workflows.
- Individual Buyers:First-time millennial purchasers and move-up households navigate mortgage qualification and inspection contingencies through agent-guided processes. Digital platform adoption accelerates in coastal metros where Compass and similar technology stacks compress search-to-offer timelines.
- Institutional Investors:Pension funds and single-family rental REITs deploy capital through specialized desks requiring cross-border placement capabilities and portfolio-level analytics. Arizona retirement corridor demographic inflows generate recurring advisory mandates for accredited investor segments.
- Corporations:Corporate real estate departments source facilities through tenant representation agreements with occupancy cost optimization mandates.
- Real Estate Developers:Ground-up project sponsors require land assemblage and entitlement navigation services ahead of construction financing.
Transaction concentration tilts toward Individual Buyers in volume terms; fee margin accrues disproportionately to Institutional Investors.
Transaction Size:
Deal scale dictates advisory depth, with high-value transactions demanding bespoke due diligence while standardized workflows capture velocity at lower tiers.
- Small Scale:Entry-level residential purchases and small commercial leases execute through streamlined platform workflows with reduced agent touchpoints. Commission compression pressures dominate this tier as cloud-based competitors challenge traditional percentage splits.
- Medium Scale:Multi-unit residential and light commercial transactions balance platform efficiency with localized expertise requirements for zoning and environmental verification.
- Large Scale:Substantial commercial assets and portfolio acquisitions command dedicated advisory teams with extended due diligence timelines.
- High-Value Transactions:Trophy assets and complex structured placements concentrate among established institutional advisors with global investor relationships and fiduciary-grade compliance infrastructure.
Platform economics favor Small Scale velocity; brand premium and expertise rents concentrate in High-Value Transactions.
Sales Channel:
Channel selection determines cost structure and regulatory exposure, with digital platforms accelerating disclosure compliance while traditional relationships retain high-stakes deal flow.
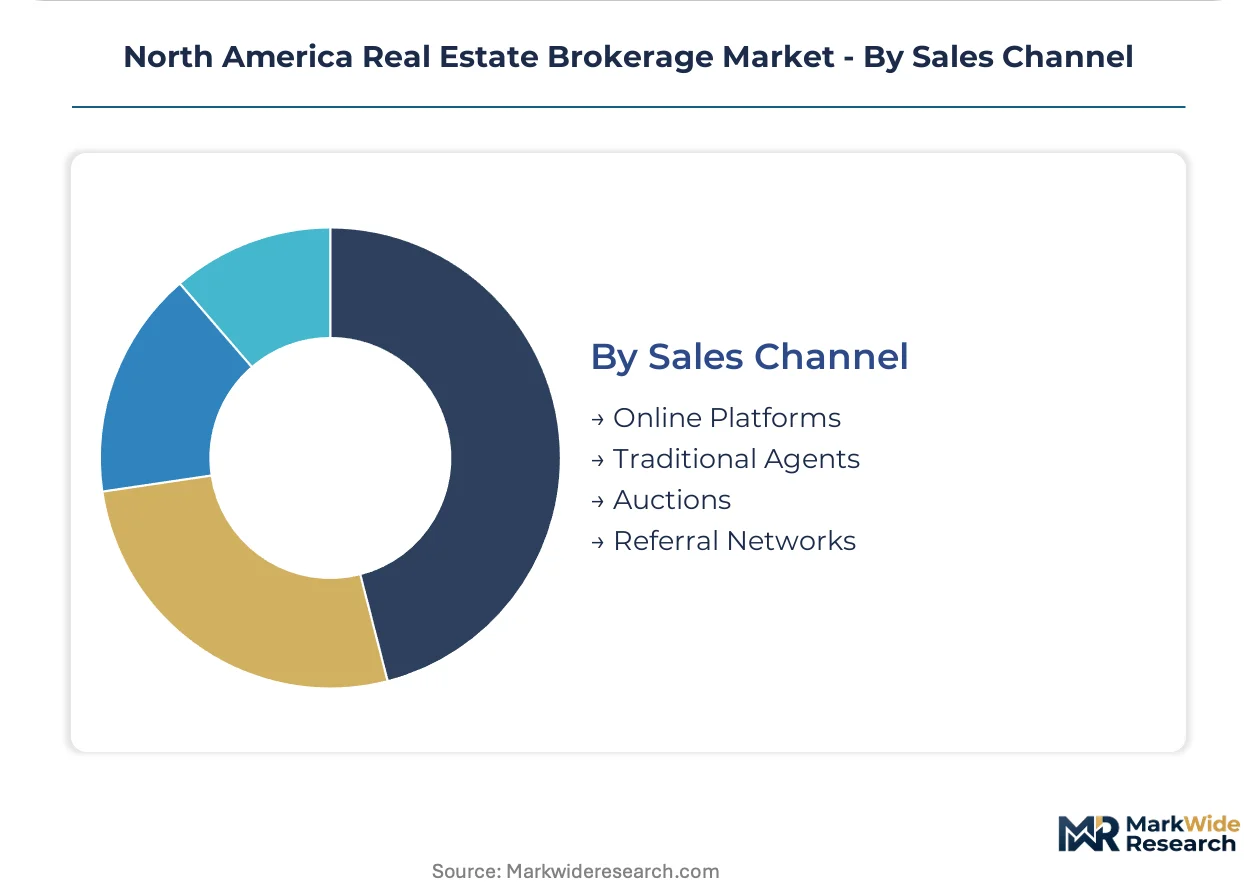
- Online Platforms:Technology-enabled marketplaces automate listing exposure, document management, and client qualification workflows. HUD digital disclosure mandates accelerate adoption across Texas and Florida markets where PropTech valuation engines reduce time-to-listing.
- Traditional Agents:Licensed intermediaries maintain relationship-driven deal execution with fiduciary duty standards and localized escrow process navigation. Brick-and-mortar cost structures face sustained pressure from cloud-based commission models.
- Auctions:Accelerated disposition channels for distressed or unique assets requiring price discovery through competitive bidding.
- Referral Networks:Inter-brokerage placement arrangements capture out-of-market buyer demand through reciprocal fee-sharing agreements.
Technology adoption climbs fastest through Online Platforms; relationship intensity and litigation risk retention favor Traditional Agents.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital flows from Canadian pension funds into Sun Belt metropolitan corridors anchor transnational brokerage activity across North America. Mexican industrial real estate draws cross-border placement mandates from US institutional advisors. The regional market fragments across three national regulatory regimes with divergent licensing and disclosure protocols.
United States
Single-family rental institutionalization and millennial first-time buyer demand concentrate transaction velocity in Texas, Florida, and Arizona metropolitan corridors. The Department of Housing and Urban Development enforces fair housing standards and digital disclosure mandates that reshape intermediary compliance obligations across all fifty states. Phoenix-Tucson metroplexes generate under-served listing inventory as demographic inflows accelerate retirement corridor penetration.
Canada
Pension fund capital deployment into US Sun Belt assets drives cross-border advisory mandates through specialized investment brokerage desks. The Financial Transactions and Reports Analysis Centre of Canada imposes anti-money laundering verification requirements on high-value property transactions. Toronto-based institutional advisors anchor fiduciary-grade placement capabilities for accredited investor segments seeking yield in foreign income-producing assets.
Mexico
Nearshoring manufacturing demand and logistics facility expansion attract industrial real estate capital from US and Canadian institutional sources. The Secretariat of Economy oversees foreign investment registry requirements that complicate cross-border transaction execution for non-domestic brokerage operators. Monterrey and Tijuana industrial corridors concentrate foreign direct investment flows requiring specialized intermediary services for land assemblage and entitlement navigation.
North America Real Estate Brokerage Market Competitive Landscape
Listed leaders compete with private specialists across capital source segmentation, creating a bifurcated market structure where scale-driven platforms and relationship-heavy boutiques coexist. Publicly traded firms dominate institutional capital deployment through global investor networks, while private operators capture high-velocity residential transactions in coastal and Sun Belt metros. Three archetypes define competitive positioning: technology-enabled volume platforms, fiduciary-grade institutional advisors, and cloud-based agent networks with minimal fixed-cost structures. M&A activity concentrates on PropTech capability acquisition, while geographic expansion targets under-penetrated retirement corridors.
Within the institutional advisory tier, CBRE Group Inc. and JLL exemplify fiduciary-grade placement capabilities for pension fund and REIT capital deployment. Compass occupies a position among technology-enabled residential platforms leveraging proprietary stacks for transaction velocity in coastal metropolitan markets. eXp Realty sits within the cloud-based network archetype, challenging legacy brick-and-mortar cost structures through distributed agent recruitment models across multiple state jurisdictions.
| Leading Market Players |
|---|
| CBRE Group Inc. |
| JLL |
| Colliers International Group Inc. |
| eXp Realty |
| Keller Williams Realty |
| Compass |
| Anywhere Advisors |
| Berkshire Hathaway HomeServices |
| HFF |
| Others |
Pricing and Supply Chain Analysis
Cloud-based agent platforms achieving 80-90% fixed-cost reduction versus brick-and-mortar operations compress price floors across Sun Belt metropolitan corridors while concentrating supply-side power among technology-enabled brokerages with scalable infrastructure. This scale dynamic simultaneously erodes traditional percentage-based commission structures and elevates platform economics for operators capturing high-velocity transaction volume.
Pricing Analysis
Legacy commission-split models versus flat-fee disruptors versus AI-augmented advisory tiers define the three-tier pricing structure across premium, standard, and economy levels in North American real estate brokerage. Price differentiation rests on technology stack sophistication and institutional client certification depth, with fiduciary-grade advisory commanding premium placement fees while cloud-based competitors drive cost compression in residential transaction tiers. Pricing pressure stems from eXp Realty's distributed agent recruitment model challenging legacy splits across multiple state markets. Retail individual buyers exhibit highest price sensitivity to commission rates, whereas pension fund capital deployment tolerates elevated advisory fees for cross-border placement capabilities.
Supply Chain Analysis
Strategic stockpiling of licensed agent relationships and MLS data access agreements dominates inventory strategy over just-in-time talent acquisition in real estate brokerage. Geographic supply concentration centers on Texas, Florida, and Arizona for transaction velocity, with California and New York anchoring high-value commercial advisory expertise. Raw material dependencies include proprietary technology stacks, multiple listing service data feeds, and fiduciary-grade compliance infrastructure. Supply chain risk concentrates in single-source vulnerability around legacy MLS protocol integration latency. Distribution runs through cloud-based agent networks displacing traditional brick-and-mortar storefront dependency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation across state licensing jurisdictions and bifurcated client demands creates white-space opportunities for specialized operators targeting underserved retirement corridors and institutional capital channels.
For Market Incumbents: Shield commission structures from cloud-based compression by deepening proprietary technology investment and capturing institutional capital deployment mandates through fiduciary-grade advisory specialization. Legacy brick-and-mortar operators face existential threat from eXp Realty's distributed cost model; vertical integration into PropTech valuation engines and AI-driven lead scoring platforms offers defensive capability differentiation. Capacity addition in Phoenix-Tucson metroplexes addresses demographic inflow concentration. For New Entrants and Emerging Players: Arizona retirement corridor penetration gaps offer immediate service-layer white-space where established volume platforms under-serve aging demographic inflows with specialized advisory needs. Single-family rental institutionalization in Dallas-Fort Worth and Phoenix presents the most penetrable segment for dedicated investment brokerage desks unbundled from property management. Go-to-market execution should prioritize 1031 exchange advisory specialization targeting accredited investor segments with tax-deferred replacement property expertise. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cloud-based agent networks with minimal fixed-cost structures and scalable commission models over legacy brick-and-mortar operators facing sustained margin compression. Long-term viability across the projection horizon accrues to platforms reconciling transaction velocity with HUD compliance depth. Acquisition targets should demonstrate AI-driven workflow integration and cross-border placement capabilities. The signal to watch is institutional buyer concentration exceeding metro-area thresholds triggering unbundling of transaction advisory from ongoing portfolio services.| Strategic Initiative | Industry Significance |
|---|---|
| PropTech Capability Acquisition | AI valuation engines reduce time-to-listing in high-velocity Texas and Florida corridors. |
| Cloud-Based Agent Network Expansion | Distributed recruitment models challenge legacy fixed-cost structures across state jurisdictions. |
| Institutional Advisory Desk Buildout | Fiduciary-grade placement capabilities capture pension fund capital deployment mandates. |
| 1031 Exchange Specialization | Tax-deferred replacement property rules create dedicated service niches for accredited investors. |
| Retirement Corridor Geographic Penetration | Phoenix-Tucson demographic inflows generate under-served listing inventory for tech-enabled operators. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with real estate brokerage executives, state licensing commission administrators, institutional capital placement officers, and PropTech platform engineers; and secondary validation through HUD regulatory filings, state real estate commission disclosure databases, MLS operator technical specifications, and SEC filings from publicly traded brokerage firms. Bottom-up transaction volume modeling triangulated against top-down capital flow estimates across the analysis window.
Forecasts spanning the projection horizon applied analytical frameworks segmenting by service type, client capital source, transaction scale tier, and sales channel technology intensity. CAGRs derived from historical transaction velocity patterns adjusted for interest rate sensitivity and institutional capital allocation shifts. Industry-specific inputs included Federal Reserve policy trajectory impacts on mortgage-dependent buyer segments and HUD algorithmic fairness audit enforcement priorities.
Forecasts assume regulatory continuity in Department of Housing and Urban Development disclosure mandates and state-level licensing frameworks; material policy shifts would require re-modeling. Revision becomes warranted when interest rate volatility crosses thresholds freezing transaction velocity or when MLS data integration latency accelerates platform displacement beyond modeled adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
Real Estate Market
Residential Real Estate Market
North America Tiny Homes Market
Residential Real Estate Market
Vietnam Residential Real Estate Market
Residential Real Estate Market
Canada E-House Market
Residential Real Estate Market
UK Residential Real Estate Market
Residential Real Estate Market
United States Manufactured Homes Market
Residential Real Estate Market
Myanmar Residential Real Estate Market
Residential Real Estate Market
Mexico Residential Real Estate Market
Residential Real Estate Market
Latin America Residential Real Estate Market
Residential Real Estate Market
Armenia Real Estate Market
Residential Real Estate Market
Saudi Arabia Residential Real Estate Market
Residential Real Estate Market
Global Manufactured Housing Market
Residential Real Estate Market
Qatar Manufactured Homes Market
Residential Real Estate Market
Singapore Real Estate Market
Residential Real Estate Market
Asia Pacific Manufactured Homes Market
Residential Real Estate Market
Germany Residential Real Estate Market