
 Real Estate Market | 2026-2036
Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Real Estate Market Intelligence
Data center and logistics demand is recalibrating institutional allocation away from conventional office and retail exposure. Blackstone leverages its scale in logistics warehouses across North America and Europe to capture e-commerce fulfillment demand. Brookfield Asset Management anchors its strategy in renewable-powered data center campuses and critical infrastructure. Prologis dominates last-mile industrial development through its proprietary land bank and pre-leased build-to-suit pipeline.
Real estate encompasses land and permanent improvements—foundations, utilities, envelopes, and mechanical systems—valued for income generation, occupancy, or capital appreciation. The asset class serves commercial, residential, industrial, and institutional users through lease structures, development yields, or operational cash flows. Residential and industrial property types currently attract the deepest capital pools, while commercial office faces structural repricing from remote work permanence. Core and value-add investment strategies draw the largest fund commitments, though opportunistic development generates the highest absolute returns in supply-constrained submarkets.
FDA oversight of medical office buildings, EPA brownfield remediation standards, and FERC interstate pipeline siting rules shape development feasibility and liability exposure across U.S. real estate. The SEC's climate disclosure mandates for public REITs now require portfolio-level emissions accounting, redirecting capital toward certified green buildings. Stakeholders must monitor how evolving carbon reporting requirements and interest rate trajectories interact to redefine asset valuations and refinancing risk.
Market Dynamics
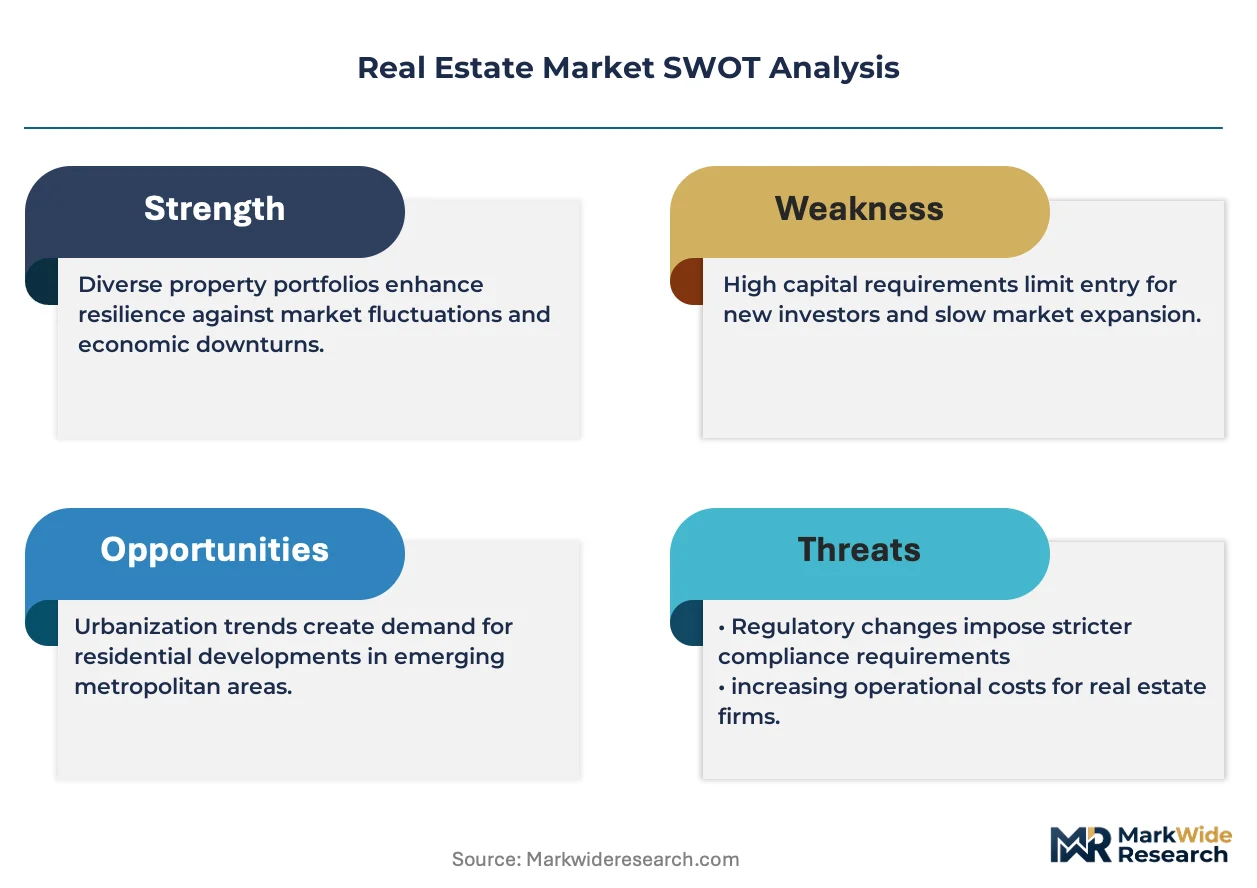
Institutional capital rotation away from traditional office assets toward logistics and data center infrastructure is compressing yield spreads and repricing risk premiums across property portfolios. The EU Green Deal's building performance standards are accelerating asset obsolescence and forcing capital deployment into retrofit pipelines.
Growth Catalysts
- E-commerce fulfillment density:Last-mile logistics demand from retail distribution networks is absorbing industrial vacancy in Sun Belt metropolitan areas. Developers are pre-leasing build-to-suit warehouses before breaking ground.
- CSRD disclosure mandates:The EU's Corporate Sustainability Reporting Directive is redirecting institutional mandates toward certified green buildings with verified emissions profiles. Asset managers face portfolio-level carbon accounting requirements.
- Hyperscale computing expansion:Cloud infrastructure providers are contracting renewable-powered data center capacity a decade in advance. Power purchase agreements and land banking precede construction starts.
Market Restraints
- Construction cost volatility:Steel and concrete input prices have destabilized development pro formas. Fixed-price contracts now carry material escalation clauses that erode developer margins.
- Zoning and entitlement timelines:Municipal approval processes for industrial and data center projects extend 24-36 months in supply-constrained submarkets. Entitlement risk capital commands premium returns.
- Interest rate sensitivity:Floating-rate construction debt and long-duration lease structures expose refinancing gaps. Cap rate expansion has compressed levered equity returns on core acquisitions.
Strategic Opportunities
- Brownfield adaptive reuse:EPA remediation standards are unlocking former industrial sites for logistics and life science conversion. Environmental liability insurance products are maturing to facilitate transactions.
- Edge data center deployment:5G network densification is creating demand for sub-5MW facilities in secondary markets. Latency-sensitive applications are bypassing hyperscale campuses.
- Residential build-to-rent pipelines:Institutional single-family rental platforms are aggregating scattered-site portfolios for operational scale. Property management technology enables centralized oversight of dispersed assets.
Industry Challenges
- Decarbonization execution:Retrofitting existing building envelopes and mechanical systems to meet performance standards requires specialized contracting capacity. Skilled labor shortages delay project timelines.
- Tenant credit underwriting:Remote work permanence has fragmented office tenant demand. Lease rollover exposure in Class B central business district assets requires granular cash flow stress testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Real Estate Market |
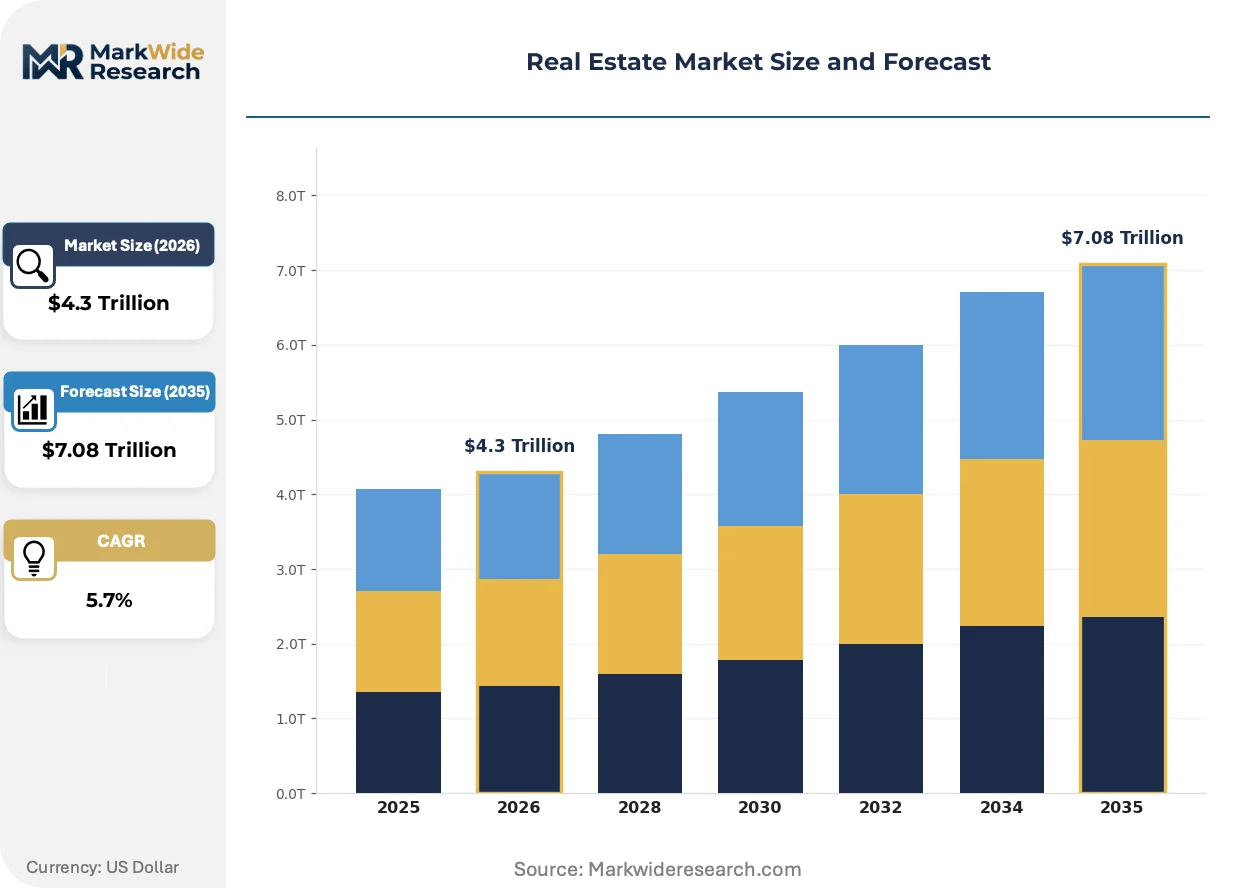
| Market Size in 2026 | $4.3 Trillion |
| Market Size in 2035 | $7.08 Trillion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Residential, Commercial, Industrial, Agricultural Investment Strategy: Value-Add, Core, Opportunistic, Development Client Type: Retail Investors, Institutions, Fund Managers, REITs Market Segmentation: Luxury, Affordable, Mid-Range, Mixed-Use |
| Companies Covered | Blackstone, Brookfield Asset Management, Blue Owl Capital, Prologis, Welltower, Equinix, Simon Property Group, Carlyle Group, TPG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Real Estate Market Strategic Shifts & Innovations
PropTech platforms and building automation systems are compressing operational inefficiencies and enabling predictive asset management. Capital deployment now discriminates based on digital infrastructure readiness.
Building electrification through heat pump retrofits and on-site solar-plus-storage systems is electrifying operational carbon profiles. Multifamily and industrial owners are adopting these packages to meet SEC climate disclosure thresholds for public REITs. The technology is compressing utility cost volatility and extending asset competitive positioning.
The EU Green Deal's building performance standards are mandating energy efficiency renovations and fossil fuel phaseouts for commercial and residential stock. Asset managers are front-loading capital plans to avoid stranded asset classification. German and French portfolios face the most compressed compliance timelines.
Institutional procurement of real estate exposure is tilting toward operational platforms with integrated property management and development capabilities. Separate account mandates favor sponsors with proprietary pipelines over fund-of-fund structures. This pattern concentrates capital with scale players in US Sun Belt and Northern European logistics corridors.
Real Estate Market Segmentation
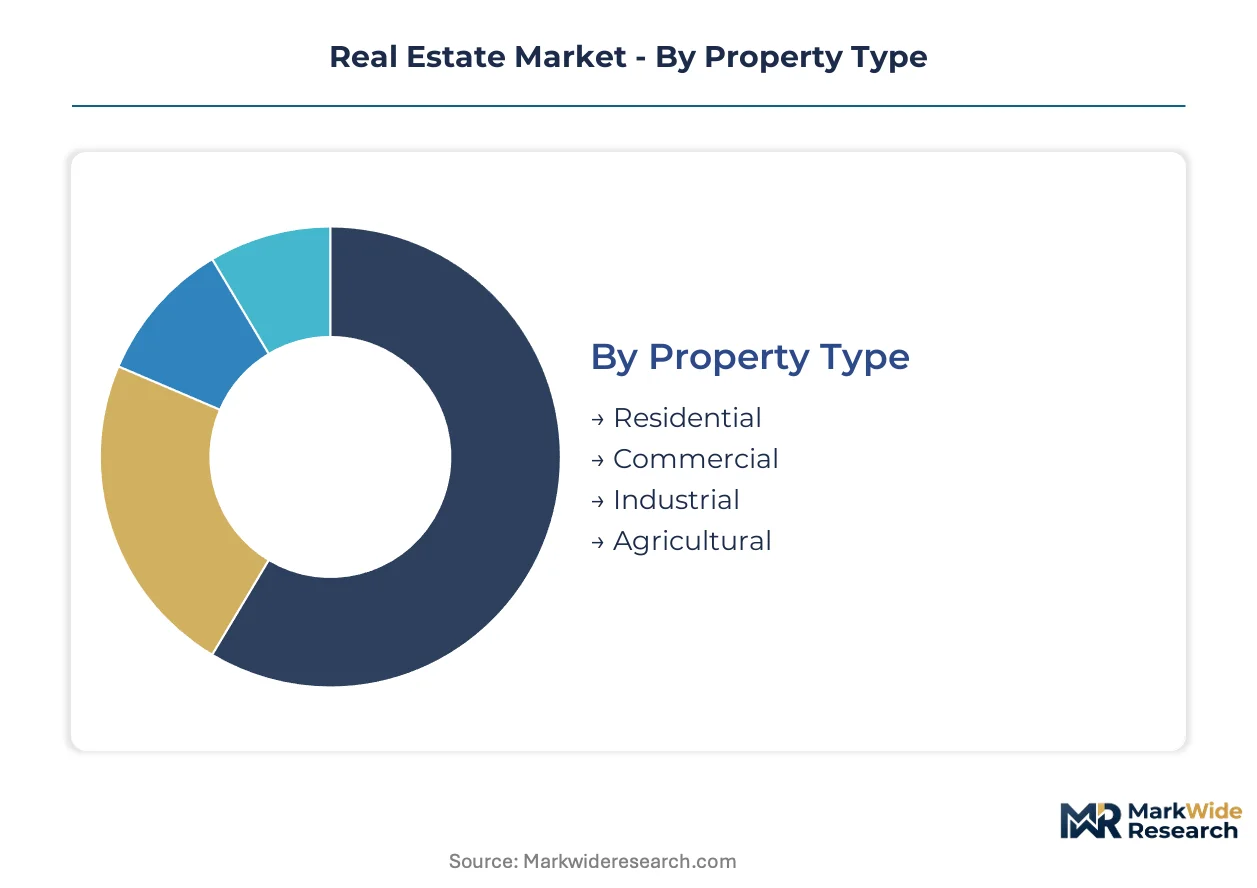
Real estate capital deployment discriminates sharply across property types and risk profiles. Segmentation reveals where institutional mandates concentrate versus where retail participation dominates, exposing divergent return expectations and liquidity characteristics.
Property Type:
Investor risk tolerance and yield requirements vary fundamentally by physical asset class and income stability.
- Residential:Multifamily and single-family rental assets generate inflation-linked lease escalations and demographic tailwinds from household formation. Sun Belt metropolitan areas absorb the deepest capital pools as population migration concentrates demand in Phoenix, Dallas, and Atlanta submarkets.
- Industrial:Logistics warehouses and last-mile fulfillment centers command premium valuations from e-commerce density requirements. Prologis and Blackstone compete for scarce land positions in supply-constrained infill locations where pre-leasing precedes construction.
- Commercial:Office and retail assets face structural repricing from remote work permanence and digital commerce displacement. Class B central business district properties carry lease rollover exposure requiring granular credit underwriting.
- Agricultural:Farmland and timberland provide inflation hedging and portfolio diversification for institutional endowments. Water rights and soil quality determine valuation premiums in water-stressed regions.
Volume sits with Residential; growth tilts toward Industrial.
Investment Strategy:
Return targets and holding periods segment capital pools across the risk spectrum from stabilized income to ground-up development.
- Core:Stabilized assets in gateway markets generate bond-like income streams with minimal value-add requirements. Pension funds and insurance mandates concentrate here for liability matching.
- Value-Add:Operational or physical improvements unlock rent premiums in undermanaged assets. Renovation pipelines target LEED certification to meet EU Green Deal building performance standards and SEC climate disclosure thresholds.
- Opportunistic:Distressed acquisitions and recapitalizations exploit dislocation events for outsized IRR targets. Floating-rate exposure and refinancing gaps create entry points during rate volatility.
- Development:Ground-up construction delivers the highest absolute returns in supply-constrained submarkets. Entitlement timelines of 24-36 months and construction cost volatility compress developer margins.
Capital commitments cluster in Core; absolute returns peak in Development.
Client Type:
Scale and regulatory sophistication determine access to off-market transactions and operational platform economics.
- Institutions:Sovereign wealth funds and pension systems deploy through separate accounts with direct asset control. Their mandates favor sponsors with proprietary pipelines over fund-of-fund structures.
- REITs:Publicly traded vehicles face SEC climate disclosure mandates requiring portfolio-level emissions accounting. Green building certification has become a capitalization rate differentiator.
- Fund Managers:Private equity real estate platforms aggregate institutional commitments into thematic strategies. Brookfield and Blackstone leverage scale for operational platform integration.
- Retail Investors:Crowdfunding platforms and non-traded REITs democratize access with lower minimums. Liquidity constraints and fee structures compress net returns versus institutional vehicles.
Transaction volume concentrates with Institutions; platform innovation favors Fund Managers.
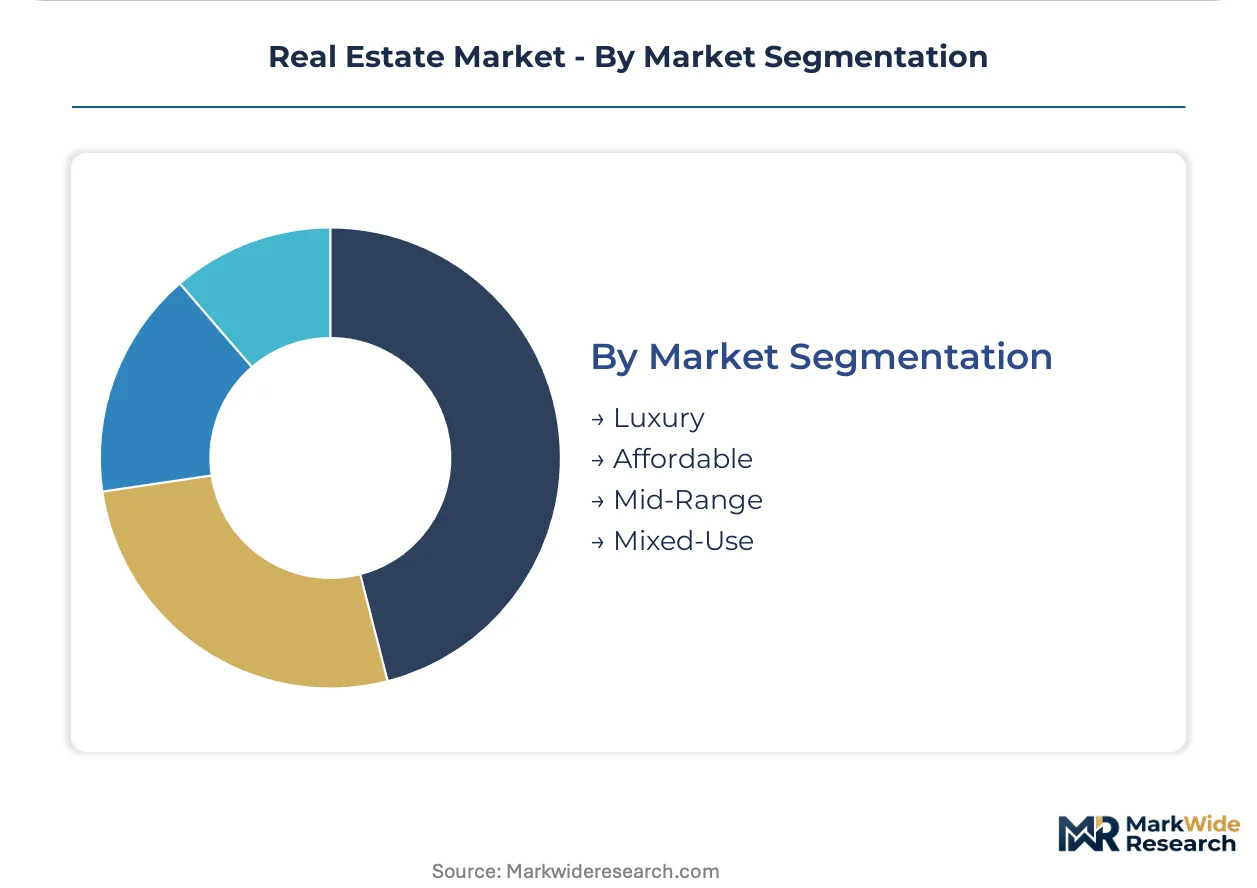
Market Segmentation:
Price point positioning reflects land scarcity, construction costs, and demographic purchasing power.
- Luxury:Trophy assets in gateway cities command scarcity premiums from ultra-high-net-worth capital preservation. New York, London, and Singapore ultra-prime residential trades as a store of wealth.
- Mid-Range:Workforce housing and Class A office in secondary markets balance yield with liquidity. This segment attracts the broadest institutional participation.
- Affordable:Subsidized and naturally occurring affordable housing faces financing complexity and regulatory oversight. Low Income Housing Tax Credits and HUD programs structure capital stacks.
- Mixed-Use:Integrated residential, retail, and office components create amenity premiums and diversified income streams. Zoning flexibility and transit proximity determine feasibility.
Development activity concentrates in Mid-Range; policy attention intensifies on Affordable.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones across the United States channel institutional capital into designated census tracts, accelerating logistics and data center development in Sun Belt metropolitan areas where population migration concentrates demand.
United States
Phoenix, Dallas, and Atlanta absorb the deepest capital pools from household formation and corporate relocations. The SEC mandates portfolio-level emissions accounting for public REITs, redirecting investment toward LEED-certified assets. Austin and Nashville submarkets face compressed industrial vacancy from e-commerce fulfillment pre-leasing.
Germany
Logistics corridors in North Rhine-Westphalia and Baden-Württemberg attract institutional mandates seeking EU Green Deal compliance. The country's building performance standards force capital deployment into retrofit pipelines. Frankfurt and Hamburg data center clusters expand renewable-powered capacity under decade-ahead power purchase agreements.
United Kingdom
London's ultra-prime residential trades as wealth preservation for international capital while regional logistics hubs capture last-mile demand. The Financial Conduct Authority's climate disclosure rules pressure REITs toward certified green buildings. The Midlands and Yorkshire industrial markets absorb build-to-suit warehouse development.
Japan
Tokyo and Osaka multifamily assets generate inflation-linked income streams from demographic density. METI promotes building electrification through heat pump retrofits and on-site solar adoption. Nagoya's industrial corridor concentrates logistics development for automotive and electronics supply chains.
Australia
Sydney and Melbourne residential build-to-rent platforms aggregate scattered-site portfolios for operational scale. The country's prudential regulator scrutinizes climate risk exposure in commercial mortgage portfolios. Brisbane and Perth logistics markets benefit from mining and energy export infrastructure proximity.
Real Estate Market Key Industry Players
Branded specialists and contract developers split share differently across property types, with scale platforms commanding separate account mandates while regional operators capture entitlement-heavy ground-up projects. The market structure concentrates capital with sponsors possessing proprietary land banks and pre-leased development pipelines. Three archetypes dominate: global allocators deploying through integrated platforms, sector specialists in logistics or data center verticals, and diversified REITs managing stabilized income portfolios. Competitive intensity manifests through operational platform acquisitions and renewable-powered asset development.
Among North American scale players, Blackstone and Prologis occupy positions at the capital deployment and logistics development vectors respectively, while Brookfield Asset Management anchors the infrastructure-integrated data center archetype. These firms exemplify how institutional procurement now discriminates based on digital infrastructure readiness and integrated property management capabilities. Their market presence reflects the broader rotation toward operational platforms with captive development pipelines over fund-of-fund structures.
| Leading Market Players |
|---|
| Blackstone |
| Brookfield Asset Management |
| Blue Owl Capital |
| Prologis |
| Welltower |
| Equinix |
| Simon Property Group |
| Carlyle Group |
| TPG |
| Others |
Cost & Logistics Intelligence
Steel and concrete input costs cascade through development pro formas to stratify pricing across premium LEED-certified assets, standard Class A properties, and economy-tier secondary market buildings. Fixed-price construction contracts now embed material escalation clauses that compress developer margins and force selective project shelving.
Pricing Analysis
Short lead-time premiums for build-to-suit industrial warehouses command 15-20% rent escalations over speculative inventory in Sun Belt submarkets. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and power infrastructure readiness. Pricing pressure stems from floating-rate construction debt exposure and cap rate expansion compressing levered equity returns. Institutional separate account mandates show lowest price sensitivity; retail crowdfunding platforms face net return compression from fee stacking.
Supply Chain Analysis
Reverse-logistics flows for building material recovery and modular component refurbishment are emerging in European retrofit pipelines under EU Green Deal demolition waste directives. Manufacturing concentration for HVAC equipment and electrical panels centers on Germany, China, and the United States. Critical dependencies include copper wiring, structural steel, and low-carbon cement formulations. Single-source vulnerability from Chinese solar panel and battery storage supply creates tariff exposure. Distribution runs through regional building material distributors and direct OEM relationships for large-scale developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Entitlement bottlenecks and skilled labor scarcity prop pricing power for sponsors with pre-approved land positions and captive construction capacity. Supply constraints favor asset holders over speculative developers.
For Market Incumbents: Cement market position through proprietary land bank expansion in Phoenix, Dallas, and Atlanta submarkets where pre-leasing precedes ground-breaking. Prioritize LEED Platinum certification investment to capture institutional capital rotation toward SEC climate disclosure compliance. Defensive consolidation of regional entitlement specialists accelerates pipeline velocity against municipal approval timeline risk. For New Entrants and Emerging Players: Begin with edge data center deployment in secondary markets bypassing hyperscale campus saturation. Target sub-5MW facilities in Nashville, Austin, and Raleigh-Durham where 5G densification creates latency-sensitive demand. Go-to-market through power purchase agreement partnerships with renewable developers to differentiate on carbon profile. For Investors and Strategic Acquirers: Distressed-cycle entries favor Class B office repositioning specialists in German and French portfolios facing compressed EU Green Deal compliance timelines. Long-term viability rests on retrofit execution capability and tenant credit underwriting discipline. Watch lease rollover schedules in central business district assets as inflection indicator for refinancing risk concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Land Bank Expansion | Pre-approved positions in Sun Belt metros compress entitlement timelines and capture e-commerce fulfillment density. |
| Renewable-Powered Development | Power purchase agreements with solar and wind developers secure institutional mandates requiring verified emissions profiles. |
| Operational Platform Acquisition | Integrated property management capabilities concentrate separate account capital away from fund-of-fund structures. |
| Brownfield Adaptive Reuse | EPA remediation standard compliance unlocks former industrial sites for logistics conversion with environmental liability insurance. |
| Build-to-Rent Pipeline Aggregation | Scattered-site single-family rental portfolios achieve operational scale through centralized PropTech oversight platforms. |
Research Approach
Independent corroboration across asset manager portfolio disclosures, municipal entitlement records, and REIT SEC filings underwrites the qualitative findings. Primary interviews with development executives, sustainability officers at pension mandates, municipal planning directors, and industrial tenant brokers combined with secondary validation from FERC siting records, EPA brownfield databases, and EU ESG disclosure registries. Bottom-up project pipeline aggregation and top-down institutional capital flow analysis triangulate market sizing.
Comparable-period anchoring to pre-pandemic development velocity and post-2022 interest rate regime shift frames the projection horizon. Segmentation modeling spans property type, investment strategy risk tier, client type sophistication, and geographic regulatory cluster. CAGRs derive from supply-constrained submarket rent growth trajectories and capital deployment velocity indices. Forecast inputs include entitlement timeline distributions and construction cost volatility bands.
Underlying measurement precision varies by segment; institutional capital flow data carries tighter precision than retail crowdfunding participation estimates. Forecasts reflect assumptions around interest rate trajectory stabilization and EU Green Deal enforcement consistency. Material deviation in refinancing gap severity or carbon accounting mandate acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
Residential Real Estate Market
Residential Real Estate Market
Saudi Arabia Residential Real Estate Market
Residential Real Estate Market
India Manufactured Homes Market
Residential Real Estate Market
France Luxury Residential Real Estate Market
Residential Real Estate Market
Singapore Real Estate Market
Residential Real Estate Market
Egypt Manufactured Homes Market
Residential Real Estate Market
Turkey Residential Real Estate Market
Residential Real Estate Market
United States Real Estate Brokerage Market
Residential Real Estate Market
ASEAN Manufactured Homes Market
Residential Real Estate Market
Spain Residential Real Estate Market
Residential Real Estate Market
Myanmar Residential Real Estate Market
Residential Real Estate Market
E House Market
Residential Real Estate Market
Online Home Rental Market
Residential Real Estate Market
Vietnam Residential Real Estate Market
Residential Real Estate Market
Malaysia Residential Real Estate Market
Residential Real Estate Market
Global Log Cabins or Log Homes Market