
 Ecuador Solar Energy Market | 2026-2036
Ecuador Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Ecuador Solar Energy Market Foresight
Utility-scale buyer concentration is hardening in Ecuador's solar sector, with mining conglomerates and banana-exporting agro-industrial groups emerging as dominant offtakers for captive power purchase agreements. Acciona SA leverages its international EPC track record to anchor large-scale project development in the Andean corridor. CELEC EP sustains its position as the state-owned grid operator and principal procurer of renewable capacity through competitive auctions. Enel Green Power competes aggressively by extending its regional operational platform into Ecuador's emerging solar park pipeline.
Ecuador solar energy encompasses photovoltaic systems that convert solar irradiation into electricity through semiconductor junctions, typically employing crystalline silicon modules rated between 400–700 Wp for utility installations and serving to displace fossil-fired generation in a hydro-dependent power matrix. Crystalline silicon technology dominates installed capacity due to proven bankability and local supply chain familiarity, while bifacial modules are gaining traction among commercial developers seeking higher energy yield per hectare in the high-irradiation coastal zone. Off-grid systems represent the fastest-growing application segment, driven by rural electrification mandates and the technical inability of isolated Andean communities to connect to the national SNI grid.
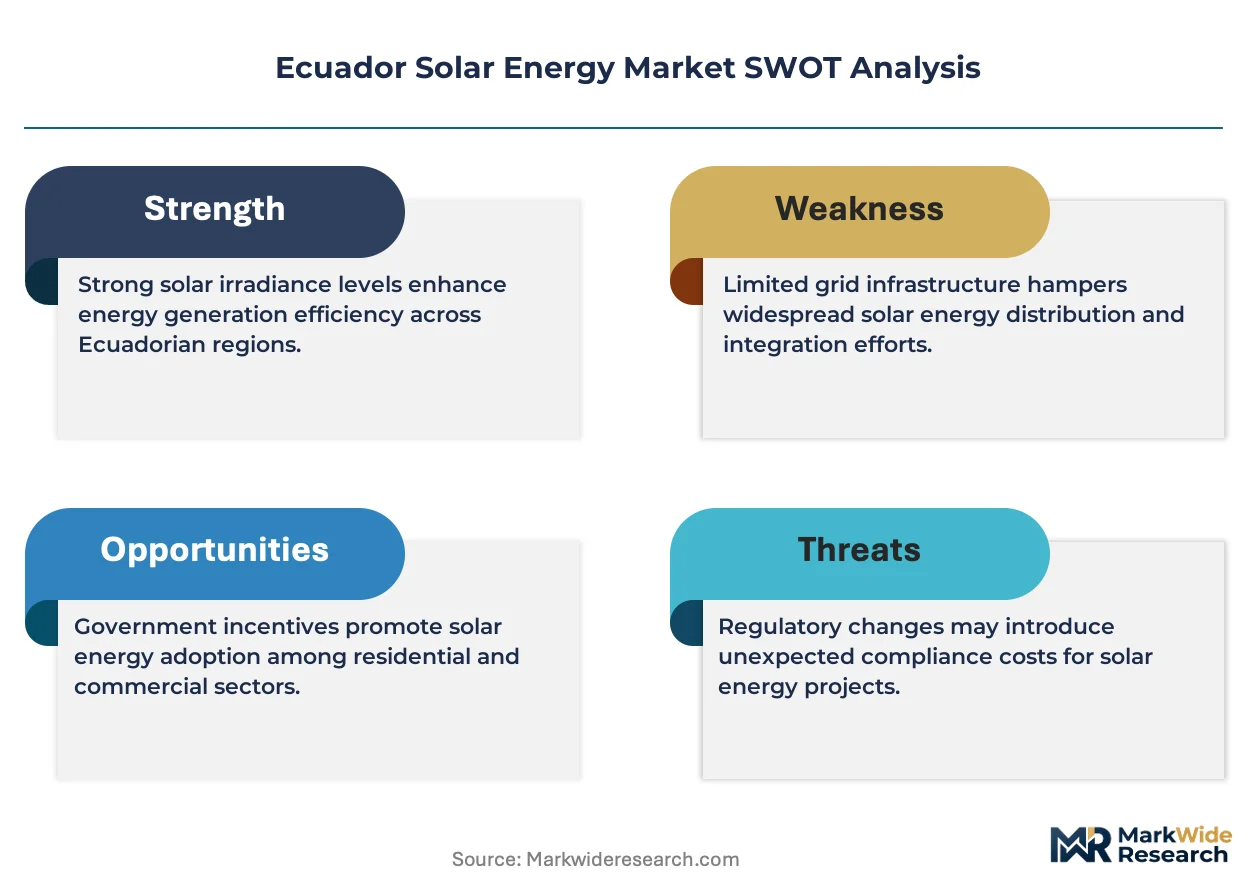
Ecuador's Ministry of Electricity and Renewable Energy governs solar deployment through the Organic Law of the Electric Sector and net metering resolutions that standardize interconnection protocols for distributed generators up to 1 MW. The national regulator ARCONEL enforces technical norms for grid-code compliance, while the Environmental Ministry issues non-replicable water and land use permits that constrain project siting in protected cloud forest zones. Stakeholders must monitor whether forthcoming renewable energy auction designs preserve bankable offtake terms or revert to regulated tariff exposure that would strand merchant solar assets.
Market Dynamics
Ecuador's solar sector pivots on the tension between hydro-dependent grid stability and the Ministry of Electricity and Renewable Energy's mandate to diversify generation sources through distributed generation frameworks and net metering protocols.
Growth Catalysts
- Net Metering Resolution:The Ministry of Electricity and Renewable Energy's interconnection standardization for systems up to 1 MW unlocks commercial and industrial rooftop deployment across Guayas and Manabí provinces.
- Mining Sector Electrification:Copper and gold extraction operations in the Andean corridor pursue captive solar arrays to offset diesel-fired generation and secure power cost predictability.
- Bifacial Module Adoption:Coastal developers deploy double-sided photovoltaic panels to capture reflected irradiation from ground surfaces, boosting yield per hectare in high-albedo banana plantation zones.
Market Restraints
- Grid Integration Bottlenecks:CELEC EP's transmission infrastructure in isolated Andean provinces lacks capacity to absorb utility-scale solar injections without reinforcement investments.
- Land Use Permit Complexity:The Environmental Ministry's non-replicable water and land use authorizations constrain project siting in protected cloud forest ecosystems, extending development timelines.
- Import Dependency:Crystalline silicon modules and inverters arrive predominantly through Colombian and Peruvian logistics corridors, exposing developers to regional supply chain disruptions and currency fluctuation risks.
Strategic Opportunities
- Off-Grid Rural Electrification:Isolated communities beyond the SNI grid perimeter represent untapped demand for decentralized solar-battery microgrids under rural electrification mandates.
- Agro-Industrial Thermal Hybridization:Banana dehydration and cocoa processing facilities integrate photovoltaic steam generation to displace biomass and fossil thermal inputs.
- Auction Design Evolution:Stakeholders anticipate forthcoming renewable energy auctions with bankable offtake terms that reduce merchant price exposure for utility-scale assets.
Industry Challenges
- Specialized EPC Talent Scarcity:Utility-scale project execution demands experienced photovoltaic construction managers and grid-code compliance engineers that Ecuador's labor market currently undersupplies.
- ARCONEL Certification Timelines:Grid-code compliance verification and interconnection approvals from the national regulator extend project commissioning schedules, compressing developer returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ecuador Solar Energy Market |
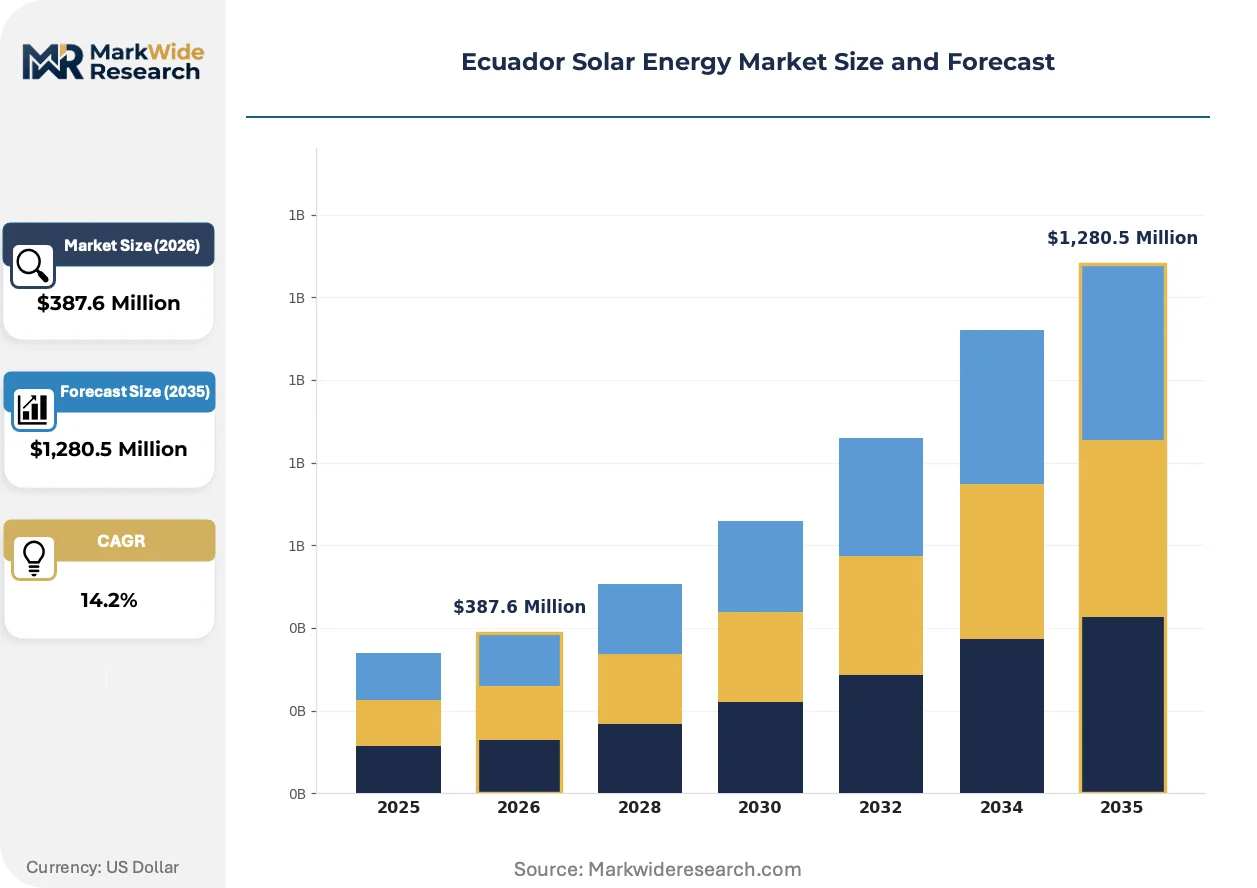
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Panels, Inverters, Batteries, Mounting Structures Application: Residential, Commercial, Industrial, Off-grid Systems Technology: Thin-Film, Crystalline Silicon, Bifacial, Concentrated Solar Power End User: Households, Businesses, Government Agencies, NGOs |
| Companies Covered | Acciona SA, CELEC EP, Renovaenergia SA, Enel Green Power, Zelestra, Solergy Ecuador C.ltda., Arausol Gmbh, GoSolar Ecuador, Enercity SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ecuador Solar Energy Market Shifts & Advancements
Technology convergence and regulatory recalibration are compressing project development cycles while reshaping how offtakers structure power purchase agreements in Ecuador's emerging solar park pipeline.
Bifacial photovoltaic technology is integrating tracker systems to optimize angular exposure throughout daylight hours. Commercial developers in Manabí province deploy these configurations to maximize energy yield per hectare on agro-industrial land leases. The technology is integrating land-use efficiency gains that reduce levelized cost thresholds for competing against subsidized hydroelectric tariffs.
Ecuador's Ministry of Electricity and Renewable Energy continues refining distributed generation regulations under the Organic Law of the Electric Sector. The framework's interconnection standardization reduces technical study requirements for commercial rooftop systems below 500 kW. Commercial banking subsidiaries now structure project finance around these streamlined approval timelines, accelerating capital deployment to qualified developers.
Mining conglomerates and agro-exporting groups are consolidating procurement authority through centralized energy management functions. Captive power purchase agreements now span 15-20 year tenors with inflation-linked escalation clauses, displacing shorter-term renewable energy certificate transactions. This concentration is most visible in the Andean corridor, where copper extraction operations negotiate directly with EPC firms for dedicated solar park development.
Ecuador Solar Energy Market Segmentation
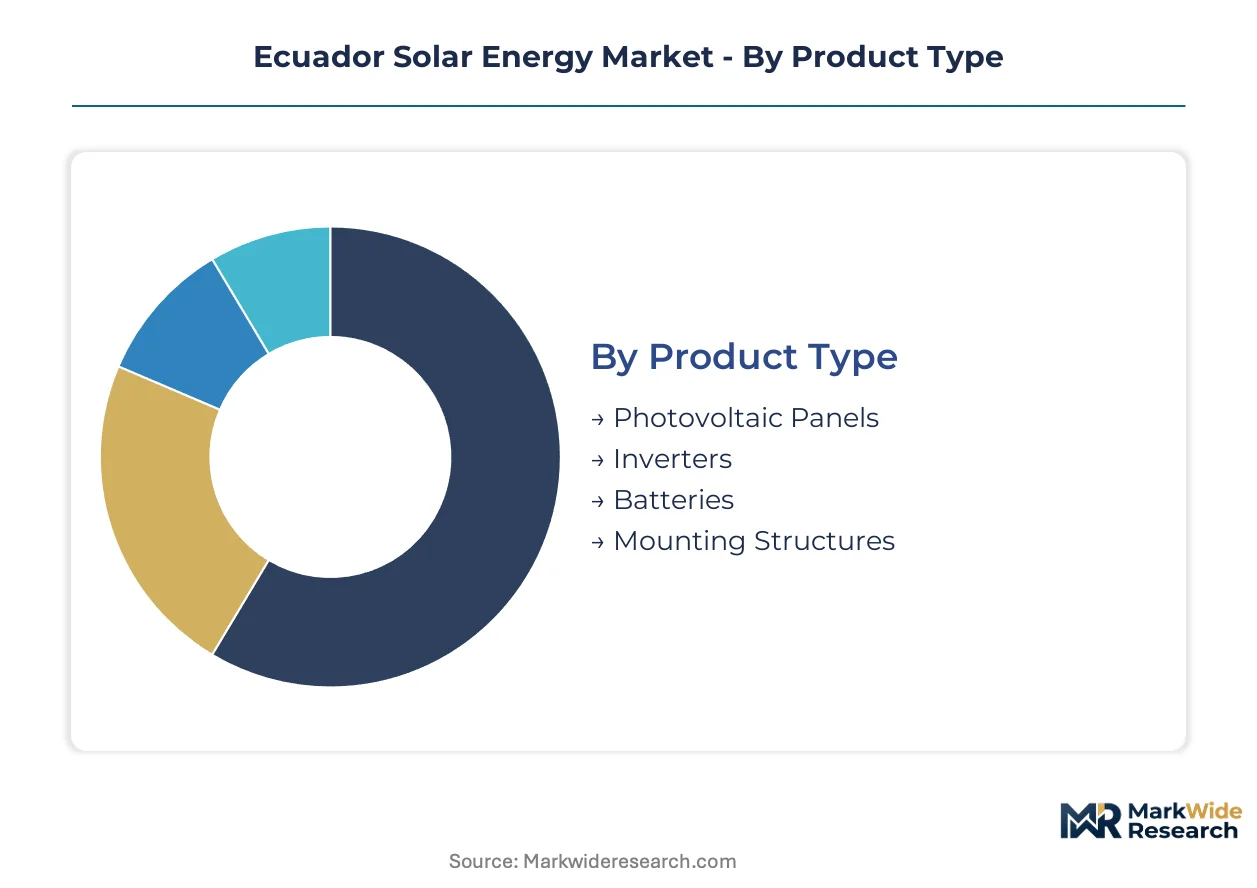
Segmentation reveals how Ecuador's solar market fragments across hardware procurement, deployment contexts, and customer economics. Understanding these divisions exposes where capital concentrates and which technology pathways offer viable returns against subsidized hydroelectric benchmarks.
Product Type:
Supply concentration in crystalline silicon modules shapes procurement patterns across Ecuador's coastal and Andean project corridors.
- Photovoltaic Panels:Crystalline silicon modules rated between 400–700 Wp dominate utility-scale installations due to proven bankability and local supply chain familiarity. Mining operations in the Andean corridor specify these panels for captive power arrays displacing diesel generation.
- Inverters:String and central inverters convert DC photovoltaic output to grid-compliant AC power. Commercial developers in Guayas province prioritize transformerless designs with integrated arc-fault protection to satisfy ARCONEL grid-code requirements.
- Batteries:Lithium-ion storage systems buffer intermittency for off-grid microgrids and net-metered commercial installations. Isolated communities beyond the SNI grid perimeter specify these for solar-battery hybrid systems under rural electrification mandates.
- Mounting Structures:Fixed-tilt and single-axis tracker systems anchor modules to ground or rooftop surfaces. Coastal banana plantation zones deploy elevated structures permitting continued agricultural activity beneath panel arrays.
Photovoltaic panels absorb the bulk of installed capacity; batteries are expanding most quickly as off-grid electrification accelerates.
Application:
Cost tier differentiation separates bankable utility-scale projects from distributed generation plays competing against subsidized residential tariffs.
- Residential:Rooftop systems below 50 kW serve urban households in Guayaquil and Quito. Net metering protocols standardize interconnection for these installations, though payback periods struggle against subsidized grid electricity rates.
- Commercial:Mid-scale rooftop and ground-mounted systems between 50 kW and 1 MW target industrial parks and retail facilities. Manabí province agro-processors deploy these configurations to offset thermal processing loads.
- Industrial:Captive solar parks above 1 MW supply mining extraction and refining operations. Copper and gold producers in the Andean corridor negotiate directly with EPC firms for dedicated generation assets.
- Off-grid Systems:Standalone solar-battery microgrids electrify isolated communities lacking SNI grid access. These installations represent the steepest expansion trajectory as government mandates prioritize rural connectivity.
Industrial applications command the highest project values per installation; off-grid systems are climbing the fastest on policy mandate tailwinds.
Technology:
Volume deployment favors mature crystalline platforms while bifacial configurations gain share in land-constrained coastal zones.
- Crystalline Silicon:Monocrystalline and polycrystalline cell technologies deliver proven efficiency and degradation profiles. The technology anchors virtually all bankable project finance in Ecuador's emerging solar park pipeline.
- Bifacial:Double-sided modules capture reflected irradiation from high-albedo ground surfaces. Developers in Manabí banana plantation zones specify these to maximize yield per hectare on agricultural land leases.
- Thin-Film:Cadmium-telluride and amorphous silicon alternatives offer lower efficiency but improved temperature coefficients. Niche applications include building-integrated photovoltaic installations in Guayaquil's commercial construction sector.
- Concentrated Solar Power:Parabolic trough and tower systems with thermal storage remain commercially absent. Ecuador's solar resource profile and project scale economics have prevented deployment of this capital-intensive technology class.
Crystalline silicon dominates current procurement volumes; bifacial configurations are gaining share fastest among coastal commercial developers.
End User:
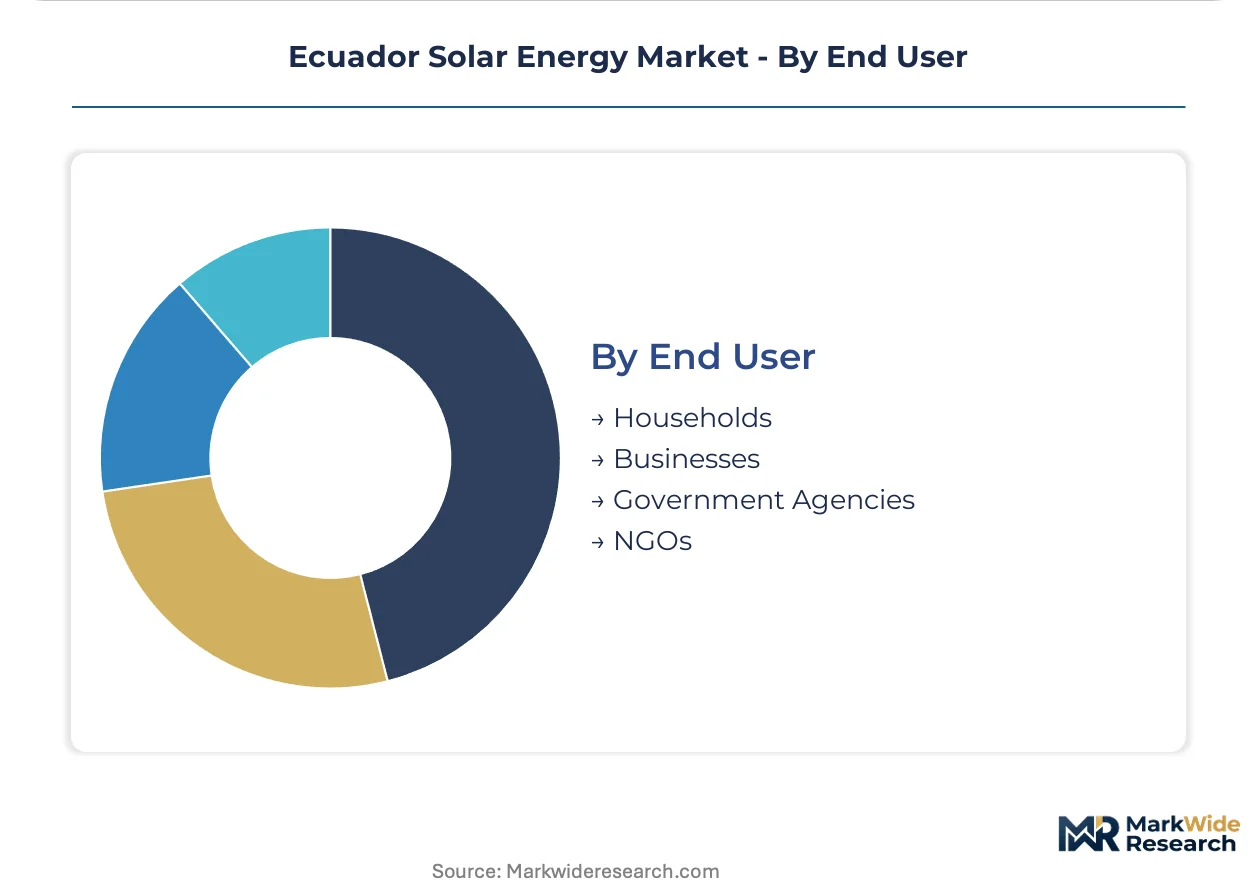
Customer type determines offtake structure, with mining conglomerates and agro-industrial groups consolidating procurement authority through centralized energy management functions.
- Businesses:Mining conglomerates and banana-exporting agro-industrial groups negotiate captive power purchase agreements spanning 15-20 year tenors. These offtakers drive utility-scale project development in the Andean corridor and coastal provinces.
- Government Agencies:CELEC EP procures renewable capacity through competitive auctions as the state-owned grid operator. Ministry of Electricity and Renewable Energy mandates shape distributed generation frameworks for public facility electrification.
- Households:Urban residential consumers in Guayaquil and Quito deploy rooftop systems primarily for backup power resilience. Net metering participation remains constrained by subsidized grid tariff economics.
- NGOs:International development organizations finance off-grid rural electrification projects in isolated Andean communities. These stakeholders specify solar-battery microgrids under technical cooperation agreements with Ecuador's rural electrification programs.
Businesses absorb the bulk of utility-scale capacity additions; NGOs are expanding most quickly as rural electrification mandates accelerate funding deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility-scale solar procurement concentrates in Ecuador's coastal provinces and Andean mining corridors, where irradiation levels and offtaker demand align. Provincial regulatory frameworks and grid infrastructure shape deployment patterns across distinct sub-regional markets.
Guayas Province
Guayas anchors Ecuador's commercial solar deployment through Guayaquil's industrial zones and port logistics infrastructure. The Ministry of Electricity and Renewable Energy's net metering protocols standardize interconnection for rooftop systems below 500 kW in this province. Banana-exporting agro-industrial groups in the Daule and Milagro cantons negotiate captive power purchase agreements with EPC developers.
Manabí Province
Manabí's high-albedo coastal plains attract bifacial module deployments for agro-industrial land lease arrangements. ARCONEL enforces grid-code compliance for commercial installations connecting through CELEC EP's transmission infrastructure in Portoviejo and Manta. Cocoa processors and dehydration facilities in the Chone River valley integrate photovoltaic steam generation to displace biomass thermal inputs.
Pichincha Province
Pichincha's Quito metropolitan zone hosts distributed generation deployment constrained by subsidized residential tariff economics. The Environmental Ministry's land use permitting framework governs project siting in the surrounding Andean páramo ecosystems. Commercial banking subsidiaries structure project finance around streamlined approval timelines for qualified developers in the capital corridor.
Azuay Province
Azuay's isolated Andean communities drive off-grid solar-battery microgrid demand beyond the SNI grid perimeter. Rural electrification mandates prioritize technical cooperation agreements for solar deployment in Cuenca's surrounding cantons. NGOs finance decentralized systems where transmission infrastructure lacks capacity to absorb utility-scale injections.
El Oro Province
El Oro's mining extraction operations in the Andean corridor pursue captive solar arrays to offset diesel-fired generation costs. Copper and gold producers negotiate directly with international EPC firms for dedicated generation assets in the Zaruma-Portovelo mining district. CELEC EP's transmission reinforcement investments remain pending for utility-scale solar absorption in this zone.
Ecuador Solar Energy Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue distributed generation and off-grid microgrid specialization. The vendor base stratifies across international EPC firms with Andean project experience, state-owned grid operators managing procurement auctions, and regional commercial developers targeting net-metered commercial installations. Three archetypes dominate: vertically integrated renewable energy conglomerates extending regional operational platforms; state-owned enterprises controlling transmission infrastructure and auction mechanisms; and specialized EPC contractors leveraging international track records for mining sector captive power development. Competitive dynamics center on auction participation rights and long-term offtake agreement tenors.
Within the international EPC tier, Acciona SA and Enel Green Power represent archetypes of renewable energy conglomerates extending regional operational platforms into Ecuador's emerging solar park pipeline. CELEC EP anchors the state-owned tier as grid operator and principal auction procurer. Among specialized regional developers, Solergy Ecuador C.ltda. occupies a position exemplifying commercial rooftop and distributed generation specialists targeting the Guayas-Manabí coastal corridor.
| Leading Market Players |
|---|
| Acciona SA |
| CELEC EP |
| Renovaenergia SA |
| Enel Green Power |
| Zelestra |
| Solergy Ecuador C.ltda. |
| Arausol Gmbh |
| GoSolar Ecuador |
| Enercity SA |
| Others |
Supply & Pricing Matrix
Captive integration into crystalline silicon module sourcing anchors both supply security and pricing power for Ecuador's utility-scale developers navigating import-dependent procurement corridors. This backward integration choice determines whether mining and agro-industrial offtakers secure fixed-cost predictability or remain exposed to regional logistics disruptions and currency fluctuation risks.
Pricing Analysis
Volume procurement concentrates among mining conglomerates and banana-exporting agro-industrial groups, while margin compression runs through distributed generation rooftop installers competing against subsidized hydroelectric tariffs. Project-based long-term offtake contracts spanning 15-20 year tenors dominate utility-scale deployment, with price differentiation hinging on ARCONEL certification tier and EPC track record. Cost compression in the commercial segment intensifies as local developers undercut international firms on installation labor. Mining operations exhibit lowest price sensitivity due to diesel displacement economics; residential households in Guayaquil and Quito remain most constrained by subsidized grid electricity benchmarks.
Supply Chain Analysis
Regional distribution centers in Guayaquil and Manta function as hub-and-spoke consolidation points for crystalline silicon modules and string inverters arriving through Colombian and Peruvian logistics corridors. China, Vietnam, and Malaysia anchor manufacturing concentration for photovoltaic cells and mounting structures. Polysilicon feedstock, aluminum framing, and lithium-ion battery cells constitute critical input dependencies. Single-source vulnerability concentrates in inverter power electronics and tracking system controllers. Distribution runs through CELEC EP's transmission infrastructure for grid-connected assets, while off-grid microgrids bypass centralized dispatch entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ecuador's solar market functions as a cost-of-compliance story where ARCONEL grid-code certification and Environmental Ministry land use permits erect barrier-to-entry moats favoring established players with regulatory navigation capabilities.
For Market Incumbents: Anchor market position through backward integration into module warehousing in Guayaquil to buffer against Colombian logistics chokepoints. Consolidate EPC talent pools through technical training partnerships with regional engineering faculties to counter specialized construction manager scarcity. Prioritize long-term offtake renegotiation with mining sector clients before auction design revisions introduce regulated tariff exposure. For New Entrants and Emerging Players: Launch via solar-battery microgrid deployment in Azuay Province's isolated Andean communities where SNI grid extension remains economically unviable. Target off-grid rural electrification as the most penetrable application segment under Ministry of Electricity and Renewable Energy mandates. Pursue technical cooperation agreements with international development NGOs as the primary go-to-market channel. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by renewable energy conglomerates seeking Andean corridor platform extension. Long-term viability hinges on auction design evolution preserving bankable offtake terms rather than merchant price exposure. Monitor CELEC EP transmission reinforcement investment announcements as the critical inflection signal for utility-scale project bankability in El Oro Province.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Structuring | 15-20 year inflation-linked offtake contracts secure mining sector revenue predictability against diesel volatility. |
| ARCONEL Certification Investment | Grid-code compliance capability compresses interconnection timelines and differentiates EPC firms in competitive auctions. |
| Backward Integration into Module Warehousing | Guayaquil inventory positioning buffers developers against Colombian logistics corridor disruptions. |
| Agro-Industrial Land Lease Arrangements | Bifacial tracker deployment on banana plantations maximizes yield per hectare while preserving agricultural revenue streams. |
| Rural Electrification Technical Cooperation | NGO partnership access unlocks off-grid microgrid funding pools under Ministry-mandated connectivity programs. |
Research Methodology
Multi-period observation of installed capacity trajectories, auction participation patterns, and net metering uptake rates anchored the trend analysis, supplemented by interviews with utility planning officers at CELEC EP, IPP project developers active in Guayas and Manabí provinces, EPC contractors with Andean corridor experience, and procurement leads at mining extraction operations. Secondary validation drew from Ministry of Electricity and Renewable Energy regulatory filings, ARCONEL interconnection statistics, Environmental Ministry permit databases, and customs import records for photovoltaic equipment. Bottom-up project pipeline aggregation triangulated against top-down macroeconomic scenario modeling.
Segment-weighting approaches distributed value projections across crystalline silicon versus bifacial technology splits, utility-scale versus distributed generation scale tiers, and grid-connected versus off-grid application contexts. CAGRs were derived from regression analysis of historical deployment velocities against policy mandate timelines and offtaker procurement cycle patterns. Forecast inputs incorporated mining sector electrification roadmaps, rural electrification mandate funding allocations, and transmission infrastructure reinforcement schedules.
Regulatory auction design reversals, currency fluctuation spikes affecting import-dependent equipment costs, and CELEC EP transmission bottleneck persistence are the dominant revision risks that could alter trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Crimp Set Market
Solar Power Systems
Rooftop Solar Photovoltaic (PV) Installation Market
Solar Power Systems
Thin Film Solar PV Market
Solar Power Systems
US Solar Market
Solar Power Systems
Brazil Solar Energy Market
Solar Power Systems
Global Micro Solar Inverter Market
Solar Power Systems
Germany Solar Energy Market
Solar Power Systems
Solar Ribbon Market
Solar Power Systems
Solar Charger Market
Solar Power Systems
Utility Solar PV EPC Market
Solar Power Systems
Solar Bug Zapper Market
Solar Power Systems
Global Solar PV Balance of System Market
Solar Power Systems
Solar Rooftop Sales Market
Solar Power Systems
Philippines Solar Energy Market
Solar Power Systems
Solar Energy Market
Solar Power Systems
Indonesia Renewable Energy Market