
 Global Transformerless UPS Market | 2026-2036
Global Transformerless UPS Market Size, Share, and Industry Trends Forecast 2026-2036
Global Transformerless UPS Market Foresight
Aftermarket service revenue is fragmenting across hardware-agnostic software platforms and predictive maintenance contracts. Eaton Corporation leverages its global service network to capture recurring revenue from efficiency optimization programs. Schneider Electric anchors its position through integrated power management software that extends hardware lifecycles. Mitsubishi Electric competes on high-efficiency inverter technology leadership in the Asia-Pacific installation base.
A transformerless uninterruptible power supply employs high-frequency switching and insulated-gate bipolar transistor arrays to deliver conditioned AC power without the weight, loss, and impedance of traditional iron-core transformers, achieving efficiency ratings above 96% at partial loads. Online UPS configurations dominate critical infrastructure deployments where zero transfer time remains non-negotiable, while modular UPS architectures represent the fastest-expanding product category as operators prioritize scalable capacity additions over upfront oversizing. Edge computing deployments are pulling demand toward compact line-interactive and modular systems designed for distributed rather than centralized power protection.
The U.S. Department of Energy efficiency standards, the EU Ecodesign Directive, and IEC 62040-3 performance classifications collectively shape product certification requirements and procurement criteria across major economies. China's GB energy efficiency labeling program adds a parallel compliance layer for manufacturers serving its domestic data center and industrial automation sectors. Stakeholders must monitor how evolving carbon disclosure rules and local grid stability mandates alter total-cost-of-ownership calculations against pure capital expenditure comparisons.
Market Dynamics
The EU Ecodesign Directive is compressing replacement cycles for legacy transformer-based UPS systems across industrial and data center installations, forcing facility operators to absorb upfront capital costs for efficiency compliance.
Growth Catalysts
- Hyperscale data center buildouts:Operators in the United States, Germany, and China are specifying transformerless architectures to meet density and thermal efficiency targets in new facilities.
- EU Ecodesign Directive:Efficiency mandates under this framework are prohibiting new transformer-based UPS sales above specified loss thresholds, redirecting procurement budgets toward high-frequency switching alternatives.
- Insulated-gate bipolar transistor arrays:Advances in IGBT semiconductor packaging are reducing switching losses and enabling compact three-phase configurations previously requiring iron-core isolation.
Market Restraints
- Semiconductor supply concentration:IGBT and silicon carbide wafer fabrication concentrates in East Asian foundry networks, exposing lead times to geopolitical friction.
- Copper and rare earth price volatility:Input costs for power conditioning components and permanent magnet materials fluctuate with commodity index movements, compressing margin visibility.
- Limited technician familiarity:High-frequency switching diagnostics require skill sets distinct from legacy transformer maintenance, constraining service network expansion.
Strategic Opportunities
- Edge computing distributed nodes:Compact line-interactive transformerless systems address power quality needs in remote manufacturing and retail locations outside centralized data center footprints.
- China GB energy efficiency labeling:Domestic certification requirements for data center infrastructure create preferential procurement channels for compliant manufacturers.
- Predictive maintenance software convergence:Integration of thermal monitoring and load forecasting algorithms opens recurring revenue streams beyond hardware shipment.
Industry Challenges
- IEC 62040-3 certification timelines:Third-party validation for online UPS performance classifications extends product launch schedules and ties up engineering resources.
- Legacy system interoperability:Transformerless units must synchronize with existing switchgear and generator sets designed for transformer impedance characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Transformerless UPS Market |
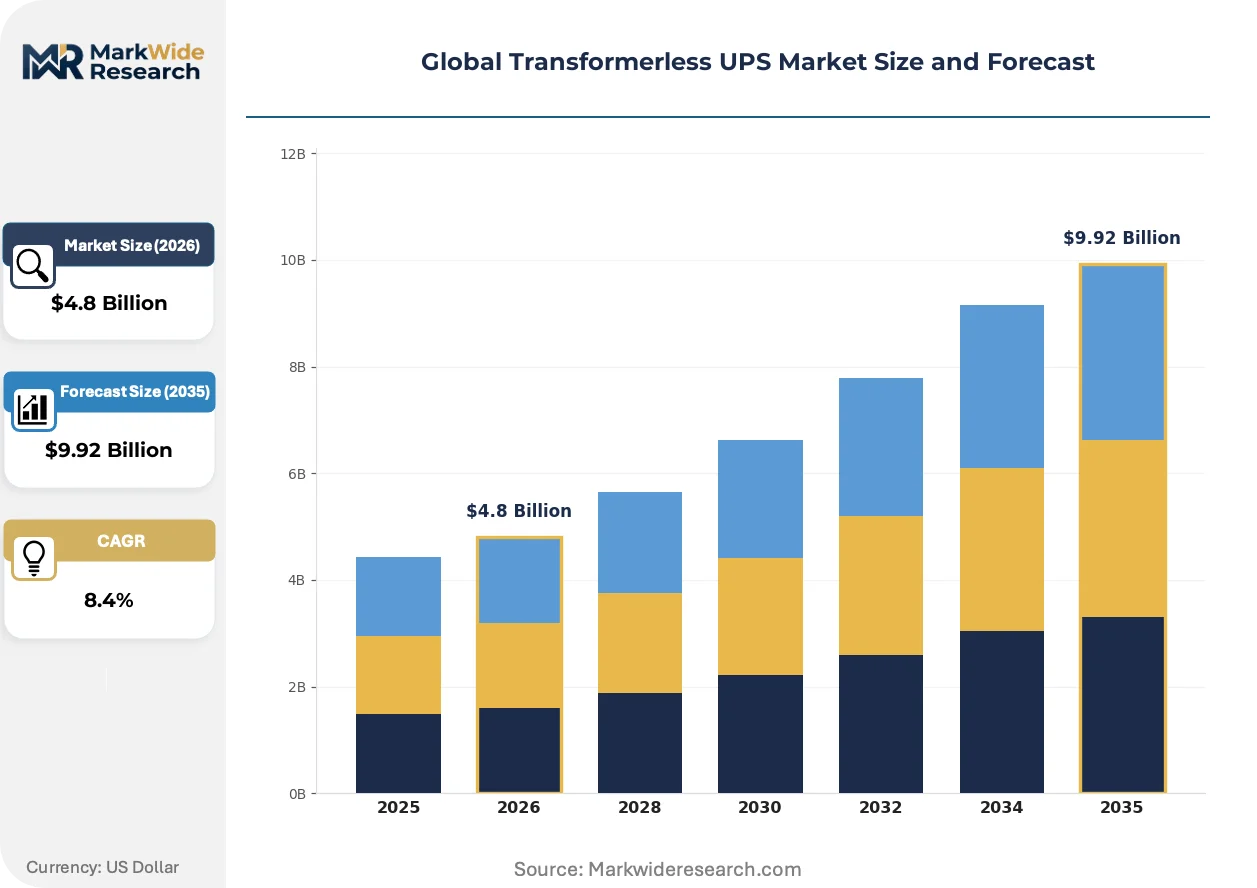
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.92 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Online UPS, Offline UPS, Line-Interactive UPS, Rotary UPS, Modular UPS Application: Data Centers, Telecommunication, Industrial Automation, Commercial Facilities, Critical Infrastructure End User: IT Enterprises, Banking Institutions, Government Agencies, Educational Institutes, Energy Sector Deployment: On-Premises, Cloud-Managed, Hybrid Systems, Edge Computing, Remote Sites |
| Companies Covered | Emerson Electric, Mitsubishi Electric, Eaton Corporation, Toshiba, Siemens, Schneider Electric, ABB, Socomec, Vertiv Group Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Transformerless UPS Market Shifts & Advancements
Digital twin architectures are penetrating power management software, compressing commissioning cycles and enabling remote optimization of transformerless UPS fleets without on-site engineering presence.
Wide-bandgap silicon carbide power semiconductors are replacing silicon IGBTs in high-frequency inverter stages, cutting switching losses and thermal management overhead. Data center operators in Northern Europe are specifying SiC-based units for heat recovery integration. This semiconductor transition is virtualizing the physical footprint of three-phase protection systems.
China's GB standards for energy efficiency labeling are tightening loss-factor thresholds for data center power equipment, forcing manufacturers to redesign magnetic components and control algorithms. Domestic facility operators must document compliance to secure grid connection permits. The industrial automation sector faces the steepest redesign burden under these rules.
Colocation buyers are unbundling hardware procurement from long-term service contracts, pressuring manufacturers to compete on capital cost while isolating maintenance revenue. This purchasing pattern is fragmenting vendor-customer relationships and compressing visibility into aftermarket lifetime value. Germany and the United States exhibit the most advanced unbundling behavior among enterprise segments.
Global Transformerless UPS Market Segmentation
Transformerless UPS architectures fragment across power conditioning topologies, facility types, and operational models. Each segment carries distinct replacement cadences, certification burdens, and margin structures that shape vendor portfolio prioritization.
Product Type:
Replacement cycles stretch from three years for edge-deployed units to fifteen years for hardened industrial configurations, compressing or extending revenue recognition windows accordingly.
- Online UPS:Double-conversion architectures deliver conditioned power through continuous AC-DC-AC transformation, eliminating transfer time entirely. Hyperscale data centers in Germany and the United States specify these for Tier III and Tier IV facilities where outage tolerance measures in milliseconds. The EU Ecodesign Directive's loss thresholds favor these high-efficiency designs over legacy alternatives.
- Modular UPS:Scalable frame architectures allow capacity additions in 50-250 kW increments without system shutdown. Colocation operators in China deploy these to match tenant growth curves rather than oversizing day-one infrastructure. Pay-as-you-grow economics reduce stranded capital.
- Offline UPS:Standby switching engages battery inversion only during grid anomalies, trading response speed for efficiency gains. Small commercial installations tolerate the 4-10 millisecond transfer gap.
- Line-Interactive UPS:Buck-boost voltage regulation with limited battery engagement addresses moderate power quality issues. Retail and light industrial sites favor these for cost-containment.
- Rotary UPS:Kinetic energy storage through flywheel mass delivers ride-through without chemical batteries. Heavy manufacturing tolerates brief outages through rotational inertia.
Online UPS anchors the volume base while Modular UPS gains share at the steepest rate.
Application:
Margin profiles diverge sharply between price-sensitive commercial facilities and specification-driven critical infrastructure where failure costs dwarf equipment outlays.
- Data Centers:Hyperscale and colocation facilities drive transformerless specification for density and thermal efficiency. Operators in the United States, Germany, and China represent the dominant procurement concentration.
- Industrial Automation:Process continuity requirements in continuous manufacturing favor online configurations with generator synchronization capability. China's industrial automation sector faces steep redesign burdens under GB energy efficiency labeling.
- Telecommunication:Network equipment shelters and central offices require compact, rack-mountable protection. Edge node proliferation pulls demand toward line-interactive and modular systems.
- Critical Infrastructure:Healthcare, transportation, and emergency services mandate IEC 62040-3 Class 1 performance with zero transfer time. Certification timelines extend product launch schedules.
- Commercial Facilities:Office buildings and retail chains prioritize capital cost over efficiency ratings, accepting offline or line-interactive trade-offs.
Data Centers command the highest average selling prices while Industrial Automation delivers the most predictable replacement pipelines.
End User:
Procurement sophistication varies from centralized IT governance in banking to fragmented purchasing across educational networks.
- IT Enterprises:Technology companies operate captive data centers with dedicated power engineering teams. These buyers unbundle hardware from service contracts most aggressively.
- Banking Institutions:Regulatory capital requirements and operational risk mandates drive premium specification. Transaction processing continuity justifies double-conversion investment.
- Government Agencies:Public procurement frameworks emphasize lifecycle cost over upfront capital. Compliance documentation burdens extend sales cycles.
- Educational Institutes:Distributed campus infrastructure and constrained capital budgets favor line-interactive and offline systems. Maintenance skill scarcity constrains high-frequency switching adoption.
- Energy Sector:Grid-connected generation and substation automation require ruggedized enclosures and wide temperature operation. Generator synchronization capability is non-negotiable.
IT Enterprises generate the largest transaction sizes while Government Agencies impose the longest sales cycles.
Deployment:
Physical versus virtualized management architectures reshape service revenue capture and customer intimacy models.
- On-Premises:Traditional facility-owned and operated systems dominate established industrial and enterprise footprints. Technician familiarity gaps constrain high-frequency switching service network expansion.
- Cloud-Managed:Remote monitoring platforms aggregate fleet visibility across distributed installations. Predictive maintenance algorithms open recurring revenue streams beyond hardware shipment.
- Edge Computing:Distributed nodes in manufacturing and retail locations outside centralized footprints demand compact, environmentally hardened systems. Northern European operators specify SiC-based units for heat recovery integration.
- Hybrid Systems:Mixed on-premises and cloud-managed architectures accommodate transition states and regulatory data sovereignty requirements.
- Remote Sites:Mining, oil and gas, and telecommunications towers require extended temperature ranges and minimal maintenance intervals. Limited technician access favors modular hot-swappable designs.
On-Premises retains the installed base majority while Cloud-Managed climbs fastest in new procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Germany prioritizes heat recovery integration and circular energy flows, while China drives volume through state-mandated data center buildouts. The United States balances hyperscale efficiency targets with fragmented edge deployment.
United States
Hyperscale operators in Northern Virginia and Dallas-Fort Worth specify transformerless architectures to meet density targets exceeding 50 kW per rack. The Department of Energy efficiency standards shape procurement criteria for federal data center consolidation. Silicon carbide-based units gain traction in Pacific Northwest facilities seeking heat recovery integration.
Germany
Frankfurt's banking and colocation clusters drive specification for IEC 62040-3 Class 1 performance with zero transfer time. The EU Ecodesign Directive prohibits new transformer-based UPS sales above specified loss thresholds. Bavarian industrial automation facilities absorb upfront capital costs for efficiency compliance under these mandates.
China
Beijing-Tianjin-Hebei and Yangtze River Delta data center construction accelerates transformerless deployment under dual carbon goals. GB energy efficiency labeling creates preferential procurement channels for compliant manufacturers. Shenzhen and Hangzhou facility operators must document compliance to secure grid connection permits.
Japan
Tokyo-Osaka corridor semiconductor fabrication facilities demand sub-millisecond power quality protection. METI efficiency guidelines pressure facility operators to replace legacy transformer-based systems. Yokohama industrial parks concentrate high-frequency switching adoption for precision manufacturing continuity.
India
Mumbai and Bengaluru data center operators expand transformerless deployments to meet tenant efficiency requirements. The Bureau of Indian Standards energy performance codes create compliance layers for domestic infrastructure. Tamil Nadu's industrial automation sector faces technician familiarity gaps constraining high-frequency switching service network expansion.
Global Transformerless UPS Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The vendor base stratifies across integrated power management conglomerates, high-frequency switching specialists, and regional electrical equipment fabricators. Three archetypes dominate: full-stack power infrastructure providers, semiconductor-anchored inverter technology leaders, and service-network-driven recurring revenue capturers. Competitive moves center on predictive maintenance software convergence and efficiency optimization program expansion.
Within the integrated infrastructure tier, Schneider Electric and Eaton Corporation exemplify full-stack positioning through power management software and global service network scale. Mitsubishi Electric occupies a specialist position anchored in high-frequency inverter technology leadership. Vertiv Group Corp represents the data center infrastructure pure-play archetype with hyperscale-focused engineering depth. These three anchors demonstrate how vendor strategies diverge across software integration, semiconductor packaging, and facility-specific application expertise.
| Leading Market Players |
|---|
| Emerson Electric |
| Mitsubishi Electric |
| Eaton Corporation |
| Toshiba |
| Siemens |
| Schneider Electric |
| ABB |
| Socomec |
| Vertiv Group Corp |
| Others |
Supply & Pricing Matrix
Semiconductor supply concentration in East Asian foundry networks determines both pricing tier spreads and supply chain shape across the transformerless UPS market. IGBT and silicon carbide wafer fabrication bottlenecks compress margin visibility for manufacturers while forcing buyers into long-term offtake commitments to secure allocation.
Pricing Analysis
Long-term offtake contracts dominate procurement for hyperscale data center operators, insulating them from spot market volatility in power semiconductor pricing. Three-tier pricing structure across premium, standard, and economy levels separates IEC 62040-3 Class 1 certified units from commercial-grade alternatives. Cost compression in the standard tier is intensifying because colocation buyers unbundle hardware from service contracts. Commercial facilities exhibit the highest price sensitivity, while banking institutions absorb premiums for zero-transfer-time performance.
Supply Chain Analysis
Silicon carbide substrate production draws from Japan, Germany, and the United States, while IGBT module packaging concentrates in China and South Korea. Raw material dependencies span high-purity silicon wafers, copper busbars, and rare earth permanent magnets. Single-source vulnerability in 200mm SiC wafer supply exposes lead times to geopolitical friction. Distribution runs through authorized electrical distributors and direct OEM channels to data center EPC contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The transformerless UPS market sits in an early-cycle expansion phase driven by EU Ecodesign Directive compliance deadlines forcing replacement of legacy transformer-based systems.
For Market Incumbents: Insulate service revenue streams by embedding predictive maintenance software into hardware sales before colocation buyers complete their unbundling transition. Deepen backward integration into IGBT and SiC semiconductor sourcing to offset East Asian foundry concentration risk. Prioritize certification investment in China's GB energy efficiency labeling program to capture preferential procurement channels. For New Entrants and Emerging Players: Pursue edge computing distributed nodes as the most penetrable white space, where compact line-interactive systems address power quality needs outside hyperscale footprints. Target India's industrial automation sector, where technician familiarity gaps constrain incumbent service network expansion. Lead with cloud-managed deployment models that open recurring revenue without requiring field engineering scale. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors semiconductor-anchored inverter technology specialists over pure-play hardware fabricators. Long-term viability hinges on software convergence and thermal monitoring algorithm development. Watch SiC penetration rates in Northern European heat recovery installations as the inflection indicator for next-generation technology adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Launch | Captures recurring revenue from Eaton Corporation and Schneider Electric service network models. |
| SiC Semiconductor Backward Integration | Reduces dependency on East Asian foundry networks for critical inverter components. |
| GB Energy Efficiency Certification | Unlocks preferential procurement channels in Beijing-Tianjin-Hebei data center construction. |
| Edge Computing Product Line Expansion | Addresses distributed node demand in manufacturing and retail outside centralized footprints. |
| Cloud-Managed Deployment Partnership | Aggregates fleet visibility across colocation tenant installations for algorithmic optimization. |
Research Methodology
Initial hypotheses were tested against primary input from data center power engineering directors, electrical contractor procurement leads, and semiconductor supply chain managers and refined through secondary validation. Primary fieldwork combined structured interviews with facility operators in Northern Virginia, Frankfurt, and Shanghai clusters. Secondary sources included IEC 62040-3 certification databases, EU Ecodesign Directive implementation reports, and hyperscaler capex disclosure filings. Bottom-up unit shipment estimates triangulated against top-down infrastructure investment forecasts.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation by product topology, facility type, and deployment architecture. CAGRs derived from replacement cycle analysis, efficiency mandate phase-in schedules, and data center construction pipeline tracking. Industry-specific inputs included IGBT pricing indices, SiC wafer capacity expansion announcements, and GB standards compliance documentation rates.
Macroeconomic conditions sit as an overlay; deviation in copper and rare earth commodity indices or East Asian logistics chokepoints would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement timelines and technology substitution elasticities. Cross-checking against DOE federal data center consolidation reports and EU member state transposition filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
North America Exhaust Heat Recovery System Market
Power Equipment
Global Power Supply Market
Power Equipment
Power Plant Lightning Protection Services Market
Power Equipment
Asia-Pacific Gas Turbine Market
Power Equipment
North America Power Plant Boiler Market
Power Equipment
Power Grid Primary and Secondary Fusion Equipment Market
Power Equipment
Power Engineering, Procurement, and Construction (EPC) Market
Power Equipment
North America SCR Power Controller Market
Power Equipment
Wind Tunnel Fans Market
Power Equipment
Power Cables Market
Power Equipment
Turbine Control Systems Market
Power Equipment
Industrial Gas Turbine Ignition System Market
Power Equipment
Process Air Heater Market
Power Equipment
Germany Power EPC Market
Power Equipment
Kazakhstan Power EPC Market
Power Equipment
China Power EPC Market