
 Nigeria Upstream Oil Sector Market | 2026-2036
Nigeria Upstream Oil Sector Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Upstream Oil Sector Market Insights
Natural gas is decoupling from crude-linked pricing in Nigerian upstream economics, creating independent revenue streams for field operators. Shell Petroleum Development Company leverages its integrated gas gathering infrastructure across the Niger Delta to capture this spread. Seplat Energy Plc anchors its portfolio on domestic gas supply obligations to power plants and industrial users. TotalEnergies EP Nigeria Ltd. competes through deepwater developments that yield higher-margin liquids with lower per-barrel lifting costs.
Nigeria upstream oil sector encompasses exploration, development, and production of crude oil and associated natural gas from onshore, shallow-water, and deepwater concessions, with typical crude gravities ranging from API 29 to 45 degrees depending on basin geology. The sector serves as the primary feedstock source for Nigeria's four refineries and generates over ninety percent of the country's foreign exchange earnings through export cargoes. Exploration and drilling services currently dominate capital deployment as operators target pre-salt and deeper horizons in the Dahomey Basin. Enhanced Oil Recovery technology is expanding fastest among production methods as mature onshore fields require pressure maintenance to sustain plateau rates. Offshore production, particularly deepwater developments, concentrates the largest margin pools due to premium crude grades and fiscal terms that favor capital-intensive projects.
The Department of Petroleum Resources enforces technical standards for well integrity and environmental management, while the Nigerian Upstream Petroleum Regulatory Commission administers licensing rounds and production quotas under the Petroleum Industry Act framework. These bodies shape market access through local content requirements that mandate minimum Nigerian participation in service contracts and engineering procurement. Operators must also satisfy the Environmental Impact Assessment Act administered by the Federal Ministry of Environment before field development approval. Stakeholders should monitor how the Commission's forthcoming marginal field bid rounds reallocate acreage to indigenous operators versus legacy international holders.
Market Dynamics
The Petroleum Industry Act is restructuring fiscal terms across Nigerian upstream acreage, shifting royalty frameworks and cost recovery ceilings that govern how international operators and indigenous firms allocate capital between onshore mature fields and deepwater greenfield developments.
Growth Catalysts
- Domestic Refining Expansion:The Dangote Refinery and rehabilitated state-owned plants are absorbing more Nigerian crude, reducing export dependency and stabilizing offtake agreements for field operators.
- Petroleum Industry Act Licensing:The Nigerian Upstream Petroleum Regulatory Commission's new bid rounds are reallocating marginal fields to indigenous operators with lower cost structures and faster development timelines.
- Gas Monetization Infrastructure:Escravos-Lagos Pipeline System expansions and Brass LNG project advances are creating dedicated revenue streams for associated gas that previously flared.
Market Restraints
- Capital Intensity Barriers:Deepwater developments in the Bonga and Egina fields require billion-dollar subsea infrastructure that only supermajors can finance, concentrating production among five operators.
- Security Infrastructure Costs:Niger Delta pipeline vandalism and crude theft force operators to deploy private maritime security and surveillance systems, adding twelve to eighteen percent to operating expenditure.
- Fiscal Term Uncertainty:Host community development levy calculations under the Petroleum Industry Act remain contested, delaying final investment decisions on frontier blocks.
Strategic Opportunities
- Pre-Salt Exploration:Dahomey Basin deep horizons below six thousand meters remain underexplored, with seismic surveys indicating recoverable volumes analogous to Brazilian analogs.
- Carbon Capture Integration:Natural gas processing facilities at Obiafu-Obrikom and Oben offer geological storage formations for CO2 streams, aligning with EU border carbon adjustment exposure on Nigerian LNG exports.
- Modular Refinery Feedstock:Twenty-three licensed modular refineries in Edo, Delta, and Rivers states need dedicated crude supply contracts, creating captive offtake for marginal field producers.
Industry Challenges
- Deepwater Drilling Expertise Gap:Nigerian content requirements mandate local participation in subsea engineering, but only three indigenous firms possess dual-gradient drilling capability certification.
- Legacy Joint Venture Arrears:Nigerian National Petroleum Corporation cash call defaults accumulated through 2023 continue to constrain partner funding for brownfield workovers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Upstream Oil Sector Market |
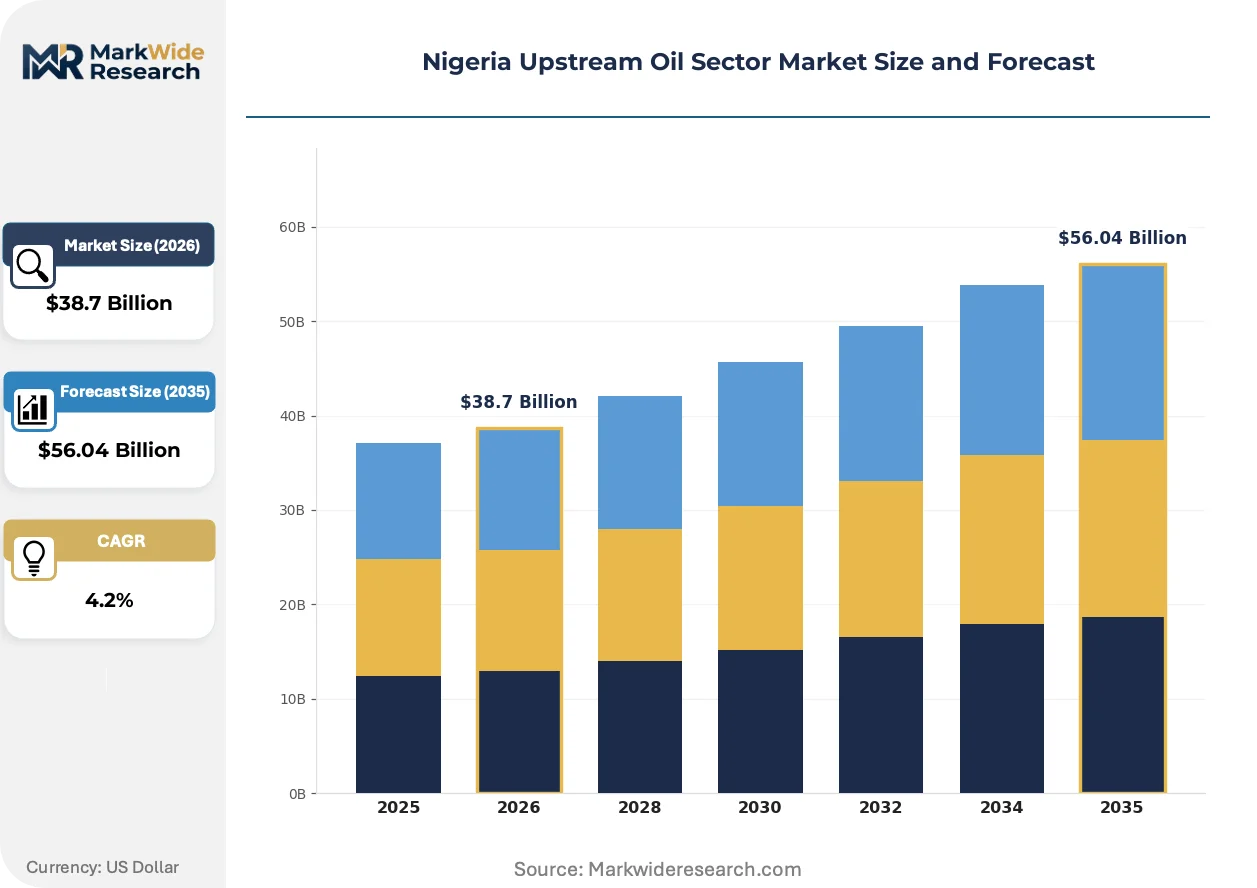
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $56.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Exploration, Drilling, Production, Facilities Management Technology: Seismic, Subsea, Enhanced Oil Recovery, Artificial Lift End User: Independent Operators, National Oil Companies, Multinational Corporations, Service Providers Production Method: Conventional, Unconventional, Offshore, Onshore |
| Companies Covered | NNPC Limited, Shell Petroleum Development Company, Chevron Nigeria Ltd., ExxonMobil Nigeria Unlimited, TotalEnergies EP Nigeria Ltd., Seplat Energy Plc, Aiteo Eastern E&P, Oando Energy Resources, Eni/NAOC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Upstream Oil Sector Market Trends and Innovations
Digital reservoir characterization and subsea electrification are compressing development timelines for Nigerian deepwater projects while the Petroleum Industry Act's local content mandates force technology transfer partnerships.
Subsea processing systems with multiphase pumps and wet gas compressors are overtaking conventional platform-based separation for Bonga Southwest and Zabazaba field developments. TotalEnergies and Shell are deploying these systems at water depths exceeding one thousand meters to eliminate surface infrastructure. This architecture is compressing capital schedules by eighteen months and reducing offshore personnel exposure.
The Nigerian Upstream Petroleum Regulatory Commission's new technical standards for well integrity and environmental management are mandating real-time monitoring systems for all drilling operations. Operators must now install blowout preventer control systems with satellite telemetry to Commission command centers. Deepwater rig contractors are absorbing compliance costs through day-rate adjustments, shifting margin pressure to exploration budgets.
Integrated service contracts are displacing discrete procurement for drilling, completions, and subsea installation. Nigerian independents with marginal field awards lack the technical staff to manage fragmented vendor relationships, driving bundled awards to Schlumberger and Halliburton affiliates. This consolidation is most visible in the Niger Delta onshore belt where Seplat and ND Western operate multiple contiguous blocks.
Nigeria Upstream Oil Sector Market Segmentation
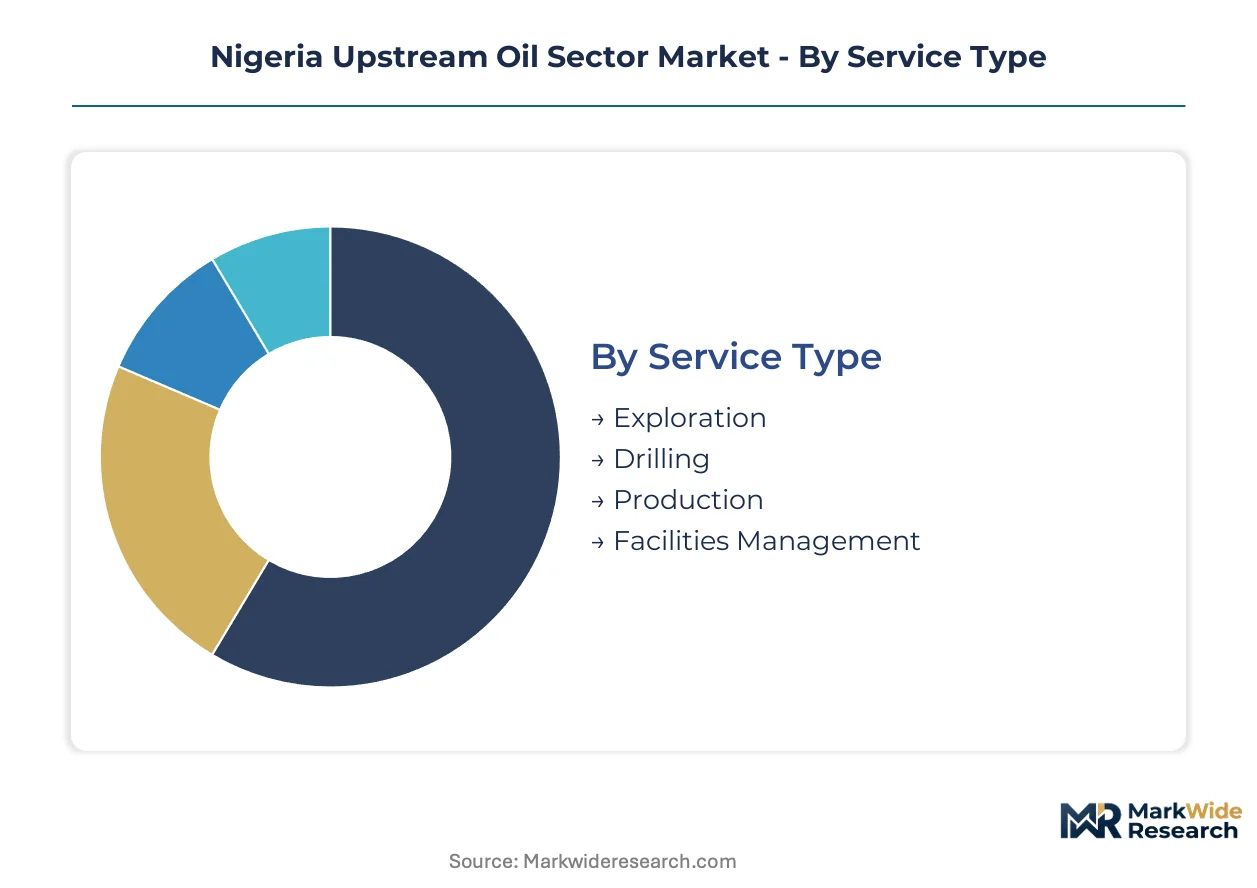
Upstream service segmentation in Nigeria tracks capital allocation across the exploration-to-production lifecycle, with each category reflecting distinct margin structures and local content compliance requirements. Technology and production method splits reveal where international operators concentrate spending versus where indigenous firms gain traction.
Service Type:
Exploration and drilling services command premium day rates given deepwater rig scarcity, while production and facilities management compete on operational efficiency metrics.
- Exploration:Seismic acquisition and geophysical interpretation services target pre-salt horizons in the Dahomey Basin. Nigerian independents concentrate demand here as marginal field awards accelerate frontier acreage evaluation.
- Drilling:Dual-gradient and managed pressure drilling systems handle overpressured formations below six thousand meters. Deepwater blocks off the Niger Delta coast absorb the bulk of rig contracting capacity from international operators.
- Production:Well intervention and workover services maintain plateau rates across mature onshore fields. Shell Petroleum Development Company and Seplat Energy Plc anchor demand through integrated production contracts.
- Facilities Management:Platform maintenance and subsea asset integrity services extend field life. Nigerian content requirements mandate local participation in engineering procurement, reshaping vendor selection criteria.
Mature deployment sits with Production. Newer deployment is concentrated in Exploration.
Technology:
Technology segmentation tracks where proprietary systems create vendor lock-in versus where standardized equipment enables competitive sourcing.
- Seismic:Wide-azimuth and ocean-bottom node surveys resolve complex salt geometries beneath the Niger Delta. TotalEnergies EP Nigeria Ltd. deploys these systems for Zabazaba field appraisal.
- Subsea:Multiphase pumps and wet gas compressors eliminate surface infrastructure at water depths exceeding one thousand meters. Subsea processing represents the steepest expansion trajectory as Bonga Southwest developments advance.
- Enhanced Oil Recovery:Gas injection and chemical flooding sustain pressure in mature onshore reservoirs. ND Western and other indigenous operators apply these methods across depleted Niger Delta fields.
- Artificial Lift:Electric submersible pumps and gas lift systems handle high-water-cut production from late-life wells. Marginal field producers rely on modular artificial lift packages for cost control.
Proprietary control concentrates with Subsea. Standardized procurement dominates Artificial Lift.
End User:
End user segmentation distinguishes capital access, risk tolerance, and local content compliance capabilities across the operator landscape.
- Independent Operators:Nigerian firms such as Seplat Energy Plc and ND Western leverage lower cost structures and faster decision cycles on marginal field developments. Domestic gas supply obligations to power plants anchor their revenue models.
- National Oil Companies:Nigerian National Petroleum Corporation retains carried interests across joint ventures and participates in production sharing contracts. Cash call arrears accumulated through 2023 constrain partner funding flexibility.
- Multinational Corporations:Shell, TotalEnergies, and ExxonMobil concentrate capital on deepwater developments yielding premium crude grades. Billion-dollar subsea infrastructure requirements limit this tier to five operators.
- Service Providers:Schlumberger and Halliburton affiliates deliver integrated drilling and completions packages under bundled contracts. Nigerian independents lacking technical staff drive demand for turnkey service arrangements.
Integrated project control sits with Multinational Corporations. Disaggregated procurement is expanding fastest among Independent Operators.
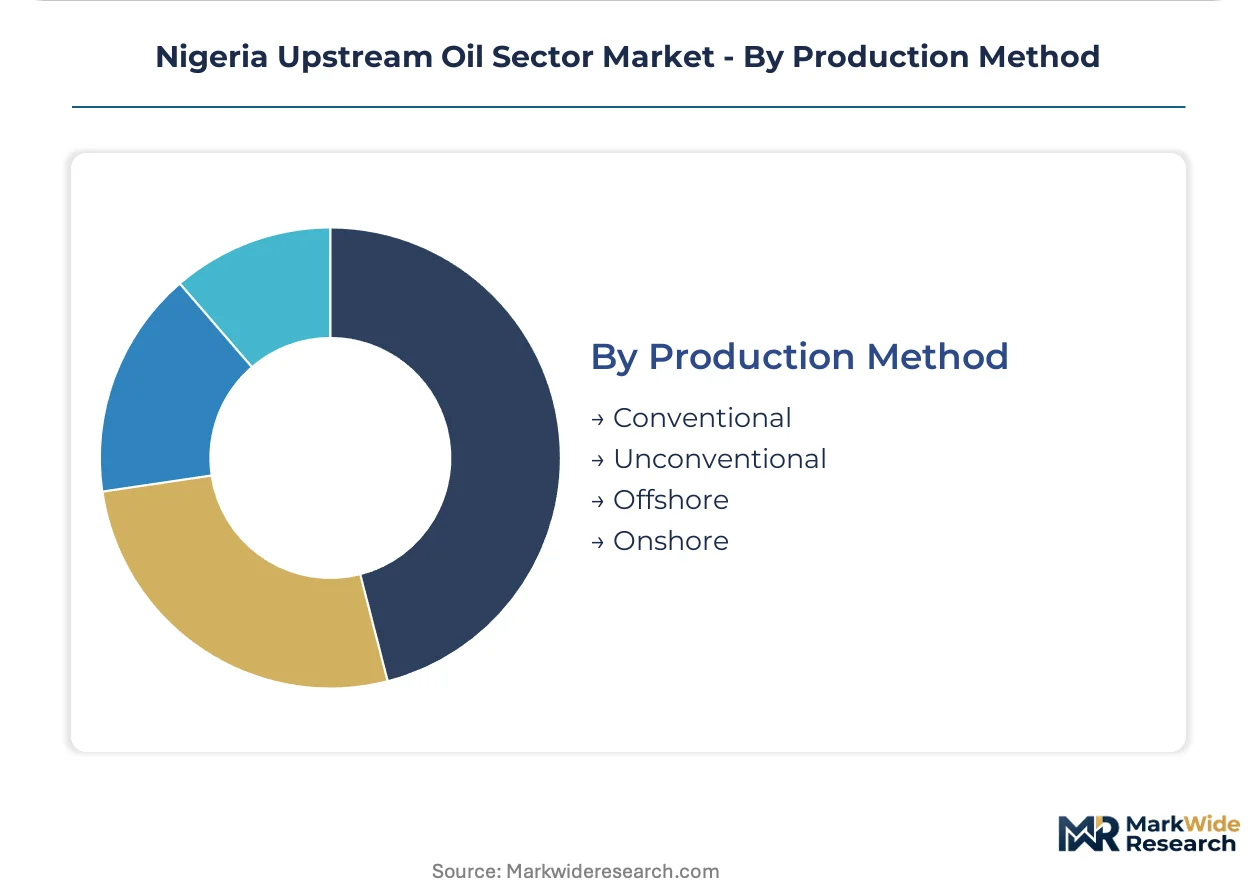
Production Method:
Production method segmentation maps geological setting against fiscal terms, security exposure, and lifting cost structures.
- Conventional:Sandstone reservoirs with natural drive mechanisms dominate onshore Niger Delta production. These fields supply feedstock to Dangote Refinery and rehabilitated state-owned plants.
- Unconventional:Tight sandstone and shale intervals remain technically challenging given limited hydraulic fracturing infrastructure. Exploration focus has not yet shifted to these resources.
- Offshore:Deepwater developments at Bonga, Egina, and Zabazaba yield higher-margin liquids with lower per-barrel lifting costs. Premium crude grades and favorable fiscal terms attract supermajor capital allocation.
- Onshore:Mature fields require enhanced oil recovery and artificial lift to sustain output. Pipeline vandalism and crude theft force twelve to eighteen percent operating expenditure premiums for security infrastructure.
Margin concentration sits with Offshore. Volume concentration remains with Onshore.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Niger Delta Free Trade Zone anchors upstream investment concentration through tax holidays and duty exemptions on drilling equipment imports. This special economic zone channels capital toward deepwater blocks off Bayelsa and Rivers states.
Niger Delta Region
Deepwater exploration and associated gas processing drive capital allocation across Bayelsa, Rivers, and Akwa Ibom states. The Nigerian Upstream Petroleum Regulatory Commission administers production sharing contracts and marginal field licensing rounds under the Petroleum Industry Act framework. Escravos-Lagos Pipeline System expansions concentrate infrastructure investment around Warri and Forcados terminals.
South-East Region
Onshore mature field rehabilitation and enhanced oil recovery operations sustain production from depleted reservoirs in Imo and Abia states. The Department of Petroleum Resources enforces well integrity standards and environmental management protocols for workover campaigns. Owerri industrial corridor hosts modular refinery projects requiring dedicated crude feedstock supply contracts.
South-West Region
Lagos serves as the commercial command center for upstream service contracting and offshore logistics coordination. The Nigerian Content Development and Monitoring Board mandates local participation in engineering procurement for subsea projects. Lekki Free Zone concentrates drilling contractor offices and marine support vessel operations serving Bonga and Egina field developments.
North-Central Region
Abuja hosts regulatory oversight functions and joint venture coordination between international operators and NNPC Limited. The Federal Ministry of Environment administers Environmental Impact Assessment Act compliance for frontier block approvals. The capital district concentrates petroleum industry advocacy groups and technical standards development committees.
Nigeria Upstream Oil Sector Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with supermajors controlling deepwater developments and indigenous operators capturing marginal field awards. The Nigerian upstream oil sector exhibits tiered concentration where five international operators dominate billion-dollar subsea infrastructure projects. Three strategic archetypes define competitive positioning: integrated supermajors with dual-gradient drilling capabilities, domestic independents with lower cost structures, and national oil company joint venture partners. Capacity expansion through subsea processing systems and strategic partnerships for local content compliance represent dominant competitive moves.
Within the integrated supermajor tier, Shell Petroleum Development Company and TotalEnergies EP Nigeria Ltd. exemplify capital-intensive deepwater operators deploying multiphase pump systems at water depths exceeding one thousand meters. Seplat Energy Plc represents the indigenous operator archetype, leveraging faster decision cycles on marginal field developments and domestic gas supply obligations to power plants.
| Leading Market Players |
|---|
| NNPC Limited |
| Shell Petroleum Development Company |
| Chevron Nigeria Ltd. |
| ExxonMobil Nigeria Unlimited |
| TotalEnergies EP Nigeria Ltd. |
| Seplat Energy Plc |
| Aiteo Eastern E&P |
| Oando Energy Resources |
| Eni/NAOC |
| Others |
Pricing and Supply Chain Analysis
Brent crude futures and Nigeria Bonny Light spot differentials cascade through upstream service contracting into three distinct pricing tiers. Deepwater rig day rates command premium positioning against standardized onshore drilling packages and discounted marginal field service bundles.
Pricing Analysis
Short lead-time premiums attach to subsea installation vessels and dual-gradient drilling systems where rig scarcity concentrates bargaining power with contractors. Three-tier pricing structure across premium, standard, and economy levels separates deepwater developments from conventional offshore and mature onshore workovers. Cost compression in the onshore tier is intensifying because indigenous operators with marginal field awards lack balance-sheet depth for long-dated contracts. National oil company joint venture partners exhibit highest price sensitivity due to cash call arrears constraining partner funding flexibility.
Supply Chain Analysis
Direct-to-operator channels handle supermajor demand for integrated drilling and completions packages through Schlumberger and Halliburton affiliates. Equipment fabrication draws from Singapore, South Korea, and the United Arab Emirates for subsea trees and blowout preventer stacks. Steel forgings, high-pressure valves, and subsea umbilical supply chains rest on single-source vulnerability at tier-two component manufacturers. Distribution runs through Lagos-based procurement offices coordinating marine logistics to offshore blocks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Nigeria upstream oil sector sits in a technology-transition phase as subsea processing systems with multiphase pumps displace conventional platform-based separation architectures.
For Market Incumbents: Acquire dual-gradient drilling capability certification assets to defend against indigenous operators capturing marginal field bid rounds. Deepen backward integration into gas gathering infrastructure across the Niger Delta to capture decoupled natural gas revenue streams. Shell Petroleum Development Company and TotalEnergies EP Nigeria Ltd. anchor this defensive posture through billion-dollar subsea infrastructure commitments. For New Entrants and Emerging Players: Indigenous engineering procurement contractors represent the most penetrable channel partner type for technology transfer partnerships under Petroleum Industry Act local content mandates. Target modular refinery feedstock supply contracts across Edo, Delta, and Rivers states where twenty-three licensed plants need dedicated crude offtake. White-space concentration sits with carbon capture integration at Obiafu-Obrikom and Oben gas processing facilities. For Investors and Strategic Acquirers: Distressed-cycle entries favor marginal field operators with domestic gas supply obligations in Bayelsa and Rivers states. Long-term viability across the analysis window hinges on Petroleum Industry Act fiscal term clarity and host community development levy resolution. Monitor Nigerian Upstream Petroleum Regulatory Commission bid round announcements as inflection indicators for acreage reallocation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Subsea Processing Deployment | Multiphase pumps at Bonga Southwest eliminate surface infrastructure and compress capital schedules. |
| Gas Monetization Infrastructure | Escravos-Lagos Pipeline System expansions convert flared associated gas into dedicated revenue streams. |
| Local Content Partnership | Technology transfer agreements with Nigerian Content Development and Monitoring Board reshape vendor selection criteria. |
| Carbon Capture Integration | Geological storage formations at Obiafu-Obrikom align with EU border carbon adjustment exposure. |
| Marginal Field Consolidation | Indigenous operators with faster development timelines capture acreage reallocated from legacy international holders. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Nigeria upstream oil sector assessment. Primary interviews with drilling contractors, subsea engineering directors, Nigerian Content Development and Monitoring Board officials, and marginal field operators combined with Department of Petroleum Resources technical standards documentation and Nigerian Upstream Petroleum Regulatory Commission licensing round records. Bottom-up field-level production estimates and top-down macroeconomic indicators underwent iterative triangulation.
Granularity-level modeling tracked service type, technology category, end user archetype, and production method across the projection horizon. Analytical framework approach derived CAGRs from historical capital deployment patterns and disclosed field development timelines. Crude grade differentials, lifting cost structures, and fiscal term variations under the Petroleum Industry Act informed segment-specific trajectory assumptions.
Caveats apply where host community development levy calculations, security infrastructure cost escalations, or joint venture cash call resolution delays could materially shift the outlook. Forecasts reflect documented assumptions regarding regulatory implementation timelines and international operator capital allocation priorities. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Mexico Wireline Services Market
Oil & Gas
Flexible Pipes for Oil and Gas Market
Oil & Gas
Asphaltene Inhibitors Market
Oil & Gas
Asia Pacific Oil Storage Tank Service Market
Oil & Gas
United States Liner Hanger System Market
Oil & Gas
Norway Oilfield Equipment Market
Oil & Gas
Oil and Gas Data Management Market
Oil & Gas
Middle East Wireline Logging Services Market
Oil & Gas
Kazakhstan Oil and Gas Market
Oil & Gas
Thermal Spray Coating for Oil and Gas Market
Oil & Gas
Russian Federation Oil and Gas Downstream Market
Oil & Gas
Pipeline Pigging Services Market
Oil & Gas
Global Shale Gas Market
Oil & Gas
Gold Mining Market
Oil & Gas
North America Artificial Lift Systems Market
Oil & Gas
Offshore Drilling Fluid Market