
 Thailand Oil and Gas Market | 2026-2036
Thailand Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Oil and Gas Market Outlook
Digital twin technology is rewriting reservoir management and downstream optimization across Thailand's petroleum value chain. PTT PCL leverages integrated digital infrastructure to coordinate upstream, midstream, and retail operations. Chevron Corporation anchors deepwater exploration expertise in the Gulf of Thailand through sustained capital deployment. TotalEnergies SE competes on liquefied natural gas import terminal access and regasification capacity.
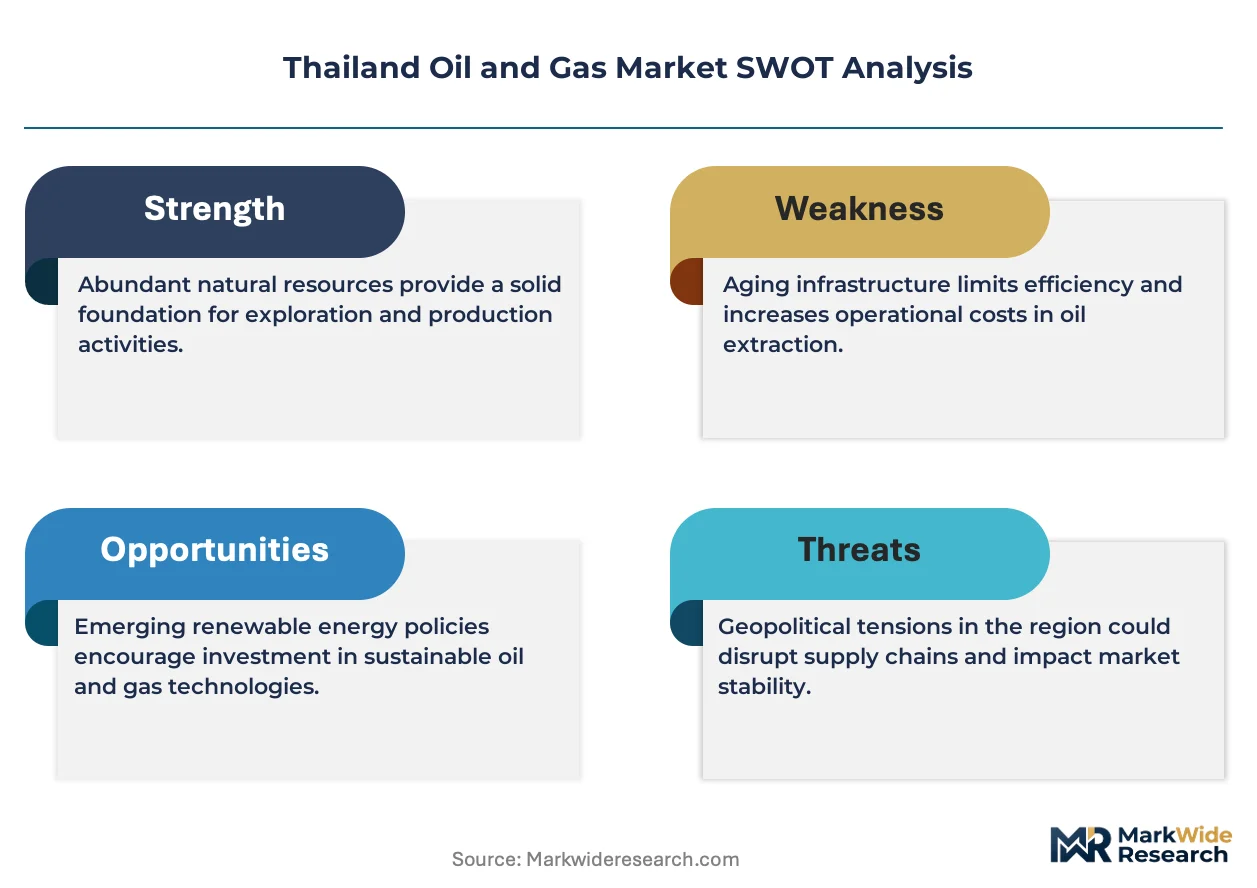
Thailand oil and gas encompasses the full hydrocarbon value chain from geological survey through refined product distribution, with crude processing capacity centered on complex refineries designed for Middle Eastern sour crude blends yielding gasoline, diesel, jet fuel, and petrochemical feedstocks. The exploration and production segment dominates value capture given Thailand's maturing offshore fields in the Gulf and ongoing concession rounds, while the refining segment faces structural margin pressure from regional overcapacity and carbon border adjustments. The power generation end user segment represents the fastest-growing demand pool as Thailand displaces coal-fired capacity with gas-to-power infrastructure under its power development plan.
Thailand's Department of Mineral Fuels administers petroleum concession agreements and production sharing contracts that determine fiscal terms and exploration commitments for operators. The Energy Regulatory Commission oversees natural gas pipeline tariffs, third-party access rules, and retail fuel pricing mechanisms that directly shape downstream economics. Stakeholders must monitor how Thailand's carbon neutrality commitments and emerging emissions trading frameworks will restructure investment incentives across the hydrocarbon value chain.
Market Dynamics
Thailand's maturing offshore concessions are forcing operators toward enhanced oil recovery and digital infrastructure investments as natural production decline rates accelerate across Gulf of Thailand fields.
Growth Catalysts
- Petrochemical Feedstock Demand:Rayong's Eastern Economic Corridor industrial zone is absorbing record naphtha and LPG volumes for olefins production, creating captive offtake for domestic refiners.
- Power Development Plan Gas-to-Power Mandate:Thailand's national energy roadmap mandates gas-fired capacity additions displacing coal baseload, locking in long-term domestic gas demand through 2035.
- Digital Twin Deployment:Reservoir simulation platforms are compressing field development cycles and optimizing recovery factors from depleted offshore blocks.
Market Restraints
- Upstream Licensing Friction:Revised petroleum concession terms from the Department of Mineral Fuels have tightened exploration commitments and extended fiscal uncertainty for new block entrants.
- Regional Refining Overcapacity:Singapore and South Korea export-oriented refiners are flooding Southeast Asian product markets, compressing clean product cracks for Thai complex refineries.
- Carbon Border Adjustment Exposure:Thailand's export-oriented refined products face emerging EU carbon border taxes that erode price competitiveness in premium European offtake markets.
Strategic Opportunities
- LNG Import Terminal Expansion:Third-party access to Map Ta Phut regasification infrastructure opens arbitrage trading and downstream power sector contracting for portfolio players.
- Hydrogen Hub Development:Thailand's industrial east coast is positioning for blue hydrogen production leveraging existing natural gas infrastructure and carbon capture partnerships.
- Biogas Upgrading Integration:Palm oil mill effluent and agricultural waste methane capture projects qualify for renewable energy certificates under national feed-in tariff mechanisms.
Industry Challenges
- Subsurface Talent Scarcity:Gulf of Thailand's complex carbonate reservoir geology demands specialized geoscience expertise that domestic universities and expatriate pools increasingly fail to supply.
- Legacy SCADA Migration:Decades-old pipeline control systems require cybersecurity-hardened replacement without interrupting natural gas delivery to Bangkok's power generation cluster.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Oil and Gas Market |
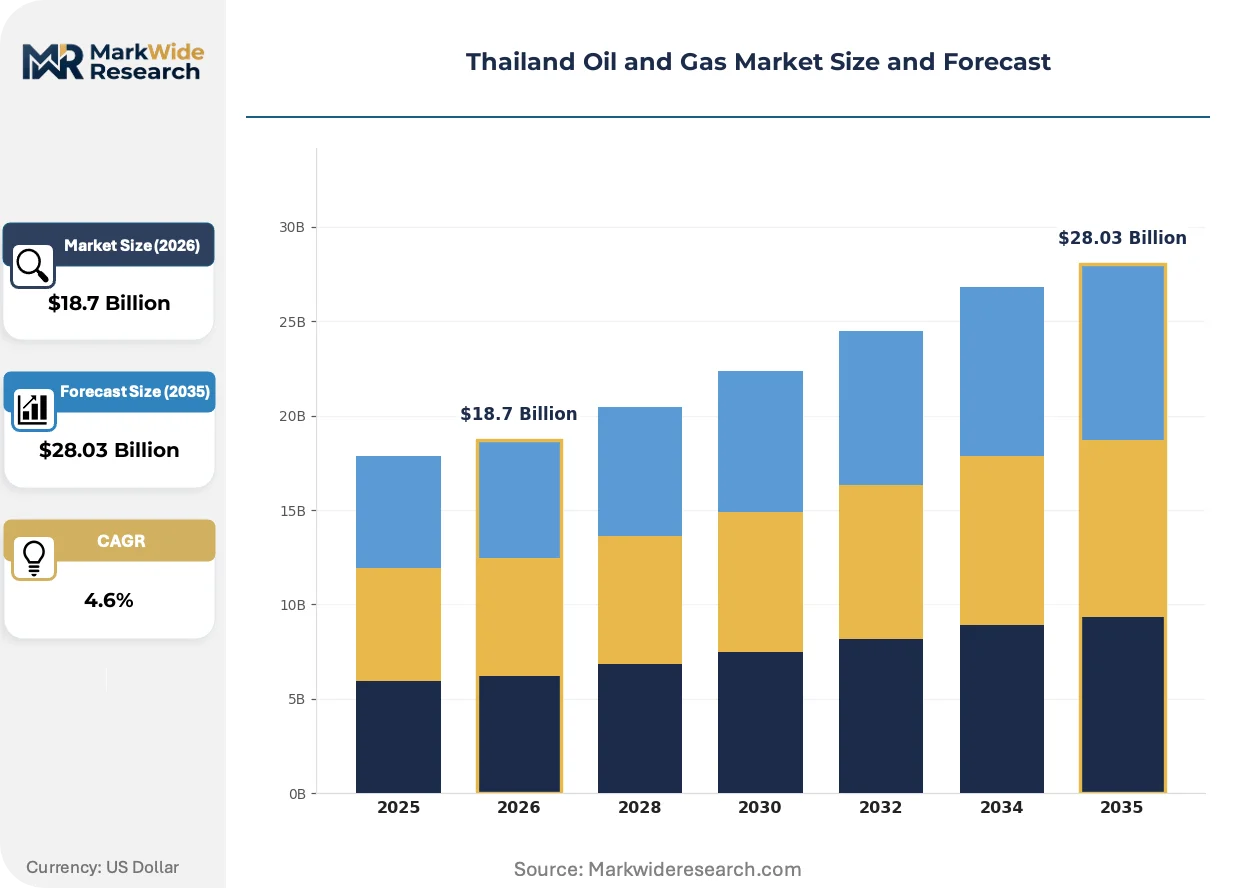
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Exploration, Production, Refining, Distribution Technology: Conventional, Unconventional, Renewable, Hybrid End User: Industrial, Commercial, Residential, Power Generation Service Type: Drilling, Maintenance, Engineering, Consulting |
| Companies Covered | PTT PCL, PTT Exploration & Production PCL, PTT Oil and Retail Business Public Company Ltd, Thai Oil Public Company Ltd, Bangchak Corp Public Company Ltd, Star Petroleum Refining Public Company Ltd, IRPC PCL, Chevron Corporation, TotalEnergies SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Oil and Gas Market Strategic Shifts
Operational technology convergence and carbon accounting pressures are restructuring investment priorities across Thailand's petroleum value chain, with digital infrastructure and emissions transparency emerging as competitive differentiators.
Advanced process control systems are migrating from rule-based automation to machine-learning-optimized refinery unit operations. Thai complex refiners processing high-sulfur Middle Eastern crudes are deploying neural network models for yield optimization and energy intensity reduction. This migration from conventional distributed control systems is compressing margin volatility and enabling real-time carbon emissions tracking for product certification.
Thailand's carbon neutrality commitments are tightening methane emissions monitoring requirements for upstream operators. The Department of Mineral Fuels is integrating satellite-based leak detection mandates into production sharing contract compliance frameworks. Offshore platform operators are responding with continuous monitoring sensor networks and automated shutdown protocols to avoid production penalties.
Industrial buyers in the Eastern Economic Corridor are consolidating procurement through long-term indexed contracts rather than spot market exposure. Petrochemical majors are negotiating 10-15 year natural gas supply agreements with price linkage to regional LNG benchmarks rather than oil-indexed legacy structures. This contract restructuring is most pronounced among olefins producers seeking feedstock cost predictability for export-competitive derivative manufacturing.
Thailand Oil and Gas Market Segmentation
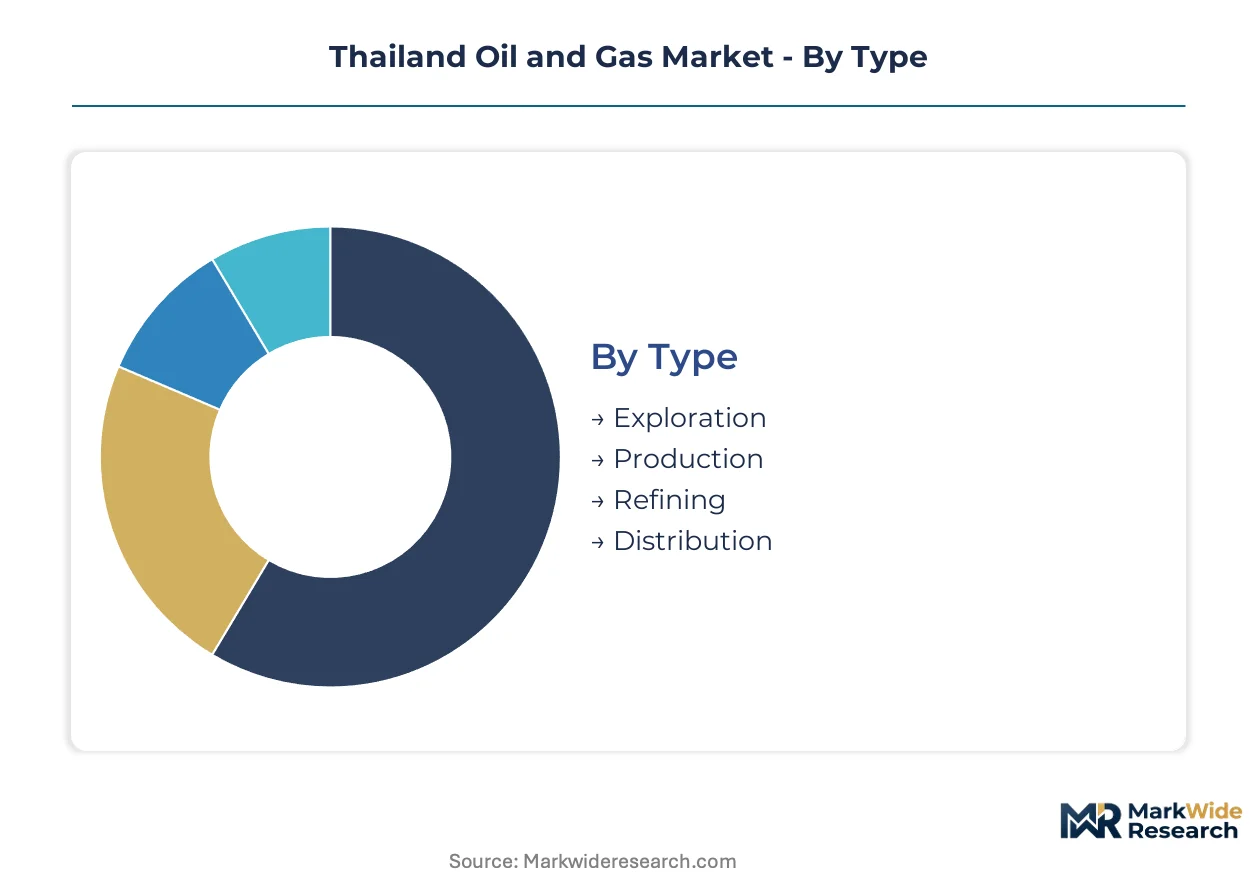
Segmentation reveals how Thailand's petroleum value chain fragments across operational stages, technology maturity levels, and customer procurement patterns. Each dimension carries distinct margin profiles and regulatory exposure that reshape capital allocation priorities for operators and service providers.
Type:
Upstream through downstream operations span radically different capital intensity cycles and concession frameworks across Thailand's Gulf of Thailand basin and Eastern Economic Corridor processing clusters.
- Exploration:Seismic survey and wildcat drilling activities targeting carbonate reservoirs in the Pattani Trough and Malay Basin. Operators face compressed drilling windows under tightened Department of Mineral Fuels licensing terms that demand accelerated commitment fulfillment.
- Production:Mature offshore field operations deploying enhanced oil recovery and digital twin infrastructure to offset natural decline rates across legacy Gulf of Thailand blocks. Rayong's processing facilities absorb the bulk of domestic crude output for petrochemical feedstock conversion.
- Refining:Complex refinery units processing high-sulfur Middle Eastern crudes into gasoline, diesel, and naphtha for Eastern Economic Corridor olefins producers. Regional overcapacity from Singapore and South Korean exporters compresses clean product cracks.
- Distribution:Pipeline networks, coastal terminals, and retail fuel stations delivering refined products to Bangkok's transport sector and provincial industrial zones. Third-party access rules under Energy Regulatory Commission oversight reshape terminal economics.
Production commands the dominant value share given concession maturity and feedstock integration, while exploration is closing the gap fastest under revised licensing rounds.
Technology:
Technology stratification reflects capital recovery horizons and carbon exposure tiers, with operators balancing reservoir depletion against energy transition positioning.
- Conventional:Fixed-platform offshore production and thermal cracking refinery processes representing installed base infrastructure across Thailand's petroleum sector. These assets face mounting methane monitoring mandates under satellite-based leak detection requirements.
- Unconventional:Enhanced oil recovery methods including gas injection and chemical flooding targeting residual oil saturation in depleted Gulf of Thailand fields. Digital twin deployment is compressing field development cycles and optimizing recovery factors.
- Renewable:Biogas upgrading from palm oil mill effluent and agricultural waste methane capture qualifying for renewable energy certificates under national feed-in tariff mechanisms. Map Ta Phut industrial buyers are contracting these volumes for process heat substitution.
- Hybrid:Integrated natural gas-to-hydrogen production with carbon capture partnerships positioning Thailand's east coast for blue hydrogen export. Existing pipeline infrastructure reduces greenfield capital requirements for industrial gas buyers.
Conventional technology retains the largest installed capacity base, though renewable segments are expanding most quickly around biogas certification and carbon-neutral fuel demand.
End User:
Customer procurement patterns diverge sharply between spot-indexed industrial buyers and regulated residential tariffs, creating distinct pricing power dynamics.
- Industrial:Petrochemical majors and olefins producers in Rayong's Eastern Economic Corridor negotiating 10-15 year indexed natural gas supply agreements. These buyers are shifting from oil-indexed legacy structures to regional LNG benchmark linkages for feedstock cost predictability.
- Commercial:Transport fleet operators, aviation fuel purchasers, and marine bunkering clients across Bangkok Port and Laem Chabang. Jet fuel demand concentrates around Suvarnabhumi Airport's expanding international route network.
- Residential:LPG cylinder distribution and piped natural gas connections for household cooking and heating in Bangkok metropolitan and provincial urban centers. Energy Regulatory Commission retail pricing mechanisms cap margin expansion.
- Power Generation:Electricity Generating Authority of Thailand and independent power producers displacing coal-fired baseload under the national Power Development Plan. Gas-to-power infrastructure mandates lock in long-term domestic gas demand through 2035.
Industrial offtake dominates volume absorption, while power generation is climbing fastest under coal displacement mandates and capacity addition timelines.
Service Type:
Service procurement splits between capital-intensive field development and recurring operational expenditure contracts with diverging margin stability.
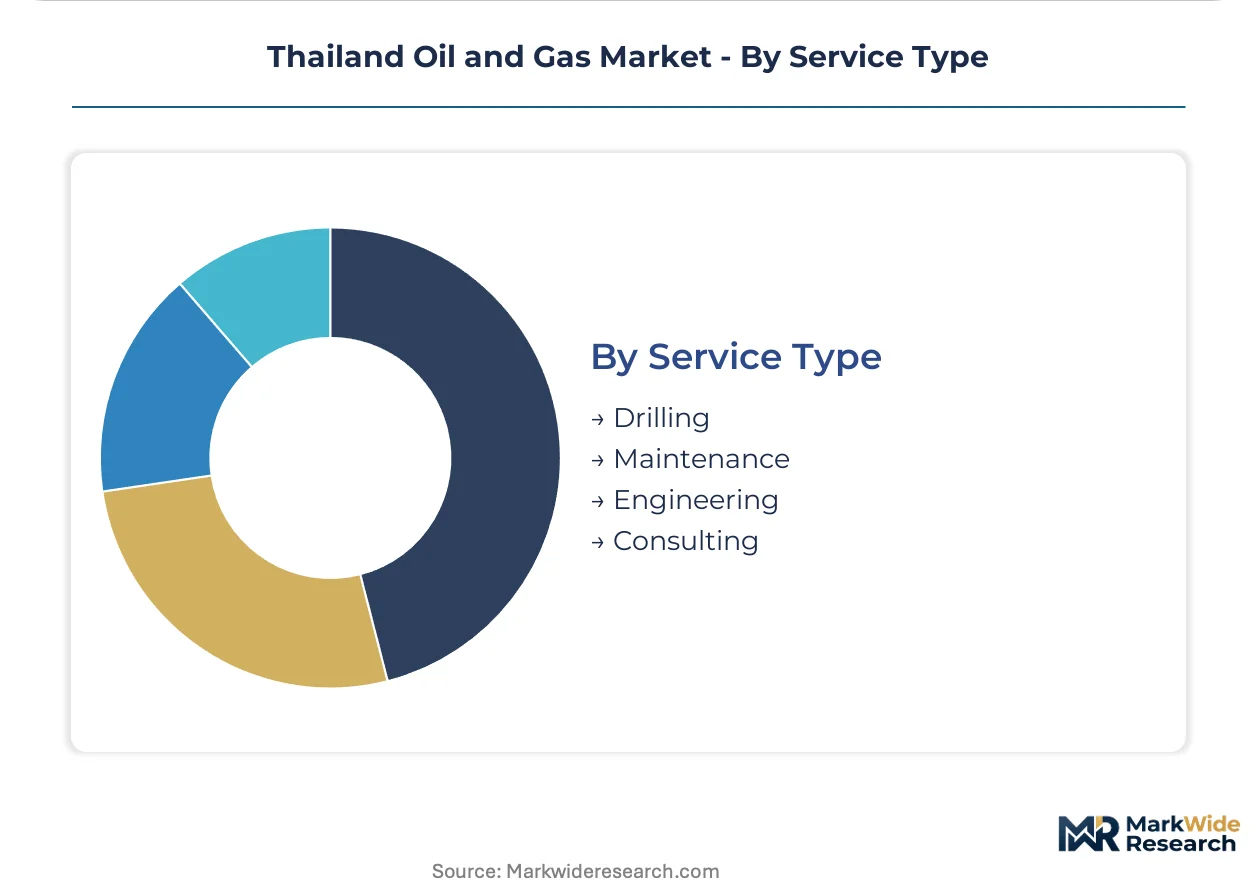
- Drilling:Offshore rig contracting, directional drilling services, and completion operations for exploration and development wells in the Gulf of Thailand. Subsurface talent scarcity for carbonate reservoir geology is tightening contractor pricing power.
- Maintenance:Platform integrity management, subsea pipeline inspection, and refinery turnaround services sustaining production from maturing concessions. Predictive maintenance algorithms are reducing unplanned outage frequency.
- Engineering:Front-end engineering design for LNG terminal expansion, hydrogen hub infrastructure, and refinery unit upgrades. Map Ta Phut regasification capacity additions drive project backlog concentration.
- Consulting:Carbon accounting, emissions trading framework advisory, and concession bid preparation under tightened Department of Mineral Fuels fiscal terms. Regulatory complexity is expanding advisory scope around methane monitoring compliance.
Maintenance services capture the steadiest revenue base from installed infrastructure, while engineering is gaining share fastest around LNG terminal and hydrogen project pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial buyers in Thailand's Eastern Economic Corridor absorb the bulk of domestic hydrocarbon output, while provincial power generators and transport operators distribute demand across Bangkok's metropolitan core and southern coastal zones.
Rayong and the Eastern Economic Corridor
Petrochemical majors in Rayong's industrial zone consume record naphtha and LPG volumes for olefins production, creating captive offtake for Thai complex refineries. The Department of Mineral Fuels administers production sharing contracts governing offshore gas deliveries to Map Ta Phut processing facilities. PTT PCL coordinates integrated upstream-through-retail operations across this corridor, anchoring Thailand's hydrocarbon value chain concentration.
Bangkok Metropolitan Region
Electricity Generating Authority of Thailand and independent power producers operate gas-fired capacity displacing coal baseload under the national Power Development Plan. The Energy Regulatory Commission oversees natural gas pipeline tariffs and third-party access rules shaping downstream economics. Bangkok's power generation cluster receives dedicated pipeline infrastructure from Gulf of Thailand offshore fields.
Gulf of Thailand Offshore Basin
Maturing carbonate reservoirs in the Pattani Trough and Malay Basin require enhanced oil recovery and digital twin deployment to offset natural decline rates. Chevron Corporation anchors deepwater exploration expertise through sustained capital deployment across legacy concession blocks. Offshore platform operators face tightened methane monitoring mandates integrating satellite-based leak detection into compliance frameworks.
Songkhla and Southern Coastal Zone
Transport fleet operators and marine bunkering clients at Laem Chabang port absorb diesel and residual fuel oil volumes for regional shipping routes. Jet fuel demand concentrates around Suvarnabhumi Airport's expanding international route network serving southern tourism corridors. Provincial industrial zones outside the Eastern Economic Corridor compete for limited pipeline capacity allocations.
Chiang Mai and Northern Upland Areas
LPG cylinder distribution networks serve household cooking demand in provincial urban centers distant from pipeline infrastructure. Biogas upgrading projects from agricultural waste methane capture qualify for renewable energy certificates under national feed-in tariff mechanisms. Palm oil mill effluent recovery operations in northern plantation zones supply process heat substitution volumes to dispersed industrial buyers.
Thailand Oil and Gas Market Competitive Environment
Channel-controlling players compete with product-specialist players across Thailand's petroleum value chain, creating a tiered structure where integrated national champions coordinate upstream-through-retail operations while international majors anchor specific technical segments. The market consolidates around three strategic archetypes: state-linked integrated operators controlling infrastructure access, international exploration specialists deploying deepwater expertise, and refining-petrochemical hybrids capturing feedstock integration economics. Dominant competitive moves include concession bidding under tightened Department of Mineral Fuels fiscal terms and digital infrastructure deployment for reservoir optimization.
Within the integrated operator tier, PTT PCL exemplifies channel control through coordinated upstream, midstream, and retail infrastructure ownership. Chevron Corporation and TotalEnergies SE represent international specialist archetypes, with the former anchoring deepwater exploration capabilities and the latter competing on liquefied natural gas terminal access and regasification capacity. These three entities occupy distinct competitive positions without overlapping core competencies.
| Leading Market Players |
|---|
| PTT PCL |
| PTT Exploration & Production PCL |
| PTT Oil and Retail Business Public Company Ltd |
| Thai Oil Public Company Ltd |
| Bangchak Corp Public Company Ltd |
| Star Petroleum Refining Public Company Ltd |
| IRPC PCL |
| Chevron Corporation |
| TotalEnergies SE |
| Others |
Value Chain & Pricing Dynamics
Map Ta Phut port logistics corridors shape cost dynamics across Thailand's petroleum value chain, concentrating supply-side leverage among integrated operators while forcing downstream price differentiation between spot-indexed industrial buyers and regulated residential tariffs.
Pricing Analysis
Long-term natural gas supply agreements indexed to regional LNG benchmarks dominate procurement patterns among Eastern Economic Corridor petrochemical majors. Price differentiation separates oil-indexed legacy contracts from regional LNG benchmark linkages, with volume scale and contract duration as secondary tiering factors. Cost compression in refining margins is intensifying because Singapore and South Korean exporters flood Southeast Asian product markets. Industrial olefins producers exhibit the least price sensitivity due to captive feedstock integration, while provincial transport fleet operators face the highest spot market exposure.
Supply Chain Analysis
Upstream crude feedstock draws from Middle Eastern sour crude producers, with secondary sourcing from regional Southeast Asian suppliers. Key inputs include high-sulfur crude blends, naphtha for olefins cracking, and LPG for petrochemical feedstock. Single-source vulnerability concentrates around Map Ta Phut regasification terminal access for LNG imports. Distribution runs through PTT PCL's integrated pipeline network, coastal terminals, and retail station infrastructure serving Bangkok's power generation cluster and provincial industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's oil and gas sector represents early-cycle expansion anchored by the Power Development Plan's gas-to-power infrastructure buildout accelerating domestic demand absorption.
For Market Incumbents: Entrench position through backward integration into biogas upgrading infrastructure and carbon capture partnerships for blue hydrogen positioning. Deepen digital twin deployment across maturing Gulf of Thailand fields to offset natural decline rates. Prioritize concession bidding discipline under tightened Department of Mineral Fuels fiscal terms to preserve capital efficiency.
For New Entrants and Emerging Players: Northern upland biogas corridors offer underpenetrated white-space for agricultural waste methane capture projects qualifying for renewable energy certificates. Third-party access to Map Ta Phut regasification infrastructure opens arbitrage trading opportunities for portfolio players lacking integrated upstream assets. Target engineering services contracting around LNG terminal expansion and hydrogen hub development with specialized carbon accounting advisory capabilities.
For Investors and Strategic Acquirers: Thailand's emerging emissions trading framework reshapes the acquisition landscape toward methane-monitoring-compliant upstream operators and carbon-neutral fuel certification holders. Long-term viability favors integrated players with captive Eastern Economic Corridor offtake and pipeline infrastructure control. Monitor satellite-based leak detection mandate enforcement as the critical signal for regulatory compliance cost inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Deployment | PTT PCL compresses field development cycles across maturing Gulf of Thailand carbonate reservoirs. |
| LNG Terminal Expansion | Map Ta Phut regasification capacity additions enable third-party access for power sector portfolio players. |
| Hydrogen Hub Development | Blue hydrogen production leverages existing natural gas infrastructure and carbon capture partnerships. |
| Biogas Upgrading Integration | Palm oil mill effluent methane capture qualifies for renewable energy certificates under national feed-in tariffs. |
| Enhanced Oil Recovery Investment | Gas injection and chemical flooding target residual oil saturation in depleted offshore blocks. |
Study Parameters
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this study. The research team conducted structured discussions with upstream project developers, refinery operations managers, Energy Regulatory Commission policy officers, and petrochemical procurement leads. Secondary sources include Department of Mineral Fuels concession databases, Energy Regulatory Commission tariff filings, PTT PCL infrastructure disclosure reports, and IEA Thailand energy balance statistics. Bottom-up segment sizing and top-down macroeconomic calibration ensure methodological triangulation.
Calibration against historical production data and announced project pipelines shapes the analytical framework across the projection horizon. Segmentation dimensions span upstream through downstream operational stages, conventional through hybrid technology tiers, and industrial through power generation end-use categories. CAGRs derive from regression analysis of concession maturity curves, demand elasticity estimates around gas-to-power substitution, and refining margin compression trends. Industry-specific inputs incorporate Power Development Plan capacity addition timelines and carbon border adjustment exposure modeling for export-oriented refined products.
Practitioners should monitor Department of Mineral Fuels licensing round participation rates and satellite-based methane detection mandate compliance costs for early signals of upstream investment sentiment shifts. Forecasts reflect assumptions around regional LNG price volatility, EU carbon border tax implementation scope, and Eastern Economic Corridor industrial demand growth trajectories. Cross-checking against IEA Thailand gas demand projections and announced refinery upgrade capital commitments is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Blowout Preventers (BOP) Market
Oil & Gas
Middle East and Africa Coiled Tubing Market
Oil & Gas
Chad Oil and Gas Market
Oil & Gas
Oilfield Drilling Elevator Market
Oil & Gas
India Artificial Lift Systems Market
Oil & Gas
Ecuador Wireline Logging Services Market
Oil & Gas
Subsea Flowlines Market
Oil & Gas
Oil and Gas Midstream Market
Oil & Gas
Oman Oil and Gas Pipeline Market
Oil & Gas
Global Deep-Well Disposal Services Market
Oil & Gas
North America Seismic Services Market
Oil & Gas
Injection Well Market
Oil & Gas
Digital Oil Rigs Market
Oil & Gas
Romania Oil and Gas Market
Oil & Gas
Smart Pipeline Pigging Market
Oil & Gas
Global Upstream Petrotechnical Training Services Market