
 Italy Oil and Gas Upstream Market | 2026-2036
Italy Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Oil and Gas Upstream Market Foresight
Power generation is realigning Italy's gas production priorities as utilities seek baseload supply from domestic offshore fields. Eni SpA anchors the Adriatic and Ionian upstream portfolio through its integrated exploration-to-production structure. Saipem SpA competes in subsea engineering and drilling services, leveraging specialized offshore capabilities. TotalEnergies sustains its position in mature Sicilian assets while navigating decommissioning obligations.
Italy oil and gas upstream encompasses exploration, drilling, and production activities targeting hydrocarbon reservoirs beneath the Po Valley, Adriatic Sea, and Sicily Channel, with wells reaching depths from 2,000 to 4,500 meters and employing seismic imaging to map carbonate and sandstone formations. The primary purpose is supplying feedstock to domestic refineries and gas-fired power plants while reducing import dependency. Drilling services and production services command the largest service-type revenue pools, though reservoir management is gaining share as mature fields require enhanced recovery techniques. Seismic imaging leads technology spending for new exploration licensing rounds, while enhanced oil recovery applications are expanding in Basilicata's declining fields.
Italy's Ministry of Environment and Energy Security enforces upstream licensing through national production-sharing contracts aligned with EU methane regulation and the F-Gas Regulation for offshore refrigeration systems. The country's central bank and energy regulator monitor investment flows and field development timelines under the National Recovery and Resilience Plan. Operators must track how EU taxonomy criteria for transitional natural gas activities reshape project financing availability and decommissioning fund requirements.
Market Dynamics
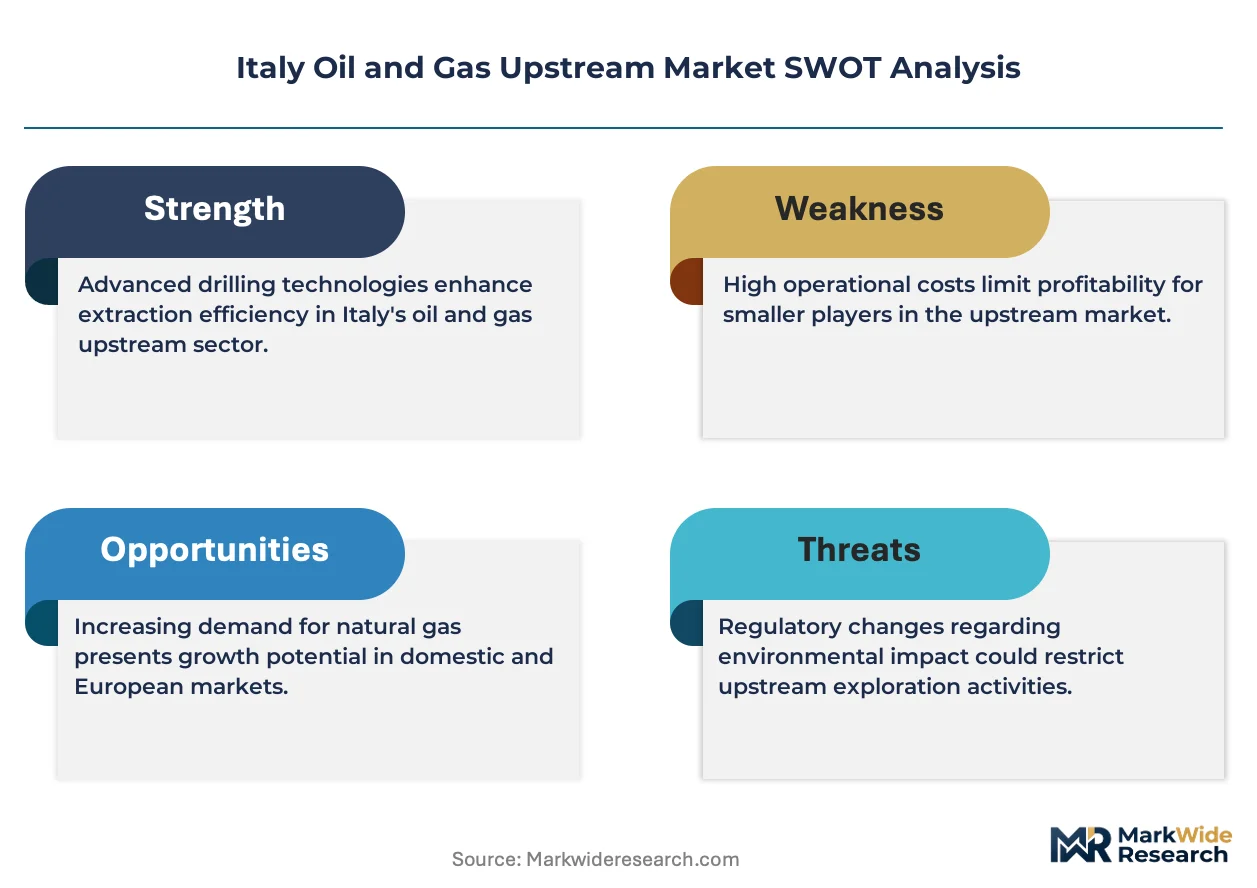
Italy's upstream sector faces a structural pivot as the National Energy and Climate Plan forces methane emissions intensity reductions, redirecting capital from pure production expansion toward leak detection infrastructure and flaring abatement systems across Adriatic and Sicilian offshore assets.
Growth Catalysts
- Power generation baseload demand:Utilities are expanding natural gas offtake from domestic Adriatic and Sicilian offshore fields to displace coal and reduce import exposure from North African pipelines.
- EU methane regulation compliance:The F-Gas Regulation and aligned national production-sharing contracts create procurement pull for emissions monitoring technologies and refrigeration system upgrades on offshore platforms.
- Carbonate formation exploration:Seismic imaging advances are unlocking deeper Apennine and Adriatic carbonate reservoirs, with Basilicata's Val d'Agri hub serving as the operational template for southern Italy expansion.
Market Restraints
- Mature field decline rates:Basilicata's Val d'Agri oil hub requires escalating enhanced oil recovery capex to maintain plateau production, compressing returns on marginal barrels.
- Decommissioning liability concentration:Sicily Channel assets face accelerating plug-and-abandonment obligations, with operators diverting free cash flow to reserve funding rather than new exploration.
- EU taxonomy transitional criteria:Project financing availability for natural gas activities is narrowing as institutional investors apply stricter sustainability screens to upstream exposure.
Strategic Opportunities
- Po Valley reactivation:Shallow onshore fields in northern Italy's Po Valley present low-capex recompletion targets for independents with specialized artificial lift expertise.
- Electrification of offshore platforms:Subsea power-from-shore and platform electrification technologies are converging with Adriatic wind development to enable near-zero operational emissions at marginal cost.
- Carbon capture integration:The National Recovery and Resilience Plan allocates capital toward depleted gas field repurposing for CO2 storage, creating dual-revenue streams from production and sequestration services.
Industry Challenges
- Subsea engineering talent scarcity:Specialized deepwater drilling and completions expertise is concentrating among a shrinking pool of contractors, inflating day rates and extending project timelines.
- Legacy platform integration:Sicilian and Adriatic mature assets require sensor retrofits and control system upgrades to meet real-time methane monitoring mandates, forcing operational shutdowns during installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Oil and Gas Upstream Market |
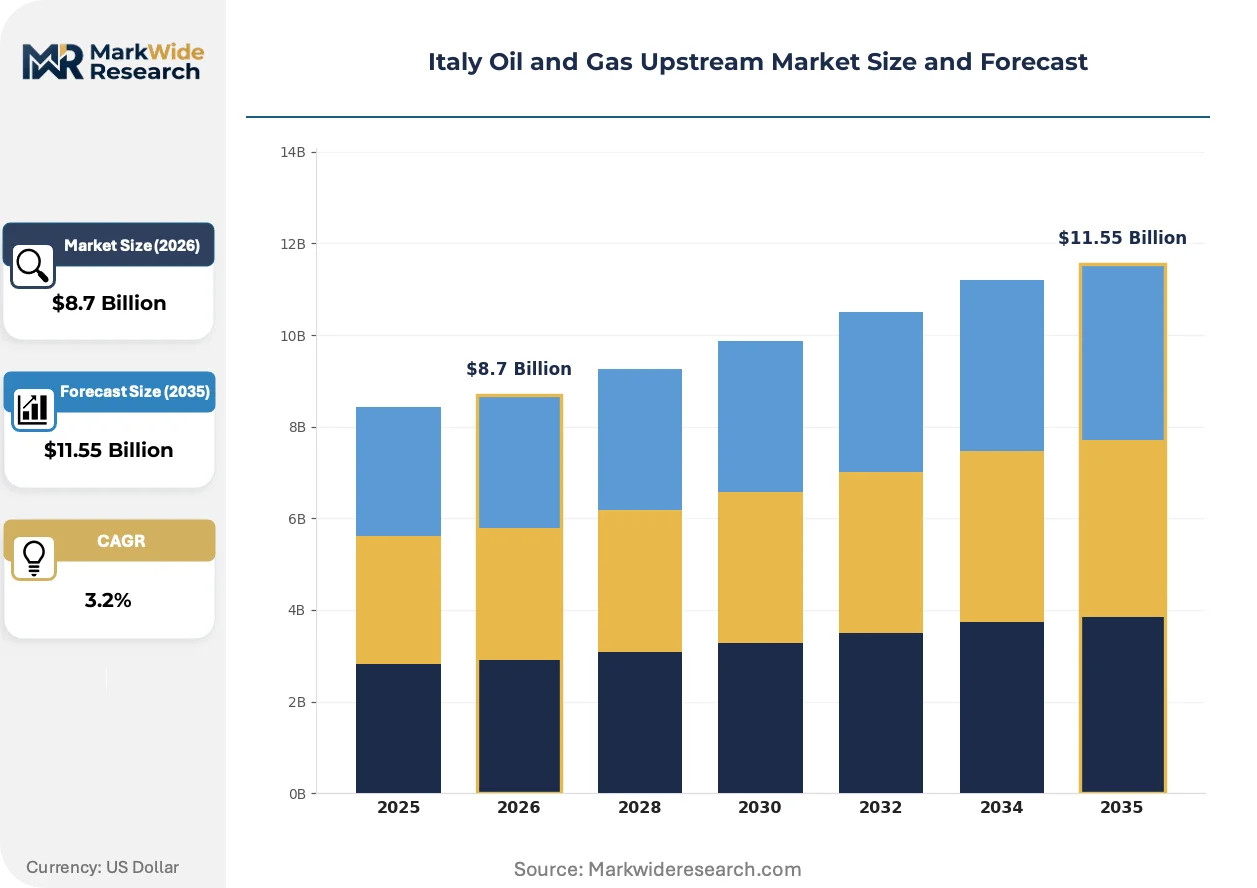
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $11.55 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Drilling Services, Well Completion, Production Services, Reservoir Management Technology: Seismic Imaging, Enhanced Oil Recovery, Hydraulic Fracturing, Vertical Drilling End User: Private Operators, National Oil Companies, Independent Producers, Service Contractors Investment Stage: Exploration, Development, Production, Decommissioning |
| Companies Covered | Eni SpA, Edison SpA, Saipem SpA, TotalEnergies, Shell Plc, ExxonMobil, BP, Chevron, Eni Sustainable Mobility, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Oil and Gas Upstream Market Shifts & Advancements
Upstream technology deployment in Italy is pivoting from volume-maximizing extraction toward emissions-accountable production systems. Operators are embedding digital infrastructure and electrification hardware into field development planning from the initial licensing phase.
Distributed fiber-optic sensing is electrifying subsea monitoring architecture across Adriatic gas fields. Eni and service contractors are deploying permanent seabed sensor arrays to replace periodic ROV inspection cycles. This shift is compressing leak detection response times from weeks to hours while reducing offshore personnel exposure.
Italy's Ministry of Environment and Energy Security is tightening upstream licensing through methane intensity benchmarks tied to EU Green Deal implementation. National production-sharing contracts now mandate continuous emissions monitoring and public disclosure protocols. Basilicata operators are responding by retrofitting Val d'Agri facilities with automated flare gas recovery systems ahead of contractual deadlines.
Integrated service contracting is displacing discrete equipment procurement across southern Italy exploration blocks. Operators are bundling seismic, drilling, and production services under single-source agreements to transfer subsurface risk to contractors. This pattern is most visible in Ionian Sea licensing rounds where Eni and partners seek guaranteed production outcomes rather than day-rate exposure.
Italy Oil and Gas Upstream Market Segmentation
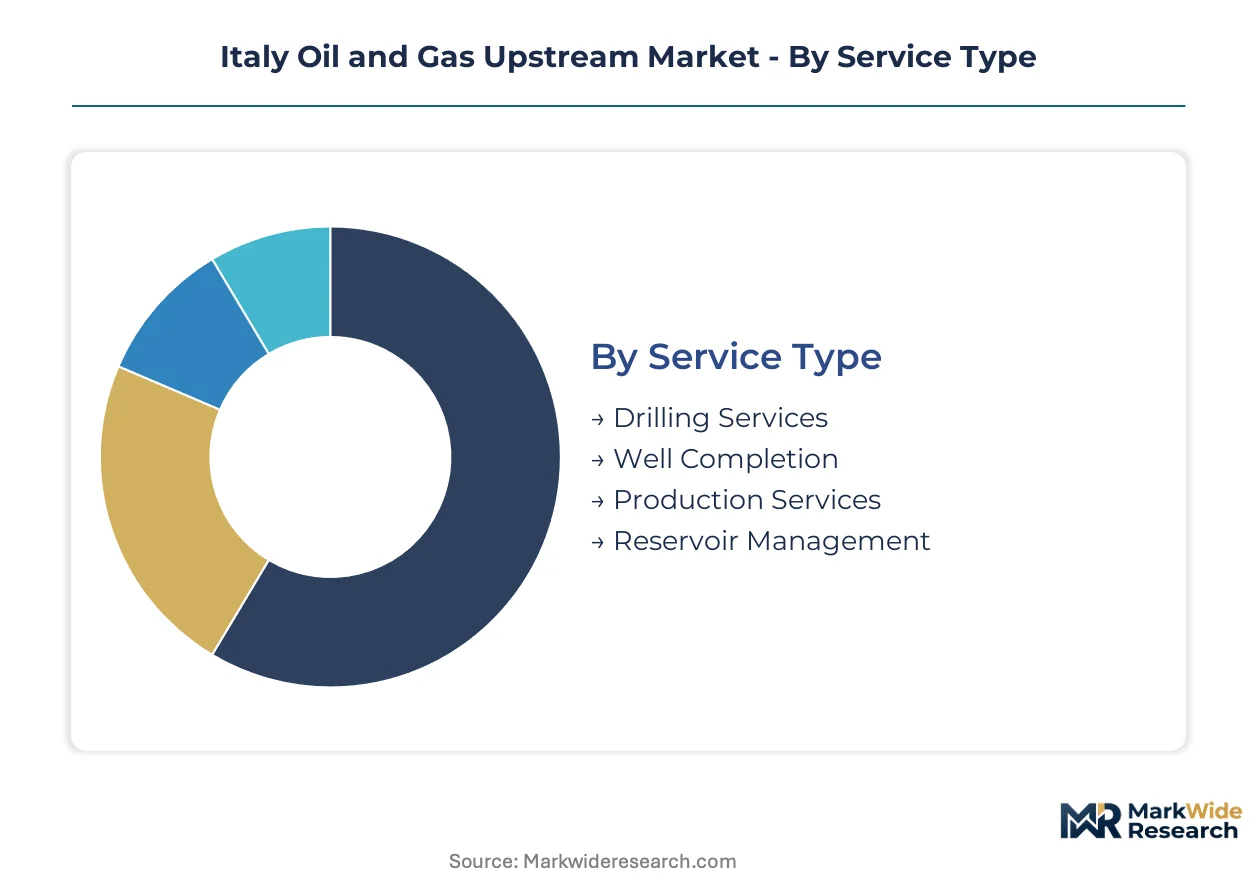
Upstream segmentation in Italy reflects capital allocation priorities shaped by methane regulation deadlines and mature field economics. Operators select service tiers and technology bundles based on whether assets sit in declining Basilicata oilfields or expanding Adriatic gas provinces.
Service Type:
Replacement cycles for offshore platforms in the Adriatic and Sicily Channel are accelerating procurement of integrated service packages over discrete equipment purchases.
- Drilling Services:Offshore jack-up and semi-submersible rigs execute wells to 4,500 meters in the Ionian Sea. Demand clusters around Eni's Adriatic exploration program where carbonate targets require specialized directional drilling. The F-Gas Regulation mandates refrigeration system upgrades during rig mobilization, extending contract scopes.
- Production Services:Artificial lift systems and subsea processing equipment maintain plateau output from Val d'Agri's mature reservoirs. Basilicata operators are bundling production optimization with flare gas recovery retrofits to meet National Energy and Climate Plan methane intensity benchmarks.
- Well Completion:Intelligent completions with permanent downhole monitoring enable real-time reservoir management in deep Apennine wells.
- Reservoir Management:Enhanced recovery simulation and geological modeling services extend field life as natural decline accelerates across Sicily Channel assets.
Volume placements concentrate in Production Services; the faster expansion belongs to Reservoir Management.
Technology:
Cost tier differentiation separates legacy asset maintenance from frontier exploration, with premium seismic and recovery technologies commanding multi-year contracting cycles.
- Seismic Imaging:Distributed fiber-optic sensing and permanent seabed arrays replace periodic ROV inspections across Adriatic gas fields. Eni deploys these systems to compress leak detection response times while reducing offshore personnel exposure.
- Enhanced Oil Recovery:CO2 injection and polymer flooding applications are expanding in Basilicata's Val d'Agri hub where natural drive mechanisms have depleted. The National Recovery and Resilience Plan allocates capital toward depleted field repurposing, creating dual-revenue production and sequestration streams.
- Hydraulic Fracturing:Limited application in tight carbonate formations of the southern Apennines faces water access constraints and permitting complexity.
- Vertical Drilling:Shallow onshore recompletions in the Po Valley employ conventional vertical architecture for low-capex reactivation targets.
Technology spending clusters in Seismic Imaging; Enhanced Oil Recovery is climbing the fastest as mature fields require escalating recovery capex.
End User:
Customer type determines contract structure, with integrated majors favoring risk-sharing partnerships and independents pursuing guaranteed production outcomes.
- National Oil Companies:Eni SpA anchors Italy's upstream through integrated exploration-to-production structures spanning Adriatic, Ionian, and Sicilian concessions. Its procurement patterns favor bundled seismic-drilling-production contracts that transfer subsurface risk to service providers.
- Private Operators:International majors including TotalEnergies sustain positions in mature Sicilian assets while navigating decommissioning obligations and emissions retrofit requirements.
- Independent Producers:Smaller operators target Po Valley recompletions and marginal Adriatic fields with specialized artificial lift expertise.
- Service Contractors:Saipem and specialized drilling contractors compete for subsea engineering scopes, though deepwater talent scarcity inflates day rates and extends project timelines.
Contract value concentrates with National Oil Companies; Independent Producers are gaining share fastest through Po Valley reactivation programs.
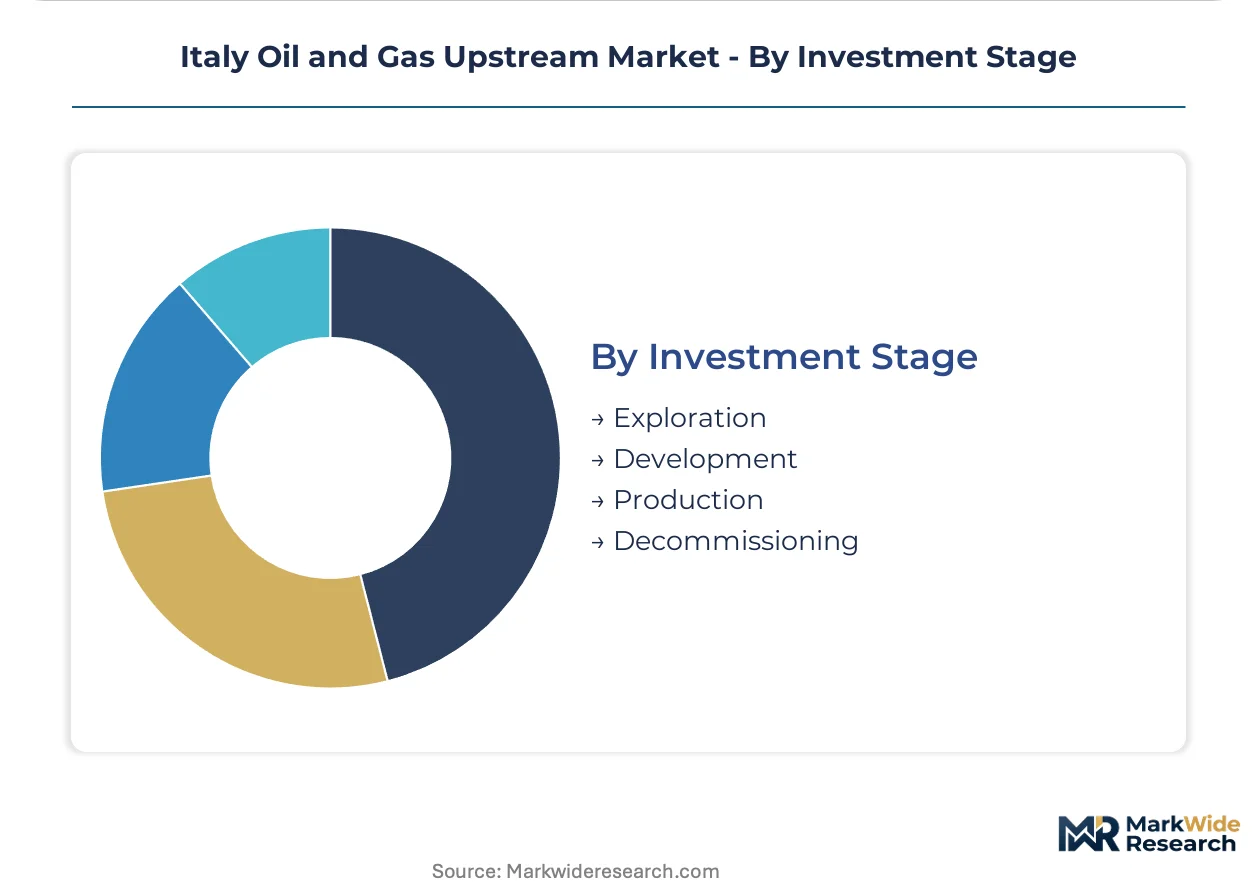
Investment Stage:
Maturity-based capital allocation reflects Italy's upstream lifecycle, with late-stage spending overtaking greenfield exploration as decommissioning liabilities crystallize.
- Production:Sustaining capital dominates Italy's upstream investment as operators maintain output from Adriatic gas fields and Basilicata oil hubs. Platform electrification and methane monitoring retrofits absorb growing maintenance budgets.
- Decommissioning:Plug-and-abandonment obligations for Sicily Channel assets are accelerating reserve fund contributions, diverting free cash flow from new exploration. Regulatory mandates for site restoration and platform removal are tightening liability recognition timelines.
- Exploration:Seismic imaging and licensing round participation target deeper Apennine carbonate reservoirs with limited recent commercial success.
- Development:Field construction and facility installation concentrate in Adriatic offshore provinces with pipeline connectivity to mainland demand centers.
Capital deployment concentrates in Production; Decommissioning shows the steepest expansion trajectory as legacy asset liabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Val d'Agri oil hub in Basilicata functions as Italy's primary tax-advantaged production zone, concentrating upstream investment and specialized service contracting across southern Apennine exploration blocks.
Basilicata
Eni SpA operates the Val d'Agri hub where enhanced oil recovery capex escalates to counter natural decline rates. The National Energy and Climate Plan mandates methane intensity cuts, redirecting capital toward flare gas recovery retrofits. The Viggiano industrial cluster hosts automated monitoring infrastructure deployment ahead of contractual deadlines.
Sicily
TotalEnergies sustains output from mature Sicily Channel assets while accelerating plug-and-abandonment reserve funding. EU methane regulation and decommissioning liability timelines compress free cash flow available for new exploration. The Gela petrochemical corridor anchors offshore service logistics and platform maintenance operations.
Adriatic Offshore
Natural gas offtake to power generation utilities drives drilling demand across Eni's Adriatic concessions. The F-Gas Regulation mandates refrigeration system upgrades during rig mobilization, extending contract scopes and compliance costs. The Ravenna port cluster supports subsea engineering and offshore construction activity.
Po Valley
Shallow onshore recompletions attract independent producers with specialized artificial lift expertise for low-capex reactivation targets. The National Recovery and Resilience Plan channels investment toward mature field revitalization. The Milan metropolitan area anchors technical services and upstream financing operations.
Ionian Sea
Carbonate formation exploration targets deeper Apennine reservoirs using advanced seismic imaging and directional drilling capabilities. Integrated service contracting bundles subsurface risk transfer to contractors under single-source agreements. The Taranto industrial zone supports offshore logistics and platform fabrication.
Italy Oil and Gas Upstream Market Competitive Landscape
Top-tier vendors anchor integrated exploration-to-production structures, while specialized service contractors compete for discrete engineering scopes. The market exhibits tiered consolidation around national oil companies with offshore portfolios, mid-tier international majors managing mature asset decline, and independent operators targeting marginal onshore recompletions. Strategic archetypes include integrated majors with bundled risk-transfer contracts, subsea engineering specialists with deepwater capabilities, and independent producers with artificial lift expertise. Competitive moves center on integrated service contracting to transfer subsurface risk and platform electrification partnerships to meet emissions benchmarks.
Among Italy-based operators, Eni SpA and Edison SpA exemplify the integrated major archetype with Adriatic-to-Sicily concession portfolios. Saipem SpA occupies a position within the specialized contractor tier, representing subsea engineering capabilities. These three entities anchor the competitive structure while international majors including TotalEnergies, Shell Plc, and ExxonMobil sit within the mature asset management segment, navigating decommissioning obligations and emissions retrofit requirements across Sicilian and Adriatic holdings.
| Leading Market Players |
|---|
| Eni SpA |
| Edison SpA |
| Saipem SpA |
| TotalEnergies |
| Shell Plc |
| ExxonMobil |
| BP |
| Chevron |
| Eni Sustainable Mobility |
| Others |
Supply & Pricing Matrix
Sovereign-backed producers anchor Italy's upstream supply base, with Eni SpA's integrated concession portfolio conferring procurement leverage that compresses service contractor margins while insulating field development costs from spot volatility. National production-sharing contracts tether pricing discipline to methane intensity benchmarks, forcing operators to internalize compliance premiums or sacrifice licensing eligibility.
Pricing Analysis
Premium pricing attaches to short-lead-time mobilization of specialized jack-up rigs for Adriatic drilling campaigns, while spot-rate discounts emerge for idle semi-submersible capacity during seasonal demand troughs. Contract-based long-term offtake structures dominate, with price differentiation resting on F-Gas Regulation compliance certification and bundled emissions monitoring service tiers. Cost compression in standard drilling packages intensifies as Saipem and international contractors compete for Eni's integrated service awards. Independent producers in the Po Valley exhibit highest price sensitivity due to marginal field economics, whereas integrated majors absorb premium tiers for guaranteed production outcomes.
Supply Chain Analysis
Direct-to-operator channels handle integrated majors' bundled procurement demand, while discrete equipment vendors serve independent recompletion programs through Ravenna and Taranto port distributors. Manufacturing concentration centers on Italy, Norway, and the Netherlands for subsea processing hardware and artificial lift systems. Raw material dependencies include specialized alloy forgings for high-pressure wellheads, fiber-optic sensing cable, and modular platform electrification components. Single-source vulnerability concentrates in deepwater drilling contractor talent pools. Distribution runs through Adriatic port clusters with pipeline connectivity to mainland demand centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's upstream sector functions as a vertical-integration race where control over subsea engineering capability and emissions-compliant production systems determines margin capture. Players are pursuing backward integration into specialized drilling and completions expertise to reduce contractor dependency.
For Market Incumbents: Cement Adriatic gas field dominance through captive investment in platform electrification partnerships that meet EU methane regulation benchmarks ahead of contractual deadlines. Acquire distressed Sicilian decommissioning liabilities to consolidate mature asset service relationships and block entrant access to Gela corridor logistics infrastructure. For New Entrants and Emerging Players: Begin with Po Valley shallow recompletions where artificial lift specialization commands premium pricing from independents lacking in-house engineering. Target Basilicata flare gas recovery retrofit demand as the most penetrable segment, leveraging modular equipment packages and rapid deployment capabilities against Eni's integrated contracting preference. For Investors and Strategic Acquirers: Distressed-cycle entries favor subsea engineering specialists with Adriatic track records and F-Gas Regulation compliance certification as Sicilian decommissioning obligations strain operator balance sheets. Long-term viability hinges on dual-revenue stream positioning across production services and carbon capture infrastructure deployment. Monitor EU taxonomy transitional criteria revisions as the critical inflection signal for natural gas project financing availability.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Electrification Partnership | Eni's Adriatic concessions achieve near-zero operational emissions aligned with National Energy and Climate Plan methane benchmarks. |
| Integrated Service Contracting | Single-source agreements transfer subsurface risk from operators to Saipem and specialized contractors across Ionian exploration blocks. |
| Decommissioning Liability Consolidation | Accelerated reserve funding for Sicily Channel plug-and-abandonment obligations diverts capital from new exploration drilling. |
| Carbon Capture Infrastructure Deployment | National Recovery and Resilience Plan capital repurposes depleted Basilicata gas fields for CO2 sequestration services. |
| Po Valley Field Reactivation | Low-capex recompletion programs attract independent producers with specialized artificial lift expertise for marginal onshore targets. |
Research Methodology
Independent corroboration across upstream operations executives, subsea engineering contractors, and Ministry of Environment and Energy Security licensing officials underwrites the qualitative findings. Primary interviews with drilling services procurement leads at integrated majors, reservoir management specialists at Basilicata field operators, and port logistics coordinators at Ravenna and Taranto industrial zones combined with secondary validation. Secondary sources include EU methane regulation implementation filings, National Energy and Climate Plan progress reports, ENI and Saipem SEC disclosures, and Adriatic licensing round documentation. Bottom-up field-level capex tracking and top-down national production forecasts were triangulated to anchor volume and value estimates.
Rate-of-change decomposition across service type, technology tier, end user category, and investment stage segmentation dimensions structured the analytical framework. CAGRs were derived from production decline curve analysis, regulatory compliance cost trajectories, and power generation demand elasticity assumptions. Forecast inputs incorporated F-Gas Regulation implementation timelines, EU taxonomy transitional criteria evolution, and electrification technology cost curves throughout the projection horizon.
Underlying measurement precision varies by segment; Production Services and Seismic Imaging carry tighter precision due to visible contracting activity, while Exploration and Decommissioning estimates reflect greater assumption dependency. Forecasts reflect documented assumptions regarding methane regulation enforcement intensity and institutional investor sustainability screening thresholds. Periodic stress-testing of base assumptions is recommended against EU Green Deal policy acceleration or abrupt taxonomy criteria revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Canada LNG Bunkering Market
Oil & Gas
Colombia Oil and Gas Midstream Market
Oil & Gas
North America Oil and Gas Storage Tank Market
Oil & Gas
Downhole Tools Market
Oil & Gas
Bunker Liners Market
Oil & Gas
Oil and Gas Data Monetization Market
Oil & Gas
India Oil and Gas Midstream Market
Oil & Gas
Asia-Pacific Intelligent Pigging Market
Oil & Gas
Norway Oil and Gas Upstream Market
Oil & Gas
Middle East and Africa Drill Collar Market
Oil & Gas
Nigeria Oil and Gas Market
Oil & Gas
Well Intervention Service Market
Oil & Gas
North America Natural Gas Market
Oil & Gas
South America Oil and Gas Storage Tank Market
Oil & Gas
Mud Mixers Market
Oil & Gas
Libya Oil and Gas Midstream Market