
 Zonal Isolation Market | 2026-2036
Zonal Isolation Market Size, Share, and Industry Trends Forecast 2026-2036
Zonal Isolation Market Analysis
Polymer-based sealant formulations is shifting economics across the zonal isolation product stack, displacing conventional Portland cement in high-temperature wells where thermal cycling degrades traditional bonds. Halliburton Company leverages its integrated well construction portfolio to anchor premium service contracts in the Gulf of Mexico. Baker Hughes Company competes through proprietary expandable steel packer architectures that sustain pressure ratings above standard elastomer alternatives. Schlumberger Ltd. dominates digital zonal isolation workflows, combining real-time downhole diagnostics with automated placement systems.
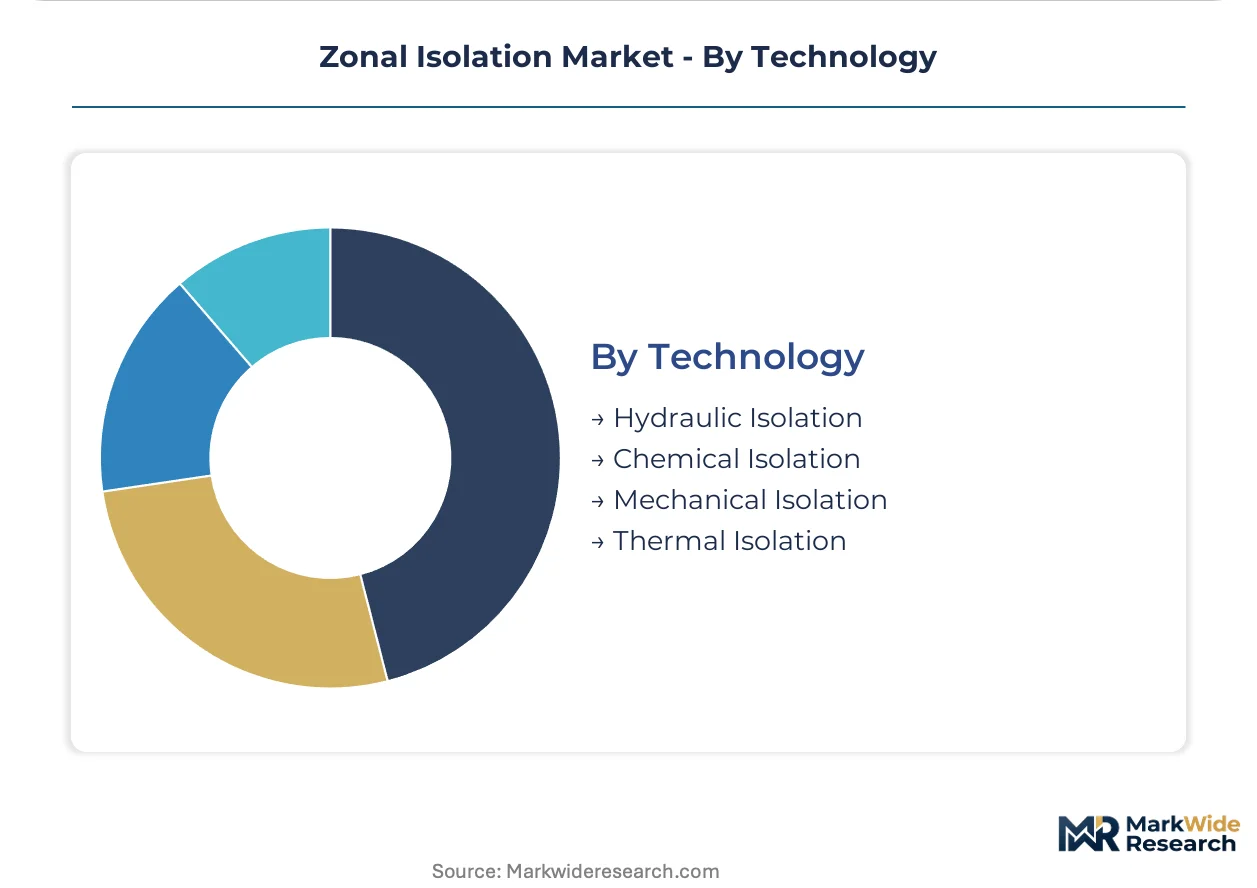
Zonal isolation encompasses engineered barrier systems—typically mechanical packers, cement sheaths, chemical sealants, or hybrid combinations—designed to prevent fluid communication between distinct reservoir zones, with specifications often requiring pressure integrity above 10,000 psi and temperature tolerance exceeding 150°C in deepwater applications. Packers and sealants command the largest share of product-type revenue, though mechanical plugs represent the fastest-growing category as operators prioritize rigless intervention economics. Hydraulic isolation technology leads deployment volumes, while chemical isolation systems capture expanding margin pools in unconventional reservoirs where cement bond failures recur.
The US Bureau of Safety and Environmental Enforcement mandates mechanical barriers plus cement verification for offshore well construction, compelling service providers to certify dual-barrier configurations. Norway's Petroleum Safety Authority and Brazil's National Petroleum Agency enforce comparable well integrity standards that restrict market access to technologies passing prescribed pressure-testing protocols. Stakeholders must monitor regulatory divergence between prescriptive barrier-count rules and performance-based risk frameworks, as this tension will determine R&D allocation between conventional cement systems and next-generation sealant chemistries.
Market Dynamics
Deepwater operators are accelerating material substitution from conventional Portland cement to engineered polymer sealants as pre-salt formations in Brazil and high-temperature Gulf of Mexico reservoirs expose the thermal cycling vulnerabilities of traditional barrier systems.
Growth Catalysts
- US Bureau of Safety and Environmental Enforcement mandates:Mechanical barrier plus cement verification requirements for offshore construction compel dual-barrier technology adoption across Gulf of Mexico drilling programs.
- Pre-salt development:Brazil's subsalt geological formations demand specialized high-pressure, high-temperature isolation systems that conventional cement cannot reliably deliver.
- Expandable steel packers:These architectures sustain pressure ratings above elastomer alternatives, enabling longer well lifespans in thermal recovery operations.
Market Restraints
- Specialized polymer feedstock concentration:Engineered sealant precursors source from limited chemical manufacturing clusters in Texas and Louisiana, creating input cost volatility.
- Norway Petroleum Safety Authority prescriptive rules:Barrier-count requirements restrict field trial flexibility for novel sealant chemistries, extending certification timelines.
- Mechanical plug substitution threat:Rigless intervention economics favor plug-based abandonment over permanent cement barriers in mature well stock.
Strategic Opportunities
- Digital zonal isolation workflows:Real-time downhole diagnostics converging with automated placement systems create service differentiation in premium offshore contracts.
- Unconventional reservoir chemical isolation:Cement bond failure recurrence in shale formations opens margin pools for self-healing sealant technologies.
- Brazil National Petroleum Agency performance frameworks:Risk-based well integrity standards reward validated next-generation barrier systems with accelerated permitting.
Industry Challenges
- HPHT certification timelines:Pressure-testing protocols above 10,000 psi and 150°C tolerance require 18-24 month validation cycles, delaying commercialization.
- Legacy well integration complexity:Retrofitting engineered sealants into existing cement sheaths demands proprietary bonding agents with uncertain long-term degradation profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zonal Isolation Market |
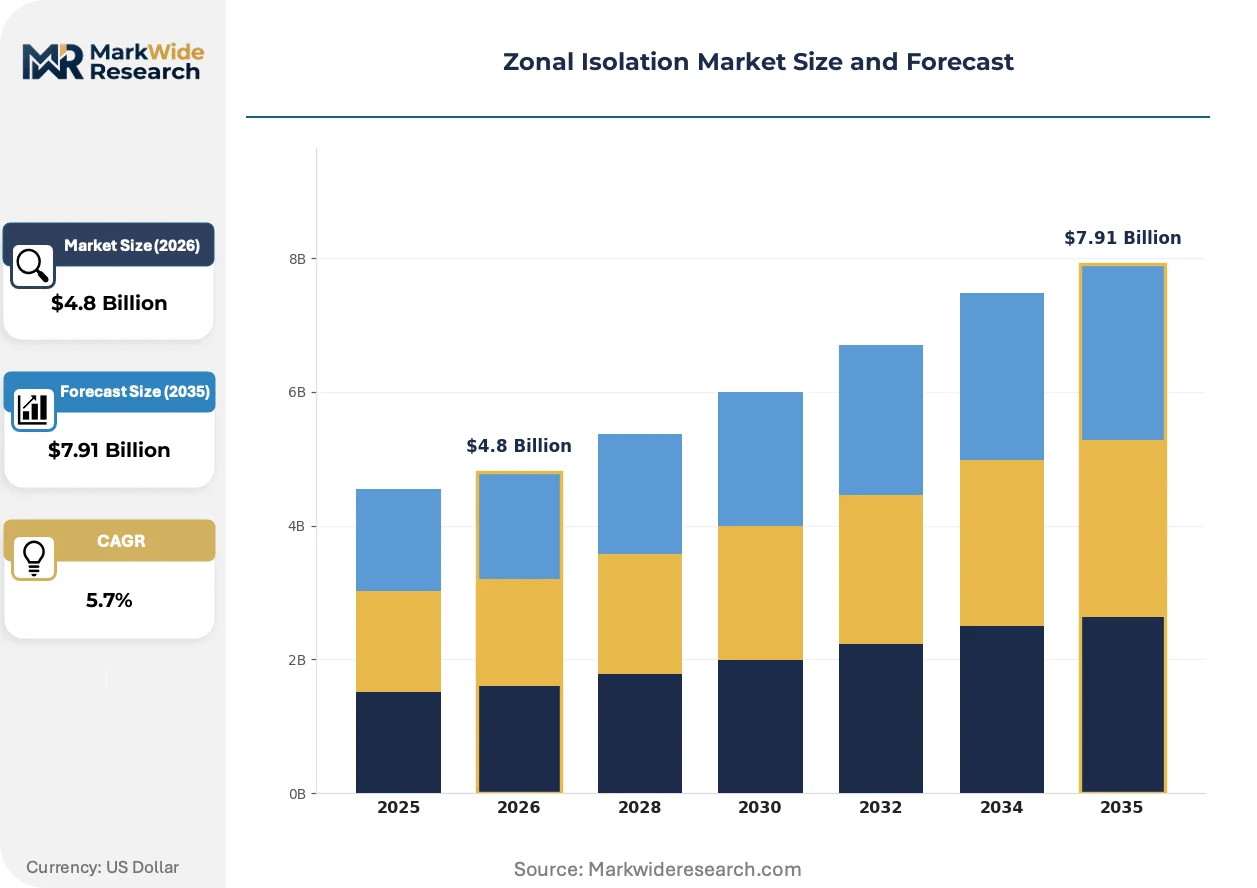
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Packers, Sealants, Cement, Mechanical Plugs Application: Oil Extraction, Gas Production, Water Injection, Wastewater Management End User: Oil & Gas Companies, Service Providers, Engineers, Government Agencies Technology: Hydraulic Isolation, Chemical Isolation, Mechanical Isolation, Thermal Isolation |
| Companies Covered | Schlumberger Ltd., Halliburton Company, Baker Hughes Company, Weatherford International plc, TechnipFMC plc, NOV Inc., Welltec, TAM International, Expro Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zonal Isolation Market Emerging Trajectories
Material science advances and regulatory verification requirements are compressing the technology lifecycle for barrier systems, forcing faster iteration between laboratory validation and field deployment.
Self-healing polymer sealant chemistry is modularizing the traditional cement-versus-mechanical binary in zonal isolation design. Operators in the Permian Basin and Bakken formations are piloting these systems for thermal cycling environments where conventional bonds degrade within 24 months. The technology is modularizing service provider offerings into tiered barrier packages rather than single-product specifications.
REACH substance authorization protocols in Europe are restricting certain epoxy-based sealant precursors used in North Sea applications. Manufacturers must reformulate with alternative chemistries or secure costly authorization exemptions. Subsea contractors serving Norwegian and UK continental shelf developments are absorbing compliance costs through premium pricing for certified low-toxicity barrier systems.
Integrated service contracts now bundle placement, verification, and remediation liability under single-provider arrangements. National oil companies in Brazil and Mexico are displacing fragmented procurement of cementing, logging, and mechanical isolation services. This consolidation is most visible in deepwater tender rounds where operators award decade-long well integrity partnerships to integrated technology providers.
Zonal Isolation Market Segmentation
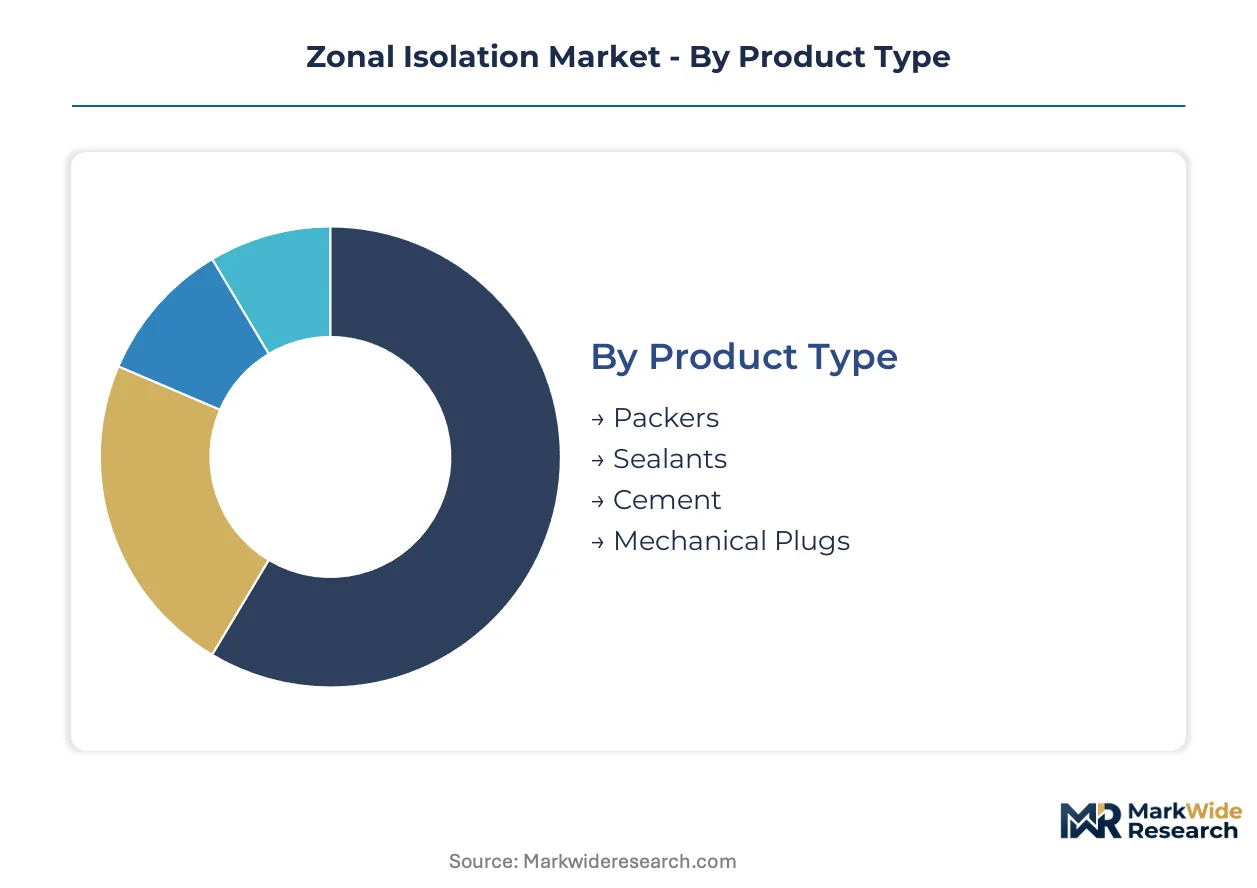
Zonal isolation procurement splits across four structural dimensions. Each category carries distinct certification burdens from regulators like the US Bureau of Safety and Environmental Enforcement, Brazil's National Petroleum Agency, and Norway's Petroleum Safety Authority.
Product Type:
Packers and sealants face the heaviest validation requirements under US Bureau of Safety and Environmental Enforcement dual-barrier mandates, while mechanical plugs navigate faster field trial pathways in mature basin abandonment programs.
- Packers:Mechanical barriers constructed from elastomer or expandable steel architectures that sustain pressure ratings above 10,000 psi in deepwater applications. Gulf of Mexico operators specify these for pre-salt and high-temperature formations where thermal cycling degrades conventional bonds. Dual-barrier certification from the US Bureau of Safety and Environmental Enforcement extends deployment timelines but locks in premium contract terms.
- Sealants:Engineered polymer or epoxy formulations displacing Portland cement in wells exceeding 150°C tolerance thresholds. Brazil's pre-salt developments concentrate demand for these systems, though REACH substance authorization protocols in Europe restrict certain epoxy-based precursors used in North Sea fields.
- Cement:Conventional Portland-based sheaths still dominate shallow-water and onshore construction where thermal stress remains moderate.
- Mechanical Plugs:Rig-deployed barriers for well abandonment and zone isolation without cement placement, gaining traction in mature Permian Basin well stock.
Leading the category by volume: Packers. Growing fastest: Mechanical Plugs.
Application:
Cost tiers stratify sharply across these four use cases, with deepwater oil extraction commanding 3-4x the per-well barrier investment of onshore wastewater management.
- Oil Extraction:Deepwater and pre-salt developments in Brazil and the Gulf of Mexico drive specification for HPHT-certified packer and sealant systems. US Bureau of Safety and Environmental Enforcement mechanical barrier mandates compound with Brazil National Petroleum Agency performance frameworks to enforce dual-redundancy designs.
- Gas Production:Sour gas formations in the Middle East and North Sea require hydrogen sulfide-resistant sealant chemistries with specialized polymer feedstocks sourced from Texas and Louisiana manufacturing clusters.
- Water Injection:Secondary recovery operations in mature fields favor lower-cost cement-based isolation with periodic mechanical plug remediation.
- Wastewater Management:Produced water disposal wells accept basic cement barriers with minimal regulatory certification overhead.
Highest margin concentration: Oil Extraction. Fastest volume expansion: Gas Production.
End User:
Customer type determines procurement structure, with national oil companies consolidating toward integrated decade-long well integrity partnerships while independents fragment across specialized service tiers.
- Oil & Gas Companies:Supermajors and national oil companies in Brazil and Mexico now bundle placement, verification, and remediation liability under single-provider arrangements, displacing fragmented procurement of cementing, logging, and mechanical isolation services.
- Service Providers:Integrated well construction portfolios anchor premium contract positions, though specialized packer manufacturers compete through proprietary expandable steel architectures.
- Engineers:Design consultants specify barrier configurations but rarely hold procurement authority in deepwater tender rounds.
- Government Agencies:Regulatory bodies including Norway's Petroleum Safety Authority and Brazil's National Petroleum Agency set barrier-count or performance-based standards without direct technology acquisition.
Dominant procurement authority: Oil & Gas Companies. Fastest-contracting segment: Service Providers.
Technology:
Maturity curves diverge across these four isolation approaches, with hydraulic systems representing installed base dominance while chemical isolation climbs the steepest adoption trajectory in unconventional reservoirs.
- Hydraulic Isolation:Conventional packer-based pressure sealing using wellbore fluid mechanics, still commanding majority deployment volumes across offshore and onshore basins.
- Chemical Isolation:Self-healing polymer sealants piloted in Permian Basin and Bakken thermal cycling environments where conventional cement bonds degrade within 24 months, capturing expanding margin pools as cement bond failure recurrence drives material substitution.
- Mechanical Isolation:Expandable steel and elastomer packer systems with established HPHT certification pathways but 18-24 month validation cycles above 10,000 psi.
- Thermal Isolation:Specialized barriers for steam-assisted gravity drainage and other thermal recovery operations, concentrated in Canadian oil sands and California heavy oil fields.
Installed base leader: Hydraulic Isolation. Steepest expansion trajectory: Chemical Isolation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deepwater oil extraction concentrates demand across four critical basins where pre-salt formations and high-pressure reservoirs mandate specialized isolation technologies. Operators in these jurisdictions face divergent regulatory frameworks that shape procurement patterns and certification timelines.
Brazil
Pre-salt development programs off the coast of Rio de Janeiro and São Paulo drive specification for high-pressure, high-temperature packer systems. The National Petroleum Agency enforces performance-based well integrity standards that reward validated next-generation barrier systems with accelerated permitting. The Santos Basin cluster anchors service provider partnerships for decade-long well integrity contracts.
United States
Gulf of Mexico deepwater drilling programs expand adoption of dual-barrier configurations to manage reservoir pressure. The Bureau of Safety and Environmental Enforcement mandates mechanical barriers plus cement verification for offshore construction. Houston and Lafayette manufacturing clusters supply engineered polymer sealant precursors to regional operators.
Norway
North Sea sour gas formations require hydrogen sulfide-resistant sealant chemistries with specialized polymer feedstocks. The Petroleum Safety Authority imposes prescriptive barrier-count requirements that restrict field trial flexibility for novel sealant chemistries. Stavanger and Bergen serve as procurement hubs for integrated well construction services.
Saudi Arabia
Gas production from carbonate reservoirs drives demand for expandable steel packer architectures that sustain pressure ratings above elastomer alternatives. The national oil company consolidates procurement toward single-provider arrangements bundling placement, verification, and remediation liability. The Eastern Province concentration hosts technical service centers for HPHT certification protocols.
United Kingdom
Mature basin abandonment programs favor rigless intervention economics and mechanical plug-based solutions over permanent cement barriers. REACH substance authorization protocols restrict certain epoxy-based sealant precursors used in North Sea applications. Aberdeen functions as the primary logistics node for subsea contractors serving UK continental shelf developments.
Zonal Isolation Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated service providers commanding premium positions in deepwater tenders while specialized packer fabricators compete on proprietary architectures. The vendor base organizes into three strategic archetypes: full-service well construction portfolios, focused mechanical isolation technologies, and digital workflow integrators. Dominant competitive moves include vertical integration into polymer feedstock manufacturing and strategic partnerships with national oil companies for multi-year framework agreements.
Within the integrated service tier, Schlumberger Ltd., Halliburton Company, and Baker Hughes Company exemplify contrasting approaches to technology positioning. Schlumberger Ltd. occupies a position emphasizing digital zonal isolation workflows combining real-time downhole diagnostics with automated placement systems. Halliburton Company anchors premium contract positions through its integrated well construction portfolio spanning placement, verification, and remediation liability. Baker Hughes Company represents the focused mechanical isolation archetype through proprietary expandable steel packer architectures.
| Leading Market Players |
|---|
| Schlumberger Ltd. |
| Halliburton Company |
| Baker Hughes Company |
| Weatherford International plc |
| TechnipFMC plc |
| NOV Inc. |
| Welltec |
| TAM International |
| Expro Group |
| Others |
Supply Flow & Price Mechanics
Dual-barrier certification mandates from the US Bureau of Safety and Environmental Enforcement compel service providers to absorb extended validation costs, forcing supply chains to cluster around Houston and Lafayette manufacturing hubs where polymer precursor synthesis can achieve scale. This procurement concentration grants integrated providers pricing power in premium offshore contracts while squeezing margins for specialized packer fabricators lacking captive feedstock production.
Pricing Analysis
Volume-margin splits separate commodity cement sheaths from engineered sealant systems. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales bundling intensity. Pricing pressure stems from rigless intervention economics favoring mechanical plugs in mature basin abandonment programs. National oil companies show lowest price sensitivity in deepwater tender rounds, while independent operators in the Permian Basin drive cost compression through competitive bidding.
Supply Chain Analysis
Single-source vulnerability sits with Texas and Louisiana chemical manufacturing clusters supplying specialized polymer feedstocks for high-temperature sealant formulations. Raw material dependencies include epoxy precursors, expandable steel alloys, and hydrogen sulfide-resistant elastomer compounds. Tariff exposure on European REACH-compliant chemistries elevates input costs for North Sea applications. Distribution runs through integrated service providers bundling placement, verification, and remediation liability under single-provider arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over polymer precursor manufacturing determines margin capture. Players are pursuing captive supply of engineered sealant feedstocks to lock in cost positions against volatile specialty chemical markets.
For Market Incumbents: Deploy digital workflow integration to anchor premium contract positions in Brazil and Gulf of Mexico deepwater tenders. Halliburton and Schlumberger exemplify this path through real-time diagnostics bundling. Counter the threat from rigless mechanical plug substitution by acquiring specialized packer fabricators with proven HPHT certification records. Cement verification mandates from the US Bureau of Safety and Environmental Enforcement create defensive moats for providers with integrated placement-remediation portfolios. For New Entrants and Emerging Players: Remote monitoring and predictive analytics platforms offer the most penetrable entry vector for unconventional reservoir operators in the Permian Basin and Bakken formations. Target chemical isolation pilots where cement bond failure recurrence opens margin pools for self-healing sealant technologies. A direct-to-operator digital sales model bypasses incumbent procurement lock-in with national oil companies. For Investors and Strategic Acquirers: The window for entry favors specialized packer manufacturers with validated expandable steel architectures and accelerated HPHT certification pathways. Long-term viability hinges on exposure to Brazil's pre-salt development programs and US Gulf of Mexico dual-barrier mandates. Watch for inflection signals in National Petroleum Agency permitting velocity for next-generation barrier systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstock Manufacturing | Captive supply of epoxy precursors from Texas chemical clusters insulates margin compression from input volatility. |
| Digital Zonal Isolation Platform Development | Real-time downhole diagnostics convergence with automated placement commands premium pricing in offshore contracts. |
| HPHT Certification Acceleration Program | Reduced 18-24 month validation cycles unlock faster commercialization for pre-salt and deepwater applications. |
| Integrated Well Integrity Partnership Structuring | Decade-long framework agreements with Brazil's national oil company displace fragmented procurement across service tiers. |
| Self-Healing Sealant Chemistry R&D Expansion | Thermal cycling resilience in Permian Basin shale formations captures margin pools from recurring cement bond failures. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with drilling engineers, well integrity managers at national oil companies, procurement leads at integrated service providers, and regulatory compliance officers at the US Bureau of Safety and Environmental Enforcement supplied operational validation. Secondary sources included Norway Petroleum Safety Authority barrier-count directives, Brazil National Petroleum Agency performance framework documentation, and SEC 10-K disclosures from listed service providers. Bottom-up well-count modeling and top-down market sizing triangulated volume estimates.
Segment-level granularity modeled product type at packer/sealant/cement/plug resolution, application at extraction/production/injection/disposal tiers, and technology across hydraulic/chemical/mechanical/thermal isolation approaches. Geographic splits captured country-specific regulatory clusters rather than continental aggregates. CAGRs derived from polynomial trend fitting across historical deployment data and projected well construction schedules. Industry-specific inputs included pre-salt development timelines, REACH substance authorization restriction trajectories, and rigless intervention adoption curves.
The model holds under stable regulatory enforcement intensity and continued deepwater capital commitment; deviation in barrier-count rule relaxation or abrupt offshore drilling moratoria would shift trajectory. Forecasts reflect documented assumptions about certification timeline compression and polymer feedstock supply elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Europe Coiled Tubing Market
Oil & Gas
Oil and Gas Electrification Market
Oil & Gas
Iraq Oil and Gas Market
Oil & Gas
Natural Gas Market
Oil & Gas
Global Well Logging Equipment Market
Oil & Gas
Oil Storage Terminal Market
Oil & Gas
Oilwell Spacer Fluids Market
Oil & Gas
India Artificial Lift Systems Market
Oil & Gas
Russia Oil and Gas EPC Market
Oil & Gas
Modular Refinery Market
Oil & Gas
Kuwait & Iraq Oilfield Chemicals Market
Oil & Gas
Asia Pacific Oil Storage Tank Service Market
Oil & Gas
Oriented Perforating System Market
Oil & Gas
Downhole Motor Market
Oil & Gas
Digital Oil Field Technology Market
Oil & Gas
Africa Oil Country Tubular Goods (OCTG) Market