
 Asia Pacific Upstream Oil and Gas Services Market | 2026-2036
Asia Pacific Upstream Oil and Gas Services Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Upstream Oil and Gas Services Market Outlook
China's dual carbon goals is restructuring capital allocation across the Asia Pacific upstream services sector, elevating the cost of entry for carbon-intensive drilling fleets. Schlumberger leverages integrated well construction platforms to anchor its position in Australia's offshore frontier basins. Baker Hughes differentiates through turbomachinery and compression systems that sustain production uptime across Southeast Asia's mature fields. Halliburton dominates hydraulic fracturing technology leadership in China's unconventional shale plays.
Asia Pacific upstream oil and gas services encompass the technical execution, equipment provision, and reservoir engineering required to locate, drill, complete, and maintain hydrocarbon-producing wells, typically operating at reservoir depths from 1,500 to 5,000 meters with bottom-hole temperatures exceeding 150°C in deepwater provinces. The primary commercial purpose is maximizing hydrocarbon recovery rates while minimizing unit production costs across geologically complex basins. Drilling services command the largest share of current expenditure across the region, reflecting sustained deepwater rig demand in Myanmar's offshore concessions and Vietnam's Ca Voi Xanh development. Subsea services represent the fastest-growing category, driven by tieback architectures that reduce topside infrastructure requirements in Australia's Scarborough and Browse basin projects. Seismic imaging technology leads margin pools, as high-density ocean-bottom node surveys command premium pricing for pre-salt and sub-basalt imaging challenges.
China's MEE enforces methane intensity benchmarks that shape equipment procurement standards for domestic operators, while Australia's NOPSEMA mandates well integrity management systems that dictate service provider certification requirements across the Timor Sea. Japan's METI coordinates strategic petroleum reserve policies that influence exploration drilling schedules in adjacent concession areas. Stakeholders must monitor how Indonesia's revised Gross Split PSC terms alter contractor risk-sharing structures and capital deployment timelines.
Market Dynamics
China's dual carbon goals are compressing capital allocation timelines across the Asia Pacific upstream services sector, forcing operators to retire carbon-intensive drilling fleets ahead of depreciation schedules while redirecting investment toward lower-emission extraction architectures.
Growth Catalysts
- Indonesia's PSC Gross Split reforms:The revised production sharing contract framework accelerates contractor capital deployment by reducing bureaucratic approval layers for mature basin redevelopment projects in the Mahakam block.
- Subsea tieback architectures:These systems eliminate topside platform requirements in Australia's Scarborough and Browse deepwater developments, slashing field development costs by half versus conventional fixed-leg structures.
- MEE methane intensity benchmarks:China's environmental ministry mandates are standardizing leak detection equipment procurement across domestic shale plays, creating dedicated service lanes for certified low-emission technology providers.
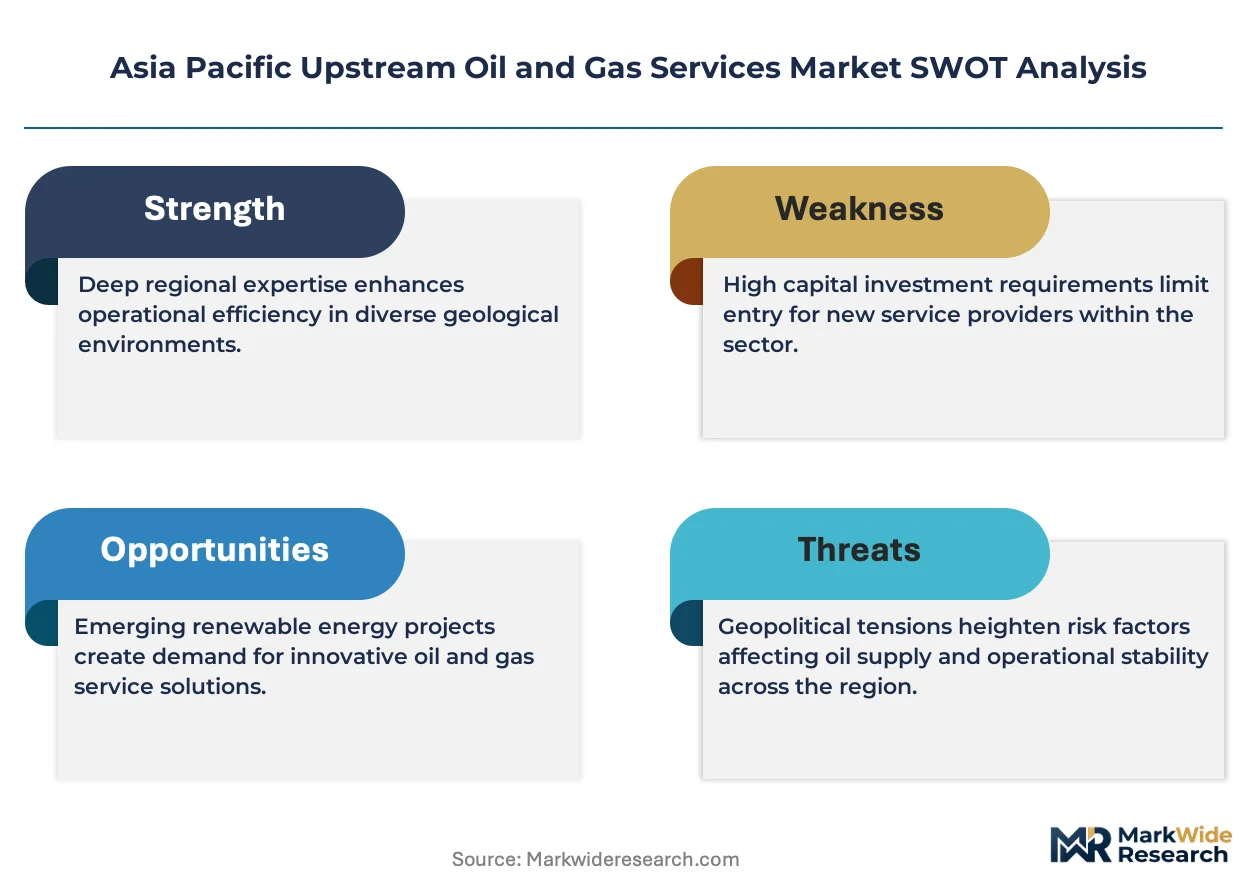
Market Restraints
- Deepwater rig supply concentration:The Asia Pacific floater fleet clusters among Singapore and South Korean shipyard operators, exposing charter rates to single-geography labor disruptions and steel input volatility.
- NOPSEMA well integrity mandates:Australia's offshore safety regulator imposes certification timelines that extend equipment qualification periods by 18-24 months versus Southeast Asian jurisdictions.
- Geothermal substitution pressure:Indonesia's state utility prioritizes geothermal capacity additions in its renewable portfolio standards, diverting exploration capital from frontier hydrocarbon acreage in the Banda Sea.
Strategic Opportunities
- Myanmar's unexplored offshore concessions:The Zawtika and Yetagun field extensions remain underpenetrated by integrated service providers despite proven reservoir analogs to adjacent Thai production.
- CCUS-enabled enhanced oil recovery:Convergence of carbon capture infrastructure with mature field rejuvenation creates hybrid service contracts in Australia's Cooper Basin and China's Shengli oilfield complex.
- Digital twin deployment:Real-time reservoir simulation platforms open new subscription revenue streams as NOCs in Vietnam and Thailand shift from day-rate contracting to performance-linked compensation models.
Industry Challenges
- Subsea controls systems integration:Legacy hydraulic umbilical architectures in Australia's Northwest Shelf fields resist retrofit with all-electric alternatives, forcing parallel maintenance of dual technology stacks.
- HPHT metallurgy certification backlog:Bottom-hole temperature ratings exceeding 200°C in Myanmar's ultra-deepwater blocks outpace qualified domestic welding inspector availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Upstream Oil and Gas Services Market |
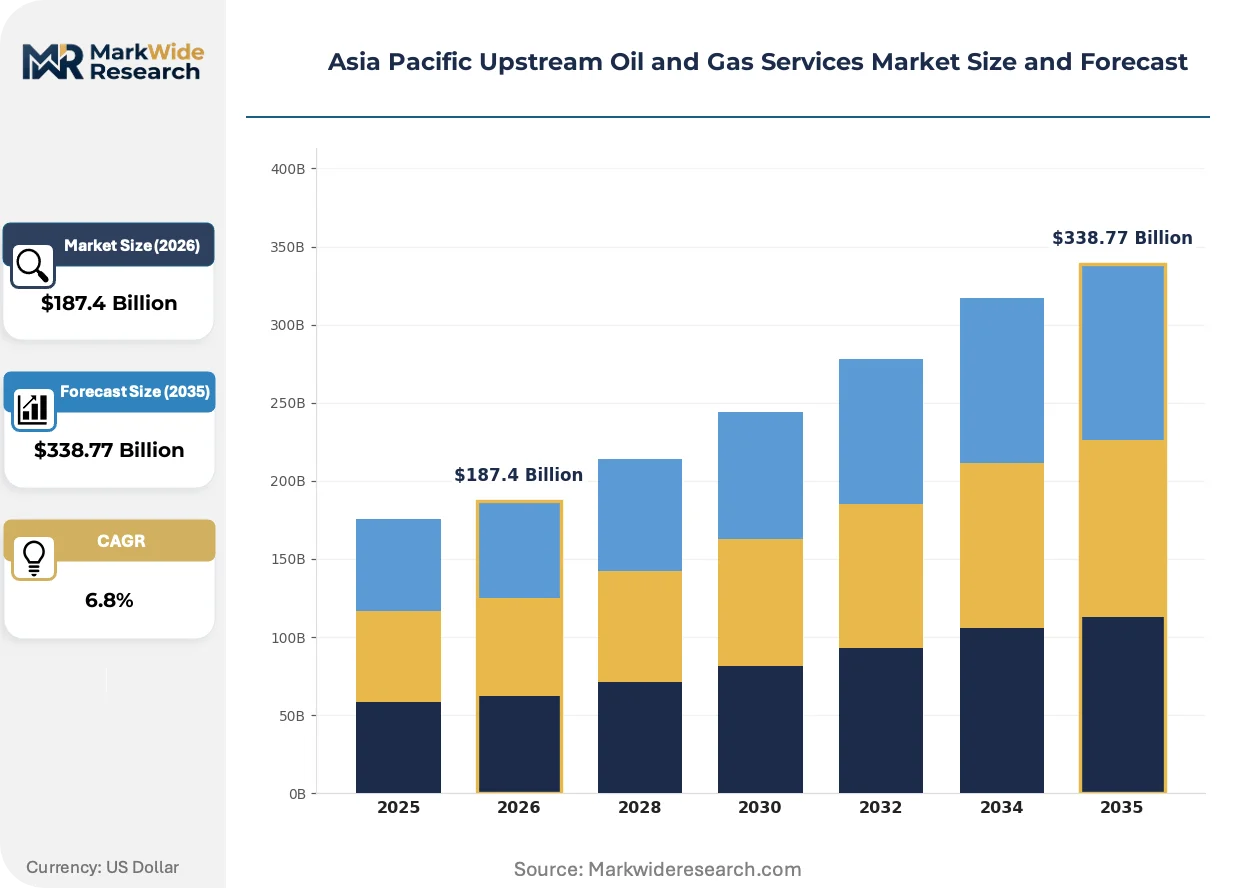
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Drilling, Well Completion, Subsea Services, Production Services Technology: Offshore Technology, Enhanced Oil Recovery, Hydraulic Fracturing, Seismic Imaging End User: Exploration Companies, Production Operators, Contractors, Government Entities Application: Onshore Development, Offshore Development, Reservoir Management, Asset Integrity |
| Companies Covered | Weatherford International, Saipem, Schlumberger, Petrofac, Subsea 7, Halliburton, TechnipFMC, National Oilwell Varco, Baker Hughes, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Upstream Oil and Gas Services Market Strategic Shifts
Electrification of subsea production systems is compressing platform staffing requirements while expanding the addressable market for seabed processing equipment across the region's deepwater frontier basins.
Subsea boosting and multiphase pumping technology is modularizing field development economics in Australia's Browse Basin, where Woodside and Santos are deploying standardized pump skids across multiple tieback developments rather than field-specific engineering. This approach collapses procurement cycles from 36 months to 18 months while enabling batch fabrication at Perth-based integration yards. The technology is modularizing supplier relationships by allowing operators to split contracts between European OEMs and regional fabricators.
China's MEE methane intensity benchmarks are mandating continuous emissions monitoring equipment across all new shale well completions, forcing service providers to integrate optical gas imaging with existing drilling control systems. The regulation compresses allowable leak detection response windows from quarterly to real-time, elevating predictive maintenance software to core contract deliverables. Domestic operators in Sichuan and Xinjiang basins are responding by bundling detection hardware with long-term analytics subscriptions.
Performance-based contracting is displacing day-rate structures in Southeast Asia's mature field services market, with Petronas and Pertamina linking contractor compensation to production uptime guarantees rather than hours worked. This reconfiguration shifts risk allocation toward service providers while demanding integrated asset management capabilities that span subsurface engineering through surface facility maintenance. The model is most visible in Indonesia's Mahakam block redevelopment, where Schlumberger and Halliburton have assumed full field operation accountability.
Asia Pacific Upstream Oil and Gas Services Market Segmentation
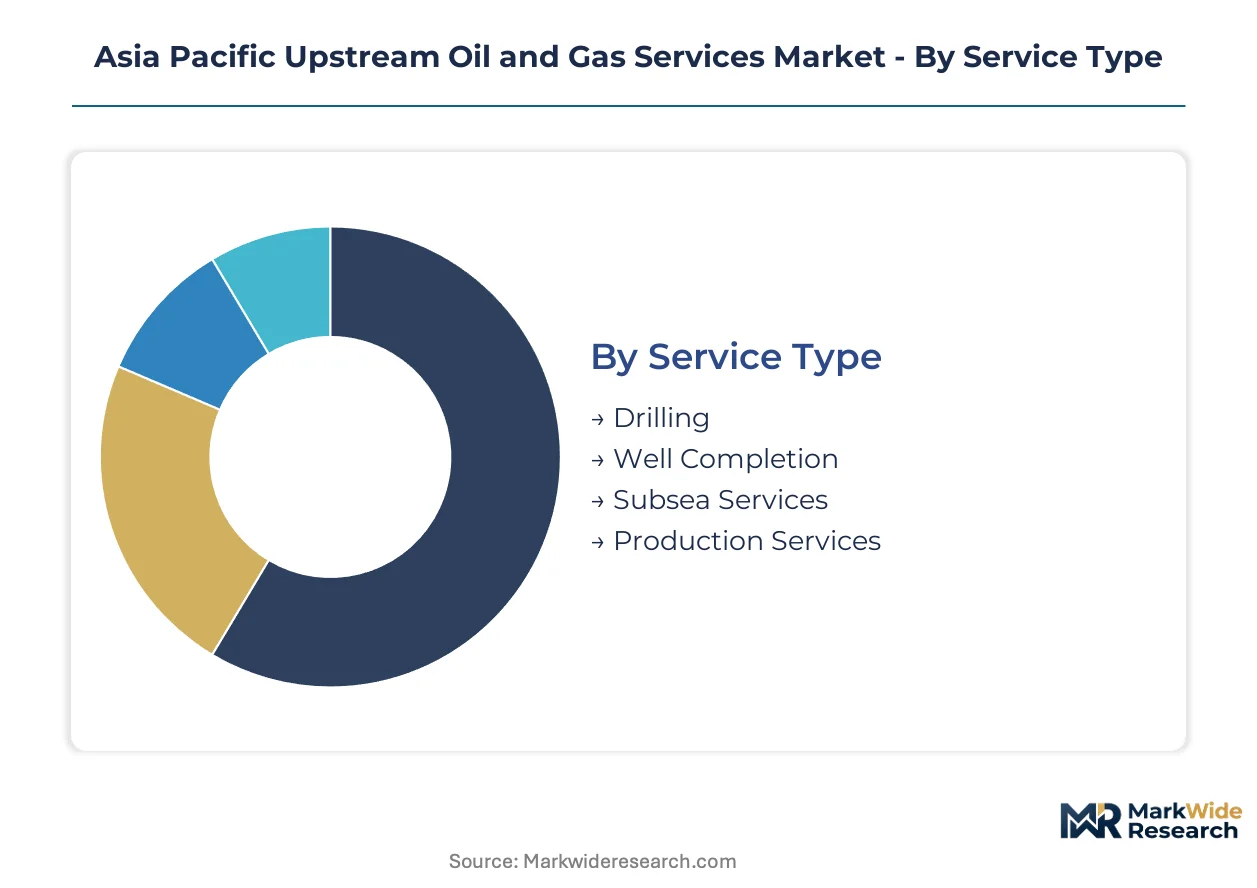
Service differentiation across Asia Pacific upstream operations follows reservoir complexity and water depth rather than uniform standards. Procurement patterns split between integrated packages for frontier basins and modular spot contracts for mature field workovers.
Service Type:
Customization intensity spans from standardized rig mobilization to fully engineered subsea architectures across this category.
- Drilling:Directional drilling assemblies and managed pressure systems dominate expenditure in Myanmar's ultra-deepwater blocks and Vietnam's Ca Voi Xanh development. Day-rate volatility concentrates around Singapore and South Korean floater yards where labor disruptions ripple through charter markets.
- Well Completion:Intelligent completion systems with permanent downhole gauges command premium pricing in Australia's Northwest Shelf high-temperature reservoirs. China's Sichuan shale operators are bundling multi-stage fracturing hardware with real-time pressure monitoring subscriptions.
- Subsea Services:Tieback installation and umbilical maintenance support Australia's Scarborough and Browse basin developments.
- Production Services:Artificial lift optimization and well intervention sustain output from Indonesia's Mahakam block mature fields.
Most installed capacity flows through Drilling. Expansion is steepest in Subsea Services.
Technology:
Technology selection tracks water depth and reservoir pressure gradients rather than operator size or basin maturity.
- Offshore Technology:Floating production systems and subsea processing modules anchor Australia's deepwater frontier developments. Woodside and Santos are deploying standardized pump skids across multiple Browse Basin tiebacks to collapse procurement cycles.
- Enhanced Oil Recovery:CO2 injection and chemical flooding rejuvenate mature fields in Australia's Cooper Basin and China's Shengli complex. CCUS convergence is creating hybrid service contracts that combine carbon capture infrastructure with reservoir pressure maintenance.
- Hydraulic Fracturing:Multi-stage horizontal completions dominate China's unconventional shale plays in Sichuan and Xinjiang basins.
- Seismic Imaging:Ocean-bottom node surveys command premium pricing for pre-salt and sub-basalt imaging challenges off Myanmar and Vietnam.
Revenue concentration sits with Offshore Technology. Technology deployment is climbing fastest in Enhanced Oil Recovery.
End User:
End user procurement sophistication correlates with reserve scale and state ownership structure across the region.
- Exploration Companies:Junior operators and NOC exploration divisions drive frontier basin seismic campaigns in the Banda Sea and Myanmar's unexplored concessions. Capital constraints limit their appetite for integrated service packages.
- Production Operators:Established field developers like Petronas and Pertamina are shifting from day-rate contracting to performance-linked compensation models in Southeast Asia's mature basins.
- Contractors:Engineering and construction firms subcontract specialized well services and subsea installation capacity.
- Government Entities:State reserves agencies and petroleum ministries influence drilling schedules through strategic stockpile policies.
Contract volume aggregates with Production Operators. Procurement reform is advancing most quickly among Exploration Companies.
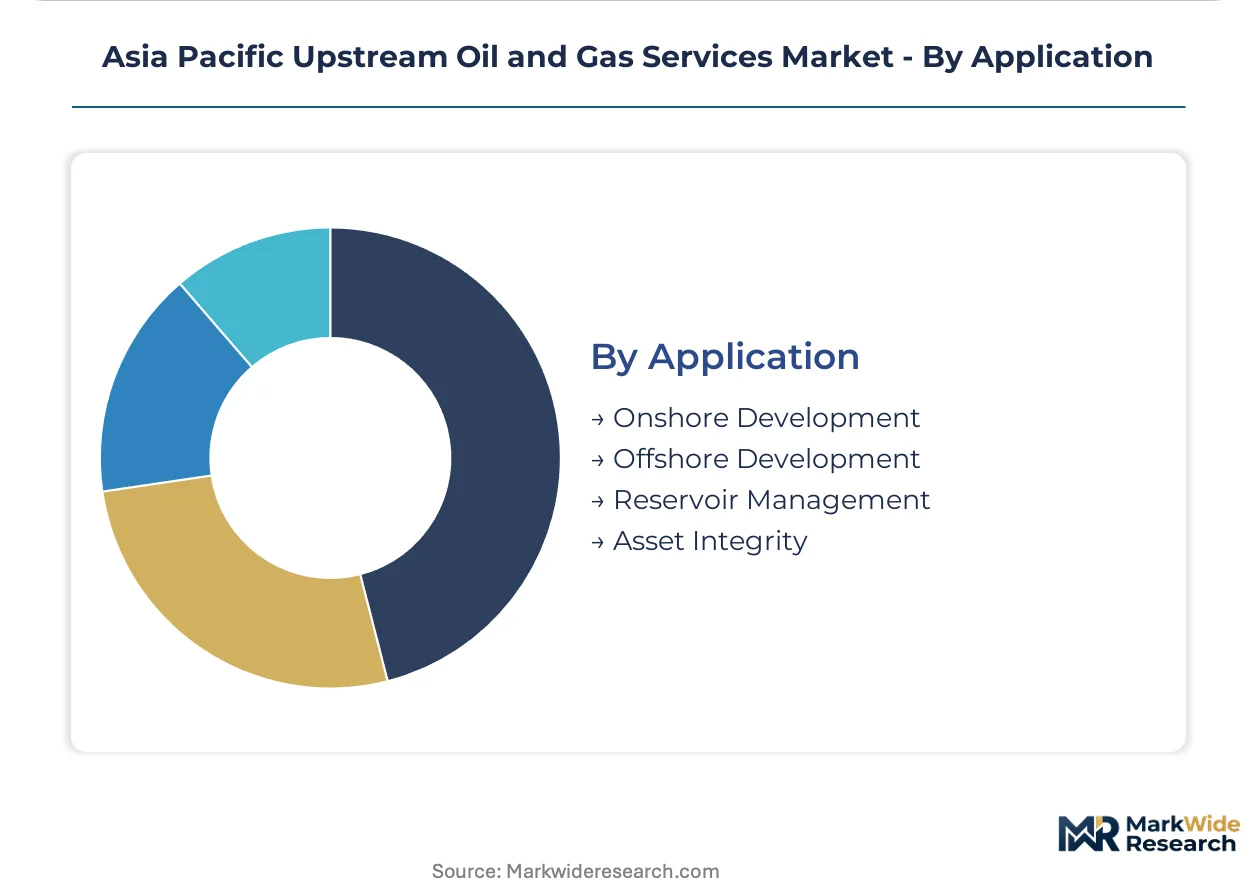
Application:
Application mix reflects the region's offshore tilt and aging infrastructure replacement cycles.
- Onshore Development:Shale fracturing and coalbed methane projects concentrate in China's Sichuan and Xinjiang basins where MEE methane intensity benchmarks mandate continuous emissions monitoring equipment.
- Offshore Development:Deepwater tieback architectures and floating production systems dominate Australia's Scarborough, Browse, and Northwest Shelf projects. Subsea boosting technology is modularizing field development economics across multiple developments.
- Reservoir Management:Digital twin deployment and real-time simulation platforms are opening subscription revenue streams as NOCs shift toward performance-linked contracts.
- Asset Integrity:Well integrity management systems and corrosion monitoring sustain production uptime across Southeast Asia's mature fields under Australia's NOPSEMA certification requirements.
Capital deployment currently favors Offshore Development. Technology uptake is accelerating fastest in Reservoir Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Asia Pacific upstream services industry traces its modern scale to Australia's Northwest Shelf developments of the 1980s, where deepwater production systems first achieved commercial viability at reservoir depths exceeding 1,500 meters.
Australia
Woodside and Santos drive subsea tieback deployments across the Scarborough and Browse basins, where standardized pump skids collapse procurement cycles. NOPSEMA mandates well integrity management systems that extend equipment qualification timelines by 18-24 months versus regional peers. Perth-based integration yards batch-fabricate subsea hardware for multiple concurrent developments.
China
Sinopec and PetroChina redirect capital toward lower-emission extraction architectures in Sichuan and Xinjiang shale plays. MEE methane intensity benchmarks mandate continuous emissions monitoring equipment across all new well completions. Domestic service providers in Sichuan basin bundle detection hardware with long-term analytics subscriptions.
Indonesia
Pertamina accelerates mature field redevelopment in the Mahakam block under revised Gross Split PSC terms that reduce bureaucratic approval layers. The state utility's renewable portfolio standards prioritize geothermal capacity, diverting exploration capital from Banda Sea frontier acreage. Jakarta-headquartered contractors assume full field operation accountability under performance-linked compensation models.
Vietnam
PetroVietnam advances the Ca Voi Xanh deepwater development with directional drilling assemblies and managed pressure systems. The national oil company shifts from day-rate contracting to production uptime guarantees for mature field services. Ho Chi Minh City serves as the procurement hub for seismic campaigns targeting pre-salt imaging challenges.
Myanmar
Myanma Oil and Gas Enterprise holds unexplored offshore concessions at Zawtika and Yetagun field extensions with proven reservoir analogs to adjacent Thai production. The national regulator coordinates strategic petroleum reserve policies that influence exploration drilling schedules. Yangon-based engineering firms subcontract specialized well services for ultra-deepwater blocks where bottom-hole temperatures exceed 200°C.
Asia Pacific Upstream Oil and Gas Services Market Competitive Environment
The competitive structure tilts toward integrated technology providers with full-field operation capabilities. Three tiers have crystallized: global majors with proprietary equipment platforms, regional specialists with fabrication proximity, and digital-native entrants with predictive analytics offerings. Consolidation pressure intensifies as operators bundle services into multi-year performance contracts. Geographic expansion and technology licensing dominate competitive moves, with European OEMs partnering Perth-based fabricators to localize subsea hardware production.
Among the integrated majors, Schlumberger, Baker Hughes, and Halliburton occupy distinct positioning vectors. Schlumberger anchors the well construction and production optimization archetype through integrated platforms deployed across Australia's frontier basins. Baker Hughes exemplifies the turbomachinery and compression systems specialist, sustaining production uptime across Southeast Asia's mature fields. Halliburton sits within the hydraulic fracturing technology leadership tier, dominating China's unconventional shale plays in Sichuan and Xinjiang basins.
| Leading Market Players |
|---|
| Weatherford International |
| Saipem |
| Schlumberger |
| Petrofac |
| Subsea 7 |
| Halliburton |
| TechnipFMC |
| National Oilwell Varco |
| Baker Hughes |
| Others |
Value Chain & Pricing Dynamics
Captive integration of subsea fabrication yards in Perth anchors both supply security and pricing leverage for Australian deepwater operators. Woodside and Santos source standardized pump skids through vertically controlled integration channels, compressing procurement cycles while insulating against Singapore and South Korean floater yard volatility.
Pricing Analysis
Bundled integrated service packages command premium positioning against unbundled spot contracts across the Asia Pacific upstream sector. Day-rate structures in drilling services differentiate by rig specification and water depth capability, while performance-linked compensation in mature field services extracts value through production uptime guarantees. Pricing pressure stems from operator consolidation of contractor panels, squeezing margins on standardized well construction services. National oil companies in Indonesia and Vietnam exhibit highest price sensitivity, prioritizing Gross Split PSC economics, whereas Australian frontier basin developers absorb premium pricing for NOPSEMA-certified well integrity systems.
Supply Chain Analysis
Welding inspector availability constraints in Singapore and South Korean shipyards bottleneck HPHT metallurgy certification for Myanmar's ultra-deepwater blocks. High-grade alloy forgings and subsea control modules flow from Japanese and European OEMs, while steel plate inputs hinge on regional mill capacity. Single-source vulnerability concentrates around specialized subsea umbilical manufacturers with limited qualified alternatives. Distribution runs through Perth-based integration yards for Australian developments and Jakarta-headquartered logistics hubs for Southeast Asian mature field campaigns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Asia Pacific upstream services rests on modular standardization collapsing fabrication costs and performance-based contracts capturing value from production uptime premiums.
For Market Incumbents: Lock in exclusive subsea fabrication slots at Perth integration yards to defend against emerging regional fabricators. Secure MEE methane intensity certification ahead of enforcement waves in China's Sichuan basin. Deepen backward integration into subsea controls engineering to offset European OEM pricing leverage on all-electric architectures. For New Entrants and Emerging Players: Junior exploration companies in Myanmar's Zawtika and Yetagun concessions represent an underserved buyer archetype with unmet demand for modular seismic and drilling packages. Digital-native entrants should target reservoir management subscriptions in Vietnam and Thailand where NOCs shift from day-rate to performance-linked compensation. Position through pilot digital twin deployments with production guarantee clauses. For Investors and Strategic Acquirers: Roll-up economics work for subsea services specialists because operator bundling into multi-year performance contracts favors scaled integrated providers. Target mid-cap fabrication assets with NOPSEMA certification and Browse Basin project exposure. Watch Indonesia's Gross Split PSC implementation velocity as the inflection signal for contractor capital deployment appetite.| Strategic Initiative | Industry Significance |
|---|---|
| Subsea Fabrication Capacity Expansion | Perth yard batch-fabrication secures Woodside and Santos tieback schedules against Singapore labor disruptions. |
| MEE Methane Certification Program | Continuous emissions monitoring hardware bundling opens recurring revenue streams in Sichuan shale plays. |
| Digital Twin Platform Integration | Real-time reservoir simulation subscriptions displace day-rate structures with Petronas and Pertamina contracts. |
| HPHT Metallurgy Specialist Acquisition | Welding inspector capacity addresses Myanmar ultra-deepwater blocks exceeding 200°C bottom-hole ratings. |
| CCUS-Enabled EOR Joint Venture | Carbon capture infrastructure hybridizes with Cooper Basin and Shengli oilfield rejuvenation contracts. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drilling contractors, subsea project managers, NOC procurement leads, and regulatory affairs officers at MEE and NOPSEMA with secondary validation through EIA data, IEA upstream investment reports, customs trade records for subsea equipment, and PSC term filings. Bottom-up project aggregation and top-down sector sizing triangulated market boundaries across service type, technology, and end user dimensions.
Comparable historical periods anchored the projection horizon to capture cyclical rig demand patterns and regulatory implementation lags. The analytical framework modeled drilling, completion, subsea, and production service segments alongside offshore technology, enhanced oil recovery, hydraulic fracturing, and seismic imaging technology tiers. CAGRs derived from operator capital expenditure trajectories, project sanctioning timelines, and equipment procurement cycle compression. Forecast inputs incorporated MEE methane intensity enforcement schedules and Indonesia's Gross Split PSC adoption velocity.
Underlying measurement precision varies by segment; drilling services carry tighter precision than emerging digital twin subscription revenue. Forecasts reflect documented assumptions about regulatory enforcement timing and operator capital allocation priorities. Material deviation in China's dual carbon policy implementation or Australia's NOPSEMA certification timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
US Oil and Gas Infrastructure Market
Oil & Gas
Oil Breather Tank Market
Oil & Gas
Sidetracking Market
Oil & Gas
Australia Oil and Gas Upstream Market
Oil & Gas
Southeast Asia Oil and Gas EPC Market
Oil & Gas
Mud Mixers Market
Oil & Gas
Norway Oilfield Equipment Market
Oil & Gas
Middle-East Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Smart Pigging Market
Oil & Gas
Oil and Gas EPC Market
Oil & Gas
Oilfield Roller Chain Market
Oil & Gas
Thailand Oil and Gas Upstream Market
Oil & Gas
Oil and Gas Pipeline Management Software Market
Oil & Gas
Oil and Gas Hose Assemblies Market
Oil & Gas
Dry Natural Gas Market
Oil & Gas
Oil & Gas Equipment MRO Market