
 Oilwell Completion Tools Market | 2026-2036
Oilwell Completion Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Oilwell Completion Tools Market Analytics
Independent producers are redrawing procurement priorities across the Oilwell Completion Tools Market, shifting from bundled service contracts toward discrete tool purchases that cut per-well costs. Schlumberger leverages integrated drilling-to-completion workflows to anchor premium positioning in deepwater applications. Baker Hughes competes through proprietary intelligent wellhead systems that sustain margins in high-pressure offshore environments. Halliburton dominates North American land markets with manufacturing scale that controls delivery timelines for multi-stage packer assemblies.
Oilwell completion tools encompass mechanical and hydraulic devices—packers, wellheads, tubing hangers, and control lines—fabricated from chrome-alloy and nickel-based steels rated for pressures exceeding 15,000 psi and temperatures above 350°F, designed to isolate zones, manage flow, and enable intervention over a well's producing life. Packer systems lead product-type revenue as zonal isolation complexity rises in extended-reach laterals, while fiber-optic technology segments expand fastest through distributed temperature and acoustic sensing that optimizes fracture diagnostics. Unconventional reservoirs anchor application demand, though offshore well tool specifications command higher unit margins due to metallurgical and certification requirements.
EPA methane rules and API 14A/14L wellhead standards shape product design and testing protocols, forcing retooling cycles that favor suppliers with in-house metallurgy labs and API-licensed manufacturing. BSEE offshore safety directives add compliance layers for Gulf of Mexico deployments, extending qualification timelines but creating barriers against lower-tier imports. Stakeholders must monitor regulatory divergence between EPA state implementation plans and emerging EU methane import standards, as compliance fragmentation will determine which tool portfolios retain market access across jurisdictions.
Market Dynamics
Multi-stage completion intensity in unconventional reservoirs is compressing tool lifecycles and forcing suppliers to redesign packer assemblies for 50-plus stage laterals where mechanical failure costs exceed $500,000 per incident.
Growth Catalysts
- EPA Methane Regulations:Tightening emission standards under the Inflation Reduction Act are mandating gas-tight packer seals and intelligent wellhead monitoring, forcing replacement cycles that favor certified domestic manufacturers.
- Fiber-Optic Sensing Convergence:Distributed temperature and acoustic sensing integration with completion strings is enabling real-time fracture diagnostics that optimize stage spacing and boost EUR per well.
- Permian Basin Drilling Density:Prolific horizontal development in Midland and Delaware sub-basins is consuming record volumes of frac plugs and composite bridge plugs as operators push lateral lengths beyond 15,000 feet.
Market Restraints
- Alloy Supply Concentration:Nickel-based superalloy sourcing depends on a limited supplier base in Pennsylvania and Texas, exposing tool fabricators to volatile Inconel 718 pricing and extended lead times.
- Deepwater Certification Friction:BSEE subsea safety directives impose 18-month qualification timelines for Gulf of Mexico wellhead systems, freezing out mid-tier competitors lacking in-house testing infrastructure.
- Composite Plug Substitution:Dissolvable frac plugs are displacing conventional drillable plugs in certain Permian applications, threatening legacy product lines optimized for mechanical milling operations.
Strategic Opportunities
- Argentina Vaca Muerta Expansion:Underdeveloped shale infrastructure in Neuquén Province offers first-mover positioning for packer suppliers willing to establish local assembly and service capabilities.
- CCUS Well Integrity Standards:Emerging EPA carbon sequestration regulations are creating demand for corrosion-resistant tubing hangers and monitoring systems in injection well completions.
- Direct-to-Operator Digital Channels:E-procurement platforms are disintermediating traditional distribution, allowing specialized packer manufacturers to capture margin previously lost to oilfield service intermediaries.
Industry Challenges
- API Q1 Certification Bottlenecks:Quality management system audits for manufacturing licenses face 9-month backlogs, delaying new product launches and facility expansions.
- Legacy SCADA Integration Complexity:Intelligent wellhead systems must interface with decades-old control architectures, requiring costly custom engineering for each offshore platform retrofit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oilwell Completion Tools Market |
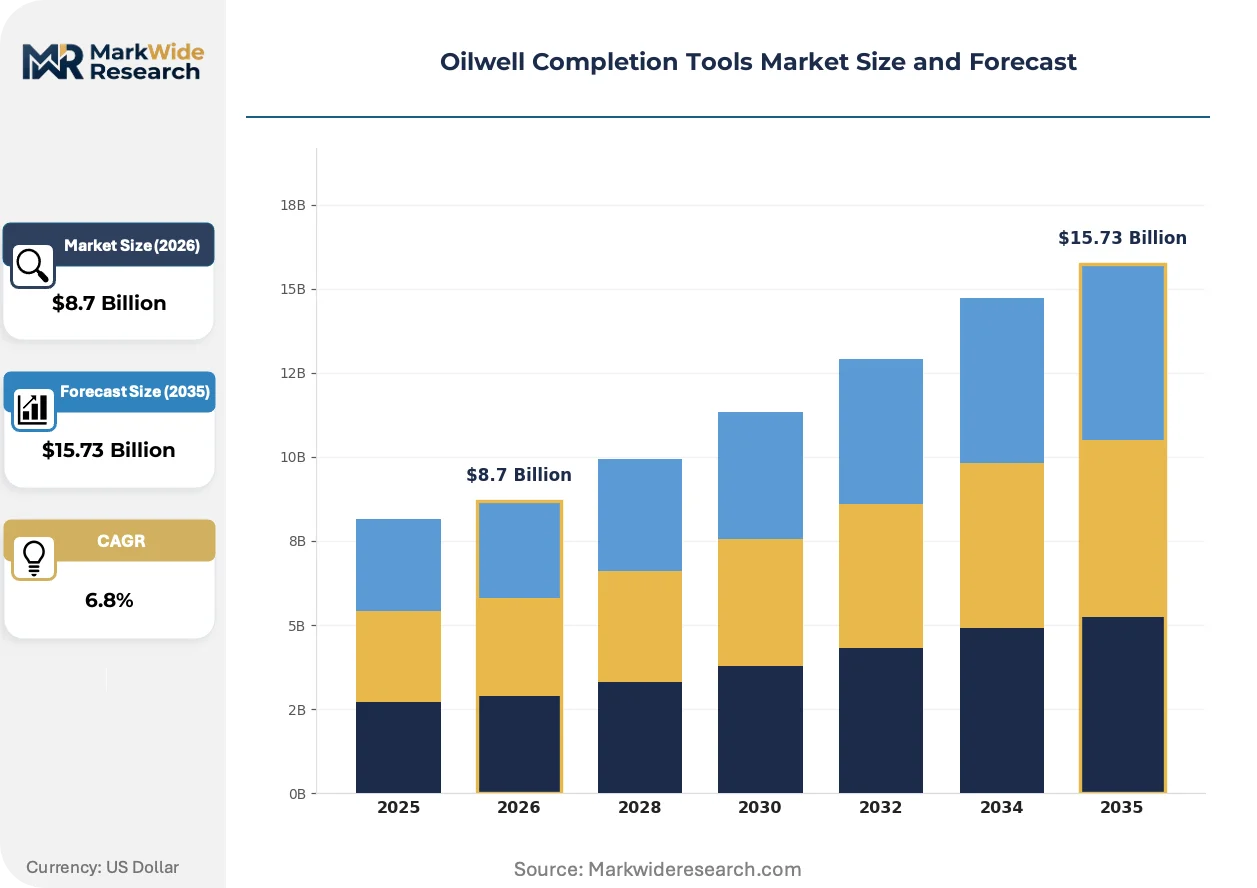
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Packer, Tubing, Wellhead, Control Line Application: Unconventional Reservoirs, Offshore Wells, Tight Gas, Enhanced Oil Recovery Technology: Spotting Services, Acoustics, Differentials, Fiber Optics End User: Oil Companies, Service Providers, Independent Producers, Contractors |
| Companies Covered | Schlumberger, Baker Hughes, Halliburton, Weatherford International, National Oilwell Varco, Packers Plus Energy Services, Welltec, Superior Energy Services, FTS International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oilwell Completion Tools Market Evolving Landscape
Downhole electronics and metallurgical advances are converging to enable autonomous zonal isolation systems that reduce intervention frequency and extend well life in high-temperature formations.
Modular packer architectures incorporating shape-memory alloy sealing elements are miniaturizing component footprints while maintaining 20,000 psi differential ratings. Operators in the Bakken and Eagle Ford are piloting these systems to reduce trip times during multi-stage completions. The technology is compressing rig-day requirements and displacing conventional elastomer-based designs in thermal applications above 400°F.
EU methane import standards under the CSRD are mandating certified low-emission completion equipment for gas entering European terminals. Tool suppliers must now document cradle-to-grave carbon intensity and maintain chain-of-custody records for alloy sourcing. Offshore wellhead manufacturers serving North Sea platforms face the steepest compliance costs, driving consolidation among smaller fabricators lacking sustainability reporting infrastructure.
Buying committees at independent Permian producers are unbundling discrete tool procurement from integrated service contracts, creating direct vendor relationships that bypass Halliburton and Schlumberger distribution networks. This pattern is most pronounced among Permian pure-plays with 50-plus well annual programs, where standardization across pad developments justifies inventory ownership and in-house specification management.
Oilwell Completion Tools Market Segmentation
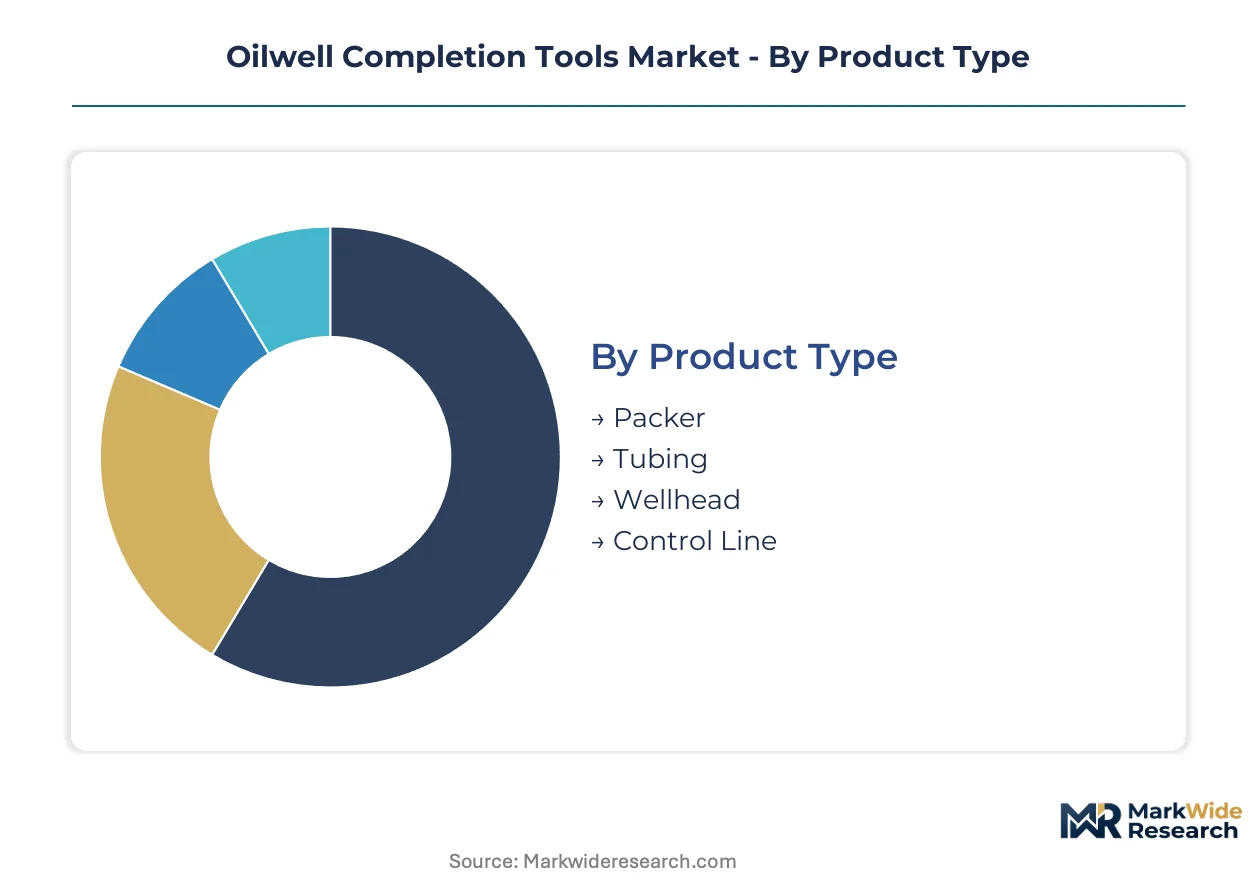
Tool specification varies sharply across completion environments, with regulatory pressure from EPA methane rules and BSEE offshore directives forcing divergence in material grades and certification requirements. Procurement committees now weight segment selection against compliance exposure as much as technical performance.
Product Type:
EPA methane regulations and API 5CT/14A standards create tiered compliance burdens that reshape supplier qualification and pricing power across mechanical component categories.
- Packer:Mechanical or hydraulic devices fabricated from chrome-alloy steels rated for 15,000-plus psi isolation, incorporating gas-tight elastomer or metal-to-metal seals. Demand concentrates in Permian Basin multi-stage laterals where 50-plus stage designs require rapid-set packer systems that withstand repeated pressure cycling without seal degradation.
- Wellhead:Casing head and tubing head assemblies housing hangers, seals, and outlet connections, governed by API 6A and BSEE subsea safety directives. Offshore Gulf of Mexico deployments drive premium specification tiers, with 18-month BSEE qualification timelines freezing out fabricators lacking in-house metallurgy labs and pressure testing infrastructure.
- Tubing:API 5CT seamless or welded conduit strings conveying production fluids, available in J55 through Q125 grades with threaded and coupled or integral joint connections. Unconventional operators in the Bakken and Eagle Ford specify high-collapse grades for extended-reach laterals.
- Control Line:Encapsulated hydraulic or electric conduits transmitting signals to downhole valves and gauges, typically 316L stainless steel or nickel-alloy encapsulated in polymer jackets. Intelligent completion adoption in North Sea platforms drives corrosion-resistant specification tiers.
Established volume favors packer systems; emerging adoption favors control line integration with fiber-optic sensing.
Application:
Completion intensity and regulatory exposure create four distinct demand pockets with divergent margin profiles and supplier qualification requirements.
- Unconventional Reservoirs:Horizontal shale and tight oil completions requiring multi-stage isolation, fracture diversion, and flowback management. Midland and Delaware sub-basin operators consume record volumes of composite frac plugs and retrievable packers as lateral lengths push beyond 15,000 feet.
- Offshore Wells:Subsea and platform completions demanding high-pressure, high-temperature ratings with BSEE, NORSOK, or ISO 13628-4 certification. Metallurgical complexity and extended qualification cycles sustain premium pricing tiers unavailable to land-market suppliers.
- Tight Gas:Low-permeability sandstone completions emphasizing zonal isolation in multi-layered pays without hydraulic fracturing. Rockies Basin operators specify slim-hole packer systems for cost-constrained development.
- Enhanced Oil Recovery:Thermal, chemical, or CO2 injection completions requiring corrosion-resistant metallurgy and monitoring capabilities. EPA carbon sequestration regulations are creating new specification tiers for injection well integrity.
Conventional unconventional reservoirs dominate unit volume; offshore specifications command the steepest margin premiums.
Technology:
Downhole sensing and intervention capabilities are segmenting the market between mechanical reliability and real-time diagnostic integration.
- Fiber Optics:Distributed temperature sensing and distributed acoustic sensing cables embedded in completion strings, enabling real-time fracture geometry mapping and flow profiling. Permian operators piloting this technology optimize stage spacing and reduce diagnostic rig time.
- Acoustics:Downhole acoustic monitoring systems detecting sand production, flow regime changes, and cement integrity without wireline intervention. Gulf of Mexico deepwater completions adopt these for subsea well surveillance.
- Spotting Services:Precision placement of cement, chemical, or mechanical plugs using wireline or coiled tubing conveyance. Bakken operators deploy spotting services for plug-and-abandonment efficiency.
- Differentials:Pressure differential measurement tools for drawdown control and formation evaluation during completion and production phases. Eagle Ford tight gas applications emphasize differential monitoring for reservoir management.
Mechanical spotting services anchor current revenue; fiber-optic integration is climbing the fastest as operators prioritize EUR optimization.
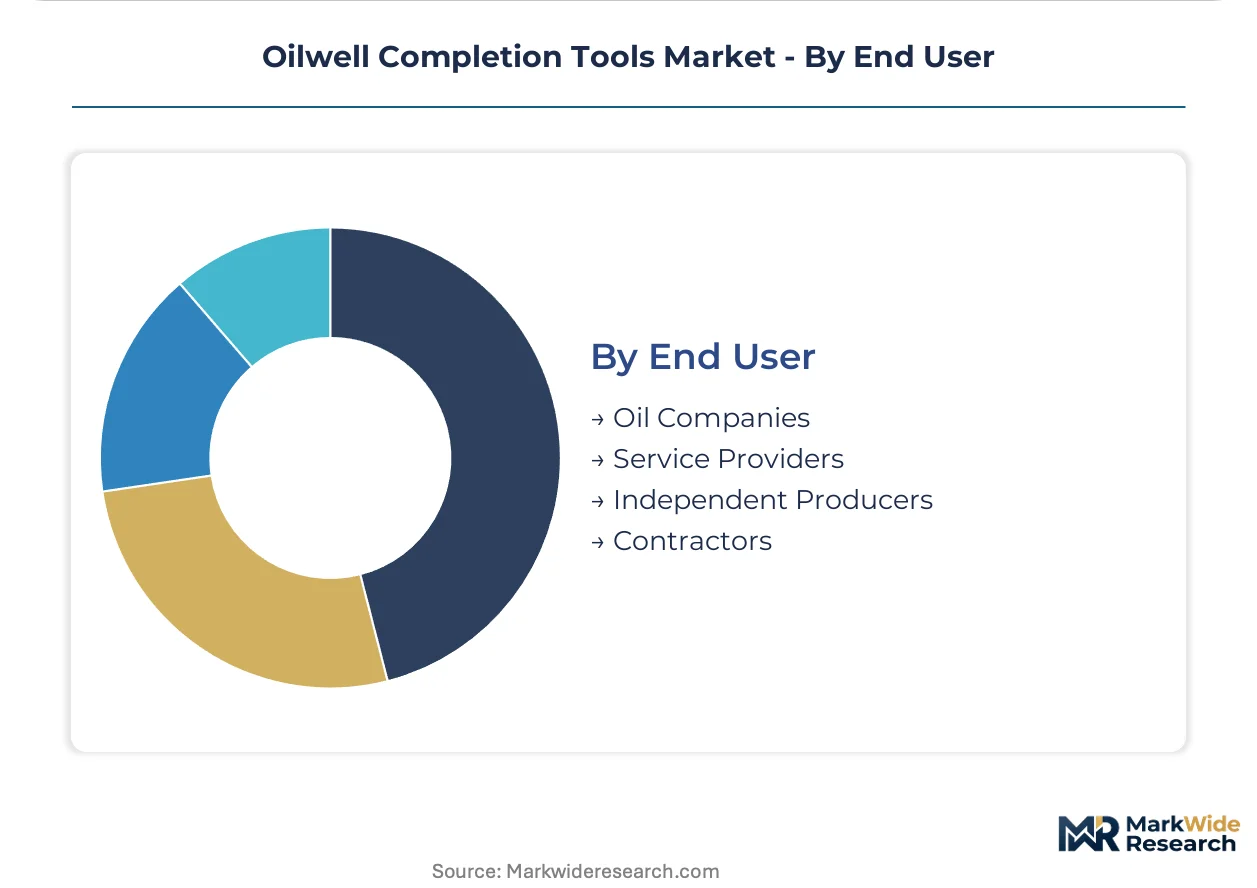
End User:
Procurement authority is fragmenting as integrated service contracts dissolve and buying committees assert direct vendor relationships.
- Independent Producers:Privately held or publicly traded E&P companies operating 50-plus well annual programs, increasingly unbundling tool procurement from integrated service contracts. Permian pure-plays now maintain direct packer and wellhead supplier relationships, bypassing traditional oilfield service intermediaries.
- Service Providers:Schlumberger, Halliburton, and Baker Hughes divisions bundling tools with pumping, drilling, and intervention services. Manufacturing scale and API-licensed facilities sustain their position in deepwater and complex land completions.
- Oil Companies:Majors and large independents with in-house engineering specifications and global supplier qualification systems. ExxonMobil and Chevron impose proprietary metallurgy standards exceeding API minimums.
- Contractors:Drilling and completion contractors executing operator-directed programs with limited procurement autonomy. Regional contractors in the Mid-Continent specify standard-grade tools for cost-sensitive development.
Service provider channels retain offshore and complex project dominance; independent producer direct procurement is gaining share fastest in North American land markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin pipeline network and Gulf Coast export terminals anchor United States dominance in oilwell completion tool demand. Infrastructure density across Texas and New Mexico shale corridors compresses delivery timelines for packer assemblies and frac plugs. Midland and Delaware sub-basin drilling programs consume the highest per-well tool volumes globally.
United States
EPA methane regulations under the Inflation Reduction Act mandate gas-tight packer seals and intelligent wellhead monitoring systems. BSEE offshore safety directives impose 18-month qualification timelines for Gulf of Mexico deployments. Houston and Oklahoma City clusters concentrate manufacturing capacity for chrome-alloy packer systems serving Permian operators.
Canada
Montney and Duvernay tight gas development drives demand for slim-hole packer systems in multi-layered pays. Health Canada and provincial regulators enforce well integrity standards exceeding API minimums for thermal and CO2 injection applications. Calgary serves as the procurement hub where independent producers negotiate direct tool contracts bypassing integrated service bundles.
Norway
North Sea subsea completions command premium specifications for high-pressure, high-temperature wellhead systems. NORSOK standards and Petroleum Safety Authority Norway directives shape metallurgical requirements and testing protocols. Stavanger and Bergen clusters host engineering centers developing corrosion-resistant control line solutions for deepwater environments.
Saudi Arabia
Gas development in the Jafurah unconventional basin expands deployment of multi-stage completion tools for tight sandstone reservoirs. Saudi Aramco imposes proprietary metallurgy standards and supplier qualification systems exceeding API certifications. Dhahran and Jubail industrial cities concentrate fabrication capacity for high-collapse tubing and premium connections.
Brazil
Pre-salt carbonate development drives demand for intelligent completion systems with real-time monitoring capabilities. ANP regulatory frameworks and Petrobras technical specifications govern subsea wellhead certification and pressure testing protocols. Rio de Janeiro and Macaé clusters anchor engineering services for deepwater packer and control line deployments.
Oilwell Completion Tools Market Competitive Landscape
Listed leaders compete with private specialists across manufacturing scale and certification depth. The vendor base stratifies into three tiers: integrated oilfield service conglomerates with API-licensed global manufacturing, regional specialists capturing direct procurement relationships with independent producers, and private fabricators serving niche metallurgy or geographic segments. Dominant competitive moves include backward integration into nickel-alloy supply chains and strategic partnerships with fiber-optic sensing technology providers.
Among Houston-based integrated service providers, Schlumberger, Halliburton, and Baker Hughes occupy positions representing the scale-driven archetype with captive manufacturing infrastructure. These entities exemplify the premium-tier competitive vector where API Q1 certification depth and BSEE qualification timelines create defensive barriers against mid-tier entrants. Danish specialist Welltec represents the technology-differentiated archetype, while Packers Plus Energy Services anchors the North American land-market specialist position through direct operator relationships in unconventional basins.
| Leading Market Players |
|---|
| Schlumberger |
| Baker Hughes |
| Halliburton |
| Weatherford International |
| National Oilwell Varco |
| Packers Plus Energy Services |
| Welltec |
| Superior Energy Services |
| FTS International |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Permian Basin operators and Houston-based packer manufacturers lock in nickel-alloy supply access while fixing price visibility across 12-24 month windows, insulating fabricators from Inconel 718 spot volatility but constraining flexibility when EPA methane rules force rapid design retooling.
Pricing Analysis
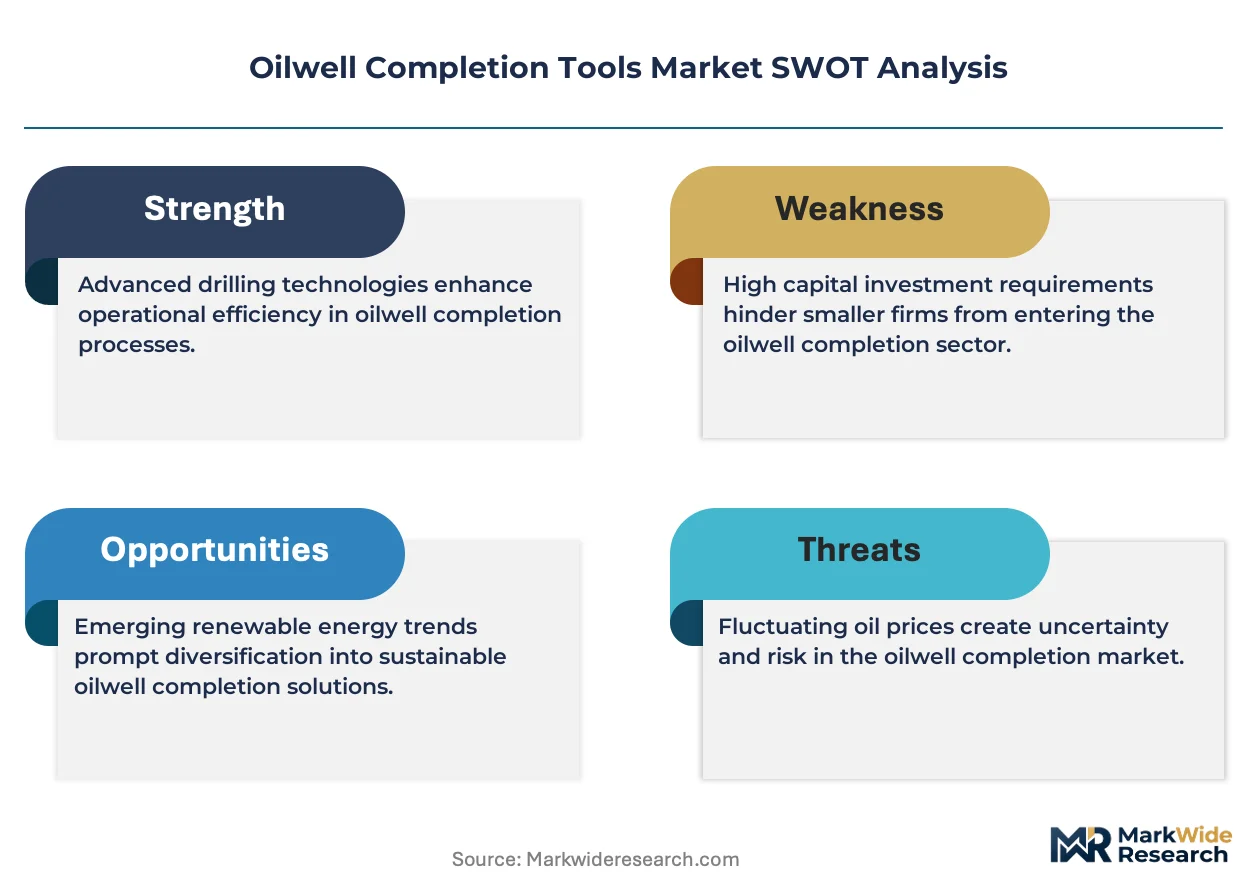
Volume-discount tiering separates deepwater-qualified wellhead systems from standard land-market packers, with BSEE certification and API Q1 licensing commanding 40-60% premiums over uncertified alternatives. Price differentiation hinges on metallurgical grade and after-sales service bundling, with chrome-alloy specifications and field engineering support justifying upper-tier positioning. Cost compression in composite frac plug lines is intensifying because dissolvable alternatives displace conventional drillable designs in Midland sub-basin applications. Independent Permian pure-plays exhibit highest price sensitivity, while offshore majors prioritize qualification depth over unit cost.
Supply Chain Analysis
Strategic stockpiling of nickel-based superalloys dominates over just-in-time approaches, with tool fabricators maintaining 6-9 month inventory buffers against Pennsylvania and Texas alloy supplier concentration. Raw material sourcing draws from Inconel 718 bar stock, chrome-alloy steel tubing, and fiber-optic sensing cables. Single-source vulnerability in nickel-alloy supply creates structural exposure to volatile pricing and extended lead times. Distribution runs through oilfield service intermediaries for offshore and complex projects, while direct-to-operator digital channels gain share in North American land markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Permian pure-plays with 50-plus well annual programs consolidate procurement authority through direct vendor relationships, fragmenting the traditional integrated service contract model that Halliburton and Schlumberger dominated.
For Market Incumbents: Secure API Q1 certification depth and in-house metallurgy lab capacity to defend against mid-tier competitors frozen out by BSEE qualification timelines. Backward integration into nickel-alloy supply chains reduces exposure to Pennsylvania and Texas supplier concentration. Channel control through e-procurement platform partnerships retains margin threatened by disintermediation.
For New Entrants and Emerging Players: API 14A fast-track certification for wellhead systems opens access to Gulf of Mexico offshore specifications where 18-month BSEE timelines currently block mid-tier fabricators. Argentina Vaca Muerta shale development offers the most penetrable geography, with underdeveloped local assembly infrastructure and Neuquén Province operators seeking packer suppliers. Go-to-market through direct digital channels bypasses established oilfield service distribution networks.
For Investors and Strategic Acquirers: Capital is best deployed toward regional specialists with captive API-licensed manufacturing and established direct operator relationships in unconventional basins, as these assets capture margin migration from integrated service bundles. Long-term viability favors fabricators with sustainability reporting infrastructure to meet EU methane import standards under CSRD. Watch for EPA carbon sequestration regulation finalization as inflection indicator for CCUS well integrity tool demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel-Alloy Supply | Reduces exposure to volatile Inconel 718 pricing from Pennsylvania and Texas suppliers. |
| API Q1 Certification Investment | Creates defensive barriers against mid-tier competitors facing 9-month audit backlogs. |
| Fiber-Optic Sensing Partnership | Enables real-time fracture diagnostics that Permian operators prioritize for EUR optimization. |
| Direct-to-Operator Digital Channel Launch | Captures margin previously lost to Halliburton and Schlumberger distribution intermediaries. |
| Argentina Local Assembly Establishment | Positions first-mover advantage in Vaca Muerta shale infrastructure buildout. |
Research Methodology
Cross-validation between primary interviews with completion engineers, procurement directors at independent producers, drilling contractors, and API certification auditors and secondary validation through BSEE enforcement records, EPA regulatory filings, and SEC 10-K disclosures anchors the qualitative findings. Bottom-up triangulation across product-type shipment data and top-down reconciliation against operator capital expenditure disclosures ensures consistency. Sources include proprietary industry databases tracking packer and wellhead deployments, customs records for nickel-alloy imports, and petroleum engineering society technical papers.
Sensitivity analysis around Permian Basin drilling density, EPA methane regulation implementation pace, and nickel-alloy price volatility informs the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application environment, technology integration level, and end-user procurement channel. CAGRs derive from historical shipment trajectories and operator completion intensity forecasts. Industry-specific inputs incorporate lateral length extension trends and stage count per well evolution in unconventional reservoirs.
Underlying assumptions cover regulatory compliance timelines, alloy supply continuity, and operator capital discipline, with deviation risk concentrated in BSEE qualification delays and EU methane import standard enforcement. Forecasts reflect documented conditions without predictive certainty. Revision becomes warranted when EPA state implementation plan divergence or EU-CSRD compliance fragmentation crosses thresholds that alter tool portfolio market access.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Kuwait Oil and Gas Upstream Market
Oil & Gas
Smart Pigging Market
Oil & Gas
US Sand Control Systems Market
Oil & Gas
Kuwait & Iraq Oilfield Chemicals Market
Oil & Gas
United States Wireline Logging Services Market
Oil & Gas
India Natural Gas Market
Oil & Gas
Vietnam Oil and Gas Upstream Market
Oil & Gas
Europe Coiled Tubing Market
Oil & Gas
Romania Oil and Gas Upstream Market
Oil & Gas
Middle East and Africa Early Production Facility Market
Oil & Gas
Russian Federation Oil and Gas Market
Oil & Gas
North America Drilling Completion Fluids Market
Oil & Gas
Small Scale LNG (SSLNG) Market
Oil & Gas
Middle East Wireline Logging Services Market
Oil & Gas
CO2 EOR Market
Oil & Gas
Oil Well Cement Market