
 Denmark Offshore Oil and Gas Decommissioning Market | 2026-2036
Denmark Offshore Oil and Gas Decommissioning Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark Offshore Oil and Gas Decommissioning Market Outlook
Multi-source contracting for heavy-lift vessel capacity is expanding across Danish decommissioning campaigns. Aker Solutions ASA leverages its integrated engineering and marine removal capabilities to anchor large-platform projects in the North Sea. Saipem S.p.A. competes through specialized heavy-lift vessel deployment for topside removal operations. Bureau Veritas SA differentiates via third-party certification and structural assessment services that validate decommissioning compliance.
Denmark offshore oil and gas decommissioning encompasses the engineered dismantling, removal, and environmental remediation of subsea production infrastructure, typically involving steel jacket platforms weighing 10,000–30,000 tonnes and pipelines requiring mechanical cutting or explosive severance at depths of 40–80 metres. The primary purpose is to restore seabed conditions to pre-production states while managing hydrocarbon reservoir integrity and marine habitat disruption. Platform removal commands the dominant share of service value, driven by the scale of steel recovery and marine logistics required for jacket and topside extraction. Remote Operated Vehicles represent the fastest-growing technology segment, displacing diver-dependent operations in hazardous subsea cutting and survey tasks across deeper Danish sector fields.
The Danish Energy Agency enforces decommissioning timelines under the Subsoil Act, while EU REACH and OSPAR Convention commitments govern hazardous material handling and marine dumping prohibitions in Danish waters. These frameworks mandate complete removal of installations unless derogation petitions demonstrate significant technical or safety barriers, directly shaping contractor procurement patterns and technology selection. Stakeholders must monitor forthcoming revisions to Denmark's marine spatial planning and carbon-accounting rules for steel recycling, as these will determine whether in-country yard dismantling or export to continental European facilities becomes the preferred route for platform materials.
Market Dynamics
The EU Offshore Safety Directive enforcement is compressing decommissioning timelines across Danish North Sea assets, forcing operators to accelerate platform removal programs before 2030 compliance deadlines. Heavy-lift vessel scarcity is concentrating contractor selection power among integrated marine service providers with owned fleet capacity.
Growth Catalysts
- Tyra Redevelopment Acceleration:The full-field redevelopment program is triggering adjacent decommissioning of legacy Tyra East and Tyra West infrastructure, creating bundled removal contracts for marine contractors.
- OSPAR 98/3 Implementation:The convention's complete removal mandate is eliminating derogation pathways for Danish jacket platforms, mandating full structure recovery rather than seabed abandonment.
- Electrification Retrofit Failures:Failed power-from-shore conversions at Dan and Halfdan fields are converting planned life extensions into decommissioning projects, expanding addressable removal volume.
Market Restraints
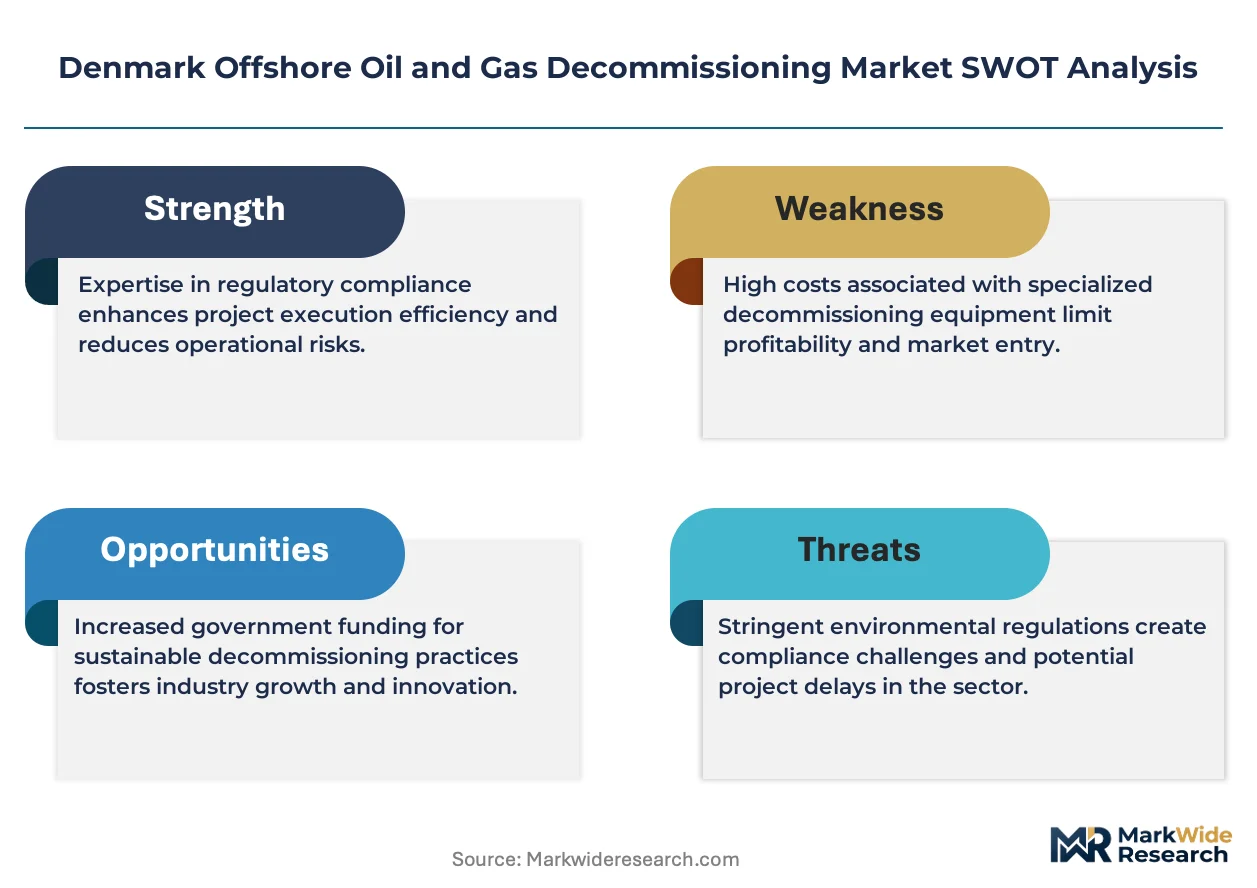
- Heavy-Lift Vessel Concentration:North Sea-capable crane vessels concentrate among three European fleet operators, creating capacity bottlenecks during summer weather windows.
- Steel Scrap Price Volatility:Platform jacket recycling economics depend on North European scrap steel indices, which fluctuate with Turkish import demand and energy-intensive smelter operating costs.
- Subsoil Act Liability Retention:Denmark's framework requires operators to retain post-decommissioning liability for reservoir integrity, discouraging asset sales to specialist removal firms.
Strategic Opportunities
- Harbor-Næstved Industrial Cluster:The Danish port's deep-water quays and existing oil service infrastructure position it for expansion into large-scale platform dismantling, competing with Rotterdam and Aalborg yards.
- Remote Operated Vehicle Convergence:Integration of autonomous underwater vehicles with resident ROV systems is enabling continuous subsea monitoring without surface vessel support, reducing day-rate exposure.
- EU Green Deal Steel Circularity:Incentives for recycled content in European steel production are improving recovered jacket steel premiums, shifting dismantling location decisions toward EU-flagged recycling facilities.
Industry Challenges
- Explosive Severance Certification:Danish Maritime Authority permitting for subsea explosive cutting requires specialized UXO clearance protocols, extending project timelines by 4-6 months.
- Reservoir Abandonment Complexity:Tyra field's chalk reservoir requires permanent well plugging with specialized cement formulations, demanding rare deep-set abandonment expertise concentrated among Norwegian specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark Offshore Oil and Gas Decommissioning Market |
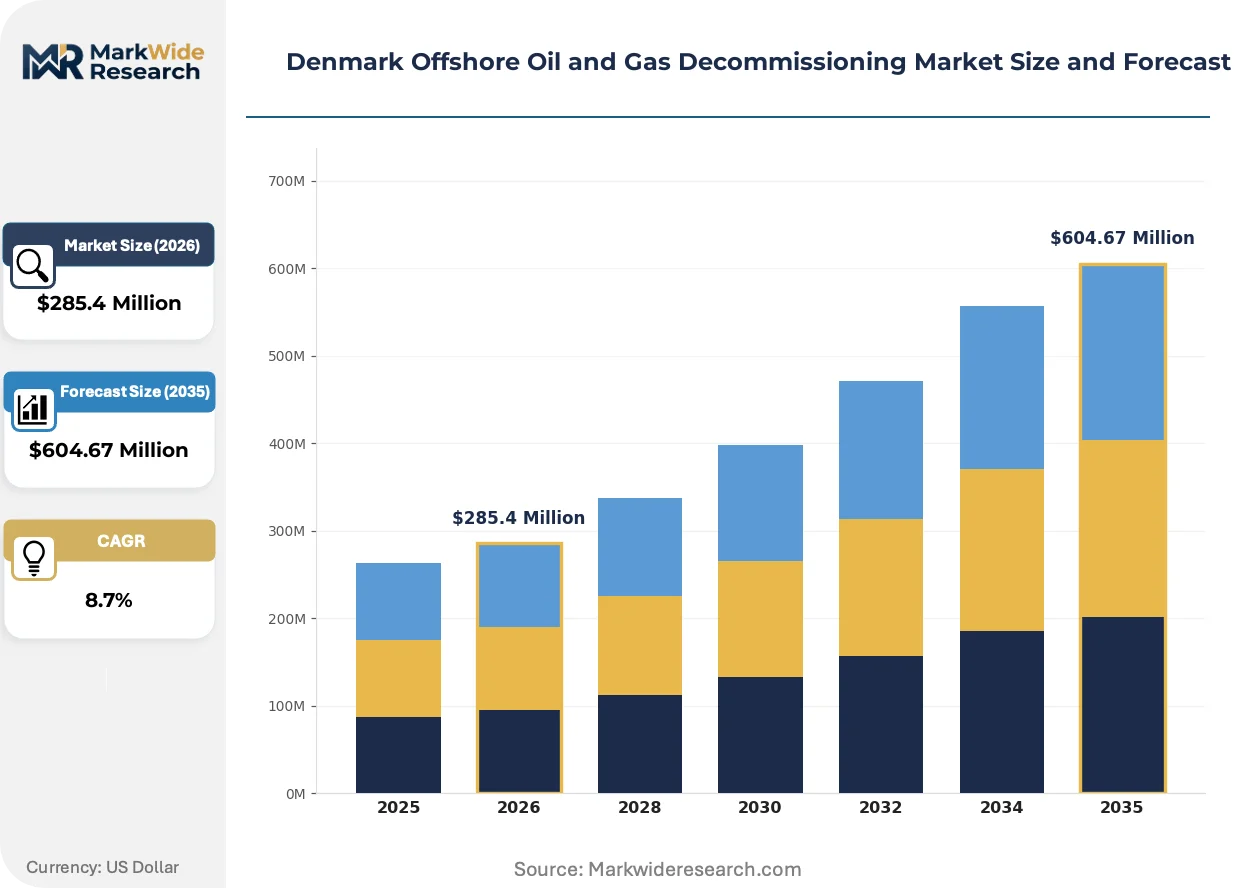
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Platform Removal, Pipeline Abandonment, Waste Management, Site Clearance Technology: Mechanical Cutting, Chemical Dismantling, Remote Operated Vehicles, Modular Solutions End User: Oil Producers, Asset Managers, Regulatory Agencies, Environmental Contractors Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects |
| Companies Covered | AF Gruppen ASA, Schlumberger Limited, Aker Solutions ASA, ABL Group, Halliburton Company, Bureau Veritas SA, A.P. Moeller Maersk A/S, Maersk Drilling, Saipem S.p.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark Offshore Oil and Gas Decommissioning Market Strategic Shifts
Digital twin technology is compressing structural assessment timelines for aging Danish platforms, while modular dismantling techniques are reducing heavy-lift vessel dependency. These shifts are reconfiguring contractor capability requirements and yard infrastructure investments.
Resident autonomous underwater vehicle systems are decentralizing subsea inspection and cutting operations across Danish sector fields. Maersk Drilling and service company alliances are deploying battery-powered AUVs for continuous jacket survey and pipeline severance monitoring. This capability is decentralizing operational control from surface vessels to shore-based remote operation centers, reducing marine spread costs by eliminating diver standby periods.
Denmark's implementation of the EU Marine Strategy Framework Directive is tightening seabed disturbance thresholds for decommissioning operations. The Danish Energy Agency now requires pre-removal benthic habitat mapping and post-operation restoration verification, extending environmental compliance phases. Shallow-water Dan field installations face the most stringent biotope recovery mandates, driving demand for low-impact cutting technologies and sediment containment systems.
Contracting structures are fragmenting from single-source EPC removal packages toward split-scope arrangements separating engineering, marine transport, and yard dismantling. Danish Oil and Natural Gas operators are unbundling these phases to optimize heavy-lift vessel scheduling against steel recycling arbitrage opportunities. This unbundling is most advanced at Halfdan field, where separate contractors now handle topside reverse engineering, jacket removal, and onshore material sorting.
Denmark Offshore Oil and Gas Decommissioning Market Segmentation
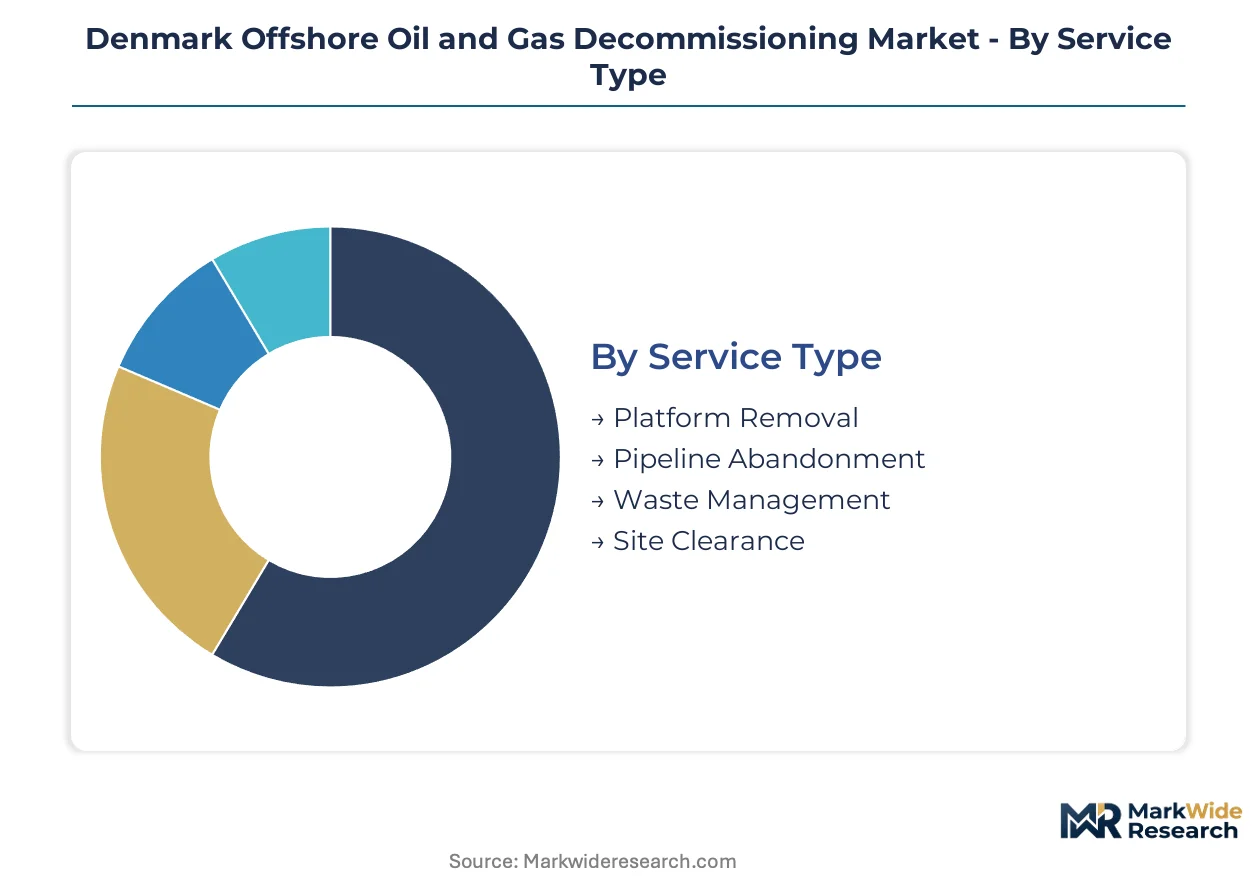
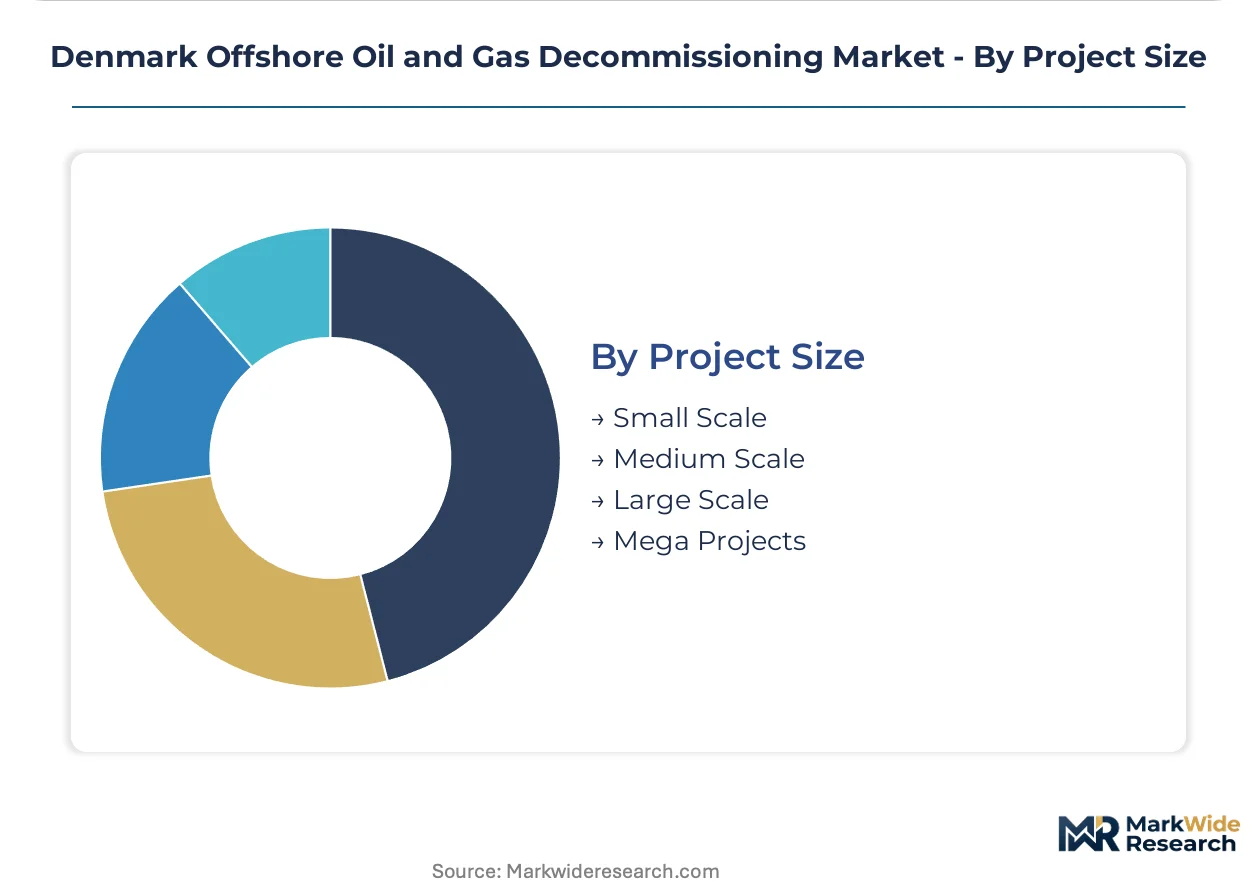
Decommissioning scope in Danish waters fragments across four distinct axes. Service type governs contractor selection and vessel scheduling. Technology choice determines regulatory approval timelines and labor intensity. End user profiles shape procurement rigor and liability retention. Project size drives bundling strategy and yard capacity allocation.
Service Type:
Service specialization aligns with the physical characteristics of Danish North Sea infrastructure and OSPAR 98/3 removal mandates.
- Platform Removal:Steel jacket and topside extraction dominates contract value, requiring heavy-lift vessel mobilization for structures weighing 10,000–30,000 tonnes. Demand concentrates at Tyra, Dan, and Halfdan field complexes where full structure recovery is mandatory.
- Pipeline Abandonment:Subsea line severance and burial operations involve mechanical cutting or explosive severance at 40–80 metre depths. Danish Maritime Authority permitting for explosive methods extends timelines by 4–6 months.
- Waste Management:Hazardous material handling under EU REACH and national marine standards governs hydrocarbon-contaminated sludge and NORM disposal. Specialized treatment facilities at Aalborg and Harbor-Næstved industrial clusters absorb this volume.
- Site Clearance:Post-removal seabed verification and debris recovery ensures compliance with Danish Energy Agency restoration standards. Benthic habitat mapping requirements under the EU Marine Strategy Framework Directive extend this phase.
Platform removal leads on scale; site clearance leads on momentum.
Technology:
Technology selection pivots on water depth, structural material, and diver safety constraints across Danish sector fields.
- Mechanical Cutting:Diamond wire and abrasive water jet systems sever steel jackets and pipelines without explosive permitting delays. Harbor-Næstved yards favor this method for onshore dismantling phases.
- Chemical Dismantling:Thermal cutting and solvent-based coating removal address specialized alloy components and hazardous surface treatments. Limited deployment due to EU REACH substance restrictions.
- Remote Operated Vehicles:Battery-powered ROV systems execute subsea survey, cutting, and monitoring without surface vessel support. Maersk Drilling alliances deploy these for continuous jacket inspection at Tyra field.
- Modular Solutions:Pre-fabricated dismantling segments and reusable lifting frames reduce heavy-lift vessel dependency. Halfdan field contractors apply this approach to separate topside reverse engineering from jacket removal.
Mechanical cutting leads on scale; ROV systems lead on momentum.
End User:
Stakeholder categories reflect liability allocation and technical oversight requirements under Denmark's Subsoil Act.
- Oil Producers:TotalEnergies and other field operators retain post-decommissioning reservoir liability, discouraging asset sales to removal specialists. Direct procurement of integrated removal packages remains preferred.
- Asset Managers:Specialist firms assume operational decommissioning execution while producers retain legal liability. Emerging presence as operators unbundle engineering, marine transport, and yard phases.
- Regulatory Agencies:Danish Energy Agency and Danish Maritime Authority enforce compliance timelines and permitting protocols. Third-party certification from Bureau Veritas validates structural assessments for agency submission.
- Environmental Contractors:Benthic survey and habitat restoration specialists address EU Marine Strategy Framework Directive thresholds. Demand intensifies at shallow-water Dan field installations with stringent biotope recovery mandates.
Oil producers lead on scale; asset managers lead on momentum.
Project Size:
Scale classification determines contractor capability requirements and steel recycling logistics across Danish decommissioning campaigns.
- Small Scale:Single-well platforms and subsea tieback infrastructure require minimal vessel spreads. Often bundled into larger field campaigns for cost efficiency.
- Medium Scale:Multi-well satellite platforms with localized processing equipment. Dan field legacy structures fall into this tier with electrification retrofit failures converting life extensions into removal projects.
- Large Scale:Central processing and accommodation platforms with integrated drilling facilities. Tyra East and Tyra West redevelopment triggers adjacent decommissioning of this magnitude.
- Mega Projects:Full-field infrastructure complexes requiring multi-vessel campaigns and dedicated yard slots. None currently active in Danish waters; reserved for future bundled cross-field programs.
Large scale projects lead on scale; medium scale projects lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Harbor-Næstved anchors Danish decommissioning capacity through deep-water quays and established oil service infrastructure. The port competes with Rotterdam and Aalborg for large-scale platform dismantling contracts. Sub-regional specialization across Denmark's maritime provinces shapes contractor procurement and steel recycling logistics.
Capital Region
Copenhagen concentrates regulatory oversight and engineering headquarters for North Sea operators. The Danish Energy Agency enforces Subsoil Act decommissioning timelines from its Copenhagen base, compressing compliance windows for platform removal programs. Hellerup hosts technical consultancies specializing in OSPAR 98/3 derogation petitions and structural assessment protocols.
Central Denmark Region
Aalborg industrial yards absorb hazardous waste streams from platform dismantling under EU REACH mandates. The city's steel recycling facilities process recovered jacket materials, with premiums fluctuating against Turkish scrap import demand. Local environmental contractors execute benthic habitat mapping for Danish Maritime Authority compliance verification.
Region Zealand
Harbor-Næstved deep-water infrastructure positions the port for Tyra field jacket dismantling campaigns. The industrial cluster leverages existing offshore supply vessel networks to reduce marine logistics costs for heavy-lift operations. Local yards compete for modular dismantling contracts unbundled from integrated removal packages.
North Denmark Region
Thyborøn fishing ports transition into decommissioning service hubs for shallow-water Dan field installations. The region's marine contractors specialize in low-impact cutting technologies for stringent biotope recovery mandates. Local ROV operators deploy autonomous systems for continuous jacket inspection without surface vessel support.
South Denmark Region
Esbjerg maintains North Sea supply vessel concentration, though heavy-lift crane vessel capacity remains scarce across European fleet operators. The port's logistics providers coordinate steel transport to continental recycling facilities under EU Green Deal circularity incentives. Local engineering firms develop digital twin applications for aging platform structural assessment.
Denmark Offshore Oil and Gas Decommissioning Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized certification and autonomous technology niches. The Danish market concentrates among integrated marine service providers with owned heavy-lift vessel capacity, while specialist firms unbundle engineering and yard phases. Three archetypes dominate: full-service EPC contractors, third-party certification bodies, and autonomous subsea technology developers. Competitive moves center on fleet capacity expansion and strategic alliances for ROV-AUV convergence.
Within the integrated engineering tier, Aker Solutions ASA represents the heavy-lift vessel anchor model for large-platform North Sea projects. Saipem S.p.A. exemplifies specialized marine removal capabilities through dedicated crane vessel deployment. Bureau Veritas SA occupies the third-party certification position, validating structural assessments for Danish Energy Agency compliance submissions.
| Leading Market Players |
|---|
| AF Gruppen ASA |
| Schlumberger Limited |
| Aker Solutions ASA |
| ABL Group |
| Halliburton Company |
| Bureau Veritas SA |
| A.P. Moeller Maersk A/S |
| Maersk Drilling |
| Saipem S.p.A. |
| Others |
Value Chain & Pricing Dynamics
Heavy-lift vessel day-rates cascade through project-based contract pricing tiers, with steel scrap arbitrage between Danish and Dutch recycling facilities determining final dismantling location economics. Harbor-Næstved yard operators leverage EU Green Deal circularity incentives to capture premium steel recovery margins against Rotterdam competitors.
Pricing Analysis
Input-cost pass-through from North European scrap steel indices governs dismantling service quotations, with Turkish import demand volatility compressing contractor margins during energy-intensive smelter operating cost spikes. Project-based pricing stratifies across integrated EPC removal packages, split-scope engineering-marine bundles, and unbundled yard dismantling phases. OSPAR 98/3 compliance certification tier and heavy-lift vessel ownership status drive price differentiation between European fleet operators and asset-light specialists. Pricing pressure stems from summer weather window capacity bottlenecks concentrating contract awards among three crane vessel owners. National oil company procurement teams exhibit highest price sensitivity due to Subsoil Act liability retention requirements, while specialist asset managers prioritize schedule certainty over rate competition.
Supply Chain Analysis
Reverse-logistics flows of recovered jacket steel from Danish sector fields to Aalborg and Rotterdam recycling yards create circular material pathways under EU Green Deal incentives. Supply concentration rests on Norway, the Netherlands, and Denmark for heavy-lift vessel mobilization and specialized well abandonment expertise. Raw material dependencies center on high-strength structural steel grades, marine-grade coatings, and specialized cement formulations for chalk reservoir plugging. Single-source vulnerability concentrates among Norwegian specialists for deep-set abandonment operations at Tyra field. Distribution runs through integrated marine service providers with owned fleet capacity rather than brokered vessel arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Denmark offshore decommissioning functions as a North Sea geographic-arbitrage play, with Harbor-Næstved industrial cluster development capturing steel recycling flows that Rotterdam yards currently dominate.
For Market Incumbents: Extend fleet capacity utilization through multi-field campaign bundling to amortize heavy-lift vessel mobilization costs across Tyra, Dan, and Halfdan removal programs. Acquire ROV-AUV convergence capabilities through service company alliances to defend against autonomous technology disruption from Maersk Drilling partnerships. Prioritize backward integration into steel recycling through Harbor-Næstved yard investments to capture EU Green Deal circularity premiums. For New Entrants and Emerging Players: Digital-channel route through shore-based remote operation centers enables low-capital entry into continuous jacket inspection services without surface vessel ownership. Target shallow-water Dan field installations with low-impact cutting technologies for stringent biotope recovery mandates. Pursue asset manager relationships as operators unbundle engineering, marine transport, and yard phases at Halfdan field. For Investors and Strategic Acquirers: Consolidation pressure builds where heavy-lift vessel scarcity concentrates contract awards among integrated providers with owned fleet capacity. Long-term viability favors specialists with resident AUV deployment capabilities and EU-flagged recycling facility access. Monitor Danish Energy Agency marine spatial planning revisions for early signals of in-country dismantling preference over export routes.| Strategic Initiative | Industry Significance |
|---|---|
| Heavy-Lift Vessel Fleet Expansion | Owned crane capacity secures Tyra field bundled removal contracts against Rotterdam competitors. |
| ROV-AUV Convergence Alliance | Maersk Drilling partnerships enable continuous jacket inspection without surface vessel day-rate exposure. |
| Harbor-Næstved Yard Investment | Deep-water quay expansion captures steel recycling flows under EU Green Deal circularity incentives. |
| OSPAR 98/3 Certification Program | Third-party validation from Bureau Veritas accelerates Danish Energy Agency compliance timelines. |
| Resident AUV Technology Licensing | Battery-powered autonomous systems displace diver-dependent operations in hazardous subsea cutting tasks. |
Study Parameters
Bottom-up platform removal modeling reconciled against top-down heavy-lift vessel capacity tracking forms the analytical core of this study. Primary interviews with decommissioning project managers, Danish Energy Agency regulatory officers, heavy-lift vessel chartering executives, and Aalborg yard operations directors combined with secondary validation from OSPAR Convention submissions, Danish Maritime Authority permitting records, EU ETS steel sector disclosures, and North European scrap steel index publications. Triangulation between contractor procurement patterns and operator capital expenditure disclosures anchored segmentation splits.
Input-output matrix framing connects field-specific removal volumes through service type, technology choice, and project size dimensions across the modeling period. CAGRs derive from installed base retirement curves and regulatory deadline compression effects. Segmentation dimensions include platform removal versus pipeline abandonment service splits, mechanical cutting versus ROV technology adoption trajectories, and oil producer versus asset manager end-user procurement patterns. Forecast inputs incorporate EU Offshore Safety Directive enforcement timelines and electrification retrofit failure rates at mature Danish fields.
The model assumes a particular technology adoption path; alternative pathways for autonomous underwater vehicle convergence would alter the outlook if regulatory approval accelerates beyond Danish Maritime Authority UXO clearance protocols. Forecasts reflect assumptions regarding heavy-lift vessel availability and EU Green Deal steel circularity incentive durability. Practitioners should monitor Danish marine spatial planning revisions and carbon-accounting rule changes for early signals of dismantling location preference shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Offshore Oilfield Services Market
Offshore Oil and Gas
Brazil Offshore Oil & Gas Upstream Market
Offshore Oil and Gas
Iran Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Equipment Market
Offshore Oil and Gas
North Sea Offshore Decommissioning Market
Offshore Oil and Gas
Southeast Asia Offshore Seismic Survey Market
Offshore Oil and Gas
Offshore Rental Equipment Market
Offshore Oil and Gas
Brazil Offshore Energy Market
Offshore Oil and Gas
India Oil and Gas Downstream Market
Offshore Oil and Gas
Oil and Gas Magnetic Ranging Market
Offshore Oil and Gas
Asia Pacific Offshore Seismic Services Market
Offshore Oil and Gas
East Africa Oil and Gas Midstream Market
Offshore Oil and Gas
Offshore Oil and Gas Communications Market
Offshore Oil and Gas
Turkmenistan Oil and Gas Upstream Market
Offshore Oil and Gas
Brazil Oil and Gas Downstream Market
Offshore Oil and Gas
Gabon Oil and Gas Downstream Market