
 North Sea Oil and Gas Market | 2026-2036
North Sea Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
North Sea Oil and Gas Market Analytics
Multi-source contracting for subsea engineering services is expanding across marginal field developments. Equinor ASA leverages integrated drilling and completion capabilities to dominate Norway's deepwater frontier. Harbour Energy anchors UK Central North Sea production through its inherited Premier Oil and Chrysaor portfolios. BP Plc sustains long-cycle investment in Clair Ridge and Quad 204 redevelopment.
North Sea oil and gas encompasses offshore hydrocarbon extraction from Paleocene-Eocene sandstone reservoirs at water depths reaching 300 meters, requiring subsea tiebacks, floating production platforms, and pipeline export systems to deliver crude and natural gas to onshore terminals. The production segment occupies the dominant value share as brownfield redevelopment and enhanced oil recovery extend field life beyond original design limits. Subsea systems technology leads capital deployment as operators advance all-electric trees and multiphase pumps to reduce topside footprint and intervention costs. Independent operators represent the fastest-growing end-user category as private equity-backed firms acquire mature assets from majors seeking portfolio rationalization.
The UK North Sea Transition Authority enforces net-zero basin targets through the North Sea Transition Deal, while Norway's Petroleum Safety Authority and CO2 storage regulations shape field development economics and decommissioning liabilities. The EU Green Deal and methane performance standards tighten operational compliance for cross-border pipeline gas entering continental markets. Stakeholders must weigh remaining reserve recovery against carbon intensity benchmarks and electrification infrastructure timing.
Market Dynamics
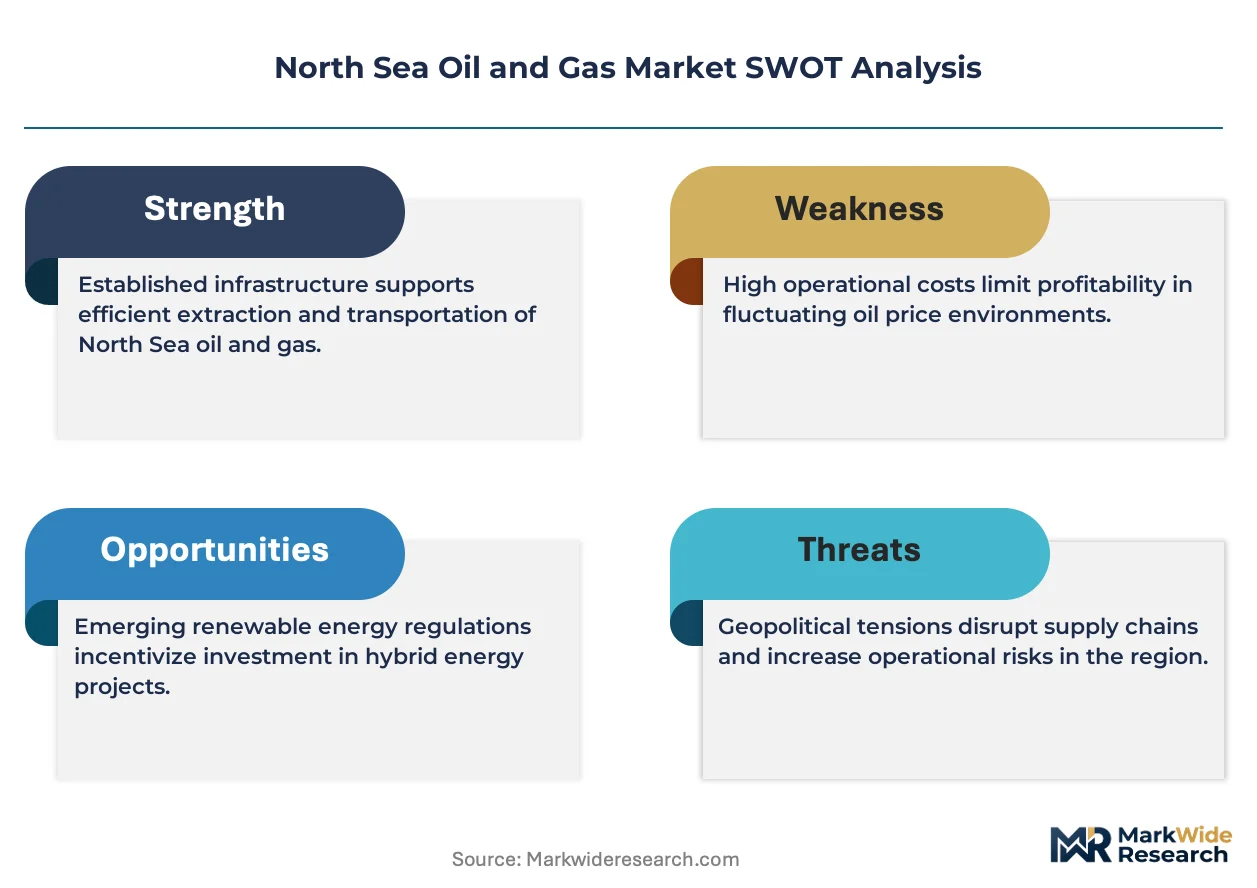
The North Sea Oil and Gas Market operates under acute pressure from the UK North Sea Transition Authority's decommissioning mandates and Norway's CO2 storage regulations, which compress field economics and force operators to front-load electrification investments before reserves deplete.
Growth Catalysts
- Enhanced Oil Recovery:Polymer flooding and gas injection techniques extend production from mature Paleocene-Eocene sandstone reservoirs beyond original design limits. Brownfield redevelopment absorbs the majority of capital deployment as operators maximize remaining reserve recovery.
- UK North Sea Transition Deal:This regulatory framework mandates methane reduction targets and electrification timelines, creating compliance-driven demand for subsea all-electric trees and topside power-from-shore infrastructure.
- Johan Sverdrup Cluster:Norway's largest producing field complex concentrates new production demand, requiring integrated drilling services and subsea tieback systems that anchor supplier order books across the Norwegian Continental Shelf.
Market Restraints
- Steel and Specialty Alloy Costs:Subsea manifold fabrication and pipeline construction face input cost volatility from nickel and chromium price swings, compressing project margins before final investment decisions.
- Decommissioning Liability Concentration:The UK Central North Sea holds the highest density of end-of-life platforms, creating concentrated asset-retirement obligations that deter new entrants and strand marginal field opportunities.
- Carbon Intensity Benchmarks:The EU Green Deal's methane performance standards impose operational compliance costs on cross-border pipeline gas, disadvantaging higher-carbon production against imported LNG alternatives.
Strategic Opportunities
- CO2 Storage Licensing:Norway's Petroleum Safety Authority regulations enable depleted hydrocarbon reservoirs to transition into carbon sequestration assets, creating dual-revenue streams for infrastructure owners.
- Power-from-Shore Electrification:Converging offshore wind and platform power demand allows shared cable infrastructure, reducing topside generator footprint and operational emissions simultaneously.
- Independent Operator Acquisition Pipeline:Private equity-backed firms target mature assets divested by majors, creating demand for subsea intervention services and late-life field management expertise.
Industry Challenges
- Subsea Systems Integration:All-electric tree deployment requires reconfiguration of existing topside control systems, creating interface complexity with legacy hydraulic infrastructure.
- Electrification Engineering Talent:The specialized skill set for high-voltage subsea power distribution remains scarce, constraining project execution timelines across multiple field developments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North Sea Oil and Gas Market |
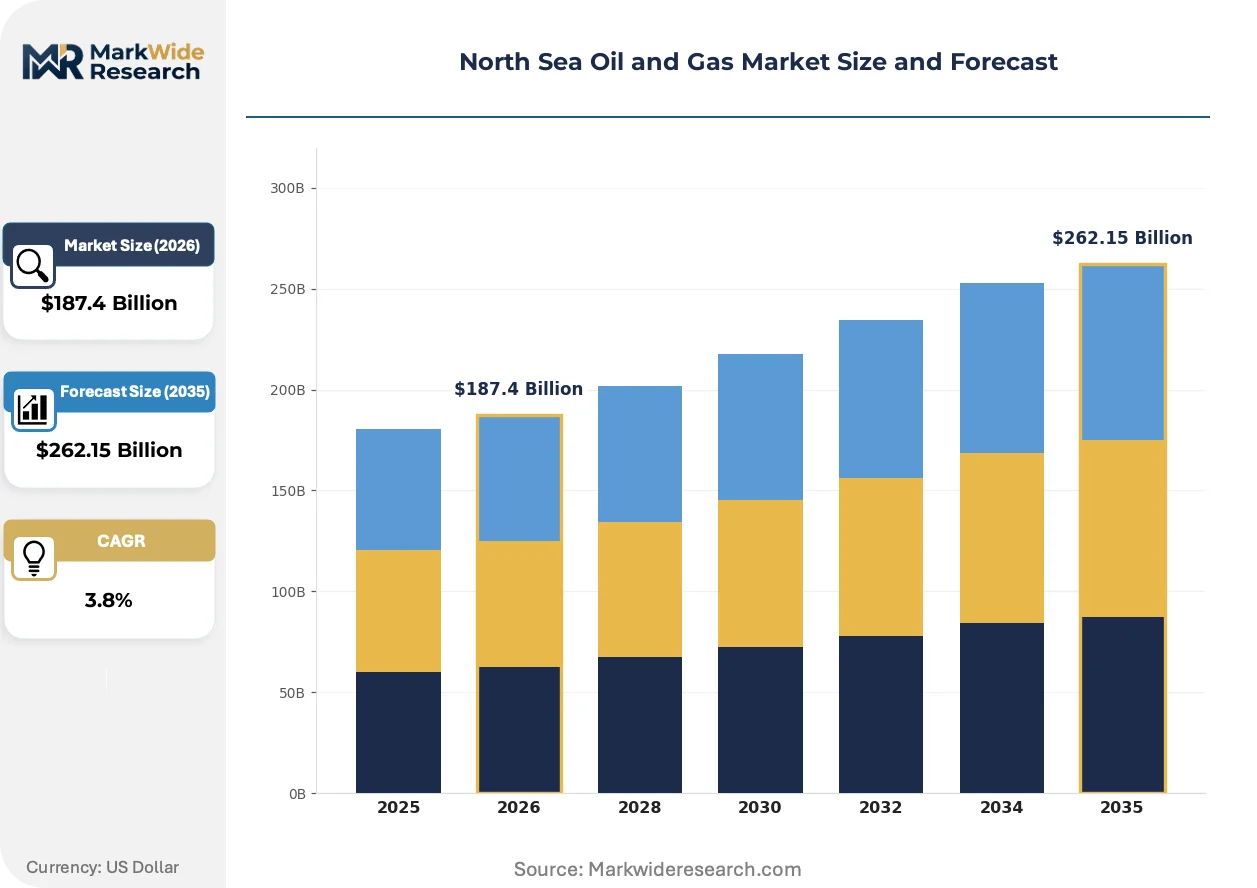
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $262.15 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Exploration, Production, Refining, Distribution Service Type: Drilling, Engineering, Maintenance, Environmental Technology: Subsea Systems, Enhanced Oil Recovery, Gas Processing, Monitoring Solutions End User: Independent Operators, National Oil Companies, Offshore Contractors, Service Providers |
| Companies Covered | Equinor ASA, BP Plc, Shell Plc, Harbour Energy, Ithaca Energy, TotalEnergies, INEOS Group, Neptune Energy, Perenco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North Sea Oil and Gas Market Evolving Landscape
Subsea engineering is pivoting from hydraulic to all-electric architectures, while regulatory frameworks force carbon accounting transparency and buyer procurement models prioritize emissions intensity alongside unit cost.
All-electric subsea production systems eliminate hydraulic fluid lines and reduce topside footprint through subsea power distribution and electrically actuated valves. Norwegian deepwater operators are deploying these systems at scale across new field developments. This technology is electrifying field architecture by enabling longer step-out distances and reducing intervention vessel requirements.
The UK North Sea Transition Authority enforces net-zero basin targets through mandatory methane monitoring and electrification timelines tied to license extensions. Operators must demonstrate progress toward emissions reduction or face production consent delays. The UK Central North Sea mature asset portfolio bears the highest compliance burden, accelerating power-from-shore project sanctioning.
Power generation utilities across Northern Europe now embed carbon intensity clauses into long-term offtake contracts, displacing pure price-based procurement. This contractual evolution favors lower-carbon Norwegian production over higher-carbon UK Central North Sea supply. German and Dutch utility procurement desks are driving this preference shift most visibly.
North Sea Oil and Gas Market Segmentation
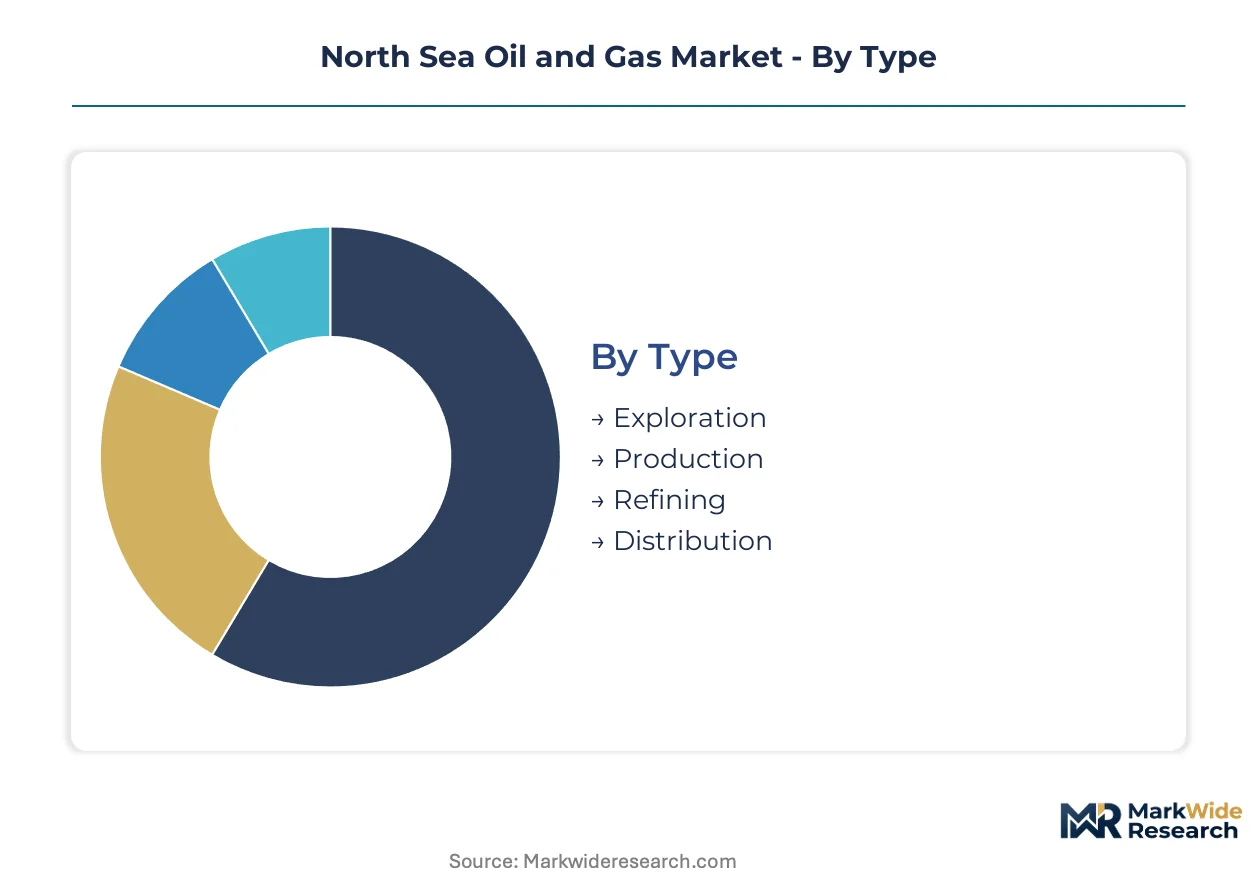
Segmentation in the North Sea oil and gas market reveals how capital allocation splits between mature asset optimization and frontier development. Technology choices and operator type determine project economics under tightening methane regulations and electrification mandates.
Type:
Technical maturity and reserve depletion rates differentiate investment intensity across the value chain.
- Exploration:Seismic acquisition and wildcat drilling target Paleocene-Eocene sandstone formations at water depths approaching 300 meters. Norway's Johan Sverdrup cluster and UK West of Shetland basins concentrate remaining greenfield prospectivity, though licensing rounds have slowed under net-zero policy pressure.
- Production:Brownfield redevelopment absorbs dominant capital share as polymer flooding and gas injection extend field life beyond original design limits. UK Central North Sea mature assets and Norwegian Continental Shelf producing complexes anchor operational expenditure.
- Refining:Crude stabilization and natural gas liquids extraction occurs at onshore terminals including St Fergus, Teesside, and Mongstad. These facilities face carbon intensity benchmarking under EU Green Deal methane performance standards.
- Distribution:Pipeline export systems and shuttle tanker operations deliver hydrocarbons to continental European markets. Cross-border infrastructure faces regulatory compliance costs that disadvantage higher-carbon production against imported LNG alternatives.
Mature deployment sits with Production. Newer deployment is concentrated in Exploration.
Service Type:
Contractor capability depth shapes procurement decisions for complex subsea interventions.
- Drilling:Integrated drilling and completion services dominate Norway's deepwater frontier, requiring high-specification rigs capable of extended-reach horizontal wells. Equinor ASA's Johan Sverdrup development anchors supplier order books.
- Engineering:Subsea tieback design and floating production platform specification demand multi-source contracting across marginal field developments. All-electric tree architecture and power-from-shore integration represent fastest-expanding engineering scope.
- Maintenance:Late-life asset integrity management and well intervention sustain output from end-of-life platforms. UK Central North Sea holds highest density of maintenance-intensive infrastructure.
- Environmental:Methane monitoring, emissions verification, and decommissioning liability assessment respond to UK North Sea Transition Authority mandates. CO2 storage site characterization represents emerging service demand under Norway's Petroleum Safety Authority regulations.
High-margin deployment sits with Engineering. Compliance-driven expansion is concentrated in Environmental.
Technology:
Electrification and digitalization intensity separate capital deployment strategies.
- Subsea Systems:All-electric production trees eliminate hydraulic fluid lines and reduce topside footprint through subsea power distribution. Norwegian operators deploy these at scale for longer step-out distances and reduced intervention vessel requirements.
- Enhanced Oil Recovery:Polymer flooding and gas injection techniques maximize remaining reserve recovery from sandstone reservoirs. Brownfield applications absorb majority of EOR capital as operators front-load investment before decommissioning timelines.
- Gas Processing:Platform-based compression and offshore LNG liquefaction handle associated gas from oil-dominant fields. UK North Sea Transition Deal electrification timelines accelerate power-from-shore integration for gas processing assets.
- Monitoring Solutions:Subsea sensors and topside digital twins enable predictive maintenance and emissions tracking. Mandatory methane monitoring under UK and Norwegian regulations drives procurement.
Capital-intensive deployment sits with Subsea Systems. Regulatory-driven adoption is concentrated in Monitoring Solutions.
End User:
Balance sheet capacity and regulatory sophistication determine market participation.
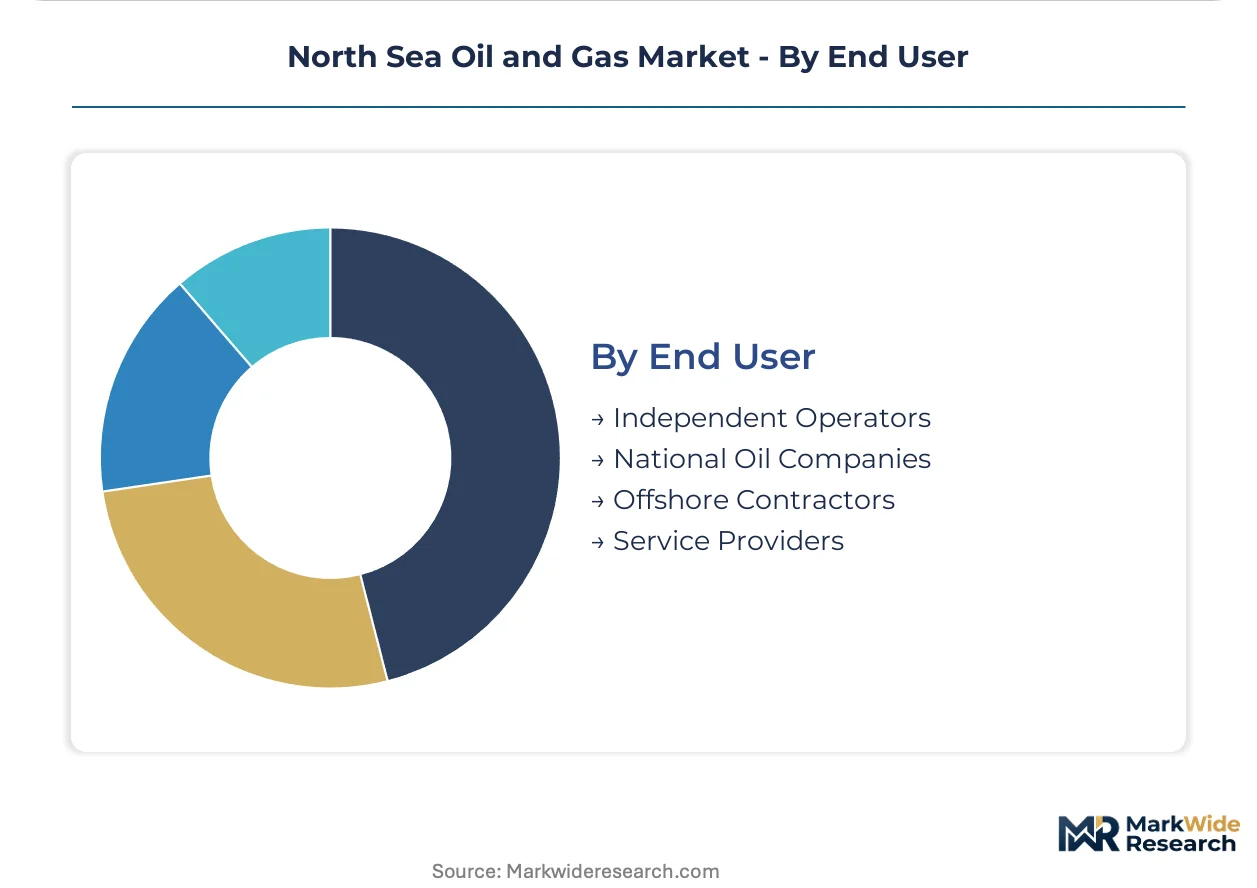
- Independent Operators:Private equity-backed firms acquire mature assets divested by majors seeking portfolio rationalization. These operators demand subsea intervention services and late-life field management expertise, climbing the fastest among end-user categories.
- National Oil Companies:Equinor ASA dominates Norwegian Continental Shelf investment through integrated project execution. State-backed financing enables long-cycle commitment to deepwater frontier developments.
- Offshore Contractors:Subsea installation and platform construction specialists execute brownfield redevelopment and decommissioning programs. UK Central North Sea asset-retirement obligations concentrate contractor activity.
- Service Providers:Engineering consultancies and equipment suppliers support electrification infrastructure and emissions compliance. Talent scarcity in high-voltage subsea power distribution constrains execution capacity.
Consolidated deployment sits with National Oil Companies. Acquisition-driven expansion is concentrated in Independent Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paleocene-Eocene sandstone reservoirs beneath the Norwegian Continental Shelf and UK Central North Sea anchor regional hydrocarbon output. Water depths reaching 300 meters demand subsea tiebacks and floating production platforms with pipeline export systems.
Norway
The Johan Sverdrup cluster concentrates new production demand through integrated drilling services and subsea tieback systems. Norway's Petroleum Safety Authority and CO2 storage regulations shape field development economics and decommissioning liabilities. Equinor ASA dominates deepwater frontier investment from the Stavanger operational hub.
United Kingdom
Harbour Energy anchors Central North Sea production through inherited Premier Oil and Chrysaor portfolios. The UK North Sea Transition Authority enforces net-zero basin targets through the North Sea Transition Deal with methane reduction mandates. Aberdeen sustains engineering service concentration despite accelerating decommissioning timelines.
Denmark
Power generation utilities across Northern Europe anchor the largest share of offtake from Danish offshore fields. EU Green Deal methane performance standards tighten operational compliance for cross-border pipeline gas entering continental markets. The Tyra field redevelopment concentrates subsea engineering procurement.
Netherlands
Rotterdam and Amsterdam terminals process natural gas liquids from North Sea pipeline imports. German and Dutch utility procurement desks embed carbon intensity clauses into long-term offtake contracts. The Groningen seismic restrictions redirect supply dependence toward offshore Norwegian and UK sources.
North Sea Oil and Gas Market Competitive Landscape
Portfolio rationalization dominates the current landscape as majors divest mature assets to private equity-backed independents. The vendor base splits between state-backed national oil companies with integrated execution capabilities and specialized independents focused on late-life field management. Strategic archetypes include deepwater frontier developers, brownfield optimization specialists, and decommissioning service providers. M&A consolidation and electrification infrastructure partnerships represent the dominant competitive vectors reshaping supplier relationships.
Among Norway-based integrated operators, Equinor ASA exemplifies state-backed financing enabling long-cycle commitment to subsea all-electric tree deployment. UK-focused independents Harbour Energy and Ithaca Energy occupy positions within the acquisition-driven tier, consolidating end-of-life platforms and demanding subsea intervention services. These three anchors span the competitive spectrum from frontier development through mature asset stewardship.
| Leading Market Players |
|---|
| Equinor ASA |
| BP Plc |
| Shell Plc |
| Harbour Energy |
| Ithaca Energy |
| TotalEnergies |
| INEOS Group |
| Neptune Energy |
| Perenco |
| Others |
Value Network & Pricing Analysis
Power generation utilities across Northern Europe anchor contract structures through long-term offtake agreements with embedded carbon intensity clauses. Pricing stratifies across premium low-carbon Norwegian supply, standard UK North Sea production, and higher-carbon marginal field tiers.
Pricing Analysis
Service bundling separates integrated drilling and completion packages from unbundled subsea engineering procurement. Three-tier pricing structure across premium, standard, and economy levels reflects methane performance certification, electrification infrastructure access, and volume commitment scale. Cost compression in UK Central North Sea brownfield services is intensifying because decommissioning liability concentration deters new supplier entry. Independent operators exhibit highest price sensitivity due to private equity return thresholds, while Equinor ASA's state-backed financing absorbs premium tier positioning.
Supply Chain Analysis
Subsea manifold fabrication draws from Norwegian engineering hubs, UK Aberdeen service clusters, and Dutch offshore fabrication yards. Nickel and chromium alloy supply rests on South African mining operations, Finnish specialty steel producers, and German precision component manufacturers. Single-source vulnerability concentrates in high-voltage subsea power distribution systems where electrification engineering talent scarcity constrains execution capacity. Distribution runs through integrated operator direct procurement for frontier developments and multi-source contracting channels for marginal field redevelopment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North Sea oil and gas market functions as a cost-of-compliance arena where the UK North Sea Transition Deal erects regulatory moats favoring operators with capitalized electrification infrastructure.
For Market Incumbents: Cement power-from-shore integration capabilities before decommissioning timelines strand marginal field economics. Acquire late-life asset management expertise through specialist hiring or capability partnerships to defend against private equity-backed independents capturing maintenance-intensive UK Central North Sea portfolios. Prioritize subsea all-electric tree deployment to meet Norwegian Petroleum Safety Authority electrification mandates.
For New Entrants and Emerging Players: Enter via CO2 storage site characterization services under Norway's reservoir transition regulations. Target environmental compliance and methane monitoring segments where UK North Sea Transition Authority mandates create demand visibility. Pursue subsea intervention service contracts with independent operators lacking in-house late-life field management capabilities.
For Investors and Strategic Acquirers: The window for entry favors infrastructure owners with dual-revenue carbon sequestration potential. Long-term viability centers on depleted reservoir assets with pipeline connectivity for CO2 storage licensing. Watch independent operator consolidation velocity as the signal for subsea service provider margin inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Power-from-Shore Electrification | Reduces topside generator footprint while satisfying UK North Sea Transition Authority consent requirements. |
| CO2 Storage Licensing | Converts depleted Norwegian reservoirs into carbon sequestration assets under Petroleum Safety Authority regulations. |
| All-Electric Subsea Deployment | Enables longer step-out distances and reduces intervention vessel requirements for Johan Sverdrup cluster expansions. |
| Late-Life Asset Acquisition | Consolidates UK Central North Sea production base through Premier Oil and Chrysaor portfolio integration models. |
| Methane Monitoring Infrastructure | Mandatory under EU Green Deal performance standards for cross-border pipeline gas entering German and Dutch markets. |
Research Methodology
Document review covered regulatory filings from the UK North Sea Transition Authority and Norway's Petroleum Safety Authority, complemented by interviews with offshore project engineers, subsea equipment procurement leads, EPC contractors, and power utility offtake managers. Secondary sources included EU emissions trading data, North Sea licensing round records, and operator annual reports. Bottom-up field development project tracking and top-down basin production estimates were triangulated for market sizing.
Historical capital expenditure patterns were cross-referenced against expert panel input on electrification timeline feasibility. The analytical framework modeled deployment across type, service category, technology, and end-user segments throughout the forecast period. CAGRs were derived from project sanctioning velocity and reserve depletion curves. Forecast inputs incorporated subsea systems technology adoption rates and independent operator acquisition pipeline visibility.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated decommissioning mandate revisions or carbon border adjustment mechanism expansions. A small set of named triggers warrants ongoing watch: UK license extension policy shifts, Norwegian CO2 storage royalty frameworks, and German utility procurement desk carbon intensity threshold adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Asia Pacific Oil and Gas CAPEX Market
Offshore Oil and Gas
Thailand Oil and Gas Downstream Market
Offshore Oil and Gas
Turkmenistan Oil and Gas Upstream Market
Offshore Oil and Gas
Europe Jackup Rig Market
Offshore Oil and Gas
Brazil Oil and Gas Upstream Market
Offshore Oil and Gas
Egypt Oil and Gas Upstream Market
Offshore Oil and Gas
Denmark Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Marine Mining Market
Offshore Oil and Gas
Subsea Equipment Market
Offshore Oil and Gas
Brazil Offshore Oil & Gas Upstream Market
Offshore Oil and Gas
Iran Oil and Gas Downstream Market
Offshore Oil and Gas
East Africa Oil and Gas Midstream Market
Offshore Oil and Gas
Europe Oil and Gas Separation Market
Offshore Oil and Gas
United Kingdom Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Central Asia Oil and Gas Upstream Market
Offshore Oil and Gas
Connected Solutions for Oil and Gas Market