
 East Africa Oil and Gas Midstream Market | 2026-2036
East Africa Oil and Gas Midstream Market Size, Share, and Industry Trends Forecast 2026-2036
East Africa Oil and Gas Midstream Market Foresight
Independent power producers are reorganizing procurement priorities around firm gas transportation contracts, displacing traditional utility direct-purchase models. TotalEnergies leverages its integrated LNG portfolio to secure throughput agreements across regional terminals. Kenya Pipeline Company Ltd anchors domestic distribution networks with exclusive rights on the Mombasa-Nairobi conduit. Tanzania Petroleum Development Corporation controls upstream-midstream linkages through participation in the Songo Songo gas processing chain.
East Africa oil and gas midstream encompasses the transportation, storage, and processing infrastructure bridging extraction points with downstream refineries and consumers, operating through pipelines rated for crude oil, natural gas, and refined products across varying pressure specifications and diameter classes. The primary commercial purpose centers on reducing logistics costs for landlocked producers while enabling export access to Indian Ocean shipping lanes. Pipeline infrastructure dominates capital deployment, absorbing the majority of sector investment as developers prioritize long-haul crude conduits from Ugandan fields to Tanzanian ports. Smart monitoring technology represents the fastest-expanding segment, with operators deploying SCADA systems and leak detection sensors to reduce unplanned outages and satisfy insurer requirements. Storage terminals constitute the most mature category, with existing tank farms in Mombasa and Dar es Salaam operating near design capacity and limiting near-term margin expansion.
Kenya's Petroleum Regulatory Authority and Tanzania's Energy and Water Utilities Regulatory Authority enforce pipeline safety codes and environmental impact standards that determine project approval timelines and capital recovery profiles. Uganda's Petroleum Authority applies local content regulations mandating domestic contractor participation in construction and maintenance activities, reshaping vendor selection criteria for international developers. Stakeholders must monitor regulatory harmonization progress across the East African Community, as divergent permitting regimes threaten to fragment cross-border infrastructure economics and delay integrated network development.
Market Dynamics
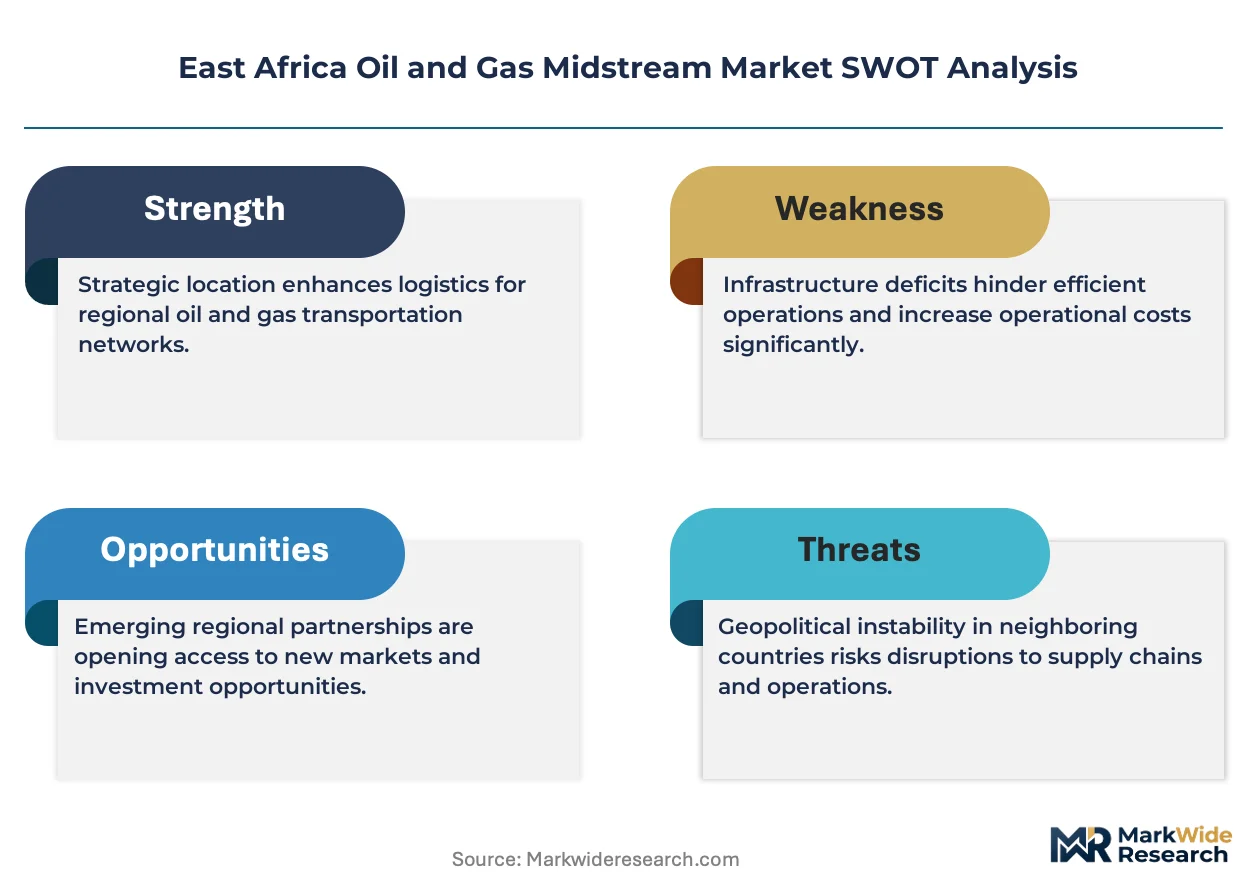
Cross-border pipeline economics are fragmenting as divergent permitting timelines between Kenya's Petroleum Regulatory Authority and Tanzania's Energy and Water Utilities Regulatory Authority create stranded capacity risks and force developers to sequence investments around political cycles rather than reservoir depletion rates.
Growth Catalysts
- Uganda's Local Content Regulations:Mandatory domestic contractor participation in construction and maintenance activities is forcing international developers to build permanent local engineering capabilities, deepening regional supply chain roots.
- Power Generation Utilities:Independent power producers are reorganizing procurement priorities around firm gas transportation contracts, displacing traditional utility direct-purchase models and locking in pipeline throughput.
- SCADA Deployment:Smart monitoring technology is reducing unplanned outages and satisfying insurer requirements, accelerating capital deployment into digitally integrated pipeline networks.
Market Restraints
- Capital Intensity:Long-haul crude conduits from Ugandan fields to Tanzanian ports absorb the majority of sector investment, starving storage terminal expansion and limiting margin recovery.
- Regulatory Fragmentation:Divergent permitting regimes across the East African Community threaten to fragment cross-border infrastructure economics and delay integrated network development.
- Storage Capacity Saturation:Existing tank farms in Mombasa and Dar es Salaam operating near design capacity constrain near-term throughput growth for new production.
Strategic Opportunities
- Tanzania's Southern Gas Corridor:Offshore discoveries feeding onshore processing infrastructure create anchor demand for expanded transmission and distribution networks.
- Cross-Border Harmonization:Streamlined pipeline permitting frameworks between national regulators would unlock economies of scale for regional infrastructure consortia.
- Digital Twin Integration:Convergence of leak detection sensors with predictive maintenance analytics enables outcome-based service contracts for pipeline operators.
Industry Challenges
- Specialized Welding Certification:Uganda's Petroleum Authority mandates specific domestic certification timelines for high-pressure pipeline construction, compressing project schedules.
- Legacy System Integration:New SCADA deployments must interface with decades-old manual monitoring infrastructure at Mombasa and Dar es Salaam terminals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | East Africa Oil and Gas Midstream Market |
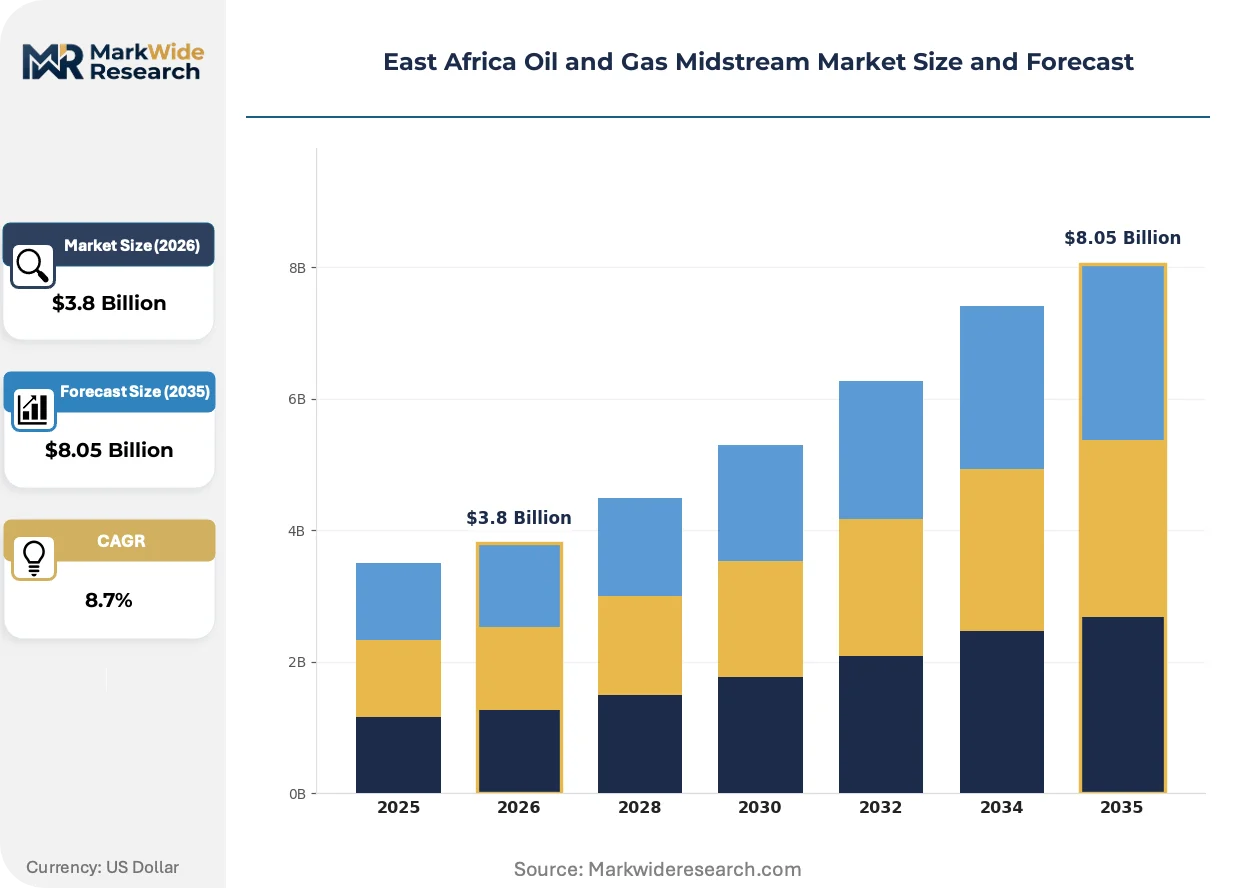
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Infrastructure Type: Pipelines, Storage Terminals, Processing Facilities, Loading Jetties Service Type: Transportation, Storage, Refining, Distribution Technology: Conventional, Modular, Smart Monitoring, LNG Technology End User: Government Agencies, Oil Companies, Logistic Providers, Industry Stakeholders |
| Companies Covered | TotalEnergies, China National Petroleum Corporation, Petróleos de Moçambique SA, Kenya Pipeline Company Ltd, Eni S.p.A., Tullow Oil, Tanzania Petroleum Development Corporation, Uganda National Oil Company, Oil and Natural Gas Corporation, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
East Africa Oil and Gas Midstream Market Shifts & Advancements
Operational technology investment patterns are fragmenting as pipeline operators balance legacy asset sweat against digital retrofit economics, with financing structures adapting to accommodate hybrid infrastructure lifecycles.
Advanced leak detection systems combining fiber-optic sensing with acoustic monitoring are fragmenting the traditional inspection services market. Major transmission operators are adopting these packages on greenfield projects while retrofitting critical segments of existing networks. The technology is fragmenting vendor relationships as integrated solution providers displace specialized inspection contractors.
Kenya's Petroleum Regulatory Authority and Tanzania's Energy and Water Utilities Regulatory Authority are converging safety code enforcement timelines to reduce cross-border project delays. This coordination is compressing environmental impact assessment periods for regional pipeline consortia. Developers are responding by consolidating permitting strategies around synchronized approval windows.
Independent power producers are unbundling long-term offtake agreements into shorter-duration, volume-flexible contracts indexed to spot LNG prices. This restructuring is displacing traditional utility direct-purchase models that locked in fixed volumes. Tanzania's southern gas corridor is witnessing the most aggressive contract restructuring as offshore production scales.
East Africa Oil and Gas Midstream Market Segmentation
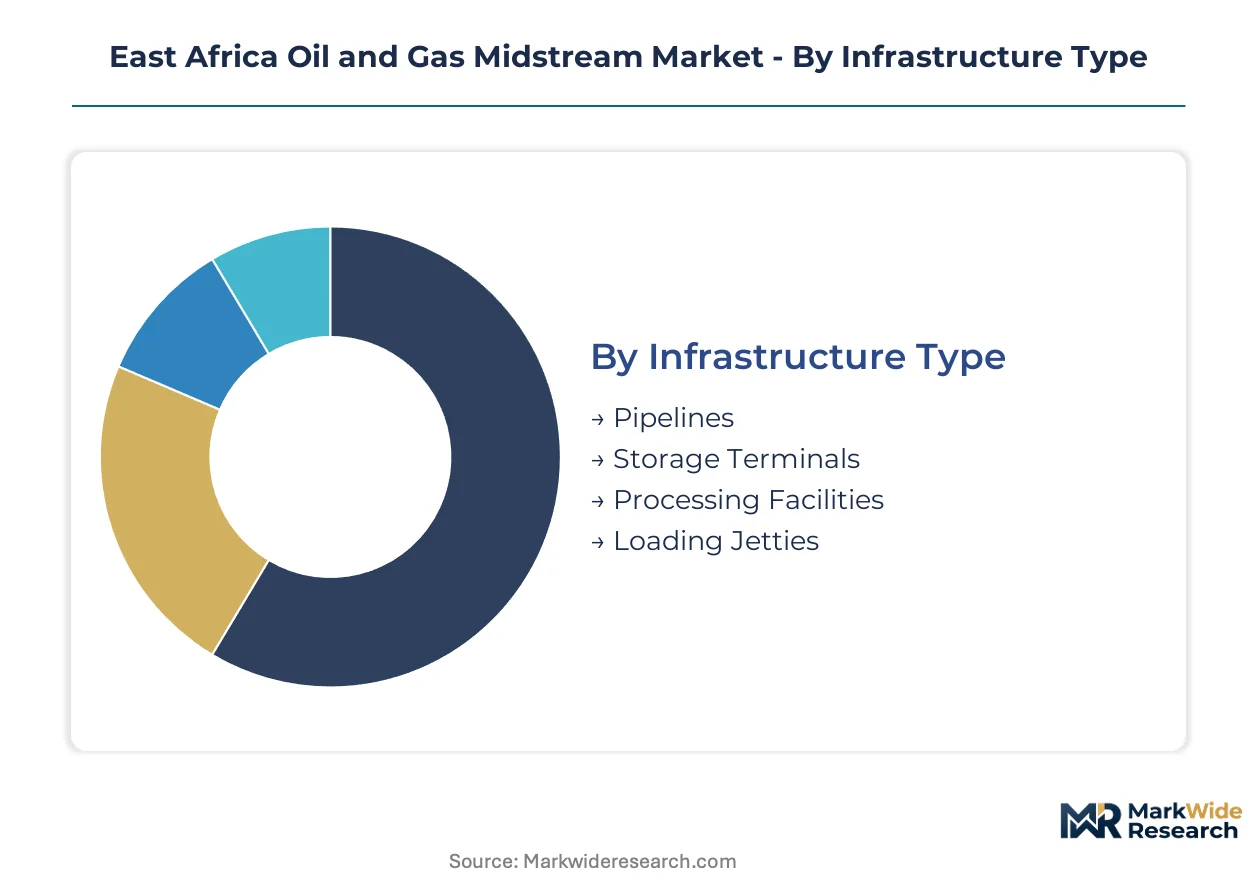
East Africa's midstream infrastructure investment decisions fragment across four distinct segmentation axes. Regulatory frameworks in Kenya, Tanzania, and Uganda create divergent compliance burdens that reshape capital allocation across infrastructure types and service categories.
Infrastructure Type:
Kenya's Petroleum Regulatory Authority applies stricter safety codes to pipeline construction than Tanzania's Energy and Water Utilities Regulatory Authority, creating cost tier differentiation across the region.
- Pipelines:Long-haul crude conduits rated for high-pressure transmission dominate capital deployment, with Uganda's Lake Albert fields driving demand for export routes to Tanzanian ports. Kenya Pipeline Company Ltd maintains exclusive rights on the Mombasa-Nairobi trunk line, locking in throughput economics for refined products distribution.
- Storage Terminals:Existing tank farms in Mombasa and Dar es Salaam operate near design capacity, constraining margin expansion for new production volumes. Independent operators face extended permitting timelines for greenfield terminal development under divergent national environmental standards.
- Processing Facilities:Tanzania's Songo Songo gas processing chain anchors regional capacity, with Tanzania Petroleum Development Corporation controlling upstream-midstream linkages through direct participation.
- Loading Jetties:Indian Ocean port infrastructure at Dar es Salaam and Mombasa handles the majority of regional export volumes, with jetty utilization rates dictating tanker scheduling economics.
Pipelines handle the majority of throughput; Smart Monitoring integration is the fastest mover on share.
Service Type:
Customer type determines contract structure, with power generation utilities shifting procurement toward firm transportation agreements.
- Transportation:Independent power producers are reorganizing procurement priorities around firm gas transportation contracts, displacing traditional utility direct-purchase models. Cross-border pipeline economics fragment as divergent permitting timelines between national regulators create stranded capacity risks.
- Storage:Tank farm operators in Mombasa and Dar es Salaam face capacity saturation, limiting near-term throughput growth for new production volumes. Legacy terminal infrastructure requires digital retrofit investments to satisfy evolving insurer requirements.
- Refining:Kenya's petroleum regulatory framework shapes domestic refining economics, with import dependency driving midstream infrastructure prioritization.
- Distribution:Last-mile logistics networks concentrate around Nairobi and Dar es Salaam demand centers, with urban fuel retail infrastructure expanding to capture transport sector consumption.
Transportation commands the largest revenue pool; firm contract restructuring is expanding most quickly.
Technology:
Application focus determines deployment priority, with leak detection and predictive maintenance reshaping operational expenditure profiles.
- Smart Monitoring:SCADA systems and fiber-optic leak detection sensors reduce unplanned outages and satisfy insurer requirements for new capital deployment. Major transmission operators are adopting integrated packages on greenfield projects while retrofitting critical segments of existing networks.
- Conventional:Decades-old manual monitoring infrastructure at Mombasa and Dar es Salaam terminals requires phased replacement, creating hybrid operational technology environments.
- Modular:Standardized processing units enable faster deployment timelines for Tanzania's southern gas corridor expansion, reducing construction risk for offshore-to-onshore linkages.
- LNG Technology:TotalEnergies leverages integrated LNG portfolio capabilities to secure throughput agreements across regional terminals, anchoring liquefaction infrastructure development.
Conventional systems retain installed base dominance; Smart Monitoring is climbing the fastest on new investment share.
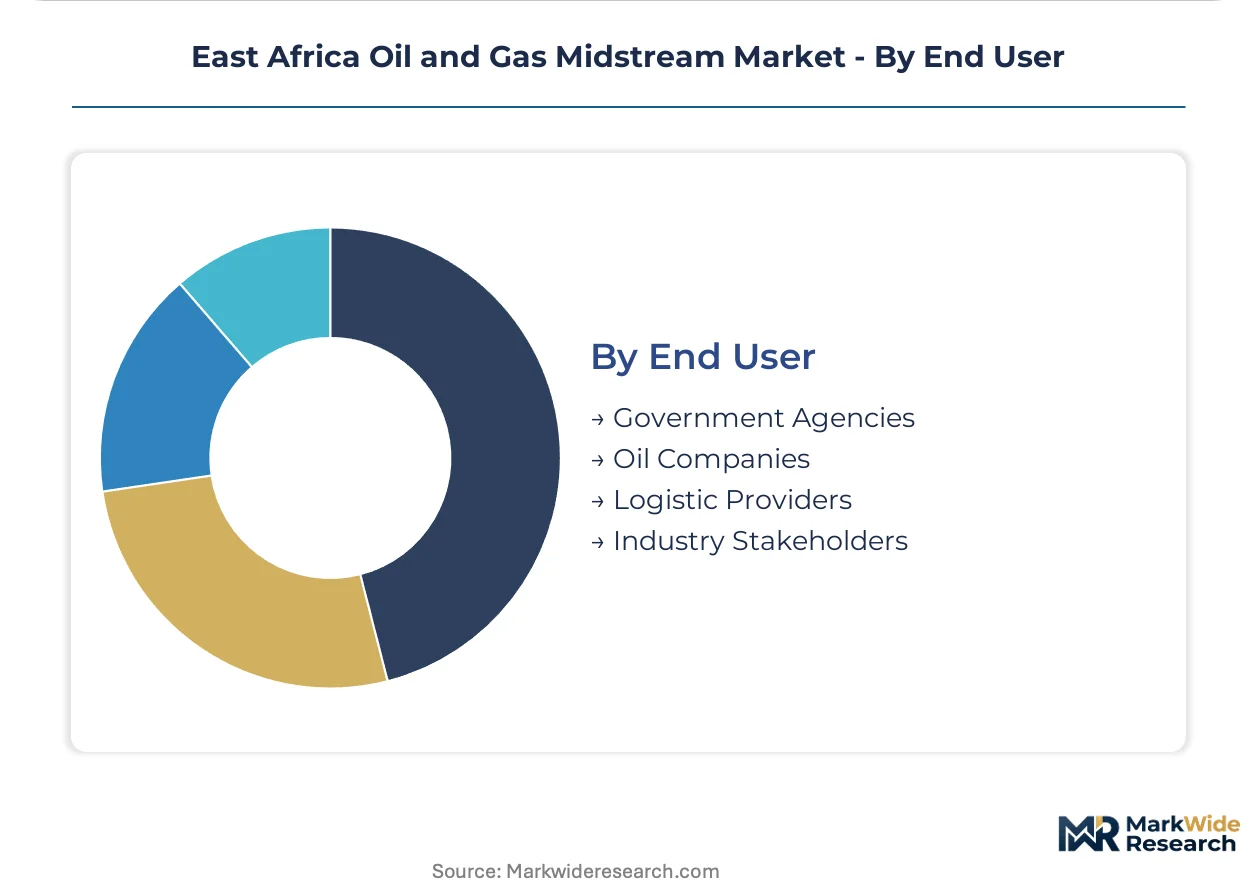
End User:
Volume concentration shapes infrastructure access priorities, with government-backed entities controlling anchor capacity commitments.
- Oil Companies:International developers must build permanent local engineering capabilities to satisfy Uganda's Petroleum Authority local content regulations, deepening regional supply chain roots through mandatory domestic contractor participation.
- Government Agencies:Kenya's Petroleum Regulatory Authority and Tanzania's Energy and Water Utilities Regulatory Authority streamline cross-border pipeline permitting frameworks, with synchronized approval windows consolidating developer strategies.
- Logistic Providers:Third-party terminal operators face margin compression from storage capacity saturation at Mombasa and Dar es Salaam, forcing diversification into value-added services.
- Industry Stakeholders:Regional infrastructure consortia coordinate across East African Community member states, monitoring regulatory harmonization progress to unlock economies of scale.
Oil Companies anchor committed throughput volumes; Government Agencies are gaining procurement influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mombasa-Nairobi trunk line anchors Kenya's midstream position, while Tanzania's Songo Songo processing chain feeds the southern gas corridor. Cross-border pipeline economics depend on regulatory synchronization between national petroleum authorities. Port infrastructure at Dar es Salaam and Mombasa handles Indian Ocean export volumes for landlocked producers.
Kenya
Independent power producers are locking in firm gas transportation contracts through the Mombasa-Nairobi conduit. Kenya's Petroleum Regulatory Authority enforces pipeline safety codes that shape capital recovery timelines for developers. The Mombasa tank farm cluster operates near design capacity, constraining throughput expansion for new production volumes.
Tanzania
Offshore discoveries in the southern gas corridor are driving anchor demand for expanded transmission networks. Tanzania's Energy and Water Utilities Regulatory Authority streamlines cross-border permitting frameworks with Kenyan counterparts. Dar es Salaam port infrastructure and Songo Songo processing facilities concentrate midstream investment in the coastal zone.
Uganda
Lake Albert field development requires long-haul crude export routes to Tanzanian ports. Uganda's Petroleum Authority mandates domestic contractor participation in pipeline construction through local content regulations. The Hoima refinery corridor and associated pipeline right-of-ways are reshaping regional infrastructure economics.
Ethiopia
Energy import dependency is driving cross-border pipeline feasibility studies with Kenyan and Djiboutian networks. The country's national petroleum regulator coordinates with East African Community frameworks on infrastructure standards. The Djibouti-Addis Ababa logistics corridor influences regional storage terminal planning.
Mozambique
Offshore LNG developments are creating demand for coastal processing and loading infrastructure. Petróleos de Moçambique SA manages upstream-midstream linkages through state participation. The Palma and Afungi industrial clusters anchor liquefaction terminal development for export markets.
East Africa Oil and Gas Midstream Market Competitive Landscape
Concentration sits with state-backed national oil companies controlling pipeline exclusivity and processing infrastructure. International oil majors leverage integrated LNG portfolios to secure throughput agreements across regional terminals. Three archetypes dominate: state-owned pipeline operators with exclusive conduit rights, integrated majors with global trading capabilities, and national oil companies managing upstream-midstream linkages. Competitive moves center on securing long-term offtake commitments and expanding storage terminal capacity near saturated port zones.
Among integrated majors with regional LNG capabilities, TotalEnergies and Eni S.p.A. exemplify portfolio-driven throughput strategies. State-backed operators include Kenya Pipeline Company Ltd and Tanzania Petroleum Development Corporation, which anchor domestic distribution networks through exclusive infrastructure rights. These entities represent the tier controlling physical access to import and export corridors.
| Leading Market Players |
|---|
| TotalEnergies |
| China National Petroleum Corporation |
| Petróleos de Moçambique SA |
| Kenya Pipeline Company Ltd |
| Eni S.p.A. |
| Tullow Oil |
| Tanzania Petroleum Development Corporation |
| Uganda National Oil Company |
| Oil and Natural Gas Corporation |
| Others |
Supply & Pricing Matrix
Scale economies at Dar es Salaam and Mombasa port terminals concentrate throughput pricing power among state-backed operators, compressing margin floors for independent storage providers while amplifying volume-discount leverage for anchor shippers across the East African Community.
Pricing Analysis
Volume-discount tiering structures dominate transportation contracting, with firm offtake commitments commanding preferential rates over spot arrangements. Pricing stratifies across premium, standard, and economy tiers differentiated by delivery reliability guarantees and SCADA integration levels. Price erosion runs through the spot storage tier as Mombasa and Dar es Salaam tank farms approach saturation. Independent power producers exhibit lowest price sensitivity due to long-term fuel security requirements, while commodity traders face acute margin compression from throughput volatility.
Supply Chain Analysis
Strait of Malacca transit routes for high-grade steel pipe and specialized pumping equipment anchor procurement timelines for cross-border pipeline developers. Equipment fabrication concentrates in China, South Korea, and India, with corrosion-resistant coatings and smart sensor packages constituting critical component dependencies. Single-source vulnerability for subsea umbilical systems creates project delay risks. Distribution runs through Nairobi and Dar es Salaam logistics hubs serving landlocked upstream developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
East Africa's midstream infrastructure operators face substitution pressure from modular LNG import terminals that bypass pipeline economics entirely, forcing incumbent network owners to defend throughput lock-in against distributed fuel alternatives.
For Market Incumbents: Secure exclusive rights on remaining greenfield corridor alignments before regulatory harmonization opens access to new consortia. Kenya Pipeline Company Ltd and Tanzania Petroleum Development Corporation should accelerate digital twin deployment across legacy assets to justify premium pricing tiers against independent storage entrants. Backward integration into Songo Songo gas processing capacity anchors upstream-midstream economics against LNG import substitution.
For New Entrants and Emerging Players: Uganda Petroleum Authority certification fast-tracks for high-pressure welding contractors create immediate white-space access for specialized engineering services. Target the Hoima refinery corridor for construction-phase logistics contracts before operational handover to state operators. Go-to-market positioning should emphasize local content compliance capabilities that international developers lack.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors infrastructure operators with installed SCADA platforms and regulatory relationships spanning multiple East African Community jurisdictions. Long-term viability rests on consolidation plays that aggregate fragmented storage terminal ownership around saturated port zones. Watch Tanzania's southern gas corridor offtake restructuring as the inflection signal for contract duration compression across regional transmission assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Border Permitting Harmonization | Synchronized approval windows between Kenya's Petroleum Regulatory Authority and Tanzania's Energy and Water Utilities Regulatory Authority compress project timelines. |
| Smart Monitoring Retrofit Deployment | SCADA integration at Mombasa and Dar es Salaam terminals satisfies insurer requirements while reducing unplanned outage costs. |
| Local Content Capability Buildout | Permanent engineering presence in Uganda satisfies Petroleum Authority mandates and deepens contractor relationships. |
| Firm Transportation Contract Restructuring | Volume-flexible terms indexed to spot LNG prices attract independent power producers displacing utility direct-purchase models. |
| Southern Gas Corridor Expansion | Offshore-to-onshore processing linkages anchor anchor demand for Tanzania Petroleum Development Corporation controlled infrastructure. |
Research Methodology
A standing panel of pipeline operations managers, EPC contract directors, regulatory affairs officers at national petroleum authorities, and independent power producer fuel procurement leads provided ongoing calibration. Primary fieldwork combined structured interviews with secondary validation against East African Community treaty documentation, national pipeline safety codes, and project development databases. Customs records for steel pipe and pumping equipment imports, alongside utility integrated resource plans, furnished demand-side triangulation. Bottom-up project economics and top-down regional capacity models were reconciled.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled infrastructure type, service category, technology tier, and end-user concentration dimensions. CAGRs were derived from throughput elasticity functions tied to upstream production profiles and downstream demand curves. Forecast inputs incorporated regulatory harmonization progress scores and SCADA adoption curves.
Decision-makers should treat outputs as directional under sustained cross-border permitting coordination and stable upstream investment commitments; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as LNG import terminal economics and renewable energy substitution rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Deepwater and Ultra-Deepwater Drilling Market
Offshore Oil and Gas
Europe Floating Offshore Wind Power Market
Offshore Oil and Gas
Abyssinian Oil Market
Offshore Oil and Gas
Asia-Pacific Floating Offshore Wind Power Market
Offshore Oil and Gas
Norway Oil and Gas Downstream Market
Offshore Oil and Gas
Egypt Oil and Gas Downstream Market
Offshore Oil and Gas
Global Floating LNG Power Vessel Market
Offshore Oil and Gas
Oman Oil and Gas Downstream Market
Offshore Oil and Gas
Denmark Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Connected Solutions for Oil and Gas Market
Offshore Oil and Gas
Offshore Contract Drilling Market
Offshore Oil and Gas
Asia-Pacific Floating Production Systems Market
Offshore Oil and Gas
India Oil and Gas Downstream Market
Offshore Oil and Gas
East Africa Oil and Gas Downstream Market
Offshore Oil and Gas
Europe Offshore Energy Market
Offshore Oil and Gas
Oil and Gas Fishing Market