
 Eccentric Tip Syringe Market | 2026-2036
Eccentric Tip Syringe Market Size, Share, and Industry Trends Forecast 2026-2036
Eccentric Tip Syringe Market Foresight
Aftermarket maintenance contracts and sterilization-validation services is shifting how suppliers monetize eccentric tip syringe relationships beyond unit sales. Becton, Dickinson and Company anchors North American hospital supply chains through captive distribution networks. Gerresheimer AG specializes in glass-barrel precision molding for high-viscosity biologic delivery. Terumo Corporation leverages polymer science capabilities across Japanese and Southeast Asian manufacturing bases.
An eccentric tip syringe positions its Luer connection at an offset angle from the barrel centerline, enabling flatter injection angles and reduced tissue trauma during subcutaneous and intramuscular administration; barrels are manufactured through precision injection molding of medical-grade polypropylene or borosilicate glass with tight concentricity tolerances. Safety syringe configurations command premium positioning as needlestick prevention regulations harden across acute care settings. Single-use plastic syringes dominate volume throughput while insulin-specific variants capture concentrated margin pools in diabetes management protocols.
FDA 510(k) clearance pathways and EMA Medical Device Regulation conformity assessments govern market access for eccentric tip syringe manufacturers, with ISO 7886-1 dimensional standards defining Luer taper interoperability. The EPA and national environmental regulators are scrutinizing single-use plastic waste streams, pressuring material substitution toward bio-based polymers or recyclable glass alternatives. Stakeholders must monitor evolving sterilization validation requirements and home care reimbursement codes to align portfolio development with shifting care delivery economics.
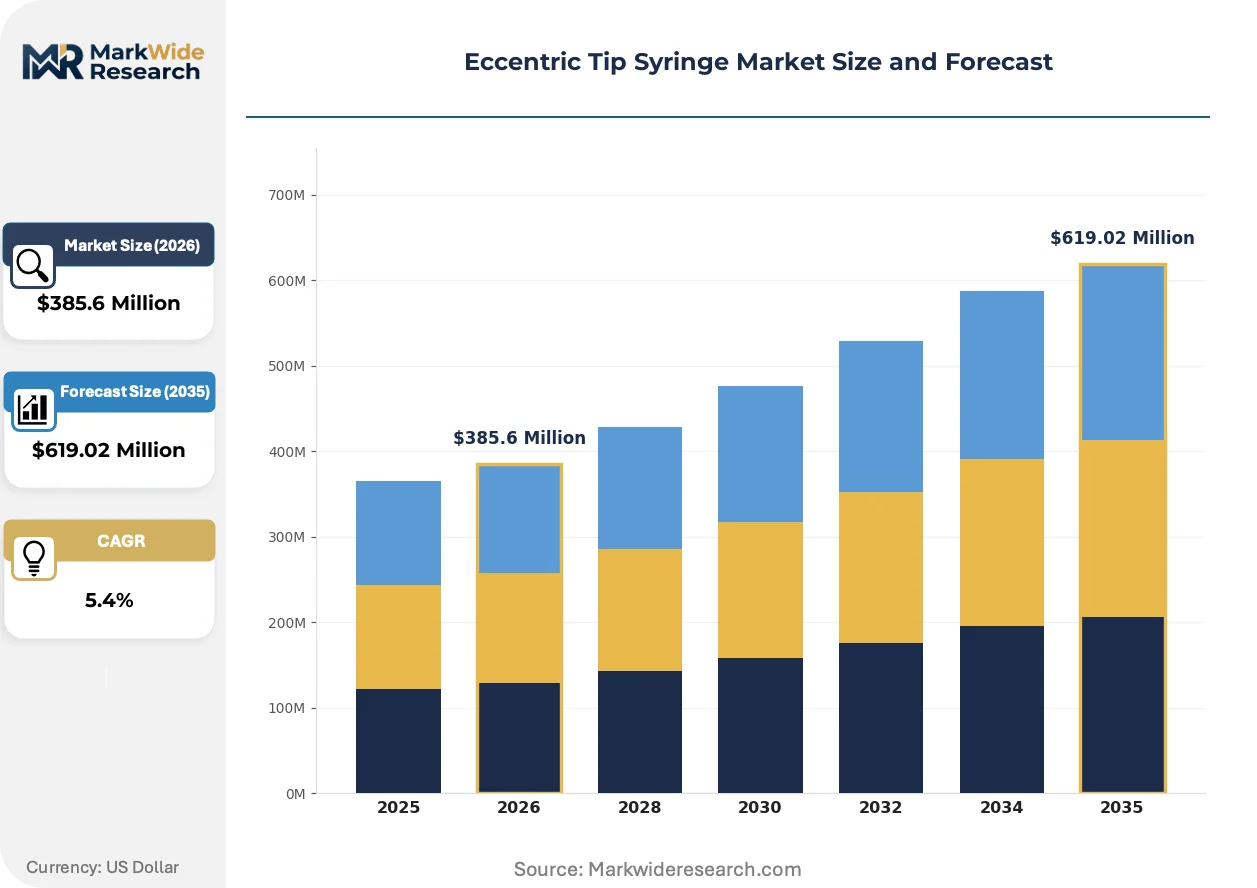
Market Dynamics
Home administration of biologics is compressing facility-based injection volumes while FDA and EMA sterilization mandates force polymer requalification cycles. Suppliers now monetize through validation services and captive maintenance contracts rather than unit sales alone.
Growth Catalysts
- Biologic self-administration protocols:Patient preference for subcutaneous delivery at home is pulling demand toward ergonomic tip geometries that reduce injection angle error and tissue trauma during self-injection.
- ISO 7886-1 interoperability mandates:Standardized Luer taper specifications are eliminating regional compatibility barriers and enabling cross-border procurement consolidation among hospital systems.
- Germany's precision manufacturing corridor:Concentrated mold-making and glass-forming expertise in Baden-Württemberg and Bavaria is supplying high-concentricity barrels for insulin and high-viscosity biologic applications.
Market Restraints
- Medical-grade polypropylene feedstock volatility:Propylene monomer supply tightness and pharmaceutical-grade additive shortages are compressing margin structures for polymer barrel producers.
- Single-supplier sterilization validation concentration:Gamma and ethylene oxide sterilization capacity clusters in the US Midwest and Western Europe create geographic chokepoints for new market entrants.
- Glass-barrel fragility in cold-chain distribution:Borosilicate breakage rates during frozen biologic transport limit glass adoption despite superior chemical inertness for sensitive formulations.
Strategic Opportunities
- Home care reimbursement code expansion:CMS and national health technology assessment bodies in France and the UK are expanding coverage for self-administered biologics, opening patient-direct channels.
- Bio-based polymer substitution:EPA and EU Green Deal pressure on single-use plastics is creating first-mover advantage for suppliers with validated polylactic acid or cellulose-derived barrel formulations.
- Connected syringe convergence:Integration of Bluetooth dose-capture modules with eccentric tip designs is enabling adherence monitoring for diabetes and growth hormone therapies.
Industry Challenges
- Polymer sterilization validation timelines:FDA 510(k) and EMA MDR submission cycles for novel barrel materials now stretch 18-24 months, freezing development pipelines.
- Precision mold-making skill scarcity:Concentricity tolerance requirements below 0.05mm demand specialized tool-and-die expertise concentrated in aging workforce pools across Germany and Japan.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eccentric Tip Syringe Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $619.02 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use Syringe, Reusable Syringe, Safety Syringe, Insulin Syringe End User: Hospitals, Clinics, Home Care, Pharmaceutical Companies Material: Plastic, Glass, Rubber, Metal Delivery Mode: Intravenous, Intramuscular, Subcutaneous, Oral |
| Companies Covered | Cardinal Health, Inc., B. Braun Melsungen AG, Becton, Dickinson and Company (BD), Hindustan Syringes & Medical Devices, Gerresheimer AG, Terumo Corporation, Smiths Medical, Novo Nordisk, Nipro Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eccentric Tip Syringe Market Shifts & Advancements
Material science advances and regulatory pressure on plastic waste are reshaping barrel composition strategies. Suppliers are repositioning around validation capabilities and connected-device integration rather than commodity manufacturing scale.
Pre-filled syringe systems with integrated eccentric tips are expanding into rheumatology and endocrinology practices where patient self-injection training costs drive preference for ready-to-use formats. Rheumatology clinics in the US and Germany are adopting these systems at accelerating pace to reduce nursing overhead. This format expansion is compressing demand for standalone syringe-needle combinations and shifting margin capture toward fill-finish service providers.
EMA Medical Device Regulation and FDA updated sterilization guidance are tightening ethylene oxide residual limits and gamma dose mapping requirements for polymer components. Industrial consequence includes forced revalidation of existing supply chains and accelerated qualification of alternative sterilization modalities such as vaporized hydrogen peroxide. High-volume insulin syringe manufacturers with European distribution are responding by consolidating sterilization partnerships and investing in in-house validation laboratories.
Hospital procurement consortia are consolidating supplier panels and unbundling after-sales service contracts from device purchases. Group purchasing organizations in the US and NHS Supply Chain in the UK are driving this consolidation, replacing fragmented regional purchasing with national framework agreements. This concentration is most visible in acute care settings where safety-engineered configurations dominate tender specifications.
Eccentric Tip Syringe Market Segmentation
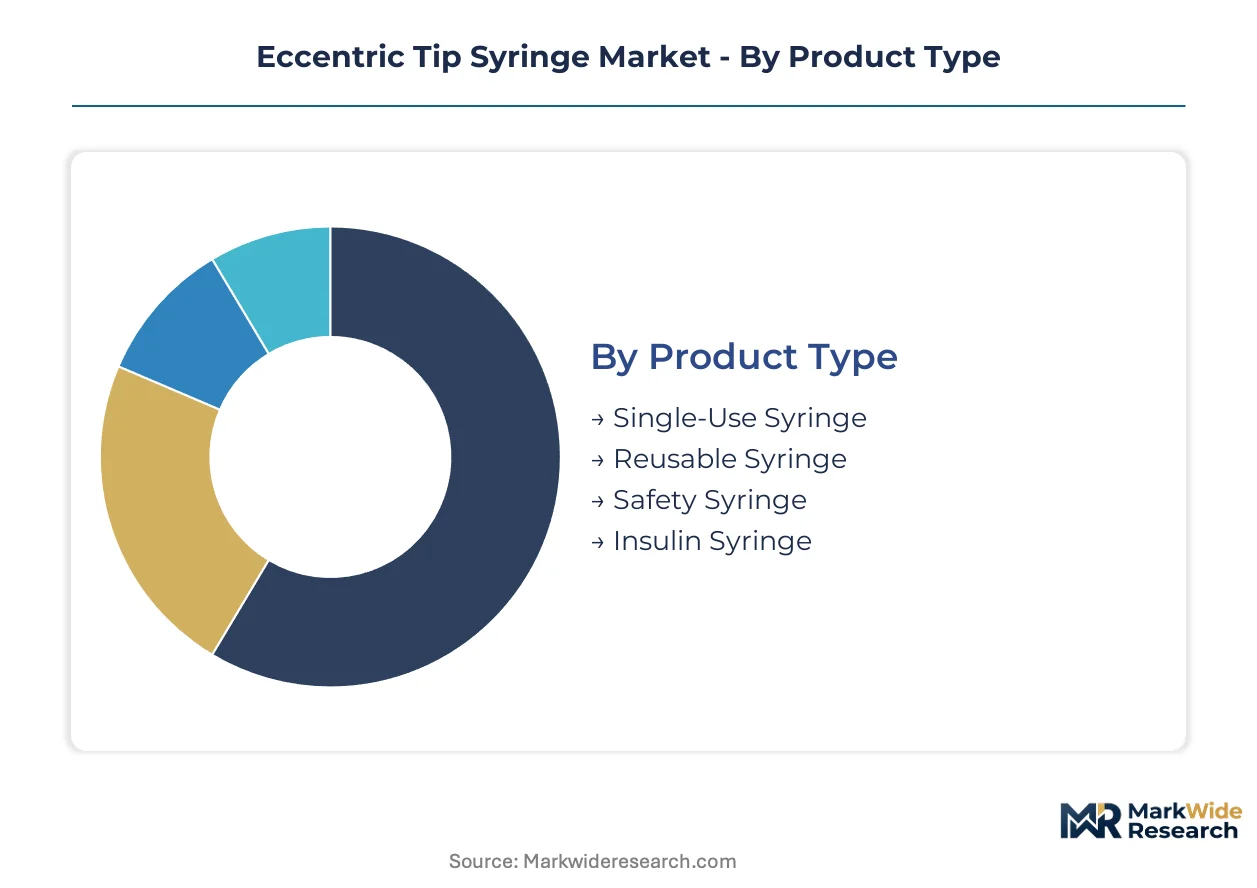
Eccentric tip syringe procurement patterns diverge sharply across clinical settings and material specifications. Upgrade cycles and replacement protocols vary by segment, creating distinct margin pools for suppliers aligned to specific usage intensities.
Product Type:
Replacement cycles accelerate where safety regulations and single-use mandates dominate purchasing protocols.
- Safety Syringe:Integrated needlestick prevention mechanisms require complete system replacement upon activation. Acute care settings in Germany and the United States are mandating these configurations through tender specifications, compressing demand for conventional alternatives.
- Single-Use Syringe:Polypropylene barrels dominate volume throughput with standardized Luer taper compatibility per ISO 7886-1. Hospital procurement consortia in the United Kingdom and France are consolidating supplier panels around these disposable formats.
- Insulin Syringe:Ultra-fine gauge needles and unit-specific graduation markings serve diabetes management protocols with concentrated margin pools.
- Reusable Syringe:Glass-barrel designs with autoclavable metal plungers persist in veterinary and research laboratory applications.
Single-Use Syringe sits at the top of the volume ranking, with Safety Syringe climbing the fastest.
End User:
Cost tier differentiation separates capital-intensive institutional buyers from patient-direct channels where reimbursement codes shape affordability.
- Home Care:Self-administration of biologics is pulling demand toward ergonomic tip geometries that reduce injection angle error. CMS in the United States and national health technology assessment bodies in France are expanding coverage codes for these patient-direct channels.
- Hospitals:Group purchasing organizations and NHS Supply Chain framework agreements dominate procurement with unbundled after-sales service contracts. Safety-engineered configurations are mandatory in tender specifications across acute care settings.
- Clinics:Outpatient rheumatology and endocrinology practices favor pre-filled systems to reduce nursing overhead.
- Pharmaceutical Companies:Fill-finish service providers capture margin through integrated eccentric tip assemblies for high-viscosity biologic delivery.
Hospitals command the highest absolute spend, though Home Care is expanding most quickly as reimbursement codes broaden.
Material:
Supply concentration for medical-grade feedstocks dictates regional manufacturing footprints and sterilization partnership strategies.
- Plastic:Medical-grade polypropylene from propylene monomer supply chains enables precision injection molding with tight concentricity tolerances. Feedstock volatility is compressing margin structures for barrel producers dependent on pharmaceutical-grade additives.
- Glass:Borosilicate formulations from Germany's precision manufacturing corridor offer superior chemical inertness for sensitive biologics. Breakage rates during frozen transport limit adoption despite performance advantages.
- Rubber:Elastomer plunger tips and tip caps require pharmaceutical-grade curing agents and extractables testing.
- Metal:Stainless steel plungers and Luer lock components serve reusable and high-durability safety mechanisms.
Plastic dominates production volume, with Glass gaining share fastest among cold-chain biologic applications.
Delivery Mode:
Application-specific performance requirements determine tip angle precision and barrel graduation specifications.
- Subcutaneous:Eccentric tip offset angles enable flatter injection trajectories that reduce tissue trauma during self-administration. Patient training protocols for biologics in rheumatology and endocrinology are standardizing around these geometries.
- Intramuscular:Deeper penetration requirements demand robust needle attachment and precise dose graduation for vaccine and hormone delivery.
- Intravenous:Direct vascular access applications require Luer lock security and minimal dead space for medication accuracy.
- Oral:Enteral feeding and medication administration utilize eccentric tip designs for precise liquid delivery to patients with swallowing difficulties.
Subcutaneous delivery commands the largest addressable volume, with Intramuscular showing the steepest expansion trajectory through vaccine distribution networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands precision manufacturing gravity for high-concentricity glass barrels, while the United States anchors safety-engineered syringe demand through hospital procurement consolidation. Japan leverages polymer science capabilities across Southeast Asian manufacturing bases. India concentrates insulin-specific volume production for diabetes management protocols.
United States
Hospital group purchasing organizations and CMS reimbursement code expansions pull demand toward home care self-administration formats. FDA sterilization guidance tightens ethylene oxide residual limits for polymer components. Midwest gamma sterilization capacity clusters create geographic chokepoints for new market entrants seeking 510(k) clearance pathways.
Germany
Baden-Württemberg and Bavaria mold-making expertise supplies precision barrels for high-viscosity biologic delivery. EMA Medical Device Regulation conformity assessments govern market access with ISO 7886-1 interoperability mandates. The precision manufacturing corridor concentrates glass-forming capabilities for chemically inert borosilicate formulations serving cold-chain applications.
Japan
PMDA regulatory frameworks align with polymer science R&D investments across domestic and Southeast Asian production bases. METI industrial policy supports medical device export competitiveness through standardized Luer taper specifications. Tokyo-Osaka manufacturing networks supply safety syringe configurations for acute care settings across Asia-Pacific distribution channels.
India
CDSCO medical device regulations and expanding diabetes prevalence concentrate insulin syringe volume production for domestic and export markets. Pharmaceutical-grade polypropylene feedstock sourcing challenges compress margin structures for barrel producers. Gujarat and Maharashtra industrial corridors host precision molding operations serving patient-direct channels.
United Kingdom
NHS Supply Chain framework agreements consolidate supplier panels around unbundled after-sales service contracts. MHRA post-Brexit regulatory alignment with EMA MDR standards shapes sterilization validation requirements for polymer components. London and Southeast England procurement hubs drive safety-engineered configuration mandates across acute care tender specifications.
Eccentric Tip Syringe Market Competitive Landscape
Top-tier vendors anchor hospital supply chains through captive distribution networks, while mid-tier specialists compete on sterilization-validation service bundling. The vendor base stratifies across three archetypes: integrated medtech conglomerates with polymer-glass dual capabilities, precision molding specialists concentrated in German and Japanese industrial corridors, and volume-scale insulin syringe fabricators serving patient-direct channels. Competitive positioning hardens through M&A consolidation of sterilization partnerships and backward integration into medical-grade polypropylene feedstock sourcing.
Among integrated medtech conglomerates, Becton, Dickinson and Company and Cardinal Health, Inc. represent the hospital supply chain anchoring archetype with North American distribution density. B. Braun Melsungen AG and Gerresheimer AG exemplify German precision manufacturing specialization, with the latter occupying a position in glass-barrel molding for high-viscosity biologics. Terumo Corporation sits within the polymer science-driven tier, leveraging Japanese R&D capabilities across Southeast Asian production bases. Hindustan Syringes & Medical Devices anchors the volume-scale insulin syringe segment serving diabetes management protocols.
| Leading Market Players |
|---|
| Cardinal Health, Inc. |
| B. Braun Melsungen AG |
| Becton, Dickinson and Company (BD) |
| Hindustan Syringes & Medical Devices |
| Gerresheimer AG |
| Terumo Corporation |
| Smiths Medical |
| Novo Nordisk |
| Nipro Corporation |
| Others |
Supply & Pricing Matrix
EU Green Deal plastic-waste mandates gate qualified supply and premium-tier pricing access by forcing polymer requalification cycles that only validated manufacturers can absorb. Buyers seeking ISO 7886-1 certified safety syringes now face bifurcated sourcing between legacy suppliers with in-house sterilization labs and commodity producers frozen out by EMA MDR compliance costs.
Pricing Analysis
Capacity additions in India's Gujarat and Maharashtra industrial corridors are reshaping price floors for standard single-use polypropylene barrels while German glass-barrel specialists maintain premium positioning. Pricing stratifies across safety-engineered configurations, ISO-certified standard disposables, and unvalidated economy tiers. Cost compression in the economy tier is intensifying because propylene monomer feedstock volatility squeezes margin structures for non-integrated molders. Hospital procurement consortia exhibit lowest price sensitivity due to unbundled service contracts, while patient-direct home care channels face highest affordability pressure from limited reimbursement coverage.
Supply Chain Analysis
Freight cost escalation for temperature-controlled borosilicate glass shipments from Germany to North American biologic fill-finish sites is accelerating regional sourcing shifts. Supply concentrates in Germany for precision glass-forming, Japan and Southeast Asia for polymer science R&D, and India for insulin syringe volume production. Raw material dependencies center on medical-grade polypropylene resin, pharmaceutical-grade rubber elastomers, and borosilicate glass tubing. Single-source sterilization validation concentration in the US Midwest creates geographic chokepoint risk. Distribution runs through hospital group purchasing organizations in North America, NHS Supply Chain in the United Kingdom, and pharmaceutical fill-finish service providers globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Eccentric Tip Syringe Market represents a late-cycle quality story as home administration of biologics pulls demand toward ergonomic tip geometries with validated sterilization documentation. Premium specifications now command pricing power that commodity producers cannot replicate.
For Market Incumbents: Acquire sterilization-validation laboratory assets to defend against emerging entrants lacking FDA 510(k) clearance capabilities. Consolidate captive maintenance contracts with hospital procurement consortia to lock in recurring revenue streams. Backward integration into medical-grade polypropylene feedstock sourcing mitigates propylene monomer volatility threatening margin structures. For New Entrants and Emerging Players: Enter via bio-based polymer barrel formulations where EPA and EU Green Deal pressure creates first-mover advantage ahead of incumbent requalification timelines. Target patient-direct home care channels in France and the United Kingdom where reimbursement code expansion outpaces supply. Pursue white-label fill-finish partnerships with pharmaceutical companies seeking integrated eccentric tip assemblies for high-viscosity biologics. For Investors and Strategic Acquirers: Roll-up economics work for precision mold-making specialists because concentricity tolerance requirements below 0.05mm demand specialized tool-and-die expertise concentrated in aging workforce pools across Germany and Japan. Five-to-ten year viability hinges on connected syringe convergence integrating Bluetooth dose-capture modules. Target acquisition archetype: mid-tier sterilization-validation service providers with EMA MDR and FDA 510(k) submission track records. Watch for inflection when CMS expands home care reimbursement codes beyond current rheumatology and endocrinology coverage.| Strategic Initiative | Industry Significance |
|---|---|
| Sterilization Validation Laboratory Acquisition | EMA MDR and FDA tightening of ethylene oxide residual limits forces captive in-house capability. |
| Bio-Based Polymer Barrel Development | EU Green Deal pressure on single-use plastics creates qualification runway for polylactic acid formulations. |
| Connected Syringe Platform Integration | Bluetooth dose-capture modules enable adherence monitoring for diabetes and growth hormone therapies. |
| Hospital GPO Contract Consolidation | NHS Supply Chain and US group purchasing organizations unbundle after-sales service from device purchases. |
| Precision Mold-Making Skill Apprenticeship | Baden-Württemberg and Bavaria aging workforce pools threaten 0.05mm concentricity tolerance supply. |
Research Methodology
Multiple input streams — primary interviews with hospital procurement managers, biomedical engineers, and GPO contracts specialists; secondary validation through FDA 510(k) filings, EMA MDR submissions, and hospital procurement databases; plus customs records for medical-grade polypropylene trade flows — were reconciled through bottom-up and top-down triangulation. Clinicians and fill-finish service providers contributed application-specific demand assessments for high-viscosity biologic delivery formats.
Historical shipment data was cross-referenced against panel input from sterilization service providers and precision mold-makers across the analysis window. Segmentation modeling spanned product type, end user, material, and delivery mode dimensions with geographic regulatory cluster overlays. CAGRs were derived from installed base replacement cycles and reimbursement code expansion trajectories. Forecast inputs included polymer feedstock cost curves and gamma sterilization capacity utilization rates.
Inputs from EMA MDR conformity assessment databases and CMS reimbursement code registers were available through the study window; gaps in real-time propylene monomer pricing transparency introduce uncertainty bands around polymer barrel cost assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Automatic Stair Climbing Wheelchair Market
Medical Devices
Consumer Grade EEG Device Market
Medical Devices
Neurothrombectomy Devices Market
Medical Devices
Surgical Robotics Performance and Safety Validation Test Platforms Market
Medical Devices
Oral Controlled Release Drug Delivery Technology Market
Medical Devices
US Neurothrombectomy Devices Market
Medical Devices
Infant Radiant Warmer Market
Medical Devices
Non-Invasive Brain Trauma Monitoring Devices Market
Medical Devices
Self-Sampling Blood Collection and Storage Devices Market
Medical Devices
Artificial Implants Market
Medical Devices
Rectal Catheters Market
Medical Devices
Global Esophageal Catheters Market
Medical Devices
Global Vagus Nerve Stimulation Market
Medical Devices
Organ Transport Devices Market
Medical Devices
Appendage Management Market
Medical Devices
Multi Dose Drug Vial Adapters Market