
 Infant Radiant Warmer Market | 2026-2036
Infant Radiant Warmer Market Size, Share, and Industry Trends Forecast 2026-2036
Infant Radiant Warmer Market Outlook
Hospital procurement of infant radiant warmers is tilting toward integrated digital platforms with remote monitoring capabilities. GE Healthcare leverages its installed base of maternal-infant care systems to sustain recurring service contracts across North American health networks. Fisher & Paykel Healthcare anchors its position in Asia-Pacific through localized manufacturing and direct hospital partnerships. Draeger competes on clinical workflow integration, bundling warmers with ventilator and monitoring ecosystems.
An infant radiant warmer is a thermoregulatory device that delivers infrared heat to maintain neonatal body temperature between 36.5°C and 37.5°C through quartz-halogen or ceramic heating elements controlled by servo-feedback skin sensors. Its primary purpose is preventing hypothermia in premature or low-birth-weight infants during resuscitation, examination, or surgical procedures. Overhead warmers dominate acute care settings where procedural access takes priority, while transport warmers represent the fastest-growing form factor as inter-facility neonatal transfers expand. Digital technology platforms command premium positioning due to integrated data logging and alarm connectivity, whereas conventional infrared units occupy cost-sensitive procurement tiers in emerging markets.
FDA 510(k) clearance requirements and the EU Medical Device Regulation shape thermal safety testing protocols and electromagnetic compatibility standards for all commercially distributed units. CE marking under MDR and ISO 9001 quality management systems govern market access across European economic zones, while China's NMPA registration mandates in-country clinical validation for imported devices. Stakeholders must monitor evolving servo-control accuracy standards and cybersecurity frameworks for networked warmer platforms as connectivity becomes standard configuration.
Market Dynamics
Hospital procurement of infant radiant warmers is pivoting toward servo-controlled platforms with integrated data logging, as tertiary neonatal intensive care units demand thermal precision that exceeds conventional infrared unit capabilities.
Growth Catalysts
- EU MDR thermal stability mandates:The Medical Device Regulation's stricter electromagnetic compatibility and servo-control accuracy requirements are accelerating replacement cycles across European tertiary hospitals.
- Inter-facility neonatal transport networks:The expansion of regional perinatal referral systems in India and China is pulling demand for portable transport warmer configurations with battery backup systems.
- Quartz-halogen to ceramic heating element migration:Ceramic infrared emitters deliver more uniform heat distribution and longer service intervals, reducing total cost of ownership for high-volume maternity centers.
Market Restraints
- Raw material concentration for quartz-halogen elements:Tungsten filament and fused quartz supply chains concentrate in specific manufacturing regions, exposing producers to input cost volatility and single-source dependency.
- FDA 510(k) clearance timelines:The agency's heightened scrutiny of servo-feedback algorithms and thermal cutout redundancies extends premarket notification review periods for new platform submissions.
- Conventional infrared unit price floors:Mature manufacturing processes for basic radiant warmers limit differentiation opportunities, compressing margins in cost-sensitive procurement tiers across emerging markets.
Strategic Opportunities
- Remote monitoring platform integration:Cloud-connected warmer ecosystems that stream thermal data to central nursing stations address staffing shortages in US and European tertiary facilities.
- India's PLI scheme for medical devices:The Production Linked Incentive program offers capital subsidies for domestic manufacturing, creating localized production pathways for regional market penetration.
- AI-enabled predictive thermal regulation:Machine learning algorithms that anticipate heat loss trajectories in premature infants represent unclaimed white space between conventional servo-control and full environmental control incubators.
Industry Challenges
- Servo-control calibration technician scarcity:The specialized skill set required for skin sensor accuracy verification and feedback loop tuning is concentrated among aging field service engineers in mature markets.
- Legacy analog warmer fleet integration:Hospitals with mixed-device environments face interoperability barriers when connecting conventional infrared units to centralized alarm management and electronic health record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infant Radiant Warmer Market |
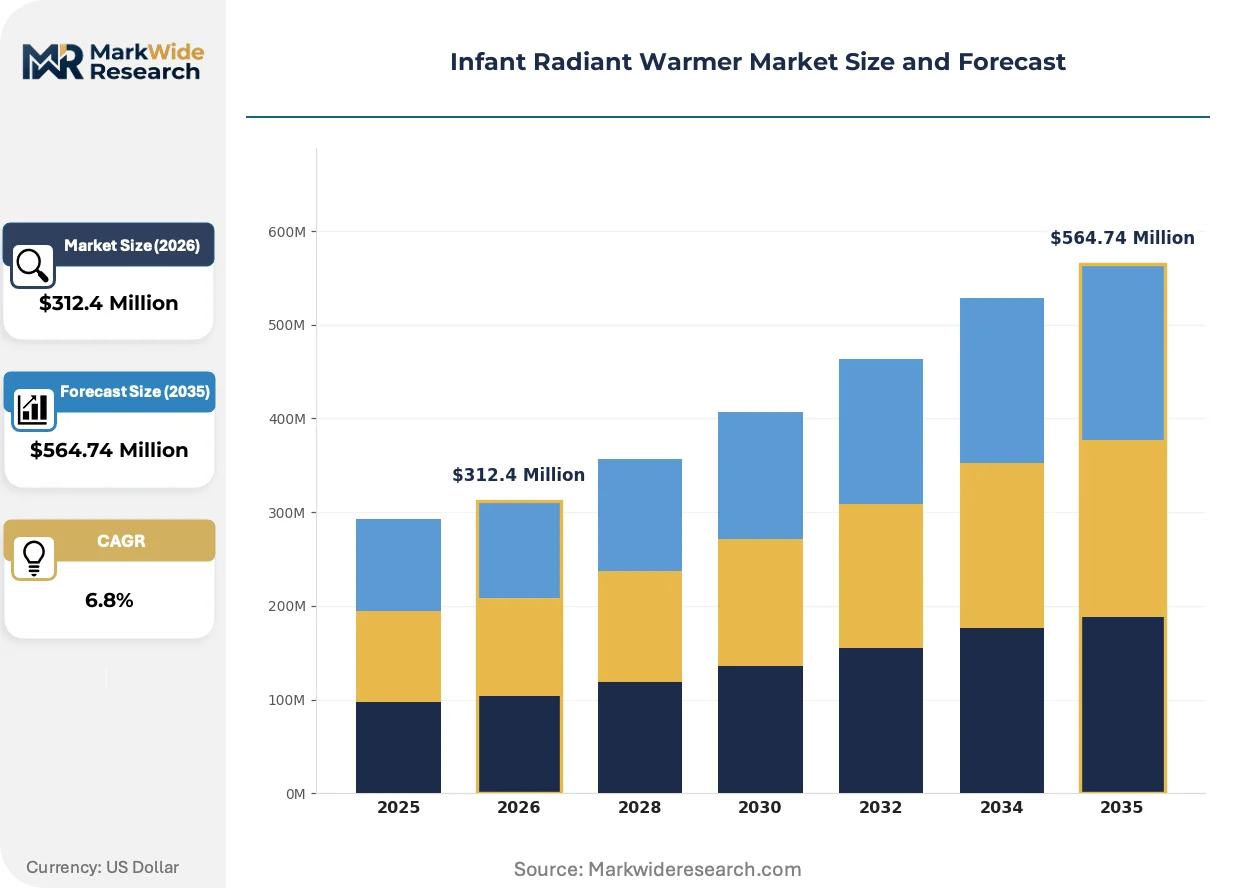
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Overhead Warmers, Neonatal Incubators, Transport Warmers, Radiant Heat Beds End User: Hospitals, Clinics, Nursing Homes, Home Care Form Factor: Mobile, Fixed, Compact, Modular Technology: Infrared, Conventional, Hybrid, Digital |
| Companies Covered | Natus Medical Incorporated, Fisher & Paykel Healthcare, GE Healthcare, Novos, Fanem, Draeger, Philips Healthcare, Phoenix Medical Systems, Atom Medical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infant Radiant Warmer Market Strategic Shifts
Digital thermal management architectures are displacing analog control systems across acute care settings, while regulatory pressure on electromagnetic emissions and cybersecurity reshapes product development roadmaps.
Dual-skin-sensor servo architectures with predictive algorithmic compensation are rendering obsolete single-point temperature monitoring systems in level III and IV neonatal intensive care units. Tertiary hospitals in the United States and Germany are specifying these platforms in bundled procurement contracts for maternal-infant care renovations. The technology is rendering obsolete conventional warmer configurations that rely on manual power adjustment and intermittent spot-check thermometry.
China's NMPA cybersecurity guidelines for networked medical devices now mandate penetration testing and data encryption protocols for warmer platforms with WiFi or Ethernet connectivity. Domestic manufacturers in Shenzhen and Beijing are restructuring firmware development cycles to accommodate these validation requirements. Imported device registrants face extended in-country clinical validation timelines as SAMR inspectors scrutinize thermal stability documentation against GB standards.
Hospital capital equipment committees are unbundling service contracts from initial hardware purchases, soliciting competitive third-party preventive maintenance bids for warmer fleets. This behavior compresses OEM service revenue streams and accelerates parts standardization pressures across North American health networks. The shift is most visible in US hospital systems pursuing GPO-negotiated multi-vendor service agreements.
Infant Radiant Warmer Market Segmentation
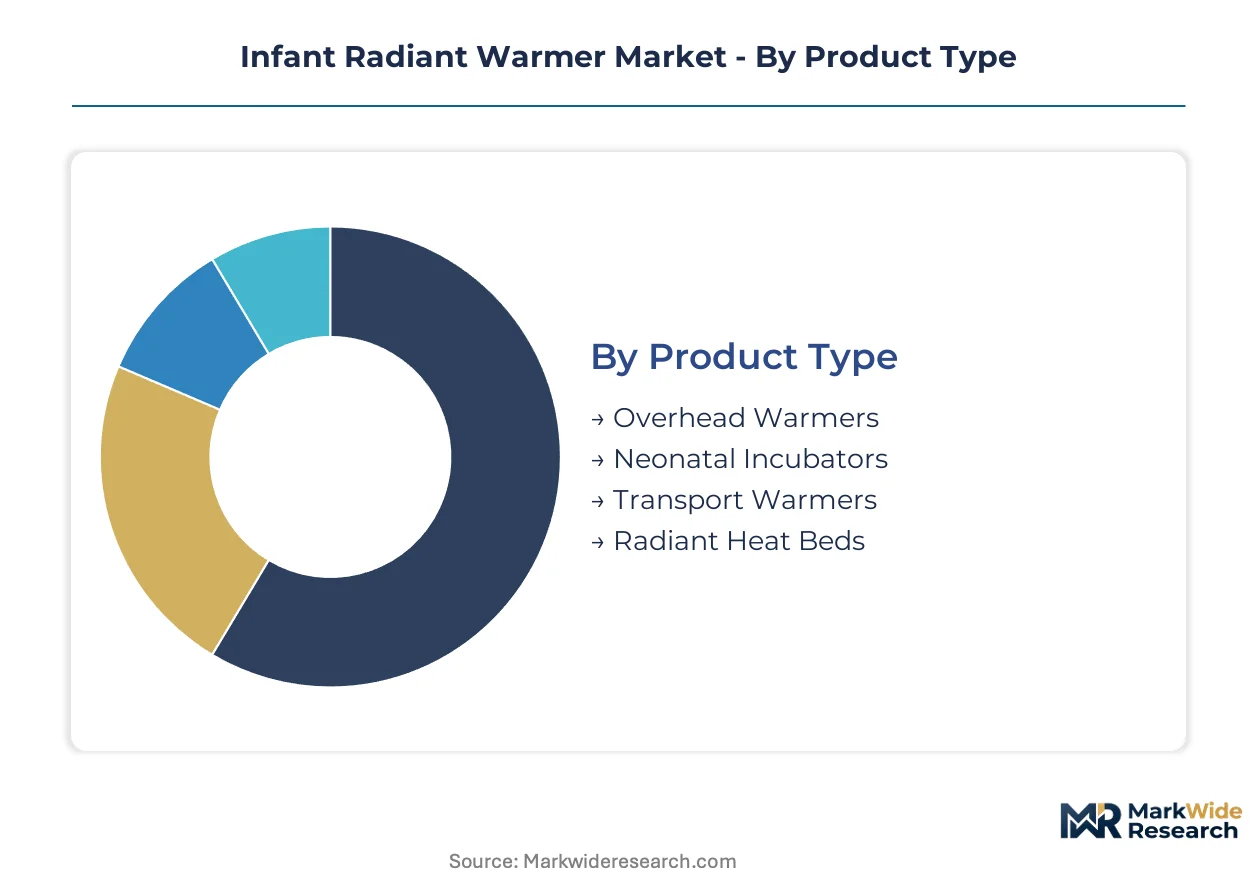
Segmentation in the infant radiant warmer market reveals how procurement priorities diverge across acute care intensity, patient mobility requirements, and technology maturity. Understanding these splits enables suppliers to align R&D investment with specific clinical workflows and reimbursement environments.
Product Type:
Mature configurations dominate high-volume maternity centers while emerging formats capture specialized transport and hybrid-care applications.
- Overhead Warmers:These suspended infrared heating systems with quartz-halogen or ceramic emitters deliver unobstructed procedural access for resuscitation and examination. Demand concentrates in United States tertiary hospitals where level III and IV NICU renovations specify servo-controlled platforms with integrated phototherapy.
- Neonatal Incubators:Closed-environment systems combining radiant heat with humidity control and isolation barriers serve extremely low-birth-weight infants requiring strict thermoregulation. China's NMPA registration requirements for imported incubators mandate extended thermal stability documentation, slowing market entry for foreign manufacturers.
- Transport Warmers:Battery-backed portable units with electromagnetic shielding enable inter-facility transfers without thermal disruption.
- Radiant Heat Beds:Flat-surface warming platforms with manual or servo-control options occupy cost-sensitive procurement tiers in Indian district hospitals.
Overhead warmers retain volume leadership; transport warmers hold the steepest expansion curve.
End User:
Customer type determines purchasing authority complexity and service contract structure across the care continuum.
- Hospitals:Tertiary medical centers with level III and IV NICUs command capital equipment budgets exceeding $50,000 per warmer platform when bundled with monitoring ecosystems. United States health networks leverage GPO-negotiated multi-vendor service agreements to unbundle preventive maintenance from hardware acquisition.
- Clinics:Outpatient birth centers and specialty clinics prioritize compact overhead warmers with rapid heat-up cycles for intermittent use.
- Nursing Homes:Long-term care facilities with neonatal observation units specify basic radiant heat beds lacking advanced servo-feedback capabilities.
- Home Care:Rental-based portable warmers serve medically fragile infants discharged early from hospital settings.
Hospitals command procurement value leadership; home care channels are climbing the fastest.
Form Factor:
Physical configuration trade-offs between mobility and stability shape installation patterns across facility types.
- Mobile:Castor-mounted units with locking mechanisms and integrated battery systems enable repositioning between delivery rooms and NICU bays. German tertiary hospitals specify these for flexible room utilization in maternal-infant care renovations.
- Fixed:Ceiling-suspended or wall-mounted permanent installations eliminate floor space constraints in high-density Indian urban hospitals.
- Compact:Reduced-footprint warmers with single heating elements serve space-constrained clinics and nursing homes.
- Modular:Configurable platforms accepting add-on phototherapy modules or weighing scales appeal to United States hospitals pursuing equipment standardization.
Mobile configurations retain installation leadership; modular systems are gaining share fastest.
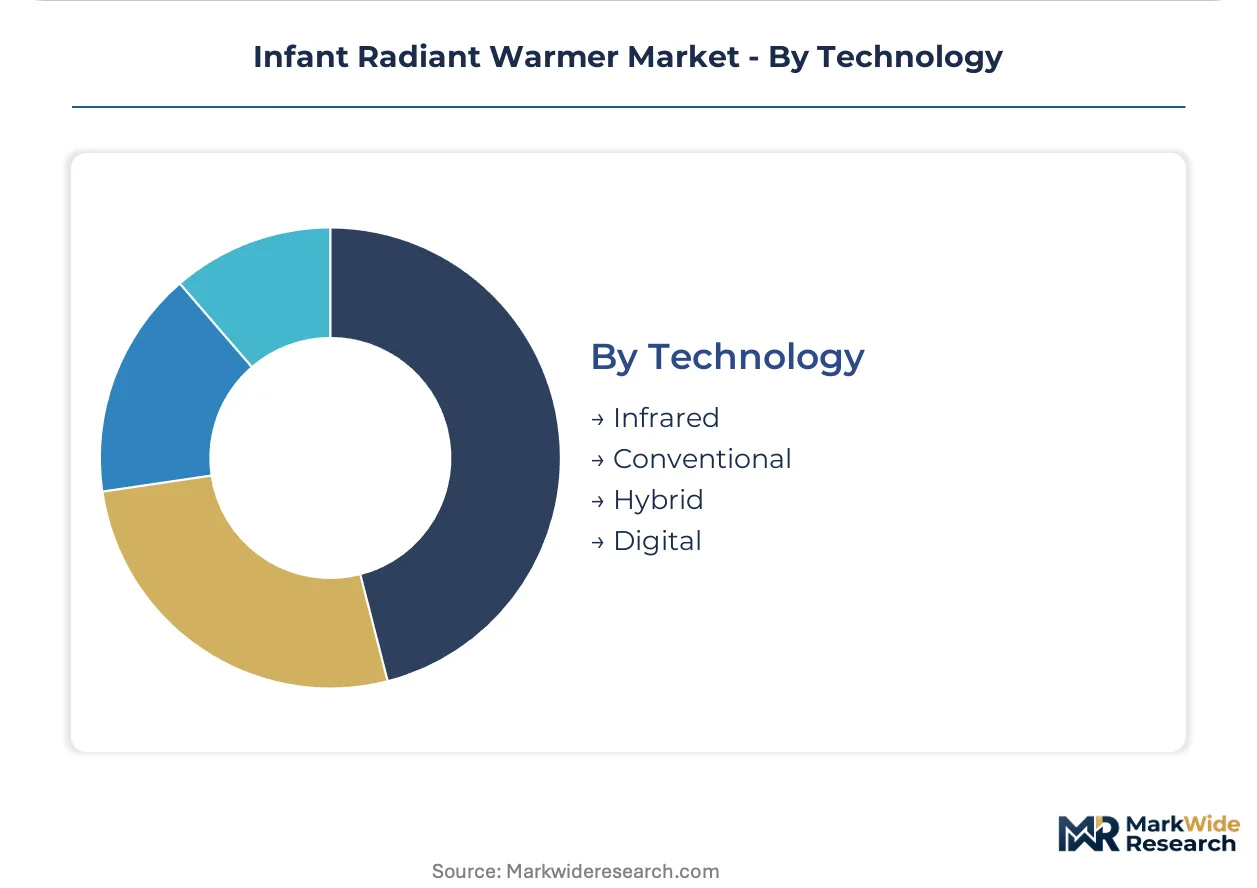
Technology:
Control architecture sophistication separates premium procurement tiers from basic infrared units in emerging markets.
- Infrared:Quartz-halogen and ceramic emitter technologies deliver radiant heat through electromagnetic wavelengths optimized for neonatal skin absorption. China's domestic manufacturers in Shenzhen dominate cost-optimized infrared production for Asia-Pacific price-sensitive segments.
- Digital:Microprocessor-controlled platforms with dual-skin-sensor servo architectures, predictive algorithms, and cloud connectivity command premium positioning in United States and German level IV NICUs.
- Conventional:Analog manual-control warmers with basic thermal cutouts occupy replacement markets and budget-constrained procurement in Indian district facilities.
- Hybrid:Combined radiant-convective systems integrating overhead infrared with forced-air warming address specific hypothermia risk profiles in premature populations.
Infrared platforms retain unit volume leadership; digital systems hold the steepest value expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for medical devices is redirecting capital toward domestic manufacturing, while China's NMPA registration requirements reshape import pathways. FDA and EU MDR thermal stability mandates are accelerating replacement cycles across tertiary hospital networks in mature markets.
United States
Level III and IV NICU renovations in US health networks specify servo-controlled warmer platforms with integrated phototherapy modules. FDA 510(k) clearance timelines for servo-feedback algorithms have extended premarket review periods. Boston and Philadelphia medical centers anchor procurement demand through GPO-negotiated multi-vendor service agreements.
China
Domestic manufacturers in Shenzhen dominate cost-optimized infrared production for Asia-Pacific price-sensitive segments. NMPA cybersecurity guidelines mandate penetration testing and data encryption for networked warmer platforms. Beijing and Shanghai tertiary hospitals drive premium-tier demand for dual-skin-sensor servo architectures.
Germany
German tertiary hospitals specify mobile castor-mounted warmers for flexible room utilization in maternal-infant care renovations. EU MDR electromagnetic compatibility requirements are accelerating replacement of legacy analog units. Munich and Hamburg medical clusters lead adoption of ceramic infrared emitter technologies.
India
Regional perinatal referral system expansion pulls demand for portable transport warmers with battery backup systems. PLI scheme capital subsidies enable domestic manufacturing pathways for regional market penetration. Delhi and Mumbai district hospitals concentrate procurement of cost-optimized radiant heat beds.
Infant Radiant Warmer Market Competitive Environment
On the supply side, the industry is consolidating around integrated maternal-infant care ecosystems rather than standalone device vendors. The competitive terrain stratifies into three tiers: diversified medical technology conglomerates with installed base leverage, specialized neonatal equipment manufacturers with clinical workflow expertise, and regional fabricators serving price-sensitive procurement channels. Dominant competitive moves include bundling warmers with monitoring and ventilation ecosystems, and unbundling service contracts from hardware purchases to capture recurring revenue streams.
Among diversified healthcare technology groups, GE Healthcare and Philips Healthcare represent the installed-base-leverage archetype, anchoring positions through maternal-infant care system integration. Fisher & Paykel Healthcare exemplifies the specialized workflow-integrated tier, while Natus Medical Incorporated occupies a position within the neonatal-focused equipment segment. These three anchors illustrate how competitive positioning diverges between conglomerate scale and clinical specialization.
| Leading Market Players |
|---|
| Natus Medical Incorporated |
| Fisher & Paykel Healthcare |
| GE Healthcare |
| Novos |
| Fanem |
| Draeger |
| Philips Healthcare |
| Phoenix Medical Systems |
| Atom Medical Corporation |
| Others |
Value Chain & Pricing Dynamics
Tungsten filament and fused quartz supply chains concentrate in Chinese and German manufacturing regions, anchoring margin pools with OEMs that command multi-year service contracts and proprietary sensor calibration protocols. Ceramic emitter migration is redistributing value toward suppliers with backward integration into rare-earth mineral processing, compressing margins for assemblers dependent on spot-market component sourcing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates servo-controlled digital platforms with cloud connectivity from conventional infrared units and basic radiant heat beds. Price differentiation hinges on FDA 510(k) clearance tier and embedded phototherapy module inclusion, with United States health networks showing lowest sensitivity due to GPO-negotiated bundled procurement. Pricing pressure stems from India's PLI scheme enabling domestic manufacturers to undercut imported units by 15-25% in district hospital tenders. Indian district hospitals and Chinese county-level facilities exhibit highest price sensitivity, while German tertiary centers prioritize thermal precision over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for quartz-halogen element sourcing, with alternative ceramic emitter production scaling in South Korea and Japan. Raw material dependencies center on tungsten wire drawing, fused quartz tube extrusion, and rare-earth ceramic substrate preparation. Single-source vulnerability concentrates in German precision sensor manufacturers serving servo-control feedback loops. Distribution runs through hospital GPO consortiums in North America, direct government tender channels in India, and provincial procurement platforms in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from preventive maintenance contracts and sensor calibration subscriptions is expanding faster than hardware unit sales, as hospital capital committees unbundle acquisition from lifecycle support. Recurring revenue pools now exceed 40% of total account value for installed-base leaders.
For Market Incumbents: Pre-empt ceramic emitter supply consolidation by securing long-term offtake agreements with South Korean substrate manufacturers before regional competitors lock in capacity. Defend against emerging Chinese domestic manufacturers by embedding predictive thermal algorithms into existing servo-control platforms, creating switching costs that offset price undercutting in tender processes. For New Entrants and Emerging Players: Build out portable transport warmer capabilities targeting India's expanding regional perinatal referral networks, where battery-backed configurations face limited indigenous competition. Capture share in Chinese NMPA cybersecurity compliance services for legacy warmer retrofitting, leveraging the regulatory mandate as a service-led entry point before hardware certification. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed neonatal equipment specialists holding strong positions in European service contracts but limited Asia-Pacific manufacturing footprint. Five-to-ten year viability favors platforms with installed-base density above 10,000 units and recurring service attachment rates exceeding 60%. Watch for FDA 510(k) clearance backlog resolution as inflection signal for new platform launch windows and valuation multiple expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR thermal stability mandates accelerate replacement demand across German and French tertiary hospitals. |
| Hospital System Partnership | GPO-negotiated multi-vendor agreements in US health networks lock in recurring service revenue streams. |
| Software Companion Development | Cloud-connected thermal data platforms address staffing shortages in level IV NICU nursing stations. |
| FDA Submission | 510(k) clearance for dual-skin-sensor servo architectures commands premium positioning in academic medical centers. |
| Reimbursement Strategy | Alignment with DRG coding for neonatal hypothermia prevention drives procurement authority in US facilities. |
Study Parameters
Cross-validation between hospital procurement database analysis and clinical workflow interviews anchors the qualitative findings in observable purchasing behavior. Primary fieldwork engaged NICU directors, biomedical engineering managers, GPO contracts specialists, and regulatory affairs leads at manufacturers across the United States, China, Germany, and India. Secondary sources encompass FDA 510(k) clearance databases, NMPA registration filings, EU MDR technical documentation, and hospital capital equipment tender records. Bottom-up unit shipment tracking and top-down healthcare expenditure allocation models were reconciled through iterative calibration.
Calibration against historical replacement cycle data and regulatory implementation timelines shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, technology tier, end-user facility class, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to technology substitution patterns and procurement elasticity estimates. Forecast inputs incorporated ceramic emitter cost-down trajectories and PLI scheme subsidy absorption rates.
Sensitivities concentrate around NMPA cybersecurity guideline enforcement intensity and FDA 510(k) review period extension. Forecasts reflect assumptions on servo-control accuracy standard adoption curves and inter-facility transport network expansion pace. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Spinal Fusion Devices Market
Medical Devices
Contact and Intraocular Lenses Market
Medical Devices
Ophthalmoscopes Market
Medical Devices
Germany Minimally Invasive Surgery Devices Market
Medical Devices
Middle East and Africa Electroencephalography Devices Market
Medical Devices
Medical Device Cros Market
Medical Devices
Global Metal Implants and Medical Alloys Market
Medical Devices
Global Self Care Medical Devices Market
Medical Devices
Italy Ophthalmic Devices Market
Medical Devices
Heel Incision Devices Market
Medical Devices
Australia Medtech Market
Medical Devices
Veterinary Anesthesia Equipment Market
Medical Devices
Cystic Fibrosis Devices Market
Medical Devices
Mhealth (Mobile Health) Devices Market
Medical Devices
Acute External Ventricular Drain Market
Medical Devices
Global Pregnancy Detection Kits Market