
 Fire and Explosion Proof Lights Market | 2026-2036
Fire and Explosion Proof Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Fire and Explosion Proof Lights Market Foresight
ATEX Zone 1 and Zone 2 certification upgrades is redrawing procurement standards across hazardous environment lighting. Eaton Corporation leverages its integrated electrical portfolio to anchor large petrochemical contracts in North America. R. STAHL AG specializes in German-engineered explosion protection systems and dominates European offshore platform retrofits. Hubbell Incorporated extends its coastal manufacturing footprint to compete on delivery speed for urgent turnaround projects.
Fire and explosion proof lights are sealed luminaires engineered with flameproof enclosures, impact-resistant borosilicate glass, and precision thermal management to prevent ignition of surrounding flammable gases or dust in classified hazardous locations. These fixtures operate across temperature classes T1 through T6, maintaining surface temperatures below auto-ignition thresholds of ambient explosive atmospheres in oil refineries, chemical plants, and underground extraction facilities. LED product types now command the dominant share of new specifications due to extended operational life and reduced wattage requirements in confined space installations. Oil and gas applications generate the deepest margin pools, though chemical processing is recording the fastest specification growth as European REACH compliance tightens volatile organic compound handling protocols. Portable installation formats remain niche but are expanding in maintenance-intensive mining environments where temporary lighting mobility reduces downtime.
ATEX directives enforced by EU member state notified bodies, IECEx international certification schemes, and UL hazardous location standards collectively dictate enclosure integrity, testing protocols, and market access eligibility for explosion-proof lighting manufacturers. OSHA process safety management regulations in the United States and China's GB standards administered by SAMR further segment compliance requirements by geography, forcing suppliers to maintain multiple certification portfolios. Stakeholders must monitor divergence between regional certification reciprocity agreements and emerging battery-powered portable fixture standards that could reshape supplier qualification costs and competitive positioning.
Market Dynamics
LED retrofit cycles on North Sea oil platforms are compressing replacement intervals from five-year to ten-year horizons, forcing incumbent suppliers to restructure service revenue models around predictive maintenance rather than fixture turnover.
Growth Catalysts
- REACH compliance tightening:European chemical processors face mandatory volatile organic compound handling protocol upgrades, triggering wholesale lighting specification reviews across solvent storage and mixing facilities.
- SAMR enforcement of GB standards:China's State Administration for Market Regulation is accelerating hazardous location certification audits, disqualifying uncertified suppliers from petrochemical tenders in Sichuan and Shandong provinces.
- Deepwater exploration resumption:Brazil's pre-salt field development is driving demand for submersible explosion-proof luminaires rated to 3,000-meter depths with integrated pressure-compensated thermal management.
Market Restraints
- Aluminum enclosure cost volatility:Die-cast aluminum housing fabrication represents 35-40% of bill-of-materials exposure, with LME price swings compressing margin buffers for mid-tier fixture assemblers.
- Single-source borosilicate glass supply:Precision glass dome production concentrates among three German and Japanese specialty manufacturers, creating vulnerability to force majeure disruptions in flameproof sealing components.
- ATEX-IECEx divergence:Non-harmonized testing protocols between EU notified bodies and international scheme operators force redundant certification expenditure for suppliers serving both European and Gulf markets.
Strategic Opportunities
- Battery-powered portable fixtures:Lithium-thionyl chloride chemistry integration enables cordless Zone 0 temporary lighting for turnaround maintenance, opening specification channels previously dominated by cabled permanent installations.
- India's underground coal safety mandate:The Coal Mine Regulation 2017 amendment requires methane-rated LED cap lamps and tunnel luminaires across Jharkhand and Odisha extraction operations, creating import substitution openings for certified suppliers.
- Digital twin integration:Embedding IoT sensors within explosion-proof enclosures enables real-time thermal monitoring and predictive failure alerting, converting hardware suppliers into recurring-revenue service providers.
Industry Challenges
- IECEx CoPC qualification scarcity:Certified personnel for explosion protection equipment installation and inspection remain concentrated in Western Europe, constraining project execution capacity in Africa and Southeast Asia expansion markets.
- Legacy halogen-LED control compatibility:Retrofit projects encounter impedance mismatches between existing cable gland configurations and LED driver electronics, extending commissioning timelines and warranty exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire and Explosion Proof Lights Market |
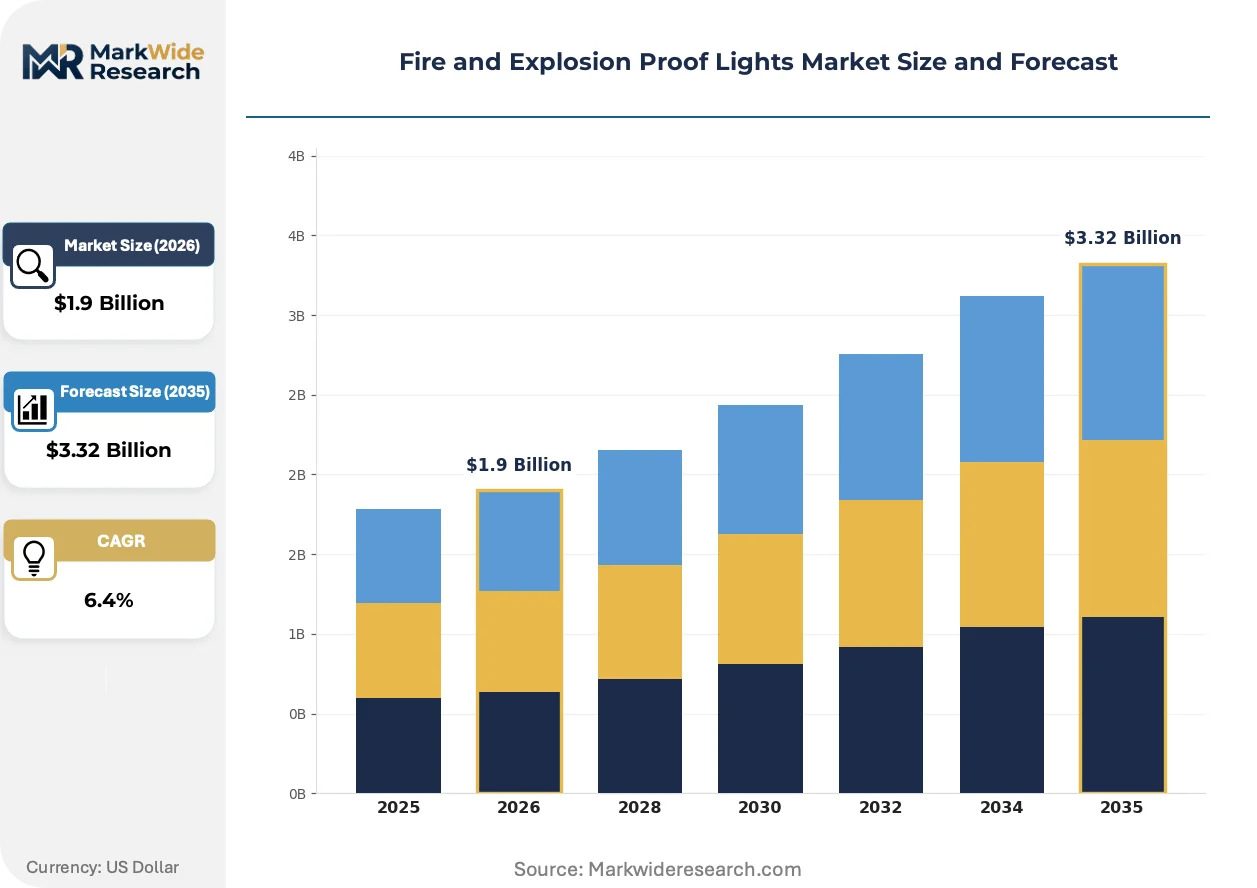
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $3.32 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Fluorescent, Halogen, Xenon Application: Oil & Gas, Chemical Processing, Mining, Aerospace Installation: Wall-mounted, Ceiling-mounted, Portable, Fixed Certification: ATEX, IECEx, UL, FM |
| Companies Covered | Eaton Corporation, Hubbell Incorporated, Emerson Electric, R. STAHL AG, Larson Electronics, Dialight plc, Phoenix Lighting, Zhejiang Tormin Electrical Co., ABB Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire and Explosion Proof Lights Market Shifts & Advancements
Explosion-proof lighting specification is pivoting from lumen-per-watt optimization toward integrated system intelligence, with thermal sensing and wireless diagnostics becoming baseline requirements in premium hazardous location tenders.
Chip-on-board LED arrays with ceramic substrate thermal dissipation are displacing discrete SMD packages in high-lumen output fixtures. Offshore platform operators in the Norwegian Continental Shelf specify these modules for helideck floodlighting applications. The technology is miniaturizing driver electronics sufficiently to embed dual-redundant power circuits within Zone 1 rated enclosures previously limited to single-channel architectures.
OSHA's updated Process Safety Management enforcement memo targets electrical ignition sources in petroleum refineries, mandating documented thermal imaging surveys of classified location luminaires. US Gulf Coast operators are accelerating LED upgrade schedules to preempt citation exposure during programmed inspections. Chemical processing facilities with legacy high-pressure sodium installations face the steepest compliance cost trajectories.
Specification authority is migrating from maintenance departments to centralized engineering procurement functions with standardized hazardous location technical competencies. This consolidation eliminates regional variance in lighting standards across multi-site petrochemical operators. The pattern is most pronounced among integrated supermajors with US, German, and Chinese manufacturing footprints seeking procurement leverage through volume aggregation.
Fire and Explosion Proof Lights Market Segmentation
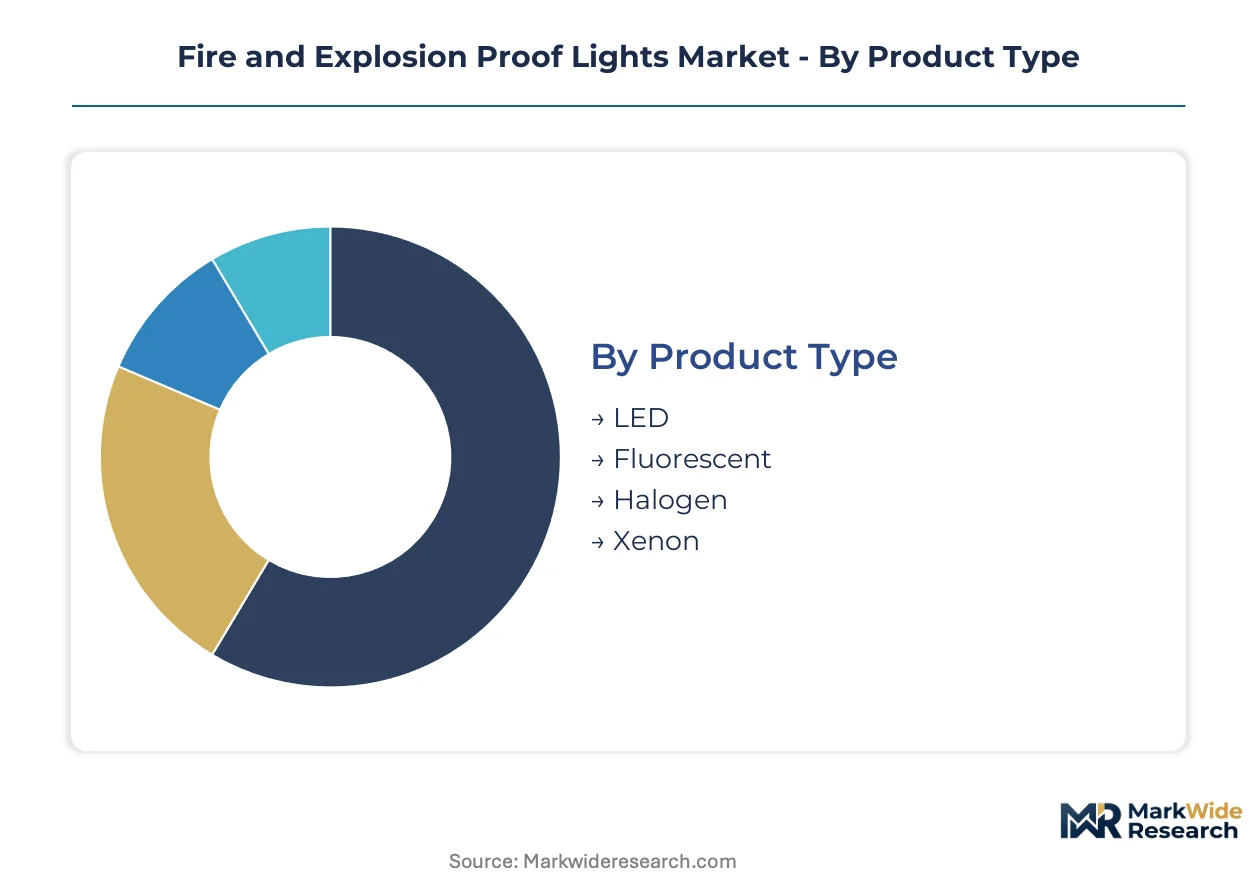
Segmentation in the Fire and Explosion Proof Lights Market reveals distinct procurement patterns across product technologies, end-use industries, and certification regimes. Specification authority varies sharply between permanent infrastructure investments and temporary maintenance deployments, with regulatory compliance costs creating divergent margin structures across each category.
Product Type:
LED fixtures dominate domestic specification in the United States, Germany, and China, while fluorescent and halogen technologies retain export-led demand in Southeast Asian and African markets with deferred capital cycles.
- LED:Chip-on-board arrays with ceramic substrate thermal dissipation enable lumen outputs exceeding 20,000 lumens in Zone 1 enclosures. Demand concentrates in Norwegian Continental Shelf offshore platforms and US Gulf Coast refineries where ten-year maintenance intervals offset premium first costs.
- Fluorescent:T5 and T8 linear fixtures with encapsulated ballasts persist in chemical processing solvent storage areas where diffuse lighting distribution reduces shadow hazards. European REACH compliance tightening is accelerating replacement schedules in German and Dutch petrochemical clusters.
- Halogen:Tungsten-halogen spot luminaires with quartz envelopes serve legacy platform infrastructure in Brazil's pre-salt fields where capital constraints delay LED retrofit cycles.
- Xenon:High-intensity discharge arc lamps with ceramic metal halide chemistry address helideck floodlighting applications requiring instant restrike capability after voltage dips.
LED holds the largest share; momentum sits with chip-on-board architectures displacing discrete SMD packages.
Application:
Oil and gas applications generate the deepest margin pools through specification bundling with integrated electrical packages, while mining and aerospace segments exhibit cost-tier fragmentation between premium-certified and economy-grade procurement channels.
- Oil & Gas:Offshore platform operators in the North Sea and Gulf of Mexico specify ATEX Zone 1 pendant luminaires with integrated junction boxes for drilling deck illumination. Brazil's deepwater pre-salt resumption is driving submersible fixture demand rated to 3,000-meter depths.
- Chemical Processing:Solvent storage tank farms and mixing facilities require T6 temperature class luminaires maintaining surface temperatures below 85°C. European ECHA enforcement of volatile organic compound handling protocols is triggering wholesale lighting specification reviews.
- Mining:Methane-rated LED cap lamps and tunnel luminaires face mandatory deployment across India's Jharkhand and Odisha coal belts under the 2017 Coal Mine Regulation amendment.
- Aerospace:Fuel cell maintenance hangars and paint booth facilities specify FM-approved fixtures with sealed conduit entries to prevent vapor ignition during aircraft coating operations.
Oil and gas commands the dominant revenue position; chemical processing is climbing the fastest on regulatory compliance pressure.
Installation:
Permanent mounting formats concentrate in greenfield petrochemical construction, while portable installations expand through maintenance contractor procurement in turnaround-intensive refining and mining operations.
- Wall-mounted:Stanchion and bracket configurations with 180-degree adjustable joints illuminate perimeter process areas and loading racks. US OSHA Process Safety Management enforcement is accelerating thermal imaging survey compliance for existing wall-mounted halogen stocks.
- Ceiling-mounted:Pendant and surface-mounted enclosures with prismatic diffusers distribute general area lighting in control rooms and analyzer shelters. German chemical processors specify these for solvent handling facilities under ATEX Zone 2 classification.
- Portable:Battery-powered units with lithium-thionyl chloride chemistry enable cordless Zone 0 temporary lighting for turnaround maintenance, opening specification channels previously dominated by cabled permanent installations.
- Fixed:Hardwired conduit systems with explosion-proof junction boxes serve permanent infrastructure in Chinese petrochemical expansions across Sichuan and Shandong provinces under SAMR-accelerated certification audits.
Fixed installation retains the largest installed base; portable formats are gaining share fastest on maintenance mobility requirements.
Certification:
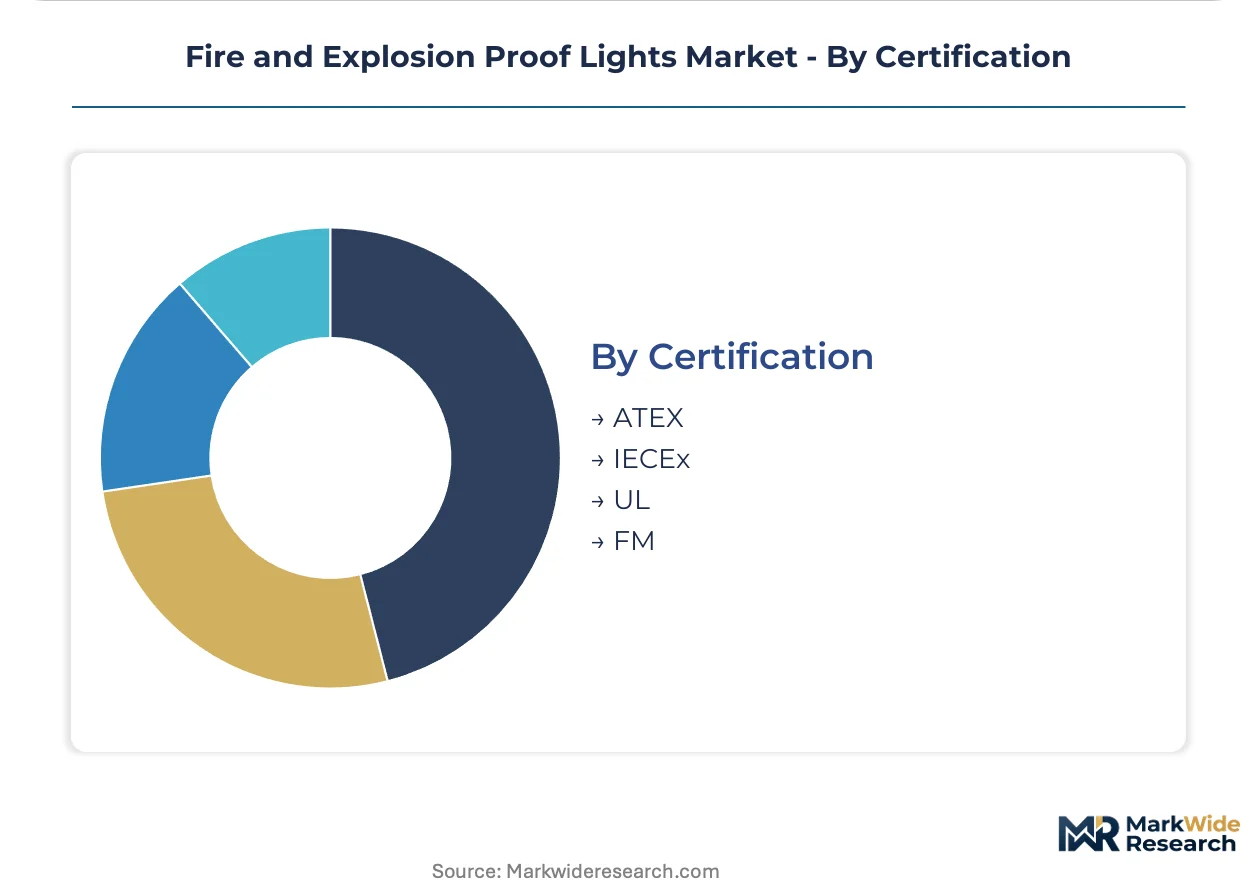
ATEX and IECEx schemes dominate European and international procurement, while UL and FM approvals gate access to North American hazardous location tenders with non-reciprocal testing requirements.
- ATEX:EU member state notified bodies enforce Directive 2014/34/EU for equipment intended for use in potentially explosive atmospheres. Harmonization pressures with IECEx are compressing supplier qualification timelines for Gulf Cooperation Council member states.
- IECEx:International Electrotechnical Commission scheme operators coordinate certification reciprocity across 35 participating countries. Divergence from ATEX testing protocols forces redundant expenditure for suppliers serving both European and Gulf markets.
- UL:Underwriters Laboratories hazardous location standards govern Class I Division 1 and Division 2 installations across US petroleum refineries and chemical plants.
- FM:Factory Mutual approval marks indicate compliance with loss prevention standards for property risk reduction in insured industrial facilities.
ATEX holds the broadest geographic recognition; IECEx is expanding most quickly through developing market adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in fire and explosion proof lighting tilt toward certification-heavy manufacturing centers supplying hazardous location infrastructure worldwide. Germany and the United States maintain structural trade surpluses in ATEX and UL-certified fixtures, while China's SAMR-accelerated domestic qualification absorbs previously import-dependent petrochemical demand.
United States
OSHA Process Safety Management enforcement targets electrical ignition sources in petroleum refineries along the Gulf Coast. The updated enforcement memo mandates documented thermal imaging surveys of classified location luminaires. Houston and Corpus Christi clusters accelerate LED upgrade schedules to preempt citation exposure during programmed inspections.
Germany
ECHA REACH compliance tightening triggers wholesale lighting specification reviews across solvent storage and mixing facilities. ATEX Directive 2014/34/EU enforcement by notified bodies compresses supplier qualification timelines. The BASF-Ludwigshafen and Bayer-Leverkusen chemical corridors drive premium fixture demand for T6 temperature class installations.
China
SAMR enforcement of GB standards disqualifies uncertified suppliers from petrochemical tenders in Sichuan and Shandong provinces. State-backed refinery expansions in the Yangtze River Delta and Bohai Bay Rim absorb domestic LED fixture output. Local certification acceleration reduces import dependency for Zone 1 and Zone 2 rated enclosures.
Brazil
Pre-salt deepwater field development drives demand for submersible explosion-proof luminaires rated to 3,000-meter depths. Petrobras procurement specifications integrate IECEx certification with national petroleum regulator ANP safety protocols. The Santos Basin offshore cluster anchors fixture deployment for integrated pressure-compensated thermal management systems.
India
The 2017 Coal Mine Regulation amendment mandates methane-rated LED cap lamps and tunnel luminaires across Jharkhand and Odisha extraction belts. Dhanbad and Talcher mining districts face procurement urgency under safety mandate deadlines. Import substitution openings emerge for certified suppliers as domestic fabrication capacity lags specification requirements.
Fire and Explosion Proof Lights Market Competitive Landscape
Concentration sits with diversified electrical conglomerates and specialized explosion protection engineering houses. The vendor base organizes around three strategic archetypes: integrated electrical portfolio suppliers, German-engineered protection system specialists, and coastal manufacturing footprint competitors. Dominant competitive moves include certification portfolio diversification across ATEX-IECEx-UL regimes and predictive maintenance service model restructuring to offset compressed LED replacement cycles.
Among diversified electrical conglomerates, Eaton Corporation and ABB Ltd occupy positions anchoring large petrochemical contracts through bundled infrastructure offerings. R. STAHL AG exemplifies the specialized German-engineered archetype dominating European offshore platform retrofits. Hubbell Incorporated sits within the coastal manufacturing tier competing on delivery speed for urgent turnaround projects. These three anchors represent distinct competitive vectors without implying specific strategic actions or market share positions.
| Leading Market Players |
|---|
| Eaton Corporation |
| Hubbell Incorporated |
| Emerson Electric |
| R. STAHL AG |
| Larson Electronics |
| Dialight plc |
| Phoenix Lighting |
| Zhejiang Tormin Electrical Co. |
| ABB Ltd |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts with integrated petrochemical operators lock in die-cast aluminum enclosure supply from German and Japanese specialty foundries while fixing price visibility across ten-year LED fixture replacement cycles. These arrangements insulate Tier 1 suppliers from LME aluminum volatility while binding mid-tier assemblers to spot-market exposure on borosilicate glass domes.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. ATEX Zone 1 certification tier commands substantial premiums over UL Class I Division 2 equivalents, with brand equity from German-engineered protection systems sustaining margin separation. Cost compression in mid-tier fixture assemblies is intensifying because Chinese SAMR enforcement has disqualified uncertified suppliers, forcing price competition among qualified incumbents. Maintenance contractors in turnaround-intensive refining operations exhibit highest price sensitivity, while offshore platform operators prioritize total cost of ownership over unit economics.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes have extended inbound logistics cycles for ceramic substrate LED arrays sourced from Taiwanese foundries. Die-cast aluminum housing fabrication concentrates in Germany, China, and the United States, while precision borosilicate glass dome production rests on three German and Japanese specialty manufacturers. Single-source vulnerability in flameproof sealing components creates force majeure exposure. Distribution runs through certified electrical distributors and direct OEM procurement channels for large petrochemical contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance service contracts are expanding faster than hardware turnover as LED retrofit cycles compress replacement intervals, converting fixture suppliers into recurring-revenue platforms anchored by thermal monitoring and failure alerting capabilities.
For Market Incumbents: Fortify certification portfolio breadth across ATEX-IECEx-UL regimes to preempt disqualification from multi-regional tenders. Deepen backward integration into ceramic substrate LED array sourcing to offset Taiwanese foundry concentration. Anchor large petrochemical contracts through bundled electrical infrastructure offerings that raise switching costs for maintenance contractors. For New Entrants and Emerging Players: Portable battery-powered Zone 0 temporary lighting represents an underserved service layer where incumbents under-serve maintenance-intensive mining and turnaround refining operations. Target India's Jharkhand and Odisha coal belts under 2017 Coal Mine Regulation mandate deadlines where domestic fabrication capacity lags specification requirements. Pursue IECEx CoPC qualification partnerships with Western European training bodies to overcome certified personnel scarcity in African and Southeast Asian expansion markets. For Investors and Strategic Acquirers: Capital is best deployed toward German-engineered explosion protection specialists with entrenched offshore platform retrofit positions and ATEX certification moats. Long-term viability hinges on conversion from transactional fixture sales to predictive maintenance service models. Watch for IECEx-ATEX harmonization progress as inflection indicator for supplier qualification cost compression and margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Portfolio Expansion | ATEX-IECEx-UL triple qualification opens access to US Gulf Coast, North Sea, and GCC petrochemical tenders simultaneously. |
| Predictive Maintenance Service Launch | IoT-embedded thermal monitoring converts hardware suppliers into recurring-revenue platforms with ten-year contract visibility. |
| Ceramic Substrate Backward Integration | In-house chip-on-board LED array production reduces dependency on Taiwanese foundry concentration and margin compression. |
| Portable Battery-Powered Fixture Development | Lithium-thionyl chloride chemistry enables cordless Zone 0 specification capture in turnaround maintenance channels. |
| IECEx CoPC Training Partnership | Certified personnel pipeline construction unlocks project execution capacity in African and Southeast Asian expansion markets. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant engineers, maintenance directors at offshore platform operators, OEM procurement teams, and aftermarket service heads; and secondary validation through ATEX notified body certification registries, IECEx equipment database filings, OSHA enforcement memoranda, and customs trade records for hazardous location electrical equipment. Bottom-up fixture shipment analysis triangulated against top-down petrochemical capital expenditure tracking.
Across the projection horizon, the analytical framework modeled volume and value outputs by product technology, end-use industry, certification regime, and installation format. CAGRs were derived from segment-level replacement cycle analysis and regulatory compliance-driven specification upgrade trajectories. SAMR audit acceleration timelines and REACH enforcement intensity served as key forecast inputs for China and European demand trajectories respectively.
Material uncertainties — aluminum LME price volatility, borosilicate glass supply disruptions, and ATEX-IECEx protocol divergence — sit outside the modeled envelope. Forecasts reflect assumptions regarding certification reciprocity progression and LED retrofit cycle stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Fire Resistant Silicone Sealant Market
Fire Safety & Protection
UAE Fire Protection System Market
Fire Safety & Protection
China Thermal Protector Market
Fire Safety & Protection
Deflagration Flame Arresters Market
Fire Safety & Protection
Civil Combustible Gas Alarm Market
Fire Safety & Protection
Cellulosic Fire Protection Market
Fire Safety & Protection
Laser Smoke Detector Market
Fire Safety & Protection
Fire Suppression Agent Market
Fire Safety & Protection
US Fire Safety Equipment Market
Fire Safety & Protection
Earthing Lightning Protection System Market
Fire Safety & Protection
Wireless Fire Detection Systems Market
Fire Safety & Protection
Commercial Smoke Alarm Market
Fire Safety & Protection
Global Fire Resistant Cable Market
Fire Safety & Protection
Fire Resistant Glass Market
Fire Safety & Protection
Africa Fire Suppression Market
Fire Safety & Protection
Fire Protection Systems Market