
 Smoke Pressure System Market | 2026-2036
Smoke Pressure System Market Size, Share, and Industry Trends Forecast 2026-2036
Smoke Pressure System Market Intelligence
Aftermarket service revenue is rewriting how suppliers capture lifetime value from installed smoke pressure infrastructure. Greenheck Fan Corporation leverages its North American service network to extend recurring revenue from fire safety system maintenance. TROX GmbH anchors its European position through specialized commissioning and retrofit services for aging commercial building portfolios.
A smoke pressure system is a mechanical ventilation assembly engineered to maintain controlled pressure differentials across building compartments during fire events, typically achieving 50 Pa to 200 Pa differential pressure to prevent smoke infiltration into escape routes. Positive pressure systems dominate procurement for high-rise stairwell protection due to their established installation protocols and simpler commissioning requirements. Electric actuator technology is displacing pneumatic alternatives in new construction as facility managers prioritize integration with building management platforms and reduced compressor maintenance.
The EU Green Deal and EN 12101 series standards from the European Committee for Standardization shape product design mandates across member states, while the EPA and NFPA 92 guidelines govern U.S. smoke control system specifications and testing protocols. China's GB standards and MIIT directives add compliance layers for manufacturers serving infrastructure projects under dual carbon goals. Stakeholders must monitor divergence between regional certification requirements as project developers pursue multi-jurisdiction building portfolios.
Market Dynamics
The EU Green Deal's carbon neutrality mandates are accelerating building electrification retrofits across Western Europe, forcing smoke pressure system suppliers to redesign fan motor architectures and control logic for tighter energy budgets while maintaining NFPA 92-equivalent safety performance.
Growth Catalysts
- EN 12101-6 Stairwell Pressurization Mandates:Updated European Committee for Standardization protocols require automatic pressure modulation in high-rise escape routes, compelling building owners to upgrade legacy constant-volume installations.
- Balanced Pressure Systems:Commercial developers in Germany and France are specifying dual-path designs that protect both stairwells and elevator lobbies from a single mechanical plant, reducing equipment footprints in constrained plant rooms.
- High-Rise Construction Corridors:Urban densification policies in Frankfurt, Paris, and Rotterdam are concentrating super-tall residential permits where smoke control complexity demands engineered pressure differential solutions.
Market Restraints
- Copper and Rare-Earth Magnet Volatility:Permanent magnet motors for high-efficiency fan drives face input cost swings from Chinese export quotas on neodymium processing.
- Certification Timeline Friction:Divergent testing protocols between EPA smoke control guidelines and EU Green Deal product environmental footprints force dual validation expenditures for multi-jurisdiction suppliers.
- Pneumatic Actuator Replacement Cycles:Existing building portfolios with compressed air infrastructure resist full electromechanical retrofits due to sunk capital in pneumatic distribution networks.
Strategic Opportunities
- Building Management System Convergence:BACnet and Modbus integration protocols enable smoke pressure units to feed real-time airflow data into centralized energy optimization platforms.
- Aging Commercial Stock in Belgium and Netherlands:Post-war office buildings approaching structural renewal windows present bundled fire safety and HVAC modernization procurement.
- MIIT Dual Carbon Alignment:Chinese infrastructure projects under national carbon peak mandates are importing European-certified smoke control designs for prestige developments in Shanghai and Shenzhen.
Industry Challenges
- Commissioning Engineer Scarcity:Specialized technicians capable of validating 50-200 Pa differential pressure setpoints across multi-zone buildings command premium labor rates and extended project timelines.
- Legacy Fire Alarm Integration:Smoke pressure systems must interface with proprietary notification appliance circuits from established fire detection vendors, requiring protocol gateway development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smoke Pressure System Market |
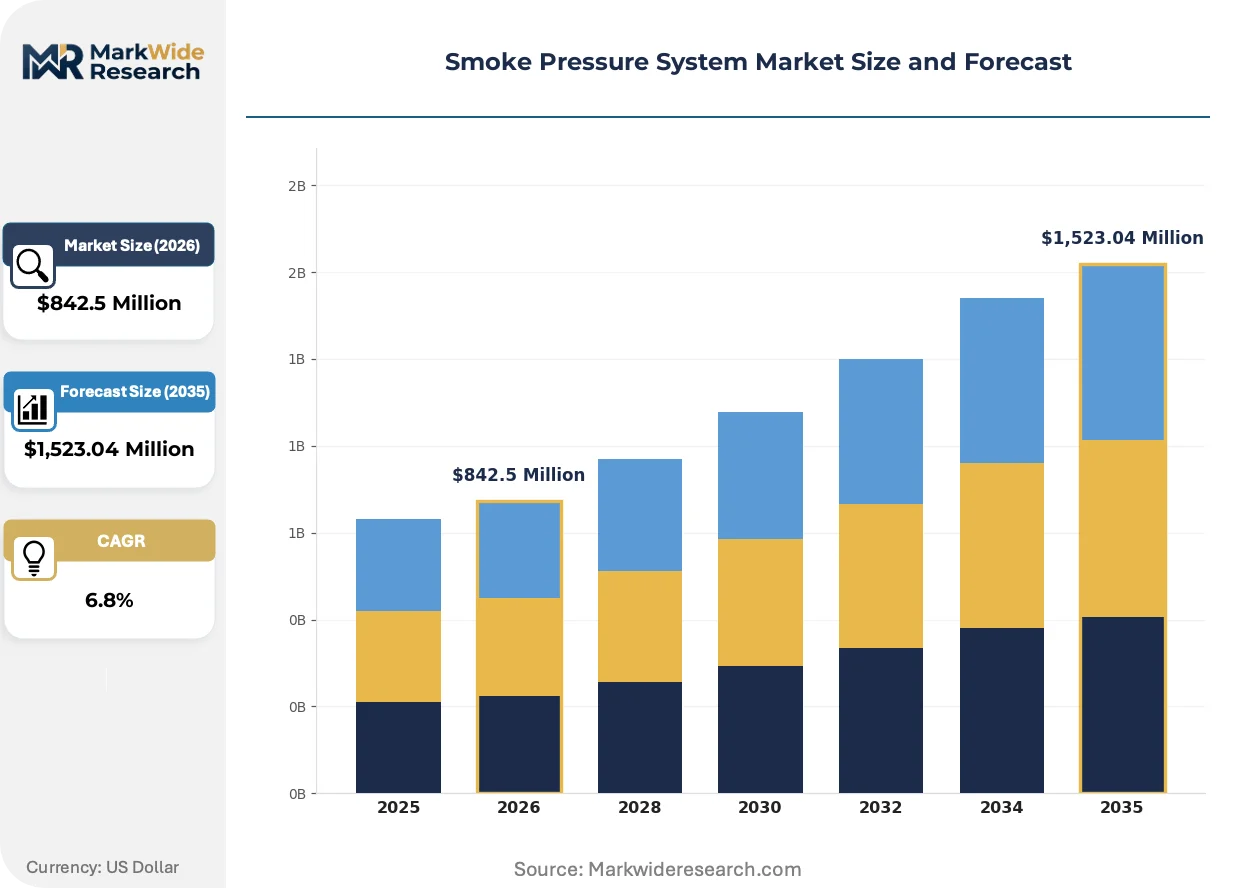
| Market Size in 2026 | $842.5 Million |
| Market Size in 2035 | $1,523.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Positive Pressure Systems, Negative Pressure Systems, Balanced Pressure Systems, Hybrid Pressure Systems Technology: Hydraulic, Pneumatic, Electric, Electro-Mechanical, Thermal Application: Fire Safety Systems, Industrial Ventilation, Commercial Buildings, Transportation Facilities, Public Infrastructure End User: Construction Firms, Factory Operators, Transport Authorities, Facility Managers, Emergency Response Teams |
| Companies Covered | Systemair AB, Greenheck Fan Corporation, FläktGroup, Johnson Controls, Colt International Ltd., TROX GmbH, Siemens Building Technologies, Soler & Palau, Nuaire, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smoke Pressure System Market Strategic Shifts & Innovations
Digital thread technologies are penetrating smoke control engineering workflows, compressing design-validation cycles while enabling predictive maintenance models that shift revenue from equipment sales to performance guarantees.
Variable frequency drive technology with embedded pressure transducers is digitizing fan speed modulation in real-time response to door-opening events and wind stack effects. Facility managers in London and Milan are specifying these self-tuning arrays to eliminate manual damper balancing during commissioning. The technology is digitizing how building operators verify life safety system readiness through continuous performance logging rather than periodic inspection.
The EU Green Deal's embodied carbon reporting requirements through the CSRD are forcing manufacturers to disclose full lifecycle emissions for steel housings and aluminum impellers. Component suppliers in Northern Italy and the Ruhr Valley are restructuring foundry energy contracts to secure renewable power certificates that satisfy tender evaluation criteria. German general contractors are now weighting environmental product declarations at 15-20% of technical scoring for public sector smoke control procurements.
Service unbundling is fragmenting traditional equipment-plus-installation contracts into separate commissioning, digital monitoring, and predictive maintenance subscriptions. Institutional property owners in Paris and Frankfurt are purchasing guaranteed pressure differential uptime rather than capital assets, transferring operational risk to OEM service arms. This model concentrates in Class A commercial towers where fire safety system downtime triggers lease penalty clauses and reputational exposure.
Smoke Pressure System Market Segmentation
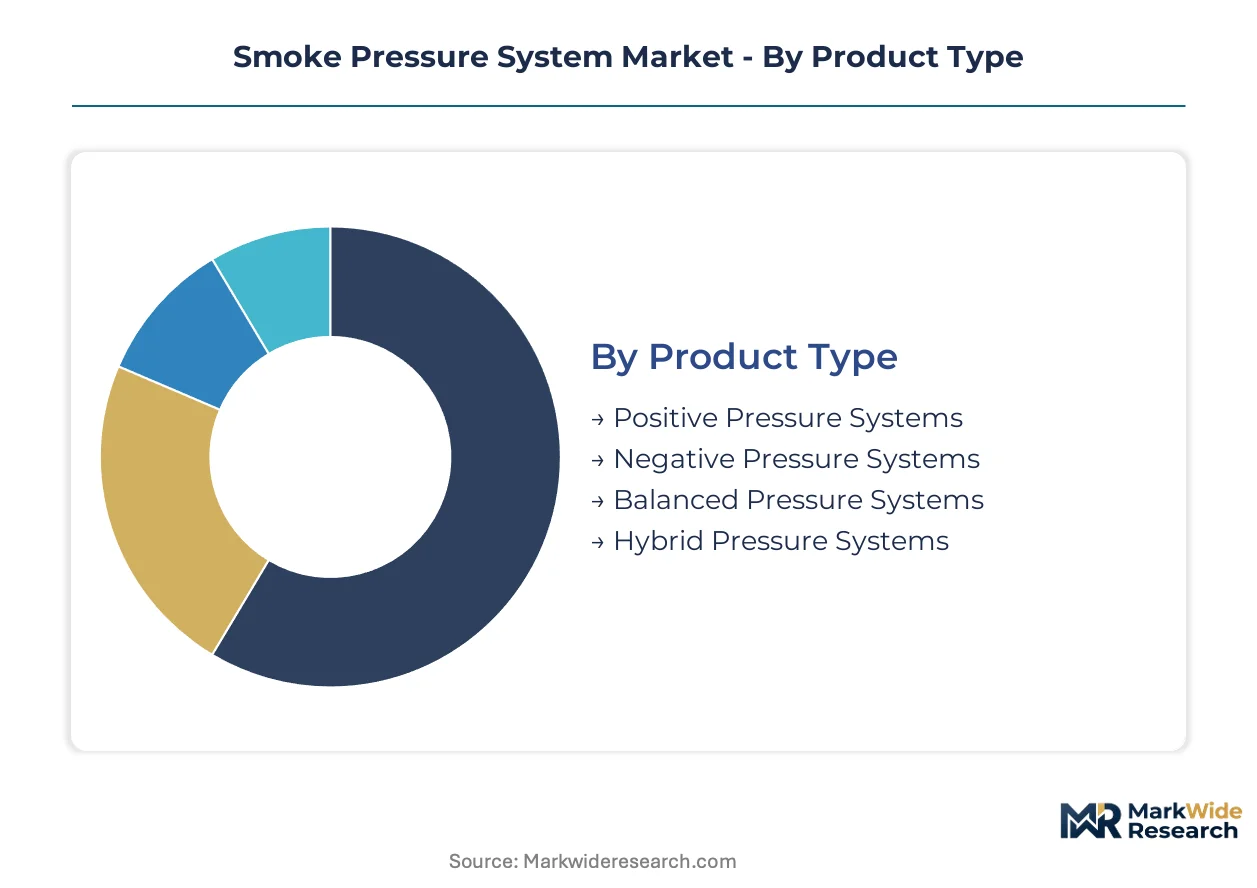
Segmentation in smoke pressure systems determines aftermarket revenue capture and commissioning complexity. Product architecture shapes maintenance intervals, while technology choices dictate integration pathways with building management platforms.
Product Type:
After-sales-service intensity varies sharply across pressure system architectures, with balanced and hybrid designs requiring specialized technician networks for multi-zone calibration.
- Positive Pressure Systems:These assemblies generate 50-200 Pa differential pressure to protect stairwells and escape routes from smoke infiltration. Demand concentrates in Frankfurt and Paris high-rise residential towers where EN 12101-6 mandates automatic pressure modulation. Commissioning protocols are standardized, reducing service technician training burdens.
- Balanced Pressure Systems:Dual-path mechanical plants protect both stairwells and elevator lobbies from centralized equipment, reducing plant room footprints. German and French commercial developers specify these for constrained urban sites. The design complexity elevates commissioning costs but lowers lifetime energy consumption through optimized fan staging.
- Negative Pressure Systems:These configurations extract smoke from fire compartments to maintain tenable conditions for occupant egress. Industrial facilities in the Ruhr Valley deploy them for atrium and warehouse protection where smoke reservoir volumes exceed stairwell pressurization capacity.
- Hybrid Pressure Systems:Configurable architectures switch between positive and negative modes based on fire location detection. Rotterdam super-tall developments specify these for flexible response to complex building geometries.
Positive pressure systems hold the largest share; momentum sits with balanced pressure systems.
Technology:
Cost tier stratification separates premium electric actuators from legacy pneumatic infrastructure, with electro-mechanical hybrids occupying the mid-market for retrofit compatibility.
- Electric:Actuator technology with embedded pressure transducers enables real-time fan speed modulation responding to door-opening events and wind stack effects. London and Milan facility managers specify these for self-tuning arrays that eliminate manual damper balancing. BACnet integration drives procurement in Class A commercial towers.
- Electro-Mechanical:Hybrid architectures combine electric precision with mechanical redundancy for life safety criticality. These systems dominate Belgian and Dutch post-war office retrofits where building managers seek incremental upgrade paths from compressed air infrastructure.
- Hydraulic:Fluid-power actuation persists in heavy industrial smoke exhaust applications where torque requirements exceed electric motor specifications. Foundry and smelting facilities in Northern Italy maintain installed bases.
- Pneumatic:Compressed air infrastructure resists full replacement in existing portfolios with sunk capital in distribution networks. Sunk cost psychology delays electromechanical conversion despite higher maintenance burdens.
- Thermal:Heat-activated damper and vent systems provide passive smoke control without electrical dependency. These occupy niche applications in heritage building renovations where wiring installation proves structurally invasive.
Electric technology holds the largest share; momentum sits with electro-mechanical hybrids.
Application:
Volume concentration tracks urban densification corridors, with super-tall construction driving engineered pressure differential procurement in Western European metropolitan clusters.
- Commercial Buildings:Office towers and mixed-use developments require stairwell pressurization, elevator lobby protection, and atrium smoke control. Paris and Frankfurt Class A assets bundle fire safety modernization with HVAC upgrades to satisfy lease penalty clauses and reputational risk management.
- Fire Safety Systems:Dedicated life safety infrastructure in high-occupancy venues demands validated pressure differential uptime. Institutional property owners purchase performance guarantees rather than capital assets, transferring operational risk to OEM service arms.
- Public Infrastructure:Transit hubs, hospitals, and government facilities specify redundant smoke control for continuity-of-operations requirements. EU Green Deal carbon neutrality mandates force fan motor redesigns for tighter energy budgets.
- Industrial Ventilation:Manufacturing and warehouse facilities deploy smoke exhaust and containment for property protection and business continuity. CSRD embodied carbon reporting pressures steel housing and aluminum impeller suppliers to secure renewable power certificates.
- Transportation Facilities:Airport terminals, rail stations, and tunnel systems require specialized smoke control for extended egress paths. Shanghai and Shenzhen prestige developments import European-certified designs under MIIT dual carbon alignment.
Commercial buildings hold the largest share; momentum sits with fire safety systems.
End User:
Customer type determines procurement modality, with facility managers driving outcome-based contracts and construction firms favoring equipment-plus-installation packages.
- Facility Managers:These operators prioritize building management system convergence and predictive maintenance subscriptions. Real-time airflow data integration into centralized energy optimization platforms drives specification of BACnet and Modbus protocols.
- Construction Firms:General contractors weight environmental product declarations at 15-20% of technical scoring for public sector procurements. German contractors bundle commissioning, digital monitoring, and maintenance into turnkey contracts.
- Factory Operators:Industrial end users emphasize equipment reliability and rapid service response for production continuity. Rare-earth magnet volatility in permanent magnet motors creates input cost exposure for high-efficiency fan drives.
- Transport Authorities:Public infrastructure owners mandate redundant systems and extended warranty coverage for critical transit assets. Procurement timelines extend due to multi-stakeholder approval processes.
- Emergency Response Teams:Fire departments and civil defense agencies influence code development and post-incident system evaluation. Their input shapes EN 12101 standard revisions and national adoption timelines.
Construction firms hold the largest share; momentum sits with facility managers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western European building codes mandate balanced pressure configurations for high-rise protection, while North American procurement favors positive pressure stairwell systems with simpler commissioning protocols. Asian infrastructure projects increasingly import European-certified designs under stricter carbon accountability frameworks.
Germany
Commercial developers in Frankfurt and Munich specify balanced pressure systems to protect both stairwells and elevator lobbies from centralized mechanical plants. The EU Green Deal's carbon neutrality mandates force fan motor redesigns for tighter energy budgets under EN 12101-6 protocols. The Ruhr Valley industrial corridor hosts component suppliers restructuring foundry energy contracts to secure renewable power certificates.
France
Paris Class A commercial towers bundle fire safety modernization with HVAC upgrades to satisfy lease penalty clauses and reputational risk management. Updated EN 12101 standards from the European Committee for Standardization require automatic pressure modulation in high-rise escape routes. Urban densification policies in Île-de-France concentrate super-tall residential permits where smoke control complexity demands engineered solutions.
United Kingdom
Facility managers in London specify electric actuator technology with embedded pressure transducers for self-tuning arrays that eliminate manual damper balancing. Building Regulations Approved Document B shapes smoke control specifications alongside BS 9999 guidance for fire safety engineering. The Midlands manufacturing belt supplies variable frequency drive technology with real-time fan speed modulation capabilities.
China
Prestige developments in Shanghai and Shenzhen import European-certified smoke control designs under MIIT dual carbon alignment mandates. GB standards and MIIT directives add compliance layers for manufacturers serving infrastructure projects under national carbon peak goals. The Yangtze River Delta corridor concentrates high-rise construction where smoke pressure system procurement is accelerating.
Netherlands
Post-war office buildings in Rotterdam and Amsterdam approaching structural renewal windows present bundled fire safety and HVAC modernization procurement opportunities. The CSRD embodied carbon reporting requirements force manufacturers to disclose full lifecycle emissions for steel housings and aluminum impellers. Dutch facility managers prioritize BACnet integration protocols that feed real-time airflow data into centralized energy optimization platforms.
Smoke Pressure System Market Key Industry Players
Capability concentration sits with specialized European engineering houses; scale advantage sits with diversified building technology conglomerates. The vendor base separates into three tiers: premium OEMs with full-lifecycle service arms, mid-market equipment fabricators, and regional installation specialists. Strategic moves center on service unbundling into predictive maintenance subscriptions and geographic expansion through certified installer networks rather than direct sales forces.
Within the premium engineering tier, TROX GmbH and Systemair AB exemplify European specialists anchoring market positions through specialized commissioning capabilities. Greenheck Fan Corporation represents the North American service-integrated model, leveraging continental maintenance networks to capture recurring revenue from installed infrastructure. These three entities occupy positions that illustrate the industry's bifurcation between project-driven equipment sales and outcome-based performance guarantees.
| Leading Market Players |
|---|
| Systemair AB |
| Greenheck Fan Corporation |
| FläktGroup |
| Johnson Controls |
| Colt International Ltd. |
| TROX GmbH |
| Siemens Building Technologies |
| Soler & Palau |
| Nuaire |
| Others |
Cost & Logistics Intelligence
Undercapacity in permanent magnet motor foundries across Northern Italy and the Ruhr Valley is compressing supplier margins while elevating pricing power for certified component vendors serving EN 12101-6 compliant projects. This utilization squeeze feeds directly into equipment procurement cycles, forcing OEMs to restructure contract terms and accelerate backward integration into rare-earth magnet sourcing.
Pricing Analysis
Long-term service contracts dominate procurement for Class A commercial towers, with facility managers purchasing guaranteed pressure differential uptime rather than capital assets. Three-tier pricing structure across premium, standard, and economy levels separates TROX GmbH and Systemair AB full-lifecycle offerings from mid-market fabricators and regional installation specialists. Cost compression in electro-mechanical hybrid systems is intensifying because Belgian and Dutch retrofit demand outpaces certified commissioning engineer supply. Construction firms exhibit highest price sensitivity due to lump-sum contract exposure, while facility managers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Contract manufacturing concentration sits with specialized foundries in Northern Italy and the Ruhr Valley for steel housings and aluminum impellers, while electric actuator assembly clusters in the Midlands manufacturing belt. Permanent magnet motors draw from Chinese neodymium processing, copper windings from Chilean concentrate, and precision-machined dampers from German metalworking networks. Single-source vulnerability in rare-earth magnet supply creates exposure to Chinese export quota volatility. Distribution runs through certified installer networks rather than direct sales forces, with TROX GmbH and Greenheck Fan Corporation leveraging continental service arms for aftermarket capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across product architecture and technology tiers creates entry niches as building electrification retrofits splinter demand between legacy pneumatic infrastructure and electric actuator upgrades. The shift from equipment sales to outcome-based performance guarantees rewards service-integrated vendors while pressuring pure-play fabricators.
For Market Incumbents: Pre-empt margin erosion in positive pressure systems by deepening backward integration into rare-earth magnet supply and acquiring certified commissioning networks in Belgium and the Netherlands. TROX GmbH and Systemair AB should lock in long-term foundry energy contracts with renewable power certificates before CSRD embodied carbon reporting tightens tender scoring. Electric actuator commoditization from Asian component suppliers represents the primary substitution threat requiring defensive patent positioning.
For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, where GB standards and MIIT dual carbon alignment create demand for European-certified designs without entrenched incumbent service networks. Hybrid pressure systems for complex geometries in Rotterdam-style super-tall developments offer technology differentiation leverage. Partner with BACnet integration specialists to bypass direct installer network buildout and embed into building management platform procurement channels.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among OEMs with captive commissioning and predictive maintenance arms serving Class A commercial towers with lease penalty exposure. Long-term viability favors vertically integrated specialists with foundry relationships and CSRD-ready environmental product declarations over equipment-only fabricators. Monitor commissioning engineer wage inflation and certification timeline friction as inflection signals for supplier consolidation pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Secures input cost stability against Chinese export quota volatility for permanent magnet motor production. |
| Certified Installer Network Expansion | Captures aftermarket revenue from EN 12101-6 mandated retrofits in aging Belgian and Dutch commercial stock. |
| CSRD-Ready Environmental Product Declaration Investment | Meets German public sector tender scoring weighting of 15-20% for lifecycle emissions disclosure. |
| BACnet Protocol Integration Development | Enables real-time airflow data feeds into centralized energy optimization platforms for facility manager specification. |
| Predictive Maintenance Subscription Launch | Transfers operational risk from capital asset sales to guaranteed pressure differential uptime contracts. |
Research Approach
Operator-level perspectives from facility managers, commissioning engineers, fire safety consultants, and general contractors anchored the qualitative base for this analysis. Primary fieldwork across Frankfurt, Paris, London, and Rotterdam construction corridors combined with secondary validation from EN 12101 standard documentation, EPA smoke control guidelines, and MIIT dual carbon policy circulars. Customs data on permanent magnet motor imports, foundry energy contract disclosures, and Class A commercial tower procurement records provided demand-side triangulation against supplier production capacity indicators. Bottom-up project pipeline assessment and top-down building stock modernization forecasts were reconciled through cross-reference.
Scenario-bracketing around EU Green Deal implementation pace and rare-earth magnet supply disruption probability framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product architecture, actuator technology tier, application vertical, and end-user procurement modality. CAGRs were derived from installed base growth, replacement cycle compression, and service revenue conversion trajectories. Fan motor efficiency standards under EN 12101-6 and NFPA 92 testing protocol divergence served as industry-specific forecast inputs shaping regional growth differentials.
Macroeconomic conditions sit as an overlay; deviation in construction lending rates, copper and neodymium price volatility, or EU carbon border adjustment implementation would shift the trajectory. Forecasts reflect documented assumptions on electrification retrofit pace and certification timeline standardization. Quarterly review of commissioning engineer labor availability, EN 12101 adoption timelines in member states, and Chinese rare-earth export quota announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Smart Smoke Alarm Market
Fire Safety & Protection
Fire Pump Market
Fire Safety & Protection
Australia Emergency Lighting Market
Fire Safety & Protection
Global Fire Suppression System Market
Fire Safety & Protection
Europe Fire-Resistant Glass Market
Fire Safety & Protection
Passive Fire Proofing System Market
Fire Safety & Protection
Global Smoke Evacuation Systems Market
Fire Safety & Protection
Cellulosic Fire Protection Market
Fire Safety & Protection
GCC Firefighting Foam Market
Fire Safety & Protection
Fire Extinguisher Market
Fire Safety & Protection
Portable Fire Extinguisher Market
Fire Safety & Protection
Global Fire Barrier Sealant Market
Fire Safety & Protection
Smoke Detector Market
Fire Safety & Protection
Global Portable Foam Fire Extinguisher Market
Fire Safety & Protection
Fire Door Market
Fire Safety & Protection
Civil Combustible Gas Alarm Market