
 Fire Suppression Agent Market | 2026-2036
Fire Suppression Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Suppression Agent Market Analytics
Recurring inspection and recharge subscription services is consolidating revenue streams for suppression system vendors, shifting capital expenditure into operational contracts. Honeywell International Inc. leverages its building automation portfolio to bundle agent monitoring with HVAC controls. Johnson Controls sustains long-term service agreements through its installed base of sprinkler and gaseous suppression hardware. Fike Corporation specializes in engineered systems for high-hazard industrial environments, anchoring its position in niche manufacturing verticals.
Fire suppression agents are formulated substances—spanning water-based solutions, chemical powders, foam concentrates, and inert gas blends—engineered to interrupt combustion through cooling, oxygen displacement, or chemical chain reaction inhibition, with critical specifications including discharge time, nozzle pressure, and clean-agent residue levels to protect sensitive electronics and occupied spaces. Inert gas systems dominate premium installations where equipment protection outweighs cost sensitivity, while dry chemical agents occupy the mass-market industrial segment driven by regulatory mandates for flammable liquid hazards. Water and foam applications retain volume leadership in warehousing and marine settings where environmental discharge restrictions remain less stringent.
The EPA's SNAP program, NFPA 2001 clean agent standards, and EU F-Gas Regulation collectively constrain halocarbon agent availability while accelerating approval pathways for low-global-warming-potential alternatives. These frameworks force manufacturers to reformulate portfolios and recertify systems, raising compliance costs but creating first-mover advantages for agents with pre-approved regulatory status. Stakeholders must monitor evolving green chemistry designations and building code adoptions to anticipate which agent families will retain market access.
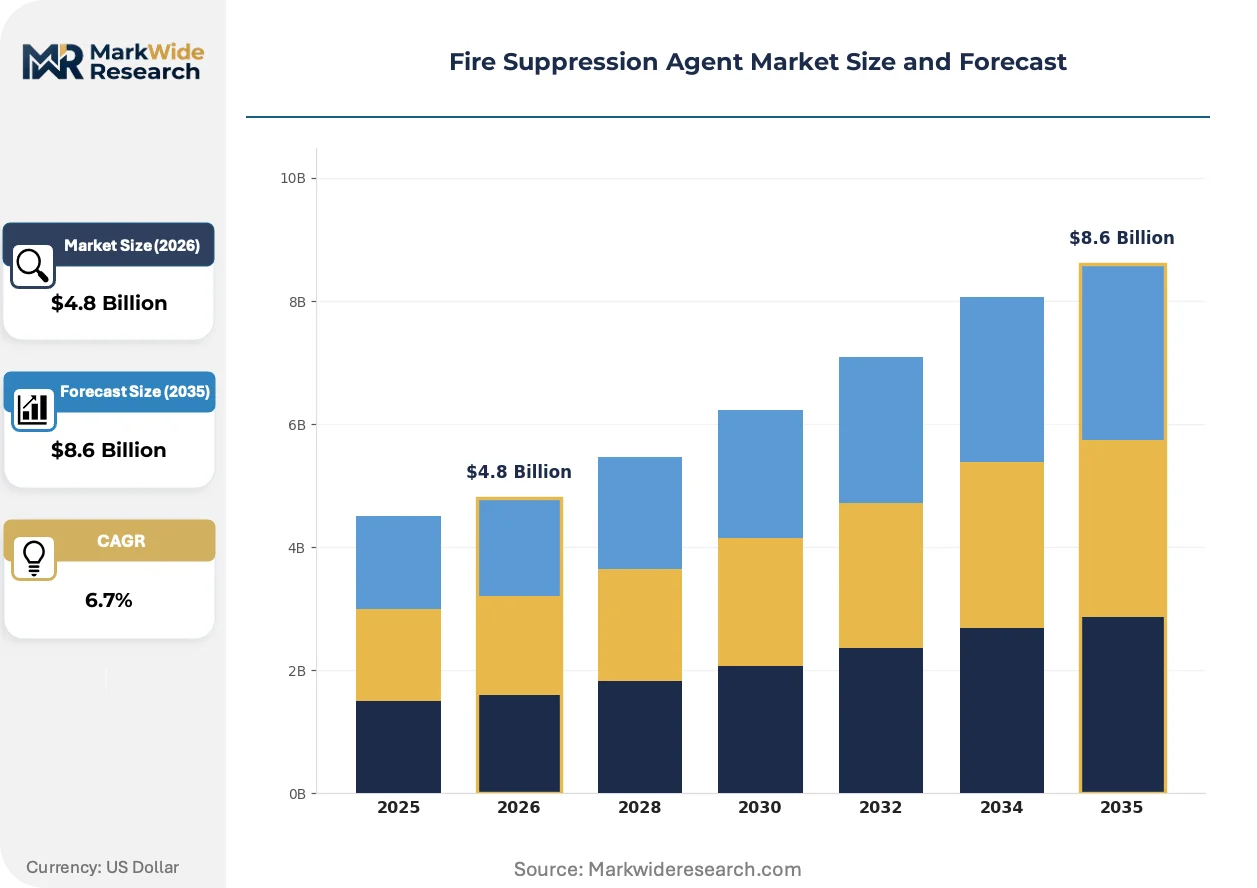
Market Dynamics
Server density escalation in hyperscale data centers is compressing discharge time requirements for clean agents, forcing reformulation of fluorinated ketone blends and inert gas blends to protect rack-level electronics without oxygen deprivation risks to technicians.
Growth Catalysts
- NFPA 2001 clean agent standards:The US National Fire Protection Association mandates are accelerating replacement of halon 1301 systems in critical infrastructure facilities. Banking, telecommunications, and defense sectors face compliance deadlines that sustain equipment upgrade cycles.
- Lithium-ion battery proliferation:Energy storage installations and electric vehicle manufacturing plants require specialized suppression agents capable of thermal runaway containment. This application category demands agents with rapid cooling properties and electrical non-conductivity.
- India:The country's Bureau of Indian Standards is implementing stricter industrial fire safety codes for petrochemical corridors and pharmaceutical manufacturing zones. Domestic production capacity for dry chemical agents is expanding to meet localized procurement requirements.
Market Restraints
- Heptafluoropropane supply concentration:Manufacturing of HFC-227ea, a dominant clean agent, concentrates among Chinese chemical producers. Geopolitical friction and export licensing delays create inventory volatility for system integrators in North America and Europe.
- EU F-Gas Regulation phase-down:The European Union's fluorinated gas restrictions are compressing availability of high-global-warming-potential halocarbons. Manufacturers face reformulation costs and recertification timelines that extend product development cycles.
- Inert gas cylinder weight:Physical density of nitrogen-argon blends requires reinforced storage infrastructure and elevated transportation costs. These constraints limit deployment in retrofit applications with load-bearing limitations.
Strategic Opportunities
- Fluorinated ketone agents:Novec 1230 and similar low-GWP alternatives are gaining pre-approval status under EPA SNAP and EU F-Gas frameworks. Early movers in agent production capture specification lock-in for data center and museum protection applications.
- Remote monitoring convergence:Integration of agent pressure sensors with building management systems enables predictive maintenance contracts. This technology pairing shifts revenue from equipment sales to recurring service subscriptions.
- Saudi Arabia:Giga-project construction and industrial city expansion under Vision 2030 are creating demand for engineered suppression systems. Local content requirements favor joint ventures between international agent suppliers and domestic distributors.
Industry Challenges
- Clean agent technician certification:Specialized training for fluorinated ketone and inert gas system installation is scarce outside major metropolitan markets. This talent gap extends deployment timelines and elevates labor costs for remote facility projects.
- Legacy halon bank depletion:Reclaimed halon 1301 supplies are diminishing faster than replacement system installations can compensate. Critical facilities face extended downtime risks if agent recharge sourcing fails during inspection cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Suppression Agent Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Agent Type: Water, Foam, Dry Chemical, Inert Gas Application: Industrial, Commercial, Residential, Marine Delivery Method: Portable Extinguishers, Sprinkler Systems, Standpipe Systems, Fixed Systems End User: Manufacturing, Warehousing, Aviation, Energy |
| Companies Covered | Johnson Controls, Honeywell International Inc., Siemens AG, Tyco Fire Products, Fike Corporation, Minimax, 3M, Amerex Corporation, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Suppression Agent Market Evolving Landscape
Agent formulation and system architecture are converging around environmental compliance requirements and digital infrastructure protection needs. Three developments are compressing competitive timelines and reshaping buyer specifications.
Fluorinated ketone blends with sub-1 global warming potential are unifying the previously separate objectives of environmental compliance and electronics protection. Hyperscale cloud operators in Northern Virginia and Frankfurt are specifying these agents for new construction to preempt regulatory phase-outs. This unification is compressing the market window for transitional HFC-based agents and accelerating capital deployment toward low-GWP production capacity.
EPA SNAP program amendments are expanding acceptable substitutes for halon 1301 while tightening restrictions on high-GWP hydrofluorocarbons. Industrial consequence includes forced portfolio rationalization among chemical manufacturers with stranded HFC-227ea capacity. Data center operators in the United States are responding by front-loading clean agent procurement to secure pre-approved formulations before supply constraints materialize.
Specification authority is migrating from facility managers to sustainability officers and risk engineering departments within large enterprises. Corporate net-zero commitments are displacing first-cost optimization as the primary agent selection criterion. This behavioral shift is most visible in European financial services and North American technology sectors where environmental disclosure requirements pressure supply chain transparency.
Fire Suppression Agent Market Segmentation
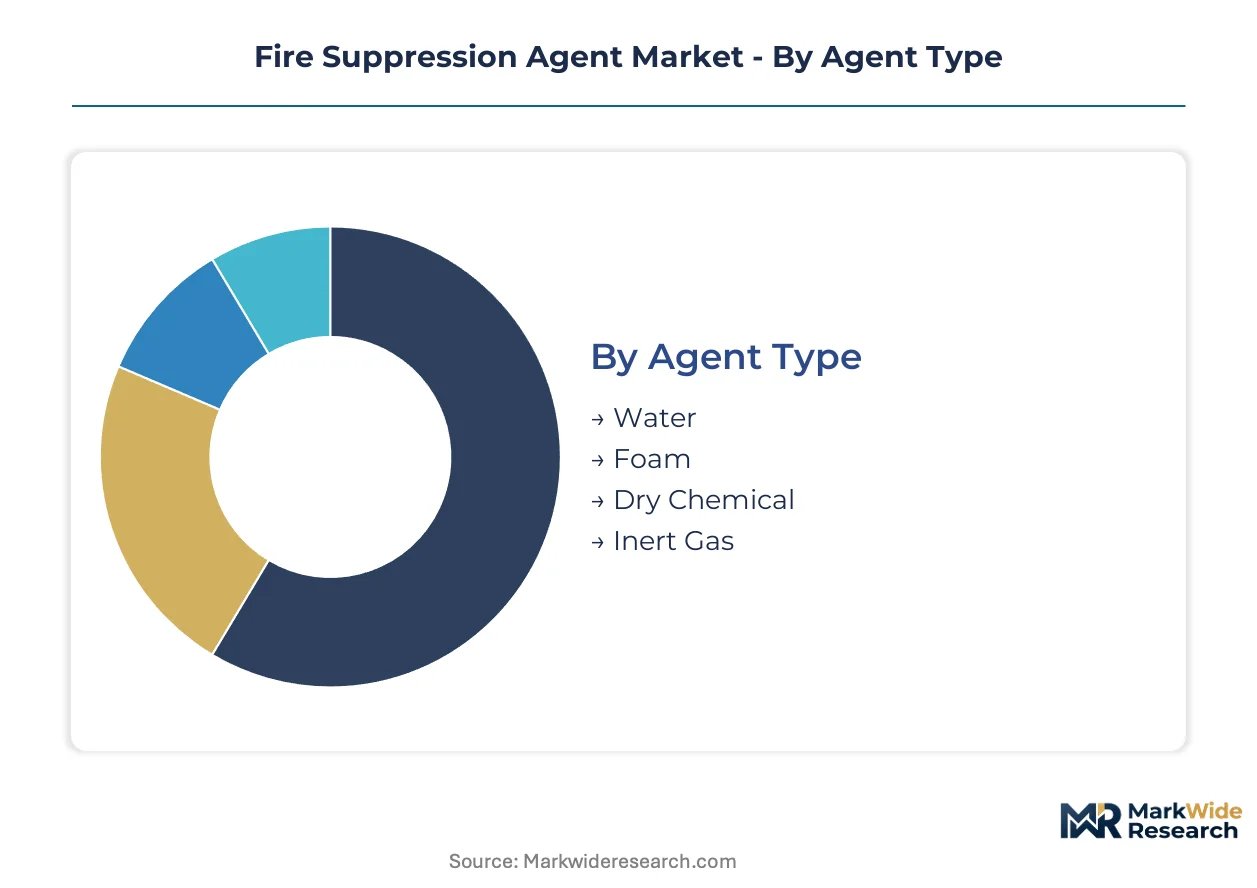
Fire suppression agents serve radically different hazard profiles across industrial, commercial, and infrastructure settings. Specification divergence between data center clean-agent requirements and heavy industrial dry chemical mandates forces manufacturers to maintain parallel formulation portfolios rather than unified product lines.
Agent Type:
Customization intensity spans from commodity water formulations to engineered fluorinated ketone blends requiring EPA SNAP pre-approval.
- Inert Gas:Nitrogen-argon blends and pure nitrogen systems displace oxygen below combustion thresholds without residue damage to electronics. Hyperscale data centers in Northern Virginia and Frankfurt specify these agents for server hall protection despite cylinder weight penalties that complicate retrofit installations.
- Dry Chemical:Sodium bicarbonate and mono-ammonium phosphate powders interrupt combustion through chemical chain reaction inhibition. Petrochemical corridors in India and Gulf industrial zones drive procurement volumes under Bureau of Indian Standards and Saudi Civil Defense mandates for flammable liquid hazard coverage.
- Water:Plain water and additive-enhanced solutions remain the default for warehousing and general occupancy protection where environmental discharge restrictions permit.
- Foam:Aqueous film-forming and protein-based concentrates seal flammable liquid surfaces against vapor release. Marine applications and aviation fueling facilities specify these formulations under ICAO and port authority regulations.
Leading the category by volume: Dry Chemical. Growing fastest: Inert Gas.
Application:
Regulatory stringency escalates from residential occupancy codes to industrial process safety mandates with catastrophic consequence thresholds.
- Industrial:Chemical processing, metalworking, and manufacturing facilities deploy specialized agents for Class B and Class D hazards. OSHA process safety management requirements and EPA risk management plan obligations force systematic suppression system redundancy in high-consequence operations.
- Commercial:Office complexes, retail centers, and hospitality venues balance occupant safety with business continuity priorities. NFPA 13 sprinkler mandates dominate specification authority, though clean-agent systems penetrate financial services and telecommunications critical infrastructure.
- Residential:Single-family and multi-family dwellings rely on smoke detection-linked water sprinklers and portable extinguisher placement under local building code adoption of NFPA 13R standards.
- Marine:Vessel engine rooms, cargo holds, and offshore platforms require agents rated for harsh environments and space-constrained installations under SOLAS conventions and flag state regulations.
Dominating procurement value: Industrial. Expanding most quickly: Commercial clean-agent retrofits.
Delivery Method:
Capital intensity separates self-contained portable units from engineered fixed systems requiring piping infrastructure and control panel integration.
- Fixed Systems:Pre-engineered and custom-designed installations deliver agent through dedicated piping networks to protected hazards. Data center white space, aviation hangars, and energy substations demand these systems for rapid discharge compliance with NFPA 2001 ten-second total flooding requirements.
- Sprinkler Systems:Wet pipe, dry pipe, pre-action, and deluge configurations constitute the default commercial and industrial protection architecture. Municipal water supply adequacy and freeze risk determine system selection across climate zones.
- Portable Extinguishers:Hand-held and wheeled units provide first-response capability for incipient stage fires. Regulatory inspection intervals and recharge service contracts generate recurring revenue streams for distributor networks.
- Standpipe Systems:Fire department connection points and interior hose stations support manual suppression in high-rise structures and large-footprint warehouses.
Commanding installed base: Sprinkler Systems. Climbing the fastest: Fixed gaseous systems.
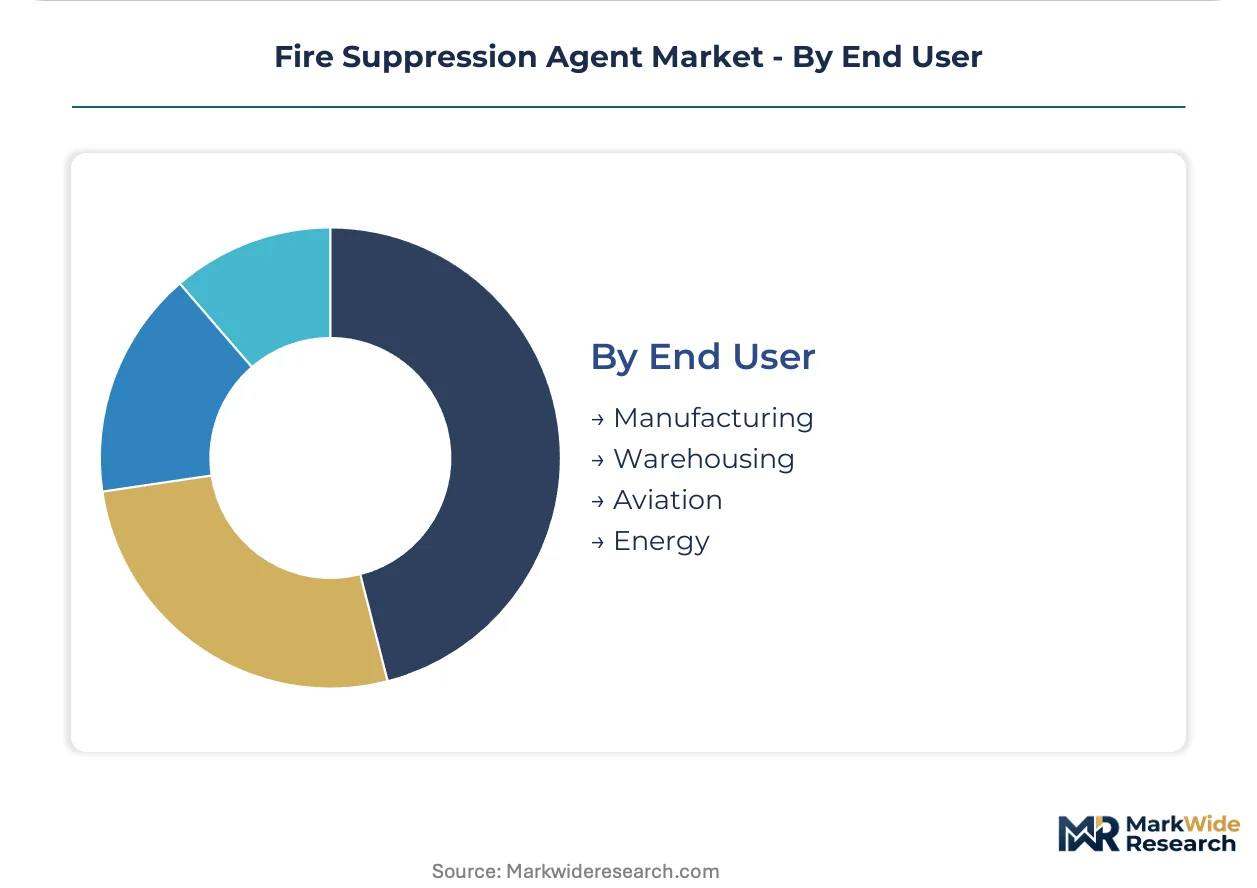
End User:
Operational criticality and asset value density determine agent specification tier and maintenance contract sophistication.
- Energy:Power generation, transmission, and battery storage facilities require agents with electrical non-conductivity and rapid cooling properties for transformer and lithium-ion containment. FERC reliability standards and utility internal risk engineering drive specification authority.
- Aviation:Aircraft hangars, fuel farms, and maintenance facilities demand agents meeting FAA and ICAO certification for flammable liquid and energized electrical hazards. Foam systems dominate fuel-related applications; clean agents protect avionics bays.
- Manufacturing:Discrete and process manufacturing operations span from light assembly with water sprinkler protection to heavy industry with specialized dry chemical and foam systems for combustible dust and flammable liquid hazards.
- Warehousing:High-piled storage configurations and automated retrieval systems create unique challenge fire profiles. Early suppression fast-response sprinklers and in-rack systems address commodity classification-driven design densities.
Gaining share fastest: Energy. Holding largest contract value: Aviation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agent production concentrates in Chinese chemical corridors while consumption tilts toward data center clusters in the United States, Germany, and India. This divergence forces logistics networks to bridge long supply chains for time-sensitive recharge services. Regional regulatory fragmentation compounds complexity as jurisdictions adopt divergent phase-out timelines for high-GWP formulations.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth drives clean-agent procurement volumes. EPA SNAP program amendments accelerate halon 1301 replacement deadlines across defense and telecommunications facilities. Banking sector risk engineering departments in New York and Chicago specify fluorinated ketone systems for trading floor protection.
Germany
Industrial manufacturing zones in North Rhine-Westphalia demand dry chemical systems for flammable liquid hazards under REACH compliance frameworks. EU F-Gas Regulation phase-down compresses availability of HFC-227ea for existing installations. Frankfurt's financial district leads European adoption of inert gas systems for server hall protection.
China
Heptafluoropropane manufacturing concentrates in Jiangsu and Zhejiang chemical parks, supplying global system integrators. Domestic demand escalates in Shenzhen and Hangzhou cloud computing facilities. GB standards implementation for lithium-ion battery storage creates specialized agent requirements for Guangdong energy projects.
India
Bureau of Indian Standards enforcement in Maharashtra and Gujarat petrochemical corridors sustains dry chemical procurement volumes. Pharmaceutical manufacturing clusters in Telangana and Karnataka adopt clean-agent systems for cleanroom protection. Domestic production capacity for sodium bicarbonate formulations expands to meet localized procurement mandates.
Saudi Arabia
Vision 2030 giga-projects in NEOM and the Red Sea coast create demand for engineered suppression systems in hospitality and industrial zones. Saudi Civil Defense mandates drive specification authority for flammable liquid protection. Joint ventures between international agent suppliers and domestic distributors satisfy local content requirements for Jubail industrial city expansions.
Fire Suppression Agent Market Competitive Landscape
Capital-heavy chemical producers compete with asset-light system integrators for margin capture across the value chain. The market structure consolidates around three tiers: multinational conglomerates with building automation portfolios, specialized engineered systems firms, and regional chemical manufacturers. Strategic archetypes include full-stack building technology providers, niche high-hazard specialists, and commodity agent bulk suppliers. Dominant competitive moves encompass vertical integration into service contracts and geographic expansion through local distributor partnerships.
Among diversified building technology conglomerates, Johnson Controls and Honeywell International Inc. exemplify the full-stack archetype by bundling agent monitoring with broader facility management platforms. Fike Corporation occupies a distinct position as a specialized engineered systems firm targeting high-consequence industrial environments. These three anchors illustrate how scale-driven diversification and niche technical depth represent alternative viable paths to sustained contract value.
| Leading Market Players |
|---|
| Johnson Controls |
| Honeywell International Inc. |
| Siemens AG |
| Tyco Fire Products |
| Fike Corporation |
| Minimax |
| 3M |
| Amerex Corporation |
| DuPont |
| Others |
Value Network & Pricing Analysis
Hyperscale data center operators in Northern Virginia and Frankfurt anchor contract pricing through multi-year procurement agreements that lock in fluorinated ketone volumes before EPA SNAP and EU F-Gas restrictions tighten supply. Their concentration of purchasing power forces tiered pricing structures that separate certified clean-agent formulations from commodity dry chemical alternatives.
Pricing Analysis
Cost-down pressure on engineered clean-agent systems accelerates because EPA SNAP pre-approval timelines extend development cycles and concentrate supply among certified producers. Three-tier pricing structure across premium inert gas installations, mid-tier fluorinated ketone systems, and economy dry chemical configurations reflects certification grade and after-sales service bundling. Price differentiation hinges on UL/FM certification status and geographic delivery cost from Chinese chemical manufacturing zones. Industrial facility managers in India and Saudi Arabia exhibit highest price sensitivity due to localized procurement mandates, while data center sustainability officers prioritize environmental compliance over first-cost optimization.
Supply Chain Analysis
Specialized chemical engineering talent scarcity in Jiangsu and Zhejiang province manufacturing corridors constrains heptafluoropropane production expansion despite climbing global demand. Supply concentrates in Chinese chemical parks for HFC-227ea and fluorinated ketone feedstocks, with secondary production nodes in Germany and the United States for inert gas blending operations. Raw material dependencies span specialty fluorochemical precursors, high-pressure cylinder alloys, and precision valve components. Single-source vulnerability from Chinese export licensing delays creates inventory volatility for North American system integrators. Distribution runs through authorized distributor networks that maintain recharge service infrastructure for time-sensitive inspection cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
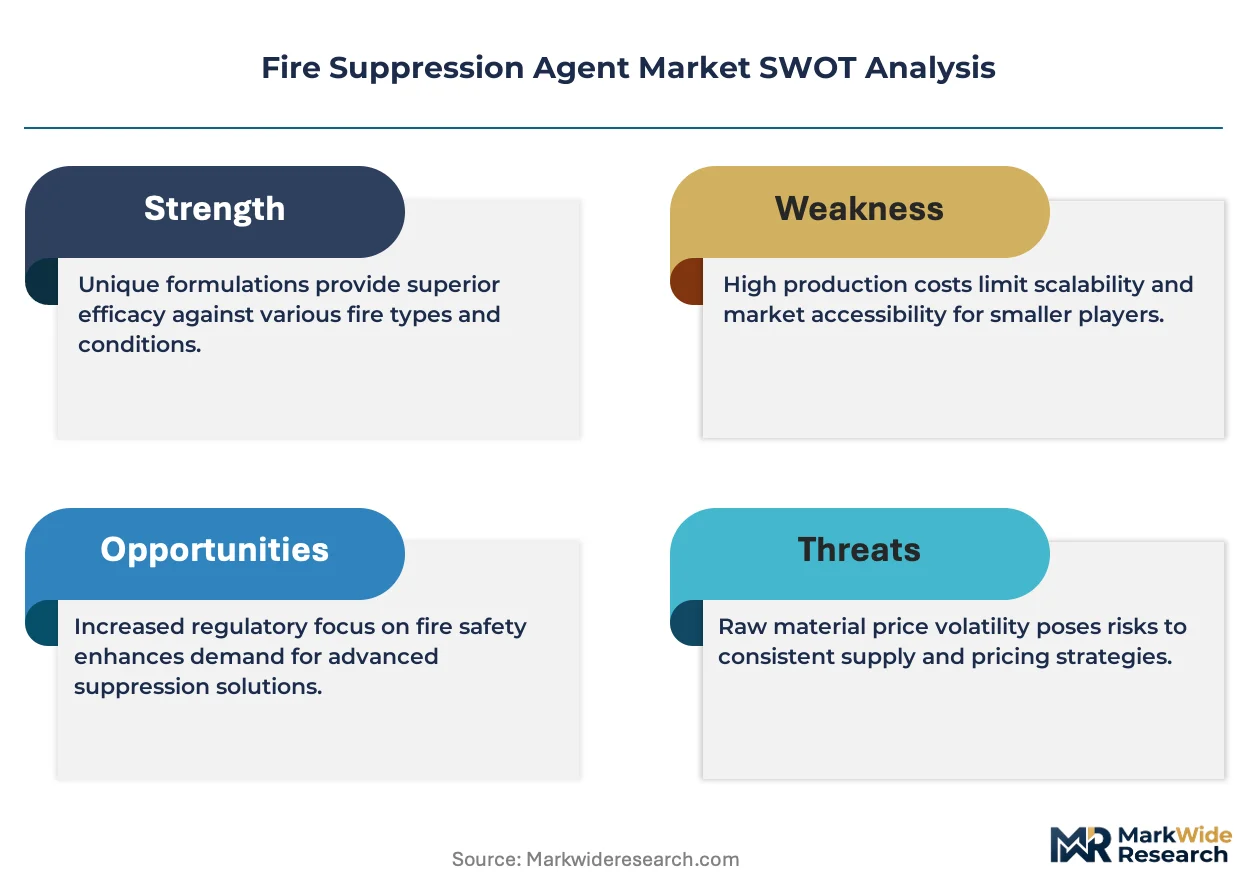
Fluorinated ketone manufacturing capacity bottlenecks prop pricing premiums for EPA SNAP-pre-approved formulations, creating margin protection for incumbent producers with certified production lines.
For Market Incumbents: Anchor market position through backward integration into specialty fluorochemical precursor production and captive cylinder refurbishment networks. Incumbents must defend against emerging low-GWP agent substitutes by accelerating EPA SNAP submission timelines for next-generation formulations. Capacity addition in domestic blending facilities reduces tariff exposure from concentrated Chinese chemical imports. For New Entrants and Emerging Players: Regional distributor partnerships in Saudi Arabia and India offer the most penetrable channel structure for agent supply and recharge service contracts. New entrants should target lithium-ion battery storage installations where thermal runaway containment specifications remain unsettled and incumbent certification lock-in is weakest. A specialized engineering services go-to-market angle bypasses capital-intensive chemical manufacturing barriers. For Investors and Strategic Acquirers: The window for entry favors vertically integrated building technology conglomerates with existing HVAC and controls portfolios that can absorb agent monitoring capabilities. Long-term viability rests on recurring inspection and recharge subscription revenue streams rather than transactional equipment sales. The signal to watch is EPA SNAP amendment velocity for halocarbon phase-out timelines that would strand HFC-227ea production capacity.| Strategic Initiative | Industry Significance |
|---|---|
| EPA SNAP Pre-Approval Investment | First-mover certification for low-GWP fluorinated ketones locks in data center specifications before competitors complete submissions. |
| Backward Integration into Precursor Chemicals | Captive supply of specialty fluorochemical feedstocks insulates margins from Chinese export volatility and tariff exposure. |
| Recharge Service Network Expansion | Localized cylinder maintenance infrastructure converts transactional equipment sales into recurring operational contracts with utility and banking clients. |
| Joint Venture with Saudi Distributors | Local content partnerships satisfy Saudi Civil Defense mandates for Vision 2030 giga-project fire suppression procurement. |
| Lithium-Ion Battery Agent Development | Thermal runaway containment formulations address fastest-growing energy storage hazard profile with limited incumbent certification lock-in. |
Research Methodology
Independent corroboration across fire suppression system integrators, chemical manufacturing plant managers, and data center facility directors underwrites the qualitative findings in this analysis. Primary interviews with EPA regulatory affairs specialists, NFPA code committee members, and Saudi Civil Defense procurement officers combined with secondary validation from SEC 10-K filings, customs trade data, and EPA SNAP submission databases. Bottom-up agent volume modeling and top-down facility construction spend triangulation anchored market sizing across the projection horizon.
Comparable-period anchoring to historical halon 1301 replacement cycles and HFC phase-out transitions structured the forecast window methodology. Segmentation dimensions modeled span agent type, delivery method, application severity class, and regional regulatory cluster. CAGRs were derived through growth driver elasticity analysis against facility construction permits and energy infrastructure investment flows. Forecast inputs incorporated hyperscaler data center capex disclosures and Bureau of Indian Standards enforcement timelines for petrochemical corridor mandates.
Several conditions sit outside the modeled scope, including unannounced EPA SNAP amendments, geopolitical disruption of Chinese chemical exports, and breakthrough solid-state battery technologies that could eliminate lithium-ion thermal runaway risks. Forecasts reflect documented assumptions about regulatory phase-out velocity and facility construction continuation. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Marine Fire Extinguishing System Market
Fire Safety & Protection
Automatic Fire Ball Extinguisher Market
Fire Safety & Protection
Australia Emergency Lighting Market
Fire Safety & Protection
Smoke and Carbon Monoxide Alarm Market
Fire Safety & Protection
Fire Alarm Systems Market
Fire Safety & Protection
Fire Protection Coating Market
Fire Safety & Protection
Automatic Fire Suppression System (AFSS) Market
Fire Safety & Protection
Global Portable Foam Fire Extinguisher Market
Fire Safety & Protection
Laser Smoke Detector Market
Fire Safety & Protection
UAE Fire Protection System Market
Fire Safety & Protection
Wireless Fire Detection Systems Market
Fire Safety & Protection
Global Fixed Firefighting Misting System Market
Fire Safety & Protection
Fire Pump Market
Fire Safety & Protection
Deflagration Flame Arresters Market
Fire Safety & Protection
Fire Safety Equipment Market
Fire Safety & Protection
North America Fire Protection Water Storage Tanks Market