
 E-Bike Rental Market | 2026-2036
E-Bike Rental Market Size, Share, and Industry Trends Forecast 2026-2036
E-Bike Rental Market Insights
Urban commuters are redrawing demand patterns away from sporadic tourists toward daily subscription users. Lime leverages its battery-swapping network to sustain high fleet utilization rates across dense metropolitan zones. Tier anchors its competitive position through vertical integration into in-house vehicle design and maintenance operations. Donkey Republic differentiates by targeting smaller European cities with flexible dockless systems that escape congestion from larger operators.
E-bike rental denotes the short-term commercial provision of electrically assisted bicycles featuring integrated hub motors, lithium-ion battery packs, and GPS-enabled locking mechanisms for per-use or subscription-based mobility. Hourly rentals still occupy the largest revenue pool among service types, though monthly subscriptions are accelerating fastest as habitual commuters replace transit passes. Tourists remain the most profitable customer type per trip, while commuters deliver superior lifetime value through recurring revenue and lower seasonal volatility.
EU Green Deal emission targets and national low-emission zone expansions in Germany, France, and the Netherlands directly shape fleet procurement standards and operating permits. GDPR compliance for mobile app data collection and CE marking for electrical safety create dual compliance thresholds that filter out undercapitalized entrants. Stakeholders must monitor how evolving battery recycling mandates under the EU Battery Regulation alter total cost of ownership calculations and partnership strategies with cell suppliers.
Market Dynamics
Battery-swapping infrastructure investments are compressing fleet downtime and enabling higher asset utilization rates across metropolitan rental networks, while EU Green Deal decarbonization mandates accelerate procurement of electrified fleets over pedal-only bicycles.
Growth Catalysts
- EU Green Deal emission mandates:National low-emission zone expansions in Germany, France, and the Netherlands directly favor rental e-bike deployment over private vehicle ownership in urban cores.
- Lithium-ion cell chemistry advances:Energy density improvements are extending per-charge range, reducing swap frequency requirements and expanding serviceable catchment areas for fleet operators.
- Cycling lane infrastructure:Dedicated path construction in Copenhagen and Amsterdam is eliminating safety barriers that previously constrained commuter adoption of two-wheeled micro-mobility.
Market Restraints
- Cell supply concentration:Lithium-ion battery production clusters in East Asia create import dependency and currency exposure for European fleet procurement budgets.
- GDPR compliance friction:Mobile app data collection requirements for GPS tracking and user authentication impose dual legal thresholds with CE electrical safety marking.
- Seasonal demand compression:Northern European winter weather patterns reduce utilization rates by forcing fleet hibernation or costly indoor storage transitions.
Strategic Opportunities
- Smaller city penetration:Secondary municipalities in Belgium and Denmark lack incumbent dockless operators, creating whitespace for flexible deployment models.
- Monthly subscription conversion:Habitual commuters are replacing transit passes with recurring rental plans, shifting revenue from transactional to predictable.
- Battery recycling partnerships:EU Battery Regulation mandates are creating incentive alignment between fleet operators and cell suppliers for closed-loop material recovery.
Industry Challenges
- Maintenance technician scarcity:Hub motor diagnostics and lithium pack refurbishment require specialized skills absent from traditional bicycle mechanic training pipelines.
- Fleet management software integration:Real-time availability apps must synchronize with legacy municipal transit payment systems, creating API compatibility friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Bike Rental Market |
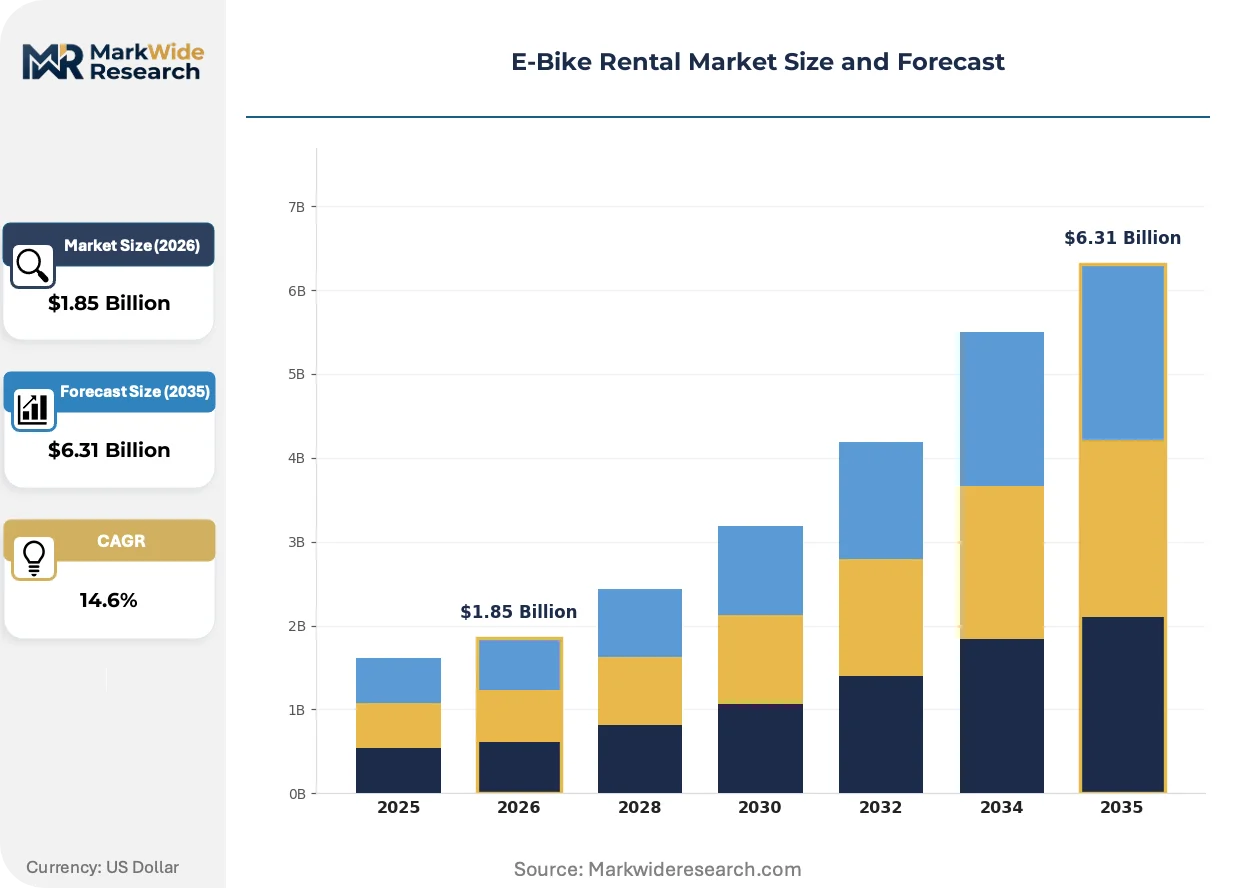
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $6.31 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Hourly Rentals, Daily Rentals, Monthly Subscriptions, Corporate Packages Customer Type: Tourists, Commuters, Students, Business Travelers Distribution Channel: Mobile Apps, Kiosks, Rental Shops, Online Portals End User: Urban Riders, Eco-Conscious Consumers, Recreational Users, Fitness Enthusiasts |
| Companies Covered | Lime, Bird, Jump, Tier, Spin, Voi, Dott, Citi Bike, Donkey Republic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Bike Rental Market Trends and Innovations
Modular hardware architectures and subscription-based commercial models are displacing asset-heavy ownership structures, while regulatory pressure on urban emissions accelerates electrification timelines across municipal procurement.
Swappable battery pack systems are decomposing the traditional fixed-charge e-bike architecture. Fleet operators in Amsterdam and Berlin are adopting hot-swap protocols that eliminate three-to-four-hour charging windows. This compression of downtime is decomposing the asset-turn economics that previously constrained fleet scale.
The EU Battery Regulation is mandating recycled content thresholds and end-of-life producer responsibility for lithium-ion cells. Fleet operators must now document chain-of-custody for cell materials from procurement through disposal. German rental networks are responding by pre-negotiating buyback agreements with Asian cell suppliers before fleet deployment.
Corporate mobility budgets are absorbing individual commuter subscriptions as taxable benefits-in-kind. Human resources departments in Paris and Frankfurt are displacing traditional transit pass allocations with pooled e-bike rental allowances. This channel shift concentrates purchasing power among fleet operators capable of enterprise-grade invoicing and consolidated reporting.
E-Bike Rental Market Segmentation
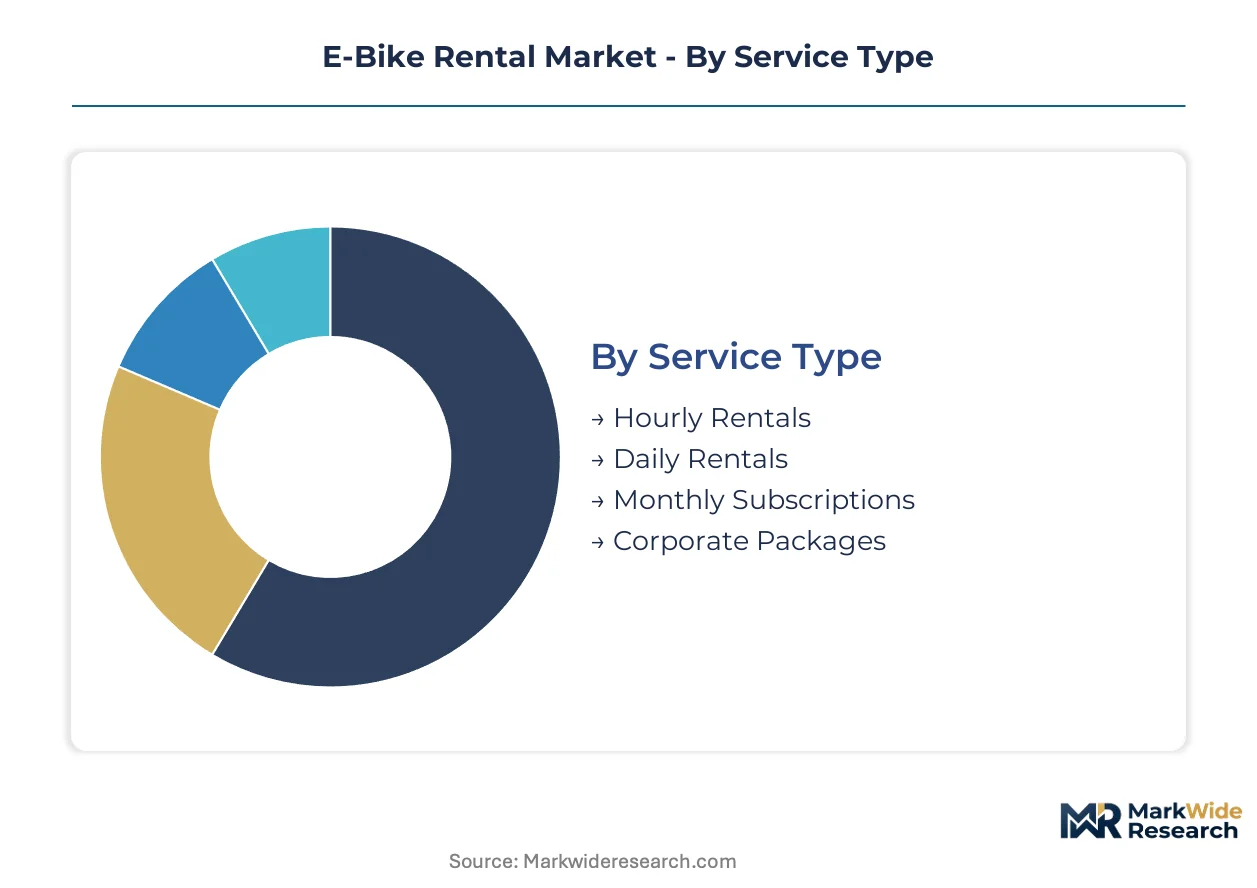
E-bike rental operators calibrate fleet allocation and pricing architecture around distinct usage patterns and channel preferences. Segmentation precision determines whether capital deploys toward high-turnover tourist hubs or recurring commuter corridors.
Service Type:
Hourly rentals flow predominantly through mobile apps and street-side kiosks in dense metropolitan cores, while monthly subscriptions anchor direct-to-consumer digital channels with embedded payment automation.
- Hourly Rentals:Per-use access with GPS-enabled unlock and dockless return flexibility. Demand concentrates in Amsterdam, Berlin, and Copenhagen city centers where tourists and occasional riders favor spontaneity over commitment. Peak utilization aligns with summer tourism windows and weekend leisure patterns.
- Monthly Subscriptions:Unlimited-ride plans with automatic renewal and corporate billing integration. Commuters in Paris, Frankfurt, and Rotterdam are displacing transit passes with these recurring arrangements, delivering predictable revenue streams and lower seasonal volatility.
- Daily Rentals:24-hour access blocks suited to weekend tourists and business travelers with extended stays.
- Corporate Packages:Pooled allowances for employer mobility budgets, typically invoiced through enterprise procurement systems.
By volume, Hourly Rentals leads. By growth pace, Monthly Subscriptions is climbing the fastest.
Customer Type:
Margin profiles diverge sharply between transient tourists delivering high per-trip yields and commuters generating superior lifetime value through habitual usage.
- Tourists:Visitors seeking short-term mobility without luggage constraints or parking burdens. Riders in Barcelona, Rome, and Vienna generate peak revenue per trip during summer months, though acquisition costs rise with seasonal advertising spend.
- Commuters:Daily travelers replacing car ownership or public transit with subscription-based access. Professionals in low-emission zones of London, Brussels, and Stockholm sustain utilization through winter months when tourist demand collapses.
- Students:Price-sensitive users concentrated near university clusters in Leuven, Utrecht, and Lund.
- Business Travelers:Expense-account riders prioritizing convenience over cost, typically sourced through hotel partnerships and airport proximity.
By revenue contribution, Tourists dominates. By retention economics, Commuters is expanding most quickly.
Distribution Channel:
Channel selection shapes customer acquisition cost and fleet utilization velocity, with mobile-first operators capturing habitual users while physical touchpoints serve walk-up demand.
- Mobile Apps:Smartphone-based booking, unlock, and payment with real-time availability mapping. Operators in Berlin, Amsterdam, and Paris capture 80%-plus of transactions through this channel, embedding loyalty programs and subscription management.
- Kiosks:Self-service terminals at transit hubs and tourist corridors enabling card-based rental without smartphone dependency. Stations at Copenhagen Central and Vienna Westbahnhof serve travelers with limited data connectivity or privacy concerns.
- Rental Shops:Staffed locations offering test rides, maintenance services, and tourist orientation.
- Online Portals:Web-based reservation systems for advance booking and corporate account management.
By transaction volume, Mobile Apps leads. By margin stability, Kiosks is gaining share fastest.
End User:
User archetypes determine vehicle specification, with urban riders demanding ruggedized hardware and eco-conscious consumers prioritizing carbon footprint transparency.
- Urban Riders:Core metropolitan users navigating congestion and parking scarcity. Riders in Amsterdam, Copenhagen, and Utrecht favor step-through frames, integrated locks, and basket configurations for multi-modal trips combining cycling with train access.
- Eco-Conscious Consumers:Sustainability-motivated users selecting operators with verified carbon offsets and renewable energy charging. Demand clusters in Freiburg, Graz, and Bordeaux where municipal procurement mandates favor certified green fleets.
- Recreational Users:Weekend leisure riders seeking scenic routes and extended range for suburban exploration.
- Fitness Enthusiasts:Performance-oriented users preferring pedal-assist over throttle control for exercise integration.
By fleet allocation, Urban Riders leads. By engagement intensity, Eco-Conscious Consumers is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese battery cell manufacturers supply European fleet operators through Rotterdam and Hamburg port corridors, creating import-dependent procurement chains for lithium-ion packs that power Amsterdam and Copenhagen rental networks.
Germany
Corporate mobility budgets in Frankfurt and Berlin are absorbing individual commuter subscriptions as taxable benefits-in-kind. The KBA enforces type-approval standards for e-bike motor systems and battery safety certification. Fleet operators in North Rhine-Westphalia are pre-negotiating cell buyback agreements with Asian suppliers ahead of EU Battery Regulation compliance deadlines.
Netherlands
Cycling lane expansion in Amsterdam and Utrecht eliminates safety barriers that previously constrained commuter adoption of two-wheeled micro-mobility. Municipal low-emission zones in Rotterdam and The Hague directly favor rental e-bike deployment over private vehicle ownership in urban cores. The Randstad cluster anchors battery-swapping infrastructure investments that compress fleet downtime across dense metropolitan networks.
France
Human resources departments in Paris are displacing traditional transit pass allocations with pooled e-bike rental allowances. ANSM and CNIL impose dual compliance thresholds for CE electrical safety marking and GDPR mobile app data collection. Operators in Île-de-France are capturing habitual users through smartphone-based booking with embedded loyalty programs and subscription management.
Denmark
Step-through frame configurations with integrated locks and basket systems dominate Copenhagen and Aarhus demand for multi-modal trips combining cycling with train access. National cycling infrastructure investment programs eliminate weather-related utilization volatility through covered path construction. Secondary municipalities in Jutland lack incumbent dockless operators, creating whitespace for flexible deployment models.
United Kingdom
Professionals in London's low-emission zones sustain utilization through winter months when tourist demand collapses. The Department for Transport coordinates with local authorities on rental operator licensing frameworks and public highway access permits. Fleet managers in Greater London are synchronizing real-time availability apps with legacy municipal transit payment systems, creating API compatibility friction.
E-Bike Rental Market Competitive Landscape
Player mix skews toward vertically integrated specialists with captive vehicle design capabilities and asset-light platform operators relying on third-party hardware procurement. Market structure concentrates around three archetypes: micro-mobility platforms with battery-swapping networks, in-house vehicle designers with maintenance operations, and flexible dockless specialists targeting secondary municipalities. Dominant competitive moves include backward integration into upstream cell supply partnerships and geographic whitespace penetration in underserved Belgian and Danish cities.
Among platform-based operators with swapping infrastructure, Lime and Tier exemplify divergent strategic positioning within the integrated specialist archetype. Lime anchors the battery-swapping network approach across dense metropolitan zones, while Tier occupies a position emphasizing in-house vehicle design and maintenance operations. Donkey Republic sits within the flexible dockless tier, representing the secondary-city penetration model that escapes congestion from larger operators.
| Leading Market Players |
|---|
| Lime |
| Bird |
| Jump |
| Tier |
| Spin |
| Voi |
| Dott |
| Citi Bike |
| Donkey Republic |
| Others |
Pricing and Supply Chain Analysis
Ninety-day lead times for lithium-ion cell procurement compress pricing flexibility for European fleet operators negotiating annual procurement cycles against Asian suppliers. This inventory pressure concentrates cost control leverage with battery pack integrators who maintain buffer stock in Rotterdam and Hamburg port zones, while rental networks pass through hardware cost volatility via subscription tier adjustments.
Pricing Analysis
Hub-motor generation gaps separate current-generation 250W drive systems from prior-generation 180W units and next-generation 500W performance tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by battery capacity grade and CE certification tier rather than brand alone. Pricing pressure stems from cell chemistry cost compression in NMC and LFP variants as Chinese suppliers expand European distribution. Commuter subscription segments exhibit lowest price sensitivity due to employer reimbursement structures, while student and tourist segments demand economy-tier access.
Supply Chain Analysis
Inventory velocity in battery-swapping networks runs through 48-hour rotation cycles that mask underlying cell supply concentration. Lithium-ion production clusters in China, South Korea, and Japan feed European assembly operations through Hamburg and Rotterdam corridors. Cell chemistry inputs draw from cobalt concentrates in the DRC, lithium brine from Chile, and nickel laterite from Indonesia. Single-source vulnerability concentrates in cathode active material processing. Distribution runs through third-party logistics providers with cold-chain requirements for cell transport.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mobility-as-a-service platform economics in European e-bike rental markets hinge on API interoperability with municipal transit payment systems, creating winner-take-most dynamics for operators achieving technical integration first.
For Market Incumbents: Shield fleet utilization rates by locking exclusive battery-swapping concessions with municipal transport authorities in Amsterdam, Berlin, and Paris. Deepen upstream control over cell refurbishment capabilities to offset EU Battery Regulation compliance costs. Defend against dockless specialists by accelerating deployment in secondary Danish and Belgian cities before whitespace closes.
For New Entrants and Emerging Players: CE marking fast-track through notified body pre-submission in Germany and France opens regulatory pathways ahead of incumbent compliance cycles. Target corporate mobility budget channels in Frankfurt and London where enterprise procurement systems lack integrated rental operators. Pursue white-label fleet management software partnerships with hotel chains and business travel platforms.
For Investors and Strategic Acquirers: Carve-out targets emerge from automotive OEM mobility subsidiaries seeking to divest non-core micro-mobility assets. Long-term viability in this sector rests on subscription revenue retention above transactional tourist yield. Monitor battery recycling partnership announcements as inflection signals for operational cost structure sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Swapping Network Expansion | Rotterdam and Amsterdam deployments compress fleet downtime below four-hour charging windows. |
| Corporate Subscription Channel Development | Paris and Frankfurt HR departments displace transit passes with pooled e-bike allowances. |
| EU Battery Regulation Compliance Partnership | German operators pre-negotiate Asian cell supplier buyback agreements ahead of mandates. |
| Secondary City Geographic Expansion | Jutland and Belgian municipalities lack incumbent dockless operators, creating whitespace. |
| Municipal Transit API Integration | London fleet managers synchronize availability apps with legacy payment systems. |
Research Methodology
Initial hypotheses were tested against primary input from fleet operations directors, municipal transport authority planners, battery procurement managers, and corporate mobility benefit administrators and refined through secondary validation. Fleet operator financial disclosures, EU transport infrastructure investment databases, customs import records for lithium-ion cells, and municipal procurement contract registries anchored bottom-up demand estimation against top-down market sizing.
Variance decomposition across service type, customer archetype, distribution channel, and geographic regulatory cluster shaped analytical framework construction throughout the modeling period. CAGRs derived from segmented growth rate blending weighted by revenue contribution share. Forecast inputs incorporated cycling lane infrastructure completion schedules and low-emission zone expansion timelines without year-specific anchoring.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement and cell supply chain stability; material deviation in battery chemistry cost curves or regulatory compliance timelines would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Bike Sharing Market
Smart Transportation Solutions
Vertical Mobility Market
Smart Transportation Solutions
Global Intelligent Traffic Management System Market
Smart Transportation Solutions
Middle East and Africa Passenger Information System Market
Smart Transportation Solutions
Parking Finder Apps Market
Smart Transportation Solutions
Road Weather Information Systems (RWIS) Market
Smart Transportation Solutions
New Energy Vehicle Sweeper Market
Smart Transportation Solutions
Rail Internet of Things (IoT) Market
Smart Transportation Solutions
Global IoT Fleet Management Market
Smart Transportation Solutions
Fleet Health Monitoring and Diagnostic Analytics Systems Market
Smart Transportation Solutions
North America Traffic Signal Recognition Market
Smart Transportation Solutions
Smart Chassis Market
Smart Transportation Solutions
North America Fleet Management Solutions Market
Smart Transportation Solutions
Shared Mobility Market
Smart Transportation Solutions
Car Sharing Market
Smart Transportation Solutions
Smart Fleet Management Market