
 E-Bike Motor Market | 2026-2036
E-Bike Motor Market Size, Share, and Industry Trends Forecast 2026-2036
E-Bike Motor Market Foresight
EU Green Deal transport decarbonization rules are consolidating the cost-of-entry calculus for e-bike motor suppliers, forcing smaller assemblers to absorb compliance overhead or exit. Bosch eBike Systems leverages its Stuttgart engineering base to sustain premium mid-drive output across European OEM channels. Shimano anchors Asian supply relationships through its Osaka manufacturing footprint and bicycle component distribution legacy. Bafang Electric competes on hub motor volume, dominating price-sensitive fleet procurement in Chinese and Southeast Asian markets.
An e-bike motor is an electric propulsion unit, typically rated between 250W and 1000W, that converts battery-stored electrical energy into rotational torque to assist or replace human pedaling; mid-drive variants position the motor at the crankset to exploit gear ratios for hill-climbing efficiency, while hub motors embed directly within wheel assemblies for simpler drivetrain integration. The motor type dimension shows mid-drive architectures capturing margin pools in premium European trekking and cargo applications where torque sensing and low center-of-gravity design command pricing power, whereas hub motors retain volume leadership in Asian commuter markets where cost minimization and maintenance simplicity outweigh performance optimization. Battery technology segmentation reveals lithium-ion chemistry as the incumbent standard, with lithium-polymer variants gaining traction in ultralight road e-bikes where energy density per kilogram determines frame design constraints.
F-Gas Regulation compliance in Europe shapes refrigerant choices in motor thermal management systems, while REACH chemical restrictions constrain magnet coatings and stator insulation materials. Japan's METI enacts efficiency labeling standards that filter import eligibility for motor systems bound for domestic OEM assembly. China's GB standards and dual carbon goals enforce domestic motor efficiency floors that ripple through export pricing. Stakeholders must monitor how fragmented national subsidy regimes for e-bike purchases reshape regional demand spikes and inventory positioning without assuming synchronized policy calendars.
Market Dynamics
The EU Green Deal's transport decarbonization mandates are consolidating supplier tiers by forcing compliance investments in motor efficiency testing and battery recyclability certification that smaller assemblers cannot amortize across thin volume bases.
Growth Catalysts
- Urban Logistics Electrification:Last-mile delivery fleets across Rotterdam, Berlin, and Copenhagen are replacing combustion vans with cargo e-bikes, pulling 250W-750W mid-drive procurement.
- REACH Chemical Compliance:Magnet coating and stator insulation reforms are filtering out low-cost competitors unable to certify rare-earth supply chains for European OEM channels.
- Lithium-Polymer Density Gains:Frame-integrated battery packs are enabling ultralight road e-bike architectures that expand the addressable cyclist base beyond utility commuters.
Market Restraints
- Neodymium Price Volatility:Rare-earth magnet input costs swing with Chinese export quota announcements, compressing margin predictability for hub motor assemblers.
- Stuttgart-Osaka Supply Concentration:Premium mid-drive engineering and manufacturing cluster in two metropolitan zones, creating single-source vulnerability for European trekking OEMs.
- F-Gas Thermal Management Constraints:Refrigerant choices in liquid-cooled motor systems face phase-down timelines that extend R&D cycles for high-torque cargo applications.
Strategic Opportunities
- Southeast Asian Fleet Conversion:Jakarta and Bangkok municipal logistics operators are piloting hub motor cargo bikes where two-wheel infrastructure outpaces four-wheel electrification.
- ISO 13849 Functional Safety Certification:Machinery directive compliance for torque cutoff systems opens premium retrofit markets among German trekking bike owners.
- Direct-to-Fleet Digital Channels:Telematics-integrated motor diagnostics are enabling subscription-based maintenance contracts that bypass traditional distributor markups.
Industry Challenges
- Embedded Software Talent Scarcity:Field-oriented motor control algorithm development competes with automotive and robotics sectors for firmware engineers in the Netherlands and Germany.
- Dual Certification Timelines:Simultaneous KBA type approval for German road use and CE machinery compliance extends product launch windows by eight to fourteen months.
- Legacy Drivetrain Integration Complexity:Mid-drive torque pulses stress traditional bicycle chain and sprocket designs, forcing co-development agreements with component suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Bike Motor Market |
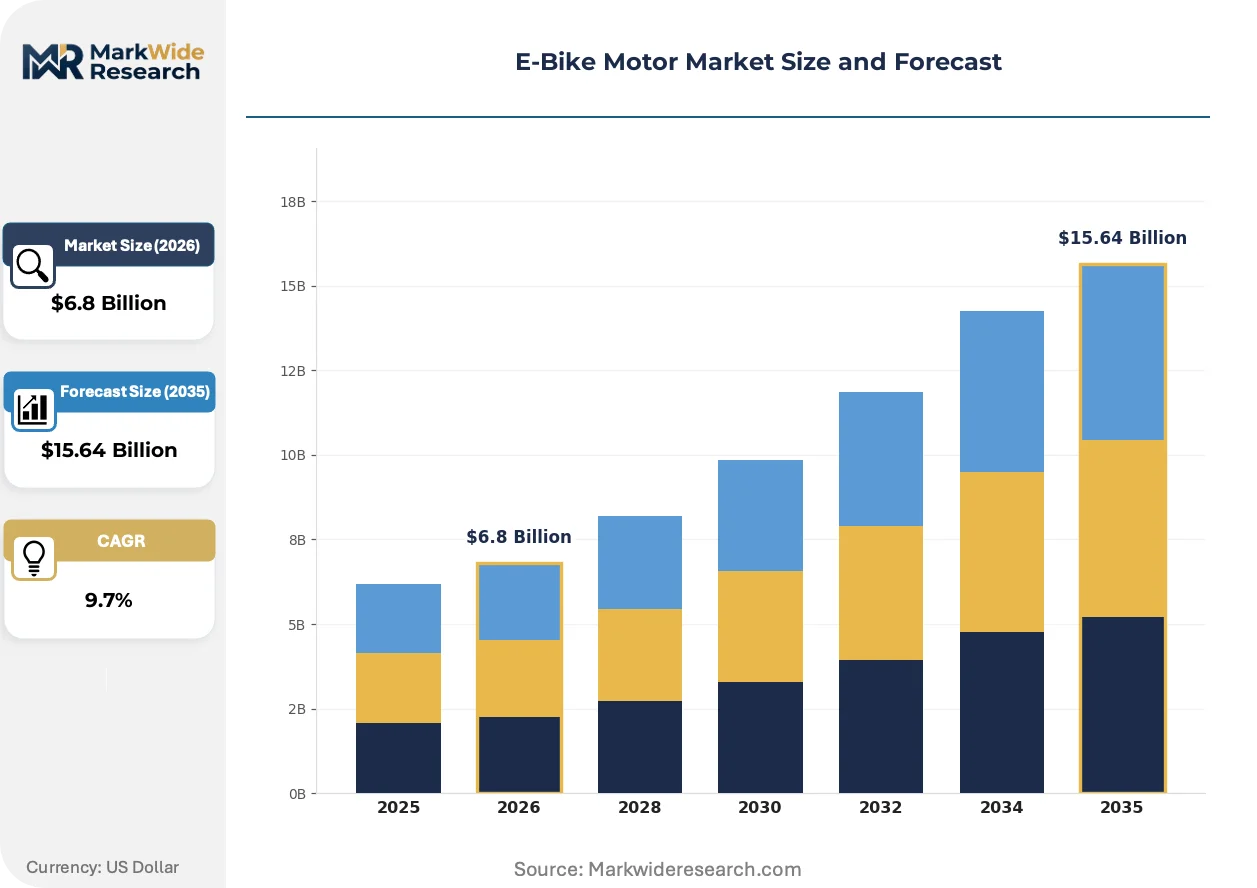
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.64 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Motor Type: Hub Motor, Mid Drive Motor, Integrated Motor, Direct Drive Motor Battery Technology: Lithium-ion, Lead-acid, Nickel-metal Hydride, Lithium-polymer Power Rating: 250W, 500W, 750W, 1000W End User: Commuters, Delivery Services, Outdoor Enthusiasts, Recreational Users |
| Companies Covered | Bosch eBike Systems, Shimano, Bafang Electric, Yamaha Motor, Brose, ZF Micro Mobility, Polini, Golden Motor Technology, DJI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Bike Motor Market Shifts & Advancements
Torque-sensing algorithms and thermal management architectures are absorbing the bulk of competitive R&D investment as motor suppliers differentiate beyond wattage ratings. Three concurrent developments are compressing product refresh cycles.
Silicon-carbide power electronics are absorbing switching losses that previously limited mid-drive motor efficiency at high cadence. Cargo fleet operators in Belgium and the Netherlands are specifying SiC-based inverters for stop-start urban routes. The technology is absorbing thermal margin that earlier designs dedicated to liquid cooling hardware, enabling lighter motor housings.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in liquid-cooled motor thermal management systems. Manufacturers are reformulating dielectric coolants and redesigning cold plates to maintain heat rejection capacity. High-torque cargo motor segments face the steepest redesign curves as power density requirements clash with refrigerant constraints.
Outcome-based service contracts are displacing unit sales in European fleet procurement. Operators in Berlin and Copenhagen are paying per-kilometer fees that bundle motor hardware, battery refresh, and predictive maintenance. The model concentrates vendor selection on uptime guarantees rather than upfront capital cost, favoring suppliers with captive service networks.
E-Bike Motor Market Segmentation
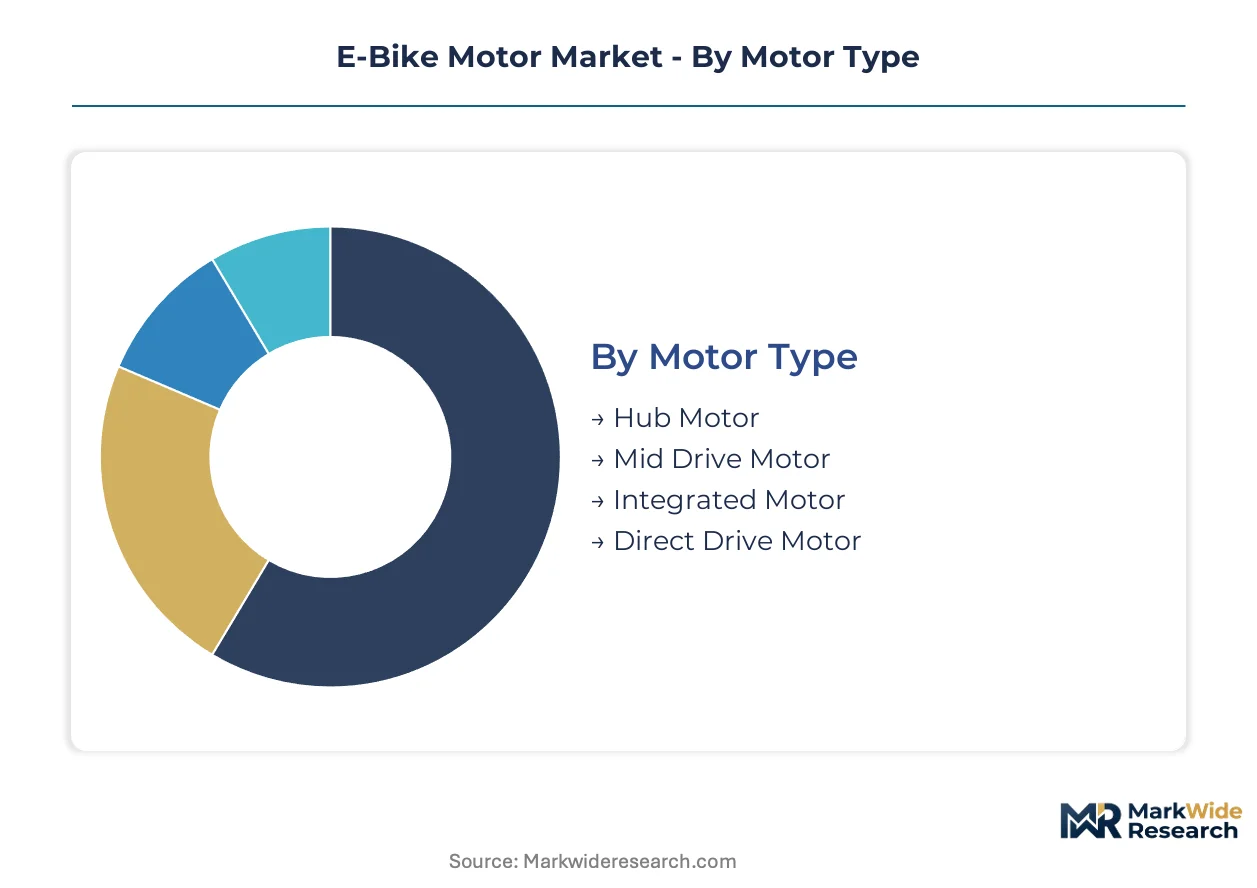
E-bike motor segmentation reveals divergent margin structures across propulsion architectures and power classes. Procurement patterns in fleet versus consumer channels reshape supplier priorities across every dimension.
Motor Type:
Hub motors dominate unit volume while mid-drive systems command premium positioning in torque-sensitive applications.
- Hub Motor:Encapsulated stator and rotor assemblies mount directly within wheel hubs, eliminating chain-driven power transmission. Fleet operators in Jakarta and Bangkok specify these for cargo bikes where maintenance simplicity outweighs hill-climb efficiency. Cost minimization drives procurement in Asian commuter markets.
- Mid Drive Motor:Crankset-mounted units exploit bicycle gearing ratios to multiply torque output for gradient climbing. European trekking OEMs in Germany and the Netherlands specify these for premium cargo and touring applications where low center-of-gravity design commands pricing power. Torque sensing and thermal management differentiate competitive offerings.
- Integrated Motor:Frame-embedded architectures merge motor housing with bottom bracket structures for aesthetic streamlining. Frame manufacturers in Italy and Portugal co-develop these with motor suppliers for urban commuter lines.
- Direct Drive Motor:Gearless hub configurations eliminate internal reduction mechanisms for silent operation and regenerative braking capability. Flat-terrain fleet operators in Denmark specify these for high-mileage routes.
Mature deployment sits with Hub Motor. Newer deployment is concentrated in Mid Drive Motor.
Battery Technology:
Chemistry selection determines energy density trade-offs that cascade through frame design and range specifications.
- Lithium-ion:Lithium cobalt oxide and lithium iron phosphate cells deliver the incumbent energy density standard across mass-market e-bikes. Cell suppliers in South Korea and China dominate cathode material sourcing for European OEM assembly.
- Lithium-polymer:Pouch-cell architectures enable irregular form factors that integrate with aerodynamic frame tubes. Ultralight road e-bike manufacturers in Switzerland and Italy specify these where gram reduction determines competitive positioning.
- Lead-acid:Flooded and sealed lead-acid configurations persist in price-sensitive fleet retrofits where battery replacement cost dominates total cost of ownership calculations.
- Nickel-metal Hydride:Rare-earth hydride cathodes offer intermediate density with reduced thermal runaway risk. Niche applications in cold-climate municipal fleets in Norway retain this chemistry for operational reliability.
Established chemistry deployment sits with Lithium-ion. Emerging chemistry deployment is concentrated in Lithium-polymer.
Power Rating:
Wattage thresholds align with regulatory classifications that determine road legality and insurance requirements across jurisdictions.
- 250W:The EU pedelec limit enables unlicensed operation on bicycle infrastructure. Urban commuters in Berlin and Amsterdam represent core demand for this threshold.
- 500W:Speed pedelec classifications in Switzerland and selected US states permit this output with helmet and registration requirements. Suburban range extension drives adoption.
- 750W:US Class 3 e-bike specifications and European cargo bike exemptions enable this rating for commercial delivery applications. Fleet operators in Copenhagen specify these for loaded urban routes.
- 1000W:Off-road and private-property applications dominate this segment where motor vehicle regulations do not constrain output. Mountain bike parks in Austria and Colorado represent concentrated demand.
Regulatory-compliant deployment sits with 250W. Performance-oriented deployment is expanding most quickly in 750W.
End User:
Customer type determines service model requirements and purchasing channel preferences that reshape supplier go-to-market structures.
- Delivery Services:Last-mile logistics operators in Rotterdam and Berlin procure mid-drive cargo configurations with telematics integration for fleet management. Subscription-based maintenance contracts displace unit sales in this channel.
- Commuters:Daily urban transport users prioritize reliability and theft deterrence over performance specifications. Hub motor simplicity dominates this segment across Asian and European cities.
- Outdoor Enthusiasts:Trekking and touring cyclists in the Alpine region demand torque multiplication for loaded gradient climbing. Mid-drive systems with extended-range batteries command premium positioning.
- Recreational Users:Weekend and leisure cyclists exhibit price sensitivity and lower utilization intensity. Entry-level hub motor configurations serve this segment through mass retail channels.
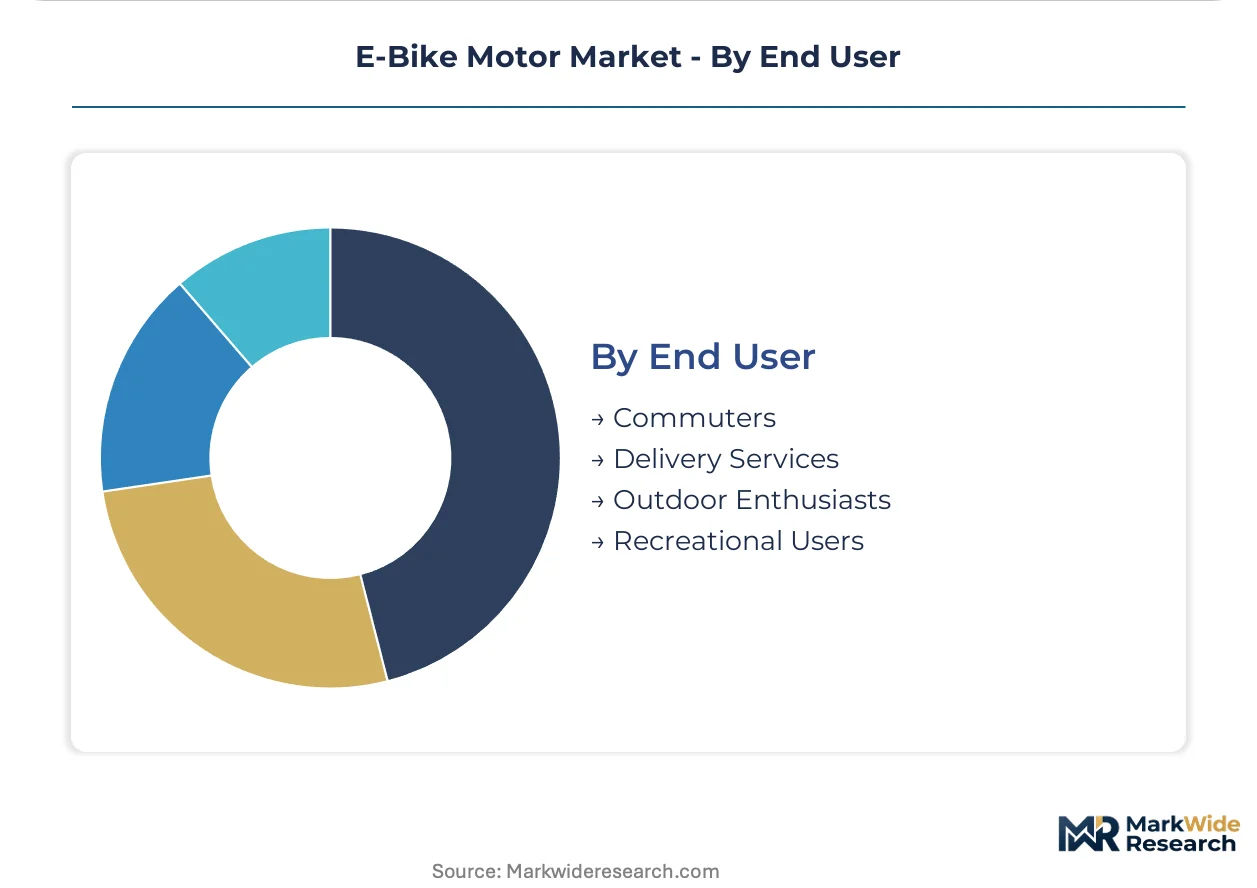
Volume deployment sits with Commuters. Service-contract deployment is concentrated in Delivery Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized industrial zones in Stuttgart, Osaka, and Shenzhen concentrate e-bike motor engineering and assembly, channeling investment into precision manufacturing clusters that feed continental supply chains.
Germany
Cargo fleet operators in Berlin and Hamburg are scaling mid-drive procurement for last-mile delivery electrification. The KBA enforces type approval standards that filter motor systems for road legality. Stuttgart anchors premium engineering clusters where torque-sensing R&D absorbs the bulk of competitive investment.
Netherlands
Rotterdam and Amsterdam logistics operators are replacing diesel vans with 750W cargo e-bikes for urban freight. EU Green Deal transport decarbonization mandates tighten efficiency thresholds for motor imports. Eindhoven manufacturing corridors concentrate assembly lines serving Benelux trekking OEMs.
China
Domestic commuter demand and Southeast Asian export orders sustain hub motor volume leadership. GB standards and dual carbon goals enforce efficiency floors that ripple through export pricing. Shenzhen and Zhengzhou production basins integrate rare-earth magnet supply with motor winding operations.
Japan
Osaka-based component suppliers leverage bicycle drivetrain heritage to anchor Asian OEM relationships. METI efficiency labeling standards filter import eligibility for domestic assembly channels. Nagoya engineering clusters focus on torque control algorithms and thermal management architectures.
United States
Class 3 e-bike adoption in Colorado and California mountain bike markets pulls 750W-1000W motor demand. State-level rebate programs in New York and Oregon reshape regional demand spikes without synchronized policy calendars. Denver and Portland fleet pilots are testing subscription-based maintenance models for commercial operators.
E-Bike Motor Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered positioning bands. The supplier base concentrates around three strategic archetypes: precision engineering houses with automotive heritage, bicycle component specialists leveraging distribution legacy, and volume-scale fabricators serving price-sensitive fleet channels. Consolidation pressure is accelerating as compliance investments in REACH certification and battery recyclability filter out smaller assemblers. Geographic expansion and captive service network buildout represent the dominant competitive moves as vendors chase outcome-based fleet contracts.
Within the precision engineering tier, Bosch eBike Systems and Brose occupy positions anchored by Stuttgart-based manufacturing and automotive supply chain heritage. Shimano exemplifies the component specialist archetype, drawing on Osaka production footprints and bicycle drivetrain distribution relationships. Bafang Electric sits within the volume-scale segment, representing hub motor specialists serving Asian commuter markets and Southeast Asian fleet conversion pilots.
| Leading Market Players |
|---|
| Bosch eBike Systems |
| Shimano |
| Bafang Electric |
| Yamaha Motor |
| Brose |
| ZF Micro Mobility |
| Polini |
| Golden Motor Technology |
| DJI |
| Others |
Supply & Pricing Matrix
Fleet procurement consolidation across Rotterdam, Berlin, and Copenhagen is mandating ISO 13849 certification and predictive maintenance bundling, forcing suppliers to absorb upfront compliance costs and recalibrate pricing across premium mid-drive and volume hub motor tiers.
Pricing Analysis
Lead-time premiums dominate contract negotiations, with European OEMs paying 15-20 percent markups for sub-eight-week delivery of REACH-certified mid-drive systems versus standard twelve-week cycles. Three-tier pricing structure across premium, standard, and economy levels separates Stuttgart-engineered torque-sensing units from Benelux-assembled mid-tier alternatives and Shenzhen-origin hub motors. Pricing pressure stems from neodymium magnet cost volatility and dual certification timelines extending product launch windows. Delivery services fleets exhibit lowest price sensitivity due to uptime guarantee requirements, while Asian commuter markets prioritize unit cost minimization above performance specifications.
Supply Chain Analysis
Dual-sourcing mandates from German and Dutch fleet operators require qualified backup suppliers for rare-earth magnet feedstock and silicon-carbide inverter components, complicating procurement for hub motor assemblers dependent on single-source relationships. Manufacturing concentrates in China, Germany, and Japan, with Shenzhen integrating magnet supply with winding operations, Stuttgart anchoring precision mid-drive engineering, and Osaka feeding component distribution networks. Raw material dependencies center on neodymium-iron-boron magnets, copper windings, and lithium-ion cathode materials. Single-source vulnerability runs through Chinese rare-earth export quota administration. Distribution runs through OEM direct channels for premium tiers and distributor networks for aftermarket replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
E-bike motor competition is becoming a vertical-integration race, with captive magnet processing and telematics-embedded service networks emerging as the decisive levers separating consolidators from exiting assemblers.
For Market Incumbents: Deploy captive rare-earth magnet processing to insulate margin structures from Chinese export quota volatility. Consolidate service network density in Benelux and German urban corridors to capture outcome-based fleet contracts. Counter emerging hub motor specialists from Southeast Asia by accelerating REACH certification timelines that smaller competitors cannot amortize. For New Entrants and Emerging Players: Direct-to-fleet digital channels offer the most penetrable route for bypassing incumbent distributor markups in European cargo bike procurement. Target Jakarta and Bangkok municipal logistics pilots where two-wheel infrastructure outpaces four-wheel electrification. Pursue white-label hub motor supply agreements with Indonesian and Vietnamese fleet operators before mid-drive incumbents establish local assembly footprints. For Investors and Strategic Acquirers: The window for entry favors component specialists with bicycle drivetrain heritage and existing Asian OEM relationships over pure-play motor fabricators. Long-term viability hinges on software-defined torque control and thermal management IP rather than winding capacity alone. Watch for inflection when subscription-based maintenance contracts exceed forty percent of European fleet procurement volume.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Processing | Captive neodymium supply insulates margin structures from Chinese export quota volatility. |
| ISO 13849 Functional Safety Certification | Machinery directive compliance opens premium retrofit markets among German trekking bike owners. |
| Telematics-Integrated Predictive Maintenance | Outcome-based contracts displace unit sales in Rotterdam and Copenhagen fleet procurement. |
| Southeast Asian Assembly Footprint Expansion | Local production captures Jakarta and Bangkok municipal logistics conversion pilots. |
| Silicon-Carbide Inverter Technology Adoption | SiC power electronics enable lighter motor housings for stop-start Belgian and Dutch urban routes. |
Research Methodology
Document review covered EU Green Deal transport decarbonization mandates, REACH chemical compliance filings, and METI efficiency labeling standards, complemented by interviews with motor system procurement directors at European cargo fleet operators, drivetrain engineers at Stuttgart and Osaka manufacturing clusters, and rare-earth magnet sourcing specialists at Shenzhen trading houses. Secondary validation drew from KBA type approval databases, ECHA substance restriction notifications, and customs trade flow records. Bottom-up motor shipment data triangulated against top-down OEM assembly forecasts.
Unit volume and value projections across the analysis window reflect segment-level modeling of motor type, battery chemistry, power rating, and end-user channel dimensions. CAGRs were derived from regression analysis of historical procurement patterns against regulatory phase-in timelines and fleet electrification adoption curves. Forecast inputs incorporated neodymium price elasticity coefficients and dual certification timeline distributions.
The model holds under stable EU F-Gas Regulation phase-down schedules and consistent Chinese rare-earth export administration; deviation in magnet quota announcements or REACH substance restriction expansions would shift supplier tier consolidation velocity. A model refresh is warranted upon material change in European fleet subscription contract penetration rates or Southeast Asian infrastructure investment commitments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Automotive Traction Motor Market
Electric Motor
Global Automotive Motor Market
Electric Motor
Electric Motor Sales Market
Electric Motor
Electric AC Motors Market
Electric Motor
Motor Gear Unit Market
Electric Motor
Global Automotive Starter Motor Market
Electric Motor
US Solar E-Bike Market
Electric Motor
High Speed Motor Market
Electric Motor
Automotive Power Steering Motor Market
Electric Motor
Global Vehicle Starter Motor Market
Electric Motor
Global in-Wheel Motors Market
Electric Motor
Intelligent Motor Control Market
Electric Motor
Hub Drive Motor Market
Electric Motor
Large Synchronous Motor Market
Electric Motor
United States AC Motor Market
Electric Motor
Automotive Torque Actuator Motor Market