
 Bike Rental Market | 2026-2036
Bike Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Bike Rental Market Analysis
ISO 4210 bicycle safety certification is reorganizing competitive entry barriers for fleet operators seeking municipal procurement contracts. Donkey Republic leverages its open-source software stack to anchor shared mobility partnerships across Nordic cities. Nextbike sustains geographic dominance through direct operational control of docking infrastructure in German-speaking markets. JCDecaux competes via its street furniture concessions that bundle advertising rights with bike station placement.
Bike rental denotes the short-term commercial provision of bicycles through time-bound access agreements, encompassing mechanical units with aluminum or carbon fiber frames and electric variants integrating lithium-ion battery systems rated between 250W and 750W motor output, serving urban mobility substitution and tourism circulation needs. Electric bike deployment captures expanding margin pools as battery costs decline and fleet operators prioritize higher-yield per-trip revenue from commuter subscriptions over tourist hourly rentals. Monthly rental structures for local residents are maturing into predictable recurring revenue bases while hourly and daily formats remain exposed to seasonal tourism volatility.
The EU Green Deal mobility targets and ECHA battery substance restrictions are tightening fleet procurement specifications across member states, compelling operators to document lifecycle carbon footprints and cobalt-free cathode chemistry. Germany's KBA type-approval framework for pedelecs above 25 km/h and France's ANSM oversight of public space deployment permits create dual compliance layers for cross-border operators. Stakeholders must monitor how municipal concession renewals integrate climate performance clauses into minimum service obligations.
Market Dynamics
Dockless electric bike fleets are restructuring competitive economics by eliminating fixed infrastructure costs and enabling rapid geographic repositioning based on real-time demand signals.
Growth Catalysts
- EU Green Deal mobility targets:Municipal procurement contracts now mandate lifecycle carbon documentation, favoring operators with battery recycling partnerships and renewable energy charging networks.
- Lithium-ion battery cost curves:Cell prices below $100 per kWh make 500Wh commuter-rated pedelecs economically viable for subscription-based fleet deployment at scale.
- Urban congestion pricing zones:London, Stockholm, and Milan's cordon charges are pushing last-mile commuters toward micro-mobility alternatives exempt from daily fees.
Market Restraints
- Cobalt supply concentration:DRC-sourced cathode materials expose fleet operators to ECHA due diligence requirements and forced labor disclosure mandates under EU battery regulations.
- Municipal concession fragmentation:City-specific operating permits prevent standardized service tiers across metropolitan clusters, inflating compliance overhead.
- Pedelec speed classification divergence:Germany's KBA 25 km/h threshold conflicts with France's 32 km/h S-pedelec category, complicating cross-border fleet standardization.
Strategic Opportunities
- Employer-sponsored mobility benefits:Dutch and Danish payroll tax exemptions for company bike subscriptions create B2B channel expansion potential.
- Intermodal transit integration:Deutsche Bahn and SNCF are opening station-adjacent parking APIs for seamless train-to-bike connectivity.
- Second-life battery storage:Retired fleet cells are repurposing into grid stabilization assets, unlocking circular revenue streams under EU circular economy action plan incentives.
Industry Challenges
- ISO 4210 certification timelines:Third-party frame testing delays of 8-12 weeks are constraining fleet refresh cycles during peak procurement windows.
- Right-of-way vandalism rates:Copenhagen and Amsterdam report 15-20% annual unit loss from theft and damage, compressing asset depreciation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bike Rental Market |
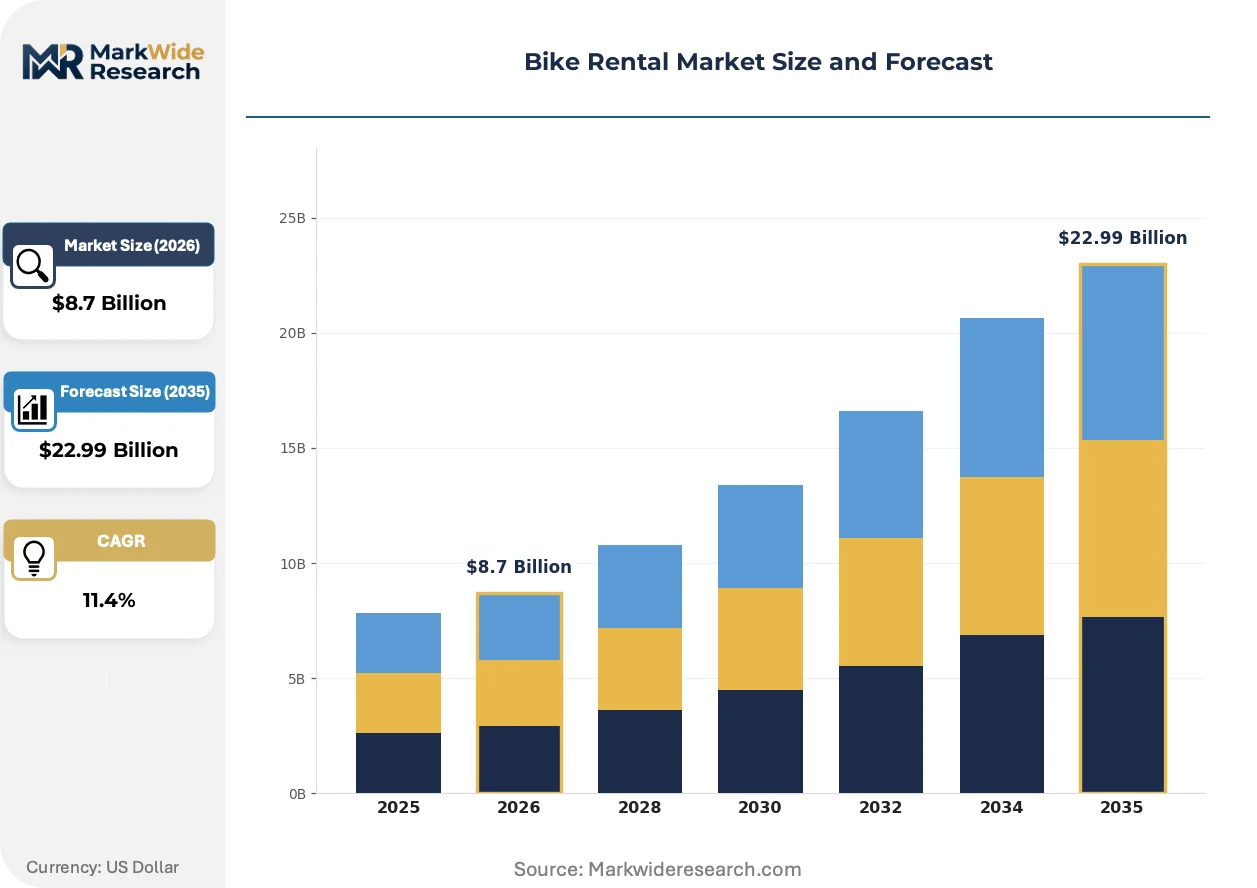
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Hourly Rental, Daily Rental, Weekly Rental, Monthly Rental Customer Type: Tourists, Commuters, Students, Local Residents Bike Type: Mountain Bike, Road Bike, Electric Bike, Hybrid Bike Distribution Channel: Online Booking, In-store Rental, Mobile App, Kiosk |
| Companies Covered | Donkey Republic, Nextbike, Swapfiets, Bolt, Keolis, JobRad, JCDecaux, ListNRide, Dance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bike Rental Market Emerging Trajectories
Swappable battery architectures are redefining fleet uptime metrics by eliminating charging downtime and enabling continuous rotation of high-utilization assets across peak demand corridors.
Modular drivetrain systems are decomposing the traditional integrated motor-battery-controller stack into standardized sub-assemblies. Tier-2 suppliers in Taiwan and South Korea are shipping interchangeable hub motors and battery packs that fleet operators mix across frame suppliers. This interoperability is compressing supplier switching costs and fragmenting component procurement away from single-source vertical arrangements.
France's ANSM public space deployment permits now require real-time sidewalk obstruction monitoring via computer vision, forcing operators to retrofit existing fleets with edge-processing cameras. The regulation disproportionately burdens mid-size operators lacking in-house AI development capabilities, accelerating consolidation toward technology-forward fleet managers.
Subscription pricing is displacing hourly tourist rentals as the dominant revenue model. German and Dutch commuters now lock in 12-month unlimited-ride contracts through employer benefit platforms, while Copenhagen's tourism board reports 40% compression in walk-up daily rentals. This shift concentrates revenue predictability with resident-focused operators and marginalizes seasonal tourist-dependent models.
Bike Rental Market Segmentation
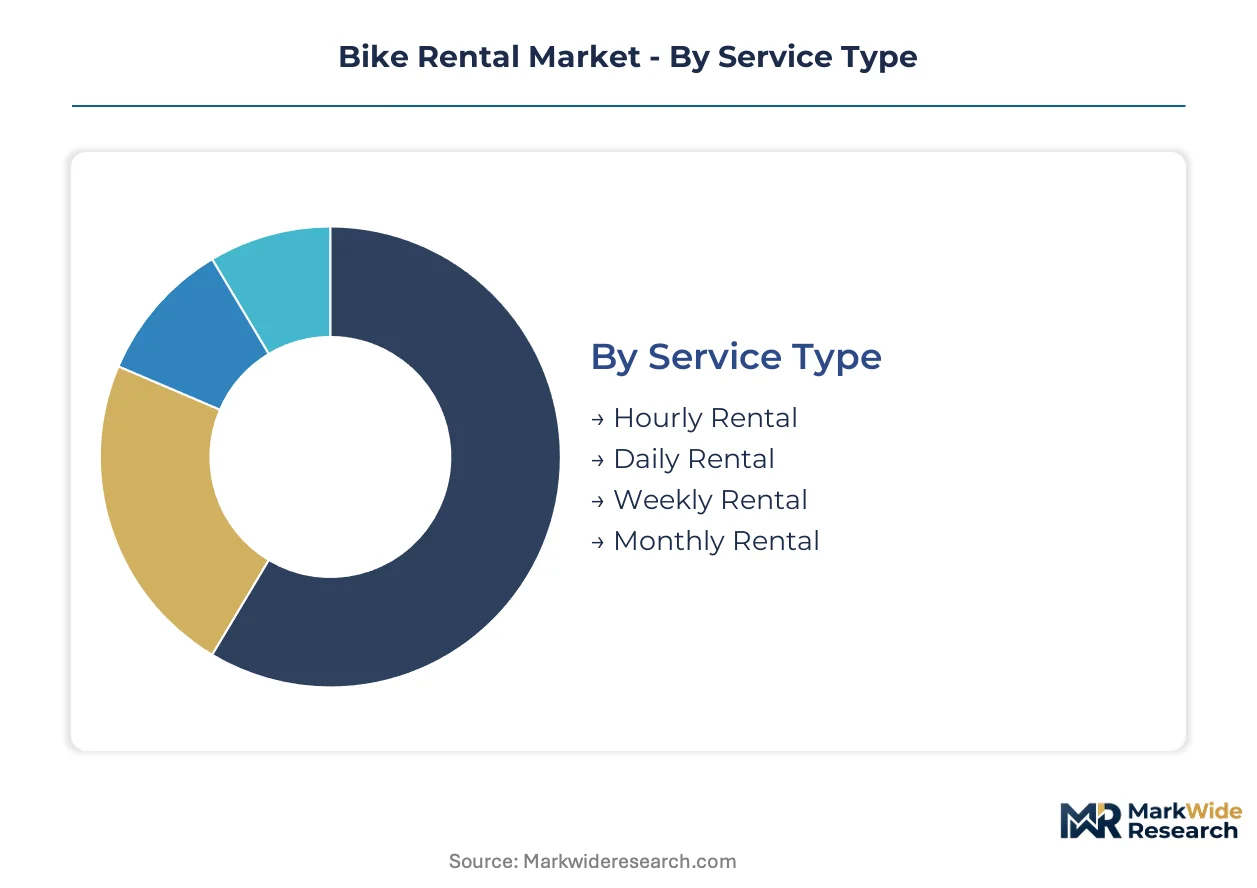
Segmentation in bike rental markets reveals divergent margin structures across service duration tiers and customer loyalty profiles. Fleet operators calibrate asset allocation and pricing architectures based on predictable commuter subscriptions versus volatile tourist demand patterns.
Service Type:
Margin pools concentrate in extended-duration commitments that amortize customer acquisition costs across predictable revenue streams.
- Hourly Rental:Short-duration access agreements typically serving spontaneous tourist demand and impulse urban mobility needs. Demand clusters around Amsterdam canal districts and Copenhagen harbor zones where cruise ship arrivals create surge pricing windows. Seasonal volatility compresses operator margins during off-peak months.
- Daily Rental:Full-day access structures dominate leisure cycling circuits in Bavarian lake regions and Dutch coastal routes. German operators report higher per-unit utilization rates on weekends when commuter subscriptions idle and tourist demand peaks.
- Weekly Rental:Compact description serving extended-stay tourists and temporary workers seeking cost-effective mobility without subscription commitments.
- Monthly Rental:Compact description anchoring recurring revenue bases for resident commuters through employer benefit platforms in Dutch and Danish metropolitan labor markets.
The dominant share belongs to Monthly Rental, while Daily Rental is closing the gap fastest.
Customer Type:
Application context determines fleet specification and service tier configuration across distinct mobility behaviors.
- Tourists:Transient users seeking recreational access to scenic corridors and heritage districts. Demand concentrates in Paris arrondissements and Barcelona waterfronts where operators deploy premium road bikes and guided tour packages. Weather dependency creates pronounced quarterly revenue swings.
- Commuters:Compact description representing the highest lifetime value segment through recurring subscription relationships and predictable daily utilization patterns.
- Students:Compact description accessing discounted semester-based pricing through university partnerships in German and Belgian academic hubs.
- Local Residents:Compact description combining occasional leisure use with supplementary mobility during transit disruptions or vehicle maintenance periods.
Commuters command the highest revenue concentration, with Local Residents expanding most quickly as municipal micro-mobility integration deepens.
Bike Type:
Supply concentration and technology cost curves fragment procurement strategies across performance tiers.
- Mountain Bike:Compact description serving recreational trail access in Alpine regions and Nordic forest networks where terrain demands specialized suspension and braking systems.
- Road Bike:Compact description targeting fitness enthusiasts and sport tourists on paved regional cycling routes with lightweight carbon fiber frame specifications.
- Electric Bike:Pedelec configurations with 250W to 750W motor output integrating lithium-ion battery systems for assisted propulsion. Demand concentrates in German commuter corridors where KBA type-approval frameworks above 25 km/h create premium S-pedelec segments. Battery cost curves below $100 per kWh are accelerating fleet electrification timelines.
- Hybrid Bike:Versatile frame geometry accommodating mixed terrain use across urban commuting and light recreational applications. Dutch operators prioritize these units for subscription fleets serving residents with varied weekly route requirements. Durability specifications reduce maintenance overhead in high-rotation deployment scenarios.
Electric Bike holds the technology leadership position, while Hybrid Bike is gaining share fastest among multi-use residential subscribers.
Distribution Channel:
Customer acquisition economics and operational overhead vary sharply across digital and physical touchpoint strategies.
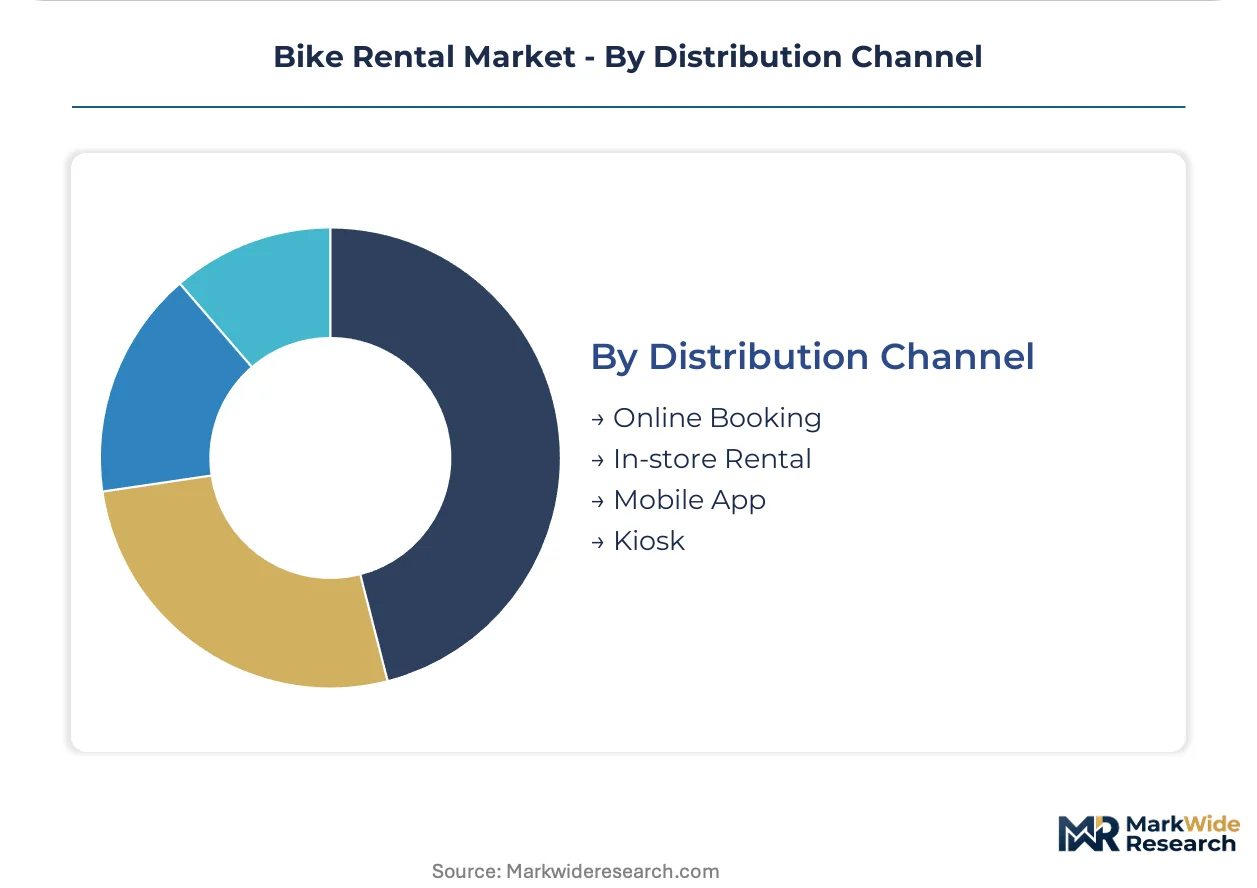
- Online Booking:Compact description enabling advance reservation and payment processing through operator websites, reducing on-site staffing requirements.
- In-store Rental:Compact description preserving high-touch service for tourists requiring fitting assistance and route consultation in dense urban retail locations.
- Mobile App:Smartphone-based access control and real-time fleet location services. Copenhagen and Berlin operators leverage these platforms for dockless electric bike unlocking and subscription management. Integration with municipal transit APIs is deepening intermodal usage patterns.
- Kiosk:Automated station interfaces supporting card payment and membership verification at docking infrastructure points. German-speaking markets maintain higher kiosk density due to Nextbike's direct operational control of fixed station networks. Hardware maintenance and right-of-way permitting create geographic fragmentation in deployment feasibility.
Mobile App commands the dominant growth trajectory, while Kiosk retains structural importance in concession-bound municipal contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commuter subscription platforms and municipal procurement contracts concentrate demand in Northern European metropolitan corridors where cycling infrastructure density supports recurring revenue models. Fleet operators prioritize Germany, Denmark, and the Netherlands for dockless electric bike deployment. Urban congestion pricing in London, Stockholm, and Milan accelerates last-mile substitution toward micro-mobility alternatives.
Germany
Employer-sponsored bike leasing through payroll tax exemptions drives B2B channel expansion. The KBA type-approval framework for pedelecs above 25 km/h creates premium S-pedelec segments distinct from standard 25 km/h classifications. Berlin and Munich anchor fleet deployment volumes where Deutsche Bahn station-adjacent parking APIs enable train-to-bike intermodal connectivity.
Netherlands
Residential commuters lock in 12-month unlimited-ride contracts through employer benefit platforms, displacing hourly tourist rentals. Municipal micro-mobility integration deepens via OV-chipkaart transit card compatibility. Amsterdam and Rotterdam concentrate subscription fleet density where cycling infrastructure supports predictable daily utilization patterns.
Denmark
Copenhagen's tourism board reports compression in walk-up daily rentals as resident subscriptions mature. The national cycling superhighway network connects peripheral municipalities to central business districts. Aarhus and Odense expand fleet coverage through municipal concession renewals integrating climate performance clauses into minimum service obligations.
France
ANSM public space deployment permits mandate real-time sidewalk obstruction monitoring via computer vision, raising compliance barriers for mid-size operators. Paris arrondissements concentrate premium road bike and guided tour package demand from recreational users. Lyon and Marseille operators retrofit existing fleets with edge-processing cameras to satisfy regulatory requirements.
United Kingdom
London's congestion charge zone pushes last-mile commuters toward exempt micro-mobility alternatives. Transport for London APIs integrate dockless bike unlocking with contactless payment infrastructure. Manchester and Birmingham expand fleet permits through devolved authority frameworks that fragment standardization across metropolitan clusters.
Bike Rental Market Vendor Landscape
Player mix skews toward vertically integrated fleet operators and technology-forward platform providers. The competitive structure fragments across municipal concession holders, dockless app-based services, and employer benefit intermediaries. Three archetypes dominate: fixed-infrastructure incumbents with direct station control, asset-light software platforms enabling partnership networks, and B2B subscription specialists integrating payroll systems. Consolidation pressure intensifies through municipal concession renewals and cross-border technology licensing arrangements.
Among Nordic software-anchored platforms, Donkey Republic exemplifies the open-source partnership model across multiple city contracts. Within German-speaking fixed-infrastructure operations, Nextbike occupies a position tied to direct docking network control. On the employer benefit vector, JobRad represents the B2B payroll integration archetype. These three anchors illustrate how competitive positioning diverges across procurement channel specialization rather than converging on uniform service delivery.
| Leading Market Players |
|---|
| Donkey Republic |
| Nextbike |
| Swapfiets |
| Bolt |
| Keolis |
| JobRad |
| JCDecaux |
| ListNRide |
| Dance |
| Others |
Supply Flow & Price Mechanics
Swappable battery architectures replacing fixed-cell designs are simultaneously shifting procurement geography toward Taiwan and South Korea while compressing per-unit pricing power across European fleet operators. This substitution dynamic decouples frame sourcing from powertrain bundling, enabling operators to arbitrage component costs across modular supplier networks.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate battery procurement agreements, insulating fleet operators from spot volatility while passing through cathode chemistry premiums. Price differentiation rests on ISO 4210 certification tiers and employer benefit platform integration depth. Pricing pressure stems from municipal concession fragmentation forcing city-specific compliance overhead. Tourist hourly renters exhibit highest price sensitivity; commuter subscribers locked through payroll tax exemptions show lowest elasticity.
Supply Chain Analysis
Inbound logistics costs from Rotterdam port congestion and Asia-Europe container availability constraints are elevating landed costs for Taiwan-sourced hub motors and South Korean battery packs. Supply concentrates in Taiwan, South Korea, and Vietnam for drivetrain components, with Chinese cell manufacturing feeding cathode material flows. Raw material dependencies span lithium carbonate, cobalt sulfate, and rare-earth magnets. Single-source vulnerability runs through DRC-sourced cobalt exposing operators to ECHA due diligence mandates. Distribution runs through direct OEM relationships with fleet operators bypassing traditional bike wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards operators who control in-house AI development for computer vision compliance, a capability gap that is accelerating consolidation toward technology-forward fleet managers with regulatory engineering benches.
For Market Incumbents: Shield subscription revenue bases by deepening employer benefit platform integrations before emerging B2B intermediaries capture payroll system access. Prioritize backward integration into second-life battery storage assets to unlock circular revenue streams under EU circular economy incentives. Municipal concession renewals with climate performance clauses represent the critical defensive lever. For New Entrants and Emerging Players: Intermodal transit integration gaps where incumbent operators under-serve Deutsche Bahn and SNCF station-adjacent parking APIs offer white-space expansion. Target mid-size French metropolitan areas where ANSM computer vision mandates have burdened legacy operators lacking AI capabilities. Pursue open-source software licensing partnerships with Nordic municipal networks as the go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed dockless platform providers seeking exit liquidity amid municipal consolidation pressures. Long-term viability favors operators with renewable energy charging networks and documented cobalt-free cathode supply chains. Watch for municipal concession renewal waves integrating climate performance clauses as the inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Swappable Battery Architecture Deployment | Eliminates charging downtime and enables continuous asset rotation across peak demand corridors in German commuter markets. |
| Employer Benefit Platform Integration | Captures Dutch and Danish payroll tax exemption flows through B2B channel expansion with predictable recurring revenue. |
| Computer Vision Retrofit Program | Satisfies France ANSM sidewalk obstruction mandates and creates technology barrier against mid-size competitors. |
| Second-Life Battery Storage Partnership | Repurposes retired fleet cells into grid stabilization assets under EU circular economy action plan incentives. |
| Municipal Concession Renewal Capture | Secures climate performance clause integration into minimum service obligations across Denmark and Netherlands networks. |
Methodological Framework
A spread of perspectives from fleet operations directors, municipal procurement officers, battery supply chain managers, and employer benefit platform executives converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through EU transport statistics, KBA type-approval filings, ECHA battery regulation guidance, and municipal concession documentation. Bottom-up fleet deployment counts triangulated against top-down mobility substitution models.
Segmentation dimensions modeled span service duration tiers, customer loyalty profiles, bike technology specifications, and distribution channel structures across the projection horizon. CAGRs derive from penetration rate trajectories in congestion pricing zones and battery cost curve assumptions. Forecast inputs incorporate employer benefit platform adoption curves and municipal procurement cycle timing.
Underlying assumptions cover EU Green Deal mobility target adherence, lithium-ion cell price trajectories, and municipal concession renewal patterns, with deviation risk concentrated in cobalt supply disruption and computer vision regulatory expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
Third Party Logistics Services Market
Transportation Services
ASEAN Taxi Market
Transportation Services
Latin America Tourism Vehicle Rental Market
Transportation Services
Aerial Lift Rental Services Market
Transportation Services
Europe Refrigerated Truck Rental Market
Transportation Services
Vehicle Management System Market
Transportation Services
Europe Light Commercial Vehicle Rental Market
Transportation Services
Global White Glove Service in Delivery Market
Transportation Services
Global Garbage Truck Market
Transportation Services
United States Car Rental Market
Transportation Services
Middle East Car Rental Market
Transportation Services
Germany Car Rental Market
Transportation Services
Thailand Car Rental Market
Transportation Services
MUV Rental Market
Transportation Services
India Two-Wheelers Rental Market
Transportation Services
Truck Sharing Market