
 Vertical Mobility Market | 2026-2036
Vertical Mobility Market Size, Share, and Industry Trends Forecast 2026-2036
Vertical Mobility Market Outlook
Market Context
Aftermarket service revenue is fragmenting across predictive maintenance platforms and on-demand technician networks. Otis Elevator Company leverages its vast installed base to sustain recurring service contracts across North American high-rises. KONE Corporation anchors its growth in smart building integration, competing through digital-native elevator systems. Schindler Group differentiates via modular modernization kits that extend equipment lifecycles without full replacement.
Technical Definition and Structural Segments
Vertical mobility encompasses electromechanical and aerodynamic systems engineered to transport passengers or cargo between elevations, with traction elevators typically operating at speeds up to 10 m/s using steel rope or belt mechanisms, and eVTOL aircraft targeting cruise altitudes below 3,000 feet for intra-urban corridors. Elevators dominate installed value across commercial real estate, while eVTOL platforms represent the fastest-growing technology category as hydrogen fuel cell propulsion and distributed electric thrust mature. The maintenance service segment captures the most stable margin pool due to regulatory-mandated inspection cycles, whereas modernization demand concentrates in aging European and North American building stocks where code upgrades trigger system overhauls.
Regulatory Frame and Outlook
The FAA's powered-lift certification pathway and EASA's SC-VTOL special condition framework govern eVTOL airworthiness, while ASME A17.1 and EN 81-20 standards dictate elevator safety protocols across construction markets. China's CAAC coordinates with municipal aviation authorities to establish low-altitude flight corridors above Shenzhen and Shanghai, compressing approval timelines for commercial urban air mobility operations. Stakeholders must monitor regulatory divergence between jurisdictions as certification reciprocity agreements remain unsettled.
Market Dynamics
The FAA's Part 23 rewrite for powered-lift certification is compressing eVTOL commercialization timelines while simultaneously fragmenting aftermarket service revenue across predictive maintenance platforms and on-demand technician networks.
Growth Catalysts
- Regulatory acceleration:The FAA's powered-lift certification pathway and EASA's SC-VTOL special condition framework are compressing approval timelines for commercial urban air mobility operations across multiple jurisdictions.
- Urban congestion infrastructure:China's megacity clusters are deploying vertical transport infrastructure to address severe ground congestion, concentrating demand in Shenzhen and Shanghai low-altitude flight corridors.
- Logistics network integration:Urban air mobility networks are attracting capital from logistics operators seeking last-mile delivery alternatives to ground-based distribution.
Market Restraints
- Certification reciprocity gaps:Unsettled reciprocity agreements between the FAA, EASA, and CAAC are creating regulatory friction for manufacturers seeking multi-jurisdiction approval.
- Hydrogen fuel cell supply concentration:Proton exchange membrane production concentrates in East Asian supply chains, exposing eVTOL propulsion system costs to input volatility.
- Traction elevator speed ceilings:Steel rope fatigue limits at speeds above 10 m/s constrain high-rise transport efficiency in supertall construction.
Strategic Opportunities
- Smart building convergence:IoT-enabled elevator systems and building management platforms are creating white space for integrated vertical transport solutions in commercial real estate.
- Modular modernization kits:Aging European and North American building stocks where code upgrades trigger system overhauls represent underpenetrated demand for lifecycle extension products.
- Dual carbon policy alignment:China's dual carbon goals are accelerating municipal investment in electric vertical mobility infrastructure above dense urban cores.
Industry Challenges
- Distributed electric thrust engineering talent:Scarce expertise in redundant motor configuration and battery thermal management is constraining eVTOL manufacturer hiring pipelines.
- Legacy elevator integration complexity:Smart building integration requires retrofitting electromechanical systems with digital-native control architectures without full replacement.
Report Scope
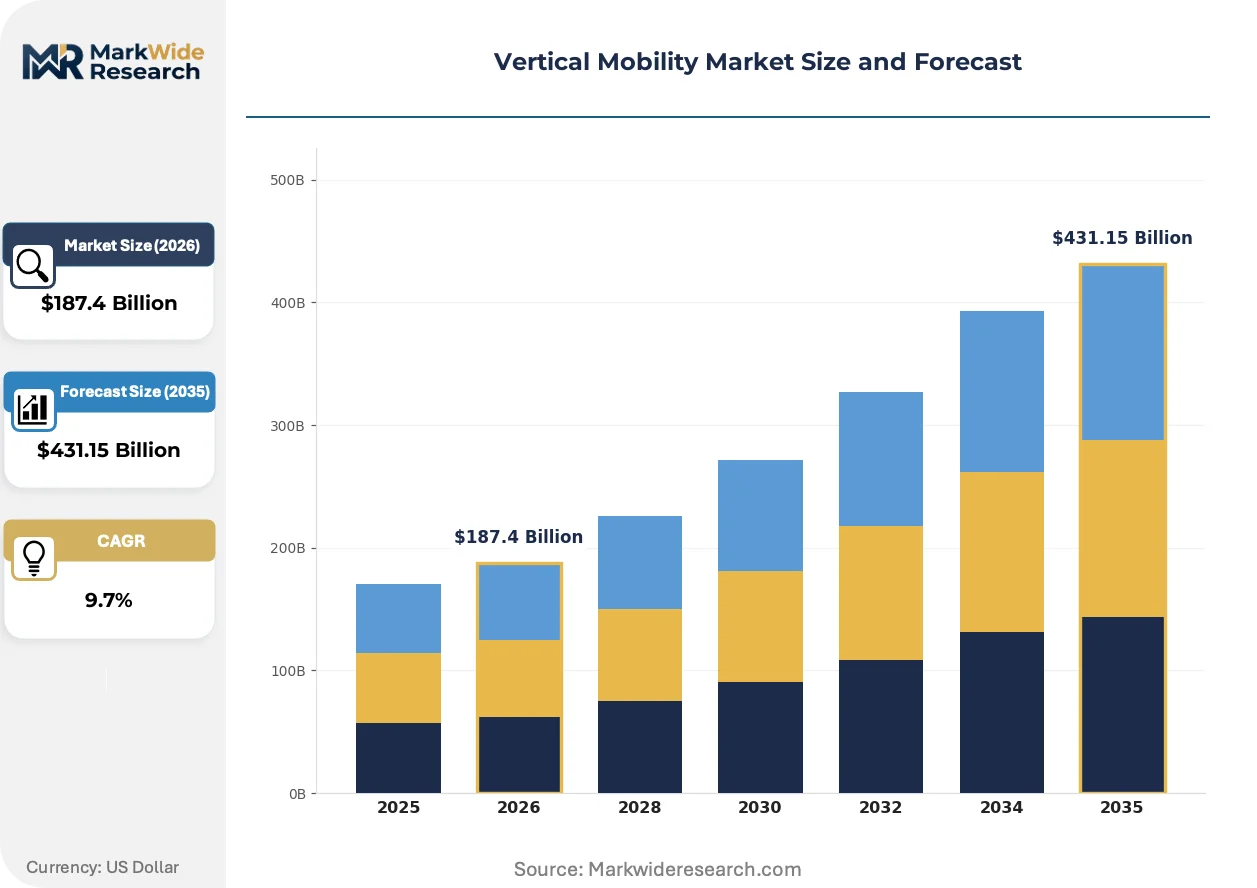
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertical Mobility Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $431.15 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Elevators, Escalators, Lifts, People Movers Technology: Hydraulic, Traction, Pneumatic, Vacuum End User: Residential, Commercial, Industrial, Institutional Service Type: Maintenance, Installation, Modernization, Consulting |
| Companies Covered | Thyssenkrupp Elevator AG, Fujitec Co., Ltd., Otis Elevator Company, Airbus SE, Hitachi Ltd., Schindler Group, Mitsubishi Electric Corporation, EHang, KONE Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertical Mobility Market Strategic Shifts
Predictive maintenance platforms are actively reshaping service economics across both elevator and eVTOL segments, compressing technician dispatch cycles and unbundling traditional inspection contracts.
Distributed electric thrust architectures are digitizing propulsion system monitoring through real-time motor health telemetry and predictive failure algorithms. Logistics operators and urban air mobility fleet managers are adopting these platforms at accelerated procurement cycles. The technology is digitizing maintenance scheduling from calendar-based to condition-based intervals, compressing downtime and extending component lifecycles.
EASA's SC-VTOL special condition framework and the FAA's powered-lift certification pathway are establishing distinct airworthiness criteria for multi-rotor electric aircraft. These regulations are forcing manufacturers to bifurcate testing protocols between European and American approval tracks. The eVTOL segment is responding by establishing dual certification engineering teams and region-specific prototype configurations.
Building operators are unbundling elevator service contracts from single-source OEM agreements toward competitive bidding for predictive analytics subscriptions and on-demand technician networks. The aftermarket segment is fragmenting as facility managers purchase maintenance software separately from labor dispatch services. This shift is most visible in North American commercial real estate where operating expense scrutiny drives vendor diversification.
Vertical Mobility Market Segmentation
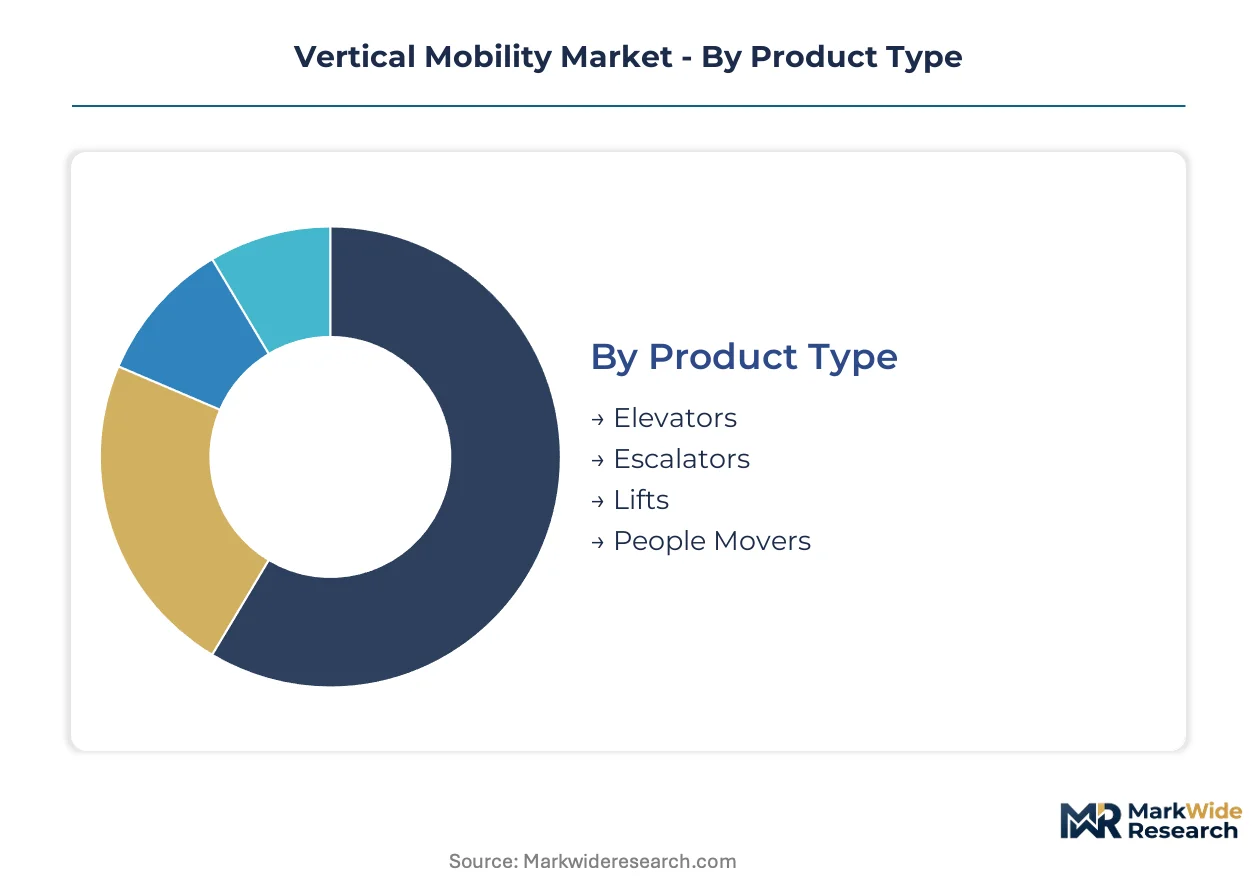
Vertical mobility procurement splits sharply between installed-base service economics and new construction technology selection. Equipment specification varies dramatically across building height, passenger density, and integration complexity.
Product Type:
Application context determines equipment selection, with throughput requirements and vertical travel distance dictating system architecture.
- Elevators:Traction and hydraulic configurations dominate commercial high-rises, with speeds reaching 10 m/s in supertall structures. Demand concentrates in China's megacity clusters where Shenzhen and Shanghai municipal authorities fast-track vertical transport permits to address severe ground congestion.
- Escalators:Continuous-loop step mechanisms serve high-volume horizontal-vertical transitions in retail and transit hubs. Installation concentrates in Asia-Pacific urban rail expansions where station depth and passenger throughput requirements exceed elevator capacity economics.
- Lifts:Compact vertical transport units serve accessibility compliance and low-rise commercial applications. Regulatory mandates in European and North American jurisdictions drive replacement cycles for aging accessibility infrastructure.
- People Movers:Automated horizontal transit systems bridge distributed vertical transport nodes in airport and campus environments. Procurement clusters in Gulf Cooperation Council aviation infrastructure expansions.
Elevators hold installed capacity. Escalators are rotating up the share rankings in transit-intensive geographies.
Technology:
Cost tier and performance specifications segment propulsion architecture selection across building classes.
- Traction:Steel rope or belt-driven systems with geared and gearless motor configurations serve mid-rise to supertall applications. Adoption concentrates in premium commercial real estate where speed and energy efficiency specifications justify higher capital expenditure.
- Hydraulic:Fluid-pressure piston mechanisms dominate low-rise commercial and industrial installations. Demand persists in North American retrofit markets where shaft infrastructure constraints preclude traction system conversion.
- Pneumatic:Air-pressure driven vacuum tube systems serve specialized accessibility and residential applications. Niche procurement in luxury residential retrofits where shaftless installation reduces structural modification costs.
- Vacuum:Self-supporting pneumatic elevators eliminate machine room requirements through differential air pressure propulsion. Penetration remains limited to residential and light commercial segments in European and Australian markets.
Traction technology captures premium construction spend. Vacuum systems are climbing the fastest in residential accessibility retrofits.
End User:
Customer type dictates service contract structure, equipment specification, and modernization trigger points.
- Commercial:Office towers, retail complexes, and hospitality properties drive smart building integration demand. Procurement in North American Class A real estate emphasizes predictive maintenance platforms and IoT-enabled traffic management.
- Residential:Multi-unit housing and single-family accessibility installations prioritize cost efficiency and space minimization. China's urban renewal programs concentrate high-volume residential elevator deployment in dense municipal clusters.
- Industrial:Manufacturing facilities and warehousing operations require freight-rated capacity and harsh-environment durability. Specification emphasizes load rating and cycle frequency over passenger comfort features.
- Institutional:Healthcare, education, and government facilities mandate compliance with accessibility codes and emergency evacuation protocols. Modernization demand concentrates in European public building stocks where aging infrastructure requires code-triggered system overhauls.
Commercial end users hold service contract value. Residential is expanding most quickly in Asia-Pacific urban densification.
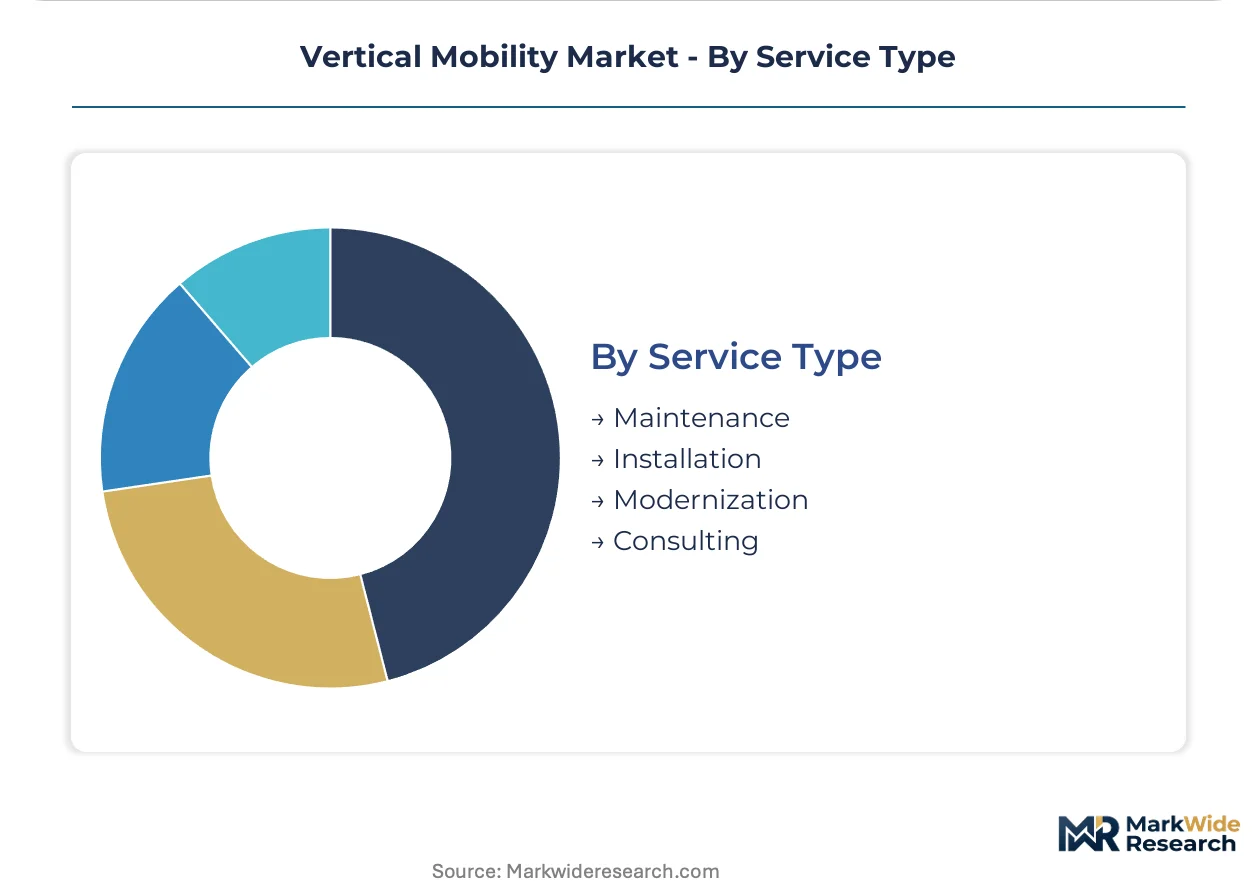
Service Type:
Margin structure and revenue stability vary dramatically across the equipment lifecycle.
- Maintenance:Regulatory-mandated inspection cycles generate recurring revenue with the most stable margin pool. ASME A17.1 and EN 81-20 compliance requirements enforce technician dispatch minimums regardless of equipment condition.
- Modernization:Lifecycle extension through control system upgrades and component replacement addresses aging European and North American installed bases. Code upgrade triggers create demand concentration in jurisdictions with stringent safety protocol updates.
- Installation:New construction and greenfield development drive capital equipment revenue with project-based margin volatility. Demand fluctuates with commercial real estate development cycles and municipal infrastructure investment timing.
- Consulting:Traffic analysis, specification engineering, and smart building integration advisory services capture value upstream of equipment procurement. Growth correlates with complex multi-vendor integration requirements in premium commercial developments.
Maintenance holds recurring revenue concentration. Modernization is gaining share fastest in aging building stock jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vertical mobility consumption patterns diverge sharply across geographies: China's megacity clusters prioritize eVTOL corridor deployment above dense urban cores, while European and North American markets concentrate investment in aging elevator modernization and smart building integration.
China
Shenzhen and Shanghai municipal authorities are fast-tracking low-altitude flight corridor permits to relieve severe ground congestion. The CAAC coordinates with city aviation regulators to compress commercial urban air mobility approval timelines. Dual carbon policy alignment is accelerating municipal investment in electric vertical transport infrastructure across the Yangtze River Delta and Pearl River Delta clusters.
United States
Class A commercial real estate in New York and Chicago drives predictive maintenance platform procurement and IoT-enabled traffic management integration. The FAA's Part 23 rewrite for powered-lift certification is compressing eVTOL commercialization timelines for logistics operators seeking last-mile delivery alternatives. Aftermarket service revenue is fragmenting across on-demand technician networks in North American high-rise markets.
Germany
Aging building stocks in Berlin and Munich trigger code-mandated elevator system overhauls and modular modernization kit demand. EASA's SC-VTOL special condition framework governs multi-rotor electric aircraft airworthiness criteria distinct from FAA pathways. Smart building integration requirements in Frankfurt's commercial towers are unbundling traditional OEM service contracts toward competitive predictive analytics bidding.
Japan
Tokyo's vertical transport infrastructure addresses seismic resilience specifications alongside throughput efficiency in high-density commercial districts. METI coordinates national standards with municipal building codes for elevator safety protocol updates. Osaka and Nagoya industrial zones concentrate traction system manufacturing for premium mid-rise to supertall applications across Asia-Pacific export markets.
United Arab Emirates
Gulf Cooperation Council aviation infrastructure expansions in Dubai and Abu Dhabi drive automated people mover procurement bridging distributed vertical transport nodes. MOHAP and municipal aviation authorities establish regulatory frameworks for low-altitude commercial operations above dense urban cores. NEOM's northwest development is integrating vertical mobility corridors into master-planned smart city infrastructure from initial construction phases.
Vertical Mobility Market Competitive Environment
Capability concentration sits with electromechanical incumbents possessing vast installed bases; scale advantage sits with diversified industrial conglomerates spanning multiple mobility modalities. The market structures around three tiers: legacy elevator OEMs with recurring service contract dominance, aerospace entrants targeting eVTOL commercialization, and regional fabricators capturing modernization demand in aging building stocks. Dominant competitive moves include portfolio diversification into predictive maintenance platforms and strategic partnerships between propulsion system developers and airframe manufacturers.
Within the legacy electromechanical tier, Otis Elevator Company, KONE Corporation, and Schindler Group exemplify the service-revenue archetype leveraging installed-base relationships to sustain recurring maintenance contracts. These entities occupy positions where regulatory-mandated inspection cycles generate stable margin pools, while their geographic diversification spans North American high-rises, European modernization markets, and Asia-Pacific new construction. EHang represents the aerodynamic mobility specialist archetype, sitting within the emerging eVTOL certification track where distributed electric thrust architectures and hydrogen fuel cell propulsion systems are maturing. The competitive terrain is bifurcating between electromechanical incumbents defending service contract value and aerodynamic entrants capturing logistics operator capital for last-mile delivery alternatives.
| Leading Market Players |
|---|
| Thyssenkrupp Elevator AG |
| Fujitec Co., Ltd. |
| Otis Elevator Company |
| Airbus SE |
| Hitachi Ltd. |
| Schindler Group |
| Mitsubishi Electric Corporation |
| EHang |
| KONE Corporation |
| Others |
Value Chain & Pricing Dynamics
Shenzhen's low-altitude flight corridor infrastructure is concentrating eVTOL propulsion system manufacturing capacity, translating upstream component scarcity into pricing power for proton exchange membrane suppliers serving urban air mobility developers.
Pricing Analysis
Long-term offtake agreements dominate eVTOL airframe procurement, while elevator service contracts fragment toward spot-market technician dispatch and subscription-based predictive analytics. Price differentiation hinges on FAA Part 23 certification tier and smart building integration complexity. Pricing pressure stems from hydrogen fuel cell supply concentration in East Asian supply chains. Logistics operators exhibit highest price sensitivity; premium commercial real estate buyers prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Contract manufacturing for distributed electric thrust systems concentrates in Osaka and Nagoya industrial zones, with final assembly gravitating toward Shenzhen and Dubai aviation hubs. Critical inputs span steel rope for traction elevators, proton exchange membranes for fuel cells, and rare earth magnets for motor assemblies. Single-source vulnerability in East Asian battery thermal management components threatens production continuity. Distribution runs through OEM-direct channels for new equipment and fragmented technician networks for aftermarket service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical mobility procurement is fragmenting across predictive maintenance platforms, on-demand labor networks, and integrated smart building solutions, creating niche specialization opportunities for regional service providers and technology-native entrants.
For Market Incumbents: Insulate recurring maintenance revenue by embedding IoT-enabled condition monitoring into legacy installed bases before predictive analytics vendors displace traditional inspection contracts. Prioritize backward integration into sensor hardware to capture data-layer margins from facility management platforms.
For New Entrants and Emerging Players: European modernization markets for aging elevator infrastructure remain underpenetrated by digital-native service platforms, offering white-space entry through modular control system retrofits. Target Germany's code-mandated overhaul cycles with subscription-based lifecycle extension products.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core vertical mobility service divisions. Monitor FAA-EASA certification reciprocity negotiations as inflection signal for multi-jurisdiction platform scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Building Platform Integration | Combines Otis and KONE traffic management APIs with Siemens and Honeywell building automation systems. |
| Predictive Maintenance Subscription Launch | Transforms Schindler's installed base into recurring software revenue streams across North American Class A properties. |
| Dual Certification Engineering Investment | Enables EHang to bifurcate testing protocols for FAA powered-lift and EASA SC-VTOL approval tracks simultaneously. |
| Hydrogen Fuel Cell Supply Agreement | Secures proton exchange membrane capacity from East Asian suppliers for eVTOL logistics fleet deployments. |
| Modular Modernization Kit Expansion | Addresses European aging building stocks with control upgrades that extend equipment lifecycles without full replacement. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with elevator maintenance directors, eVTOL propulsion engineers, facility management procurement officers, and smart building integration specialists; and secondary validation against FAA certification filings, EASA SC-VTOL documentation, ASME A17.1 code revisions, and municipal aviation authority permits. Bottom-up equipment unit economics triangulated against top-down construction spending and logistics fleet investment flows.
Forecast inputs span traction elevator speed tiers, eVTOL cruise altitude bands, service contract structure evolution, and regional regulatory framework divergence across the projection horizon. CAGRs derive from segmented growth rate modeling across product type, technology, end user, and service type dimensions, incorporating hydrogen fuel cell cost curves and smart building penetration assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by aerospace entrants or platform consolidation by predictive analytics vendors would shift outcomes. Quarterly review of FAA-EASA reciprocity negotiations, municipal low-altitude corridor approvals, and proton exchange membrane spot pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Smart Car Tracking Systems Market
Smart Transportation Solutions
Fleet Management Software Market
Smart Transportation Solutions
Europe Electronic Toll Collection Market
Smart Transportation Solutions
Global Ridesharing Market
Smart Transportation Solutions
Automotive Digital Mapping Market
Smart Transportation Solutions
New Energy Vehicle Sweeper Market
Smart Transportation Solutions
Smart Rail Suite Solutions Market
Smart Transportation Solutions
Temperature-Controlled Last-Mile Delivery Services Market
Smart Transportation Solutions
Smart Fleet Management Market
Smart Transportation Solutions
Intelligent Traffic Management Market
Smart Transportation Solutions
Global Parking Management Software Market
Smart Transportation Solutions
Mexico Ride Hailing Market
Smart Transportation Solutions
Personal Transporter Market
Smart Transportation Solutions
Car Sharing Market
Smart Transportation Solutions
Automated Robotic Parking System Market
Smart Transportation Solutions
Ride-Hailing Market