
 Smart Chassis Market | 2026-2036
Smart Chassis Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Chassis Market Insights
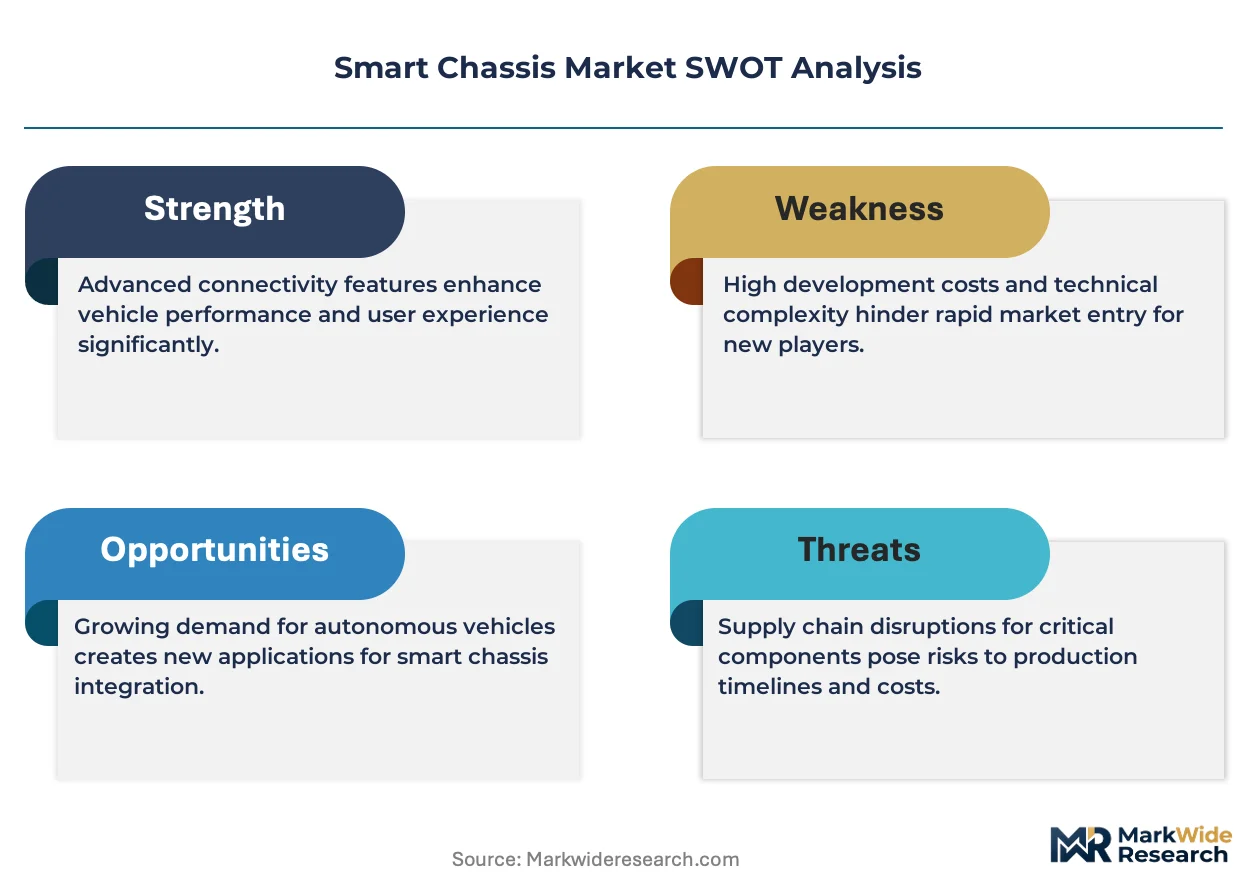
Platform-grade electrification is rotating the Smart Chassis market toward higher-margin integrated architectures. ZF Friedrichshafen anchors European supply through its systems integration depth for premium OEMs. BYD leverages captive battery and semiconductor capacity to control chassis-electric powertrain interfaces. NIO Inc. differentiates through proprietary steer-by-wire and active suspension calibration for its premium EV lineup.
A smart chassis constitutes the structural frame integrating embedded control modules, sensor arrays, and actuation hardware that govern ride dynamics, energy recuperation, and autonomous trajectory execution, typically operating at CAN-FD or Ethernet backbone speeds exceeding 500 kbps. Passenger vehicles and luxury vehicles concentrate current revenue as OEMs prioritize cabin comfort differentiation and automated lane-keeping precision. Adaptive suspension and energy management systems represent the fastest-expanding technology pair, driven by fleet operators demanding predictive maintenance integration and aftermarket providers retrofitting legacy platforms.
China's NMPA enforces GB/T vehicle cybersecurity standards that mandate encrypted chassis control domain access, while Europe's UNECE WP.29 and CE marking frameworks compel traceable software update mechanisms for safety-critical steering and braking functions. The US NHTSA FMVSS braking and stability controls further shape product qualification pathways for suppliers seeking multi-region homologation. Stakeholders must monitor regulatory divergence between cybersecurity certification regimes and decide whether to architect region-specific control modules or pursue unified platforms with configurable compliance layers.
Market Dynamics
Drive-by-wire architecture migration is compressing tiered supplier hierarchies into integrated platform ecosystems, forcing chassis module vendors to absorb sensor fusion and domain controller competencies previously held by separate ECU specialists.
Growth Catalysts
- UNECE WP.29 cybersecurity mandates:European OEMs must deploy encrypted chassis control domains by regulatory deadlines, accelerating procurement of pre-certified intelligent platforms over discrete component sourcing.
- Active suspension calibration:Premium EV lineups now specify predictive damper control as standard equipment, pulling chassis software development upstream into vehicle program definition phases.
- China's dual carbon goals:National emissions reduction targets prioritize energy recuperation systems in chassis design, mandating integrated brake-by-wire and thermal management architectures for new vehicle homologation.
Market Restraints
- Rare earth magnet supply concentration:Permanent magnet dependencies for chassis-mounted electric motors concentrate in single-source refining corridors, exposing actuator production to export quota volatility.
- GB/T certification complexity:China's NMPA cybersecurity standards require localized encryption modules that fragment software architectures and prevent true global platform standardization.
- Silicon carbide substrate scarcity:Power electronics for chassis-integrated inverters face ingot supply bottlenecks that constrain high-voltage actuator rollout timelines.
Strategic Opportunities
- Retrofit aftermarket channels:Fleet operators seek predictive maintenance integration for legacy diesel platforms, opening revenue streams for adaptive suspension and energy management retrofit kits.
- India's PLI scheme for automotive:Component-level incentives attract chassis module assembly investments serving domestic EV programs and export markets.
- Ethernet backbone convergence:Sensor fusion and actuation control merging onto unified 1 Gbps networks enables new entrants to displace incumbents locked into CAN-FD legacy architectures.
Industry Challenges
- Embedded software talent scarcity:Functional safety engineering for ISO 26262 ASIL-D chassis functions commands premium compensation that mid-tier suppliers struggle to match.
- Homologation timeline compression:Simultaneous NHTSA FMVSS braking validation and UNECE WP.29 cybersecurity certification creates parallel track resource drains.
- Legacy powertrain integration friction:Intelligent chassis platforms must maintain backward compatibility with internal combustion drivelines during extended transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Chassis Market |
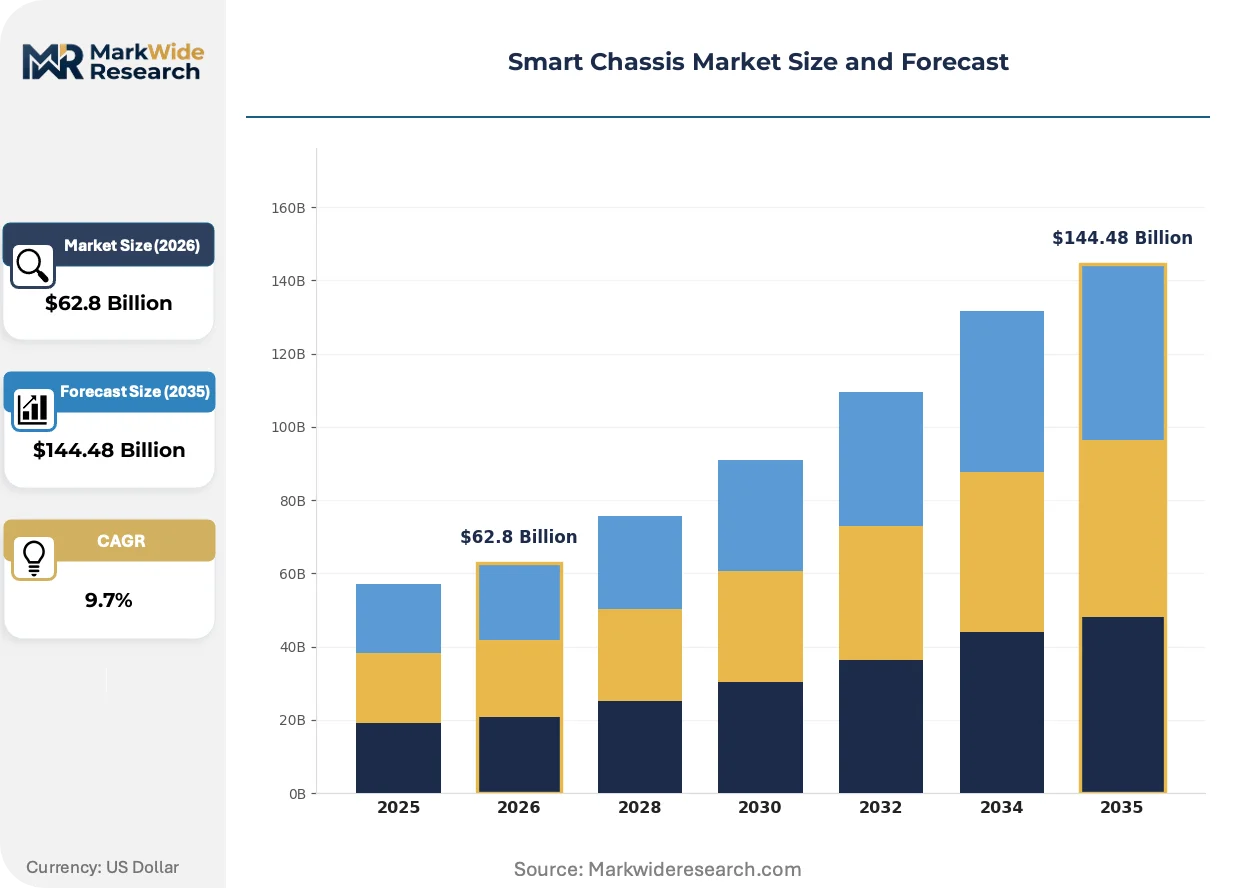
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $144.48 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Vehicles, Commercial Vehicles, Luxury Vehicles, Heavy-Duty Trucks Technology: Embedded Systems, IoT Solutions, Adaptive Suspension, Energy Management Systems End User: OEMs, Fleet Operators, Aftermarket Providers, Research Institutions Application: Autonomous Driving, Vehicle Tracking, Fleet Management, Performance Optimization |
| Companies Covered | NIO Inc., Qualcomm Technologies, SAIC Motor Corporation Limited, XPENG Motors, Great Wall Motor, BYD, ZF Friedrichshafen, Li Auto Inc., Geely Holding Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Chassis Market Trends and Innovations
Software-defined chassis architectures are collapsing hardware boundaries between suspension, steering, and braking domains, enabling over-the-air calibration updates that shift value capture from mechanical precision to algorithmic refinement.
Steer-by-wire systems eliminate mechanical steering columns entirely. Premium EV platforms are adopting these architectures for packaging flexibility and crash safety optimization. This displacement of hydraulic and electromechanical assist units is compressing supplier margins on legacy rack-and-pinion assemblies.
Europe's CSRD sustainability reporting framework now mandates supply chain emissions disclosure for chassis component sourcing. Tier-1 suppliers must deploy blockchain-tracked material provenance systems. Battery-electric vehicle programs face the steepest compliance burdens due to aluminum and rare earth content intensity.
Fleet procurement departments now specify chassis health monitoring as a contract requirement rather than aftermarket option. Leasing companies embed predictive maintenance APIs into usage-based financing structures. Germany's commercial vehicle operators lead this behavioral shift, demanding brake wear and suspension fatigue telemetry as standard data deliverables.
Smart Chassis Market Segmentation
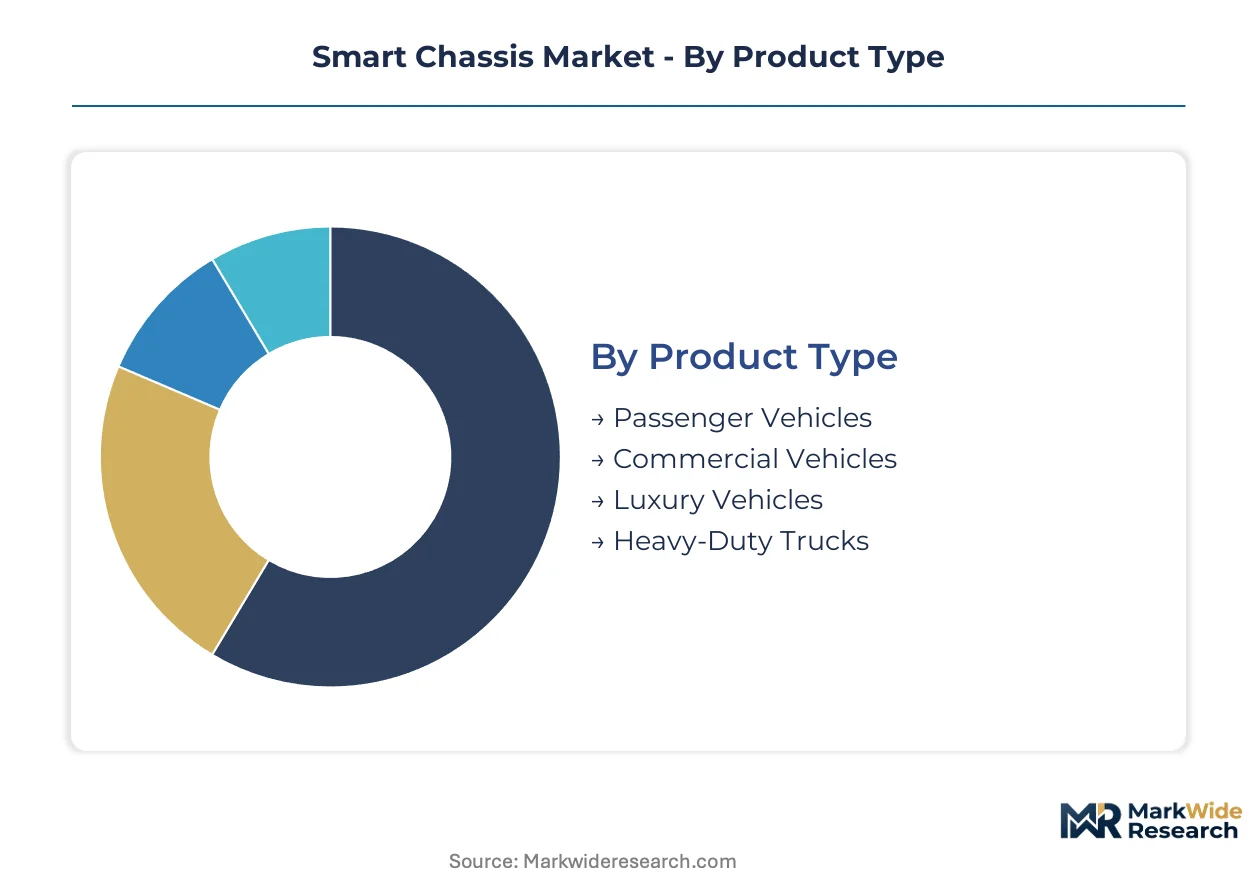
Smart chassis procurement patterns diverge sharply across vehicle classes and technology tiers. OEMs configure platform architectures differently for domestic compliance versus export homologation, creating distinct specification clusters within each segment category.
Product Type:
Passenger vehicle chassis dominate domestic Chinese programs, while luxury and heavy-duty configurations skew toward export-led demand from European and North American OEMs.
- Passenger Vehicles:Standardized embedded control modules with CAN-FD backbone integration serve mass-market EV platforms. BYD and XPENG anchor procurement volumes for domestic Chinese homologation under NMPA cybersecurity rules.
- Luxury Vehicles:Active suspension calibration and steer-by-wire architectures define this tier. German OEM programs specify predictive damper control as standard, pulling chassis software development upstream into vehicle definition phases.
- Commercial Vehicles:Fleet operators specify predictive maintenance APIs as contract requirements rather than aftermarket options. Brake wear telemetry and suspension fatigue monitoring integrate into usage-based financing structures.
- Heavy-Duty Trucks:Energy recuperation systems and thermal management architectures address China's dual carbon mandates for new vehicle homologation. Integrated brake-by-wire dominates specification sheets.
Passenger vehicles hold the largest share; momentum sits with luxury vehicles.
Technology:
Cost tier stratification separates commodity embedded controllers from premium adaptive systems requiring silicon carbide power electronics.
- Adaptive Suspension:Predictive damper control algorithms operate at millisecond refresh rates, enabling real-time road surface compensation. Premium EV lineups specify these systems as standard equipment, displacing passive spring-damper assemblies.
- Energy Management Systems:Integrated thermal management and brake-by-wire recuperation architectures capture kinetic energy at the chassis level. China's national emissions reduction targets mandate these systems for new energy vehicle certification.
- Embedded Systems:Control modules operating at CAN-FD or Ethernet backbone speeds govern ride dynamics and trajectory execution. ISO 26262 ASIL-D functional safety certification commands premium engineering compensation.
- IoT Solutions:Over-the-air calibration updates and predictive maintenance telemetry connect chassis health data to fleet management platforms. Leasing companies embed these APIs into contract structures.
Embedded systems anchor current revenue; adaptive suspension is expanding most quickly.
End User:
Volume concentration varies by customer type, with OEMs driving platform standardization while aftermarket channels address legacy fleet retrofit demand.
- OEMs:Integrated drive-by-wire architectures compress tiered supplier hierarchies into unified platform ecosystems. NIO and BYD pursue captive chassis-electric powertrain interface control.
- Fleet Operators:Predictive maintenance integration and chassis health monitoring now appear as contract requirements. German commercial vehicle leasing companies lead this behavioral specification shift.
- Aftermarket Providers:Retrofit kits for adaptive suspension and energy management serve legacy diesel platforms during extended transition periods. Supply concentrates in specialized integration workshops.
- Research Institutions:Autonomous trajectory validation and steer-by-wire safety testing drive prototype procurement. UNECE WP.29 cybersecurity pre-certification programs anchor institutional demand.
OEMs command the largest share; aftermarket providers are gaining share fastest.
Application:
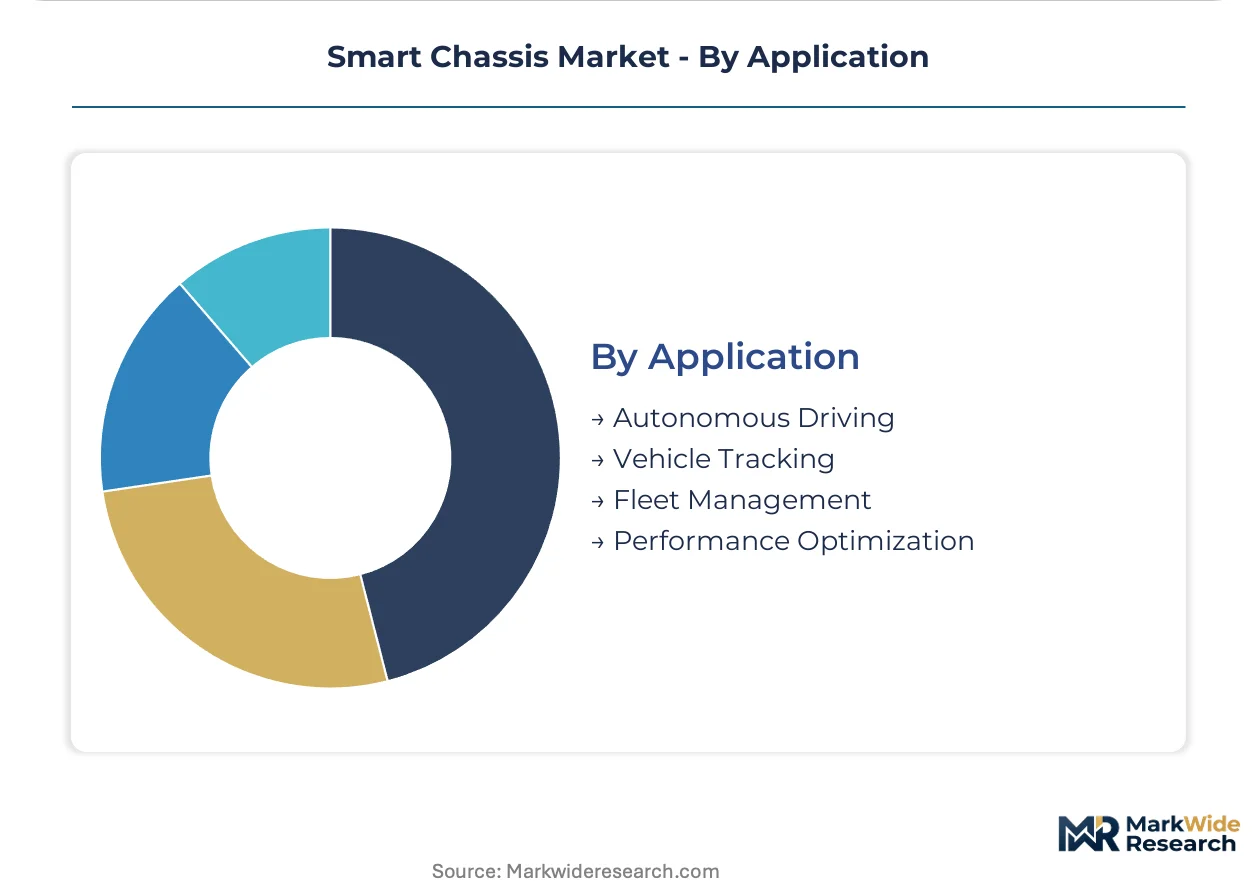
Maturity differentiation separates established fleet management deployments from emerging autonomous driving integrations requiring redundant control domains.
- Autonomous Driving:Redundant steer-by-wire and brake-by-wire architectures eliminate mechanical linkages for trajectory execution safety. UNECE WP.29 mandates encrypted chassis control domain access for these functions.
- Fleet Management:Chassis health telemetry integrates into usage-based financing and predictive maintenance scheduling. Brake wear and suspension fatigue data flow through standardized APIs.
- Vehicle Tracking:Embedded sensor arrays monitor location and operational status without full chassis control integration. Lower specification barriers attract mid-tier module vendors.
- Performance Optimization:Algorithmic refinement of damper calibration and energy recuperation settings shifts value capture from mechanical precision to software-defined tuning.
Fleet management holds the largest share; autonomous driving shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chassis module production concentrates in automotive engineering clusters where tier-1 suppliers maintain captive test facilities and homologation laboratories. Regulatory divergence between cybersecurity regimes fragments platform architectures across export markets.
China
NIO, BYD, and XPENG anchor domestic procurement volumes for intelligent chassis platforms under NMPA GB/T cybersecurity mandates. MIIT dual carbon goals mandate integrated brake-by-wire and thermal management for new energy vehicle certification. Shanghai and Shenzhen host the principal engineering centers where steer-by-wire calibration and domain controller integration occur.
Germany
ZF Friedrichshafen sustains premium OEM program leadership through systems integration depth for Mercedes-Benz and BMW architectures. UNECE WP.29 cybersecurity deadlines accelerate encrypted chassis control domain deployment. Stuttgart and Friedrichshafen concentrate functional safety engineering talent for ISO 26262 ASIL-D certification.
United States
NHTSA FMVSS braking and stability control validation shapes qualification pathways for suppliers seeking multi-region homologation. Commercial fleet operators specify predictive maintenance APIs as contract requirements. Michigan and California host the primary validation corridors where autonomous trajectory testing and redundant control domain verification proceed.
Japan
METI automotive technology roadmaps prioritize steer-by-wire safety architecture development for export market compliance. JIS standards govern chassis-mounted sensor array specifications. Nagoya and Tokyo metropolitan areas concentrate precision manufacturing for electromechanical actuator assemblies.
India
PLI scheme component-level incentives attract chassis module assembly investments serving domestic EV programs and export markets. BIS certification requirements for automotive electronics create localized compliance layers. Tamil Nadu and Maharashtra host emerging integration facilities where tier-2 suppliers establish module assembly operations.
Smart Chassis Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated platform specialists absorb sensor fusion and domain controller competencies previously held by separate ECU vendors. Three archetypes dominate: captive automotive groups with in-house chassis development, independent tier-1 systems integrators, and semiconductor-enabled platform providers. Competitive moves center on strategic partnerships for software stack access and capacity expansion for silicon carbide power electronics.
Within the captive automotive tier, NIO Inc. and BYD exemplify vertical control over chassis-electric powertrain interfaces. Among independent systems integrators, ZF Friedrichshafen occupies a position representing European engineering depth for premium OEM programs. These three anchors illustrate how competitive positioning splits between semiconductor-enabled newcomers and established mechanical precision incumbents.
| Leading Market Players |
|---|
| NIO Inc. |
| Qualcomm Technologies |
| SAIC Motor Corporation Limited |
| XPENG Motors |
| Great Wall Motor |
| BYD |
| ZF Friedrichshafen |
| Li Auto Inc. |
| Geely Holding Group |
| Others |
Pricing and Supply Chain Analysis
UNECE WP.29 cybersecurity mandates gate both supplier qualification and price differentiation simultaneously, forcing chassis module vendors to absorb encryption certification costs that stratify procurement tiers across European OEM programs and export markets.
Pricing Analysis
UNECE WP.29 dictates the pricing tier structure by mandating encrypted chassis control domain certification as a baseline qualification. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified steer-by-wire architectures from CAN-FD embedded controllers and basic sensor arrays. Cost compression in standard-tier modules is intensifying because silicon carbide substrate scarcity constrains high-voltage actuator rollout. Fleet operators exhibit highest price sensitivity, while luxury OEMs prioritize predictive damper calibration over unit economics.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes inject volatility into inbound logistics costs for silicon carbide wafers and rare earth magnets. Manufacturing concentrates in China, Germany, and Japan, with chassis module assembly drawing from Taiwanese semiconductor foundries and Australian lithium hydroxide refiners. Single-source vulnerability in permanent magnet refining corridors exposes actuator production to export quota disruptions. Distribution runs through tier-1 systems integrators that maintain captive homologation laboratories in Stuttgart, Shanghai, and Nagoya.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Smart Chassis Market is recovering from cyclical lows as electric vehicle platform refresh cycles accelerate OEM procurement of intelligent architectures.
For Market Incumbents: Consolidate sensor fusion competencies through targeted acquisition of domain controller specialists, as Ethernet backbone convergence threatens CAN-FD legacy positions. Deepen backward integration into silicon carbide power electronics to defend margin structures against semiconductor-enabled newcomers. Prioritize ISO 26262 ASIL-D certification investment for steer-by-wire functions to maintain premium OEM access. For New Entrants and Emerging Players: Predictive maintenance API integration for legacy diesel fleets represents an underserved service-layer gap where incumbents under-serve fleet operators during extended transition periods. India's PLI scheme component-level incentives offer the most penetrable geography for chassis module assembly investments serving domestic EV programs. Pursue direct fleet operator contracting to bypass tier-1 supplier gatekeeping. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across steer-by-wire and brake-by-wire architectures due to functional safety engineering talent scarcity and parallel-track homologation requirements. Target acquisition archetypes include mid-tier suppliers with captive ASIL-D certification capabilities and established NMPA GB/T compliance pathways. Monitor silicon carbide ingot supply expansion as the critical inflection signal for high-voltage actuator rollout viability.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Unified drive-by-wire architectures reduce OEM integration costs and compress tiered supplier hierarchies. |
| Battery Supply Agreement | Captive lithium cell sourcing secures chassis-integrated thermal management system cost predictability. |
| Software-Defined Vehicle Investment | Over-the-air calibration capabilities shift value capture from mechanical precision to algorithmic refinement. |
| Geographic Manufacturing Footprint | Tamil Nadu and Maharashtra assembly investments leverage India's PLI scheme for export market access. |
| Charging Infrastructure Partnership | Energy recuperation system integration with grid-connected charging optimizes fleet operator total cost of ownership. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and tier-1 supplier procurement data anchors the qualitative findings. Primary interviews with chassis module procurement leads, functional safety engineering directors, fleet operator maintenance managers, and aftermarket integration specialists combine with secondary validation from vehicle production databases, NMPA GB/T certification registries, UNECE WP.29 pre-homologation filings, and SEC supplier filings. Bottom-up segment sizing and top-down market triangulation reconcile volume estimates across passenger, luxury, and commercial vehicle classes.
Sensitivity analysis around silicon carbide substrate availability and rare earth magnet export quota scenarios informs the analytical framework. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster across the analysis window. CAGRs derive from regression analysis of historical procurement patterns and technology adoption curves. Forecast inputs incorporate NMPA cybersecurity deadline enforcement intensity and dual carbon mandate compliance trajectories.
Underlying assumptions cover sustained electric vehicle platform investment cycles and regulatory deadline adherence, with deviation risk concentrated in silicon carbide ingot supply expansion timelines and GB/T certification pathway fragmentation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Intelligent Traffic Management Market
Smart Transportation Solutions
Transportation Predictive Analytics Market
Smart Transportation Solutions
Global Connected Mobility Solutions Market
Smart Transportation Solutions
Mobility Technologies Market
Smart Transportation Solutions
Automatic Identification Systems (AIS) Market
Smart Transportation Solutions
Global Smart Parking Market
Smart Transportation Solutions
Sustainable Last-Mile Delivery Network Design Services Market
Smart Transportation Solutions
Mexico Ride Hailing Market
Smart Transportation Solutions
Autonomous Warehouse Charging Infrastructure Market
Smart Transportation Solutions
Automotive Vehicle to Everything (V2X) Market
Smart Transportation Solutions
Global Electric Public Transport Market
Smart Transportation Solutions
Automotive Platooning Systems Market
Smart Transportation Solutions
Smart Fleet Management Market
Smart Transportation Solutions
Transportation Analytics Market
Smart Transportation Solutions
Automotive Digital Mapping Market
Smart Transportation Solutions
Closed Platform Screen Doors Market