
 Road Weather Information Systems (RWIS) Market | 2026-2036
Road Weather Information Systems (RWIS) Market Size, Share, and Industry Trends Forecast 2026-2036
Road Weather Information Systems (RWIS) Market Insights
Modular sensor packages bundled with real-time data analytics are recalibrating how transportation authorities evaluate vendor proposals. Vaisala leverages its meteorological heritage to dominate atmospheric sensor accuracy benchmarks. Campbell Scientific anchors its position through ruggedized hardware designed for remote alpine deployments. Boschung America differentiates via integrated ice-detection systems that combine pavement sensors with automated treatment recommendations.
Road Weather Information Systems comprise networked environmental sensors, communication infrastructure, and decision-support software that monitor pavement temperature, atmospheric conditions, and visibility to inform winter maintenance and traffic operations. Typical fixed installations integrate remote processing units with ultrasonic wind sensors and non-invasive road surface probes transmitting data at sub-minute intervals to central traffic management centers. Sensor stations command the largest share of capital expenditure due to recurring calibration requirements and harsh-environment durability demands, while mobile units represent the fastest-expanding deployment category as fleets seek route-specific microclimate intelligence. Integrated systems capture disproportionate margin pools by embedding predictive algorithms that reduce chemical usage and labor dispatch costs.
The Federal Highway Administration Road Weather Management Program shapes United States procurement specifications, while the European Commission's ITS Directive mandates cross-border data interoperability for member state highway networks. State-level departments of transportation increasingly require NTCIP-compliant communication protocols, narrowing vendor qualification to suppliers with certified protocol stacks. Stakeholders must weigh the trade-off between proprietary analytics ecosystems and open-architecture platforms that simplify multi-vendor network expansion.
Market Dynamics
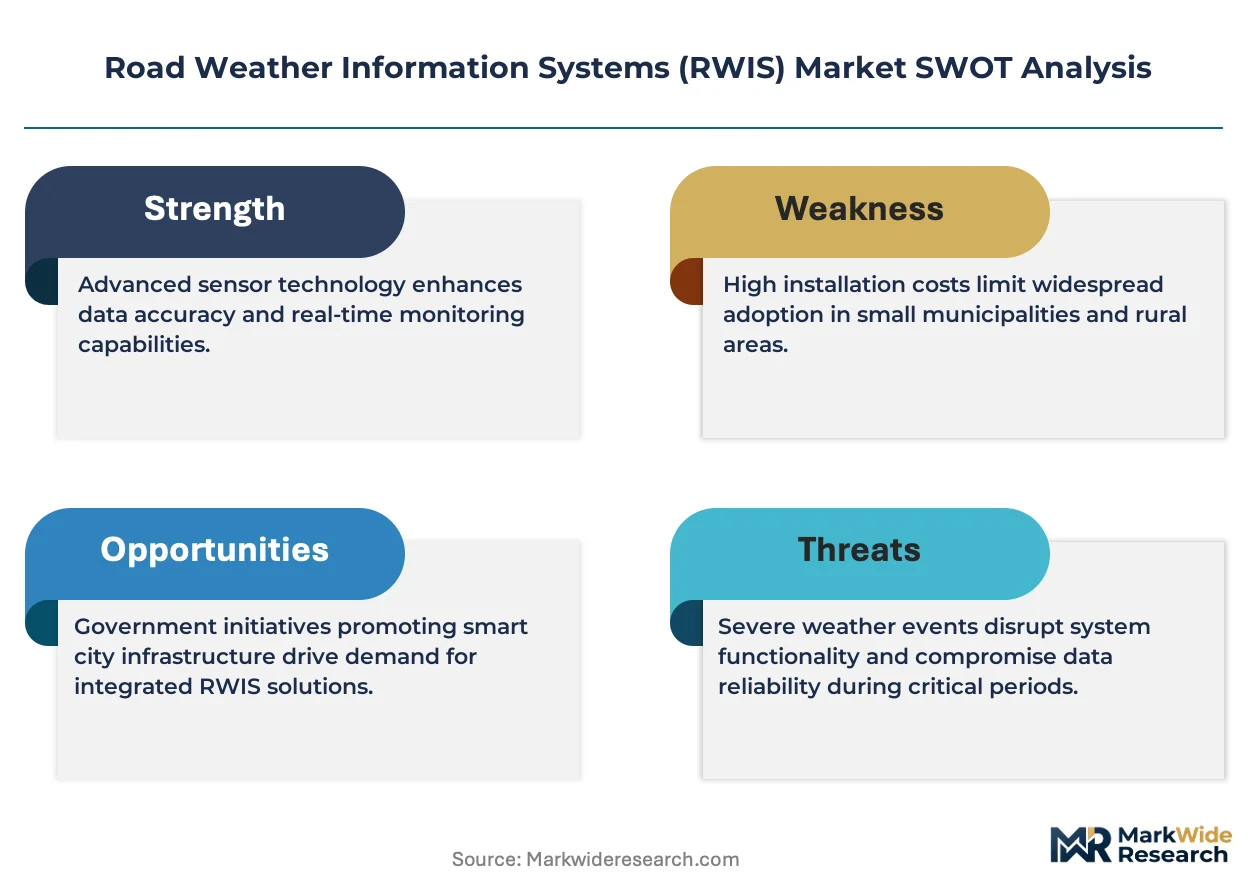
Fixed sensor station procurement is tightening around NTCIP-compliant protocol stacks, squeezing vendors without certified communication architectures out of state transportation department bidding pools.
Growth Catalysts
- Federal Highway Administration mandates:Road Weather Management Program specifications require sub-minute data transmission intervals, forcing network modernization cycles.
- Freeze-thaw corridor degradation:Mountainous state highway departments in Colorado, Utah, and Wyoming prioritize avalanche-risk monitoring to reduce road closure duration.
- Ultrasonic wind sensing:Non-mechanical atmospheric measurement eliminates moving-part maintenance in remote alpine installations.
Market Restraints
- Calibration cost structure:Annual sensor recertification consumes 15-20% of total lifecycle expenditure for fixed installations.
- Supply concentration in Nordic sensor foundries:Atmospheric probe manufacturing clusters in Finland and Sweden create single-source vulnerability.
- Proprietary analytics lock-in:Vendor-specific prediction algorithms complicate multi-supplier network expansion for transportation authorities.
Strategic Opportunities
- Mobile fleet penetration:Commercial trucking operators in Alberta and Quebec seek route-specific microclimate intelligence for hazmat transport.
- EU ITS Directive interoperability:Cross-border data standardization mandates create opening for protocol-certified vendors in Eastern European member states.
- LiDAR-thermal convergence:Combined pavement condition and atmospheric visibility sensing reduces hardware count per station.
Industry Challenges
- Field technician scarcity:Harsh-environment calibration and repair work struggles to attract skilled instrumentation specialists.
- Legacy SCADA integration:1990s-era traffic management centers require custom middleware to ingest modern JSON telemetry streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Road Weather Information Systems (RWIS) Market |
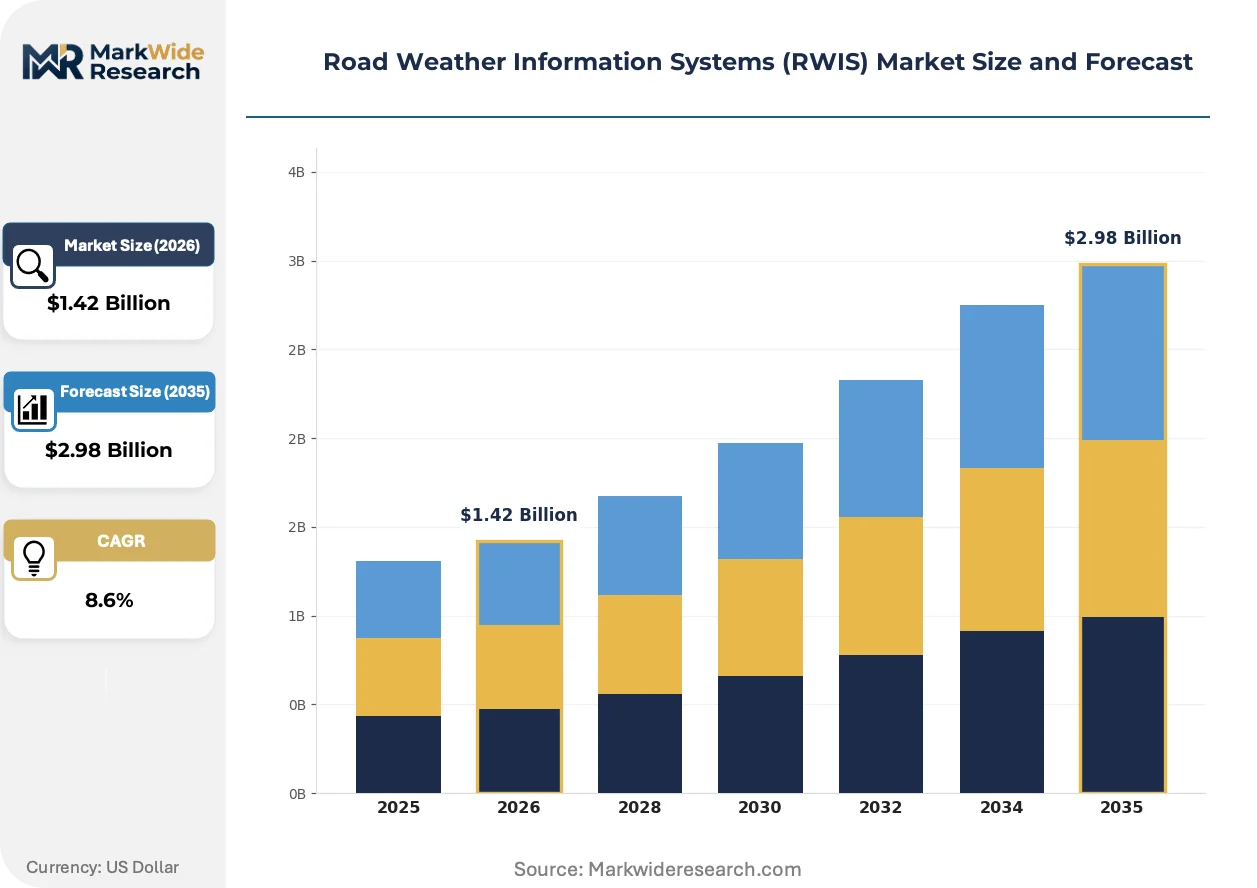
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensor Stations, Environmental Sensors, Cameras, Communication Units Deployment: Fixed Installations, Mobile Units, Portable Devices, Integrated Systems Application: Traffic Management, Snow Control, Emergency Services, Infrastructure Monitoring End User: Transportation Authorities, Municipalities, Road Maintenance Crews, Weather Forecasting Agencies |
| Companies Covered | High Sierra Electronics, Observator Group, Vaisala, Forest Technology Systems, Teconer, Campbell Scientific, Boschung America, MTX, OTT HydroMet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Road Weather Information Systems (RWIS) Market Trends and Innovations
Real-time analytics is compressing decision latency from hours to minutes, reshaping how maintenance dispatchers allocate chemical treatment resources during storm events.
Edge computing architectures are unifying sensor preprocessing with localized inference engines. State departments of transportation in Minnesota and Wisconsin are piloting these configurations to reduce backhaul bandwidth costs. The technology is unifying hardware and software procurement decisions into single-vendor evaluation frameworks.
REACH substance restrictions on heavy metals in electronics are forcing sensor housing material transitions. European vendors are accelerating aluminum-to-engineered-polymer substitutions ahead of compliance deadlines. Station manufacturers serving EU member state contracts face accelerated redesign cycles.
Performance-based service contracts are displacing capital purchase models for mobile RWIS deployments. Fleet operators now demand guaranteed uptime thresholds with vendor-managed maintenance. This shift is most visible among Canadian provincial trucking associations seeking operational expenditure predictability.
Road Weather Information Systems (RWIS) Market Segmentation
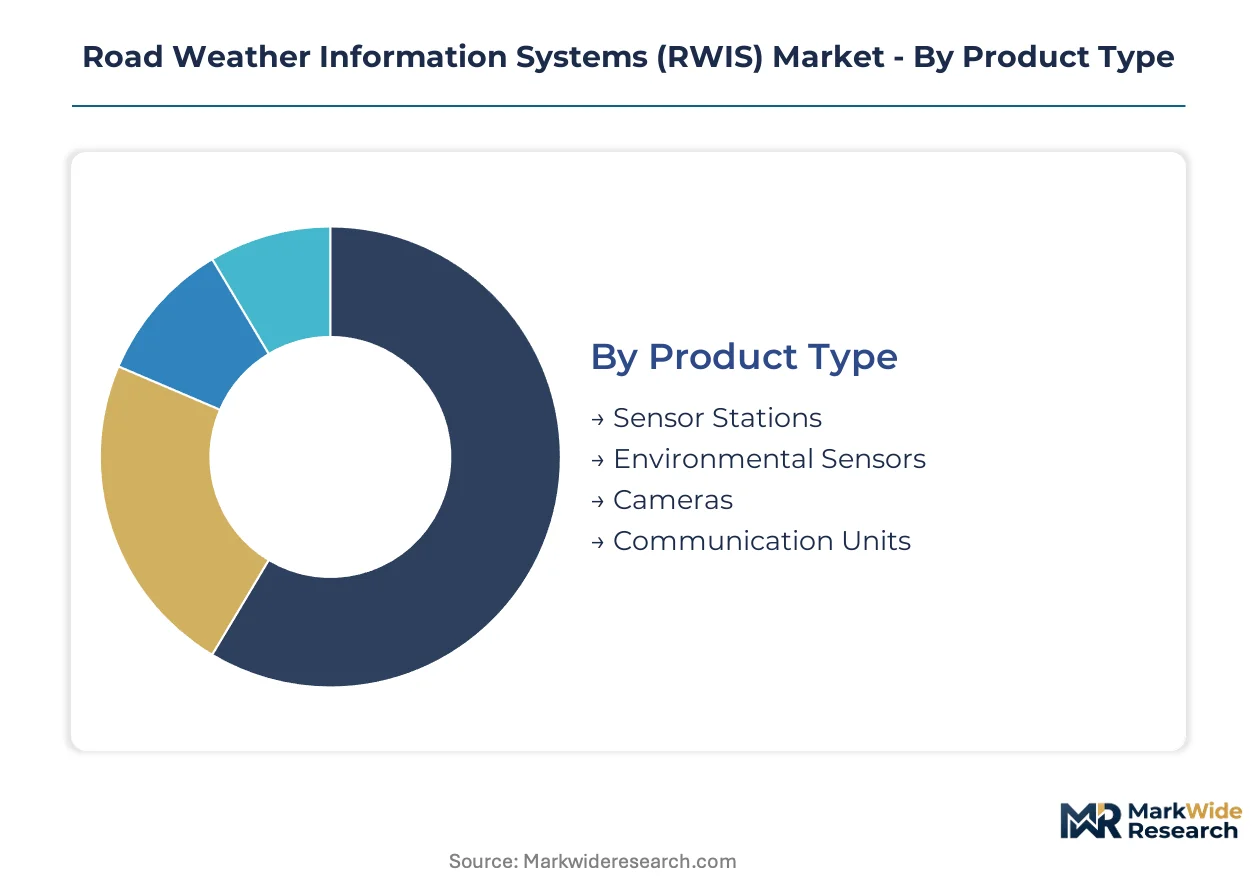
Road Weather Information Systems procurement diverges sharply across hardware categories, deployment models, and operational applications. Capital allocation patterns reveal where transportation authorities prioritize network density versus analytical sophistication.
Product Type:
Capital intensity concentrates in integrated hardware packages requiring field calibration infrastructure and multi-year durability specifications.
- Sensor Stations:Enclosures house remote processing units, power systems, and telemetry hardware rated for sub-zero operation. State departments of transportation in Colorado and Utah prioritize avalanche-risk corridors for dense station placement. Annual recertification consumes 15-20% of lifecycle budgets.
- Environmental Sensors:Atmospheric probes measure temperature, humidity, wind speed, and precipitation with ultrasonic or mechanical transduction. Nordic manufacturing clusters in Finland and Sweden supply precision instrumentation to North American procurement channels. REACH substance restrictions are accelerating aluminum-to-polymer housing transitions.
- Cameras:Visible-spectrum and thermal imaging units provide visibility verification and incident confirmation.
- Communication Units:NTCIP-compliant protocol stacks enable standardized data exchange with legacy traffic management centers.
Sensor Stations absorb the bulk of installed capacity; Environmental Sensors are expanding most quickly through modular retrofit programs.
Deployment:
Operational permanence versus mobility determines procurement contract structures and vendor qualification requirements.
- Fixed Installations:Permanent roadside infrastructure with buried pavement probes and mast-mounted atmospheric sensors. Federal Highway Administration Road Weather Management Program mandates sub-minute transmission intervals, forcing modernization cycles at aging sites. Harsh-environment calibration work struggles to attract skilled technicians.
- Integrated Systems:Combined hardware-software packages embed predictive algorithms for treatment optimization. Minnesota and Wisconsin pilots are unifying edge computing with localized inference engines. Single-vendor evaluation frameworks now cover both equipment and analytics procurement.
- Mobile Units:Vehicle-mounted sensors provide route-specific microclimate intelligence for commercial fleets.
- Portable Devices:Temporary deployments for construction zones or emergency response staging areas.
Fixed Installations dominate capital expenditure; Mobile Units are climbing the fastest through performance-based service contracts with Canadian provincial trucking associations.
Application:
Functional priority shapes sensor configuration density and data latency requirements across operational scenarios.
- Snow Control:Pavement temperature monitoring combined with automated treatment recommendations. Boschung America's integrated ice-detection systems reduce chemical usage through real-time dispatch algorithms. Wyoming highway departments prioritize rapid deployment to minimize road closure duration.
- Traffic Management:Visibility and surface condition data fed directly to dynamic message signs and speed limit systems. European Commission ITS Directive mandates cross-border data interoperability for member state networks. Protocol-certified vendors gain preferential access to Eastern European procurement.
- Emergency Services:Hazmat transport routing and incident response coordination.
- Infrastructure Monitoring:Long-term pavement degradation tracking and bridge deck thermal stress analysis.
Snow Control commands the densest sensor placement; Traffic Management is gaining share fastest through centralized command center integration.
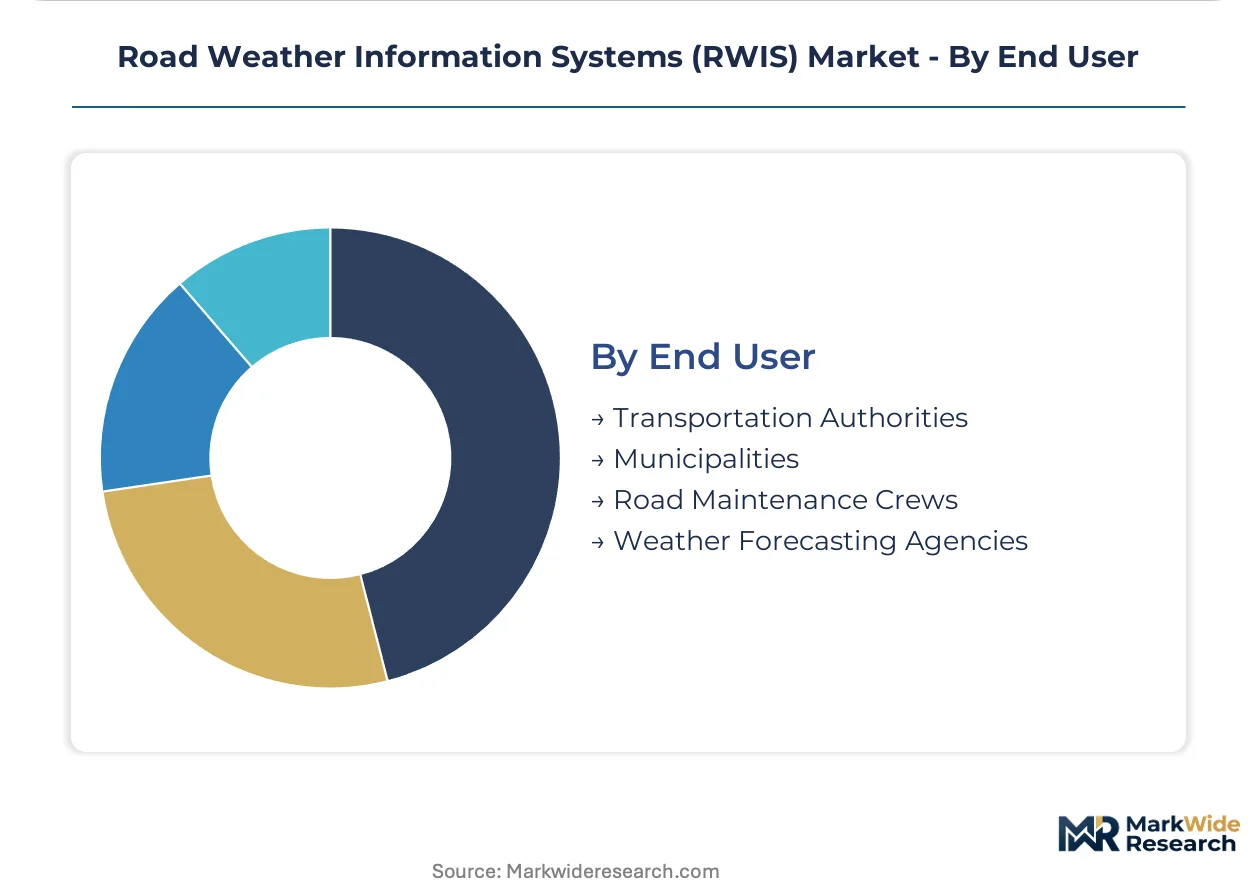
End User:
Budget authority and technical staffing capacity segment purchasing behavior across institutional categories.
- Transportation Authorities:State and provincial departments of transportation with centralized procurement and network-wide standardization mandates. NTCIP compliance requirements narrow vendor pools to suppliers with certified protocol architectures. Multi-year maintenance contracts bundle calibration and firmware updates.
- Road Maintenance Crews:Field operations units requiring ruggedized handheld units and simplified diagnostic interfaces.
- Municipalities:Local governments with limited technical staffing and budget constraints favoring turnkey service agreements.
- Weather Forecasting Agencies:National meteorological services integrating roadside data with atmospheric modeling systems.
Transportation Authorities control the majority of network deployment; Road Maintenance Crews are expanding most quickly through mobile fleet penetration in Alberta and Quebec.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in the UAE and special economic corridors in Saudi Arabia are channeling infrastructure investment toward intelligent transportation systems. Nordic manufacturing clusters supply precision atmospheric sensors to North American procurement channels. Cold-climate corridors across multiple continents drive dense sensor network deployment.
United States
State transportation departments in Colorado, Utah, and Wyoming prioritize avalanche-risk monitoring to minimize highway closure duration. The Federal Highway Administration Road Weather Management Program mandates sub-minute data transmission intervals, forcing network modernization at aging installations. Minneapolis-St. Paul serves as a testbed for edge-computing pilot programs unifying sensor preprocessing with localized inference engines.
Canada
Provincial trucking associations in Alberta and Quebec are adopting performance-based service contracts for mobile fleet deployments. Transport Canada harmonizes winter maintenance standards with US protocols under the Beyond the Border initiative. Montreal-based operators demand guaranteed uptime thresholds with vendor-managed maintenance for hazmat transport corridors.
Germany
Baden-Württemberg and Bavaria anchor automotive corridor monitoring where pavement thermal stress analysis protects high-value freight routes. The KBA enforces ITS-G5 communication standards for vehicle-to-infrastructure integration. Stuttgart's industrial automation sector supplies calibration equipment to alpine sensor networks in Austria and Switzerland.
Sweden
Nordic sensor foundries in Uppsala and Linköping manufacture precision atmospheric probes for export to North American markets. REACH substance restrictions on heavy metals accelerate aluminum-to-engineered-polymer housing transitions. The Swedish Transport Administration mandates cross-border data interoperability with Norwegian and Finnish highway networks under Nordic cooperation frameworks.
Japan
Expressway operators in the Tohoku and Hokkaido regions deploy ultrasonic wind sensors to eliminate moving-part maintenance in heavy snowfall zones. METI subsidizes smart infrastructure upgrades through the Society 5.0 initiative. Nagoya's precision manufacturing cluster produces non-invasive road surface probes for domestic and Southeast Asian export markets.
Road Weather Information Systems (RWIS) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers. The vendor base organizes around three strategic archetypes: meteorological heritage firms leveraging atmospheric sensing credibility, ruggedized hardware specialists targeting remote alpine installations, and integrated system providers bundling sensors with predictive analytics. Consolidation pressure intensifies as transportation authorities narrow bidding pools to NTCIP-compliant protocol architects. Capacity expansion and strategic partnerships dominate competitive moves as vendors seek to anchor multi-year maintenance contracts.
Within the meteorological heritage tier, Vaisala and OTT HydroMet represent established atmospheric sensing franchises. Campbell Scientific anchors the ruggedized hardware segment through its designation as a scientific instrumentation supplier. Boschung America occupies a position within the integrated systems archetype, exemplifying vendors that combine pavement sensors with automated treatment recommendation engines. These three entities illustrate the competitive spectrum from component specialization to full-stack service provision.
| Leading Market Players |
|---|
| High Sierra Electronics |
| Observator Group |
| Vaisala |
| Forest Technology Systems |
| Teconer |
| Campbell Scientific |
| Boschung America |
| MTX |
| OTT HydroMet |
| Others |
Pricing and Supply Chain Analysis
Field instrumentation specialists concentrated in Uppsala and Linköping command wage premiums that compress margin spreads between premium-tier and economy-tier sensor packages. Labor-cost differentials between Nordic manufacturing clusters and Eastern European assembly operations widen pricing-tier spreads across the European procurement landscape.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to NTCIP-certified protocol stacks needed for Federal Highway Administration compliance timelines, while spot inventory of non-certified alternatives trades at discounted levels. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because transportation authorities consolidate vendor pools around certified architectures. State departments of transportation exhibit the highest price sensitivity due to centralized procurement mandates, while commercial fleet operators in Alberta and Quebec show greater tolerance for premium pricing under performance-based service contracts.
Supply Chain Analysis
Direct-to-transportation-authority channels handle hyperscale procurement volumes from state departments in Colorado, Utah, and Wyoming, while systems integrators serve mid-tier municipal buyers. Atmospheric probe manufacturing concentrates in Finland, Sweden, and Japan, with non-invasive road surface probe fabrication anchored in Nagoya's precision manufacturing cluster. Supply chains draw from engineered polymers, ultrasonic transducers, and edge-computing chipsets as critical inputs. Single-source vulnerability in Nordic sensor foundries creates exposure to REACH substance restriction compliance delays. Distribution runs through certified systems integrators for complex integrated deployments and direct manufacturer relationships for standardized sensor station replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Road Weather Information Systems sector is transitioning from mechanical to solid-state sensing architectures, with ultrasonic and LiDAR-thermal convergence displacing legacy moving-part instrumentation. This technology replacement cycle compresses product lifecycles and recalibrates vendor qualification criteria.
For Market Incumbents: Hedge against proprietary analytics lock-in by embedding open-architecture protocol stacks that simplify multi-vendor network expansion for transportation authorities. Deepen backward integration into engineered polymer housing production ahead of REACH compliance deadlines to defend margin position against material cost volatility. Prioritize certification investment in NTCIP-compliant communication architectures to maintain bidding eligibility as state procurement specifications tighten. For New Entrants and Emerging Players: Begin with mobile fleet deployments in Canadian provincial trucking associations, where performance-based service contracts create accessible entry points without competing for fixed-installation capital budgets. Target hazmat transport corridors in Alberta and Quebec as the most penetrable application segment given operational expenditure predictability demands. Pursue a route-specific microclimate intelligence go-to-market angle that emphasizes guaranteed uptime thresholds with vendor-managed maintenance. For Investors and Strategic Acquirers: The window for entry favors protocol-certified mid-cap specialists with established NTCIP stack architectures and multi-year maintenance contract backlogs. Long-term viability hinges on positioning for the edge-computing unification trend where sensor preprocessing and localized inference engines merge procurement decisions. Watch for Federal Highway Administration mandate expansion beyond sub-minute transmission intervals as the inflection signal indicating accelerated network modernization cycles.| Strategic Initiative | Industry Significance |
|---|---|
| NTCIP Protocol Certification | Federal Highway Administration mandates squeeze non-certified vendors from state bidding pools. |
| Edge Computing Pilot Expansion | Minnesota and Wisconsin deployments validate unified hardware-software procurement frameworks. |
| Mobile Fleet Service Contracts | Alberta and Quebec trucking associations shift capital expenditure to operational predictability models. |
| REACH Compliance Redesign | European vendors accelerate aluminum-to-polymer transitions ahead of heavy metals restrictions. |
| Cross-Border Data Interoperability | EU ITS Directive creates procurement openings for protocol-certified vendors in Eastern Europe. |
Research Methodology
Trade association filings, customs and import-export records, and Federal Highway Administration procurement databases formed the secondary backbone of this analysis. Primary interviews with state transportation department procurement officers, winter maintenance dispatch supervisors, systems integration engineers, and atmospheric sensor calibration technicians combined with secondary validation through bottom-up and top-down triangulation. The research synthesized equipment shipment records, maintenance contract disclosures, and regulatory compliance filings to construct market sizing and competitive positioning assessments.
Bottom-up approaches modeled installed base expansion across fixed installations, mobile units, and portable devices, while top-down validation cross-checked against transportation authority capital expenditure disclosures. Segmentation dimensions included product type, deployment model, application function, and end-user category across the analysis window. CAGRs were derived from equipment replacement cycles, mandate-driven modernization timelines, and fleet penetration trajectories. Forecast inputs incorporated Federal Highway Administration Road Weather Management Program specification evolution and EU ITS Directive implementation pace.
Underlying measurement precision varies by segment; fixed installation sensor stations carry tighter precision than emerging mobile fleet categories due to established procurement reporting requirements. Forecasts reflect assumptions regarding mandate enforcement consistency, supply chain resilience in Nordic manufacturing clusters, and transportation authority budget allocation stability. Periodic stress-testing of base assumptions is recommended given regulatory timeline uncertainty and field technician scarcity risks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
US Smart Highway Market
Smart Transportation Solutions
North America IoT Transportation Market
Smart Transportation Solutions
Micro Mobility Market
Smart Transportation Solutions
Fleet Management Software Market
Smart Transportation Solutions
Smart Parking Systems Market
Smart Transportation Solutions
Automotive Digital Mapping Market
Smart Transportation Solutions
Global Crowdsourced Smart Parking Market
Smart Transportation Solutions
Smart Parking Technologies Market
Smart Transportation Solutions
Fleet Health Monitoring and Diagnostic Analytics Systems Market
Smart Transportation Solutions
Mobility As a Service Market
Smart Transportation Solutions
Vietnam Ride-Hailing Market
Smart Transportation Solutions
Traffic Monitoring Market
Smart Transportation Solutions
Big Data Analytics in Transportation Market
Smart Transportation Solutions
Automotive Platooning Systems Market
Smart Transportation Solutions
Mexico Ride Hailing Market
Smart Transportation Solutions
France Ridesharing Market