
 Global Intelligent Traffic Management System Market | 2026-2036
Global Intelligent Traffic Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Intelligent Traffic Management System Market Foresight
ISO 39001 certification for road traffic safety management systems is collapsing the vendor qualification cycle, forcing smaller integrators to either absorb compliance costs or exit procurement frameworks entirely. Siemens leverages its embedded hardware-software stack to dominate European urban corridor contracts. Kapsch TrafficCom anchors its position through captive tolling-to-urban expansion pathways across multiple continents. Cisco Systems competes on edge-computing infrastructure density, positioning its networking layer as the connective tissue for multi-vendor deployments.
An intelligent traffic management system comprises sensor arrays, edge processors, and centralized software platforms that ingest real-time vehicle flow data to dynamically adjust signal timing, detect incidents, and coordinate multimodal transit priority. These systems typically operate on sub-100-millisecond latency thresholds to prevent cascade congestion events in high-density corridors. Adaptive signal control technology leads deployment value where legacy fixed-timing infrastructure requires phased replacement, while cloud computing platforms represent the fastest-expanding margin pool as municipalities shift from capital-intensive on-premise installations to subscription-based traffic analytics services. Software platforms capture disproportionate recurring revenue compared to hardware components, which face commoditization pressure from Asian electronics manufacturers.
The U.S. Department of Transportation's MUTCD compliance requirements and the European Union's CE marking under the Radio Equipment Directive jointly determine which sensor and communication modules gain market access in their respective jurisdictions. India's BIS certification for intelligent transport system equipment adds a third qualification layer that shapes vendor prioritization for emerging-economy tenders. Stakeholders must monitor how algorithmic auditing mandates from the EU AI Act propagate into procurement specifications beyond European borders, as this will determine which platform architectures require fundamental redesign versus incremental compliance patching.
Market Dynamics
The transition from capital-intensive hardware procurement to subscription-based traffic analytics services is compressing vendor margins while elevating software platforms to the primary value-capture layer in municipal contracts.
Growth Catalysts
- EU AI Act algorithmic auditing mandates:European procurement specifications now require explainable AI decision trails in signal control systems, creating qualified vendor scarcity that benefits compliant integrators.
- India's smart-city corridor mandates:Central government directives in Delhi, Mumbai, and Bangalore are accelerating integrated corridor management system deployment through standardized tender templates.
- Edge-computing latency thresholds:Sub-100-millisecond real-time processing requirements for cascade congestion prevention are driving sensor-to-cloud architecture upgrades in high-density urban corridors.
Market Restraints
- ISO 39001 certification compliance costs:Road traffic safety management system accreditation is forcing smaller integrators to absorb substantial audit expenses or exit procurement frameworks entirely.
- Asian electronics manufacturing commoditization:Hardware sensor and communication module production concentration in East Asian supply chains is eroding equipment margins for system integrators.
- Legacy fixed-timing infrastructure replacement cycles:Phased municipal capital budgeting for adaptive signal control technology extends payback periods and delays full-system modernization.
Strategic Opportunities
- Cloud-based subscription analytics services:Municipalities shifting from on-premise installations to recurring-revenue traffic management platforms represent the fastest-expanding margin pool for software vendors.
- Multimodal transit priority integration:Bus rapid transit and bicycle corridor signal preemption applications are opening new deployment verticals beyond private vehicle optimization.
- EU AI Act regulatory propagation:Algorithmic governance frameworks are reshaping vendor qualification requirements in Middle Eastern and Southeast Asian procurement specifications, creating first-mover advantage for compliant architectures.
Industry Challenges
- Cross-jurisdiction certification stacking:U.S. MUTCD compliance, EU CE marking under the Radio Equipment Directive, and India's BIS certification for intelligent transport system equipment create fragmented qualification timelines for global vendors.
- Multi-vendor deployment integration complexity:Edge-computing infrastructure from networking specialists must interoperate with legacy signal controllers, requiring custom protocol translation layers that extend commissioning cycles.
- Real-time data fusion skill scarcity:Traffic engineering teams lack personnel capable of calibrating machine learning models for incident detection across heterogeneous sensor arrays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Intelligent Traffic Management System Market |
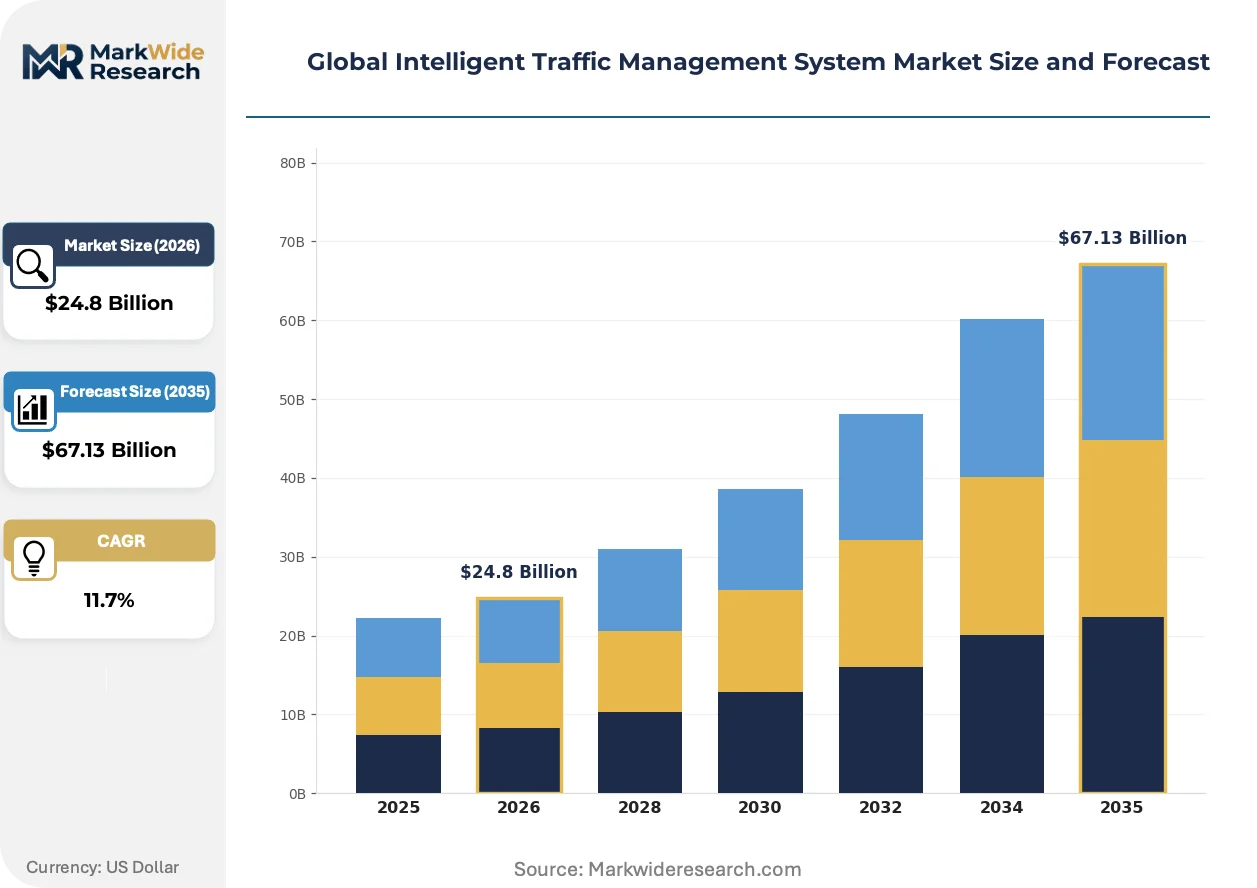
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $67.13 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Traffic Sensors, Control Units, Communication Modules, Software Platforms, Data Analytics Tools Technology: Adaptive Signal Control, Video Detection Systems, Wireless Sensor Networks, GPS Tracking, Cloud Computing Application: Congestion Management, Incident Detection, Parking Management, Public Transit Coordination, Emission Control End User: Municipal Authorities, Traffic Operation Centers, Transportation Consultants, Infrastructure Developers |
| Companies Covered | Siemens, Thales, Cubic Corporation, IBM, Kapsch TrafficCom, TransCore, Cisco Systems, TomTom, Teledyne FLIR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Intelligent Traffic Management System Market Shifts & Advancements
Software-defined traffic infrastructure is decoupling control logic from proprietary hardware, enabling municipal buyers to unbundle procurement and pit specialized vendors against one another in layered system architecture competitions.
Edge-native artificial intelligence inference engines are supplanting centralized cloud processing for real-time signal optimization. Municipal authorities in Singapore and the Netherlands are deploying these distributed architectures to eliminate round-trip latency in emergency vehicle preemption scenarios. This shift is compressing the addressable market for legacy centralized traffic management platforms while expanding opportunities for semiconductor vendors with automotive-grade edge processor portfolios.
The EU AI Act's risk-based classification system for automated decision-making in transport infrastructure is mandating algorithmic impact assessments and human-in-the-loop override capabilities. European urban corridor contracts now specify documentation burdens that favor vendors with embedded compliance engineering teams. System integrators serving Germany and France are restructuring platform architectures to generate auditable decision logs without degrading sub-second response times.
Municipal procurement officers are unbundling long-term service contracts from initial system deployment, separating hardware installation from ongoing traffic analytics subscriptions. This disintermediation of the traditional single-vendor model is visible in California and Texas corridor tenders, where cities award edge infrastructure to networking specialists while contracting signal optimization software to specialized analytics firms. The shift is fragmenting vendor relationships and compressing contract renewal cycles from decade-long maintenance agreements to annual software license negotiations.
Global Intelligent Traffic Management System Market Segmentation
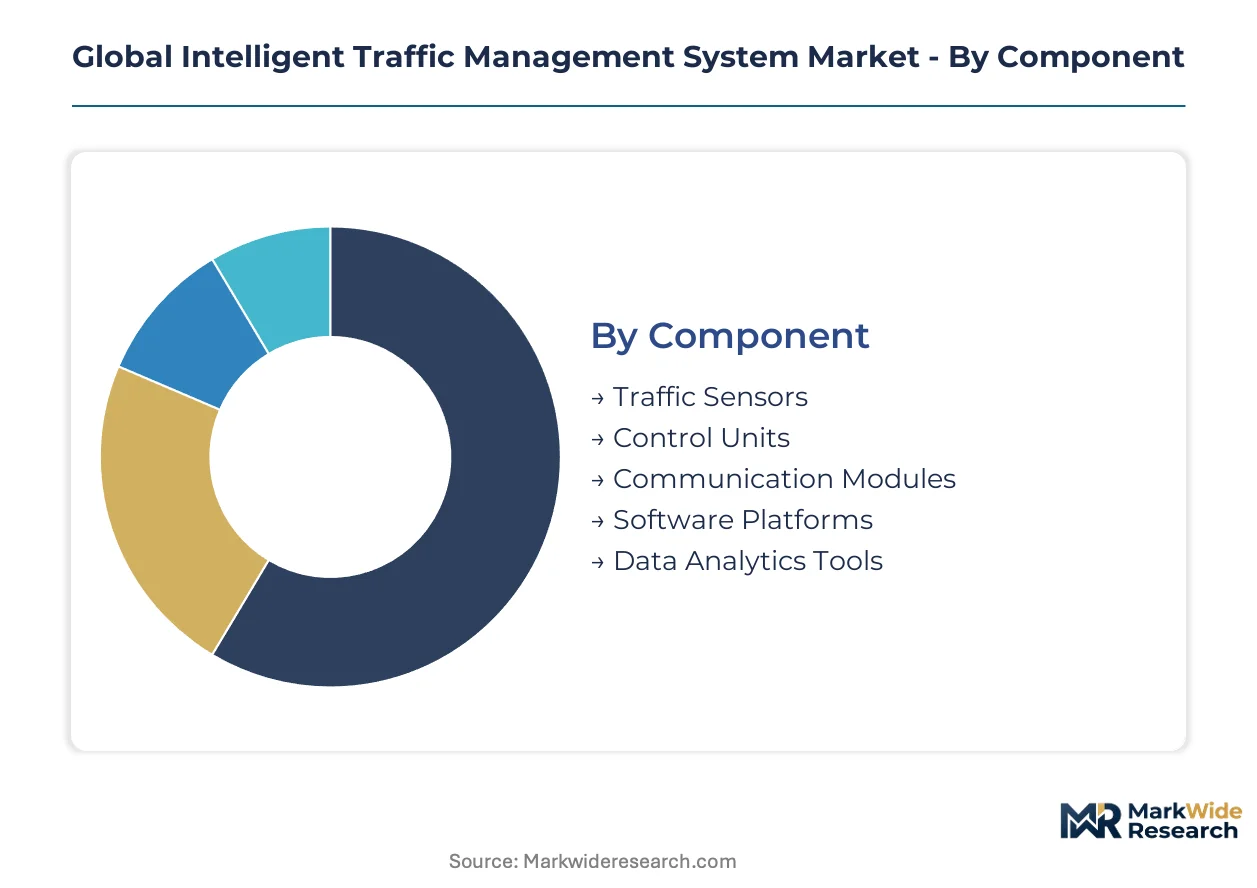
Segmentation in intelligent traffic management systems reveals how procurement channels fragment across hardware, software, and service layers. Municipal buyers unbundle component sourcing from analytics subscriptions, reshaping vendor relationships and margin capture across the value chain.
Component:
Hardware components flow through systems integrators with ISO 39001 certification, while software platforms increasingly route direct to municipal IT procurement channels.
- Traffic Sensors:Inductive loops, radar, and LiDAR arrays embedded in roadway infrastructure detect vehicle presence, speed, and classification. Demand concentrates in Delhi, Mumbai, and Bangalore where India's smart-city mandates require high-density sensor deployment for corridor management.
- Software Platforms:Centralized and edge-distributed applications orchestrate signal timing, incident response, and multimodal coordination. Procurement is shifting to subscription models in California and Texas corridor tenders, compressing traditional maintenance contract cycles.
- Control Units:Signal controllers and edge processors execute real-time optimization algorithms with sub-100-millisecond latency requirements.
- Communication Modules:DSRC and C-V2X transceivers enable vehicle-to-infrastructure data exchange under FCC and CE marking compliance frameworks.
- Data Analytics Tools:Machine learning pipelines for congestion prediction and emission modeling operate on cloud infrastructure.
Control units dominate installed base. Software platforms are where expansion concentrates.
Technology:
Technology selection tracks municipal maturity curves, with advanced economies prioritizing latency-critical edge architectures while emerging markets build foundational detection layers.
- Adaptive Signal Control:Real-time algorithms adjust signal phasing based on detected demand, replacing fixed-timing schedules. Deployment concentrates in European urban corridors where EU AI Act mandates require explainable decision trails and human-in-the-loop override capabilities.
- Cloud Computing:Centralized traffic analytics platforms enable subscription-based service models and predictive maintenance. Singapore and Netherlands authorities are deploying edge-native alternatives to eliminate round-trip latency in emergency preemption scenarios.
- Video Detection Systems:Camera-based vehicle and pedestrian recognition feeds incident detection and violation enforcement.
- Wireless Sensor Networks:Mesh deployments of battery-powered nodes extend coverage to unsignalized intersections and rural corridors.
- GPS Tracking:Fleet probe data supplements fixed infrastructure for network-wide travel time estimation.
Video detection systems dominate installed base. Cloud computing is gaining share fastest.
Application:
Application prioritization reflects municipal pain points, with congestion and incident response commanding capital budgets while sustainability-linked programs compete for grant funding.
- Congestion Management:Network-wide signal coordination and dynamic routing guidance target throughput maximization. Demand concentrates in megacity corridors where cascade failure risks justify sub-100-millisecond latency infrastructure investments.
- Public Transit Coordination:Bus rapid transit signal preemption and multimodal priority integration open deployment verticals beyond private vehicle optimization. European tenders specify these capabilities under EU Green Deal mobility targets.
- Incident Detection:Automated collision identification and emergency response dispatch reduce secondary accident rates.
- Parking Management:Guidance systems and dynamic pricing reduce curb search traffic in central business districts.
- Emission Control:Signal optimization for stop-and-go minimization supports air quality compliance in low-emission zones.
Congestion management dominates installed base. Public transit coordination is climbing the fastest.
End User:
End-user procurement authority determines contract structure, with municipal direct purchases favoring unbundled component sourcing while centralized operators consolidate multi-city analytics platforms.
- Municipal Authorities:City transportation departments hold primary procurement authority for corridor-specific deployments. India's standardized tender templates in Delhi, Mumbai, and Bangalore accelerate integrated system adoption through centralized mandates.
- Traffic Operation Centers:Regional control facilities manage real-time operations across multiple jurisdictions. These entities concentrate software platform demand where cloud-based subscription models enable shared infrastructure costs across participating municipalities.
- Transportation Consultants:Engineering firms specify system architectures and oversee commissioning for municipal clients.
- Infrastructure Developers:Private concessionaires deploy systems under build-operate-transfer arrangements for toll roads and managed lanes.
Municipal authorities dominate installed base. Traffic operation centers are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government mandates for smart-city corridors and algorithmic governance frameworks are concentrating procurement authority in specific national jurisdictions, reshaping vendor qualification requirements and deployment timelines.
United States
The Federal Highway Administration's MUTCD compliance requirements govern sensor and communication module market access, while California and Texas corridor tenders unbundle edge infrastructure from signal optimization software. Dallas and Houston traffic operation centers are shifting to annual software license negotiations, fragmenting traditional decade-long maintenance agreements.
Germany
KBA vehicle safety standards and EU AI Act algorithmic auditing mandates require explainable decision trails in signal control systems, creating qualified vendor scarcity. Munich and Stuttgart urban corridor contracts specify documentation burdens that favor integrators with embedded compliance engineering teams.
India
Central government smart-city mandates through BIS certification for intelligent transport system equipment are accelerating integrated corridor management deployment. Delhi, Mumbai, and Bangalore standardized tender templates concentrate demand for high-density sensor arrays and adaptive signal control technology.
Singapore
Land Transport Authority directives prioritize edge-native artificial intelligence inference engines to eliminate round-trip latency in emergency vehicle preemption scenarios. The city-state's distributed architectures are compressing the addressable market for legacy centralized traffic management platforms.
Netherlands
EU Green Deal mobility targets specify bus rapid transit signal preemption and multimodal priority integration in Rotterdam and Amsterdam tenders. Dutch authorities are deploying edge-computing infrastructure to meet sub-100-millisecond latency thresholds for cascade congestion prevention.
Global Intelligent Traffic Management System Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with embedded hardware-software stacks, creating tiered competition between full-stack integrators and specialized component vendors. Siemens, Kapsch TrafficCom, and Cisco Systems anchor distinct strategic positions across European, tolling-to-urban, and edge-computing vectors respectively. Market structure rewards captive supply chain control and regulatory pre-certification. Dominant competitive moves include portfolio diversification into multimodal transit priority applications and geographic expansion through standardized tender template adaptation.
Within the full-stack integrator tier, Siemens leverages its embedded hardware-software architecture to dominate European urban corridor contracts. Kapsch TrafficCom occupies a position anchored through tolling-to-urban expansion pathways across multiple continents. Cisco Systems exemplifies the networking-layer specialist competing on edge-computing infrastructure density as connective tissue for multi-vendor deployments.
| Leading Market Players |
|---|
| Siemens |
| Thales |
| Cubic Corporation |
| IBM |
| Kapsch TrafficCom |
| TransCore |
| Cisco Systems |
| TomTom |
| Teledyne FLIR |
| Others |
Supply & Pricing Matrix
East Asian sensor manufacturing scale at 70-80 percent utilization anchors global hardware cost floors, compressing margins for system integrators while concentrating procurement leverage among semiconductor vendors with automotive-grade edge processor portfolios. Municipal buyers exploit this concentration through unbundled tender structures that pit networking specialists against analytics firms in layered architecture competitions.
Pricing Analysis
Certification level (ISO 39001/CE marking/BIS-grade) creates the primary spread between qualified integrators and commodity hardware vendors. Three-tier pricing structure across premium, standard, and economy levels reflects compliance engineering depth, with EU AI Act algorithmic auditing mandates adding documentation premiums to European contracts. Cost compression in hardware tiers is intensifying because Asian electronics manufacturing commoditization erodes equipment margins. Municipal authorities in India exhibit highest price sensitivity due to standardized tender templates, while German traffic operation centers prioritize compliance over unit cost.
Supply Chain Analysis
Taiwan Strait semiconductor transit underwrites global edge processor availability for sub-100-millisecond latency infrastructure. Manufacturing concentrates in China, South Korea, and Taiwan for LiDAR arrays, radar modules, and DSRC transceivers. Raw material dependencies span silicon wafers, rare earth magnets, and copper for inductive loop deployment. Single-source vulnerability concentrates in automotive-grade GPU supply for AI inference engines. Distribution runs through systems integrators with ISO 39001 certification, though software platforms increasingly route direct to municipal IT procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where EU AI Act pre-certification creates switching costs that entrench compliant incumbents against emerging software-defined challengers.
For Market Incumbents: Compound embedded compliance engineering capabilities to capture algorithmic auditing premiums in European and Middle Eastern tenders. Absorb ISO 39001 certification costs to force smaller integrators toward exit, consolidating procurement framework access. Prioritize multimodal transit priority integration as defensive expansion against pure-play analytics entrants. For New Entrants and Emerging Players: BIS certification fast-track for intelligent transport system equipment unlocks India's smart-city corridor mandates as the most penetrable geography. Target California and Texas municipalities unbundling edge infrastructure from signal optimization software. Pursue subscription-based traffic analytics positioning to bypass capital-intensive hardware procurement barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-defined traffic infrastructure vendors with cloud-native architectures over legacy centralized platform incumbents. Five-to-ten year viability hinges on edge-AI inference engine deployment density. Monitor EU AI Act regulatory propagation into Southeast Asian procurement specifications as inflection indicator for compliant architecture demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Compliance Engineering Investment | EU AI Act documentation burdens favor vendors with embedded audit trail capabilities in German and French tenders. |
| Edge-Native AI Inference Deployment | Singapore Land Transport Authority directives eliminate round-trip latency for emergency vehicle preemption scenarios. |
| Multimodal Transit Priority Integration | EU Green Deal mobility targets specify bus rapid transit signal preemption in Rotterdam and Amsterdam corridor contracts. |
| Subscription Analytics Platform Launch | Dallas and Houston traffic operation centers shift from decade-long maintenance to annual software license negotiations. |
| Standardized Tender Template Adaptation | India's central government mandates in Delhi, Mumbai, and Bangalore accelerate integrated corridor management adoption. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, EIA infrastructure disclosures, EU procurement databases, and municipal tender documentation. Primary interviews engaged traffic operation center directors, municipal procurement officers, systems integration engineers, and semiconductor vendor account managers. Secondary validation drew from FCC equipment authorization records, BIS certification registries, and KBA vehicle safety standards documentation. Bottom-up deployment tracking triangulates against top-down market sizing across component, technology, application, and end-user segmentation dimensions.
Segmentation dimensions modeled span hardware components (sensors, control units, communication modules), software platforms (adaptive signal control, cloud computing, edge-native AI), applications (congestion management, public transit coordination, incident detection), and end users (municipal authorities, traffic operation centers, infrastructure developers) across the analysis window. CAGRs derive from installed base replacement cycles, smart-city mandate acceleration curves, and subscription revenue transition rates. Industry-specific inputs include sub-100-millisecond latency infrastructure investment thresholds and algorithmic auditing compliance cost structures.
Underlying assumptions cover EU AI Act regulatory propagation timelines, India smart-city mandate execution rates, and edge-computing semiconductor supply continuity, with deviation risk concentrated in cross-jurisdiction certification stacking delays and legacy infrastructure replacement cycle extensions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
North America Vehicle Tolling System Market
Smart Transportation Solutions
Global Smart Parking Market
Smart Transportation Solutions
North America IoT Transportation Market
Smart Transportation Solutions
Europe Passenger Information System Market
Smart Transportation Solutions
Mobility Technologies Market
Smart Transportation Solutions
Vietnam Ride-Hailing Market
Smart Transportation Solutions
Global Electric Public Transport Market
Smart Transportation Solutions
5G in Automotive and Smart Transportation Market
Smart Transportation Solutions
Global Ridesharing Market
Smart Transportation Solutions
North America Smart Transportation Market
Smart Transportation Solutions
Personal Transporter Market
Smart Transportation Solutions
Micro Mobility Market
Smart Transportation Solutions
Smart Fleet Management Market
Smart Transportation Solutions
North America Fleet Management Solutions Market
Smart Transportation Solutions
Connected Parking Solutions Market
Smart Transportation Solutions
GCC Electronic Toll Collection Market