
 E-Bike Battery Pack Market | 2026-2036
E-Bike Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
E-Bike Battery Pack Market Foresight
Commercial fleet operators are bifurcating from retail consumers as the dominant volume buyers for e-bike battery packs. BMZ GmbH anchors European supply through its integrated pack assembly operations in Germany. Samsung SDI leverages cylindrical cell expertise to compete in premium commuter and mountain bike segments. LG Energy Solution extends its position through partnerships with major European original equipment manufacturers.
An e-bike battery pack integrates cells, battery management systems, thermal controls, and enclosures into a removable or frame-integrated power unit, typically delivering 36V to 48V with capacities from 10 Ah to over 40 Ah for propulsion assistance. Lithium-ion chemistry dominates current production due to energy density advantages and declining cell costs, while the above 40 Ah capacity tier captures expanding margin pools from cargo and delivery applications. The fleet operator end-user segment exhibits the fastest structural expansion as logistics electrification intensifies replacement cycles and standardizes pack formats across vehicle platforms.
EU Battery Regulation and CE marking requirements enforce carbon footprint disclosure and recycled content thresholds for packs sold in Europe, while China's GB standards and MIIT technical conditions govern cell safety and swap compatibility in the largest manufacturing base. The US Consumer Product Safety Commission and EPA frameworks are tightening fire-safety testing protocols for imported lithium-ion systems. Stakeholders must monitor divergence between regional certification regimes and the pace of harmonization for swappable battery interfaces.
Market Dynamics
Fleet electrification mandates across urban logistics networks are compressing replacement cycles and forcing standardization of pack formats across incompatible vehicle platforms.
Growth Catalysts
- EU Battery Regulation:Carbon footprint disclosure and recycled content thresholds for packs sold in Europe are accelerating investment in sustainable supply chains and circular economy infrastructure.
- Last-mile delivery electrification:Urban logistics operators in Germany and the Netherlands are mandating zero-emission fleets, creating concentrated demand for high-capacity swappable architectures.
- Lithium iron phosphate chemistry:Commercial-grade durability requirements are redirecting supplier R&D toward thermal stability and extended cycle life for cargo applications.
Market Restraints
- Cobalt and lithium price volatility:Raw material cost swings constrain margin predictability for pack assemblers dependent on spot-market cell procurement.
- Cell supply concentration in China:GB standards and MIIT technical conditions govern the dominant manufacturing base, creating geopolitical exposure for European and North American downstream customers.
- Energy density ceiling:Lithium-ion chemistry faces physical limits that prevent further mass reduction for high-capacity cargo configurations above 40 Ah.
Strategic Opportunities
- India's urban freight corridors:BIS certification alignment and PLI scheme incentives for domestic cell manufacturing create entry pathways for pack integrators serving two-wheeler logistics.
- Battery-as-a-service models:Subscription-based ownership separates asset risk from vehicle purchase, unlocking fleet adoption among capital-constrained delivery operators.
- Interoperability standards:Swappable interface harmonization across MIIT, EU Battery Regulation, and ISO frameworks enables platform-agnostic pack deployment.
Industry Challenges
- Fire-safety testing protocols:US Consumer Product Safety Commission and EPA frameworks for imported lithium-ion systems impose extended certification timelines that delay market entry.
- Pack-platform integration complexity:Frame-integrated thermal management and battery management system calibration require specialized engineering talent scarce outside Germany and China.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Bike Battery Pack Market |
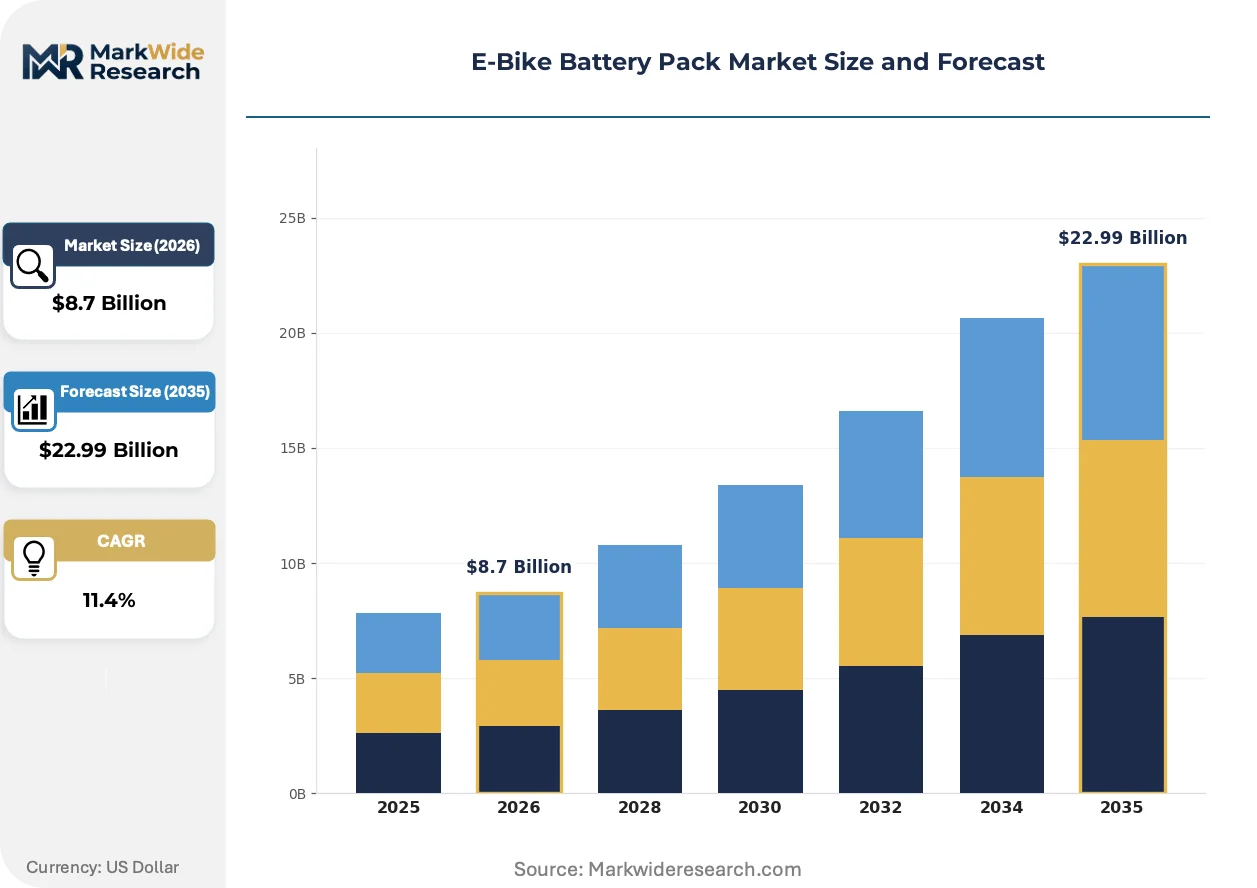
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-metal Hydride, Lead Acid, Lithium Polymer Capacity: 10-20 Ah, 20-30 Ah, 30-40 Ah, Above 40 Ah Application: Commuter, Mountain, Cargo, Folding End User: Retail Consumers, Fleet Operators, Delivery Services, Rentals |
| Companies Covered | EVE Energy, BMZ GmbH, CATL, Phylion, BENZO Energy, Samsung SDI, LG Energy Solution, BAK Battery, Panasonic Industry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Bike Battery Pack Market Shifts & Advancements
Active thermal management architectures and solid-state prototyping pipelines are redefining performance benchmarks while regulatory pressure on carbon intensity reshapes supplier qualification criteria.
Solid-state electrolyte research is bifurcating the technology roadmap between near-term silicon-anode enhancements and longer-term ceramic separator deployment. Premium commuter and mountain bike segments are absorbing early production volumes at 2-3x conventional pack costs. This chemistry transition is bifurcating supplier investment between incremental lithium-ion optimization and disruptive solid-state manufacturing scale-up.
REACH substance restrictions and EU Battery Regulation due diligence obligations are forcing pack assemblers to document supply chain provenance back to mined raw materials. Industrial consequence includes mandatory third-party auditing of cell suppliers and pre-qualification barriers for non-compliant manufacturers. Cargo and delivery pack categories face the steepest compliance cost escalation as recycled content thresholds tighten fastest for commercial-grade products.
Fleet procurement departments are consolidating vendor relationships around multi-year service agreements that bundle pack supply, swap infrastructure, and predictive maintenance analytics. Direct OEM relationships and dedicated swap-station networks are displacing traditional distributor channels for volumes above 500 units annually. This concentration is most visible in the Netherlands and Denmark where municipal logistics electrification timelines compress decision cycles and favor integrated solution providers.
E-Bike Battery Pack Market Segmentation
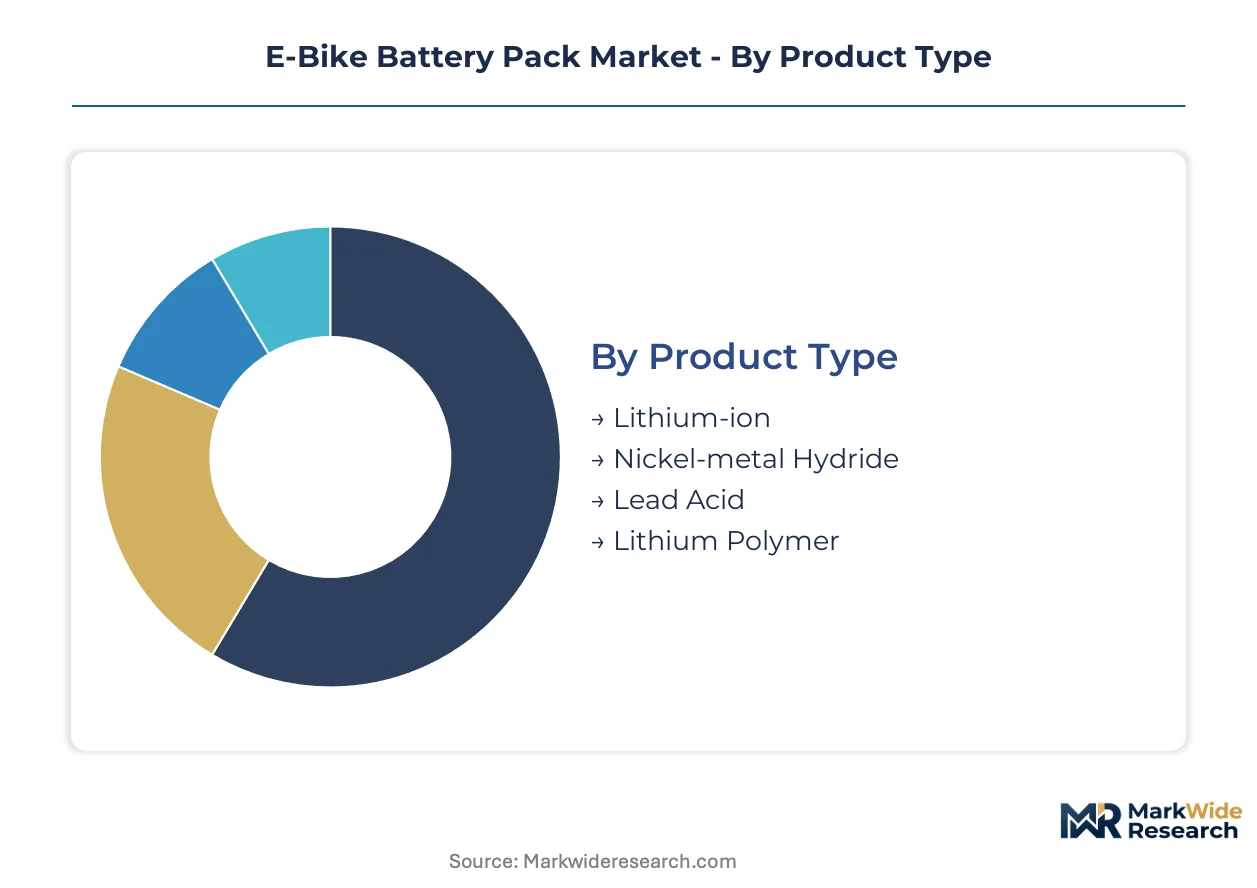
Segmentation in the E-Bike Battery Pack Market reveals divergent supply chain architectures across chemistry types and capacity tiers. Fleet procurement patterns differ sharply from retail distribution channels in sourcing cadence and technical specifications.
Product Type:
Geographic concentration varies sharply by chemistry, with lithium-ion cell production anchored in China under MIIT technical conditions while European pack assembly serves regional demand under REACH substance restrictions.
- Lithium-ion:Dominant chemistry delivering 36V to 48V configurations through cylindrical or prismatic cell arrangements. Demand concentrates in Germany and the Netherlands where urban logistics electrification mandates require high energy density for cargo platforms.
- Lithium Polymer:Pouch-cell architectures enable flexible form factors for frame-integrated designs. Netherlands-based fleet operators specify these packs for custom cargo bike geometries where space constraints dominate.
- Nickel-metal Hydride:Legacy chemistry retained in cost-sensitive replacement markets with established recycling infrastructure.
- Lead Acid:Limited to entry-level commuter segments in developing markets with minimal regulatory enforcement on energy density.
Lithium-ion commands the established base. The steepest expansion runs through Lithium Polymer.
Capacity:
Cost stratification separates commodity replacement packs from premium configurations, with thermal management complexity escalating above the 30 Ah threshold.
- Above 40 Ah:High-capacity architectures with active thermal management and reinforced enclosures for commercial cargo applications. Delivery services in Germany standardize on this tier to maximize route range and minimize swap frequency.
- 30-40 Ah:Mid-tier configurations balancing weight and range for premium commuter and mountain bike segments. Netherlands fleet operators deploy these for mixed urban-suburban routes with moderate payload requirements.
- 20-30 Ah:Volume tier for standard commuter replacements with passive cooling and simplified battery management systems.
- 10-20 Ah:Entry-level capacity for folding bikes and short-range urban mobility with minimal regulatory compliance overhead.
The 30-40 Ah tier anchors current production volumes. Above 40 Ah configurations are climbing the fastest as logistics electrification accelerates.
Application:
Customer type fragmentation splits engineering requirements between recreational performance specifications and commercial durability standards.
- Cargo:Reinforced pack architectures with extended cycle life ratings and swappable interfaces for continuous fleet utilization. German municipal logistics contracts mandate these specifications for last-mile delivery electrification.
- Mountain:Vibration-resistant enclosures and rapid-discharge cell configurations for high-torque pedal-assist systems. European premium OEMs specify these for integrated frame designs with proprietary thermal management.
- Commuter:Standardized form factors for aftermarket replacement with broad compatibility across frame mounting systems.
- Folding:Compact, lightweight packs with reduced capacity for portability constraints in multi-modal transit integration.
Commuter applications retain the largest installed base. Cargo platforms are gaining share fastest as fleet procurement scales.
End User:
Procurement channel structure diverges between direct OEM supply agreements and aftermarket distribution networks serving fragmented retail demand.
- Fleet Operators:Centralized procurement with multi-year service agreements bundling pack supply, predictive maintenance, and swap infrastructure. Denmark and Netherlands municipal operators consolidate volumes above 500 units annually.
- Delivery Services:Capital-constrained operators adopting battery-as-a-service models to separate asset risk from vehicle ownership. German urban freight corridors drive standardization of swappable formats across incompatible vehicle platforms.
- Retail Consumers:Price-sensitive aftermarket replacement through distributor channels with minimal technical support requirements.
- Rentals:High-utilization operators prioritizing rapid swap compatibility and standardized charging infrastructure across mixed fleets.
Retail Consumers represent the largest addressable population. Delivery Services are expanding most quickly as subscription ownership models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese cell manufacturers supply European pack assemblers through direct procurement contracts, while German logistics operators drive demand for high-capacity swappable architectures. This trade corridor shapes investment flows across the value chain.
Germany
Municipal logistics electrification mandates in Berlin and Hamburg concentrate demand for 40+ Ah cargo configurations. KBA vehicle-type approval requirements enforce thermal management standards for commercial-grade packs. Stuttgart anchors automotive supplier migration into e-bike battery assembly operations.
China
Domestic e-bike production absorbs cylindrical and prismatic cell output from CATL and EVE Energy facilities. MIIT technical conditions govern swap compatibility standards across shared mobility platforms. Shenzhen and Dongguan cluster pack integrators serving export markets under GB certification protocols.
Netherlands
Amsterdam and Rotterdam delivery fleets standardize on swappable lithium-polymer formats for continuous route coverage. EU Battery Regulation carbon footprint disclosure applies to all packs sold through Dutch distribution channels. Eindhoven hosts thermal management engineering specialists supporting frame-integrated designs.
India
Urban freight corridors in Mumbai and Bangalore generate procurement volumes for two-wheeler logistics electrification. BIS certification alignment and PLI scheme incentives attract pack integrators to domestic cell manufacturing partnerships. Tamil Nadu assembly plants supply South Asian replacement markets.
United States
Last-mile delivery operators in New York and San Francisco pilot battery-as-a-service models to separate asset ownership from fleet utilization. CPSC fire-safety testing protocols extend certification timelines for imported lithium-ion systems. California energy storage procurement rules influence pack warranty and cycle-life specifications.
E-Bike Battery Pack Market Competitive Landscape
Player mix skews toward diversified battery manufacturers with automotive-grade cell expertise extending into micromobility applications. The supplier base stratifies between integrated cell-to-pack producers and specialist assemblers dependent on third-party cell procurement. Tier-one automotive suppliers and dedicated e-bike pack houses constitute the dominant strategic archetypes. Competitive positioning hardens around backward integration into cell manufacturing and captive supply agreements with fleet operators.
Among Asian cell producers, CATL and EVE Energy exemplify the scale-driven archetype with automotive-derived cylindrical and prismatic platforms repurposed for e-bike applications. BMZ GmbH occupies a position within the European specialist tier, representing integrated pack assembly operations serving regional OEM requirements. Samsung SDI and LG Energy Solution anchor the premium-tier vector, leveraging Korean manufacturing standards for commuter and mountain bike segments where energy density commands price premiums.
| Leading Market Players |
|---|
| EVE Energy |
| BMZ GmbH |
| CATL |
| Phylion |
| BENZO Energy |
| Samsung SDI |
| LG Energy Solution |
| BAK Battery |
| Panasonic Industry |
| Others |
Supply & Pricing Matrix
Automotive-scale cylindrical cell production in China underwrites cost floors across the e-bike battery pack market, concentrating pricing power among integrated manufacturers while forcing specialist assemblers toward service-based revenue models. This scale dynamic compresses margins on commodity packs below 30 Ah while elevating premium capture for active thermal management configurations above 40 Ah.
Pricing Analysis
Current-generation lithium-ion packs trade at substantial discounts to early solid-state prototypes, which command two-to-three-fold premiums in premium commuter and mountain bike segments. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by thermal management sophistication and cycle-life certification. Cost compression in the 20-30 Ah tier intensifies as Chinese cell overcapacity feeds spot-market procurement. Retail consumers exhibit highest price sensitivity, while fleet operators prioritize total-cost-of-ownership metrics that favor higher upfront investment in swappable architectures.
Supply Chain Analysis
Strait of Malacca transit routes underpin lithium carbonate and cobalt sulfate flows from Australian mines and Indonesian processing facilities to Chinese cell fabrication centers. Cell production concentrates in China, South Korea, and Japan, with pack assembly gravitating toward Germany and the Netherlands to satisfy EU Battery Regulation compliance. Raw material dependencies span lithium carbonate, nickel sulfate, and electrolyte solvents subject to commodity price volatility. Distribution runs through direct OEM supply agreements for fleet volumes above 500 units annually, while aftermarket channels serve fragmented retail replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The e-bike battery pack market constitutes a defensive-moat opportunity anchored in regulatory entrenchment: EU Battery Regulation carbon footprint disclosure and recycled content thresholds create pre-qualification barriers that favor incumbent pack assemblers with established circular economy infrastructure.
For Market Incumbents: Fortify backward integration into cell supply through captive agreements with cylindrical producers in China and South Korea, insulating margin structures from spot-market volatility. Deepen swap-station network density in German and Dutch urban freight corridors to lock in fleet operator multi-year service agreements. Invest in predictive maintenance analytics capabilities to differentiate from commodity pack assemblers facing margin erosion.
For New Entrants and Emerging Players: Anchor in India's urban freight corridors where BIS certification alignment and PLI scheme incentives create entry pathways for domestic pack integration partnerships. Target battery-as-a-service subscription models for capital-constrained delivery operators in German and US markets, separating asset ownership from fleet utilization. Pursue white-label pack assembly for European OEMs seeking to diversify cell supply beyond dominant Asian producers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet operator service agreements bundling pack supply, swap infrastructure, and predictive maintenance, offering superior cash flow visibility versus transactional aftermarket sales. Acquisition targets should prioritize pack integrators with MIIT-certified swap compatibility and established EU Battery Regulation compliance documentation. Monitor solid-state electrolyte manufacturing scale-up announcements as inflection indicators for chemistry-transition timing and premium pricing sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Swap Infrastructure Partnership | Locks in fleet operator volumes through multi-year service agreements in German logistics corridors. |
| Backward Integration into Cell Supply | Captures margin pool currently absorbed by Chinese cylindrical producers subject to spot volatility. |
| Battery-as-a-Service Platform Launch | Separates asset risk from vehicle ownership for capital-constrained delivery operators in urban markets. |
| EU Battery Regulation Pre-Certification | Creates pre-qualification barriers against non-compliant assemblers in European distribution channels. |
| Solid-State Prototype Investment | Positions for premium pricing capture in mountain and commuter segments as ceramic separators mature. |
Research Methodology
The analysis maps lithium-ion, lithium-polymer, and solid-state chemistry trajectories, each validated through fleet procurement directors, pack assembly engineers, and thermal management specialists. Primary fieldwork encompassed structured interviews with OEM platform engineers, swap-station operators, and cell supplier account managers across Germany, China, and the Netherlands. Secondary validation drew from MIIT technical condition filings, EU Battery Regulation implementation guidance, KBA vehicle-type approval databases, and customs trade flow records. Bottom-up volume estimates triangulated against top-down market sizing from production capacity and replacement cycle assumptions.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled chemistry type, capacity tier, application segment, and end-user procurement channel dimensions. CAGRs derived from regression analysis of historical replacement cycles, fleet electrification mandate timelines, and cell cost decline curves. Industry-specific inputs included swap-station deployment rates, thermal management patent filings, and carbon footprint audit penetration across European pack assemblers.
Decision-makers should treat outputs as directional under assumptions of sustained lithium carbonate supply expansion and stable EU Battery Regulation enforcement timelines; material deviation in raw material cost trajectories or regulatory harmonization pace would warrant model refresh. Practitioners should keep alternative scenarios live as solid-state manufacturing scale-up and India PLI scheme implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
E-Lock for Electric Vehicle Charging Market
Electric Vehicles
France Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Electric Vehicle UBI Market
Electric Vehicles
Agricultural Electric Vehicles Market
Electric Vehicles
Electric Vehicle HVAC Market
Electric Vehicles
Middle East and Africa Electric Vehicle Thermal Management System Market
Electric Vehicles
Electric Vehicle Battery Trays Market
Electric Vehicles
Electric Delivery Vans Market
Electric Vehicles
Electric Vehicle Sound Generators Market
Electric Vehicles
Preassembled Harness Modules for Skateboard EV Platforms Market
Electric Vehicles
Battery-Swapping for Electric Two-Wheeler Market
Electric Vehicles
Micro Electric Vehicle Market
Electric Vehicles
EV Coolants Market
Electric Vehicles
China Automotive High Performance Electric Vehicle Market
Electric Vehicles
Electric Vehicle Electric Heating Film Market
Electric Vehicles
India Electric Car Market