
 EV Coolants Market | 2026-2036
EV Coolants Market Size, Share, and Industry Trends Forecast 2026-2036
EV Coolants Market Foresight
Commercial fleet electrification is realigning coolant procurement priorities across North America and Europe. BASF SE leverages its glycol chemistry expertise to supply battery-grade formulations for heavy-duty electric trucks. Shell plc anchors its position through integrated direct liquid cooling partnerships with European automakers. Valvoline Inc. specializes in aftermarket thermal management service programs for legacy fleet conversions.
EV coolants are heat-transfer fluids engineered with low electrical conductivity below 100 µS/cm and dielectric strength above 30 kV to prevent short circuits in high-voltage battery packs. These formulations circulate through cold plates and cooling jackets to maintain lithium-ion cells within 15°C to 35°C operating windows. Glycol-based products dominate current volume due to freeze protection and corrosion inhibition, while non-aqueous dielectric fluids capture margin pools in premium battery architectures. Direct liquid cooling leads technology adoption as energy densities climb, though phase change materials gain traction in solid-state battery prototypes.
The EPA enforces refrigerant and thermal-efficiency standards under SNAP regulations, while the EU F-Gas Regulation phases down fluorinated coolant compounds. China's MIIT mandates GB/T thermal-management testing protocols for domestic EV certification. OEMs and chemical suppliers must monitor how REACH chemical restrictions and evolving dielectric-fluid specifications reshape formulation roadmaps and regional market access requirements.
Market Dynamics
Direct liquid cooling architectures are compressing thermal management into battery pack substrates, eliminating separate heat exchanger assemblies and rewiring procurement relationships between automakers and chemical formulators.
Growth Catalysts
- EPA SNAP refrigerant mandates:Thermal-efficiency standards under SNAP are forcing OEMs to specify higher-performance dielectric fluids, expanding addressable volume for low-conductivity glycol formulations in US passenger EV programs.
- Commercial fleet electrification:Heavy-duty electric trucks and delivery vans require 3-4x coolant volume per vehicle versus passenger cars, concentrating procurement decisions among North American logistics operators with centralized maintenance contracts.
- China MIIT GB/T certification:Domestic EV manufacturers must pass standardized thermal-management testing protocols, creating captive demand for locally produced battery-grade coolants that meet dielectric strength and conductivity specifications.
Market Restraints
- Ethylene glycol price volatility:Petrochemical feedstock costs fluctuate with crude oil and natural gas benchmarks, squeezing margin stability for formulators committed to long-term supply contracts with automotive OEMs.
- Fluorinated compound phase-down:EU F-Gas Regulation restricts perfluorinated thermal fluids in premium battery architectures, forcing R&D redirection toward alternative chemistries with unproven scale economics.
- Dielectric fluid performance ceiling:Aqueous glycol solutions face fundamental conductivity floors near 50 µS/cm that limit deployment in 800V architectures pushing toward solid-state prototypes.
Strategic Opportunities
- India PLI scheme for cell manufacturing:Production-linked incentives for domestic lithium-ion gigafactories will generate parallel demand for localized coolant blending capacity and technical service infrastructure.
- Second-life battery thermal management:Stationary energy storage repurposing retired EV packs requires adapted coolant formulations with extended service intervals and corrosion profiles tuned for static operation.
- Closed-loop recycling mandates:Extended producer responsibility frameworks in Germany and France are creating service revenue pools for coolant recovery, reconditioning, and re-deployment in aftermarket channels.
Industry Challenges
- Electrochemical compatibility testing:Formulators must validate coolant interactions with novel cell chemistries—silicon-anode, lithium-metal, and solid-electrolyte interfaces—extending qualification timelines to 18-24 months.
- Cross-contamination risk in service networks:Independent repair facilities lack standardized equipment for flushing legacy internal combustion cooling systems before EV coolant introduction, creating warranty exposure for OEM thermal management programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Coolants Market |
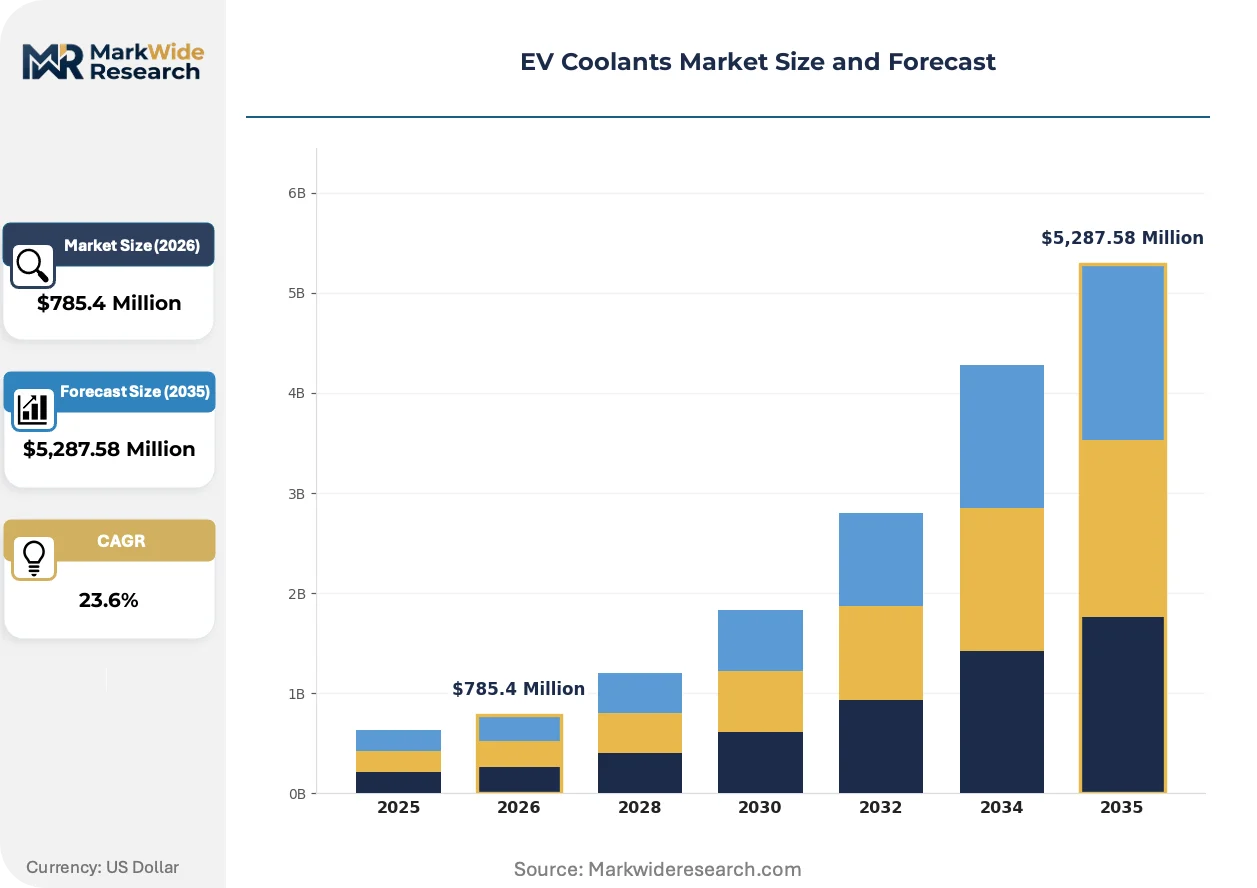
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $5,287.58 Million |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aqueous, Non-Aqueous, Glycol-Based, Organic Application: Battery Cooling, Motor Cooling, Thermal Management, Radiator Systems Technology: Direct Liquid Cooling, Air Cooling, Phase Change Materials, Hybrid Systems End User: Automakers, OEMs, Manufacturing Plants, Aftermarket Providers |
| Companies Covered | BASF SE, Shell plc, Exxon Mobil Corporation, Valvoline Inc., TotalEnergies SE, Castrol Limited, Chevron Corporation, GS Caltex, Dober, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Coolants Market Shifts & Advancements
Formulation science is pivoting from freeze-protection priority to dielectric performance optimization as battery voltages climb and cell densities compress thermal margins.
Phase change materials embedded in cold plate substrates are converging with direct liquid cooling circuits to create hybrid thermal architectures. Solid-state battery developers at Korean and Japanese OEMs are piloting paraffin-impregnated aluminum matrices that absorb transient heat spikes before fluid circulation removes steady-state loads. This convergence is collapsing the distinction between passive and active thermal management tiers, forcing coolant suppliers to co-develop integrated subsystem specifications with pack engineers rather than deliver commodity fluids.
EU F-Gas Regulation amendments will prohibit virgin hydrofluorocarbon use in battery thermal management systems by 2030. Formulators are accelerating non-fluorinated dielectric fluid development, with silicone-based and synthetic hydrocarbon candidates advancing through OEM validation protocols. Premium European EV architectures face the most compressed substitution timeline, driving partnerships between chemical suppliers and vehicle thermal teams to revalidate entire cooling circuit material compatibility.
Fleet operators are unbundling coolant procurement from vehicle purchase agreements and contracting directly with chemical suppliers for lifecycle thermal management services. North American heavy-duty electric truck deployments are piloting fluid-as-a-service models where formulators retain ownership of coolant inventory and charge per thermal-kilometer delivered. This disintermediation is most advanced among California-based logistics operators subject to CARB fleet electrification mandates with total cost of ownership scrutiny.
EV Coolants Market Segmentation
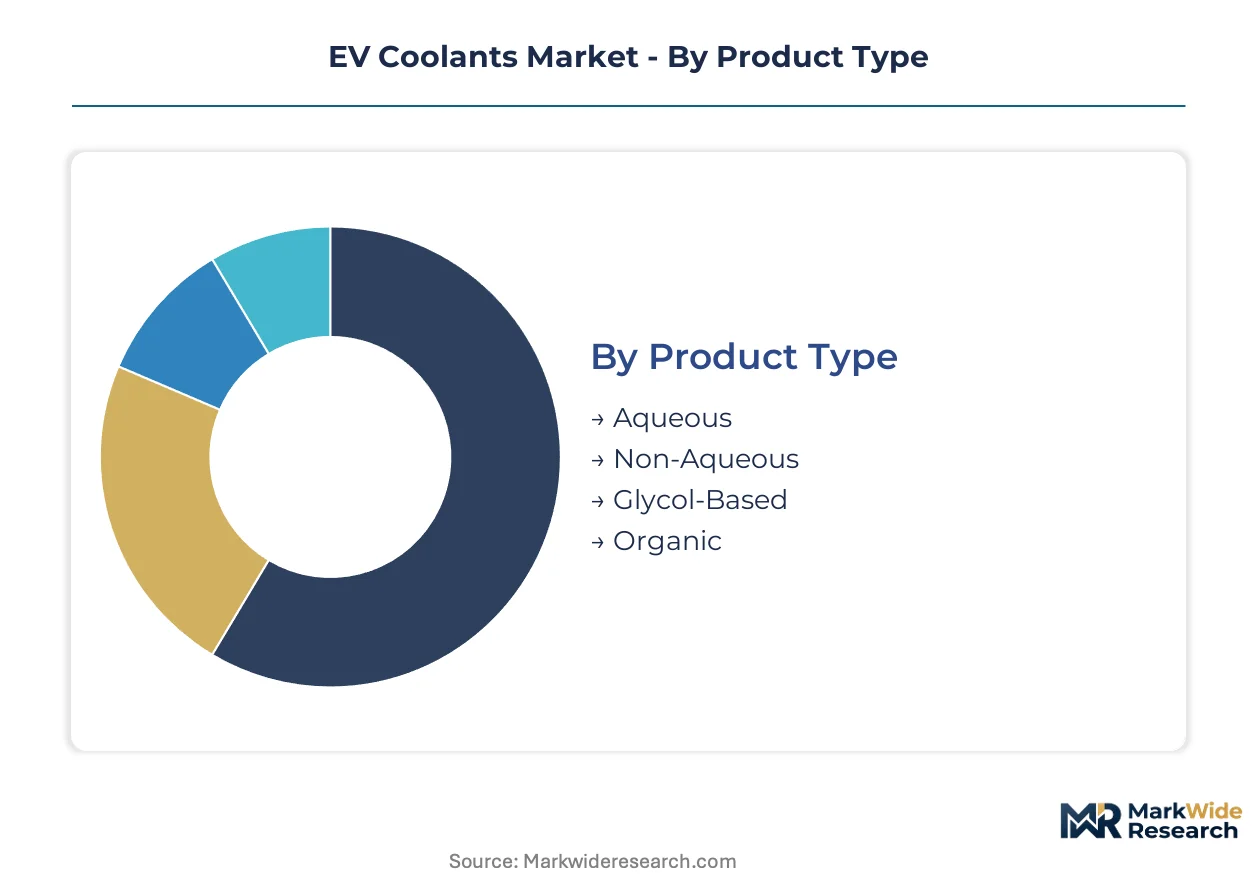
EV coolant segmentation reveals how thermal management requirements diverge across battery architectures and vehicle platforms. Formulators must align product portfolios with distinct dielectric specifications, cooling circuit designs, and procurement relationships that vary by integration depth and customer type.
Product Type:
Integration depth separates standalone coolant formulations from chemically embedded thermal interface materials that bond directly to cell surfaces.
- Glycol-Based:Ethylene and propylene glycol formulations dominate current procurement volumes with freeze protection below -40°C and corrosion inhibition for aluminum cooling circuits. Heavy-duty electric truck fleets in the United States specify these fluids for their balance of cost and dielectric performance under EPA SNAP thermal-efficiency mandates.
- Aqueous:Water-glycol blends with electrical conductivity controlled below 100 µS/cm circulate through cold plates in 400V battery packs. Chinese EV manufacturers under MIIT GB/T certification protocols source aqueous formulations from domestic blenders for their established supply security and technical service infrastructure.
- Non-Aqueous:Synthetic hydrocarbon and silicone dielectric fluids serve 800V architectures and solid-state battery prototypes where conductivity floors near 50 µS/cm disqualify aqueous options.
- Organic:Bio-based propylene glycol derivatives address sustainability procurement criteria in European fleet electrification programs subject to EU Green Deal chemical restrictions.
Glycol-based formulations lead volumes today; non-aqueous fluids are gaining share fastest in premium battery architectures.
Application:
Cost tiering separates commodity thermal management from engineered subsystems commanding formulation premiums and technical service contracts.
- Battery Cooling:Direct liquid cooling circuits maintain lithium-ion cells within 15°C to 35°C operating windows through cold plate circulation. This application concentrates procurement decisions among battery pack integrators in Germany and Japan who validate coolant-cell electrochemical compatibility across 18-24 month qualification timelines.
- Thermal Management:Integrated subsystem specifications combine coolant circulation with phase change materials and heating elements for all-climate performance. Korean OEMs pilot these hybrid architectures for solid-state battery prototypes requiring transient heat absorption before steady-state fluid removal.
- Motor Cooling:Power electronics and e-motor cooling circuits demand lower dielectric strength specifications than battery applications, opening volume opportunities for standard glycol formulations.
- Radiator Systems:Legacy thermal management hardware in converted internal combustion platforms retains separate coolant loops with distinct corrosion inhibitor packages.
Battery cooling leads volumes today; integrated thermal management is climbing the fastest as energy densities compress thermal margins.
Technology:
Volume concentration tracks with energy density trajectories—higher cell densities force adoption of more thermally aggressive cooling architectures.
- Direct Liquid Cooling:Cold plate substrates with embedded microchannels circulate dielectric fluid at pack level, eliminating separate heat exchanger assemblies. This technology anchors procurement relationships between European automakers and integrated chemical suppliers like Shell plc for next-generation 800V platforms.
- Phase Change Materials:Paraffin-impregnated aluminum matrices absorb transient thermal spikes before fluid circulation removes steady-state loads. Japanese and Korean solid-state battery developers pilot these materials for their passive-active hybrid performance in premium vehicle architectures.
- Air Cooling:Simplified thermal management persists in entry-level urban EVs where cell energy densities and duty cycles permit passive dissipation.
- Hybrid Systems:Converged passive-active architectures collapse traditional tier distinctions, requiring coolant suppliers to co-develop specifications with pack engineers rather than deliver commodity fluids.
Direct liquid cooling leads volumes today; phase change materials are expanding most quickly in solid-state battery development programs.
End User:
Customer type determines procurement structure—captive manufacturing favors long-term supply contracts while aftermarket channels generate service revenue pools.
- Automakers:Integrated vehicle manufacturers specify coolant formulations during pack design phases, locking in 5-7 year supply agreements with technical service requirements. Tesla, BYD, and Volkswagen Group anchor global formulation demand through direct liquid cooling mandates in their premium EV architectures.
- Aftermarket Providers:Independent thermal management service programs address legacy fleet conversions and second-life battery stationary storage applications. Valvoline Inc. specializes in this channel with adapted coolant formulations featuring extended service intervals for static operation.
- OEMs:Battery pack and thermal subsystem suppliers procure coolant as part of integrated module deliveries to vehicle manufacturers, concentrating volume among Tier 1 suppliers in China and South Korea.
- Manufacturing Plants:Gigafactory operators with captive blending capacity source base glycol and additive packages rather than finished formulations, compressing margins for commodity suppliers.
Automaker direct procurement leads volumes today; aftermarket providers are gaining share fastest as commercial fleet electrification accelerates service contract unbundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting coolant formulation investment toward jurisdictions where thermal-management compliance costs diverge from production scale advantages. China and the United States currently present the widest gap between certification stringency and manufacturing density, attracting capital from European formulators facing compressed fluorinated-compound phase-down timelines.
China
Domestic EV production exceeding seven million units annually generates concentrated procurement demand for GB/T-certified coolant formulations. MIIT mandates standardized thermal-management testing protocols that effectively screen out imported formulations lacking local validation infrastructure. The Yangtze River Delta region surrounding Shanghai hosts the densest cluster of battery pack integrators and captive blending facilities serving BYD and CATL supply chains.
United States
Heavy-duty electric truck deployments across California and Texas are unbundling coolant procurement from vehicle purchase agreements. EPA SNAP refrigerant mandates under thermal-efficiency standards force OEMs to specify higher-performance dielectric fluids for passenger EV programs. The Detroit-Warren corridor retains formulation R&D concentration despite production migration toward Southern states with lighter regulatory burdens.
Germany
Premium European EV architectures face the most compressed substitution timeline under EU F-Gas Regulation amendments prohibiting virgin hydrofluorocarbon use by 2030. The country's national automotive regulator KBA enforces type-approval protocols that extend coolant qualification timelines to 18-24 months. Bavaria's chemical corridor between Ludwigshafen and Munich anchors integrated direct liquid cooling partnerships between formulators and OEM thermal engineering teams.
South Korea
Solid-state battery developers at domestic OEMs are piloting hybrid thermal architectures combining phase change materials with direct liquid cooling circuits. The Ministry of Trade, Industry and Energy supports non-fluorinated dielectric fluid development through national R&D consortia. The Gyeonggi-Seoul corridor concentrates pack engineering talent and validation laboratories serving Hyundai-Kia and LG Energy Solution supply chains.
India
Production-linked incentives for domestic lithium-ion gigafactories under the PLI scheme will generate parallel demand for localized coolant blending capacity. The Central Electricity Authority mandates thermal-management compliance for grid-connected battery storage systems. Tamil Nadu and Gujarat are emerging as the primary states for integrated cell-and-coolant manufacturing clusters serving domestic EV programs and export markets.
EV Coolants Market Competitive Landscape
Capacity expansion dominates the current landscape as formulators race to secure positions in high-growth regional supply chains. The vendor base concentrates among integrated petrochemical majors with captive glycol production and specialized additive houses serving niche dielectric specifications. Three strategic archetypes define competitive positioning: integrated oil majors leveraging hydrocarbon chemistry expertise, diversified chemical conglomerates with corrosion inhibition portfolios, and regional blenders capturing local certification requirements. Geographic expansion and technology licensing represent the dominant competitive moves, with European formulators seeking Asian production partnerships and Korean suppliers licensing hybrid thermal architectures to Western OEMs.
Among integrated oil majors, Shell plc and Exxon Mobil Corporation exemplify scale-driven positioning through direct liquid cooling partnerships with premium automakers. BASF SE anchors the diversified chemical archetype with glycol chemistry expertise extending into battery-grade formulations. These three companies represent distinct strategic postures: hydrocarbon-based dielectric fluids, integrated supply chain control, and formulation science specialization respectively.
| Leading Market Players |
|---|
| BASF SE |
| Shell plc |
| Exxon Mobil Corporation |
| Valvoline Inc. |
| TotalEnergies SE |
| Castrol Limited |
| Chevron Corporation |
| GS Caltex |
| Dober |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation amendments prohibiting virgin hydrofluorocarbon use by 2030 gate qualified supply and premium-tier pricing access, compressing substitution timelines for European formulators while opening margin pools for non-fluorinated dielectric fluid producers with validated OEM partnerships.
Pricing Analysis
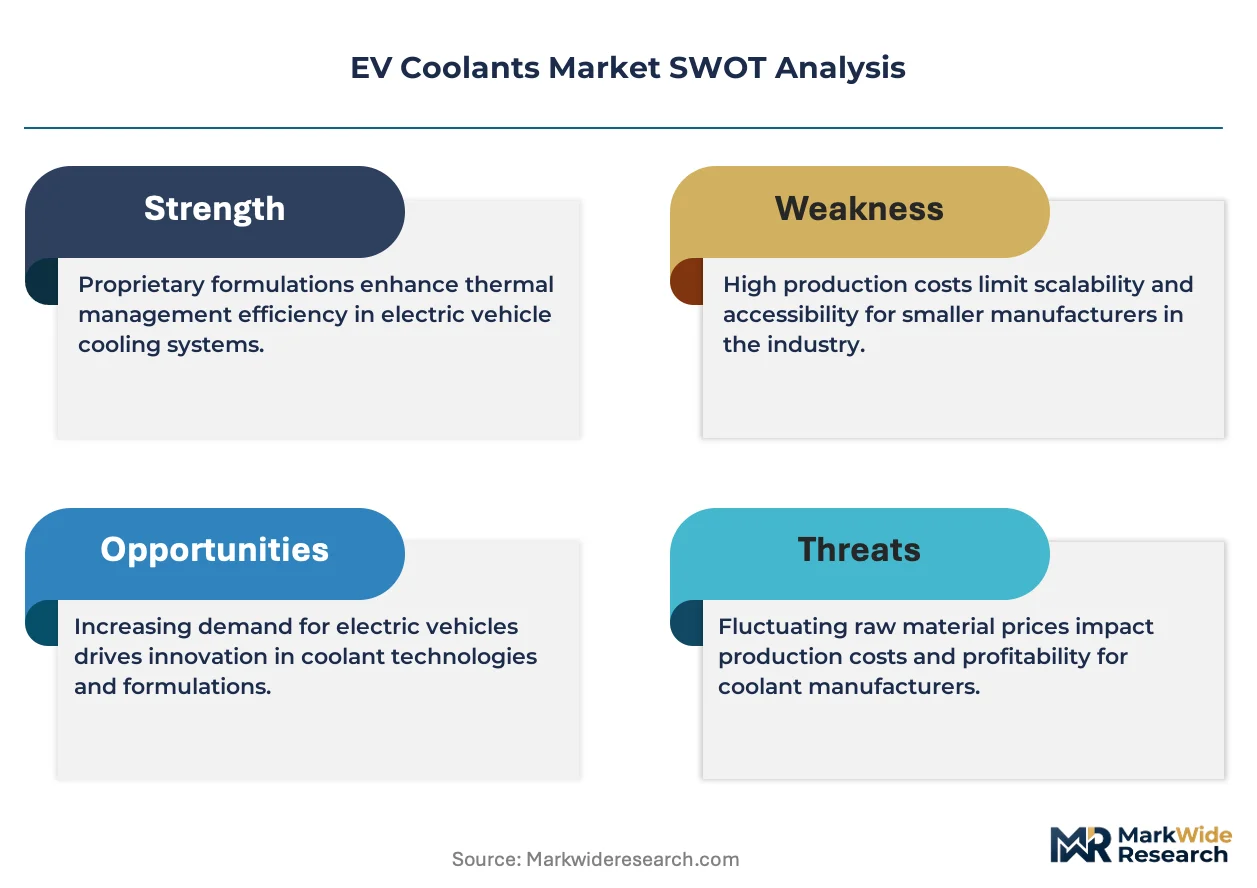
Distributor margin layers in battery-grade coolant procurement compress as automakers consolidate direct relationships with integrated chemical suppliers. Three-tier pricing structure across premium, standard, and economy levels separates non-aqueous dielectric fluids for 800V architectures from aqueous glycol blends for 400V packs and commodity ethylene glycol base stocks. Pricing pressure stems from ethylene glycol feedstock volatility tied to crude oil benchmarks, squeezing formulators locked into long-term OEM contracts. Fleet operators exhibit highest price sensitivity through unbundled fluid-as-a-service procurement, while premium automakers prioritize dielectric performance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from European and North American OEMs mandate multi-supplier qualification for critical thermal management fluids, preventing single-source dependency in battery pack supply chains. Manufacturing concentrates in China, Germany, and South Korea, with the Yangtze River Delta, Bavarian chemical corridor, and Gyeonggi-Seoul cluster anchoring regional production. Feedstock supply draws from ethylene oxide crackers, silicone precursors, and synthetic hydrocarbon refineries. Tariff exposure on Chinese-sourced glycol derivatives poses structural risk as trade policy shifts. Distribution runs through captive blending facilities at gigafactory sites and regional chemical distributors serving aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EV coolant demand compounds as a regulatory mandate, with EPA SNAP thermal-efficiency standards and EU F-Gas phase-downs forcing specification upgrades across passenger and commercial vehicle programs.
For Market Incumbents: Extend formulation R&D partnerships with solid-state battery developers to secure qualification timelines before 800V architectures mainstream, while adding captive blending capacity in India and Southeast Asia to capture PLI-scheme-driven localization requirements. Non-fluorinated dielectric fluid validation represents the critical defensive lever against specialty chemical entrants.
For New Entrants and Emerging Players: Silicone-based dielectric fluid platforms offer technology-first wedge opportunity in premium European EV architectures facing compressed fluorinated-compound substitution deadlines. Target aftermarket thermal management services for legacy fleet conversions and second-life battery stationary storage applications where established suppliers lack dedicated service infrastructure. Pursue direct contracting with California-based logistics operators piloting fluid-as-a-service models.
For Investors and Strategic Acquirers: Roll-up economics work for regional blenders with GB/T certification infrastructure because China's MIIT mandates effectively screen out unqualified imports, creating captive local demand pools. Five-to-ten-year viability hinges on non-fluorinated formulation portfolios. Watch for EPA SNAP rulemaking expansion to heavy-duty segments as the inflection signal for commercial fleet coolant volume acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Captive glycol feedstock supply secures margin stability against petrochemical volatility for BASF and Shell. |
| Non-Fluorinated Dielectric Fluid Development | Silicone and synthetic hydrocarbon platforms address EU F-Gas prohibitions for premium European OEM thermal teams. |
| GB/T Certification Infrastructure Investment | Localized testing capabilities unlock Chinese EV procurement under MIIT mandates for BYD and CATL supply chains. |
| Fluid-as-a-Service Contracting | Lifecycle thermal management revenue pools emerge as California fleet operators unbundle coolant from vehicle purchase agreements. |
| Solid-State Battery Co-Development Partnerships | Hybrid phase-change and liquid cooling specifications require early coolant supplier engagement with Korean and Japanese OEMs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with thermal management engineers at battery pack integrators, procurement leads at commercial fleet operators, chemical formulator R&D directors, and aftermarket service program managers with secondary validation through EPA SNAP regulatory filings, EU F-Gas Regulation amendments, MIIT GB/T certification protocols, customs trade data on glycol derivative flows, and SEC 10-K disclosures from integrated oil majors. Bottom-up volume estimates from vehicle production databases and top-down market sizing from chemical consumption trends were triangulated to anchor projections.
Comparable-period anchoring linked historical reference data across the projection horizon to modeled forward estimates. Segmentation dimensions included coolant chemistry type, battery voltage architecture, cooling technology integration depth, vehicle platform class, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to validated base-year estimates, with inputs from electrochemical compatibility testing timelines and fluorinated compound phase-down schedules.
The model holds under stable petrochemical feedstock pricing and sustained EV production scaling; deviation in trade policy restrictions on Chinese chemical exports or accelerated solid-state battery commercialization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
BEV Electric Drive Unit Market
Electric Vehicles
India Solar E-Bike Market
Electric Vehicles
Europe Fuel Cell Electric Vehicle Market
Electric Vehicles
Belgium E-Bike Market
Electric Vehicles
Automotive Battery Pack Compression Pad Market
Electric Vehicles
Electric Vehicle Liquid-Cooled Charging Connector Market
Electric Vehicles
France Hybrid Electric Vehicle Battery Market
Electric Vehicles
Global Smart Electric Drive Market
Electric Vehicles
Electric Passenger Cars Market
Electric Vehicles
Electric Vehicle Testing, Inspection, and Certification Market
Electric Vehicles
Off-Highway Electric Machine Battery Pack Systems Market
Electric Vehicles
Electric Vehicle (EV) Battery Housing Market
Electric Vehicles
Commercial Electric Vehicle Dynamic Braking Resistors Market
Electric Vehicles
Electric Vehicle Control Unit Market
Electric Vehicles
Europe Hybrid Electric Vehicle Battery Market
Electric Vehicles
Germany Solar E-Bike Market