
 China Automotive High Performance Electric Vehicle Market | 2026-2036
China Automotive High Performance Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
China Automotive High Performance Electric Vehicle Market Intelligence
Market Context
Silicon carbide power electronics is fragmenting legacy IGBT supply chains across China's high-performance EV sector. BYD leverages captive semiconductor fabrication to shield margin pools from external foundry constraints. NIO sustains battery-swap infrastructure as a proprietary moat against plug-in charging commoditization. XPeng competes on software-defined architecture, pushing over-the-air update cadence as a retention mechanism.
Technical Definition and Segment Structure
China automotive high performance electric vehicles are battery-electric drivetrain platforms engineered for sustained output above 200 kW, utilizing liquid-cooled thermal management systems and dual-motor torque vectoring for dynamic stability control. These vehicles serve commercial fleet operators and private buyers demanding sub-four-second acceleration with highway-range capability exceeding 500 km under CLTC protocols. Battery technology stratification shows lithium iron phosphate dominating volume production for mid-range SUVs while nickel-manganese-cobalt chemistry anchors premium sports car architectures where energy density commands price premiums. Vehicle type segmentation reveals passenger cars as the mature revenue base whereas sports cars represent the fastest-growing margin pool as domestic brands challenge imported performance heritage.
Regulatory Framework and Outlook
MIIT administers NEV credit mandates and GB standards for electromagnetic compatibility, while SAMR enforces market access rules and anti-monopoly scrutiny of vertical tie-ins between automakers and charging networks. MEE's dual carbon goals tighten lifecycle emission accounting, pressuring manufacturers to localize battery recycling and renewable energy procurement for production facilities. Stakeholders must monitor how GB standard revisions for solid-state battery safety protocols reshape certification timelines and first-mover qualification windows.
Market Dynamics
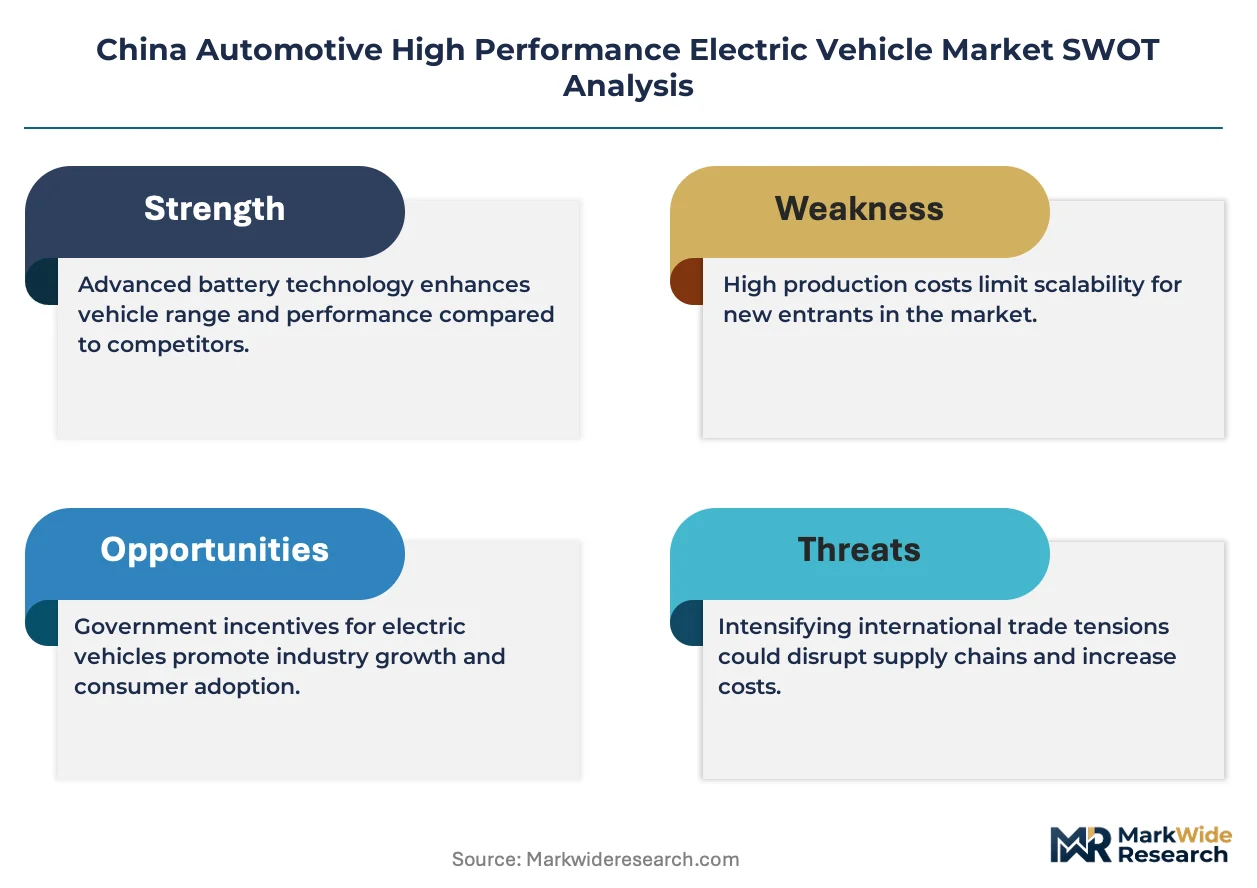
Silicon carbide power electronics is collapsing legacy IGBT supply chains across China's high-performance EV sector, forcing automakers to secure captive semiconductor fabrication or risk margin erosion from external foundry constraints.
Growth Catalysts
- Fleet operator procurement:Logistics and ride-hailing services are scaling high-performance EV procurement to meet dual carbon compliance deadlines and reduce total cost of ownership across high-mileage duty cycles.
- MIIT dual credit policy:Tightened NEV credit thresholds compel domestic manufacturers to accelerate high-performance platform development or face purchasing credit deficits from competitors.
- Yangtze River Delta concentration:Shanghai, Suzhou, and Ningbo form a dense supplier ecosystem where battery cell, motor, and power electronics production clusters within 200-kilometer radii.
Market Restraints
- IGBT supply concentration:Legacy power semiconductor supply chains remain concentrated among a limited set of external foundries, exposing automakers to allocation risk during capacity crunches.
- Nickel-manganese-cobalt input volatility:Premium sports car architectures depend on energy-dense cathode chemistries vulnerable to cobalt and nickel price swings on global commodity exchanges.
- GB standard revision friction:Pending electromagnetic compatibility certification updates create timeline uncertainty for platform launches, compressing first-mover qualification windows.
Strategic Opportunities
- Battery-swap infrastructure:Proprietary swap station networks offer differentiation against plug-in charging commoditization, particularly for fleet operators demanding minimal downtime.
- Solid-state battery transition:Emerging safety protocols under GB standard development create qualification advantages for early movers in premium performance segments.
- Software-defined architecture:Over-the-air update capabilities enable recurring revenue streams and retention mechanisms beyond initial vehicle sale transactions.
Industry Challenges
- Power electronics talent scarcity:Silicon carbide device design and thermal management engineering expertise remains concentrated among semiconductor specialists, forcing automakers to compete for limited personnel.
- Battery recycling localization:MEE lifecycle emission accounting mandates require domestic recycling infrastructure investment, yet qualified hydrometallurgical processing capacity lags cell production expansion.
- Thermal system integration complexity:Dual-motor torque vectoring and sustained 200 kW+ output demand liquid-cooled architectures that strain existing supplier engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Automotive High Performance Electric Vehicle Market |
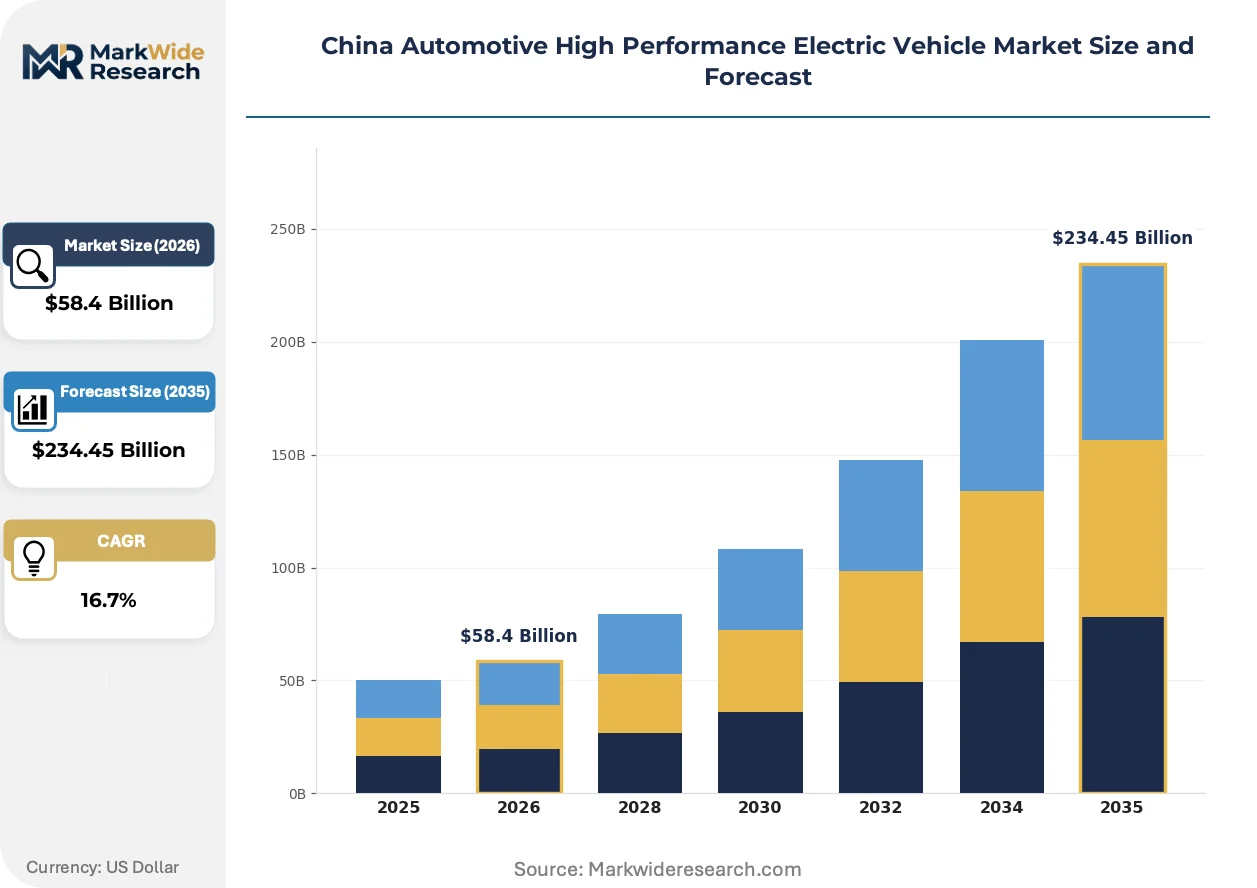
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $234.45 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Cars, SUVs, Sports Cars, Light Trucks Battery Technology: Lithium-Ion, Solid-State, Nickel-Manganese-Cobalt, Lithium Iron Phosphate Charging Infrastructure: Fast Charging Stations, Home Chargers, Ultra-Fast Chargers, Wireless Charging Market Segment: Luxury Segment, Mid-Range Segment, Budget Segment, Fleet Management |
| Companies Covered | BYD, NIO, XPeng, Geely, Li Auto, Xiaomi, Leapmotor, GAC Aion, SAIC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Automotive High Performance Electric Vehicle Market Strategic Shifts & Innovations
Power semiconductor substrate technology is actively reshaping cost structures and thermal performance benchmarks across China's high-performance EV supply base, compressing traditional component hierarchies.
Silicon carbide MOSFETs replace silicon IGBTs in traction inverters, enabling higher switching frequencies and reduced thermal losses. Tier-1 suppliers and captive automaker fabs are converting 8-inch wafer lines to accommodate automotive-grade SiC device volumes. This transition is collapsing the cost premium between high-performance and mass-market drivetrain architectures, democratizing sub-four-second acceleration capability.
MEE dual carbon goals tighten lifecycle emission accounting for production facilities and supply chains. Manufacturers must localize renewable energy procurement and battery recycling operations to satisfy carbon intensity thresholds for NEV credit qualification. Premium sports car segments face the steepest compliance costs given energy-intensive nickel-manganese-cobalt cell production.
Fleet procurement committees now prioritize total cost of ownership metrics over upfront capital expenditure, compressing traditional dealer-centric sales cycles. Direct manufacturer relationships and subscription-style service bundling displace legacy distribution channels for logistics and ride-hailing operators. This behavioral shift concentrates most visibly in the Yangtze River Delta, where fleet density and charging infrastructure maturity enable operational data transparency.
China Automotive High Performance Electric Vehicle Market Segmentation
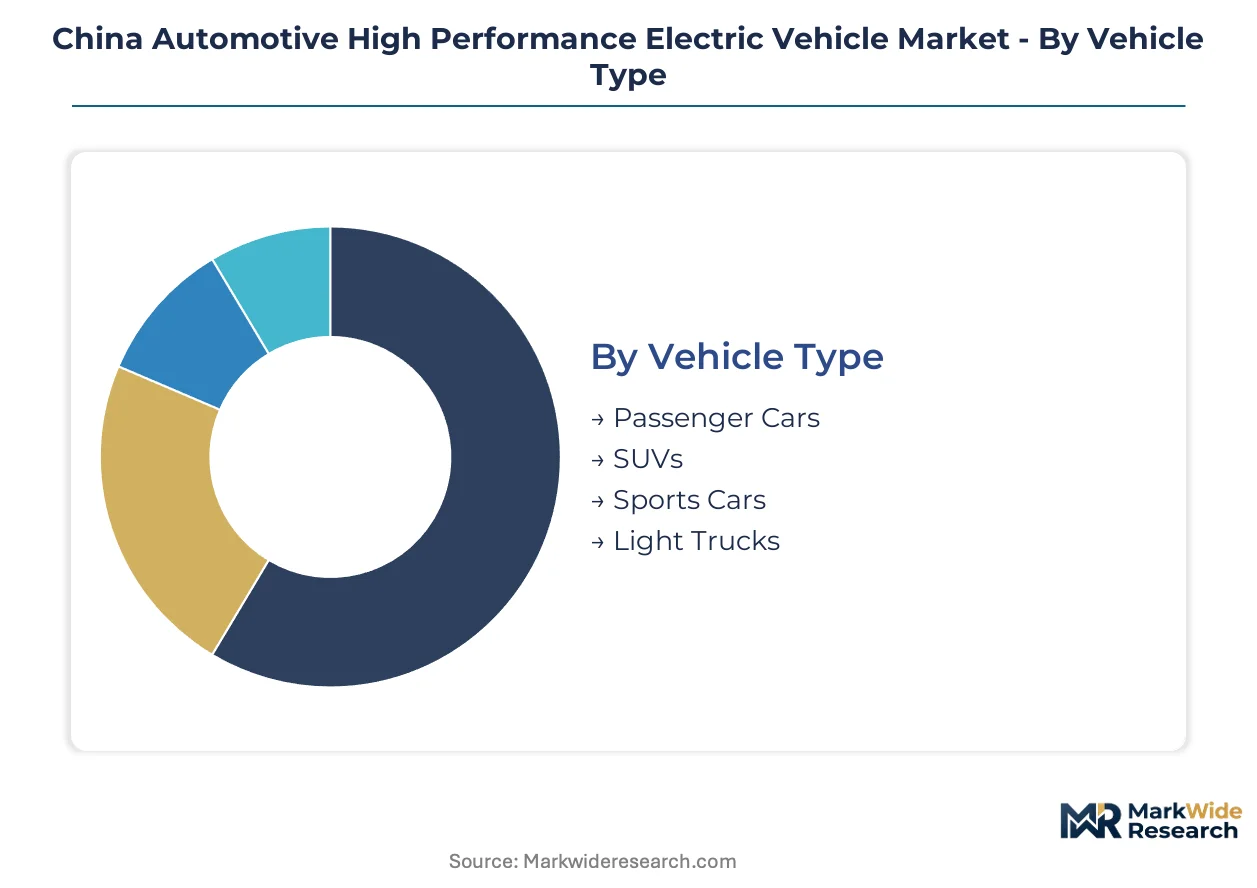
Segmentation in China's high-performance EV market reveals how distinct customer cohorts demand differentiated service architectures. Fleet operators prioritize uptime guarantees and swap-station proximity, while private buyers in premium tiers emphasize performance calibration and over-the-air feature continuity.
Vehicle Type:
After-sales-service intensity varies sharply across vehicle architectures, with dual-motor platforms demanding specialized thermal system diagnostics and torque-vectoring recalibration protocols.
- Passenger Cars:Liquid-cooled battery packs and sustained 200 kW+ output define these platforms. Demand clusters among Yangtze River Delta private buyers seeking sub-four-second acceleration with highway-range capability exceeding 500 km under CLTC protocols, though MIIT credit thresholds pressure manufacturers to localize semiconductor fabrication.
- SUVs:Dual-motor torque vectoring and dynamic stability control dominate engineering specifications. Logistics fleet operators in Shanghai and Suzhou scale procurement for high-mileage duty cycles where total cost of ownership metrics override upfront capital expenditure.
- Sports Cars:Energy-dense nickel-manganese-cobalt chemistries anchor premium architectures. Domestic brands challenge imported performance heritage.
- Light Trucks:Commercial logistics applications prioritize payload capacity and charging infrastructure compatibility. Ride-hailing services in Ningbo pilot operational deployments.
By volume, SUVs lead procurement scales among fleet operators. By growth pace, Sports Cars are ahead as margin pools attract domestic engineering investment.
Battery Technology:
Cost tier stratification determines which chemistries penetrate mass production versus premium niche applications.
- Lithium-Ion:Mature cell architectures with established supply chains and recycling infrastructure. Yangtze River Delta manufacturers leverage proximity to cathode material processing facilities.
- Solid-State:Emerging safety protocols under GB standard development create qualification windows for early movers. Premium sports car segments pilot pre-commercial volumes pending certification timeline clarity from SAMR.
- Nickel-Manganese-Cobalt:Energy density commands price premiums in sustained high-output applications. Cobalt and nickel price volatility on global commodity exchanges exposes margin pools.
- Lithium Iron Phosphate:Dominates mid-range SUV volume production where thermal stability and cycle life outweigh energy density requirements. BYD's captive cell production exemplifies backward integration strategies.
By installed capacity, Lithium Iron Phosphate leads production volumes. By technology transition momentum, Solid-State is climbing the fastest pending GB standard finalization.
Charging Infrastructure:
Application context dictates infrastructure investment priority, with fleet operators demanding minimal downtime and residential users emphasizing cost efficiency.
- Fast Charging Stations:200 kW+ DC infrastructure enables 30-minute replenishment cycles. NIO's proprietary swap station networks differentiate against plug-in charging commoditization in Shanghai metropolitan corridors.
- Home Chargers:AC Level 2 residential installations dominate private ownership economics. Suzhou and Ningbo suburban penetration rates reflect dwelling-type distribution and grid capacity allocation.
- Ultra-Fast Chargers:Silicon carbide power electronics enable 350 kW+ peak delivery. Highway corridor deployment concentrates along Yangtze River Delta intercity routes serving fleet logistics operators.
- Wireless Charging:Inductive pad systems pilot in premium residential and commercial parking applications. Standardization gaps under MIIT electromagnetic compatibility protocols delay mass deployment.
By deployment scale, Fast Charging Stations lead infrastructure investment. By capability expansion, Ultra-Fast Chargers are gaining share fastest as SiC device costs compress.
Market Segment:
Customer type determines pricing architecture and distribution channel configuration, with direct manufacturer relationships displacing legacy dealer networks.
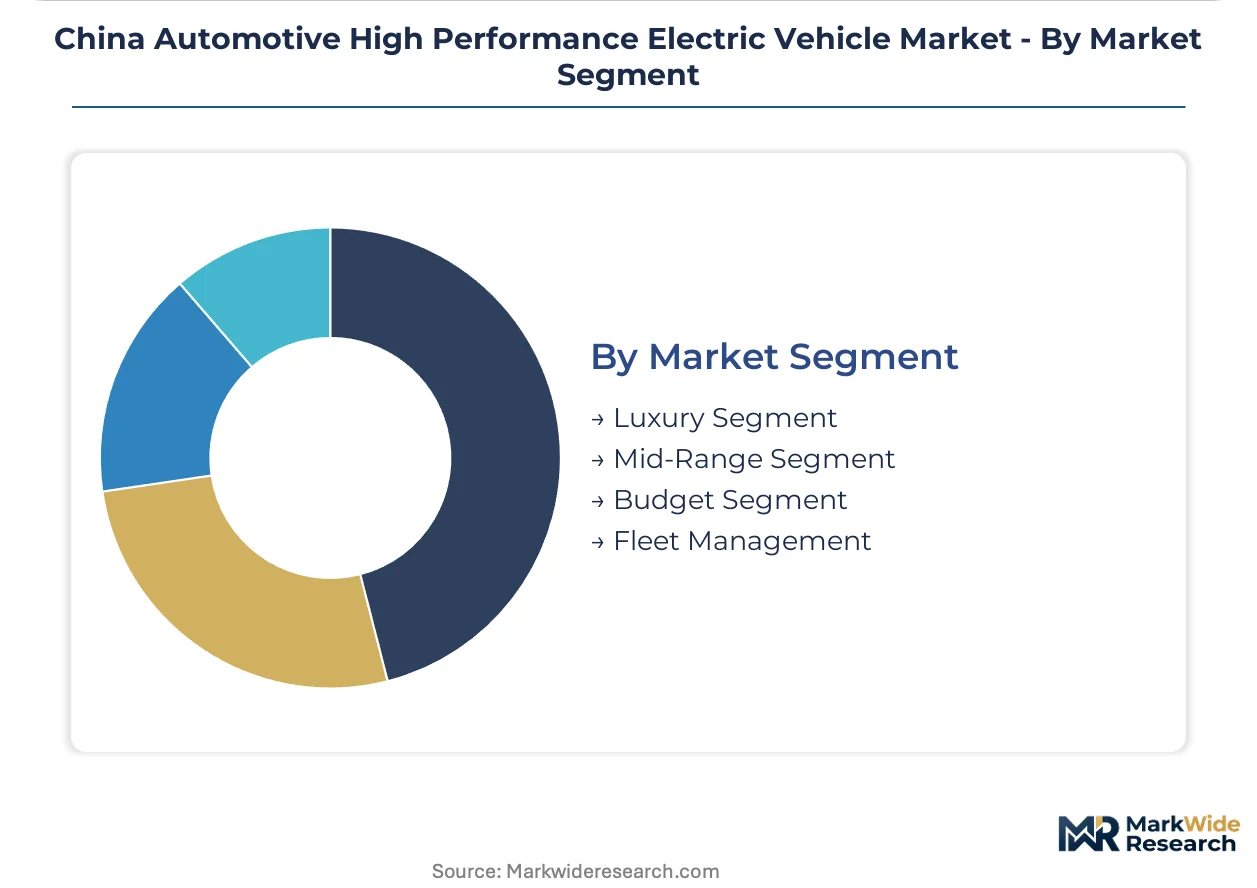
- Luxury Segment:Software-defined architectures with over-the-air update cadence as retention mechanisms. XPeng competes on autonomous driving compute and user experience differentiation.
- Mid-Range Segment:Lithium iron phosphate platforms balance performance accessibility with total cost of ownership optimization. Yangtze River Delta household penetration concentrates here.
- Budget Segment:Constrained thermal management and single-motor configurations prioritize capital efficiency. MIIT dual credit policy compliance thresholds limit manufacturer participation.
- Fleet Management:Subscription-style service bundling and predictive maintenance contracts align procurement with operational data transparency. Logistics and ride-hailing operators in Shanghai scale high-performance EV procurement to meet MEE dual carbon compliance deadlines.
By revenue concentration, Luxury Segment anchors margin extraction. By expansion trajectory, Fleet Management is expanding most quickly as procurement committees institutionalize total cost of ownership metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports high-performance EV platforms and battery systems to European fleet operators and Southeast Asian markets, with Yangtze River Delta production clusters serving as the primary dispatch nodes for international shipments.
Yangtze River Delta
Shanghai, Suzhou, and Ningbo concentrate battery cell, motor, and power electronics production within 200-kilometer radii. MIIT dual credit policy thresholds compel manufacturers here to accelerate high-performance platform development. Logistics fleet operators in Shanghai metropolitan corridors scale procurement to meet MEE dual carbon compliance deadlines.
Pearl River Delta
Shenzhen and Guangzhou anchor silicon carbide device fabrication and automotive semiconductor design centers. SAMR market access rules enforce anti-monopoly scrutiny of vertical tie-ins between automakers and charging networks. Premium sports car engineering teams cluster in Guangzhou to challenge imported performance heritage.
Beijing-Tianjin-Hebei
Beijing-based autonomous driving compute development and policy pilot zones drive software-defined architecture investment. MEE lifecycle emission accounting mandates pressure manufacturers to localize renewable energy procurement for production facilities. Ride-hailing services in Tianjin pilot battery-swap operational deployments.
Sichuan-Chongqing
Chengdu and Chongqing serve as western manufacturing hubs for lithium iron phosphate battery pack assembly. GB standards for electromagnetic compatibility create certification timeline uncertainty for platform launches. Logistics operators here leverage lower electricity costs for high-mileage fleet duty cycles.
China Automotive High Performance Electric Vehicle Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base clusters around three strategic archetypes: captive semiconductor fabricators shielding margin pools, proprietary infrastructure operators differentiating through service ecosystems, and software-centric challengers competing on over-the-air capability. Dominant competitive moves include backward integration into power electronics supply and strategic partnerships for battery-swap network density.
Among domestic automakers, BYD exemplifies the captive fabrication archetype through in-house semiconductor production. NIO occupies a position within the infrastructure-operator tier, while XPeng represents the software-defined challenger segment. These three companies anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| BYD |
| NIO |
| XPeng |
| Geely |
| Li Auto |
| Xiaomi |
| Leapmotor |
| GAC Aion |
| SAIC |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta production cluster anchors China's high-performance EV supply base, with Shanghai, Suzhou, and Ningbo concentrating battery cell and power electronics fabrication within tight radii. This geographic density grants incumbent manufacturers procurement leverage over cathode material and silicon carbide substrate suppliers, compressing input cost differentials between volume and premium tiers while amplifying pricing power for fleet-scale contracts.
Pricing Analysis
Silicon carbide MOSFET pricing against legacy silicon IGBT benchmarks defines the current technology-generation gap in traction inverter costs. Three-tier pricing structure across premium, standard, and economy levels stratifies by thermal management sophistication and over-the-air service bundling, with certification grade for GB electromagnetic compliance adding further differentiation. Cost compression in mid-range SUVs intensifies as lithium iron phosphate cell output scales, while premium sports car segments retain pricing resilience through nickel-manganese-cobalt chemistry scarcity. Fleet operators exhibit highest price sensitivity due to total cost of ownership procurement mandates, whereas luxury private buyers prioritize performance calibration over capital expenditure.
Supply Chain Analysis
Export control regimes on advanced lithography equipment constrain domestic semiconductor fabrication scaling for automotive-grade silicon carbide devices. China, South Korea, and Japan anchor cathode active material production, with the Yangtze River Delta drawing from Indonesian nickel and Chilean lithium feedstocks. Single-source vulnerability concentrates in high-purity silicon carbide substrate supply, where limited qualified wafer vendors expose automakers to allocation risk. Distribution runs through captive OEM logistics networks and Tier 1 system integrators serving fleet procurement committees directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as fleet procurement committees institutionalize total cost of ownership metrics, creating niche openings for specialized service bundling and swap-station operators outside incumbent direct-sales channels.
For Market Incumbents: Insulate margin pools through captive silicon carbide fabrication investment, mirroring BYD's backward integration into semiconductor production. Secure long-term offtake agreements with Indonesian nickel and Chilean lithium suppliers to hedge cathode chemistry cost volatility. Prioritize GB standard certification pre-positioning for solid-state battery protocols ahead of SAMR timeline clarity.
For New Entrants and Emerging Players: Establish a beachhead in battery-swap infrastructure deployment for logistics fleet operators in Ningbo and Suzhou, where charging downtime costs exceed premium hardware pricing. Target ride-hailing procurement committees with subscription-style service bundling that decouples vehicle access from ownership. Differentiate through predictive maintenance contracts leveraging operational data transparency.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-defined architecture specialists with over-the-air update capabilities and autonomous driving compute roadmaps. Long-term viability over a multi-year horizon rests on recurring revenue attachment rates beyond initial vehicle transactions. Monitor NIO's swap-station network density metrics as an inflection indicator for infrastructure-operator model scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Fabrication Scale-Up | Captive wafer production shields BYD from external foundry allocation constraints during capacity crunches. |
| Battery-Swap Network Expansion | NIO's proprietary station density creates service differentiation against plug-in charging commoditization in Shanghai corridors. |
| Software-Defined Vehicle Investment | XPeng's over-the-air cadence enables retention mechanisms and recurring revenue streams beyond initial sales. |
| Solid-State Battery Certification Pathway | Early GB standard qualification creates first-mover positioning in premium sports car segments pending SAMR clarity. |
| Fleet Management Platform Integration | Direct manufacturer relationships with logistics operators displace legacy dealer networks through operational data transparency. |
Research Approach
Findings reconcile primary fieldwork against secondary review of MIIT production filings, SAMR market access registrations, and Yangtze River Delta customs data for battery component trade flows. OEM platform engineers, Tier 1 supplier procurement leads, fleet operations directors at logistics and ride-hailing services, charging infrastructure developers, and semiconductor fabrication specialists provided structured input. Bottom-up vehicle production estimates triangulated against top-down NEV credit compliance modeling.
Forecast inputs span vehicle class segmentation, propulsion architecture differentiation, battery chemistry stratification, and regional production cluster capacity expansion across the analysis window. CAGRs derived from installed base turnover rates, technology substitution curves for silicon carbide adoption, and fleet procurement cycle timing. MIIT dual credit policy thresholds and MEE lifecycle emission accounting mandates shaped scenario weightings.
Stress conditions across nickel-cobalt price volatility, GB standard revision timelines, and silicon carbide wafer supply allocation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on fleet electrification deadlines and renewable energy procurement localization. Material shifts in export control regime stringency or solid-state battery certification acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Loader Rickshaw Market
Electric Vehicles
US Electric Vehicle Market
Electric Vehicles
Self Balancing Electric Scooter Market
Electric Vehicles
Singapore Electric Vehicle Market
Electric Vehicles
New Zealand E-Bike Market
Electric Vehicles
Electric Passenger Cars Market
Electric Vehicles
Global Golf Cart and Neighborhood Electric Vehicle (NEV) Market
Electric Vehicles
China NEV Taxi Market
Electric Vehicles
Italy Hybrid Electric Vehicle Battery Market
Electric Vehicles
Electric Vehicle Traction Inverter System Market
Electric Vehicles
Canada Solar E-Bike Market
Electric Vehicles
Global Automotive Inductive Wireless Charging Systems Market
Electric Vehicles
Middle-East and Africa E-Bike Market
Electric Vehicles
Electric Vehicle Cold Plates Market
Electric Vehicles
Asia Pacific Automotive High Performance Electric Vehicles Market
Electric Vehicles
Electric Vehicle Skateboard Chassis Market