

Preassembled Harness Modules for Skateboard EV Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Preassembled Harness Modules for Skateboard EV Platforms Market Insights
China's wire harness manufacturing belt is consolidating as domestic EV platform producers expand captive sourcing. Aptiv leverages its integrated electrical architecture portfolio to anchor premium skateboard platform contracts. Sumitomo Electric Industries sustains high-volume production lines optimized for flat, flexible conductor geometries. Yazaki Corporation dominates traditional automotive harness channels while extending engineering resources toward low-voltage skateboard configurations.
Preassembled harness modules for skateboard EV platforms integrate power distribution, signal routing, and sensor interfacing into compact, flat-form cable assemblies designed for under-deck mounting in battery-skateboard architectures. These modules typically employ aluminum conductors with silicone insulation rated to 150°C, manufactured via automated crimping and ultrasonic welding to withstand vibration and thermal cycling in urban mobility duty cycles. Power distribution harnesses occupy the largest revenue pool due to copper-aluminum hybrid conductor premiums and high-current connector specifications. Ethernet-based communication data harnesses represent the fastest-expanding technology segment as skateboard platforms adopt domain-controller architectures requiring 100 Mbps+ data throughput.
China's MIIT enforces GB/T standards for EV high-voltage wiring that directly shape conductor gauge and insulation requirements for export-bound skateboard platforms. The EU's REACH and RoHS frameworks restrict halogenated flame retardants in harness sheathing, compelling material reformulation across Asian supplier bases. Stakeholders must monitor how battery enclosure integration trends will redefine harness routing geometries and connector accessibility requirements.
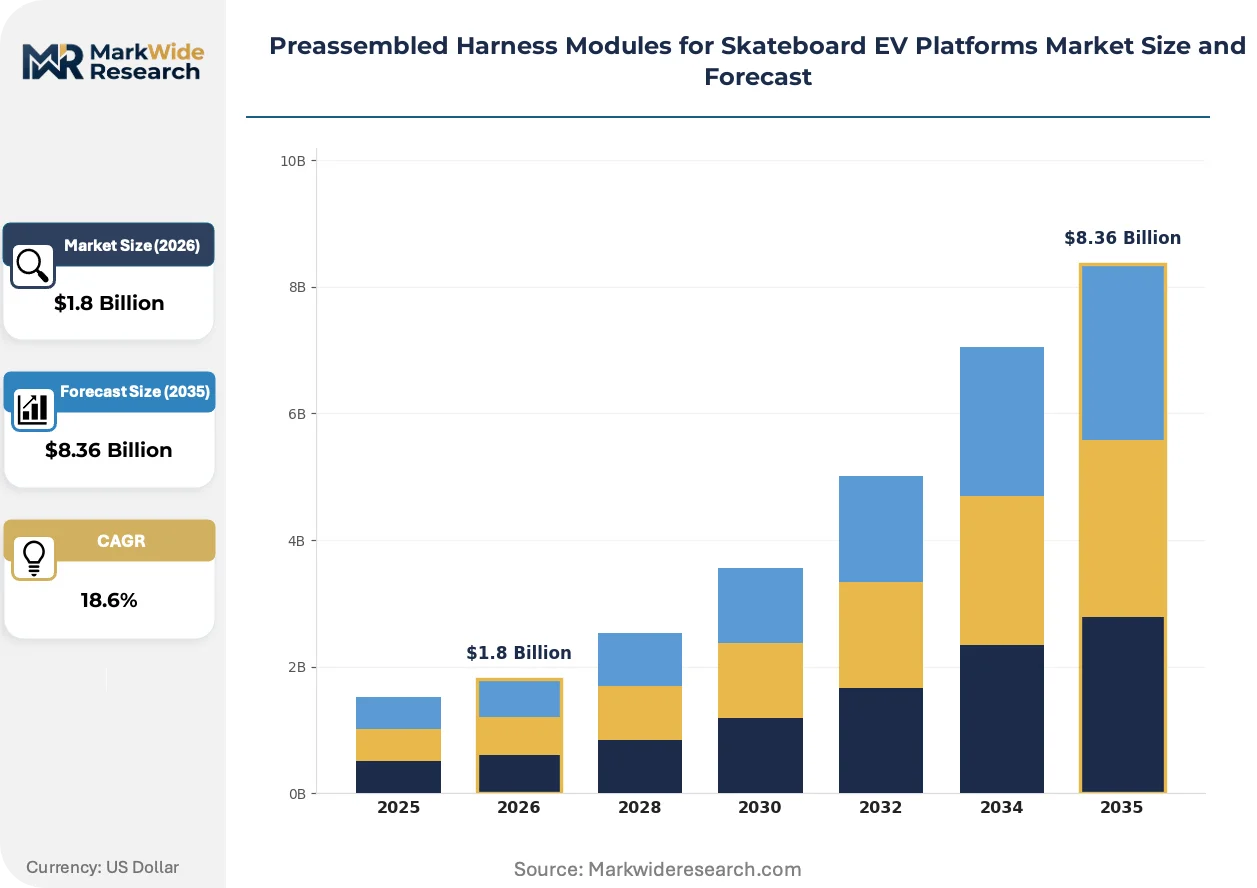
Market Dynamics
Skateboard EV platform standardization is compressing harness design cycles as OEMs migrate from vehicle-specific wiring to modular, reusable architectures. China's MIIT GB/T standards and the EU's REACH framework are forcing simultaneous compliance across conductor materials and flame-retardant sheathing, creating dual-certification burdens for export-oriented suppliers.
Growth Catalysts
- MIIT dual carbon mandates:China's binding emissions targets accelerate EV platform electrification, expanding captive harness module procurement from domestic OEMs.
- Domain-controller architectures:Skateboard platforms integrating battery management and thermal systems require consolidated power-signal-data harness modules.
- Guangdong supplier clustering:Tier-one harness manufacturers co-locating with BYD and Xpeng assembly plants reduce logistics friction and enable just-in-sequence delivery.
Market Restraints
- Aluminum conductor volatility:London Metal Exchange aluminum pricing swings compress module margins for suppliers locked into annual OEM contracts.
- Single-source connector dependency:High-current interface designs from TE Connectivity and Amphenol create supply concentration risk for 300A+ power distribution harnesses.
- REACH substance restrictions:ECHA's evolving SVHC list forces iterative reformulation of halogen-free sheathing compounds, extending R&D timelines.
Strategic Opportunities
- India PLI scheme for EV components:Production-linked incentives attract harness module assembly to Tamil Nadu and Gujarat as domestic skateboard platform demand emerges.
- Solid-state battery integration:Next-generation cell architectures with reduced thermal management complexity enable slimmer, lower-cost harness routing geometries.
- Service-unbundled aftermarket:Independent repair networks create replacement harness module demand outside OEM captive supply chains.
Industry Challenges
- Ultrasonic welding technician scarcity:Automated aluminum-to-copper jointing requires specialized equipment operators, constraining capacity expansion at tier-two suppliers.
- Cross-border GB/T-REACH compliance:Dual certification testing for Chinese domestic and EU-export platforms extends product validation cycles by 4-6 months.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Preassembled Harness Modules for Skateboard EV Platforms Market Trends and Innovations
Harness module architectures are flattening and consolidating as skateboard platforms eliminate traditional engine-bay packaging constraints. Three intersecting developments are restructuring supplier technical roadmaps and OEM sourcing criteria.
Ethernet-based data harnesses are converging with power distribution layers in unified flat-cable assemblies. Tier-one skateboard platform producers in China and Germany are adopting 100BASE-T1 and 1000BASE-T1 specifications for camera-lidar fusion and over-the-air update pipelines. This convergence is compressing connector count per module and shifting value toward semiconductor-embedded intelligent junction boxes.
REACH Annex XVII restrictions on halogenated flame retardants are compelling silicone and thermoplastic polyurethane sheathing reformulations. ECHA's 2023-2024 substance evaluations have disqualified several phosphorus-based alternatives, forcing Asian compound suppliers toward unproven ceramic-filled elastomers. Power distribution harnesses with 150°C continuous rating requirements face the steepest material recertification burdens.
OEM technical specifications are hardening around module-level IP67 sealing and 10-year corrosion warranties. Procurement teams at Volkswagen's CARIAD and Geely's SEA platform divisions now require supplier-financed validation testing for thermal cycling and salt-spray exposure. Chinese OEMs are extending these warranty terms fastest, pressuring domestic harness suppliers to absorb lifetime reliability risk.
Preassembled Harness Modules for Skateboard EV Platforms Market Segmentation
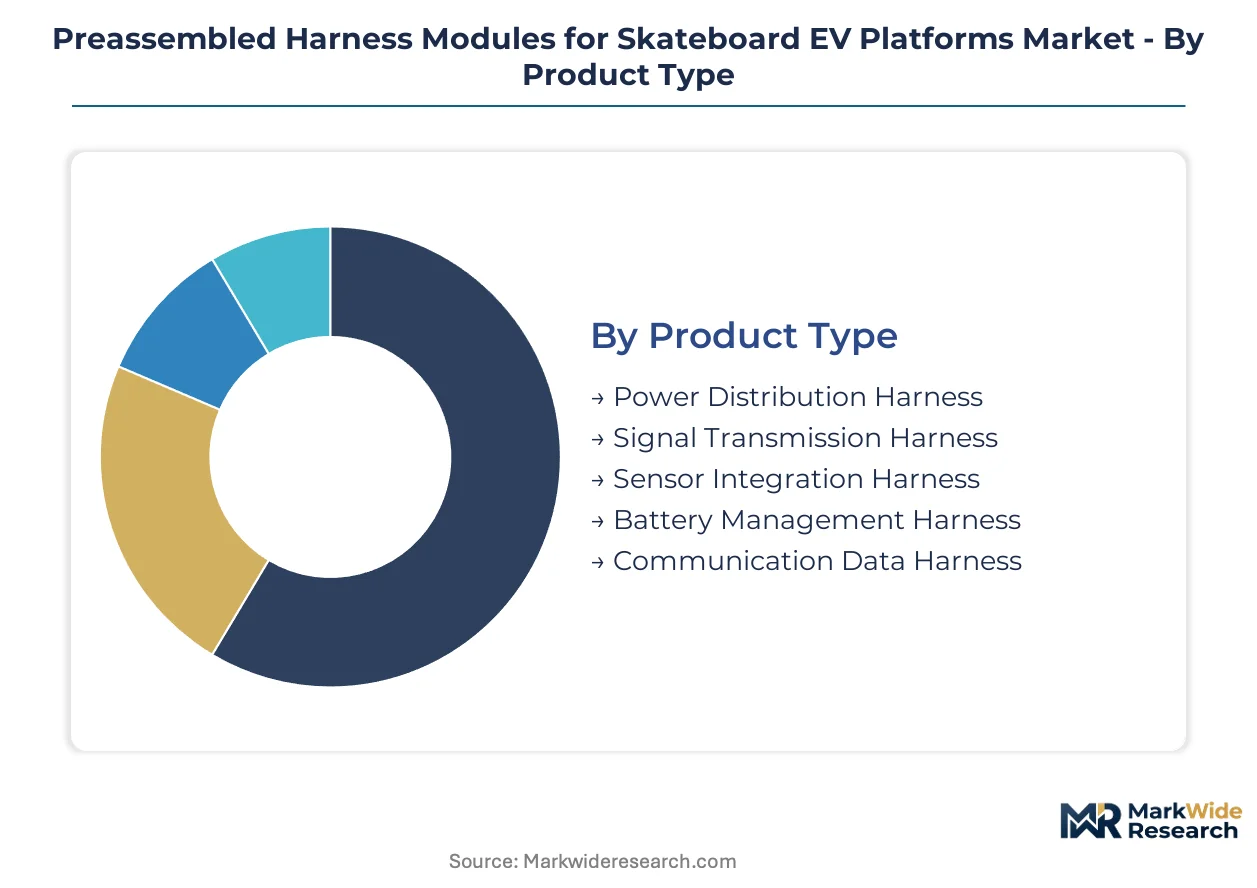
Skateboard EV platform standardization is collapsing traditional vehicle-specific wiring into modular, reusable harness architectures. OEM procurement teams now segment suppliers by conductor material compatibility, communication protocol integration, and thermal rating rather than legacy automotive connector families. This resegmentation rewards manufacturers with automated aluminum-copper welding capabilities and domain-controller-ready Ethernet portfolios.
Product Type:
Supply concentration in Guangdong Province's wire harness manufacturing belt favors suppliers with integrated power-signal-data capabilities over single-function specialists.
- Power Distribution Harness:Aluminum conductors with copper terminals dominate under-deck mounting applications, rated to 300A continuous current. BYD and Xpeng assembly plants in Shenzhen and Huizhou drive captive procurement of hybrid copper-aluminum geometries to reduce platform weight.
- Communication Data Harness:100BASE-T1 and 1000BASE-T1 Ethernet specifications enable camera-lidar fusion and over-the-air update pipelines for domain-controller architectures. German skateboard platform producers at CARIAD specify semiconductor-embedded intelligent junction boxes, compressing connector count per module.
- Signal Transmission Harness:Low-voltage twisted-pair assemblies for brake-by-wire and steering actuation.
- Sensor Integration Harness:Multi-drop configurations aggregating temperature, pressure, and position sensors.
- Battery Management Harness:High-voltage interlock loops and cell monitoring taps integrated into battery enclosure frames.
Today's leader: Power Distribution Harness. Tomorrow's challenger: Communication Data Harness.
Technology:
Cost tiers separate legacy automotive bus protocols from Ethernet-based architectures demanded by next-generation skateboard platforms.
- Ethernet:100BASE-T1 and 1000BASE-T1 specifications deliver 100 Mbps+ throughput for autonomous sensor fusion and software-defined vehicle updates. Tier-one Chinese OEMs specify Ethernet as mandatory for new platform generations, displacing CAN Bus in premium configurations.
- CAN Bus:Controller Area Network remains the volume workhorse for powertrain and chassis control, with ISO 11898-2 compliance required for MIIT GB/T certification. Cost-optimized personal mobility devices in India PLI scheme production clusters specify CAN Bus to minimize microcontroller complexity.
- LIN Bus:Single-wire low-cost protocol for door modules and lighting control in compact urban vehicles.
- FlexRay:Deterministic high-speed bus reserved for brake-by-wire safety-critical loops.
- MOST Bus:Media-oriented transport for infotainment backbones in leisure transport configurations.
Volume concentration favors CAN Bus. Margin expansion concentrates on Ethernet.
Application:
Customer type stratification separates fleet-scale procurement from specialized mobility retail channels with divergent warranty and service requirements.
- Electric Skateboard:The core platform architecture integrating battery-skateboard decks with hub motors and steer-by-wire systems. Geely's SEA platform division and Volkswagen's CARIAD specify preassembled harness modules with 10-year corrosion warranties and IP67 sealing validation.
- Compact Urban Vehicle:Four-wheeled low-speed platforms for last-mile logistics and shared mobility services. Rental fleet operators in Tamil Nadu and Gujarat procurement clusters demand standardized connector accessibility for rapid field replacement.
- Personal Mobility Device:Single-rider electric unicycles and self-balancing transporters.
- Micro-Mobility Solution:Docked and dockless scooter-sharing platforms with high-cycling duty requirements.
- Leisure Transport Device:Golf carts, resort vehicles, and recreational off-road platforms with extended warranty terms.
Procurement scale centers on Electric Skateboard. Service-unbundled growth emerges in Compact Urban Vehicle.
End User:
Geography determines whether harness modules ship through OEM captive supply chains or independent aftermarket networks.
- OEM Manufacturers:Vertically integrated platform producers including BYD, Xpeng, and NIO operate captive harness sourcing with just-in-sequence delivery from Guangdong-based tier-one suppliers. MIIT dual carbon mandates accelerate module standardization across domestic EV platform portfolios.
- Aftermarket Suppliers:Independent repair networks and refurbishment operators create replacement harness demand outside OEM supply chains. ECHA REACH substance restrictions force iterative reformulation of halogen-free sheathing compounds, extending R&D timelines for aftermarket certification.
- Vehicle Assemblers:Contract manufacturers assembling white-label platforms for multiple OEM brands.
- Specialized Mobility Retailers:Direct-to-consumer channels for premium personal mobility devices.
- Rental Fleet Operators:Shared mobility services requiring rapid-swappable harness architectures for uptime optimization.
Volume capture belongs to OEM Manufacturers. Margin defense shifts toward Aftermarket Suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT dual carbon mandates are compressing harness design cycles faster than Germany's REACH-driven material reformulations, yet both geographies now demand simultaneous GB/T and EU certification for export-bound skateboard platforms.
China
Guangdong Province's electronics manufacturing corridor concentrates tier-one harness suppliers adjacent to BYD and Xpeng assembly plants. MIIT enforces GB/T standards for EV high-voltage wiring that dictate conductor gauge and silicone insulation specifications. Shenzhen and Huizhou clusters enable just-in-sequence module delivery to domestic OEM captive supply chains.
Germany
Volkswagen's CARIAD and BMW's Neue Klasse platforms specify preassembled harness modules with 10-year corrosion warranties and IP67 sealing validation. ECHA REACH Annex XVII restrictions on halogenated flame retardants compel silicone and thermoplastic polyurethane sheathing reformulations. Baden-Württemberg suppliers face steepest material recertification burdens for 150°C continuous rating requirements.
United States
Tesla's Cybertruck and Rivian's skateboard architectures drive demand for aluminum-conductor power distribution harnesses rated to 300A continuous current. NHTSA safety standards and EPA emissions frameworks indirectly shape EV platform electrification timelines. Michigan and California assembly plants source from tier-one suppliers with automated crimping and ultrasonic welding capabilities.
India
Tamil Nadu and Gujarat production clusters attract harness module assembly under the PLI scheme for EV components as domestic skateboard platform demand emerges. BIS certification requirements and state-level EV policies accelerate supplier localization. Chennai-based contract manufacturers are scaling capacity for compact urban vehicle fleets requiring standardized connector accessibility.
Japan
Sumitomo Electric Industries and Yazaki Corporation anchor high-volume production lines optimized for flat, flexible conductor geometries. METI carbon neutrality targets and JIS standards shape module standardization for export markets. Kanto and Kansai manufacturing belts sustain engineering resources toward low-voltage skateboard configurations alongside traditional automotive harness channels.
Preassembled Harness Modules for Skateboard EV Platforms Market Competitive Landscape
Chinese producers anchor the high-volume tier; Japanese and German specialists hold premium positions through integrated electrical architecture portfolios. The vendor base splits between consolidated tier-one suppliers with automated aluminum-copper welding capabilities and fragmented tier-two operators constrained by ultrasonic welding technician scarcity. Three archetypes dominate: integrated electrical architecture providers, high-volume flat-conductor specialists, and connector-anchored power distribution fabricators. Capacity expansion and dual-certification compliance investments constitute the dominant competitive moves.
Within the integrated architecture tier, Aptiv exemplifies premium skateboard platform positioning through its consolidated power-signal-data harness modules. Sumitomo Electric Industries and Yazaki Corporation occupy positions among high-volume specialists with optimized production geometries for under-deck mounting applications. TE Connectivity and Amphenol anchor the connector-anchored segment where high-current interface designs create supply concentration risk for 300A+ power distribution harnesses.
| Leading Market Players |
|---|
| Aptiv |
| Samvardhana Motherson |
| Yazaki Corporation |
| Sumitomo Electric Industries |
| LEONI |
| Lear Corporation |
| TE Connectivity |
| Amphenol |
| Furukawa Electric |
| Others |
Pricing and Supply Chain Analysis
Automated ultrasonic welding adoption across Guangdong Province's tier-one harness suppliers is simultaneously compressing per-unit labor costs and concentrating production among operators with certified technician pools. This technology transition rewards scale players with captive aluminum-copper jointing capabilities while tier-two suppliers face margin erosion from manual process premiums and extended validation cycles for GB/T-REACH dual certification.
Pricing Analysis
Capacity additions in Tamil Nadu and Gujarat under India's PLI scheme are reshaping price floors for standard CAN Bus harness modules serving compact urban vehicle fleets. Three-tier pricing structure across premium Ethernet-integrated, standard hybrid conductor, and economy aluminum-only configurations separates OEMs with domain-controller architectures from cost-optimized personal mobility device assemblers. Price differentiation hinges on certification grade and volume scale, with MIIT GB/T compliance commanding premiums over domestic-only configurations. Pricing pressure stems from London Metal Exchange aluminum volatility, with annual contract lock-ins squeezing module margins when spot prices spike. Fleet-scale procurement teams at rental operators exhibit highest price sensitivity, while German platform engineering divisions at CARIAD prioritize performance warranties over unit economics.
Supply Chain Analysis
Ultrasonic welding technician scarcity across Shenzhen and Huizhou manufacturing corridors constrains capacity expansion at tier-two suppliers attempting to scale aluminum-conductor production. Supply concentrates in China, Japan, and Germany, with Guangdong's electronics belt anchoring high-volume output for BYD and Xpeng captive sourcing. Raw material dependencies rest on London Metal Exchange aluminum, copper terminal stock from Korean smelters, and silicone insulation compounds subject to ECHA REACH Annex XVII reformulation mandates. Single-source vulnerability permeates high-current connector procurement from TE Connectivity and Amphenol for 300A+ power distribution harnesses. Distribution runs through OEM captive supply chains with just-in-sequence delivery, though aftermarket suppliers in India and Southeast Asia are building independent refurbishment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in preassembled harness modules derives from Ethernet-integrated premium tier displacement of legacy CAN Bus configurations, enabled by domain-controller architecture standardization across skateboard EV platforms. Aluminum conductor adoption and automated welding penetration create cost-down headroom for suppliers with scale.
For Market Incumbents: Hedge aluminum price exposure through long-term London Metal Exchange hedging instruments or backward integration into conductor drawing operations. Defend against tier-two supplier technology leapfrogging by accelerating ultrasonic welding technician certification programs in partnership with Guangdong vocational institutes. Prioritize GB/T-REACH dual certification investment to capture export-bound platform contracts from German OEMs. For New Entrants and Emerging Players: Enter via India's PLI scheme production clusters in Tamil Nadu and Gujarat, where domestic skateboard platform demand is emerging and captive supplier relationships remain unformed. Target compact urban vehicle fleet operators requiring standardized connector accessibility for rapid field replacement, a segment underserved by incumbent just-in-sequence models. Pursue aftermarket certification pathways for service-unbundled replacement harness demand outside OEM supply chains. For Investors and Strategic Acquirers: Valuations sit cheapest among tier-two suppliers with automated welding equipment but lacking dual-certification completion, creating acquisition targets for capability rollup. Long-term viability favors integrated electrical architecture providers with Ethernet portfolios and domain-controller engineering relationships over single-function power distribution specialists. Watch ECHA SVHC list expansion velocity as inflection indicator for material recertification burden severity and R&D timeline extension risk.| Strategic Initiative | Industry Significance |
|---|---|
| GB/T-REACH Dual Certification Investment | Unlocks export-bound contracts from Volkswagen CARIAD and Geely SEA platform divisions. |
| Ultrasonic Welding Technician Certification Programs | Addresses capacity constraints at tier-two suppliers in Guangdong manufacturing corridors. |
| Aluminum Conductor Backward Integration | Insulates margins from London Metal Exchange price volatility in annual OEM contracts. |
| Ethernet-Integrated Module Portfolio Expansion | Captures premium tier displacement as 100BASE-T1 specifications become mandatory. |
| India PLI Scheme Manufacturing Footprint | Positions for emerging domestic skateboard platform demand in Tamil Nadu and Gujarat clusters. |
Research Methodology
Multiple input streams — OEM platform engineering specifications, tier-one supplier production data, and regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Primary interviews with harness module procurement managers, EV platform architects, and ultrasonic welding equipment specialists were validated against secondary sources including MIIT GB/T standard documentation, ECHA REACH substance evaluation records, and vehicle production databases. Trade flow analysis from customs records and aluminum conductor import registries provided material cost benchmarking.
Data-stream reconciliation across the projection horizon applied segment-specific growth assumptions for power distribution, communication data, and signal transmission harness categories. The analytical framework modeled vehicle class, propulsion architecture, and regional production cluster dimensions alongside conductor material and communication protocol technology tiers. CAGRs were derived from installed base expansion curves and content-per-vehicle trajectories for skateboard platform architectures, with Ethernet adoption rates and aluminum conductor penetration serving as key forecast inputs.
The model holds under stable regulatory enforcement timelines and aluminum price bands; deviation in ECHA SVHC list expansion velocity or London Metal Exchange volatility spikes would shift module margin assumptions and certification timeline estimates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.