
 Battery-Swapping for Electric Two-Wheeler Market | 2026-2036
Battery-Swapping for Electric Two-Wheeler Market Size, Share, and Industry Trends Forecast 2026-2036
Battery-Swapping for Electric Two-Wheeler Market Outlook
Delivery services is consolidating as the dominant end-use vertical for battery-swapping networks, displacing commuter-centric deployment models. Gogoro Inc. leverages its Taiwan manufacturing base to anchor dense station networks across East Asian metros. Sun Mobility competes through fleet-exclusive partnerships with Indian logistics operators. Battery Smart specializes in asset-light operator models for last-mile delivery aggregators.
Battery-swapping for electric two-wheelers denotes a system where depleted battery packs are exchanged for charged units at automated or attended stations, typically completing the swap within two to four minutes to eliminate charging downtime. The architecture relies on standardized pack geometries, CAN-bus communication interfaces, and cloud-connected battery management systems to track state-of-health and cycle count across distributed inventories. Swappable Batteries command the primary revenue pool due to capital intensity in pack production and station buildout, while Hybrid Systems represent the fastest-growing configuration as manufacturers hedge against infrastructure gaps. Smart Charging Solutions within the Technology dimension concentrate margin capture through software-layer subscriptions and predictive maintenance algorithms.
India's CEA and BIS shape pack safety and interoperability mandates, while the PLI scheme directs capital toward domestic cell and pack assembly capacity. Taiwan's NCC and industrial regulators under METI-Japan influence communication protocol standards and cross-border station equipment certification. Stakeholders must monitor whether regulatory fragmentation around battery dimensions and data protocols hardens into trade barriers or converges through IEC and ISO harmonization efforts.
Market Dynamics
Delivery fleet operators are consolidating demand around battery-swapping networks, compressing deployment timelines and forcing infrastructure providers to prioritize high-utilization corridors over scattered commuter stations.
Growth Catalysts
- India's PLI scheme:Domestic cell and pack assembly incentives are reducing import dependency for swappable battery production. Fleet operators are locking in long-term supply contracts with certified local manufacturers.
- Last-mile logistics electrification:E-commerce and quick-commerce delivery aggregators face mounting pressure to eliminate vehicle downtime. Swapping stations positioned at distribution hubs enable continuous fleet rotation.
- CAN-bus standardization:Unified communication protocols between battery management systems and station hardware are cutting integration costs for multi-brand deployments.
Market Restraints
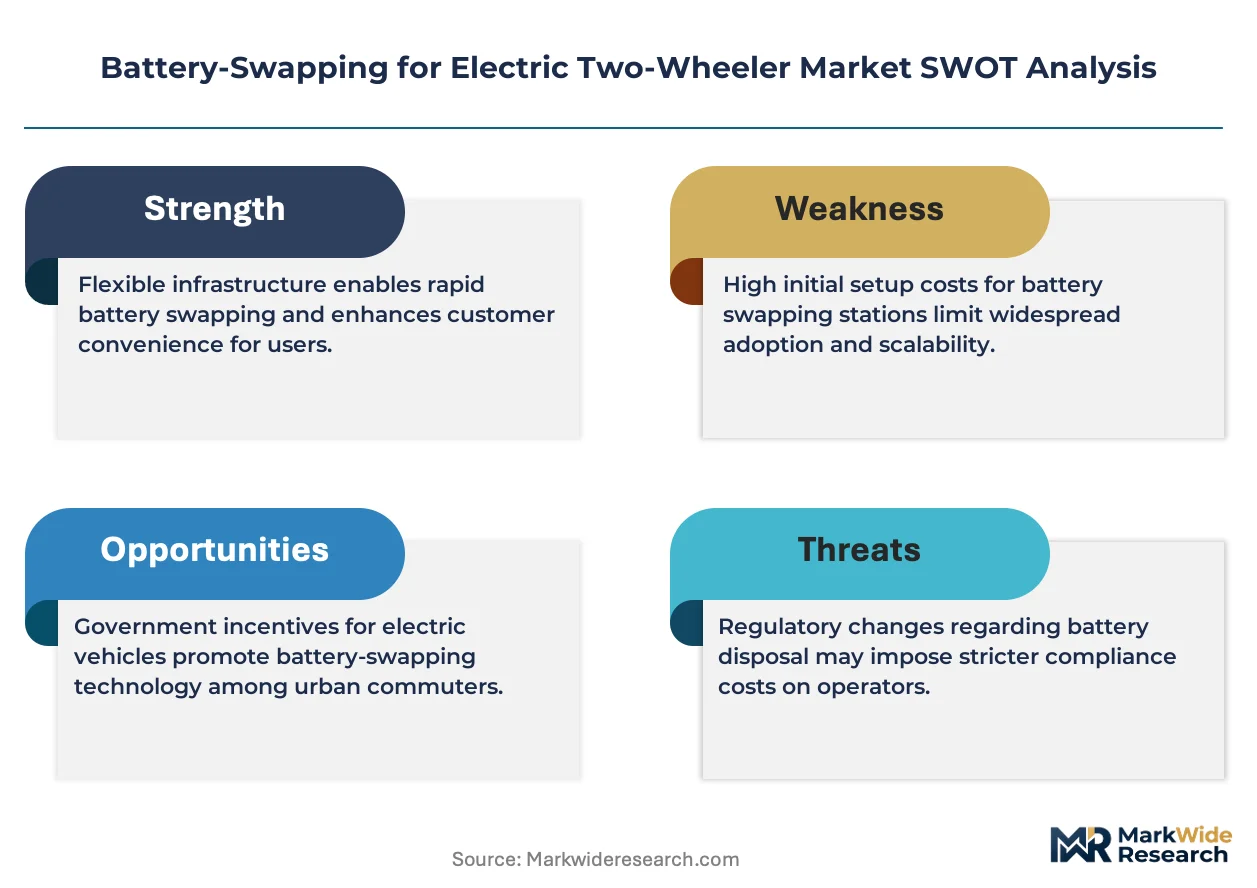
- Lithium price volatility:Cell chemistry costs represent the dominant share of pack manufacturing expenditure, exposing operators to commodity swings without hedging mechanisms.
- Taiwan manufacturing concentration:Station hardware and battery pack assembly clusters heavily around a single geography, creating vulnerability to trade disruption or capacity constraints.
- Interoperability fragmentation:Divergent pack dimensions and data protocols across OEMs force redundant inventory stocking, inflating working capital requirements for network operators.
Strategic Opportunities
- Vietnam urban corridors:Ho Chi Minh City and Hanoi demonstrate concentrated two-wheeler density with minimal home-charging infrastructure, creating first-mover advantage for station networks.
- Cloud-based predictive maintenance:Battery health monitoring subscriptions generate recurring revenue streams independent of physical swap volumes.
- Hybrid system configurations:Manufacturers are hedging infrastructure gaps by offering vehicles compatible with both swapping and plug-in charging, expanding addressable customer segments.
Industry Challenges
- BMS firmware integration:Each OEM requires customized software bridges to station networks, stretching engineering timelines and complicating multi-brand station economics.
- Fire safety certification:Thermal runaway testing protocols under India's CEA and BIS mandates are extending product approval cycles, delaying network expansion schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery-Swapping for Electric Two-Wheeler Market |
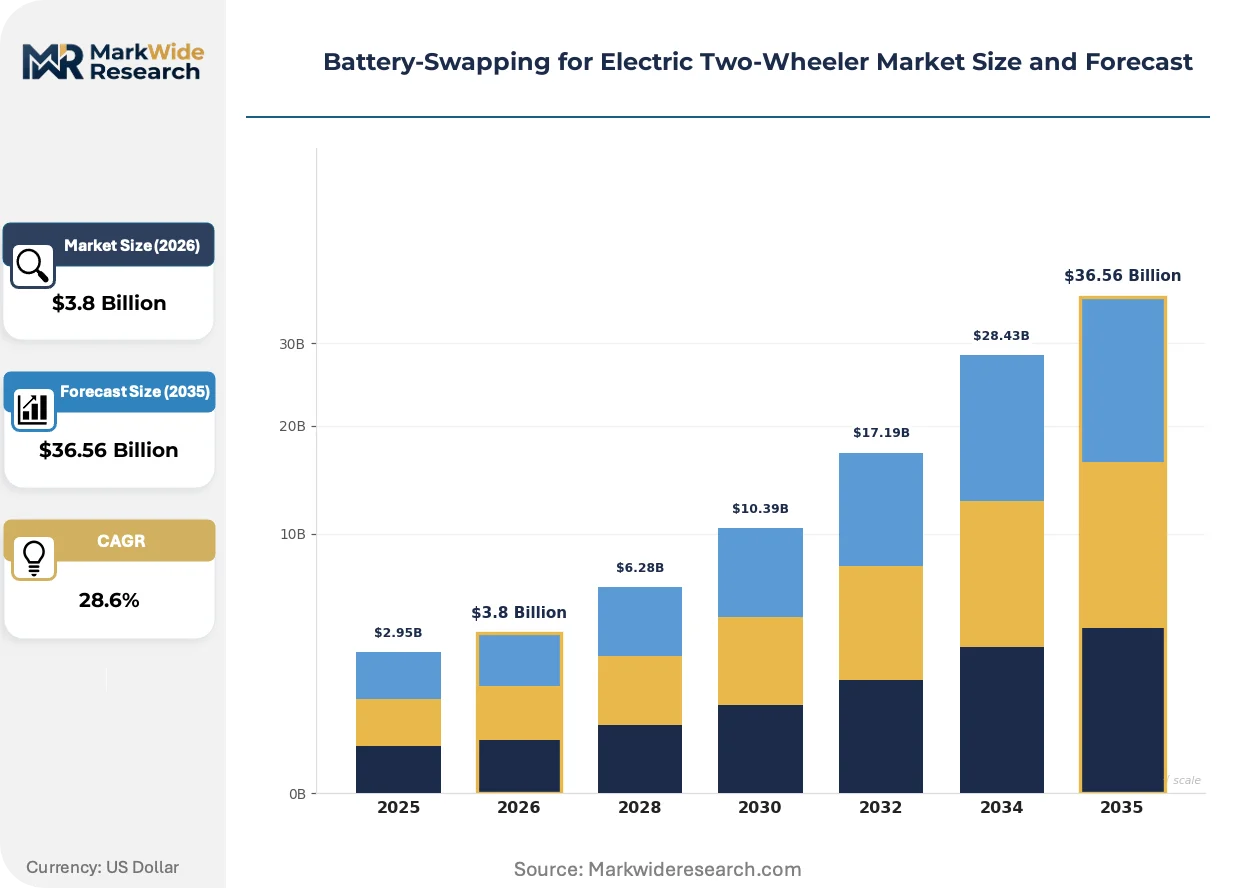
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.56 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Swappable Batteries, Fixed Batteries, Hybrid Systems, Modular Batteries Technology: Smart Charging Solutions, Battery Management Systems, Communication Protocols, Rapid Charging End User: Delivery Services, Commuter Users, Fleet Operators, Electric Motorcycle Enthusiasts Distribution Channel: Online Retail, Physical Stores, Service Outlets, Direct Sales |
| Companies Covered | Gogoro Inc., Sun Mobility, Kwang Yang Motor Co., Ltd., Oyika Pte. Ltd., Battery Smart, Swobbee, Spiro, Immotor Technology, VoltUp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery-Swapping for Electric Two-Wheeler Market Strategic Shifts
Software-layer monetization is overtaking hardware margins as the primary value capture mechanism, while regulatory pressure on pack safety is accelerating standardization efforts across manufacturing clusters.
Modular battery architectures are unifying pack geometries across scooter and motorcycle platforms, enabling station operators to service multiple vehicle categories from a single inventory pool. Fleet managers in Indian logistics are standardizing procurement around these interoperable formats to reduce spare-part complexity. This convergence is unifying previously fragmented station economics, allowing asset-light operators to achieve utilization thresholds faster.
India's CEA and BIS are tightening thermal runaway containment standards for swappable lithium-ion packs, mandating redundant cooling systems and fire-suppression integration in station design. Station operators must retrofit existing infrastructure or write down early-generation assets. Tier-1 logistics fleets are responding by demanding certified pack inventories exclusively, filtering smaller operators from contract eligibility.
Subscription-based battery access is displacing outright pack ownership among delivery fleet operators, transferring capital intensity and degradation risk to network providers. This model is compressing payback periods for station deployment by guaranteeing minimum utilization commitments. The shift is most visible in Indian urban logistics, where aggregators negotiate fleet-wide service agreements rather than per-vehicle battery purchases.
Battery-Swapping for Electric Two-Wheeler Market Segmentation
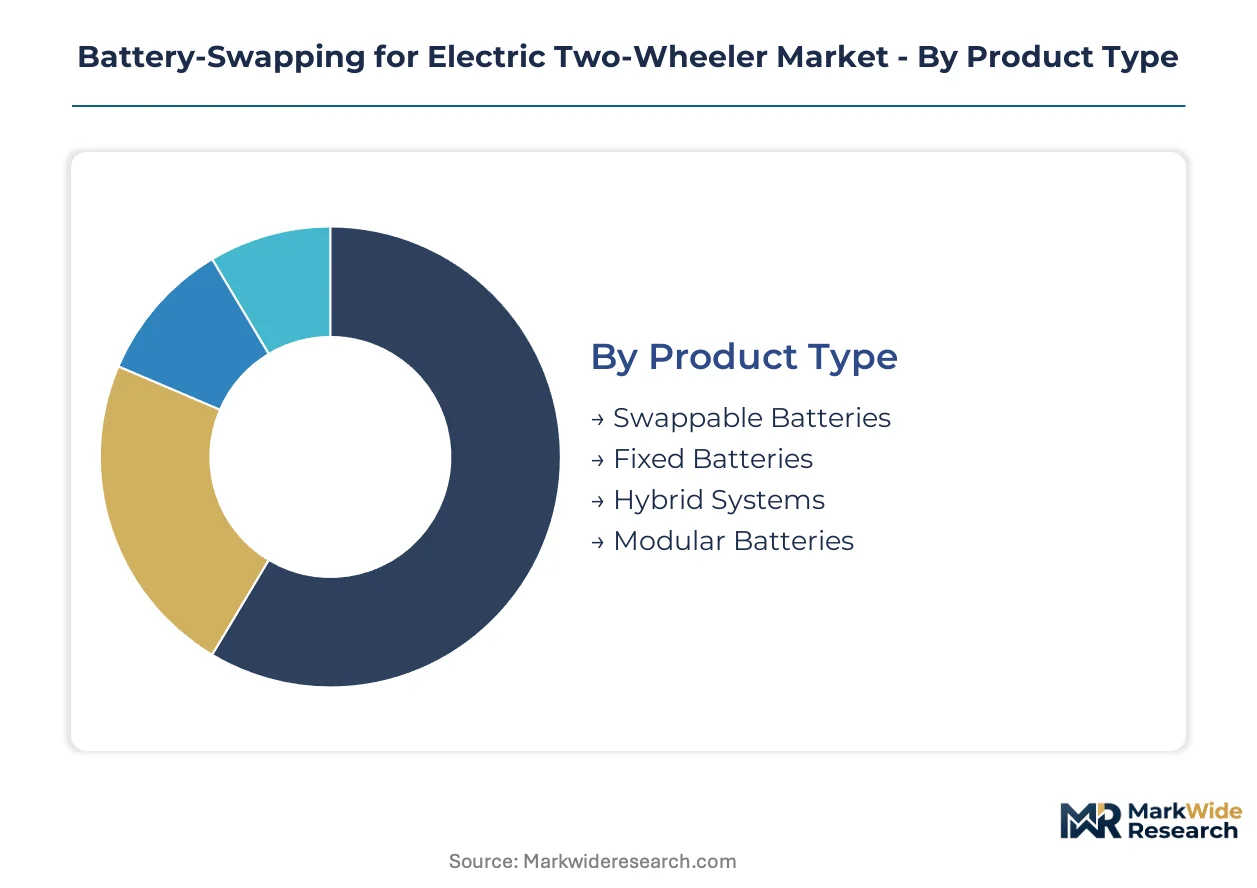
Segmentation in battery-swapping markets reveals how capital intensity, utilization patterns, and regulatory exposure fragment across product architectures and customer types. Each dimension carries distinct margin structures and infrastructure requirements that determine operator viability.
Product Type:
Standalone swappable configurations dominate fleet-heavy deployments, while embedded-fixed alternatives persist in consumer segments where home-charging access exists.
- Swappable Batteries:These packs feature standardized geometries with CAN-bus interfaces enabling rapid exchange at automated stations. Delivery fleets in India concentrate procurement here, driven by the PLI scheme's domestic assembly incentives and continuous-rotation operational models.
- Hybrid Systems:Dual-mode architectures accommodate both swapping and plug-in charging, hedging against station network gaps. Vietnam's urban corridors show concentrated uptake where infrastructure buildout lags vehicle penetration.
- Fixed Batteries:Permanently integrated packs with conventional charging ports serve commuter segments with reliable home or workplace electricity access.
- Modular Batteries:Scalable cell configurations allow capacity customization across scooter and motorcycle platforms, reducing spare-part complexity for multi-vehicle fleet operators.
Volume placements concentrate in Swappable Batteries; the faster expansion belongs to Hybrid Systems.
Technology:
Software-layer components capture recurring revenue streams, while hardware elements face commodity cost pressures from lithium supply volatility.
- Smart Charging Solutions:Cloud-connected platforms deliver predictive maintenance algorithms and utilization optimization for network operators. Fleet managers in Indian logistics subscribe to these services to minimize downtime and extend pack cycle life.
- Battery Management Systems:Firmware controlling cell balancing, thermal regulation, and state-of-health monitoring requires customized integration per OEM, stretching deployment timelines.
- Communication Protocols:Standardized CAN-bus and emerging wireless interfaces enable interoperability between packs and station hardware.
- Rapid Charging:High-power station electronics compress replenishment windows but demand reinforced grid connections and fire-suppression infrastructure under CEA and BIS mandates.
Revenue pools concentrate in Smart Charging Solutions; Battery Management Systems face the steepest integration friction.
End User:
Commercial utilization models generate superior station economics compared to intermittent consumer demand, reshaping network deployment priorities.
- Delivery Services:E-commerce and quick-commerce aggregators negotiate fleet-wide battery access agreements, guaranteeing minimum utilization commitments that compress station payback periods.
- Fleet Operators:Dedicated logistics providers standardize procurement around interoperable pack formats to simplify maintenance and spare-part management across vehicle pools.
- Commuter Users:Individual riders with inconsistent usage patterns and scattered residential distribution challenge station utilization thresholds.
- Electric Motorcycle Enthusiasts:Performance-oriented segments prioritize energy density and acceleration characteristics over swapping convenience.
Contract value concentrates in Delivery Services; Fleet Operators show the most rapid subscription migration.
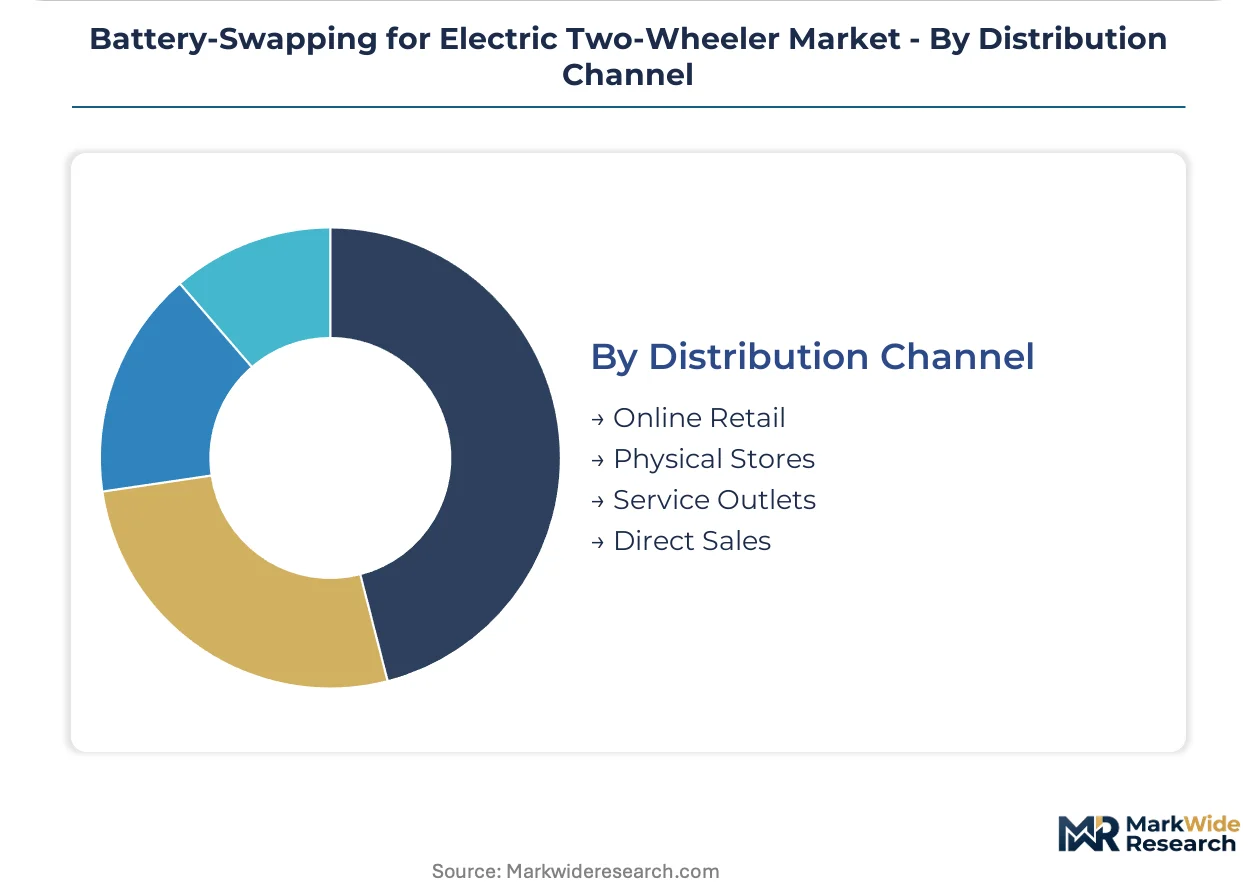
Distribution Channel:
Physical infrastructure requirements for battery handling and safety certification constrain pure digital distribution models in this market.
- Service Outlets:Attended stations with trained technicians handle pack exchange, thermal monitoring, and fire-response protocols mandated by India's CEA and BIS.
- Physical Stores:OEM-branded retail locations integrate vehicle sales with battery subscription sign-ups and station access enrollment.
- Direct Sales:Fleet operators negotiate enterprise agreements bypassing retail intermediaries, locking in long-term service commitments at volume discounts.
- Online Retail:Digital platforms facilitate subscription enrollment and station locator services but require physical handoff points for actual pack exchange.
Transaction volume concentrates in Service Outlets; Direct Sales deliver the highest contract margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters concentrate in Taiwan and Vietnam while consumption tilts toward India's logistics corridors and Vietnam's urban density belts.
India
Delivery aggregators in Mumbai and Delhi-NCR are locking fleet-wide battery subscriptions under the PLI scheme's domestic assembly incentives. CEA and BIS thermal runaway mandates are retrofitting station fire-suppression systems. Tamil Nadu's Sriperumbudur electronics corridor hosts pack assembly lines serving logistics operators.
Taiwan
Station hardware and battery pack manufacturing clusters anchor supply for East Asian network buildouts. METI-Japan cross-border certification protocols govern equipment exports to Japanese markets. Taipei and Kaohsiung metros demonstrate dense station networks with sub-three-minute swap cycles.
Vietnam
Ho Chi Minh City and Hanoi two-wheeler density exceeds home-charging infrastructure capacity, forcing delivery fleets toward swapping models. The country's national transport regulator is drafting interoperability standards for pack dimensions. Binh Duong province industrial zones host station component fabrication for domestic network deployment.
China
MIIT battery standardization directives are converging pack geometries across scooter and motorcycle OEMs. Yangtze River Delta manufacturing bases export CAN-bus-enabled station electronics to Southeast Asian operators. Shenzhen's electronics corridor supplies cloud-connected battery management firmware.
Indonesia
Jakarta's last-mile delivery electrification is attracting swapping network pilots from regional operators. The country's national standards body is adapting IEC protocols for tropical climate pack safety. Surabaya and Bandung urban corridors demonstrate concentrated two-wheeler ownership without residential charging access.
Battery-Swapping for Electric Two-Wheeler Market Competitive Environment
Top-tier vendors anchor integrated hardware-software platforms, while mid-tier operators compete through fleet-exclusive partnerships and asset-light station models. The structure fragments across three strategic archetypes: Taiwan-based manufacturing integrators, Indian logistics-focused service providers, and Southeast Asian network operators. Competitive moves concentrate on station density races in urban corridors and subscription-based battery access contracts that transfer degradation risk from fleet operators.
Within the integrated platform tier, Gogoro Inc. and Kwang Yang Motor Co., Ltd. exemplify manufacturing-origin players with captive station ecosystems. Sun Mobility occupies a position representing India-focused fleet service specialists, while Battery Smart exemplifies asset-light operator models targeting last-mile delivery aggregators. These three archetypes capture the dominant competitive vectors: hardware integration depth, fleet contract exclusivity, and capital-light network expansion.
| Leading Market Players |
|---|
| Gogoro Inc. |
| Sun Mobility |
| Kwang Yang Motor Co., Ltd. |
| Oyika Pte. Ltd. |
| Battery Smart |
| Swobbee |
| Spiro |
| Immotor Technology |
| VoltUp |
| Others |
Value Chain & Pricing Dynamics
Lithium carbonate and nickel sulfate feedstock costs cascade through cell manufacturing in Taiwan and Vietnam, compressing pack assembly margins before subscription pricing reaches Indian delivery fleet operators under CEA and BIS certification tiers.
Pricing Analysis
Margin tightening in certified pack tiers reflects India's PLI scheme localization requirements and CEA thermal runaway testing mandates. Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified inventories from uncertified alternatives, with fleet operators showing highest price sensitivity to per-swap rates and network providers least sensitive to station hardware capex. Cost-down pressure on standard-tier subscriptions accelerates because logistics aggregators negotiate fleet-wide minimum utilization guarantees.
Supply Chain Analysis
Freight costs from Taiwan's manufacturing clusters to Indian deployment corridors add 8-12% to landed station hardware expenses, incentivizing regional assembly investments. Cell chemistry inputs draw from South Korea and Japan, while CAN-bus electronics and BMS firmware feed from China's Yangtze River Delta. Single-source vulnerability concentrates in Taiwan's pack assembly capacity, with distribution running through OEM-direct channels for fleet contracts and service outlet networks for retail access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's CEA and BIS thermal runaway mandates erect a cost-of-compliance barrier that filters uncertified operators from Tier-1 logistics contracts, creating defendable moats for players with fire-suppression-integrated station infrastructure.
For Market Incumbents: Deepen backward integration into domestic cell assembly under PLI scheme incentives to offset lithium price volatility exposure. Fortify station density in Mumbai and Delhi-NCR corridors before emerging entrants secure last-mile aggregator exclusives, leveraging CEA certification timelines as a competitive delay mechanism against unqualified challengers.
For New Entrants and Emerging Players: Capture Vietnam's Ho Chi Minh City and Hanoi urban corridors where home-charging infrastructure gaps force delivery fleets toward swapping models. Penetrate through asset-light operator partnerships with quick-commerce aggregators, avoiding capital-heavy station buildout until utilization commitments lock in.
For Investors and Strategic Acquirers: BIS certification completion timelines shortening toward six-month cycles is the leading indicator that regulatory moats are stabilizing and consolidation value is crystallizing. Target acquisition archetypes combine cloud-connected BMS platforms with established fleet service agreements, monitoring PLI scheme beneficiary lists as inflection signals for domestic manufacturing viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Fire-Suppression Station Retrofit | CEA and BIS mandates force asset upgrades that filter smaller competitors from contract eligibility. |
| Fleet-Exclusive Subscription Lock-in | Delivery aggregators in Indian logistics guarantee minimum utilization commitments compressing payback periods. |
| Domestic Pack Assembly Expansion | PLI scheme incentives reduce import dependency for cell and pack production serving logistics operators. |
| Cloud-Based Predictive Maintenance Launch | Battery health monitoring subscriptions generate recurring revenue independent of physical swap volumes. |
| Hybrid System Configuration Rollout | Dual-mode architectures hedge against station network gaps in Vietnam's infrastructure-lagging corridors. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews spanning swapping network operators, fleet procurement managers at delivery aggregators, BMS firmware engineers, and CEA compliance officers. Secondary sources included BIS certification databases, PLI scheme beneficiary disclosures, Taiwan's METI-Japan cross-border equipment filings, and Vietnam's national transport regulator interoperability drafts. Bottom-up station deployment counts triangulated against top-down battery pack production estimates across the analysis window.
Data-stream reconciliation across product type, technology layer, end-user vertical, and distribution channel dimensions shaped the analytical framework. CAGRs derived from logistic curve fitting to fleet penetration rates and station utilization thresholds, with inputs from lithium carbonate price indices and CEA mandate implementation timelines across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to IEC harmonization progress on pack dimensions and lithium supply contract renegotiations. Forecasts reflect documented assumptions around fleet electrification commitments and regulatory enforcement consistency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Japan Electric Car Market
Electric Vehicles
France Solar E-Bike Market
Electric Vehicles
New Zealand E-Bike Market
Electric Vehicles
Scooter Market
Electric Vehicles
ASEAN Countries Plug-In Hybrid Electric Vehicle Battery Market
Electric Vehicles
China Electric Car Market
Electric Vehicles
Electric Vehicle Thermal Management Market
Electric Vehicles
Car Battery Chargers Market
Electric Vehicles
Electric Axle Drive Systems Market
Electric Vehicles
Solar Car Market
Electric Vehicles
Electric Vehicle Panoramic Sunroof Market
Electric Vehicles
Electric Vehicle Battery Enclosure Market
Electric Vehicles
Central and Eastern Europe E-Bike Market
Electric Vehicles
Automotive Energy Harvesting and Regeneration Market
Electric Vehicles
Japan Electric Vehicle Market
Electric Vehicles
Electric Shuttle Market