
 Micro Electric Vehicle Market | 2026-2036
Micro Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Micro Electric Vehicle Market Analysis
Aftermarket battery refurbishment is narrowing as a margin pool as OEMs tighten control over cell diagnostics and replacement protocols. BYD leverages in-house lithium-iron-phosphate cell production to anchor its cost position across mini car and three-wheeler lines. NIU specializes in premium two-wheeler designs with integrated IoT telemetry, while Yadea dominates mass-market e-scooter distribution through offline dealer density in Chinese provincial cities.
Micro electric vehicles denote battery-powered transport machines with curb weights below 1,500 kg, operating at speeds typically capped at 45–80 km/h and driven by permanent magnet synchronous motors with 5–25 kWh pack configurations. Their primary commercial purpose centers on intra-urban mobility, cargo hauling, and fleet logistics where full-size vehicle footprints create congestion and energy inefficiency. Two-wheeler and e-scooter segments lead volume shipments across Asian urban corridors, while commercial fleets and delivery services represent the fastest-expanding end user category as logistics operators electrify last-mile routes. Lithium-ion chemistry anchors the power source mix, though solid-state prototypes are entering pilot validation with select manufacturers.
China's MIIT enforces GB/T standards for vehicle safety and battery interchangeability, while the EU's F-Gas Regulation and CE marking framework shape import compliance for European market entry. India's PLI scheme for advanced chemistry cell manufacturing is redirecting supply chain investment toward domestic battery pack assembly. Stakeholders must monitor regulatory divergence between battery-swapping interoperability mandates and home charging safety codes as these standards crystallize across jurisdictions.
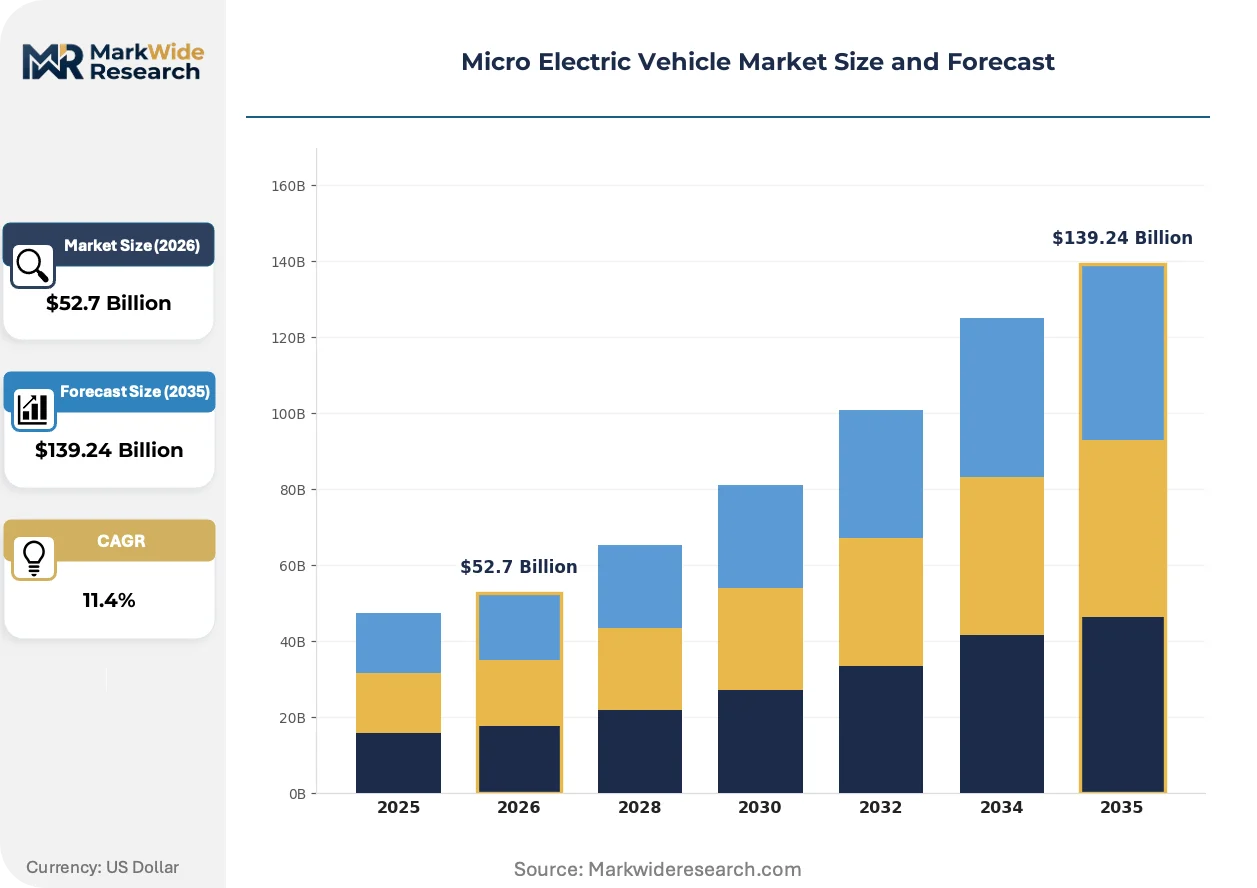
Market Dynamics
Last-mile electrification mandates from municipal regulators are forcing fleet operators to replace combustion-powered delivery vehicles with micro electric alternatives, compressing replacement cycles and concentrating procurement volumes among logistics operators.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for fluorinated greenhouse gases in transport refrigeration are accelerating adoption of electric cargo bikes and micro vans for cold-chain urban delivery.
- Battery-swapping infrastructure:Standardized interchange protocols under China's GB/T framework are reducing downtime for commercial fleet operators and enabling asset-light ownership models.
- Intra-urban mobility demand:Congestion pricing zones in London, Singapore, and Milan are redirecting commuter and courier traffic toward sub-80 km/h electric two-wheelers and quadricycles.
Market Restraints
- Lithium carbonate volatility:Cell chemistry cost fluctuations are compressing margin pools for pack assemblers without captive mining offtake or long-term cathode supply contracts.
- Charging infrastructure gaps:Residential building codes in dense urban districts lack mandated EV-ready parking provisions, constraining overnight charging for private micro EV owners.
- Speed and range limitations:Permanent magnet synchronous motors capped at 45 km/h under L6e quadricycle classifications disqualify micro EVs from highway-adjacent logistics routes.
Strategic Opportunities
- India's PLI scheme for ACC manufacturing:Domestic cell production incentives are creating localized battery pack assembly capacity for micro three-wheeler and e-scooter OEMs serving South Asian markets.
- Solid-state pilot validation:Prototype cells with ceramic electrolytes are entering fleet testing with select manufacturers, promising energy density improvements for commercial cargo applications.
- Subscription and mobility-as-a-service channels:B2B fleet leasing platforms are displacing direct ownership for last-mile operators, opening recurring revenue streams independent of unit sales cycles.
Industry Challenges
- Interoperability certification delays:Divergent battery-swapping connector standards across China's MIIT, India's BIS, and EU technical committees are fragmenting platform economics for network operators.
- Diagnostic protocol lock-in:OEM-controlled cell management system software is restricting third-party refurbishment access and compressing aftermarket service margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro Electric Vehicle Market |
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $139.24 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Two-Wheeler, Three-Wheeler, Mini Car, E-Scooter Power Source: Lithium-Ion, Lead Acid, Solid-State, Hydrogen Fuel Cell End User: Personal Use, Commercial Fleets, Ride-Sharing, Delivery Services Charging Infrastructure: Home Charging, Public Charging Stations, Wireless Charging, Battery Swapping |
| Companies Covered | NIO, NIU, BYD, Yamaha, Honda, Xiaomi, Yadea, Uniti, XPeng, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro Electric Vehicle Market Emerging Trajectories
Telematics integration and solid-state prototyping are converging to reshape how fleet operators manage asset utilization and total cost of ownership across micro electric vehicle deployments.
Integrated IoT telemetry platforms are digitizing real-time battery health monitoring, geofencing compliance, and predictive maintenance scheduling for commercial two-wheeler and three-wheeler fleets. Logistics operators in the Yangtze River Delta cluster are adopting these systems fastest, using granular ride data to optimize route efficiency and reduce premature cell degradation. The technology is digitizing fleet management from reactive repair models toward uptime-guaranteed service contracts.
China's MIIT enforcement of GB/T standards for battery interchangeability is mandating unified connector geometries and communication protocols across domestic micro EV manufacturers. The regulation is compressing proprietary lock-in strategies and forcing OEMs to compete on vehicle dynamics rather than ecosystem captivity. Commercial fleet buyers in Shanghai and Hangzhou are responding by consolidating procurement around swap-compatible platforms.
Leasing and battery-as-a-service arrangements are displacing direct vehicle ownership among urban delivery contractors and gig-economy riders. Subscription models decouple hardware acquisition from energy access, transferring residual value risk to fleet aggregators. This shift is most visible in Chinese provincial cities where Yadea's dealer density supports rapid asset turnover and localized swap station coverage.
Micro Electric Vehicle Market Segmentation
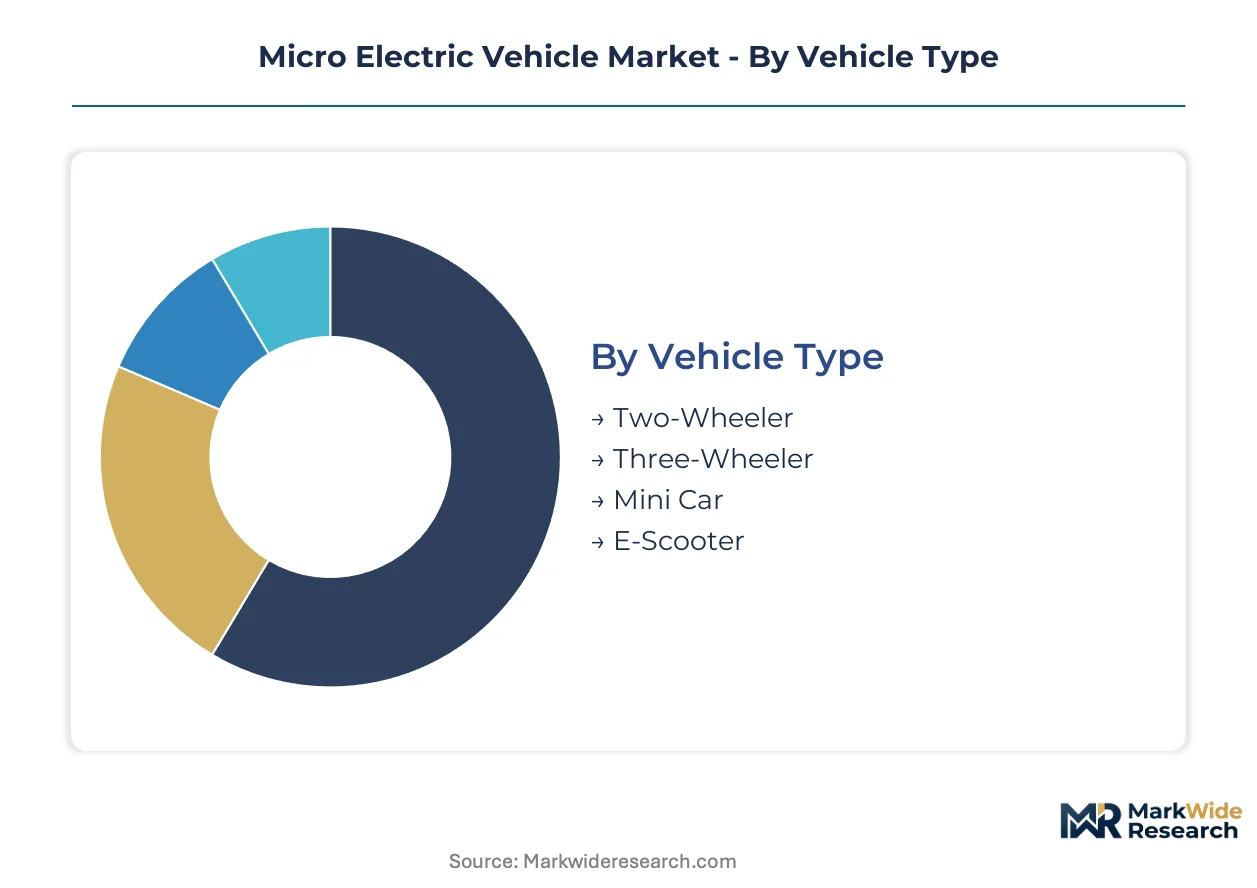
Segmentation in micro electric vehicles reveals how procurement cycles, energy access models, and fleet ownership structures create divergent margin pools across hardware categories. Understanding these divisions helps stakeholders align product roadmaps with the operational realities of urban logistics operators and individual commuters.
Vehicle Type:
Replacement cycles stretch from 18 months for shared e-scooters to 7-10 years for privately held mini cars, compressing revenue recognition timelines for high-turnover formats.
- Two-Wheeler:Battery-powered motorcycles and mopeds with 2-5 kWh packs dominate Asian urban corridors. Demand concentrates among gig-economy delivery contractors in Shanghai and Jakarta where congestion pricing and fuel cost differentials accelerate payback periods. Fleet operators favor swap-compatible models to eliminate charging downtime.
- Three-Wheeler:Cargo and passenger variants with 5-15 kWh configurations serve last-mile logistics and informal transit. Indian and Bangladeshi urban freight operators are electrifying these platforms fastest under tightening municipal diesel bans.
- Mini Car:Quadricycles and neighborhood electric vehicles with enclosed cabins target suburban commuters and small commercial fleets. European L6e classifications cap speeds at 45 km/h, restricting these units to intra-urban routes.
- E-Scooter:Standing and seated kick-scooter formats with sub-2 kWh packs anchor shared mobility fleets. High asset turnover and vandalism exposure compress operator margins despite volume deployment.
Two-wheelers dominate installed base. Three-wheelers are where expansion concentrates.
Power Source:
Cost tiers separate captive cell producers from pack assemblers dependent on spot-market cathode materials.
- Lithium-Ion:NMC and LFP chemistries anchor current production with energy densities of 150-250 Wh/kg. Yangtze River Delta manufacturers leverage in-house LFP production to defend margin positions against volatile carbonate pricing.
- Lead Acid:Legacy chemistry persists in price-sensitive South Asian three-wheeler markets where total cost of ownership calculations favor upfront savings over cycle life. Recycling infrastructure maturity in India sustains this segment's residual economics.
- Solid-State:Ceramic electrolyte prototypes are entering pilot validation with select OEMs, promising 400+ Wh/kg densities for commercial cargo applications where payload efficiency determines route economics.
- Hydrogen Fuel Cell:PEM systems for extended-range three-wheeler prototypes target cold-chain logistics where battery thermal management degrades performance.
Lithium-ion commands current production volumes. Solid-state prototypes are climbing the fastest toward commercialization.
End User:
Customer type determines pricing power, with B2B fleet contracts enabling subscription models that decouple hardware from energy access.
- Personal Use:Individual owners purchasing for commuting and recreation. Residential charging constraints in dense urban districts limit adoption where building codes lack EV-ready parking mandates.
- Commercial Fleets:Logistics operators and delivery services electrifying last-mile routes under municipal mandate pressure. These buyers concentrate procurement volumes and negotiate swap-network access as contract terms.
- Ride-Sharing:Platform-mediated mobility services deploying shared assets with high utilization targets. Unit economics depend on asset durability and rapid battery exchange protocols.
- Delivery Services:E-commerce and food delivery contractors operating on thin margins. These operators prioritize total cost of ownership and uptime guarantees over acquisition price.
Personal use anchors historical volumes. Commercial fleets are gaining share fastest as electrification mandates tighten.
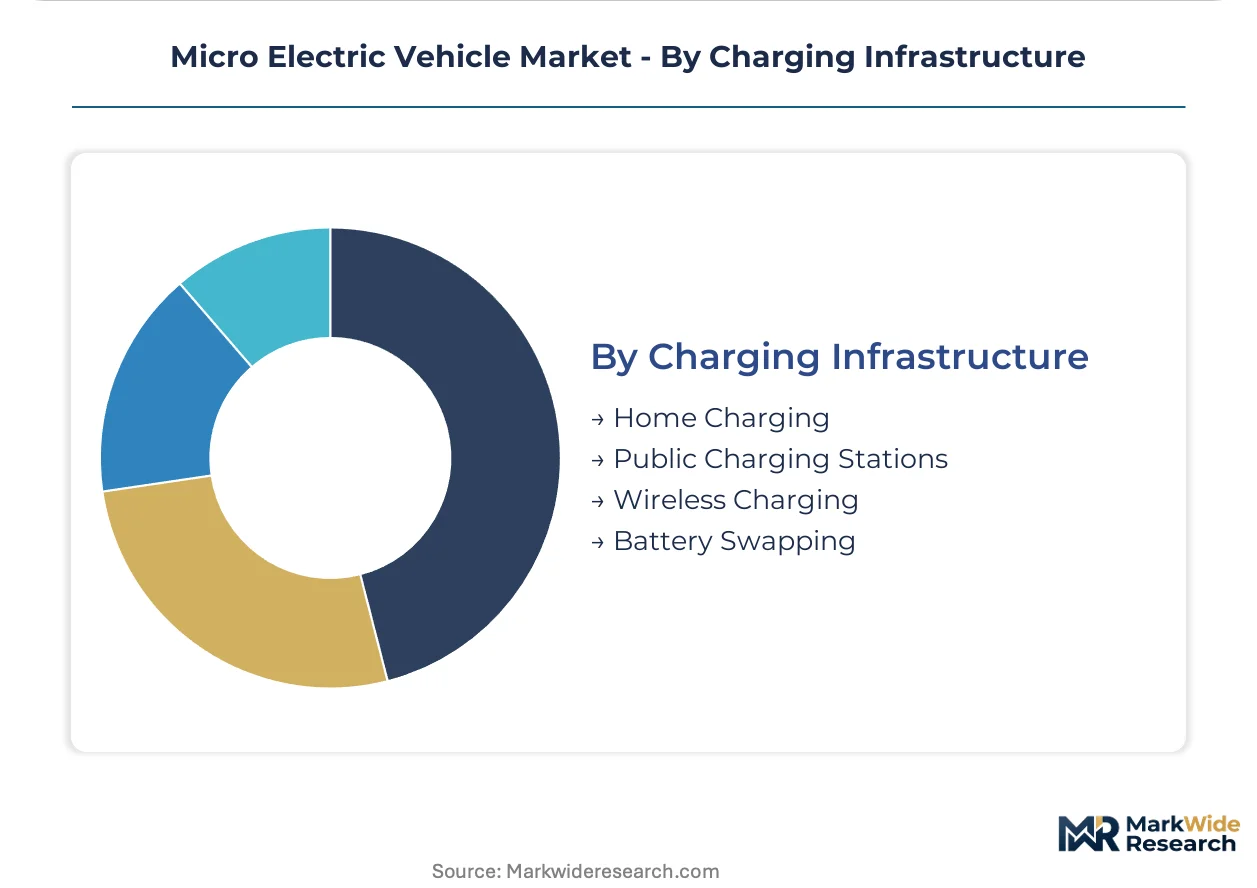
Charging Infrastructure:
Asset ownership models fragment across infrastructure types, with swapping networks enabling capital-light fleet expansion.
- Home Charging:Level 1 and Level 2 residential installations for private owners. Dense Asian urban districts with limited parking access constrain penetration regardless of hardware cost declines.
- Public Charging Stations:Curbside and dedicated-lot infrastructure for opportunity charging. Deployment economics struggle in micro EV segments where dwell times are short and connector standardization lags.
- Wireless Charging:Inductive pad systems for fleet depots and fixed-route applications. High capital costs and efficiency losses limit deployment to premium commercial segments.
- Battery Swapping:Standardized interchange stations under China's GB/T protocols reducing asset downtime. Fleet aggregators in Shanghai and Hangzhou are consolidating procurement around swap-compatible platforms.
Home charging dominates the installed base. Battery swapping is where infrastructure investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys micro electric vehicles predominantly for commercial fleet logistics, while European adoption tilts toward personal commuting and suburban mobility, and Indian demand concentrates on three-wheeler freight electrification under municipal diesel bans.
China
Commercial fleet operators in the Yangtze River Delta cluster drive procurement volumes for swap-compatible two-wheelers and mini trucks. MIIT enforces GB/T standards for battery interchangeability, compressing proprietary lock-in strategies among domestic manufacturers. Shanghai, Suzhou, and Hangzhou concentrate battery-swapping infrastructure investment and NEV credit system utilization.
Germany
Urban logistics operators adopt electric cargo bikes and L6e quadricycles for last-mile delivery under tightening municipal low-emission zones. The EU F-Gas Regulation accelerates cold-chain electrification by phasing down fluorinated greenhouse gases in transport refrigeration. Industrial activity clusters in Bavaria and Baden-Württemberg where automotive suppliers pivot toward micro EV component production.
India
Three-wheeler freight operators electrify fastest under diesel bans in Delhi, Mumbai, and Bangalore. The PLI scheme for advanced chemistry cell manufacturing redirects supply chain investment toward domestic battery pack assembly. Tamil Nadu and Maharashtra host emerging cell production capacity serving South Asian micro EV OEMs.
United States
Delivery service contractors and campus mobility operators represent the primary demand segment, with limited personal adoption due to suburban sprawl and highway-centric infrastructure. NHTSA regulations govern low-speed vehicle classifications that cap micro EV operations to roads with posted limits below 56 km/h. California and New York Metro lead deployment through state-level zero-emission vehicle mandates and congestion pricing experiments.
Indonesia
Gig-economy delivery contractors in Jakarta and Surabaya propel two-wheeler electrification as fuel cost differentials accelerate payback periods. The national energy ministry coordinates battery-swapping pilot programs with state utility PLN to address residential charging constraints in dense urban districts. Java island concentrates manufacturing investment from regional OEMs seeking proximity to nickel processing facilities.
Micro Electric Vehicle Market Vendor Landscape
Capability concentration sits with vertically integrated cell producers; scale advantage sits with mass-market assemblers leveraging dealer density and swap-network partnerships. The market structures around three archetypes: captive lithium-iron-phosphate producers, IoT-integrated premium designers, and high-volume distribution platforms. Competitive moves center on backward integration into cathode materials and subscription-based mobility-as-a-service channel development.
Within the captive production tier, BYD anchors cost positioning through in-house cell manufacturing. NIU and Yadea occupy distinct positioning vectors: the former exemplifies premium-tier design with integrated telemetry, while the latter represents mass-market scale through offline dealer penetration in Chinese provincial cities.
| Leading Market Players |
|---|
| NIO |
| NIU |
| BYD |
| Yamaha |
| Honda |
| Xiaomi |
| Yadea |
| Uniti |
| XPeng |
| Others |
Supply Flow & Price Mechanics
China's Yangtze River Delta concentration of lithium-iron-phosphate cell production anchors cost positioning downstream, transferring margin capture to OEMs with captive cathode supply while pack assemblers face volatile carbonate spot markets. This geographic clustering of upstream feedstock refining and cell manufacturing creates divergent pricing power between integrated producers and component-dependent assemblers.
Pricing Analysis
Long-term offtake contracts dominate procurement between fleet operators and swap-network providers, insulating volume buyers from lithium carbonate spot volatility while spot-market dependence compresses margins for smaller pack assemblers. Three-tier pricing structure across premium telemetry-integrated, standard swap-compatible, and economy lead-acid tiers reflects brand positioning and certification grade. Cost compression in economy segments is intensifying as Indian PLI-subsidized domestic cell capacity comes online. Delivery service contractors exhibit highest price sensitivity, while commercial fleet aggregators prioritize uptime guarantees over unit acquisition cost.
Supply Chain Analysis
Upstream feedstock concentration in Chile, Australia, and Indonesia for lithium, cobalt, and nickel processing creates geographic dependency for cathode precursor supply. Cell manufacturing draws from refined materials processed in China's Fujian and Sichuan provinces, with South Korean and Japanese producers competing on high-nickel chemistry specialization. Single-source vulnerability in permanent magnet rare earth processing poses structural risk for motor suppliers. Distribution runs through OEM-captive dealer networks in Chinese provincial cities and third-party fleet aggregators in European urban logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists across battery-as-a-service platforms and solid-state pilot programs as municipal electrification mandates create procurement niches unaddressed by incumbent volume players.
For Market Incumbents: Pre-empt swap-network consolidation by locking exclusive fleet contracts in Jakarta and Surabaya before regional OEMs scale dealer density. Secure captive lithium-iron-phosphate supply through backward integration into cathode precursor processing. Defend margin pools against diagnostic protocol lock-in by opening cell management system interfaces to third-party refurbishment channels.
For New Entrants and Emerging Players: Build out solid-state validation partnerships with cold-chain logistics operators in Germany's Bavaria cluster, where EU F-Gas Regulation creates premium payload efficiency demand. Target three-wheeler freight electrification in India's Tamil Nadu and Maharashtra under diesel ban enforcement. Pursue direct B2B subscription models decoupling hardware from energy access to bypass incumbent dealer infrastructure.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fleet aggregators in Shanghai and Hangzhou holding swap-network infrastructure and municipal procurement relationships. Long-term viability centers on subscription revenue durability rather than unit sales cyclicality. Monitor GB/T standard adoption velocity across China's MIIT enforcement zones as inflection indicator for platform economics consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery-as-a-Service Platform Launch | Decouples hardware acquisition from energy access, transferring residual value risk to fleet aggregators. |
| Solid-State Cell Pilot Validation | Enters fleet testing with ceramic electrolyte prototypes promising 400+ Wh/kg density for commercial cargo. |
| Swap-Network Infrastructure Partnership | Consolidates procurement around GB/T-compatible platforms in Yangtze River Delta logistics corridors. |
| Backward Integration into Cathode Materials | Secures LFP precursor supply against carbonate spot volatility for cost-position defense. |
| Telematics-Integrated Fleet Contracting | Shifts revenue from unit sales to uptime-guaranteed service contracts with predictive maintenance scheduling. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of MIIT regulatory filings, EU F-Gas Regulation implementation reports, and vehicle production databases. Interviews with fleet operations directors, battery swap network managers, OEM platform engineers, and municipal transport regulators informed demand-side validation. Trade data from China's customs administration and India's DGFT complemented SEC filings from listed component suppliers. Bottom-up unit shipment estimates triangulated against top-down addressable fleet spend analysis.
Forecast inputs span vehicle type segmentation by power source chemistry and end-user ownership model across the projection horizon. Modeled dimensions include two-wheeler versus three-wheeler platform splits, lithium-ion versus solid-state technology transitions, and personal versus commercial fleet procurement patterns. CAGRs derived from logistic curve adoption modeling applied to municipal mandate enforcement timelines and infrastructure deployment schedules. Battery-swapping station density and NEV credit system utilization curves served as industry-specific demand proxies.
Practitioners should monitor lithium carbonate spot price volatility, GB/T standard interoperability certification delays, and solid-state pilot validation outcomes for early signals requiring forecast revision. Cross-checking against IEA electric vehicle deployment benchmarks and national automotive production statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle (EV) Battery Housing Market
Electric Vehicles
Electric Vehicle Rental Market
Electric Vehicles
Global Smart Electric Drive Market
Electric Vehicles
Automotive Energy Harvesting and Regeneration Market
Electric Vehicles
Construction Electric Vehicle Market
Electric Vehicles
Saudi Arabia E-Bike Market
Electric Vehicles
Asia-Pacific Electric Vehicle Market
Electric Vehicles
E-Bike Battery Pack Market
Electric Vehicles
Automotive Battery Packs Market
Electric Vehicles
North America Electric Vehicle (EV) Fluids Market
Electric Vehicles
Japan Solar E-Bike Market
Electric Vehicles
Driveline Electric Vehicle Market
Electric Vehicles
ASEAN Electric Vehicle Market
Electric Vehicles
Electric Vehicle UBI Market
Electric Vehicles
Singapore Electric Vehicle Market
Electric Vehicles
High-Performance Electric Sports Cars Market