
 France Electric Commercial Vehicle Battery Pack Market | 2026-2036
France Electric Commercial Vehicle Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
France Electric Commercial Vehicle Battery Pack Market Insights
European cell manufacturing is rebalancing toward France as state-backed gigafactory investments scale. Automotive Cells Company (ACC) anchors domestic lithium-ion supply through its Douvrin plant. Forsee Power specializes in modular pack architectures for bus and truck OEMs. Saft Groupe S.A. leverages its Bordeaux engineering base to sustain defense-to-commercial technology transfer.
A France Electric Commercial Vehicle Battery Pack is an integrated electrochemical energy storage system comprising cells, battery management electronics, and thermal regulation hardware, typically engineered for 100-400 kWh nominal capacity and 800V-class electrical architectures to power heavy-duty traction motors. The lithium-ion technology segment dominates current installations due to established supply chains and cost curves, while solid-state chemistries attract R&D funding for future energy density gains. The logistics providers end-user category occupies the largest addressable pool as e-commerce fulfillment networks electrify van and light-truck fleets, and the 201-300 kWh capacity band captures the strongest growth trajectory in medium-duty distribution vehicles.
France's national low-emission zone framework, the EU CO2 standards for heavy-duty vehicles, and ECHA's battery passport requirements under the EU Battery Regulation collectively mandate cleaner powertrains, standardized recyclability protocols, and supply-chain traceability. These rules force OEMs to source compliant packs and disclose carbon footprints across cell-to-pack production. Stakeholders must monitor how ANSM and DGEC interpret secondary-life battery deployment for grid storage, as this regulatory clarity will determine residual value capture strategies.
Market Dynamics
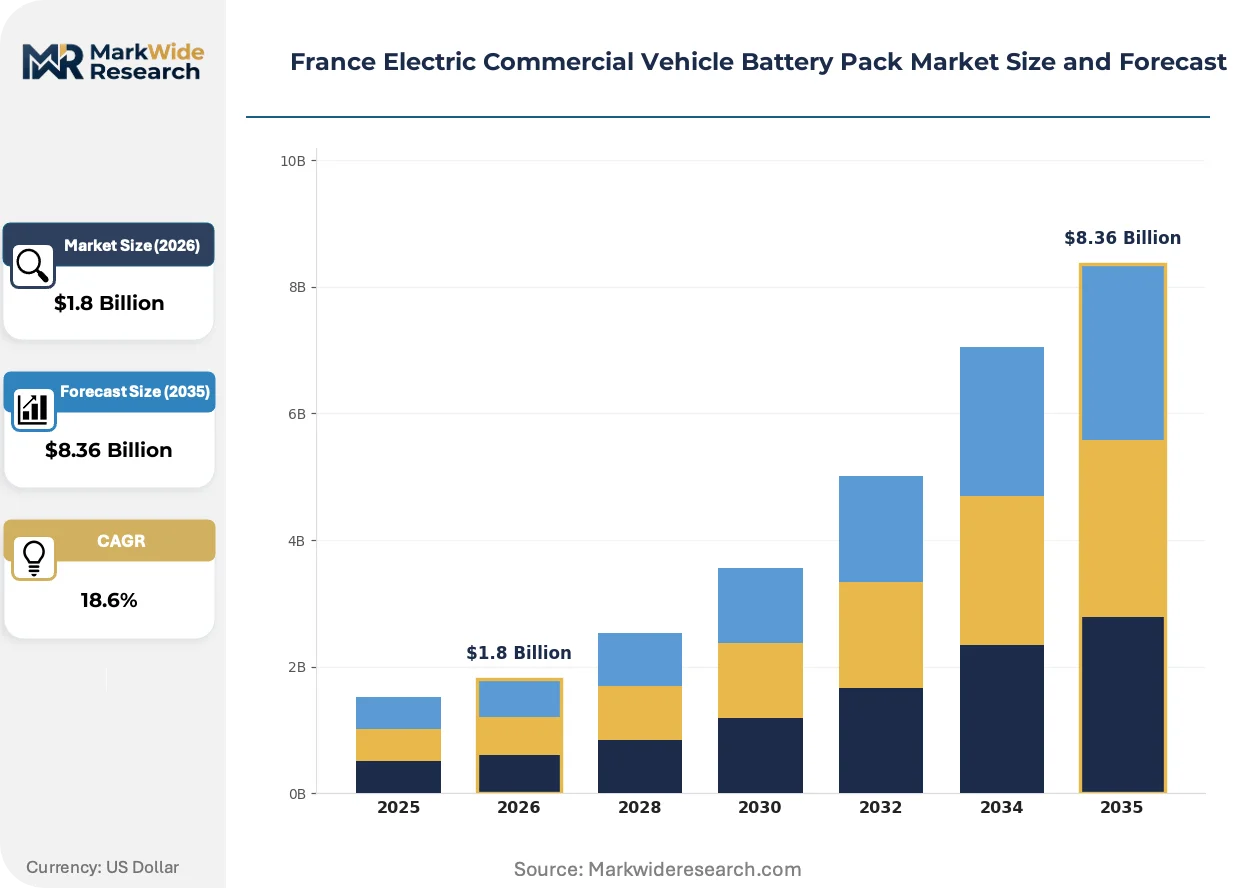
The France electric commercial vehicle battery pack market pivots on regulatory compression from the EU CO2 standards for heavy-duty vehicles, which mandates zero-emission powertrains and forces fleet operators into accelerated procurement cycles for compliant battery systems.
Growth Catalysts
- Low-emission zone mandates:France's national LEZ framework in Île-de-France and Lyon-Saint-Étienne corridors compels logistics operators to electrify van and light-truck fleets, generating concentrated battery pack demand.
- E-commerce fulfillment networks:Parcel and last-mile delivery operators are scaling electric van deployments to meet urban emissions restrictions and brand sustainability commitments.
- State-backed gigafactory investments:Domestic lithium-ion cell production capacity expansion reduces import dependency and shortens pack assembly lead times for French OEMs.
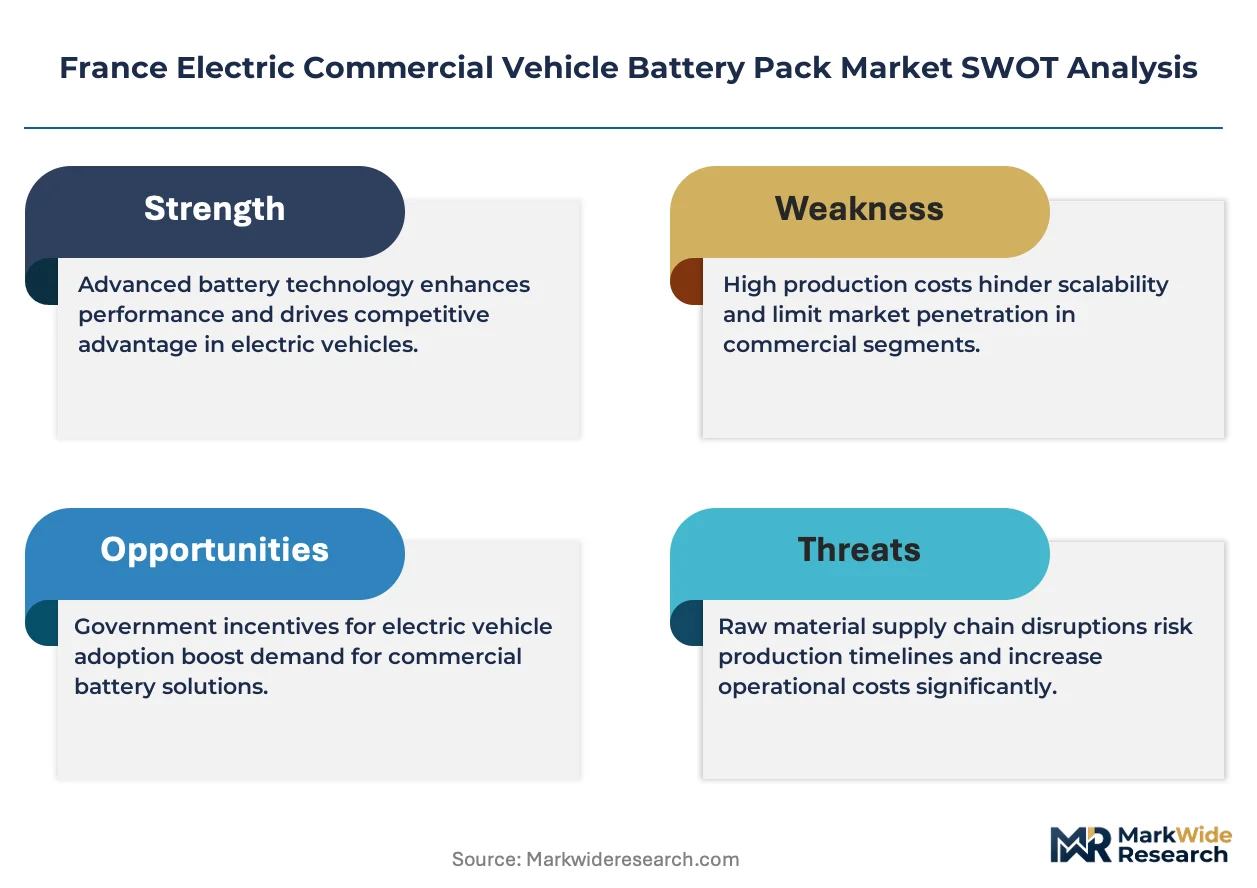
Market Restraints
- Raw material price volatility:Lithium and nickel cost fluctuations compress pack manufacturer margins and destabilize long-term fleet electrification budgets.
- Cell supply concentration:Dependency on Asian cathode and anode material suppliers exposes French pack assemblers to geopolitical trade friction and shipping disruptions.
- Energy density limitations:Current lithium-ion chemistries impose weight and range trade-offs that constrain medium-duty truck electrification for regional haul routes.
Strategic Opportunities
- Battery passport compliance services:ECHA's traceability requirements under the EU Battery Regulation create revenue pools for supply-chain auditing and carbon accounting platforms.
- Secondary-life grid storage:ANSM and DGEC regulatory clarity on retired commercial vehicle battery redeployment will unlock residual value capture for fleet operators and utilities.
- Solid-state chemistry convergence:Next-generation electrolyte and ceramic separator R&D promises energy density breakthroughs for heavy-duty traction applications.
Industry Challenges
- Battery management systems engineering talent:Scarce firmware and electrochemical modeling expertise constrains pack optimization and thermal runaway prevention capabilities.
- Homologation timeline compression:Accelerated EU type-approval processes for new vehicle platforms strain testing laboratory capacity and certification documentation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Electric Commercial Vehicle Battery Pack Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Lithium-ion, Solid State, Nickel-Metal Hydride, Lead-Acid Component: Battery Cells, Battery Management System, Thermal Management, Charging System End User: Logistics Providers, Public Transport, Retail Delivery, Construction Capacity: 100-200 kWh, 201-300 kWh, 301-400 kWh, Above 400 kWh |
| Companies Covered | Automotive Cells Company (ACC), Forsee Power, Groupe Renault, Akasol AG, Contemporary Amperex Technology Co. Ltd. (CATL), Blue Solutions SA, Elecsys France, LG Energy Solution Ltd., Saft Groupe S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Electric Commercial Vehicle Battery Pack Market Trends and Innovations
Technology unification across cell chemistry, thermal management, and power electronics is compressing development cycles and redefining competitive differentiation in French commercial vehicle electrification.
Cell-to-pack architectures are unifying structural and thermal functions by eliminating traditional module housings and integrating cooling plates directly into the pack enclosure. Bus and truck OEMs in the Île-de-France logistics corridor are adopting these designs to maximize volumetric energy density and reduce assembly complexity. This unification is compressing bill-of-material costs and enabling 800V-class fast-charging compatibility for depot-based fleet operations.
The EU Battery Regulation's carbon footprint disclosure mandates are forcing pack manufacturers to document lifecycle emissions from mining through recycling. Industrial consequence includes accelerated supplier audits and binding renewable energy sourcing contracts for cell production. French pack assemblers serving the Lyon-Saint-Étienne corridor are most affected, responding by securing low-carbon aluminum and recycled cathode material streams.
Fleet operators are consolidating procurement around total-cost-of-ownership frameworks that internalize energy, maintenance, and residual value risks into single-source battery service agreements. Traditional equipment financing channels face displacement from energy-as-a-service platforms and battery leasing subsidiaries. This shift is most visible among national postal and parcel carriers operating high-utilization van fleets under multi-year electrification mandates.
France Electric Commercial Vehicle Battery Pack Market Segmentation
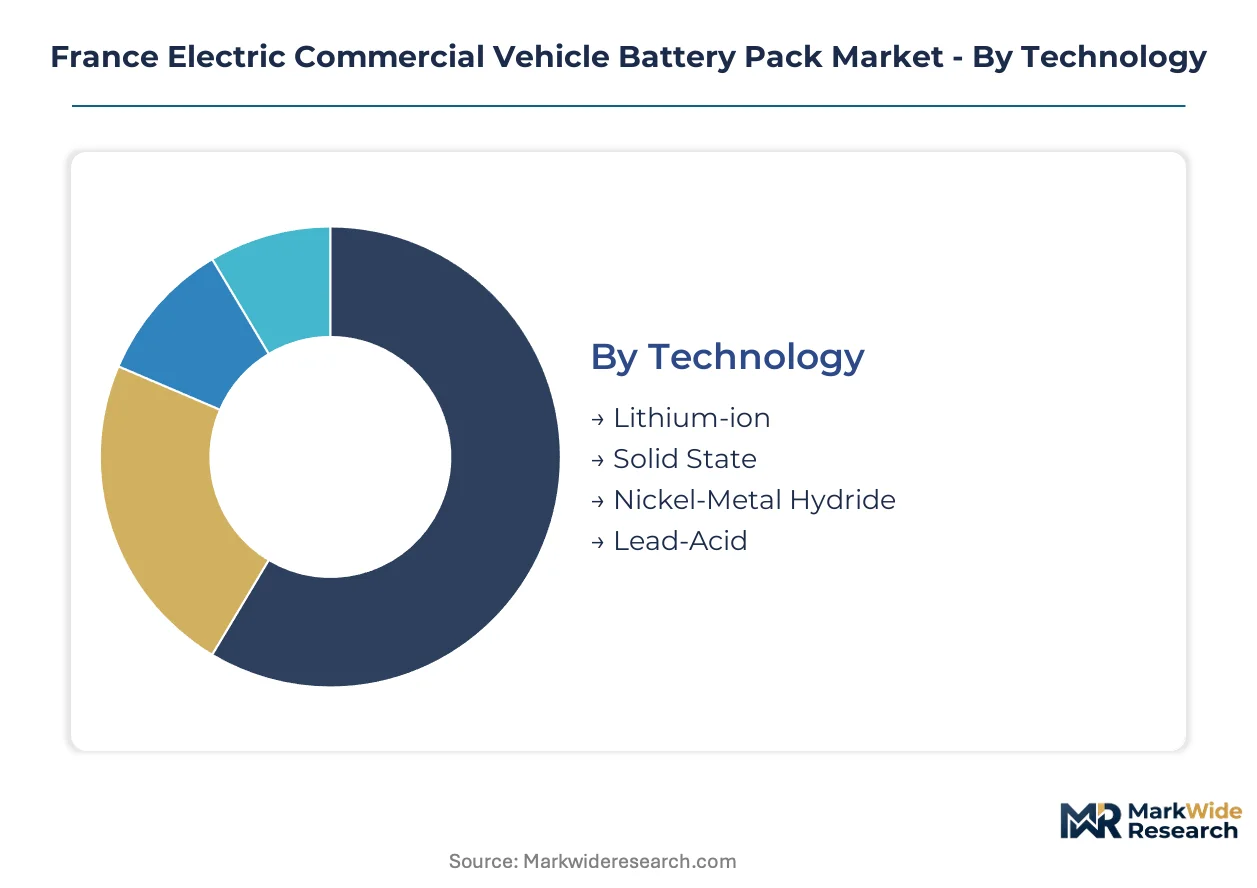
Segmentation in the France electric commercial vehicle battery pack market reveals how regulatory mandates, duty-cycle requirements, and fleet procurement economics fragment demand across distinct technical and commercial profiles. Understanding these divisions exposes where pack assemblers must configure product lines and where pricing power concentrates.
Technology:
Buyers in this category differentiate by energy density requirements, thermal stability needs, and supply-chain maturity rather than upfront cost alone.
- Lithium-ion:Dominant electrochemistry employing nickel-manganese-cobalt or lithium-iron-phosphate cathodes paired with graphite anodes, engineered for 150-250 Wh/kg cell-level energy density. Demand concentrates among Île-de-France logistics fleets operating high-utilization van routes where established supply chains and cost curves outweigh density limitations. The EU Battery Regulation's carbon footprint disclosure mandates force manufacturers to document mining-to-recycling emissions, accelerating supplier audits and renewable energy sourcing contracts.
- Solid State:Next-generation architecture replacing liquid electrolytes with ceramic or sulfide-based solid conductors, promising 400+ Wh/kg density and intrinsic thermal runaway suppression. Development programs at Bordeaux and Grenoble engineering clusters target heavy-duty regional haul applications where current lithium-ion weight-range trade-offs constrain payload capacity. ANSM and DGEC regulatory clarity on homologation timelines remains the critical path variable.
- Nickel-Metal Hydride:Mature chemistry retaining niche deployment in hybrid auxiliary power units and temperature-sensitive urban bus applications where proven safety records outweigh energy density disadvantages.
- Lead-Acid:Legacy technology confined to low-voltage auxiliary systems and starter functions in retrofitted commercial chassis, excluded from primary traction applications by weight and cycle-life constraints.
Lithium-ion leads volumes today; solid-state is gaining share fastest.
Component:
Procurement patterns in this category track where OEMs retain in-house engineering versus outsource to tier-one suppliers.
- Battery Cells:Electrochemical core comprising cathode, anode, separator, and electrolyte materials, constituting 60-70% of pack-level bill-of-materials. Domestic sourcing from ACC's Douvrin gigafactory reduces import dependency for French OEMs serving the Lyon-Saint-Étienne logistics corridor, though cathode active material remains concentrated among Asian suppliers.
- Battery Management System:Firmware and hardware stack monitoring cell-level voltage, temperature, and state-of-charge to prevent thermal runaway and optimize cycle life. Scarce embedded systems engineering talent in the Paris-Saclay cluster constrains development velocity for mid-tier pack assemblers.
- Thermal Management:Cooling plates, refrigerant loops, and phase-change materials maintaining cell temperatures within 15-35°C operational windows. Cell-to-pack architectures are unifying structural and thermal functions by eliminating module housings and integrating cooling directly into enclosures.
- Charging System:Onboard power electronics and connector interfaces enabling 800V-class fast-charging compatibility for depot-based fleet operations. E-commerce fulfillment networks are consolidating procurement around total-cost-of-ownership frameworks that internalize charging infrastructure into battery service agreements.
Battery cells dominate component spending; battery management systems show the steepest expansion trajectory as software differentiation intensifies.
End User:
Duty-cycle intensity and regulatory exposure determine pack specification priorities across buyer categories.
- Logistics Providers:Parcel and freight operators electrifying last-mile and regional distribution fleets under France's national low-emission zone framework. E-commerce fulfillment networks in Île-de-France are scaling electric van deployments to meet urban emissions restrictions and brand sustainability commitments, generating concentrated demand for 100-300 kWh packs with rapid depot charging.
- Public Transport:Municipal and regional bus operators procuring under multi-year electrification mandates with standardized tender specifications. RATP and other French transit authorities are driving modular pack architectures that enable mid-life capacity refurbishment rather than full replacement.
- Retail Delivery:Grocery and quick-commerce platforms operating temperature-controlled van fleets with auxiliary refrigeration loads. Cold-chain energy demands compress effective range, driving preference for higher-capacity packs than equivalent dry-freight applications.
- Construction:Heavy-duty vocational vehicles including dump trucks and concrete mixers requiring 400+ kWh configurations for intermittent high-torque duty cycles. Site charging infrastructure limitations and payload sensitivity to battery weight constrain electrification velocity relative to urban freight segments.
Logistics providers anchor current volumes; public transport is expanding most quickly as municipal electrification mandates accelerate.
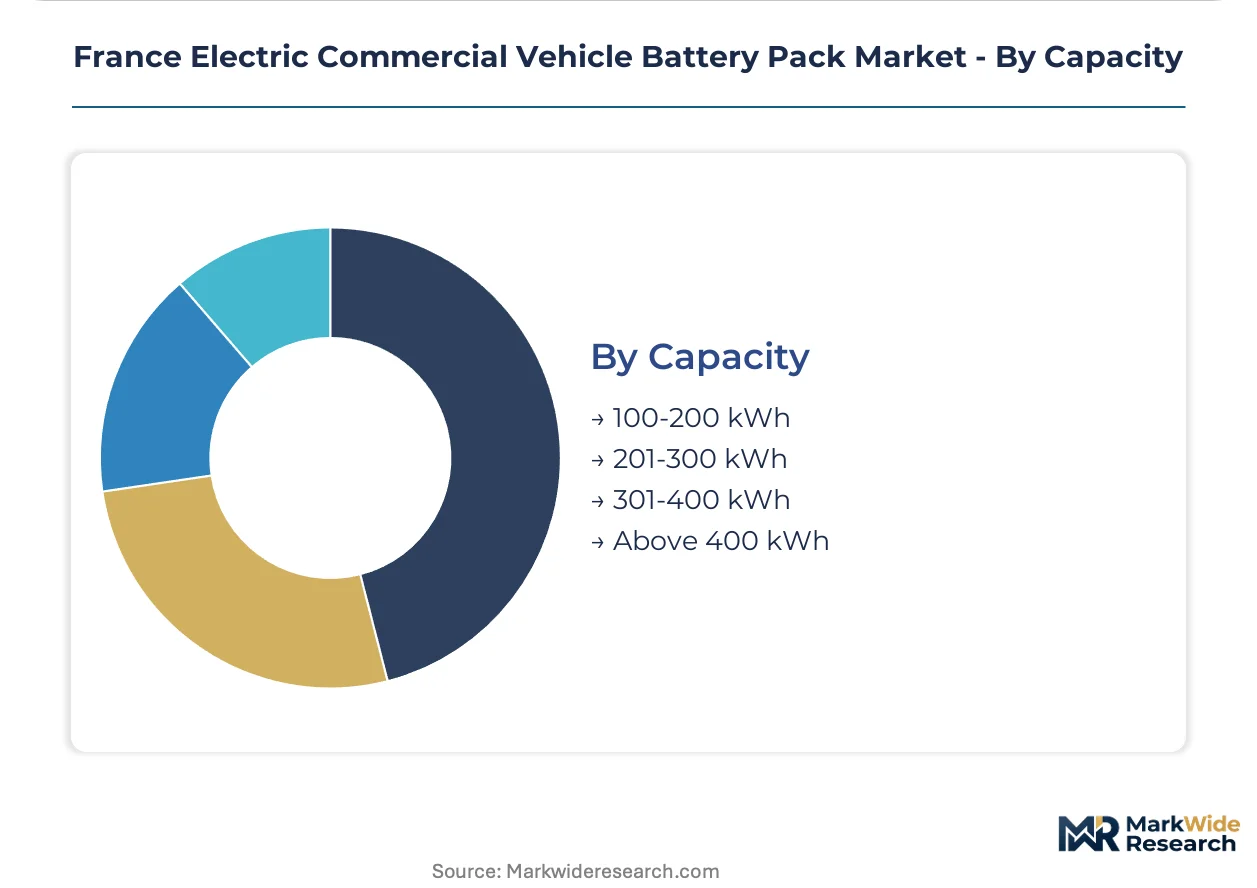
Capacity:
Vehicle class and route profile dictate energy storage scale, with procurement economics shifting dramatically across threshold bands.
- 100-200 kWh:Standard configuration for light commercial vans and urban delivery vehicles operating sub-150 km daily routes. Parcel carriers in the Lyon-Saint-Étienne corridor are deploying these packs under battery leasing structures that transfer residual value risk to energy-as-a-service platforms.
- 201-300 kWh:Medium-duty distribution and interurban freight applications requiring 200-400 km daily range with depot fast-charging. This band captures the strongest growth trajectory as regional haul electrification extends beyond last-mile boundaries.
- 301-400 kWh:Heavy-duty rigid trucks and articulated tractors for longer regional routes with intermediate charging infrastructure. Cell supply concentration and raw material price volatility compress manufacturer margins most acutely in this band.
- Above 400 kWh:Specialized vocational and long-haul configurations where energy density limitations impose severe weight and packaging constraints. Solid-state chemistry convergence promises to unlock viability in this segment.
The 201-300 kWh band leads absolute volumes today; above-400 kWh configurations are climbing the fastest as heavy-duty electrification advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps across French sub-regions are redirecting battery pack assembly investments toward zones with streamlined environmental permitting and proximity to vehicle OEM integration sites. Regional specialization patterns reflect logistics corridor density, state-backed industrial policy targeting, and local authority electrification procurement mandates.
Île-de-France
Paris-region logistics operators electrify last-mile van fleets under strict LEZ enforcement. DGEC and ANSM coordinate on secondary-life battery deployment rules for grid storage applications. The Paris-Saclay engineering cluster concentrates battery management systems firmware talent for pack assemblers serving RATP and national postal electrification tenders.
Auvergne-Rhône-Alpes
The Lyon-Saint-Étienne freight corridor generates concentrated demand for 201-300 kWh medium-duty distribution packs. Regional low-emission zone mandates accelerate procurement cycles for interurban freight operators. Grenoble engineering institutes anchor solid-state electrolyte R&D programs targeting heavy-duty regional haul applications.
Hauts-de-France
ACC's Douvrin gigafactory anchors domestic lithium-ion cell production, reducing import dependency for French OEMs. State-backed industrial contracts under France's battery strategy secure cathode active material supply chains. The Lille metropolitan area clusters pack assembly operations serving Benelux cross-border logistics fleets.
Nouvelle-Aquitaine
Saft Groupe S.A. maintains its Bordeaux engineering base for defense-to-commercial technology transfer in thermal management systems. Regional authorities prioritize municipal bus fleet electrification under multi-year procurement mandates. The Arcachon Bay area hosts testing facilities for maritime-commercial battery applications in port logistics.
France Electric Commercial Vehicle Battery Pack Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue solid-state chemistry convergence and battery passport compliance services. The market exhibits moderate consolidation around domestic cell manufacturing and modular pack architecture specialists. Three archetypes dominate: gigafactory-integrated cell producers, modular systems engineers for bus and truck OEMs, and energy-as-a-service platform operators capturing residual value. Capacity expansion and strategic technology licensing constitute the dominant competitive moves as firms secure cathode material supply agreements.
Among France-based producers, Automotive Cells Company (ACC), Forsee Power, and Saft Groupe S.A. exemplify distinct strategic positioning within the market structure. ACC represents the gigafactory-integrated archetype with state-backed industrial scale. Forsee Power occupies the modular systems engineering tier serving commercial vehicle OEMs. Saft Groupe S.A. anchors the defense-to-commercial technology transfer segment with established Bordeaux engineering capabilities.
| Leading Market Players |
|---|
| Automotive Cells Company (ACC) |
| Forsee Power |
| Groupe Renault |
| Akasol AG |
| Contemporary Amperex Technology Co. Ltd. (CATL) |
| Blue Solutions SA |
| Elecsys France |
| LG Energy Solution Ltd. |
| Saft Groupe S.A. |
| Others |
Pricing and Supply Chain Analysis
The EU Battery Regulation's carbon footprint disclosure mandates gate qualified supply and premium-tier pricing access for French pack assemblers, forcing renewable energy sourcing contracts and low-carbon material streams as table stakes for Tier 1 OEM procurement eligibility.
Pricing Analysis
Distributor margins compress toward direct-to-OEM contract structures as fleet operators consolidate procurement around battery service agreements. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and volume scale, with ECHA battery passport compliance commanding material premiums. Pricing pressure stems from raw material volatility in cathode active materials. Logistics providers exhibit highest price sensitivity due to thin fleet electrification budgets, while municipal transit authorities show lowest sensitivity under state-backed procurement mandates.
Supply Chain Analysis
Cathode active material supply rests on Chinese, South Korean, and Japanese specialty chemical producers, with graphite anode processing similarly concentrated in Asian manufacturing hubs. French pack assemblers draw from ACC's Douvrin gigafactory for domestic cell sourcing, though lithium carbonate and nickel sulfate remain import-dependent. Single-source vulnerability in separator membrane supply exposes assemblers to geopolitical trade friction. Distribution runs through Tier 1 supplier networks directly into OEM vehicle integration sites, bypassing traditional aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by France's national low-emission zone framework, which mandates zero-emission fleet procurement on predictable regulatory timelines.
For Market Incumbents: Anchor cell supply security through backward integration into cathode precursor processing or binding long-term offtake agreements with ACC's Douvrin expansion phases. Solid-state chemistry convergence threatens lithium-ion cost curves; defend through accelerated R&D partnerships with Grenoble engineering clusters and patent positioning in ceramic electrolyte architectures. For New Entrants and Emerging Players: Fleet operators represent the most penetrable channel partner type for modular pack-as-a-service platforms targeting mid-sized logistics providers excluded from OEM direct procurement. White-space concentrates in secondary-life battery redeployment for grid storage, pending ANSM and DGEC regulatory clarity. Pursue white-label battery management system firmware licensing to accelerate time-to-revenue without capital-intensive cell manufacturing. For Investors and Strategic Acquirers: Roll-up economics work for modular pack architecture specialists because OEM consolidation around standardized platform designs creates acquisition currency for engineering talent and homologation certificates. Five-to-ten-year viability hinges on solid-state chemistry convergence timelines. Target acquisition candidates with established EU Battery Regulation compliance infrastructure and binding renewable energy sourcing contracts. The signal to watch is DGEC guidance on secondary-life battery grid storage deployment, which would unlock residual value capture models and re-rate serviceable addressable market.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | ACC's Douvrin capacity expansion reduces import dependency for French OEMs serving Lyon-Saint-Étienne logistics corridors. |
| Backward Integration | Cathode precursor processing investments insulate margins from Asian material price volatility and trade friction. |
| Platform Standardization | Cell-to-pack architectures unify thermal and structural functions, compressing bill-of-material costs for 800V-class fast-charging compatibility. |
| Technology Licensing | Solid-state electrolyte patents from Grenoble engineering clusters enable heavy-duty regional haul electrification beyond lithium-ion density limits. |
| Charging Infrastructure Partnership | Depot-based fast-charging networks integrated into battery service agreements lock in multi-year fleet operator relationships. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with battery pack procurement directors at Île-de-France logistics operators, ACC platform engineers, Forsee Power commercial directors, Saft thermal management specialists, and DGEC policy officers with secondary validation against EU Battery Regulation filings, ANSM technical guidance documents, ECHA supply chain traceability standards, and French customs trade data for lithium-ion cell imports. Bottom-up fleet electrification demand models and top-down OEM production forecasts were triangulated for consistency.
Segment-weighting approaches distributed volume and value across technology, component, end-user, and capacity dimensions, with additional modeling for regional production cluster concentration and regulatory compliance tier differentiation. CAGRs were derived from fitted growth curves incorporating fleet operator procurement cycle timing, gigafactory capacity ramp schedules, and low-emission zone mandate enforcement calendars. Cell supply concentration indices and cathode material price elasticity informed scenario-bound projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to solid-state chemistry commercialization timelines, DGEC secondary-life battery rulings, and EU-Asia trade policy shifts. Forecasts reflect documented assumptions around ACC Douvrin output ramp, ECHA battery passport implementation schedules, and ANSM thermal runaway testing protocol adoption. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Electric Heating Film Market
Electric Vehicles
Electric Vehicle Air Conditioning Market
Electric Vehicles
Asia-Pacific Electric Vehicle Thermal Management System Market
Electric Vehicles
India Electric Bus Market
Electric Vehicles
Electric Shuttle Market
Electric Vehicles
Battery Electric Vehicle (BEV) Market
Electric Vehicles
Lithium Battery Electric Scooters Market
Electric Vehicles
India Electric Car Market
Electric Vehicles
Asia Pacific Automotive High Performance Electric Vehicles Market
Electric Vehicles
Saudi Arabia E-Bike Market
Electric Vehicles
Europe Electric Vehicle (EV) Fluids Market
Electric Vehicles
North America Electric Vehicle Battery Market
Electric Vehicles
US Automotive High Performance Electric Vehicle Market
Electric Vehicles
Global Electric All Wheel Drive (AWD) Market
Electric Vehicles
Norway E-Bike Market
Electric Vehicles
Special Purpose Electric Vehicle Market