
 Electric Vehicle Electric Heating Film Market | 2026-2036
Electric Vehicle Electric Heating Film Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Electric Heating Film Market Insights
REACH substance restrictions is realigning the cost-of-entry calculus for European suppliers of polymer-based heating films. BorgWarner Inc leverages its thermal systems heritage to anchor battery heating contracts with premium EV platforms. Modine Manufacturing Company competes through integrated HVAC-to-battery thermal architectures that reduce vehicle-level complexity. RexVa Co. Ltd. specializes in thin-film carbon formulations that sustain price-performance ratios under escalating raw material scrutiny.
Electric vehicle electric heating film denotes a resistive, flexible substrate—typically 0.1 to 0.5 millimeters thick—engineered from carbon, polymer, metal, or composite layers that convert electrical energy to controlled thermal output for cabin comfort, visibility, and battery conditioning. Carbon film formulations dominate current OEM specifications due to superior thermal uniformity and mechanical flexibility across curved battery pack geometries. Composite film segments are gaining fastest traction where battery heating applications demand simultaneous dielectric isolation and rapid thermal response. Smart heating technology integration is concentrating margin pools among Tier-1 suppliers capable of embedding temperature feedback loops directly into vehicle CAN bus architectures.
EPA tailpipe regulations and NHTSA safety standards in the United States are mandating faster cabin warmup times that elevate heating film performance thresholds. China's MEE enforces dual carbon compliance timelines that filter out energy-inefficient thermal solutions from domestic EV supply chains. ECHA REACH protocols in Europe restrict halogenated flame retardants in polymer substrates, forcing reformulation investments. Stakeholders must monitor how battery chemistry shifts toward solid-state architectures will redefine heating film power density and spatial distribution requirements.
Market Dynamics
The shift toward solid-state battery architectures is redrawing thermal management requirements, forcing heating film suppliers to engineer higher power density solutions that integrate with next-generation pack geometries while maintaining dielectric isolation standards.
Growth Catalysts
- China's dual carbon compliance timelines:Domestic EV supply chains must demonstrate energy efficiency gains, accelerating replacement of resistive wire heaters with polymer film alternatives that reduce thermal mass and warmup latency.
- Battery chemistry evolution:Lithium iron phosphate and sodium-ion formulations exhibit narrower optimal temperature windows, expanding the addressable installed base for active heating films in cold-climate markets.
- East Asian manufacturing concentration:South Korean battery production hubs and Chinese EV assembly corridors generate procurement pull that concentrates supplier investment in localized film fabrication capacity.
Market Restraints
- Silver and copper price volatility:Conductive ink formulations depend on precious metal feedstocks whose cost swings compress margin predictability for film manufacturers locked into annual OEM supply agreements.
- Polymer substrate concentration:High-performance polyimide supply chains cluster among Japanese and South Korean chemical conglomerates, creating single-source vulnerability for European and North American heating film assemblers.
- REACH substance restrictions:ECHA protocols on halogenated flame retardants force reformulation investments that delay product recertification cycles by 12-18 months for suppliers serving European OEMs.
Strategic Opportunities
- Commercial vehicle electrification:Bus and heavy-duty truck battery packs require larger active heating areas than passenger cars, opening volume contracts for suppliers with scalable carbon film deposition capabilities.
- Smart heating convergence:Integration of temperature feedback loops with vehicle CAN bus architectures enables predictive thermal management that differentiates Tier-1 suppliers from component vendors.
- India's PLI scheme for advanced chemistry cells:Domestic cell manufacturing incentives are attracting heating film suppliers to establish localized production for emerging EV platforms targeting tropical and Himalayan climate extremes.
Industry Challenges
- Multiphysics simulation talent scarcity:Film suppliers struggle to hire engineers capable of modeling coupled electrical-thermal-mechanical behavior across curved battery surfaces, slowing design iteration cycles.
- Automotive-grade qualification timelines:OEMs demand AEC-Q200 compliance and PPAP submission packages that extend new product introduction by 24-36 months, straining working capital for mid-cap suppliers.
- Legacy HVAC integration complexity:Heating film retrofits into existing vehicle thermal architectures require coordination with refrigerant loop designers, creating interface specification disputes that delay SOP dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Electric Heating Film Market |
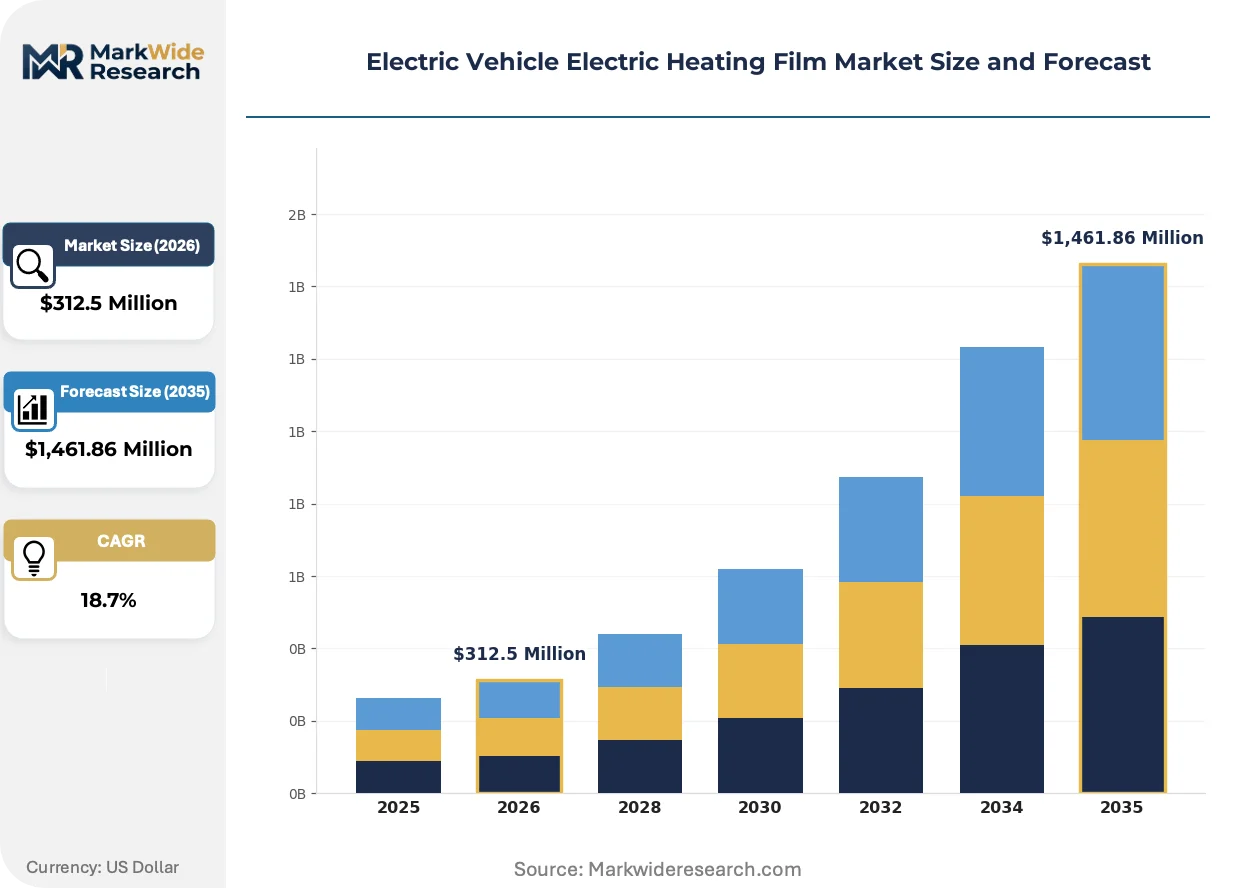
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $1,461.86 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Film, Polymer Film, Metal Film, Composite Film Application: HVAC Systems, Window Heating, Seat Heating, Battery Heating End User: OEMs, Tier-1 Suppliers, Aftermarket Installers, Vehicle Assemblers Technology: Infrared Heating, Conduction Heating, Radiant Heating, Smart Heating |
| Companies Covered | Modine Manufacturing Company, BorgWarner Inc, Fenix Group, RexVa Co. Ltd., Zhonghui Floor Heating, Calorique, Termofol, BVF Heating Solutions, LivingHeat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Electric Heating Film Market Trends and Innovations
Carbon-based thin-film formulations are capturing specification share from metal-wire alternatives as OEMs prioritize thermal uniformity and pack-level weight reduction. Three developments are compressing competitive timelines.
Composite film stacks combining carbon conductive layers with polyimide dielectric substrates are consolidating technical specifications across premium EV platforms. Battery engineers at Korean and Chinese OEMs specify these formulations for 800V architectures where rapid thermal response must coexist with electrical isolation. The technology is consolidating procurement decisions around suppliers with in-house lamination and laser-patterning capabilities, marginalizing pure film converters.
ECHA REACH protocols restricting halogenated flame retardants in polymer substrates are forcing material reformulations across European supply chains. Suppliers serving German and Swedish OEMs must substitute phosphorus-nitrogen intumescent systems that maintain UL94 V-0 ratings without brominated additives. Korean film exporters are accelerating REACH-compliant product line development to defend existing contracts with European battery pack assemblers.
Fleet operators and shared mobility platforms are compressing supplier qualification cycles as they specify heating films through battery pack integrators rather than OEM thermal engineering departments. This channel shift elevates the importance of module-level thermal validation data over traditional vehicle-level homologation. Chinese battery swap station operators are driving this pattern most aggressively, requiring heating film suppliers to certify directly with CATL and BYD pack assembly divisions.
Electric Vehicle Electric Heating Film Market Segmentation
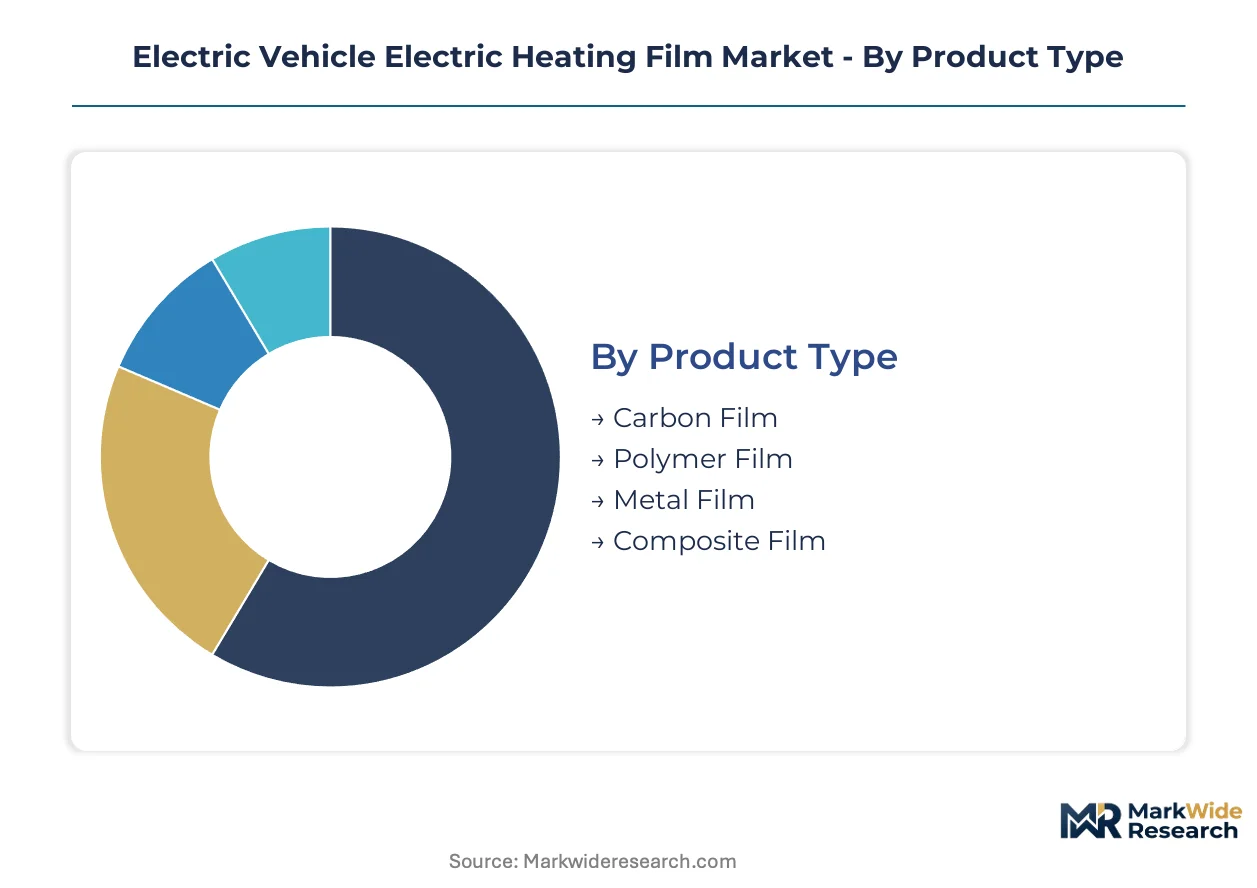
Heating film segmentation determines procurement patterns across EV thermal architectures. Product chemistry and application placement dictate qualification timelines, pricing tiers, and supplier margin structures differently across passenger and commercial vehicle platforms.
Product Type:
Carbon film formulations demand the heaviest upfront capital allocation for specialized deposition equipment and cleanroom fabrication lines. Polymer and metal alternatives require less intensive tooling investments but face steeper raw material cost volatility.
- Carbon Film:Thin-film carbon layers deliver superior thermal uniformity across curved battery pack geometries. Korean battery cell manufacturers specify these formulations for 800V architectures where rapid thermal response must coexist with electrical isolation standards.
- Composite Film:Laminated stacks combining conductive carbon with polyimide dielectric substrates are consolidating technical specifications across premium EV platforms. Chinese OEMs specify composite formulations for battery heating applications where simultaneous dielectric isolation and thermal response prove critical.
- Polymer Film:Polyimide and PET-based substrates offer cost-efficient alternatives for cabin comfort applications with moderate thermal loads.
- Metal Film:Copper and aluminum trace configurations persist in legacy seat heating modules where flexibility requirements remain less stringent.
Carbon film absorbs the bulk of installed capacity; composite film is expanding most quickly.
Application:
Battery conditioning applications command premium pricing tiers due to dielectric isolation requirements and AEC-Q200 qualification burdens. Cabin comfort applications compete on volume scale with thinner margin profiles.
- Battery Heating:Active thermal management films maintain lithium iron phosphate and sodium-ion cells within narrow optimal temperature windows. Cold-climate markets in northern China and South Korea are accelerating procurement of high-power-density formulations for winter range preservation.
- HVAC Systems:Integrated cabin heating modules replace resistive wire heaters with polymer film alternatives that reduce thermal mass and warmup latency. China's dual carbon compliance timelines are forcing domestic OEMs to prioritize these retrofits.
- Seat Heating:Low-voltage carbon fiber mats dominate passenger comfort specifications with established supply chains and minimal certification friction.
- Window Heating:Transparent conductive oxide and silver nanowire films address defogging requirements with optical clarity constraints.
Battery heating claims the steepest expansion trajectory; HVAC systems anchor current volume concentration.
End User:
OEM direct procurement concentrates among premium platforms with in-house thermal engineering capabilities. Tier-1 suppliers intermediate volume contracts for mass-market vehicle lines.
- OEMs:Premium German and Swedish manufacturers specify heating films directly through battery pack engineering divisions, bypassing traditional thermal subsystem integrators.
- Tier-1 Suppliers:Thermal management specialists aggregate film procurement across multiple OEM platforms, capturing scale advantages in qualification and logistics.
- Vehicle Assemblers:Contract manufacturers in Chinese EV corridors source heating films through pack integrators rather than OEM thermal departments.
- Aftermarket Installers:Retrofit specialists target cold-climate fleet operators with battery warming solutions for existing EV platforms.
Tier-1 suppliers channel the majority of contract volume; vehicle assemblers are gaining procurement influence fastest.
Technology:
Smart heating architectures require embedded sensor networks and CAN bus integration capabilities that filter out pure component vendors. Conduction and radiant alternatives compete on unit economics with thinner differentiation.
- Smart Heating:Temperature feedback loops embedded directly into vehicle CAN bus architectures enable predictive thermal management. Tier-1 suppliers with embedded systems capabilities are consolidating margin pools around these integrated offerings.
- Infrared Heating:Far-infrared carbon formulations penetrate cabin surfaces without air circulation, reducing energy consumption versus forced-air alternatives.
- Conduction Heating:Direct contact film-to-surface configurations dominate battery pack applications where thermal transfer efficiency outweighs comfort considerations.
- Radiant Heating:Panel-based radiant systems persist in commercial vehicle cabins where zonal control requirements prove less complex.
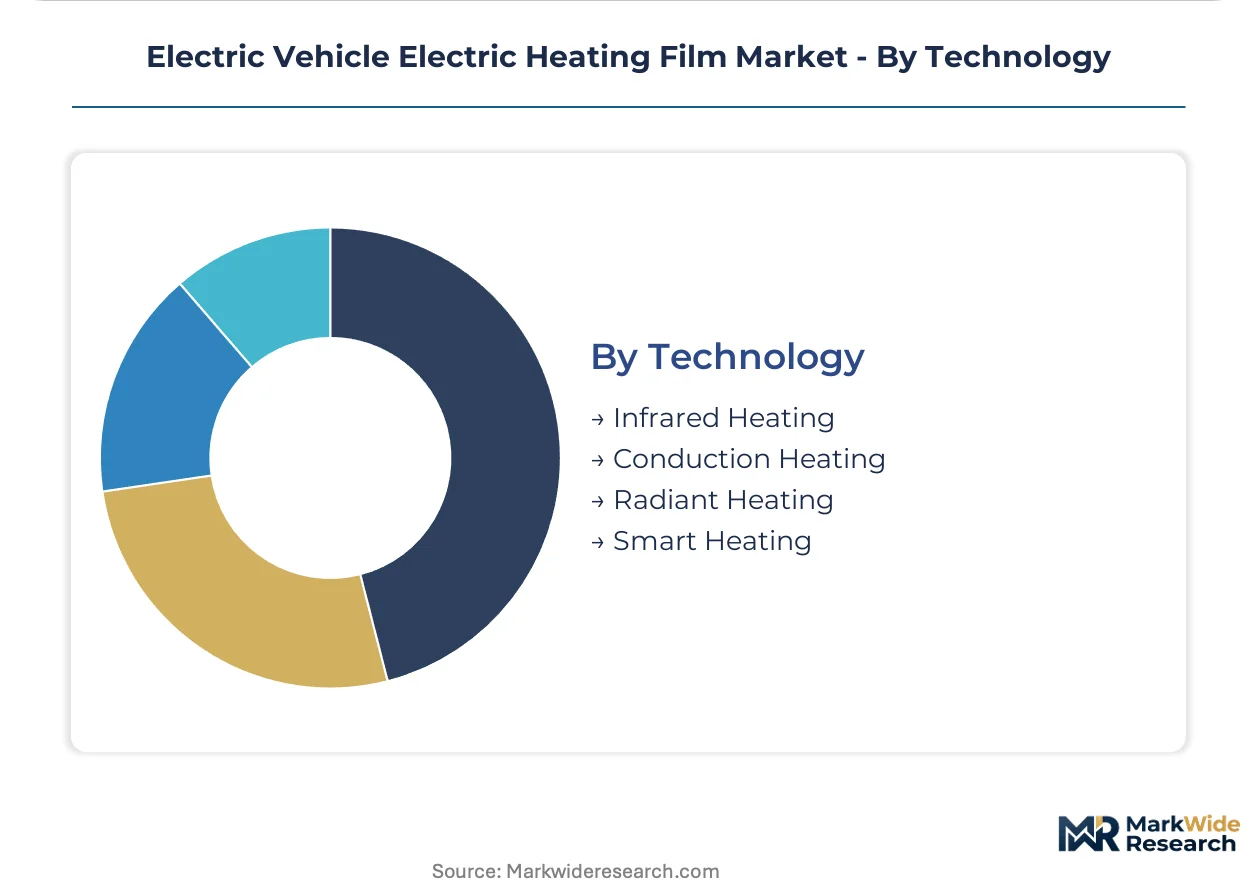
Conduction heating maintains dominant installed base; smart heating is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate EV battery manufacturing, pulling heating film suppliers toward localized fabrication capacity. Korean free economic zones around Busan and Ulsan anchor carbon film deposition expertise for 800V architectures. German automotive clusters in Baden-Württemberg enforce REACH-compliant material specifications that filter supplier participation.
China
Battery swap station operators in Shenzhen and Ningbo are compressing supplier qualification cycles by sourcing directly from CATL and BYD pack divisions. The Ministry of Ecology and Environment enforces dual carbon compliance timelines that eliminate energy-inefficient resistive wire heaters from domestic supply chains. Shanghai and Suzhou manufacturing corridors concentrate composite film lamination capacity serving premium EV platforms.
South Korea
LG Energy Solution and SK On cell production in Gwangju and Sejong generates procurement pull for high-power-density carbon formulations. The Ministry of Trade, Industry and Energy coordinates battery material localization incentives that favor domestic heating film suppliers. Busan-Ulsan chemical complexes supply polyimide substrates to regional film fabricators.
Germany
Premium OEMs in Stuttgart and Munich specify heating films directly through battery pack engineering divisions, bypassing traditional thermal integrators. ECHA REACH protocols restrict halogenated flame retardants, forcing phosphorus-nitrogen intumescent reformulations. Bavarian automotive clusters demand AEC-Q200 compliance that extends supplier qualification timelines.
United States
EPA tailpipe regulations and NHTSA safety standards mandate faster cabin warmup times that elevate heating film performance thresholds. Michigan and Ohio battery assembly corridors attract Korean film suppliers establishing localized production. IRA domestic content provisions incentivize North American fabrication capacity for commercial vehicle electrification.
India
Tropical and Himalayan climate extremes in Maharashtra and Tamil Nadu create divergent thermal management requirements for emerging EV platforms. The PLI scheme for advanced chemistry cells attracts heating film suppliers to establish localized production near cell manufacturing hubs. Gujarat and Karnataka automotive corridors concentrate vehicle assembly capacity driving procurement scale.
Electric Vehicle Electric Heating Film Market Competitive Landscape
East Asian producers anchor one tier; European and North American specialists hold qualification advantages in regulated markets. The supplier base stratifies across integrated thermal system architects, pure film converters, and automotive-grade material specialists. Two strategic archetypes dominate: Tier-1 thermal integrators bundling heating films with HVAC modules, and component specialists certifying directly with battery pack assemblers. Capacity expansion and REACH-compliant reformulation represent the dominant competitive moves.
Among integrated thermal system architects, BorgWarner Inc and Modine Manufacturing Company exemplify Tier-1 positioning that bundles heating films with broader vehicle thermal architectures. RexVa Co. Ltd. occupies a specialist tier focused on thin-film carbon formulations. These three entities represent contrasting archetypes: the diversified thermal integrator leveraging HVAC heritage, the integrated battery-to-cabin system architect, and the focused material specialist sustaining price-performance ratios under raw material scrutiny.
| Leading Market Players |
|---|
| Modine Manufacturing Company |
| BorgWarner Inc |
| Fenix Group |
| RexVa Co. Ltd. |
| Zhonghui Floor Heating |
| Calorique |
| Termofol |
| BVF Heating Solutions |
| LivingHeat |
| Others |
Pricing and Supply Chain Analysis
Carbon film deposition technology migration from batch to roll-to-roll processing is compressing unit economics while concentrating fabrication capacity among East Asian equipment holders. This dual effect simultaneously lowers per-square-meter production costs and raises capital barriers for European and North American suppliers seeking scale parity.
Pricing Analysis
Short lead-time premiums for REACH-compliant composite films now command 15-25% spreads over standard polyimide formulations in European procurement. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q200 certified battery-grade films from cabin comfort modules and aftermarket retrofit solutions. Cost compression in standard-grade polymer films is intensifying because Korean suppliers are flooding spot markets with excess carbon film inventory. Fleet operators and battery swap station integrators exhibit highest price sensitivity; premium German OEMs direct-purchasing through pack engineering divisions show least.
Supply Chain Analysis
AEC-Q200 and PPAP certification gating restricts qualified supplier pools to fewer than two dozen film fabricators globally. Polyimide substrate supply concentrates in Japan and South Korea; carbon conductive ink formulation draws from Chinese and German chemical specialists. Silver and copper price volatility creates margin unpredictability for ink-dependent film manufacturers locked into annual OEM contracts. Distribution runs through Tier-1 thermal integrators bundling films with HVAC modules, though battery pack assemblers are capturing direct procurement influence fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as REACH reformulation costs and AEC-Q200 qualification burdens force mid-cap pure-film converters toward exit or acquisition. Smaller players lacking in-house lamination capabilities face structural margin compression.
For Market Incumbents: Extend certification moats by accelerating phosphorus-nitrogen intumescent flame retardant formulations ahead of ECHA enforcement timelines. Capture backward integration into polyimide substrate production to reduce single-source exposure from Busan-Ulsan chemical complexes. Defensive capacity expansion in Michigan and Ohio battery corridors counters Korean suppliers establishing localized production.
For New Entrants and Emerging Players: India's PLI scheme for advanced chemistry cells opens a window for localized film fabrication serving tropical and Himalayan climate extremes with divergent thermal specifications. Target commercial vehicle battery conditioning where larger active heating areas and less stringent OEM direct-purchase protocols reduce qualification friction. Pursue module-level thermal validation partnerships with CATL and BYD pack divisions rather than vehicle-level homologation routes.
For Investors and Strategic Acquirers: Exit pathways concentrate in Tier-1 thermal integrators seeking carbon film deposition capabilities to complete battery-to-cabin system architectures. Long-term viability favors suppliers with embedded sensor networks and CAN bus integration competencies over pure component vendors. Watch for solid-state battery architecture announcements as inflection indicators requiring redesigned power density and spatial distribution specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Reformulation | ECHA phosphorus-nitrogen intumescent systems defend European OEM contracts against Korean exporters. |
| Roll-to-Roll Capacity Expansion | Busan-Ulsan chemical complexes anchor high-throughput carbon film deposition for 800V architectures. |
| Smart Heating Integration | CAN bus temperature feedback loops differentiate Tier-1 suppliers from pure film converters. |
| India PLI Localization | Maharashtra and Tamil Nadu production proximity captures emerging EV platform procurement. |
| Battery Pack Direct Certification | CATL and BYD pack division validation bypasses traditional OEM thermal engineering gatekeepers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with OEM platform engineers, Tier-1 thermal integrator procurement leads, carbon film deposition equipment specialists, and battery pack assembly division technical directors combined with ECHA REACH substance restriction databases, NMPA safety protocol filings, and Korean Ministry of Trade industry incentive disclosures. Bottom-up installed base modeling and top-down OEM thermal system spending estimates underwent cross-validation.
Data-stream reconciliation across vehicle production databases, battery pack thermal management specifications, and supplier qualification registries informed the analytical framework. Segmentation dimensions modeled include product chemistry tier, application placement, end-user procurement channel, and technology architecture across the projection horizon. CAGRs derived from coupled electrical-thermal-mechanical demand modeling and raw material cost trajectory assumptions. Solid-state battery thermal requirements and dual carbon compliance timeline enforcement served as scenario-variant inputs.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery architectures would alter the outlook for power density and dielectric isolation specifications. Forecasts reflect documented assumptions regarding OEM platform rollout cadences and regulatory enforcement intensity. A model refresh is warranted upon material change in ECHA REACH implementation timelines or solid-state cell commercialization announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Peer-To-Peer Electric Vehicle Charging Market
Electric Vehicles
Recreational Vehicle (RV) Batteries Market
Electric Vehicles
Global Electric Cars Market
Electric Vehicles
Electric Vehicle NVH Material Market
Electric Vehicles
China Electric Car Market
Electric Vehicles
Automotive Battery Powered Propulsion System Market
Electric Vehicles
Belgium Solar E-Bike Market
Electric Vehicles
Asia-Pacific Solar E-Bike Market
Electric Vehicles
48V Mild Hybrid Electric Vehicle (MHEV) Market
Electric Vehicles
Norway Electric Vehicle Market
Electric Vehicles
Electric Vehicle Battery Cases Market
Electric Vehicles
Used EV Market
Electric Vehicles
E-Lock for Electric Vehicle Charging Market
Electric Vehicles
Electric Vehicle Thermal Management Market
Electric Vehicles
Commercial Vehicle Traction Battery Systems Market
Electric Vehicles
Electric Mobility Market