
 Cargo Bike Market | 2026-2036
Cargo Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Cargo Bike Market Intelligence
Expanded manufacturing capacity in Southeast Asia is fragmenting the supply base for cargo bike components and assembly. Urban Arrow leverages its strong brand in the premium family and commercial segments in Europe. In contrast, Rad Power Bikes competes on a direct-to-consumer model with accessible price points. Tern Bicycles differentiates with its focus on compact and folding designs for urban commuters.
A cargo bike is a human- or electric-assisted cycle specifically engineered with an integrated chassis to carry loads heavier or bulkier than those manageable by a standard bicycle. Key design parameters include frame material, typically steel or aluminum, and load capacity, which can range from 40kg to over 250kg. Electric models now dominate new sales, particularly in the last-mile delivery application where operational efficiency is paramount. Among end users, logistics providers and courier services represent the fastest-growing segment, displacing passenger carrying as the primary commercial use case.
The European Union's EN 15194 standard for electrically power-assisted cycles governs market access, while in the United States, regulations from the Consumer Product Safety Commission (CPSC) set safety benchmarks. Additionally, municipal policies in cities like Copenhagen and Amsterdam that restrict van traffic directly incentivize commercial cargo bike adoption. Stakeholders must now decide whether to pursue captive fleet models or rely on third-party leasing and rental services to scale operations.
Market Dynamics
Municipal policies restricting traditional van access in dense urban cores are the central force shaping the market. The expansion of low-emission zones in cities like Berlin and Paris directly incentivizes commercial fleet conversion to electric cargo bikes for last-mile delivery.
Growth Catalysts
- Urban Access Regulations:Low-emission zones in European cities like Berlin restrict van traffic, creating a direct regulatory incentive for commercial cargo bike adoption.
- Battery Technology Gains:Advances in lithium-ion battery density extend vehicle range and reduce operational costs, making electric models viable for logistics fleets.
- Last-Mile Delivery Pressure:E-commerce growth drives demand for efficient urban delivery solutions, where cargo bikes outperform vans in congested areas.
Market Restraints
- High Initial Capital Outlay:The upfront cost of commercial-grade electric cargo bikes remains a significant adoption barrier for small businesses and independent couriers.
- Inadequate Urban Infrastructure:A lack of secure parking and charging stations in cities increases theft risk and complicates daily logistics for fleet operators.
- Regulatory Fragmentation:Inconsistent rules on vehicle weight and motor power across different municipalities create compliance challenges and costs for large-scale fleet deployments.
Strategic Opportunities
- North American Market Entry:Densely populated cities in the United States and Canada with rising traffic congestion represent underpenetrated markets for commercial cargo bike fleets.
- Service-Based Applications:Specialized models for mobile tradespeople, municipal maintenance crews, and food catering offer diversification opportunities beyond standard parcel delivery.
- Fleet-as-a-Service Models:Subscription and leasing services lower the high initial capital barrier for commercial users, accelerating adoption by converting it to an operational expense.
Industry Challenges
- Maintenance and Repair Skills Gap:A shortage of technicians trained in the specific mechanics and electronics of commercial-grade cargo bikes creates service bottlenecks and increases fleet downtime.
- Component Interchangeability:The lack of standardization for key components like batteries and motors across different manufacturers complicates fleet maintenance and limits supplier options.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cargo Bike Market |
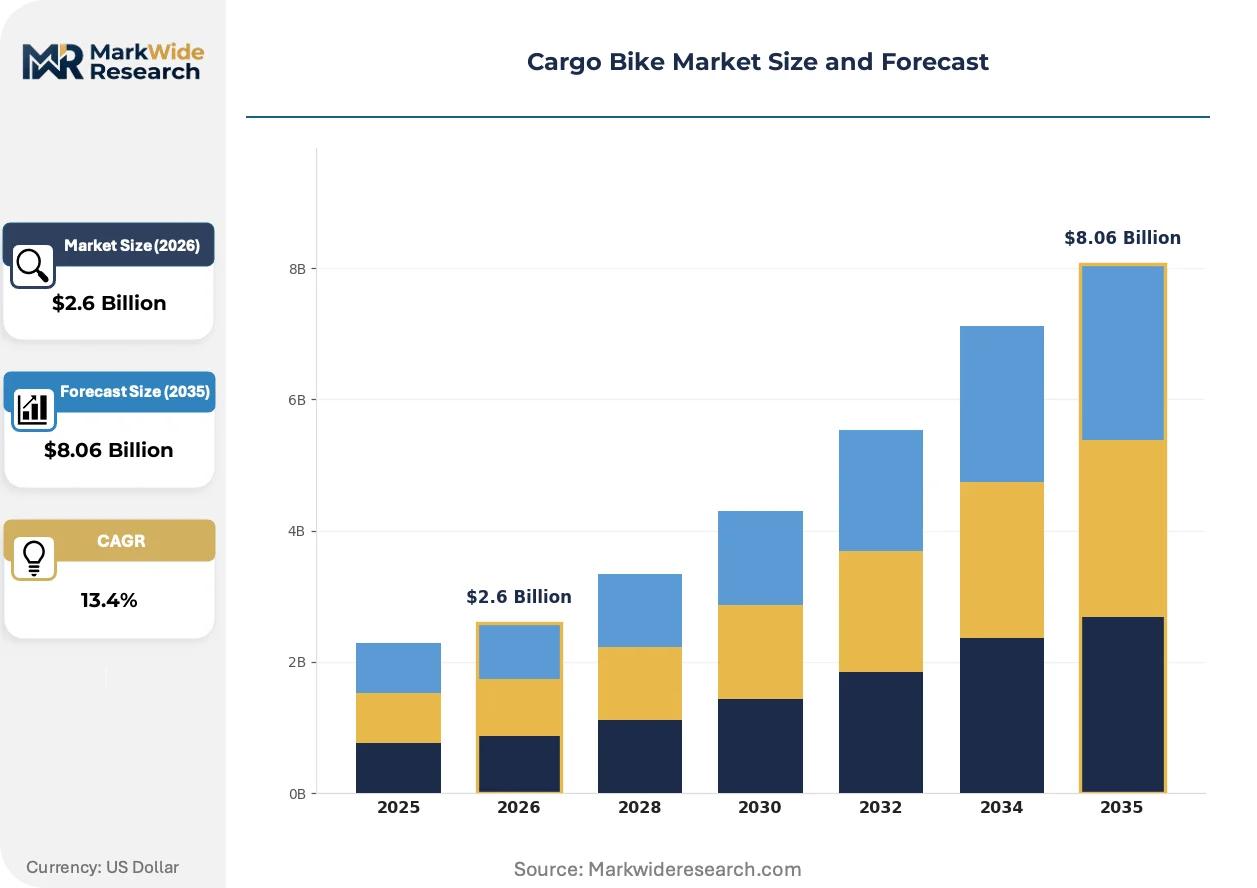
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $8.06 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Non-Electric, Tricycles, Folding, Longtail, Modular Application: Last-Mile Delivery, Cargo Transport, Passenger Carrying, Food & Beverage Distribution, Postal Services, Waste Collection End User: Logistics Providers, Courier Services, Retail Chains, Urban Commuters, Municipal Agencies, Delivery Startups Distribution Channel: Online Stores, Specialty Bicycle Shops, Direct Sales, Fleet Leasing, Rental Services, Wholesale Distributors |
| Companies Covered | Riese & Müller, Urban Arrow, Rad Power Bikes, Bakfiets.nl, Clever Cycles, Tern Bicycles, Brompton Bicycle, Specialized, Yuba Bicycles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cargo Bike Market Strategic Shifts & Innovations
Urban logistics integration is reshaping the cargo bike market, moving it from niche applications to a core infrastructural component. This evolution is driven by technological convergence and the formalization of operational requirements for commercial fleets.
Modular cargo bike platforms feature a standardized chassis with interchangeable front or rear cargo modules, such as boxes or flatbeds. Logistics providers adopt these systems to maximize the utility of a single frame for multiple purposes. This modularity is collapsing the distinction between single-purpose commercial and consumer models.
The European Union’s EN 15194 standard establishes critical safety requirements for electrically assisted cycles, including cargo bikes. Compliance serves as a mandatory gateway for market access, influencing global design for motor output and braking systems. The commercial segment is most affected, aligning product development with these European benchmarks to target Germany.
A notable shift in acquisition strategy is occurring as commercial operators move away from direct capital expenditure on vehicle purchases. Third-party fleet management and leasing services are gaining traction, offering packages that include the bikes, maintenance, and insurance for a fixed monthly fee. This trend is most prominent among large-scale logistics providers in Europe who seek to maintain fleet flexibility and minimize upfront investment.
Cargo Bike Market Segmentation
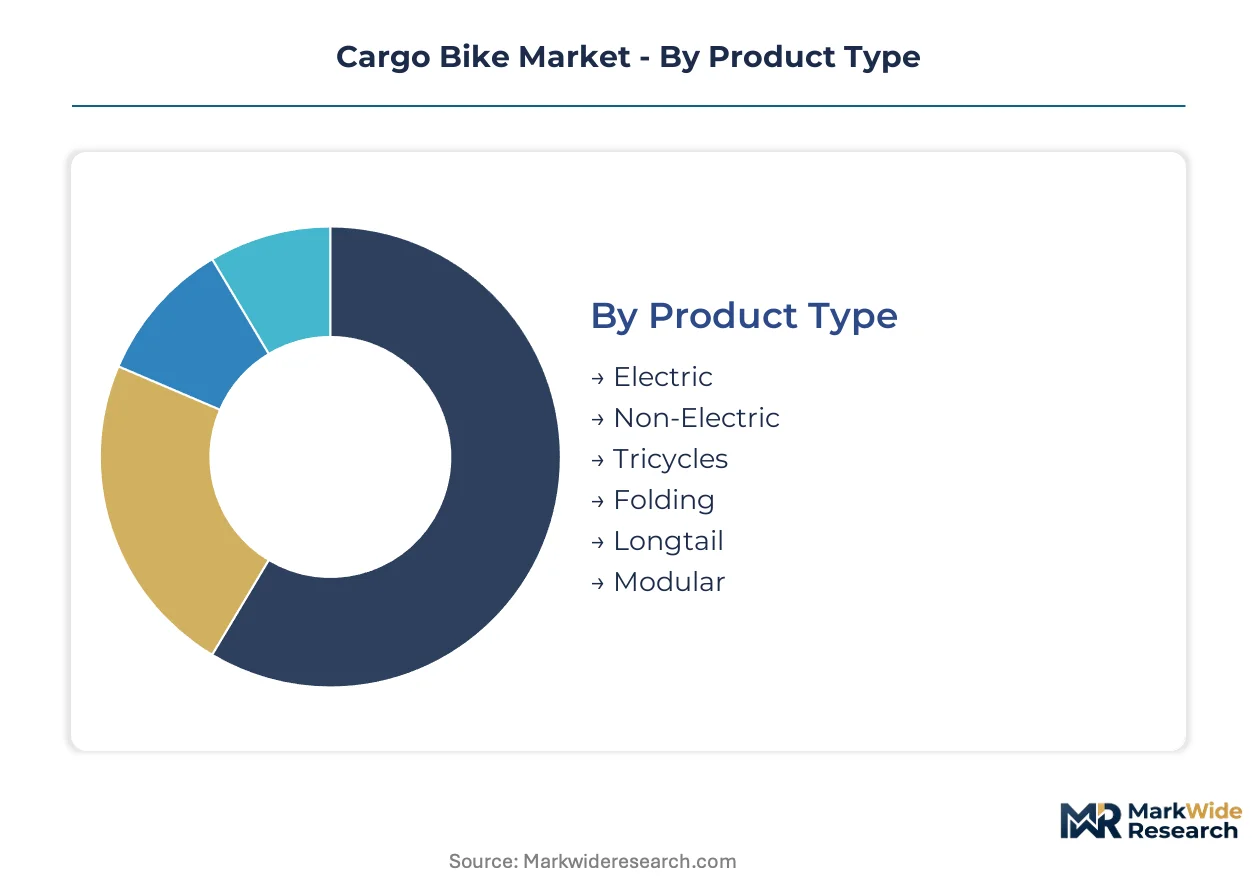
Market segmentation provides a granular view of the cargo bike industry, distinguishing distinct product configurations, application areas, end-user profiles, and distribution mechanisms. Understanding these segments is crucial for stakeholders to align product development and market entry strategies with specific demand patterns and operational requirements.
Product Type:
The cargo bike market's product segmentation reflects a diverse use-case spectrum, addressing varied operational demands and user preferences across urban environments.
- Electric:These cycles integrate an electric motor and battery system, providing pedal assistance to augment human power. New sales concentrate in last-mile delivery applications, driven by efficiency gains and regulatory incentives in European cities.
- Modular:Modular platforms feature a standardized chassis designed to accept interchangeable front or rear cargo modules. Logistics providers adopt these systems for operational flexibility, maximizing utility for multiple purposes in dense urban centers.
- Non-Electric:Human-powered cargo bikes offer a cost-effective solution for shorter distances and lighter loads.
- Tricycles:Three-wheeled designs provide enhanced stability and greater load capacity for specific commercial tasks.
- Folding:Compact designs cater to urban commuters prioritizing portability and secure storage in limited city spaces.
- Longtail:Extended rear frames accommodate larger loads or additional passengers, popular among families and small businesses.
The dominant share belongs to Electric models, while Modular platforms are closing the gap fastest in commercial adoption.
Application:
Application segmentation highlights the specific operational requirements cargo bikes fulfill across various urban services.
- Last-Mile Delivery:This application involves transporting goods from a distribution hub directly to the end customer, often within congested urban areas. E-commerce growth drives demand for efficient urban delivery solutions, where cargo bikes outperform vans in cities like Berlin and Paris.
- Food & Beverage Distribution:This segment focuses on specialized transport of prepared meals, groceries, or beverages, often requiring insulated containers. Urban density and demand for rapid, eco-friendly food delivery services concentrate demand in European metropolitan areas.
- Cargo Transport:General hauling of goods for businesses, often replacing traditional vans for intra-city logistics.
- Passenger Carrying:Transport of children or adults, primarily for family use or niche taxi services in pedestrian zones.
- Postal Services:National postal carriers utilize cargo bikes for efficient mail and small parcel delivery in residential districts.
- Waste Collection:Municipal agencies deploy specialized cargo bikes for localized waste and recycling collection in narrow urban streets.
Last-Mile Delivery applications are driving the market expansion, with Food & Beverage Distribution also showing significant growth.
End User:
End user segmentation clarifies the stakeholder-specific needs and operational models that influence cargo bike adoption.
- Logistics Providers:These large-scale companies integrate cargo bikes into their fleet for optimized last-mile operations and emissions reduction. Growth concentrates in Europe, where urban access regulations directly incentivize fleet conversion to electric cargo bikes.
- Municipal Agencies:Public sector entities deploy cargo bikes for diverse tasks, including maintenance, waste management, and public service delivery. Cities like Copenhagen and Amsterdam, with strong sustainable transport policies, show high adoption rates for these specialized applications.
- Courier Services:Independent couriers and smaller firms utilize cargo bikes for flexible, on-demand parcel and document delivery.
- Retail Chains:Businesses use cargo bikes for local deliveries from stores, enhancing customer service and reducing transport costs.
- Urban Commuters:Individuals leverage cargo bikes for daily transport of groceries, children, or work equipment within cities.
- Delivery Startups:New companies focus on niche or hyper-local delivery models, often built entirely around cargo bike fleets.
Logistics Providers seek the highest operational efficiency, while Delivery Startups represent a dynamic segment adapting quickly to market shifts.
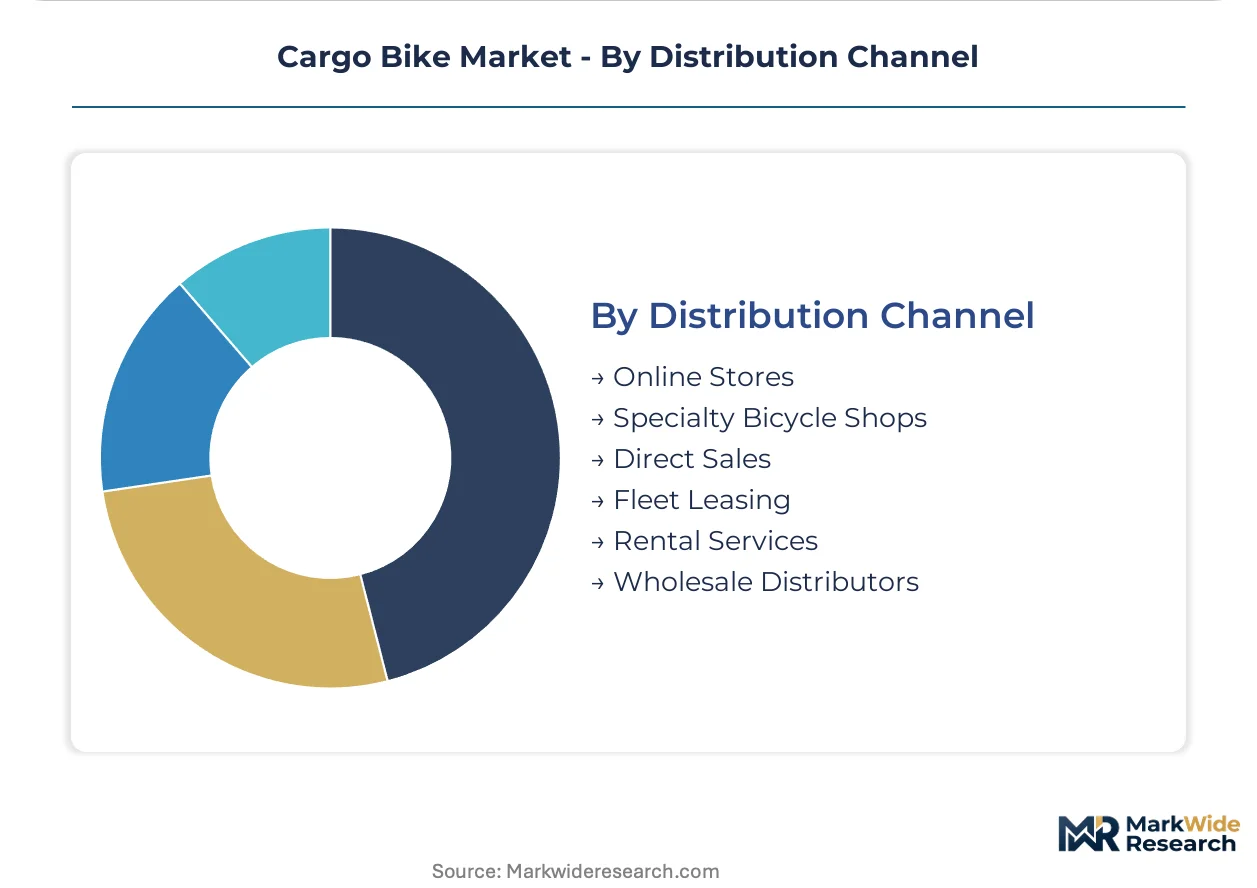
Distribution Channel:
Distribution channel segmentation outlines the primary market access and procurement strategies for cargo bike acquisition.
- Fleet Leasing:This channel offers subscription and leasing services, bundling bikes, maintenance, and insurance for commercial users. Large-scale logistics providers in Europe increasingly favor this model to lower initial capital outlay and maintain fleet flexibility.
- Specialty Bicycle Shops:These retail outlets provide expert advice, assembly, and after-sales service for both consumer and commercial cargo bikes. Premium brands like Urban Arrow leverage these shops for brand presence and customer engagement in key European markets.
- Online Stores:E-commerce platforms provide direct access to a wide range of cargo bike models at competitive price points.
- Direct Sales:Manufacturers engage directly with large commercial clients or municipal agencies for bulk orders and custom solutions.
- Rental Services:Short-term and long-term rental options cater to occasional users or businesses testing cargo bike integration.
- Wholesale Distributors:These intermediaries supply cargo bikes to smaller retailers and commercial clients across broader geographical areas.
Fleet Leasing is optimizing cost structures for commercial operators, while Online Stores expand consumer accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While European markets prioritize commercial fleet adoption and family transport, North American demand for cargo bikes is increasingly driven by urban commuting and small business logistics. This geographic divergence influences regulatory frameworks and infrastructure development across continents. Different policy incentives shape market growth trajectories in key regions.
Germany
Demand for cargo bikes in Germany is robust, driven by both commercial logistics providers and private consumers. German cities implement stringent low-emission zones, directly incentivizing electric cargo bike adoption for last-mile delivery. Berlin's municipal policies actively support cargo bike fleets, fostering a concentrated market for innovative urban mobility solutions.
Netherlands
Dutch urban planning prioritizes cycling infrastructure, making the Netherlands a leading market for cargo bike integration into daily life. Municipal policies in cities like Amsterdam restrict car traffic, providing a strong incentive for commercial and family cargo bike use. Amsterdam's dense urban core sees widespread adoption, with many businesses and families relying on cargo bikes for transport.
France
French cities face intense last-mile delivery pressure, driving demand for efficient and environmentally friendly cargo bike solutions. The EU Green Deal initiatives influence French urban planning, promoting sustainable transport alternatives like electric cargo bikes. Paris actively expands its network of cycling lanes and low-emission zones, accelerating fleet conversion for logistics providers.
United States
Urban congestion in densely populated US cities creates a significant opportunity for commercial cargo bike fleets. The Consumer Product Safety Commission (CPSC) sets safety benchmarks for electric bicycles, influencing product design for market entry. New York City's growing bike lane infrastructure supports increased cargo bike usage for local deliveries and small businesses.
Canada
Canadian cities experience rising traffic congestion and e-commerce growth, stimulating demand for efficient urban delivery. Provincial and municipal regulations in Canada often govern e-bike classifications, impacting cargo bike market access and use. Vancouver's commitment to sustainable urban transport encourages pilot programs and wider adoption of cargo bikes for various services.
Cargo Bike Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another in the cargo bike market. The market exhibits a tiered structure, with established European brands often occupying the premium segment, while direct-to-consumer models drive accessibility. Strategic archetypes include Premium Innovators, Value-Oriented D2C players, and Niche Specialists. Dominant competitive moves involve geographic expansion into underpenetrated markets and portfolio diversification, particularly through modular platform development.
Within the premium segment, Urban Arrow exemplifies European engineering focused on family and commercial utility. Rad Power Bikes, a US-based company, occupies a position emphasizing direct-to-consumer sales with accessible price points. Tern Bicycles, with its focus on compact and folding designs, anchors the niche for urban commuters prioritizing portability and storage efficiency.
| Leading Market Players |
|---|
| Riese & Müller |
| Urban Arrow |
| Rad Power Bikes |
| Bakfiets.nl |
| Clever Cycles |
| Tern Bicycles |
| Brompton Bicycle |
| Specialized |
| Yuba Bicycles |
| Others |
Cost & Logistics Intelligence
Southeast Asian manufacturing capacity dynamics influence downstream cargo bike pricing power. This expanded capacity fragments the supply base for components and assembly, leading to competitive pricing pressures for finished goods.
Pricing Analysis
European geographic price spreads reflect varying regulatory incentives and consumer demand levels. The dominant pricing model remains per-unit transactional, though subscription and leasing services are gaining traction. Price differentiation stems from brand premium and after-sales service bundles. Pricing pressure stems from increased manufacturing competition and the high initial capital outlay for commercial users. Logistics providers exhibit higher price sensitivity for fleet deployments, while premium consumer segments tolerate higher costs.
Supply Chain Analysis
Chinese and Southeast Asian contract manufacturers hold significant capacity for cargo bike components. The supply chain draws from global sources for lithium-ion batteries and specialized electric motors. Component interchangeability presents a structural risk, creating maintenance bottlenecks for fleet operators. Distribution runs through a hybrid model, combining direct sales to large commercial clients and specialty bicycle shops for consumer and smaller commercial sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits as a substitution defense play. Incumbents must navigate the threat of traditional light commercial vehicles (LCVs) adapting to urban restrictions, potentially offering hybrid or smaller electric van alternatives.
For Market Incumbents: Harden existing European market positions by deepening vertical integration into proprietary component manufacturing, particularly for electric drivetrains. Invest in expanding secure urban infrastructure partnerships to mitigate theft risks and charging station scarcity for fleet clients. Counter regulatory fragmentation by actively participating in standardization bodies like EN 15194 to shape future compliance requirements.
For New Entrants and Emerging Players: Build out specialized service-based applications beyond standard parcel delivery, targeting mobile tradespeople or municipal maintenance crews. The North American market, specifically densely populated US cities, represents a penetrable geography due to rising traffic congestion and nascent infrastructure. A direct-to-consumer sales model with accessible price points can capture early adopters in these underpenetrated regions.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-dependent growth play because widespread adoption hinges on urban planning and regulatory support. Target acquisition profiles include modular platform developers or fleet-as-a-service providers with established maintenance networks. A signal to watch is the accelerated expansion of dedicated cargo bike lanes and secure charging hubs in major North American cities.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Development | Standardized chassis designs maximize utility for logistics providers across diverse applications. |
| Fleet-as-a-Service Expansion | Subscription models lower initial capital barriers, accelerating adoption among commercial operators. |
| Battery Technology Partnerships | Collaborations with battery manufacturers extend vehicle range and reduce operational costs. |
| Urban Infrastructure Advocacy | Engagement with municipal agencies promotes secure parking and charging solutions. |
| Specialized Technician Training | Developing skilled labor addresses maintenance bottlenecks and reduces fleet downtime. |
Research Approach
A standing panel of logistics fleet managers, urban planners, cargo bike manufacturers, and specialty retailers provided ongoing calibration for market dynamics. This primary research, involving in-depth interviews, was validated against secondary data from transport authorities, urban mobility reports, and manufacturer financial statements. The analysis employed both bottom-up aggregation of segment data and top-down market sizing.
Scenario-bracketing framed the market projections, considering varied policy interventions and technological advancements across the analysis window. The analytical framework integrated segmentation dimensions including product type, application, end user, distribution channel, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected demand drivers, with key inputs including urban population density shifts and e-commerce penetration rates.
Stress conditions across battery cost fluctuations and regulatory implementation timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding sustained urban policy support and continued investment in cycling infrastructure. Quarterly review of low-emission zone expansions and battery energy density improvements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Bike Taxi Market
Bikes and Motorcycles
Malaysia Bicycle Market
Bikes and Motorcycles
Global Motorcycle Airbag System Market
Bikes and Motorcycles
Australia E- Bike Market
Bikes and Motorcycles
Two-Wheeler Lighting Market
Bikes and Motorcycles
Electric Motorsport Market
Bikes and Motorcycles
Austria E-Bike Market
Bikes and Motorcycles
Bicycle Brake Lever Market
Bikes and Motorcycles
Denmark E-Bike Market
Bikes and Motorcycles
Smart Bicycle Accessories Market
Bikes and Motorcycles
Sweden Electric Bike Market
Bikes and Motorcycles
Motorbike Carburetor Market
Bikes and Motorcycles
Latin America Fuel Cell Bikes Market
Bikes and Motorcycles
China Motorcycle ADAS Market
Bikes and Motorcycles
Motorcycle Accessories Market
Bikes and Motorcycles
Europe E-Cargo Bike Market