
 Electric Vehicle UBI Market | 2026-2036
Electric Vehicle UBI Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle UBI Market Insights
The gap between raw telematics capture and real-time risk scoring is narrowing as edge computing migrates into vehicle firmware. Progressive leverages its proprietary Snapshot platform to sustain competitive differentiation in data granularity. Tesla Insurance anchors its model on direct vehicle telemetry, bypassing third-party hardware entirely.
Electric Vehicle UBI refers to insurance products where premiums adjust dynamically based on actual vehicle usage patterns, battery performance metrics, and driver behavior data transmitted via onboard telematics modules operating at sub-second sampling frequencies. The primary commercial purpose is to align insurance costs with empirical risk exposure rather than static demographic proxies. Pay-As-You-Drive service types command the deepest margin pools where low-mileage EV owners cluster. Telematics technology dominates infrastructure investment as insurers demand millisecond-latency data streams for immediate premium adjustments.
The National Association of Insurance Commissioners in the United States coordinates state-level UBI regulatory frameworks, while the EU AI Act imposes algorithmic transparency requirements on automated underwriting decisions. The California Department of Insurance maintains the most stringent prior-approval regime for telematics-based rate filings, forcing carriers to demonstrate actuarial equivalence. Stakeholders must monitor whether emerging battery degradation models gain regulatory recognition as valid risk inputs before competitors lock in data partnerships with OEMs.
Market Dynamics
The migration of risk-scoring computation from cloud servers into vehicle firmware is collapsing latency windows for premium adjustments, forcing insurers to rebuild actuarial infrastructure around edge-native telemetry architectures.
Growth Catalysts
- Fleet electrification mandates:Commercial transport operators across Germany, France, and the Netherlands face binding decarbonization timelines that accelerate telematics adoption for usage-based coverage.
- GDPR-compliant data frameworks:The EU AI Act establishes algorithmic transparency standards that legitimize automated underwriting decisions, reducing regulatory friction for predictive premium models.
- Edge computing integration:Sub-second sampling frequencies in onboard modules enable real-time battery degradation tracking, expanding the addressable risk surface for dynamic pricing.
Market Restraints
- Silicon supply concentration:Semiconductor fabrication for telematics control units clusters in East Asian foundries, exposing insurers to geopolitical disruption in module procurement.
- Actuarial validation costs:California's prior-approval regime forces carriers to demonstrate equivalence between telematics-based and traditional rating methods, extending product launch timelines.
- Data interoperability gaps:OEMs deploy proprietary telemetry protocols that fragment the aftermarket hardware ecosystem, limiting insurer choice in data sourcing.
Strategic Opportunities
- Second-life battery insurance:Stationary energy storage applications create demand for coverage products tied to degraded EV battery packs, opening a parallel revenue stream.
- Pay-As-You-Drive penetration in Italy:Mediterranean markets with high urban density and low annual mileage per vehicle remain underpenetrated relative to Northern European adoption rates.
- CSRD-aligned ESG reporting:Corporate sustainability disclosure requirements position UBI products as verifiable Scope 3 reduction instruments for fleet sustainability officers.
Industry Challenges
- Cross-border data governance:The KBA's connected vehicle standards in Germany diverge from French CNIL consent frameworks, complicating pan-European product standardization.
- Battery chemistry expertise scarcity:Underwriting teams lack sufficient electrochemical engineering depth to validate degradation models supplied by OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle UBI Market |
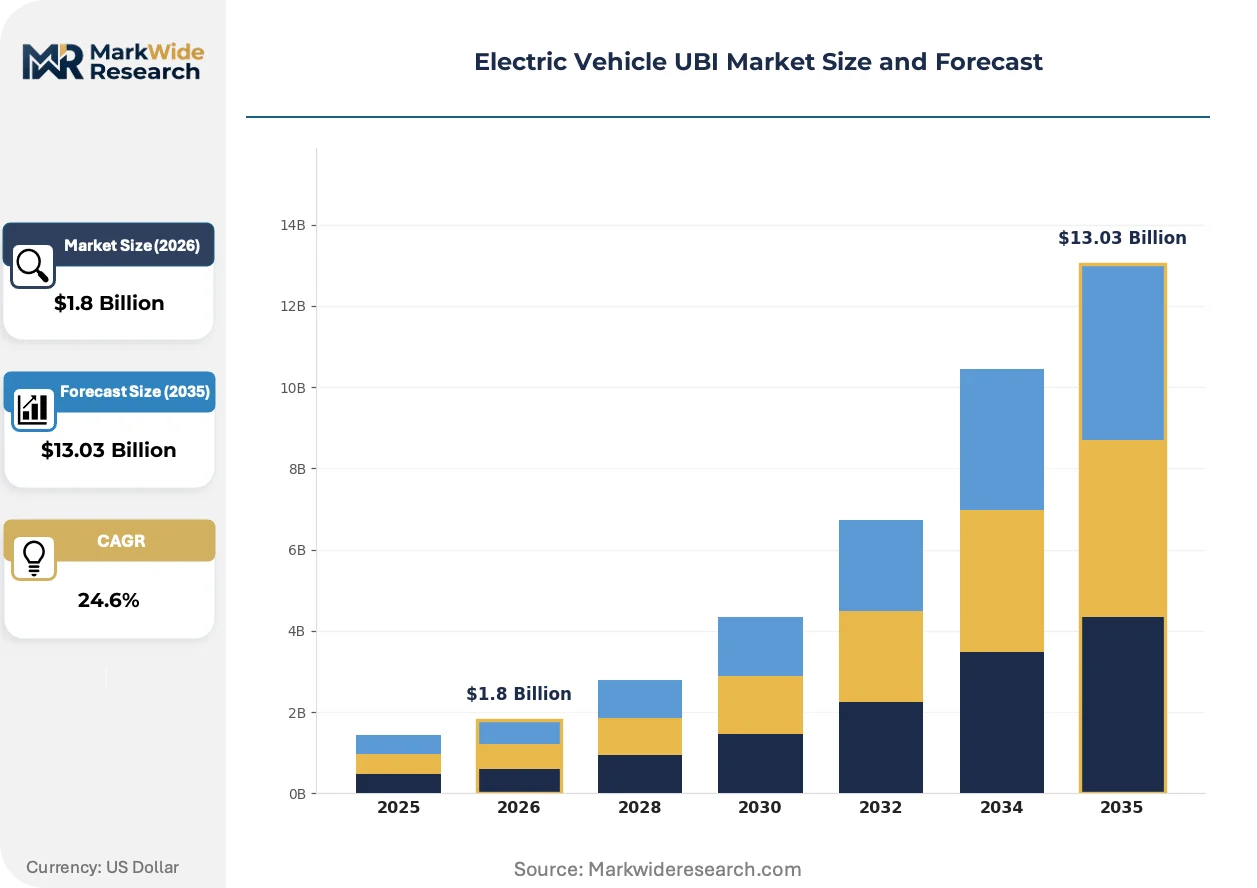
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $13.03 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Pay-Per-Mile, Pay-As-You-Drive, Usage-Based, Risk-Based Technology: Telematics, Mobile Apps, GPS, Data Analytics End User: Individual Drivers, Fleet Operators, Insurers, Leasing Companies Billing Model: Subscription, One-Time Fee, Microtransactions, Discounts |
| Companies Covered | Root Insurance, Metromile, Progressive, Nationwide, Allianz Insurance, Liberty Mutual, State Farm, Tesla Insurance, Lemonade, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle UBI Market Trends and Innovations
Telematics architecture is shifting from retrospective data logging toward predictive risk engines that anticipate incidents before they materialize, compressing the traditional claims cycle.
Embedded SIM technology is collapsing the distinction between vehicle manufacturing and insurance distribution. Automakers now provision connectivity at the factory floor, enabling zero-touch policy activation upon vehicle registration. Fleet operators purchasing in volume are demanding this integration as standard, bypassing aftermarket hardware installation entirely.
The EU AI Act imposes mandatory documentation requirements on automated underwriting algorithms. Insurers must maintain technical files demonstrating bias testing and human oversight protocols. This regulatory architecture most acutely affects German and French carriers with the largest portfolios of algorithmically priced EV policies, forcing structural investments in compliance infrastructure.
Commercial buyers are consolidating procurement around integrated mobility service contracts that bundle vehicle lease, energy, maintenance, and insurance into single agreements. Traditional brokers face displacement as OEM captive finance arms and energy utilities capture these consolidated relationships. This pattern concentrates most visibly in Nordic markets where corporate fleet electrification timelines are most advanced.
Electric Vehicle UBI Market Segmentation
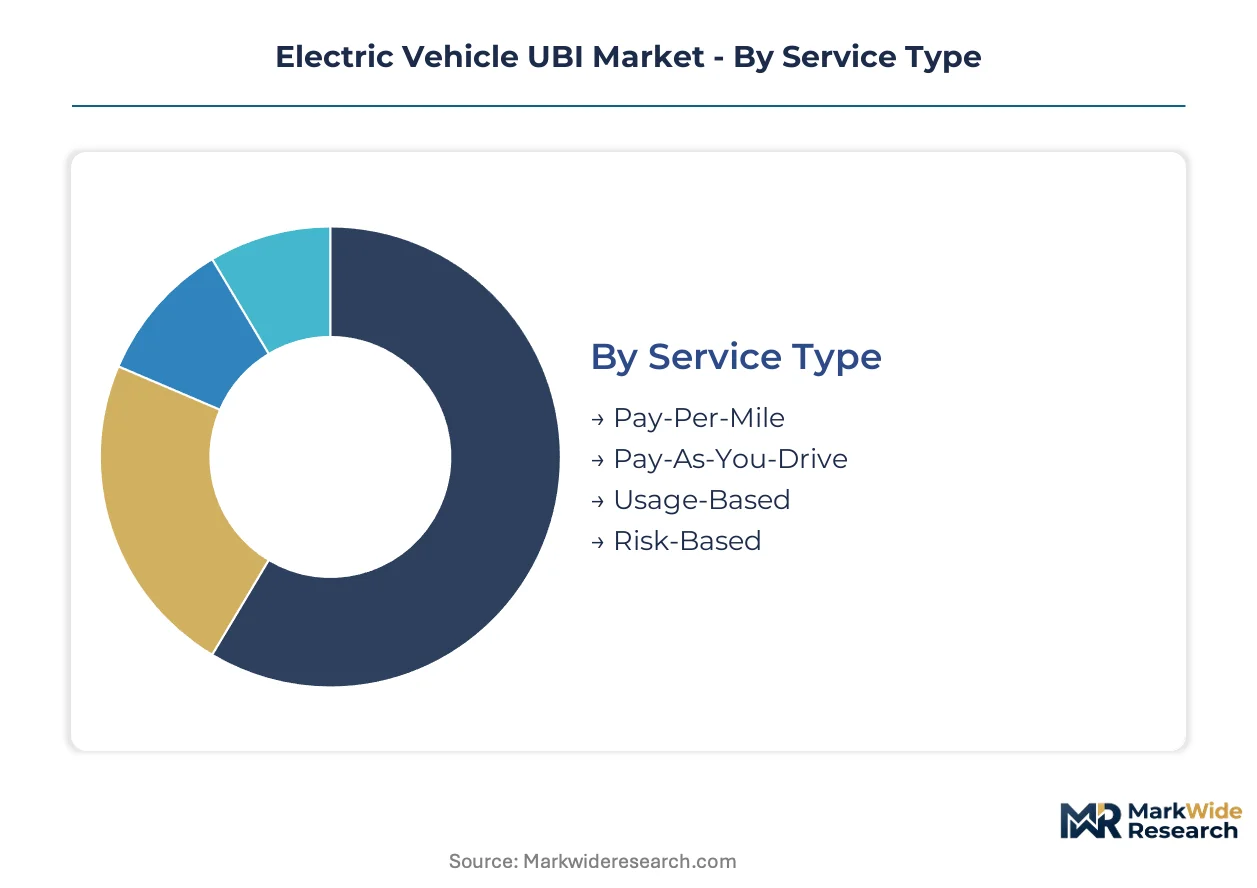
Segmentation in the Electric Vehicle UBI market determines how data collection infrastructure aligns with risk pricing mechanics and customer acquisition costs. Service type and technology choices directly impact actuarial model complexity and regulatory compliance burdens across jurisdictions.
Service Type:
After-sales service intensity varies sharply across service types, with Risk-Based models demanding continuous algorithmic recalibration and dedicated data science support teams.
- Pay-Per-Mile:Premiums scale linearly with odometer readings transmitted via embedded telematics modules. Demand clusters among low-mileage urban commuters in Germany and the Netherlands where annual vehicle kilometers fall below regional medians.
- Pay-As-You-Drive:Combines distance metrics with temporal risk factors including time-of-day and road type classifications. Fleet operators purchasing integrated mobility contracts in Nordic markets are driving the steepest expansion trajectory for this segment.
- Usage-Based:Incorporates multi-dimensional behavioral telemetry including acceleration patterns and regenerative braking efficiency. Battery performance degradation tracking adds actuarial complexity unique to electrified powertrains.
- Risk-Based:Deploys predictive algorithms scoring collision probability from real-time sensor fusion. The EU AI Act documentation requirements impose compliance overhead that favors carriers with existing algorithmic governance infrastructure.
By volume, Pay-As-You-Drive leads. By growth pace, Risk-Based is ahead.
Technology:
Cost tier differentiation separates premium integrated systems from aftermarket retrofit solutions, with OEM-embedded hardware commanding three to five times the unit economics of third-party alternatives.
- Telematics:Onboard modules sampling vehicle telemetry at sub-second frequencies enable real-time premium adjustments. Edge computing migration into vehicle firmware is collapsing latency windows for risk-scoring computation.
- Mobile Apps:Smartphone-based data capture offers lower entry costs but suffers from GPS drift and driver distraction validation gaps. Italian and Spanish insurers favor this approach for price-sensitive individual driver segments.
- GPS:Location tracking underpins geofenced pricing zones and theft recovery services. Cross-border data governance variations between German KBA standards and French CNIL consent frameworks complicate pan-European deployment.
- Data Analytics:Predictive engines processing multi-source telemetry streams require specialized battery chemistry expertise scarce in traditional underwriting teams.
Telematics dominates revenue contribution. Data Analytics is climbing the fastest.
End User:
Customer type segmentation reveals divergent procurement patterns, with fleet operators demanding bundled service contracts while individual drivers respond to direct-to-consumer digital distribution.
- Individual Drivers:Price-sensitive owners of privately registered EVs purchasing coverage through digital comparison platforms. German and French markets show highest penetration rates among early electric vehicle adopters.
- Fleet Operators:Commercial transport managers procuring integrated mobility services combining lease, energy, maintenance, and insurance. Binding decarbonization timelines across Germany, France, and the Netherlands are accelerating telematics adoption.
- Insurers:Carriers building proprietary data assets or sourcing telemetry through OEM partnerships. California's prior-approval regime forces extended validation timelines for telematics-based rate filings.
- Leasing Companies:Asset owners requiring residual value protection through usage monitoring and driver behavior enforcement.
Fleet Operators lead by policy count. Insurers are gaining share fastest.
Billing Model:
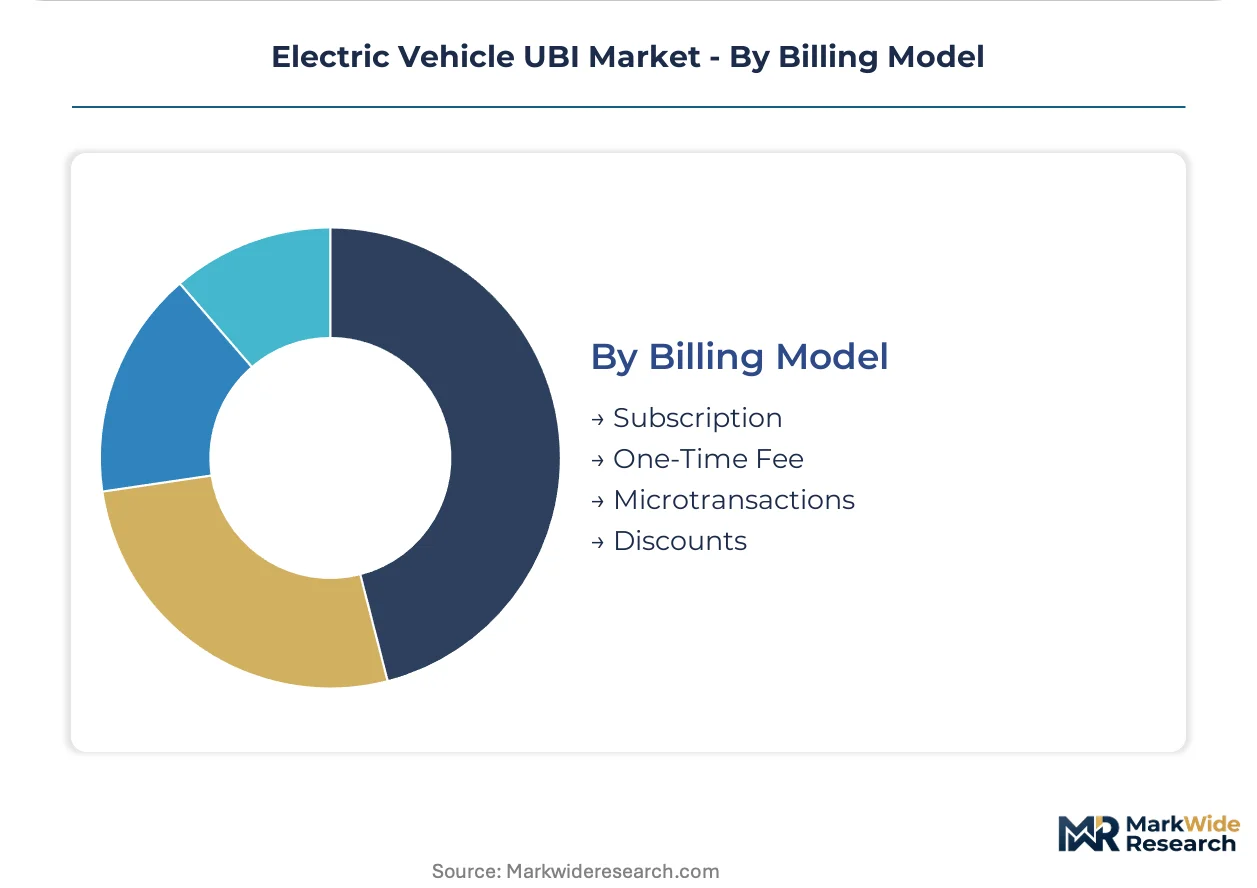
Margin structure varies across billing approaches, with Subscription models offering predictable revenue streams while Microtransactions demand sophisticated payment infrastructure.
- Subscription:Recurring monthly or annual payments with tiered feature access. Standard for integrated fleet contracts and OEM captive insurance products.
- One-Time Fee:Single upfront payment for fixed-duration coverage periods. Appeals to seasonal vehicle users and second-home owners with intermittent EV usage patterns.
- Microtransactions:Per-trip or per-kilometer billing requiring real-time payment processing integration. Embedded SIM factory provisioning enables zero-touch policy activation.
- Discounts:Retrospective premium reductions based on verified safe driving scores. Progressive's Snapshot platform exemplifies this behavioral incentive architecture.
Subscription dominates by revenue stability. Microtransactions show steepest expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telematics module trade flows favor Germany and the United States as net importers of Asian-manufactured semiconductors, while regulatory divergence across jurisdictions fragments product standardization. Data localization mandates in France and consent framework variations in Germany complicate cross-border policy administration for multinational carriers.
United States
Fleet electrification timelines in California and New York accelerate commercial UBI adoption among logistics operators. The California Department of Insurance maintains stringent prior-approval requirements for telematics-based rate filings. Silicon Valley hosts the densest concentration of insurtech startups developing predictive driving algorithms.
Germany
Binding commercial transport decarbonization mandates drive fleet operator demand for integrated mobility contracts. The KBA oversees connected vehicle data standards that shape insurer-OEM integration protocols. Munich and Stuttgart anchor the European telematics engineering cluster, hosting captive finance arms of major automakers.
France
Urban low-emission zones in Paris and Lyon expand addressable markets for pay-per-mile products among occasional drivers. The CNIL imposes granular consent requirements for biometric driver data processing that exceed baseline GDPR standards. The Île-de-France region concentrates insurtech development talent and regulatory compliance expertise.
Netherlands
High urban density and compressed average trip distances favor pay-as-you-drive penetration among private EV owners. National climate agreements mandate fleet electrification timelines that outpace most European neighbors. Amsterdam hosts headquarters for several mobility platform operators bundling insurance into subscription services.
China
Domestic EV production volumes exceed any other market, creating latent demand for usage-based coverage products. MIIT standards govern connected vehicle data transmission protocols that influence telematics architecture design. The Yangtze River Delta region concentrates battery manufacturers and telematics control unit fabricators.
Electric Vehicle UBI Market Competitive Landscape
On the supply side, the industry is bifurcated between legacy carriers rebuilding actuarial infrastructure and technology-native entrants unencumbered by legacy policy administration systems. Strategic archetypes divide into OEM-captive insurers leveraging factory-embedded telemetry, independent insurtechs sourcing data through aftermarket hardware partnerships, and traditional carriers acquiring telematics capabilities through strategic investments. Dominant competitive moves center on OEM data partnership exclusivity and edge computing integration into vehicle firmware.
Among technology-native entrants, Root Insurance and Metromile exemplify the mobile-first data capture archetype that bypasses dedicated hardware installation. Progressive anchors the traditional carrier transformation tier, having sustained competitive differentiation through proprietary platform development. Tesla Insurance occupies a singular position as the only OEM-captive insurer with direct access to factory-embedded telemetry streams.
| Leading Market Players |
|---|
| Root Insurance |
| Metromile |
| Progressive |
| Nationwide |
| Allianz Insurance |
| Liberty Mutual |
| State Farm |
| Tesla Insurance |
| Lemonade |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta freight corridor carries semiconductor components from East Asian foundries to German telematics engineering clusters in Munich and Stuttgart, with logistics cost inflation amplifying the spread between OEM-embedded hardware premiums and aftermarket retrofit alternatives. This corridor's congestion patterns directly shape how insurers source telematics modules and where they accept margin compression.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with factory-embedded telematics commanding three to five times the unit economics of third-party alternatives. Price differentiation rests on certification grade alignment with KBA connected vehicle standards and volume scale in fleet procurement contracts. Pricing pressure stems from silicon supply concentration in East Asian foundries, compressing margins for carriers dependent on aftermarket hardware sourcing. Fleet operators purchasing integrated mobility contracts show lowest price sensitivity, while individual drivers accessing coverage through digital comparison platforms exhibit highest elasticity.
Supply Chain Analysis
Telematics control unit fabrication concentrates in Taiwan, South Korea, and mainland China, with foundry capacity allocation favoring automotive-grade semiconductor orders from captive OEM finance arms. Raw material dependencies span lithium-ion battery cells for secondary-life coverage products, rare earth elements for GPS module magnetics, and specialized substrates for edge computing chipsets. Single-source vulnerability in advanced node semiconductor production exposes insurers to geopolitical disruption in module procurement. Distribution runs through OEM captive channels for factory-embedded solutions and aftermarket installer networks for retrofit hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Electric Vehicle UBI market sits in early-cycle expansion, with fleet electrification mandates across Germany, France, and the Netherlands accelerating telematics adoption faster than individual driver penetration.
For Market Incumbents: Insulate proprietary data assets through exclusive OEM partnership lock-ups before algorithmic transparency requirements under the EU AI Act commoditize predictive scoring models. Deepen edge computing integration into vehicle firmware to collapse latency windows that new entrants cannot replicate without factory-embedded telemetry access. Prioritize compliance infrastructure investment in Germany and France where algorithmic documentation mandates are most stringent. For New Entrants and Emerging Players: Mediterranean markets with high urban density and low annual mileage per vehicle offer the most penetrable white-space for pay-per-mile products, with Italian and Spanish price-sensitive individual driver segments responding to smartphone-based data capture at lower entry costs. Target second-life battery insurance for stationary energy storage applications as a parallel revenue stream with minimal incumbent competition. Pursue direct-to-consumer digital distribution bypassing traditional broker channels. For Investors and Strategic Acquirers: Carve-out targets emerge from traditional carriers divesting telematics infrastructure investments that failed to achieve actuarial validation under California's prior-approval regime. Long-term viability over the next decade hinges on securing OEM data partnership exclusivity before factory-embedded connectivity becomes standard. Monitor regulatory recognition of battery degradation models as valid risk inputs as the critical inflection signal for valuation step-ups. Quarterly review of KBA standard adoption rates and CNIL consent framework harmonization progress is advised to detect inflection.| Strategic Initiative | Industry Significance |
|---|---|
| OEM Data Partnership Exclusivity | Factory-embedded telemetry access locks out competitors from real-time battery degradation scoring. |
| Edge Computing Firmware Integration | Sub-second risk-scoring latency enables dynamic premium adjustments before cloud-native rivals respond. |
| EU AI Act Compliance Infrastructure | Algorithmic documentation capabilities satisfy French CNIL and German KBA transparency mandates simultaneously. |
| Second-Life Battery Coverage Launch | Stationary storage applications open revenue streams outside saturated primary vehicle insurance pools. |
| Integrated Mobility Contract Bundling | Nordic fleet procurement consolidation captures lease, energy, maintenance, and insurance in single agreements. |
Research Methodology
Initial hypotheses were tested against primary input from fleet operations managers, insurance actuarial directors, OEM platform engineers, and regulatory compliance officers, and refined through secondary validation against SEC carrier filings, KBA technical standards documentation, EU AI Act implementation guidance, and vehicle production registration databases. Bottom-up policy volume estimates triangulated with top-down telematics module shipment data.
Demand-supply-balance framing structured the analytical approach across the projection horizon, with segmentation modeling across service type, technology tier, end-user category, and billing model dimensions. CAGRs were derived from fitted adoption curves incorporating fleet electrification mandate timelines and battery degradation model regulatory acceptance trajectories. Forecast inputs included OEM captive insurance penetration rates and aftermarket hardware cost compression curves.
Practitioners should monitor silicon supply disruption indicators, EU AI Act enforcement variance across member states, and battery degradation model validation acceptance for early signals of forecast revision. Quarterly review of KBA standard adoption rates and CNIL consent framework harmonization progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Germany Electric Bus Battery Pack Market
Electric Vehicles
Automotive Battery Pack Pressure Equalization Membrane Market
Electric Vehicles
Electric Vehicle Regenerative Braking System Market
Electric Vehicles
Europe Electric Vehicle Thermal Management System Market
Electric Vehicles
Electric Sports Utility Vehicle (E-SUV) Market
Electric Vehicles
Electric Bus Market
Electric Vehicles
Electric Axle Drive Systems Market
Electric Vehicles
Norway Electric Vehicle Market
Electric Vehicles
Automotive Coolant Distribution Manifold for EV Battery Market
Electric Vehicles
ASEAN EV Battery Pack Market
Electric Vehicles
One Wheel Electric Scooter Market
Electric Vehicles
Electric Vehicle Battery Trays Market
Electric Vehicles
Europe Fuel Cell Electric Vehicle Market
Electric Vehicles
South America Electric Vehicle (EV) Fluids Market
Electric Vehicles
AC BEV On-Board Charger Market
Electric Vehicles
Electric Vehicle Communication Controller Market