
 Electric Vehicle Sound Generators Market | 2026-2036
Electric Vehicle Sound Generators Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Sound Generators Market Intelligence
Passenger vehicle procurement is shifting from standalone external speaker systems toward fully integrated acoustic vehicle alert systems embedded at the platform design stage. Continental AG leverages its Tier-1 supplier relationships to dominate integrated system architecture for European OEMs. Aptiv sustains technology leadership in resonator-based alert modules through concentrated R&D spending on frequency modulation algorithms. Denso Corporation anchors its position in piezoelectric transducer supply chains across Japanese and Korean vehicle programs.
Electric vehicle sound generators are electromechanical or solid-state acoustic devices engineered to emit synthesized or amplified sound patterns at frequencies between 500 Hz and 10 kHz, primarily to satisfy pedestrian safety mandates in near-silent battery-electric drivetrains. These systems employ piezoelectric actuators, electromagnetic drivers, or MEMS-based resonators to generate directional audio output with programmable amplitude envelopes tailored to vehicle speed and operating mode. Acoustic vehicle alert systems command the largest installed base due to regulatory mandates, while active sound enhancement captures expanding margin pools as luxury OEMs pursue brand-differentiated cabin acoustics. Ultrasonic detector applications in parking assistance represent the fastest-growing technology segment as automakers consolidate sensor fusion architectures.
The U.S. NHTSA Federal Motor Vehicle Safety Standard No. 141 mandates minimum sound levels for hybrid and electric vehicles, compelling hardware compliance across all light-duty platforms sold domestically. The EU's UN Regulation No. 138 and forthcoming amendments under the EU Green Deal framework are tightening AVAS performance thresholds and expanding coverage to heavier vehicle classes. Stakeholders must monitor regulatory divergence between U.S. minimum-sound rules and EU directional-accuracy requirements when configuring global platform architectures.
Market Dynamics
Platform-level integration of acoustic alert hardware is compressing procurement timelines and forcing Tier-1 suppliers to co-develop with OEMs during vehicle architecture definition rather than at post-design validation stages.
Growth Catalysts
- UN Regulation No. 138:The EU's updated AVAS mandates expand coverage to heavier vehicle classes and tighten directional-accuracy thresholds, compelling hardware redesigns across European platforms.
- Piezoelectric transducer miniaturization:Advances in solid-state acoustic generation enable embedded mounting within bumper fascias and wheel arches, reducing packaging constraints for compact EV architectures.
- German premium OEM bundling:Stuttgart and Munich-based automakers are pairing pedestrian alert systems with active cabin sound enhancement, creating dual-revenue attachment opportunities for acoustic module suppliers.
Market Restraints
- Rare-earth magnet cost volatility:Neodymium price swings disrupt electromagnetic driver manufacturing economics, squeezing margins for resonator-based alert module producers.
- Japanese-Korean supply concentration:Piezoelectric ceramic substrate fabrication clusters in Osaka and Seoul create single-source vulnerability for transducer assembly lines.
- Frequency modulation IP thickets:Patent estates held by audio semiconductor incumbents block independent development of algorithmic sound shaping for speed-variable amplitude envelopes.
Strategic Opportunities
- India's PLI scheme for auto components:The production-linked incentive framework for advanced automotive electronics creates localized assembly incentives for AVAS module manufacturers.
- Sensor fusion convergence:Integration of ultrasonic parking detectors with pedestrian alert speakers enables consolidated ECU architectures and reduced wiring harness complexity.
- China's dual carbon enforcement:Provincial implementation of NEV safety standards in Jiangsu and Guangdong provinces accelerates retrofit demand for commercial electric van and bus fleets.
Industry Challenges
- Acoustic engineer scarcity:The intersection of automotive NVH expertise and digital signal processing specialization remains critically underpopulated across supplier engineering centers.
- UN Regulation No. 138 homologation timelines:Directional sound testing protocols require anechoic chamber certification cycles that extend platform launch schedules by 4-6 months.
- Legacy ICE platform retrofit complexity:Accommodating AVAS hardware within existing internal combustion vehicle electrical architectures demands custom harness routing and power distribution redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Sound Generators Market |
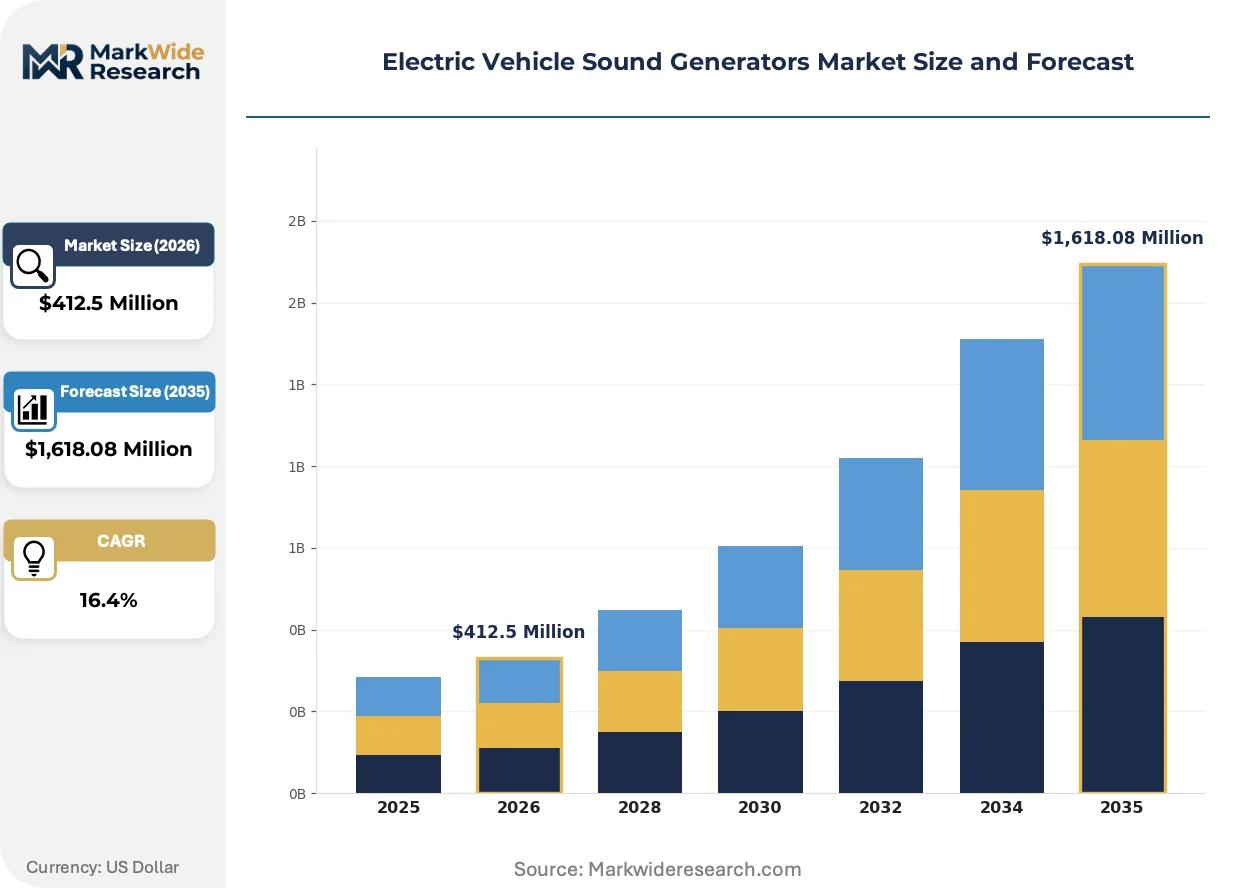
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,618.08 Million |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Sound Enhancement, Passive Sound Generator, External Speaker System, Acoustic Vehicle Alert System, Ultrasonic Detector Technology: Piezoelectric, Electromagnetic, Ultrasonic, Microelectromechanical Systems, Resonator-Based Application: Pedestrian Safety, Parking Assistance, Collision Avoidance, Blind Spot Detection, Vehicle Identification End User Segment: Original Equipment Manufacturers, Tier-1 Suppliers, Aftermarket Service Providers, Vehicle Assemblers |
| Companies Covered | Aptiv, Forvia Hella, Continental AG, Brigade Electronics, STMicroelectronics, Denso Corporation, Hyundai Mobis, Brose Fahrzeugteile, Harman International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Sound Generators Market Strategic Shifts & Innovations
MEMS-based resonator technology is consolidating multiple acoustic functions into single-chip architectures, collapsing the traditional separation between pedestrian alert generation and cabin sound enhancement systems.
MEMS resonator arrays are unifying directional beamforming with programmable frequency sweeps in surface-mount packages. Premium German OEMs are embedding these devices during platform definition rather than post-validation. This unification is compressing supplier tiers and eliminating discrete amplifier-module procurement for integrated cockpit domains.
NHTSA's Federal Motor Vehicle Safety Standard No. 141 minimum sound requirements are tightening enforcement protocols for hybrid vehicle categories previously granted provisional exemptions. US light-duty truck platforms face retroactive compliance obligations. Heavy-duty pickup electrification programs in Detroit and Dearborn are accelerating hardware redesigns to meet revised decibel thresholds at low-speed operation.
Fleet procurement of commercial EVs is fragmenting across vocational specifications rather than consolidating around standard configurations. Municipal transit authorities in California and Texas are issuing separate RFPs for bus AVAS systems with distinct acoustic signatures. This fragmentation is forcing acoustic module suppliers to maintain parallel firmware branches for customer-specific sound profiles.
Electric Vehicle Sound Generators Market Segmentation
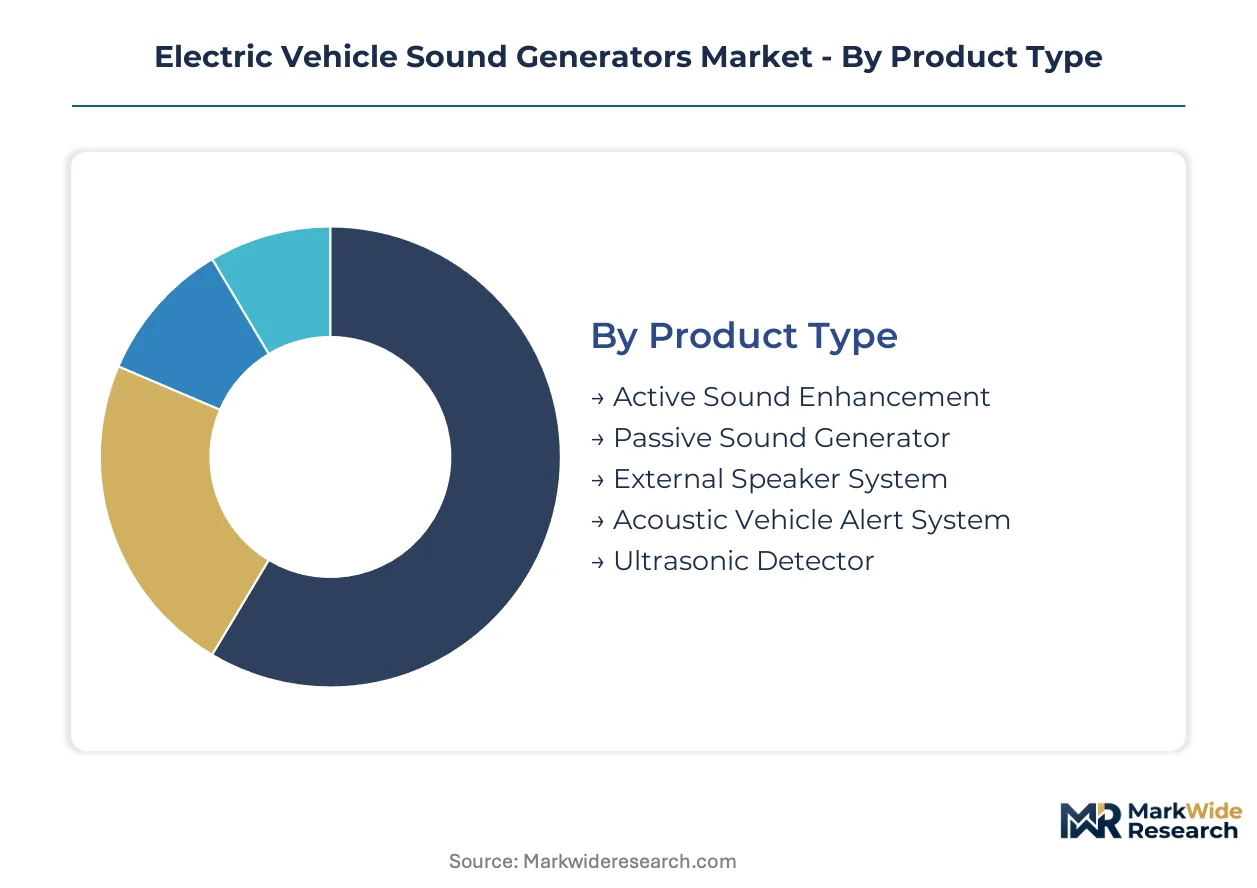
Segmentation in the electric vehicle sound generators market reveals how regulatory mandates, platform architecture choices, and supply chain positioning create divergent value pools. Each dimension exposes different competitive dynamics between integrated system suppliers and discrete component vendors.
Product Type:
Procurement patterns differentiate buyers between those seeking regulatory compliance alone versus those pursuing brand-differentiated acoustic signatures.
- Acoustic Vehicle Alert System:Electromechanical or solid-state devices emitting synthesized sound patterns between 500 Hz and 10 kHz to satisfy pedestrian safety mandates in near-silent battery-electric drivetrains. Demand concentrates in Germany, where Stuttgart and Munich-based automakers bundle AVAS hardware with active cabin sound enhancement systems under tightening UN Regulation No. 138 directional-accuracy thresholds.
- Active Sound Enhancement:Programmable audio generation systems that create brand-specific cabin acoustics and exterior vehicle signatures beyond minimum regulatory requirements. Premium OEM architectures in Germany and California are driving attachment rates as electrification strips away traditional ICE sound cues that previously defined brand identity.
- Passive Sound Generator:Mechanical acoustic devices without electronic modulation capability, typically employed in cost-optimized vehicle programs where regulatory minimums suffice.
- External Speaker System:Discrete amplification and driver assemblies mounted in bumper fascias or wheel arches, facing procurement pressure from platform-integrated alternatives.
- Ultrasonic Detector:High-frequency acoustic sensors for parking assistance and proximity detection, consolidating with alert speakers in next-generation sensor fusion architectures.
AVAS leads volumes today; active sound enhancement is gaining share fastest.
Technology:
Cost tiers separate adopters between premium solid-state solutions and conventional electromagnetic alternatives facing rare-earth magnet volatility.
- Piezoelectric:Solid-state transducers using ceramic substrates to generate directional audio output without electromagnetic coils. Fabrication clusters in Osaka and Seoul create supply concentration risks for Japanese and Korean vehicle programs.
- MEMS:Microelectromechanical systems unifying multiple acoustic functions into single-chip architectures with surface-mount packaging. Premium German OEMs embed these during platform definition, collapsing traditional separations between pedestrian alert and cabin enhancement systems.
- Electromagnetic:Conventional voice-coil drivers dependent on neodymium permanent magnets, suffering margin compression from rare-earth price volatility.
- Resonator-Based:Tuned cavity or membrane systems using frequency modulation algorithms for speed-variable amplitude envelopes.
- Ultrasonic:High-frequency transducers above human hearing range for parking assistance and proximity detection applications.
Piezoelectric technology dominates current installations; MEMS architectures show the steepest expansion trajectory.
Application:
Regulatory maturity separates applications between mandated pedestrian safety systems and optional driver-assistance functions.
- Pedestrian Safety:Mandated acoustic emission systems for low-speed vehicle operation to prevent collisions with visually impaired pedestrians and cyclists. NHTSA Federal Motor Vehicle Safety Standard No. 141 and UN Regulation No. 138 enforcement protocols are tightening across US and EU platforms.
- Parking Assistance:Ultrasonic proximity detection combined with audible feedback for maneuvering in confined spaces. Municipal transit authorities in California and Texas are issuing separate RFPs for bus AVAS systems with distinct acoustic signatures, fragmenting firmware requirements.
- Collision Avoidance:Acoustic warning systems integrated with forward-facing sensors for imminent impact alerts.
- Blind Spot Detection:Side-mounted acoustic alerts supplementing visual indicators during lane-change maneuvers.
- Vehicle Identification:Customizable sound signatures for fleet operators seeking acoustic brand differentiation or operational identification.
Pedestrian safety commands the largest installed base; parking assistance is climbing the fastest.
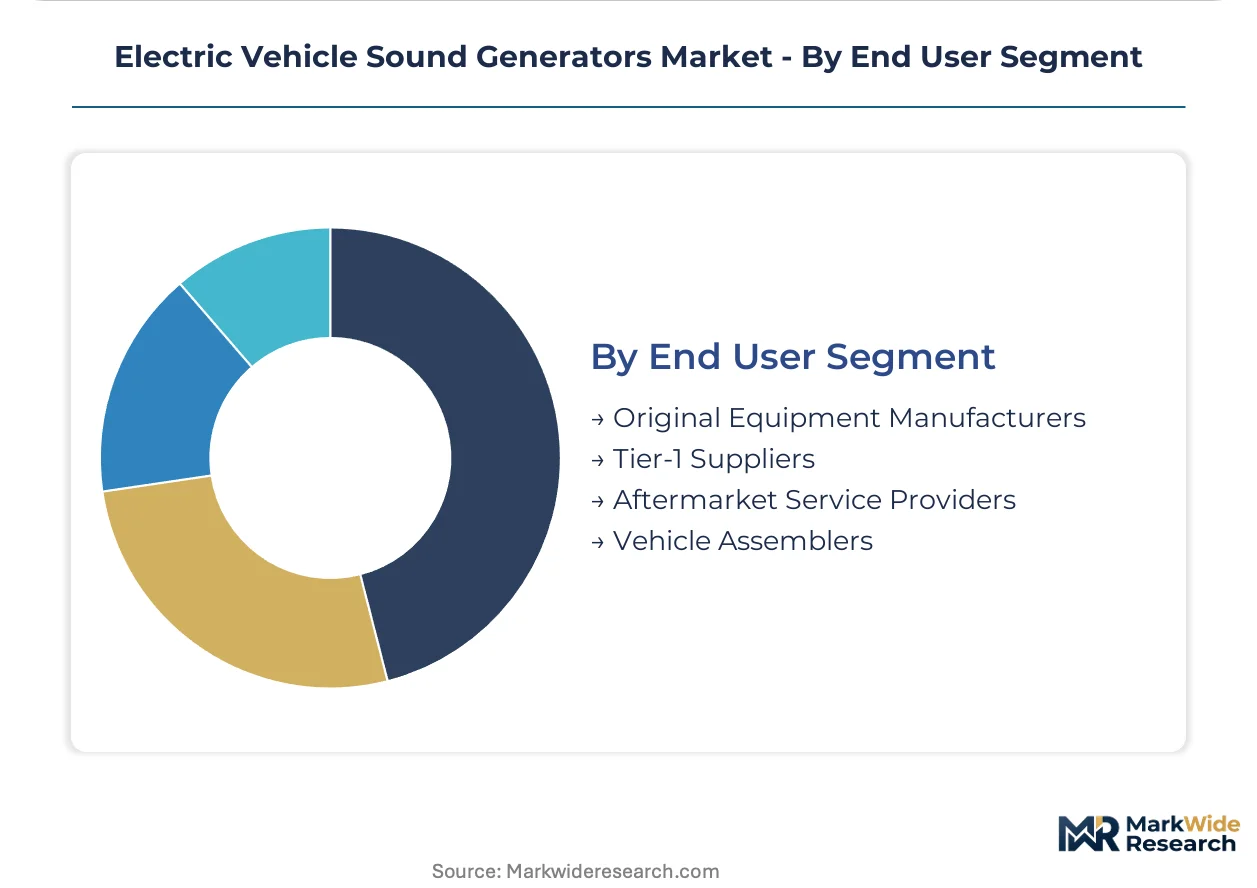
End User Segment:
Supply chain position determines whether buyers specify components during platform definition or procure through aftermarket channels.
- Original Equipment Manufacturers:Vehicle brand owners defining acoustic system requirements during architecture stage and sourcing through Tier-1 partnerships. Platform-level integration is compressing procurement timelines and forcing co-development with suppliers during vehicle architecture definition rather than post-design validation.
- Tier-1 Suppliers:Integrated system providers managing subsystem design, validation, and homologation on behalf of OEM customers. Continental AG leverages these relationships to dominate integrated system architecture for European OEMs.
- Vehicle Assemblers:Contract manufacturers executing production under OEM direction with limited acoustic system specification authority.
- Aftermarket Service Providers:Independent channels addressing retrofit demand from commercial fleet operators in China's Jiangsu and Guangdong provinces under provincial NEV safety standard enforcement.
OEMs lead specification authority today; Tier-1 suppliers are capturing margin expansion fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as suppliers migrate toward jurisdictions with streamlined homologation pathways and localized incentive structures. Production capacity is concentrating where compliance costs and certification timelines create measurable competitive gaps.
Germany
Stuttgart and Munich-based OEMs are bundling AVAS hardware with active cabin sound enhancement systems under tightening UN Regulation No. 138 directional-accuracy thresholds. The KBA enforces expanded coverage to heavier vehicle classes through amended type-approval protocols. Engineering clusters in Baden-Württemberg and Bavaria dominate integrated system architecture development for European platforms.
United States
Detroit and Dearborn electrification programs are accelerating hardware redesigns to meet revised NHTSA Federal Motor Vehicle Safety Standard No. 141 decibel thresholds at low-speed operation. Heavy-duty pickup platforms face retroactive compliance obligations previously granted provisional exemptions. Midwest automotive corridors concentrate electromagnetic driver assembly lines serving domestic light-duty truck programs.
China
Provincial implementation of NEV safety standards in Jiangsu and Guangdong provinces accelerates retrofit demand for commercial electric van and bus fleets. The MIIT coordinates GB standard alignment with UN technical regulations while preserving domestic certification autonomy. Yangtze River Delta fabrication clusters supply piezoelectric ceramic substrates for transducer assembly across Asian vehicle programs.
Japan
Osaka-based fabrication clusters create supply concentration risks for piezoelectric ceramic substrate production serving Japanese and Korean OEMs. METI guidelines harmonize domestic technical standards with UN Regulation No. 138 performance benchmarks. Kansai engineering centers specialize in frequency modulation algorithm development for speed-variable amplitude envelope systems.
India
The PLI scheme for advanced automotive electronics creates localized assembly incentives for AVAS module manufacturers targeting export and domestic OEM procurement. BIS certification pathways for automotive electronics are streamlining homologation timelines for Tier-1 suppliers establishing greenfield capacity. Tamil Nadu and Gujarat automotive corridors attract acoustic module assembly investments from multinational component suppliers.
Electric Vehicle Sound Generators Market Key Industry Players
Platform-level co-development partnerships dominate the current landscape as procurement timelines compress and Tier-1 suppliers embed earlier in vehicle architecture definition. The vendor structure concentrates around integrated system providers with established OEM relationships, while discrete component specialists face margin pressure from platform-integrated alternatives. Three archetypes define competitive positioning: full-system integrators with architecture-level design authority, resonator-based technology specialists holding frequency modulation IP, and piezoelectric transducer fabricators anchored in ceramic substrate supply chains. M&A activity and strategic technology licensing are the dominant competitive moves as suppliers seek to collapse traditional separations between pedestrian alert and cabin enhancement functions.
Among European-integrated system providers, Continental AG and Forvia Hella exemplify the full-system integrator archetype with established architecture-level relationships. Denso Corporation anchors the Asia-Pacific supply position for piezoelectric transducer fabrication. Aptiv occupies a specialist position in resonator-based alert module technology. These three represent the competitive core around which market structure organizes.
| Leading Market Players |
|---|
| Aptiv |
| Forvia Hella |
| Continental AG |
| Brigade Electronics |
| STMicroelectronics |
| Denso Corporation |
| Hyundai Mobis |
| Brose Fahrzeugteile |
| Harman International |
| Others |
Cost & Logistics Intelligence
Platform-integrated versus discrete-component procurement bifurcation creates divergent margin structures across the electric vehicle sound generator value chain. German OEMs commanding architecture-level co-development partnerships capture pricing premiums through bundled AVAS and active sound enhancement configurations, while aftermarket retrofit channels in China's commercial fleet segment compete on neodymium cost pass-through economics and piezoelectric substrate availability.
Pricing Analysis
Distributor margins compress toward single-digit percentages for standard AVAS modules sold through Tier-1 supplier channels, while direct-to-OEM negotiated contracts for integrated acoustic architectures sustain healthier returns. Three-tier pricing structure across premium MEMS-based systems, standard piezoelectric configurations, and economy electromagnetic alternatives reflects certification grade differentiation under UN Regulation No. 138 and NHTSA FMVSS 141. Pricing pressure stems from rare-earth magnet volatility disrupting electromagnetic driver economics. Fleet operators in commercial EV segments exhibit highest price sensitivity, whereas Stuttgart and Munich-based luxury OEMs prioritize directional-accuracy performance over unit cost.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Detroit, and Osaka coordinate hub-and-spoke patterns feeding assembly lines across European, North American, and Asian vehicle programs. Manufacturing concentration in Germany, China, and Japan reflects proximity to premium OEM engineering centers and ceramic substrate fabrication clusters. Raw material dependencies center on neodymium permanent magnets, piezoelectric ceramic substrates, and MEMS silicon wafers. Single-source vulnerability in Osaka and Seoul ceramic production creates supply chain risk for transducer assembly lines. Distribution runs through Tier-1 supplier direct-ship arrangements to OEM platform engineering centers, bypassing traditional aftermarket warehousing for original equipment procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as pedestrian safety mandates harden into platform design requirements rather than post-hoc compliance add-ons. Procurement patterns favor suppliers embedding during vehicle architecture definition rather than validation-stage competition.
For Market Incumbents: Extend platform-level co-development relationships with German and US OEMs to lock out resonator-based technology specialists seeking frequency modulation IP licensing revenue. Deepen backward integration into piezoelectric ceramic substrate production to offset Osaka and Seoul supply concentration risks. Capture margin expansion through bundled AVAS and active cabin sound enhancement architectures before MEMS unification collapses discrete amplifier-module procurement tiers.
For New Entrants and Emerging Players: UN Regulation No. 138 in the European Union opens a window for specialized directional-accuracy testing and homologation service providers as anechoic chamber certification cycles extend platform launch schedules. Target India's PLI scheme for advanced automotive electronics to establish localized AVAS module assembly capacity serving export and domestic OEM procurement. Pursue sensor fusion convergence opportunities integrating ultrasonic parking detectors with pedestrian alert speakers for consolidated ECU architectures.
For Investors and Strategic Acquirers: Consolidation pressure builds where MEMS-based resonator technology collapses traditional separations between pedestrian alert and cabin enhancement functions, eliminating discrete component specialists. Position for long-term viability around full-system integrators with architecture-level design authority and established OEM platform engineering relationships. Monitor frequency modulation algorithm patent estate developments as inflection indicator for resonator-based technology specialist acquisition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform-Level Co-Development Partnerships | Early embedding with Stuttgart and Detroit OEMs locks in architecture-stage specification authority before validation-phase competition. |
| Piezoelectric Ceramic Substrate Backward Integration | Captive supply of Osaka and Seoul-dependent materials insulates margin compression from rare-earth magnet volatility. |
| MEMS Resonator Technology Licensing | Single-chip acoustic architectures unify pedestrian alert and cabin enhancement, collapsing traditional supplier tiers. |
| India PLI Scheme Manufacturing Localization | Tamil Nadu and Gujarat greenfield capacity targets export and domestic OEM procurement with streamlined BIS certification. |
| Sensor Fusion ECU Consolidation | Integration of ultrasonic parking detectors with AVAS speakers reduces wiring harness complexity for next-generation architectures. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and acoustic system R&D directors with secondary validation against vehicle production databases, IHS Markit registration data, UN Regulation No. 138 homologation records, and NHTSA FMVSS 141 compliance filings. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates across technology, product type, and application dimensions.
Historical reference periods anchored growth trajectory assumptions across the projection horizon, with analytical frameworks modeling vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster segmentation. CAGRs derived from installed base expansion rates, replacement cycle timing, and technology substitution curves. Forecast inputs incorporated UN Regulation No. 138 amendment timelines, NHTSA enforcement protocol tightening, and MEMS resonator adoption curves in premium German OEM platforms.
Revisions become necessary when regulatory divergence between US minimum-sound rules and EU directional-accuracy requirements accelerates, rare-earth magnet price volatility disrupts electromagnetic driver manufacturing economics, or MEMS unification timelines collapse discrete component demand faster than modeled. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Global EV on-Board Chargers Market
Electric Vehicles
China Electric Vehicle Market
Electric Vehicles
High Voltage PTC Heaters for Electric Vehicles Market
Electric Vehicles
Global Smart Electric Drive Market
Electric Vehicles
Off-Highway Electric Machine Battery Pack Systems Market
Electric Vehicles
Self Balancing Electric Scooter Market
Electric Vehicles
Plug-In Hybrid Electric Vehicle Battery Market
Electric Vehicles
India Electric Bus Market
Electric Vehicles
UK Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
UK Electric Bus Battery Pack Market
Electric Vehicles
Hoverboard Scooter Market
Electric Vehicles
South Africa Electric Cars Market
Electric Vehicles
Electric Vehicle Rental Market
Electric Vehicles
Electric Vehicle HVAC Market
Electric Vehicles
Electric Vehicle (EV) Fluids Market
Electric Vehicles
Europe Electric Vehicle Thermal Management System Market